
 Guided Munitions Market | 2026-2036
Guided Munitions Market Size, Share, and Industry Trends Forecast 2026-2036
Guided Munitions Market Outlook
The EU Green Deal's embedded defense procurement sustainability criteria is expanding contract eligibility requirements for European suppliers. Lockheed Martin leverages its vertical integration across solid-rocket motor and seeker production to sustain delivery timelines for precision munitions programs. RTX Corporation anchors its position through in-house production of guided weapon subsystems across multiple NATO supply chains. Thales Group differentiates via specialized European manufacturing for scalable precision-strike architectures.
Guided munitions are ordnance systems incorporating onboard navigation and terminal homing to achieve precision engagement against designated targets, typically employing composite airframe structures, multi-spectral seekers, and programmable warhead packages manufactured through vacuum-assisted resin transfer molding and precision machining. Their primary purpose is to deliver kinetic effects with minimized circular error probable against fixed, mobile, or time-sensitive targets across contested operational environments. Missiles command the dominant share of product-type value pools due to recurring procurement of standoff-range systems for air-to-ground and naval warfare applications, while GPS-enabled technology leads volume shipment as satellite-navigation dependencies mature across military end-user inventories. Imaging infrared guidance represents the fastest-growing technology segment as seekers penetrate contested electronic warfare environments where GPS denial tactics proliferate.
The US Department of Defense, NATO Standardization Office, and EU Defence Fund collectively shape procurement eligibility, technical interoperability mandates, and cross-border joint development financing for guided munitions programs. NATO STANAG compliance requirements directly determine market access for non-allied suppliers seeking European defense contractor partnerships. Stakeholders must monitor evolving autonomous-engagement policy boundaries and export-control list revisions as determinants of next-generation product development roadmaps and partnership eligibility.
Market Dynamics
Autonomous targeting architectures are compressing development cycles across NATO precision-strike programs as military end-users demand reduced operator-in-the-loop dependencies for contested electromagnetic environments.
Growth Catalysts
- EU Defence Fund cross-border financing:Joint development programs for interoperable seeker technologies expand contract pools for qualified European suppliers meeting NATO STANAG compliance thresholds.
- Indo-Pacific territorial flashpoints:Inventory modernization cycles in the theater accelerate procurement of standoff-range systems for maritime strike and area-denial missions.
- Imaging infrared seeker penetration:Multi-spectral terminal homing capabilities proliferate as electronic warfare environments degrade GPS-dependent navigation reliability.
Market Restraints
- Solid-rocket motor supply concentration:Propulsion component manufacturing clusters in limited geographies create single-source vulnerabilities for precision munitions assembly lines.
- Export control list friction:International Traffic in Arms Regulations and allied dual-use technology restrictions delay technology transfer timelines for cross-border joint ventures.
- GPS-deniation countermeasure costs:Alternative navigation subsystem integration raises unit economics for satellite-navigation-dependent munitions categories.
Strategic Opportunities
- EU Green Deal defense procurement criteria:Sustainability eligibility requirements create first-mover advantages for European suppliers with certified low-carbon manufacturing processes.
- Dual-use guidance component manufacturing:Commercial sensor and microelectronics production lines in China offer cost-accessible subsystems for non-allied market segments.
- Autonomous-engagement policy boundaries:Evolving rules of engagement for human-machine teaming create white space for semi-autonomous targeting system developers.
Industry Challenges
- Seeker-to-airframe integration complexity:Multi-spectral sensor fusion with composite vacuum-assisted resin transfer molded structures demands specialized aerospace-electronics hybrid engineering talent.
- NATO interoperability certification timelines:STANAG compliance testing protocols extend product qualification cycles for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guided Munitions Market |
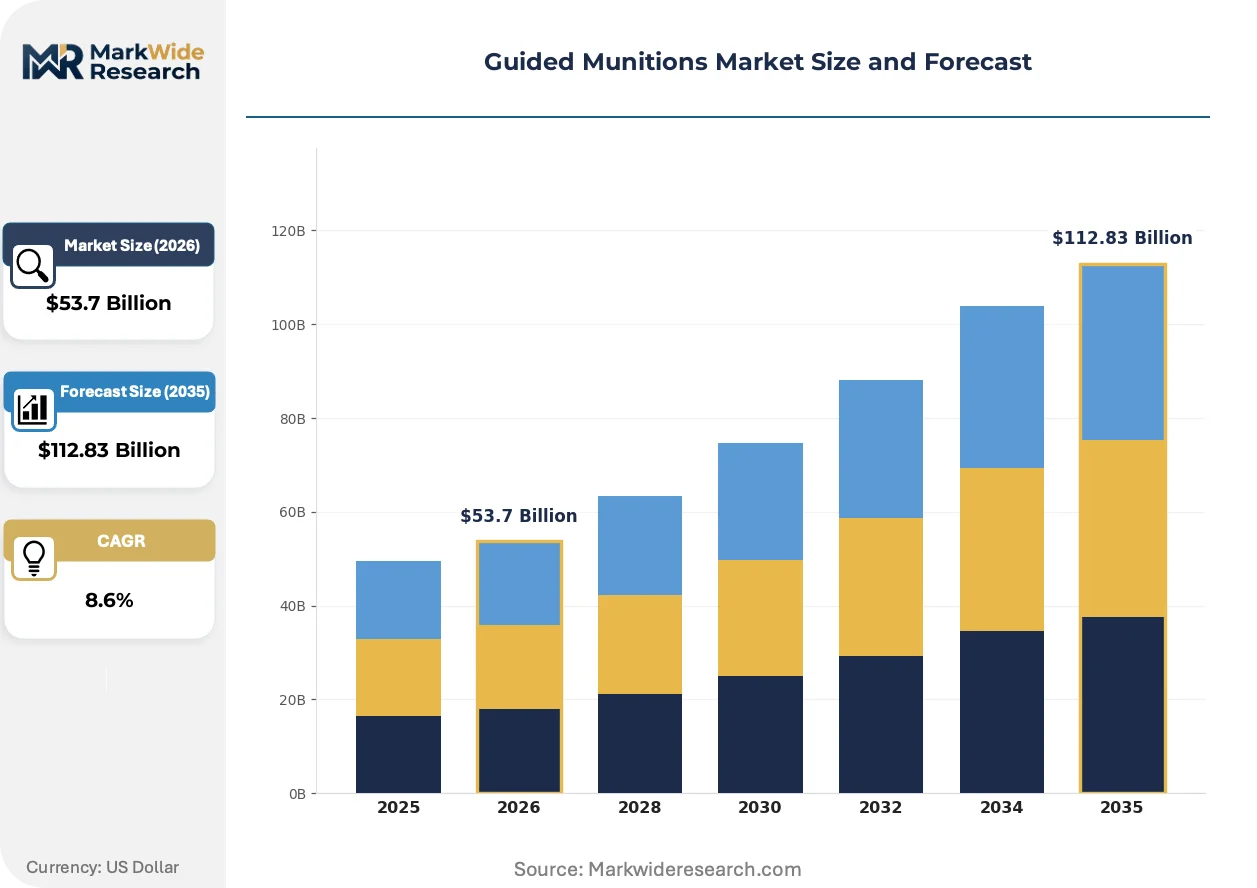
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $112.83 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missiles, Bombs, Torpedoes, Rockets Technology: GPS, Laser Guidance, Inertial Navigation, Imaging Infrared Application: Air-to-Ground, Ground-to-Air, Naval Warfare, Space End User: Military, Defense Contractors, Government Agencies, Security Forces |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, BAE Systems, Boeing, General Dynamics, MBDA, Israel Aerospace Industries, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guided Munitions Market Strategic Shifts
Precision-strike architectures are migrating toward modular seeker packages that swap guidance modalities without airframe redesign, compressing upgrade cycles for fielded inventories.
Multi-spectral imaging infrared seekers are rewriting engagement profiles in GPS-contested environments. Naval and air-warfare end-users in the Indo-Pacific theater are accelerating fielding of these terminal-homing alternatives. The technology is compressing reliance on satellite-navigation infrastructure for time-sensitive target prosecution.
EU Green Deal embedded sustainability criteria are reshaping contract eligibility for European defense procurement. Suppliers must now document carbon footprint across solid-rocket motor and seeker production chains. Precision munitions programs with certified low-carbon manufacturing gain preferential scoring in NATO member state tenders.
Buyer concentration among NATO defense contractors is consolidating subsystem vendor bases. Prime contractors are narrowing approved supplier lists for guidance electronics and composite airframe components. This pattern concentrates procurement leverage with RTX Corporation, Lockheed Martin, and Thales Group vertical integration strategies.
Guided Munitions Market Segmentation
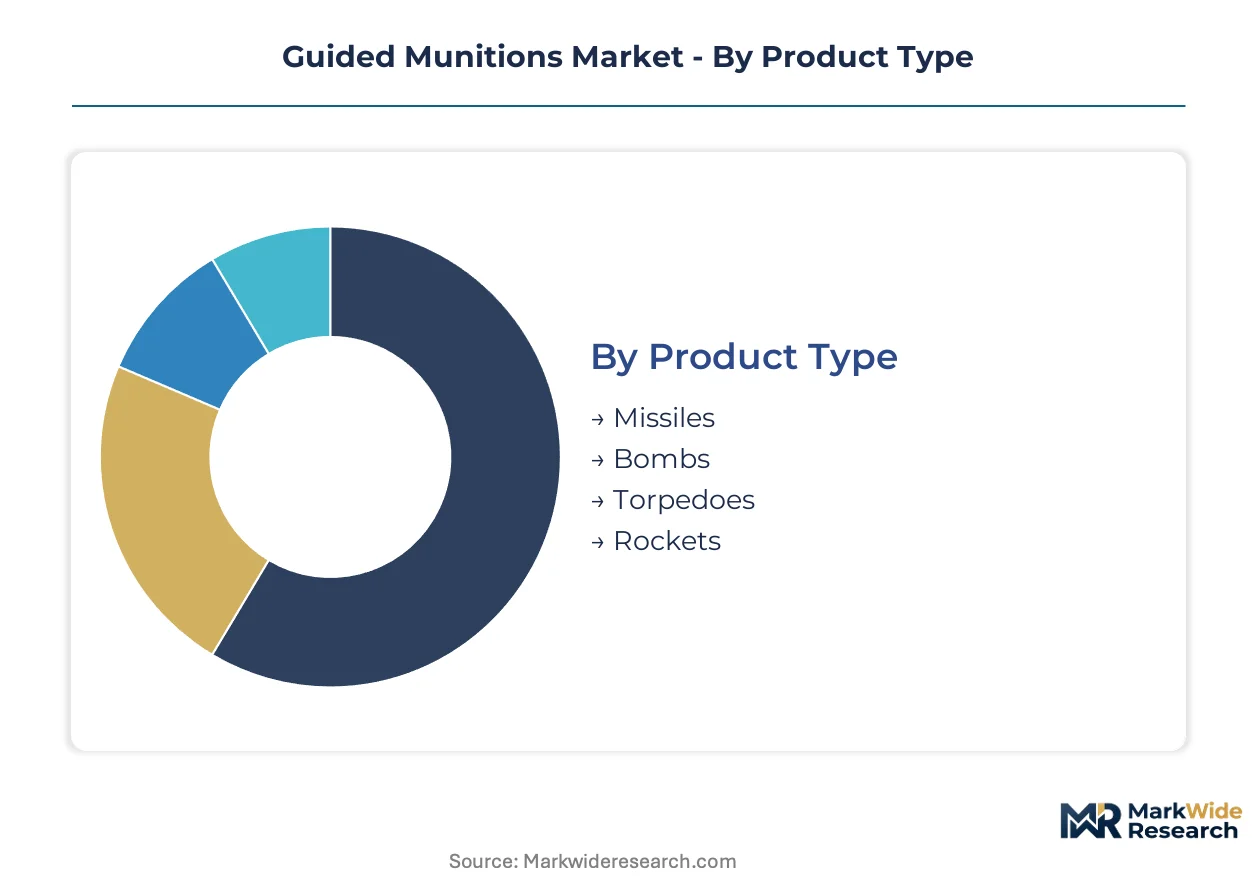
Segmentation in guided munitions reveals how procurement priorities diverge across mission profiles and electromagnetic threat environments. Military end-users select guidance architectures based on target mobility, engagement range, and satellite-navigation dependency risks.
Product Type:
Procurement budgets concentrate on standoff-range systems that minimize platform exposure in contested air defense environments.
- Missiles:Self-propelled precision-strike systems integrate solid-rocket motors with multi-spectral seekers for air-to-ground and naval warfare applications. NATO defense contractors prioritize recurring procurement of these systems for Indo-Pacific maritime strike missions where area-denial capabilities threaten legacy platforms.
- Bombs:Glide and precision-guided munitions employ GPS-aided inertial navigation with optional laser or imaging infrared terminal homing. Demand clusters in close air support roles across Middle Eastern and Eastern European theaters where collateral damage constraints dominate engagement rules.
- Torpedoes:Underwater kinetic systems with acoustic and wire-guided terminal homing for anti-submarine and anti-surface warfare.
- Rockets:Unguided and precision-guided artillery projectiles with reduced circular error probable through fin-stabilization and course correction.
Missiles lead on scale; imaging infrared seeker integration is gaining share fastest across product type development roadmaps.
Technology:
Electronic warfare proliferation is reshaping guidance modality selection as GPS-deniation tactics mature across peer adversary inventories.
- GPS:Satellite-navigation-dependent systems dominate volume shipment through mature receiver integration and cost-accessible chipset supply. Military end-users in permissive electromagnetic environments continue procurement, though alternative navigation backup requirements raise subsystem complexity.
- Imaging Infrared:Multi-spectral terminal homing seekers penetrate contested environments where GPS jamming degrades satellite-navigation reliability. Naval and air-warfare programs in the Indo-Pacific theater accelerate fielding as electronic warfare threats intensify.
- Laser Guidance:Semi-active and beam-riding systems requiring continuous target designation for precision engagement.
- Inertial Navigation:Self-contained gyroscopic and accelerometer-based positioning without external signal dependency.
GPS leads on scale; imaging infrared climbs the fastest as seekers displace satellite-dependent architectures in contested theaters.
Application:
Mission profile determines guidance package specifications, with maritime strike demanding specialized anti-ship seeker configurations.
- Air-to-Ground:Fixed-wing and rotary-platform delivered munitions for close air support, interdiction, and strategic strike. Procurement concentrates in NATO member states modernizing fighter-bomber inventories for reduced collateral engagement profiles.
- Naval Warfare:Anti-ship and land-attack missiles with sea-skimming flight profiles and counter-countermeasure seeker logic. Indo-Pacific territorial flashpoints drive inventory modernization cycles for maritime area-denial missions.
- Ground-to-Air:Surface-to-air missile systems for area and point defense against aerial threats.
- Space:Orbital and suborbital kinetic systems for anti-satellite and space situational awareness applications.
Air-to-ground leads on scale; naval warfare shows steepest expansion trajectory as maritime flashpoints reshape procurement priorities.
End User:
Budget authority and operational doctrine differentiate procurement patterns across institutional buyer categories.
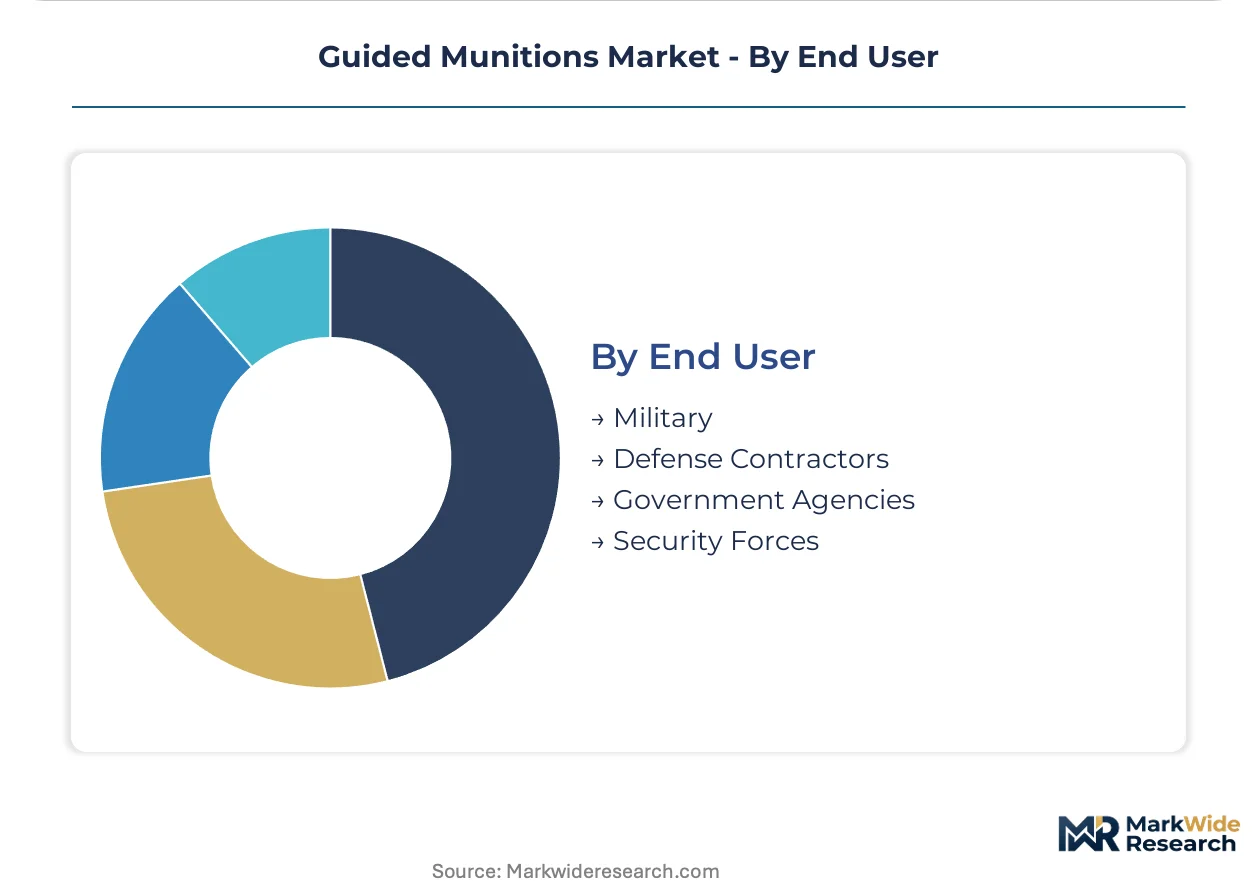
- Military:Uniformed service branches with direct operational employment of precision-strike systems. The US Department of Defense and NATO allied ministries of defense anchor demand through multi-year procurement programs for standoff-range capabilities.
- Defense Contractors:Prime and subsystem suppliers procuring guidance components and airframe structures for government contract fulfillment. RTX Corporation and Lockheed Martin vertical integration strategies concentrate vendor base leverage.
- Government Agencies:Non-military state entities with specialized precision-strike requirements for border security and critical infrastructure protection.
- Security Forces:Paramilitary and internal security units with limited precision munitions procurement for counter-insurgency applications.
Military end-users lead on scale; defense contractors drive supply chain momentum through subsystem integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The guided munitions industry traces its modern precision-strike lineage to post-Cold War US defense modernization programs that established satellite-guided engagement architectures. These foundational investments created the technology base now diffusing across allied inventories worldwide.
United States
The US Department of Defense anchors procurement volume through multi-year precision-strike programs emphasizing autonomous targeting capabilities. FAA and DoD acquisition regulations govern airworthiness certification and export control compliance for guided weapon platforms. Tucson, Arizona and Orlando, Florida host concentrated seeker and solid-rocket motor manufacturing clusters serving prime contractor supply chains.
Germany
Bundeswehr modernization initiatives drive demand for interoperable precision munitions meeting NATO STANAG requirements. EU Green Deal embedded defense procurement criteria impose sustainability documentation obligations on subsystem suppliers. Bavaria's aerospace-electronics corridor around Munich hosts specialized guidance component manufacturing for European missile programs.
France
DGA procurement programs prioritize sovereign precision-strike capabilities for expeditionary warfare and nuclear deterrence missions. REACH and EU Defence Fund cross-border financing mechanisms shape joint development eligibility for seeker technologies. The Île-de-France region concentrates prime contractor engineering centers and subsystem integration facilities.
China
PLA Rocket Force expansion accelerates domestic procurement of dual-use guidance components for anti-access area-denial architectures. MIIT and SAMR regulations govern military-civil fusion technology transfers and microelectronics production standards. The Yangtze River Delta manufacturing belt scales output of commercial sensor subsystems with precision guidance applications.
Israel
IDF operational requirements prioritize compact precision munitions for contested urban and subterranean engagement profiles. National export licensing frameworks balance technology transfer opportunities with security classification protocols. Haifa's defense technology corridor hosts specialized seeker development and composite airframe prototyping facilities.
Guided Munitions Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and NATO certification access. The vendor base stratifies between vertically integrated primes controlling solid-rocket motor and seeker production, specialized subsystem suppliers, and emerging dual-use component manufacturers. Three archetypes dominate: full-stack platform integrators, guidance electronics specialists, and propulsion subsystem suppliers. Competitive positioning depends on backward integration into critical components and strategic partnerships for electromagnetic spectrum resilience.
Among US-based defense primes, Lockheed Martin Corporation and RTX Corporation exemplify the vertically integrated archetype through captive supply of guided weapon subsystems. Thales Group represents the European specialist model with concentrated manufacturing for scalable precision-strike architectures. These three anchors demonstrate how geographic regulatory alignment and in-house production capabilities determine contract access across NATO procurement programs.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Boeing |
| General Dynamics |
| MBDA |
| Israel Aerospace Industries |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Solid-rocket motor propellant costs cascade through precision munitions pricing tiers from raw material procurement in limited geographies to NATO-certified assembly lines, compressing margins for non-integrated subsystem suppliers while vertically integrated primes capture value through captive supply of seeker and airframe components.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NATO STANAG-certified precision munitions from dual-use component alternatives and unguided ordnance categories. Price differentiation hinges on seeker technology complexity and carbon-footprint certification status under EU Green Deal procurement criteria. Cost compression in standard-tier GPS-dependent munitions is intensifying because alternative navigation backup requirements raise subsystem integration expenses. Defense contractors exhibit lowest price sensitivity due to multi-year program commitments, while security forces in emerging markets face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Tucson, Arizona and Orlando, Florida anchor hub-and-spoke patterns for seeker and solid-rocket motor components serving prime contractor assembly lines. Manufacturing gravity centers on the United States, Germany, and China for guidance electronics, propulsion systems, and dual-use sensor subsystems respectively. Critical dependencies include rare-earth magnet alloys for seeker gimbals, ammonium perchlorate for propellant formulations, and gallium arsenide for infrared detector arrays. Single-source vulnerability in solid-rocket motor production creates chokepoint exposure. Distribution runs through defense prime contractor vendor-managed inventory systems with NATO ally priority allocation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The guided munitions market functions as a geographic-arbitrage play where EU Green Deal carbon-certification costs in European manufacturing contrast with cost-accessible dual-use component sourcing from China's Yangtze River Delta microelectronics belt.
For Market Incumbents: Anticipate margin compression from Chinese dual-use sensor manufacturers penetrating non-allied market segments through commercial microelectronics export channels. Prioritize backward integration into solid-rocket motor production to eliminate single-source propulsion vulnerabilities. Accelerate NATO STANAG certification investments to maintain European procurement eligibility as sustainability criteria tighten. For New Entrants and Emerging Players: Multi-spectral imaging infrared seeker miniaturization offers entry pathways into GPS-contested theater applications where electronic warfare proliferation degrades satellite-navigation reliability. Target naval warfare programs in Indo-Pacific maritime strike roles as inventory modernization cycles accelerate. Pursue joint development partnerships with EU Defence Fund-qualified suppliers to access cross-border financing mechanisms. For Investors and Strategic Acquirers: Consolidation pressure builds where subsystem vendor bases narrow under prime contractor vertical integration strategies and NATO interoperability certification barriers rise. Long-term viability favors acquisition targets with captive seeker production and established STANAG compliance track records. Monitor autonomous-engagement policy boundary revisions as inflection indicators for semi-autonomous targeting system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid-Rocket Motor Production | Eliminates single-source propulsion vulnerabilities for Lockheed Martin and RTX Corporation assembly lines. |
| EU Green Deal Carbon Certification Program | Creates preferential tender scoring for Thales Group and MBDA in NATO European procurement pools. |
| Imaging Infrared Seeker Platform Integration | Enables GPS-denied engagement profiles for Indo-Pacific maritime strike missions. |
| Joint Venture for Dual-Use Component Sourcing | Accesses Yangtze River Delta microelectronics cost structures for non-allied market segments. |
| NATO STANAG Interoperability Certification | Determines market access eligibility for European defense contractor partnership opportunities. |
Study Parameters
Direct dialogue with precision munitions program managers, solid-rocket motor procurement leads, seeker subsystem engineers, and NATO standardization officers grounded qualitative assessments in operational procurement realities. Secondary validation drew from US Department of Defense budget justification materials, EU Defence Fund award disclosures, FAA airworthiness certification databases, and International Traffic in Arms Regulations filing records. Bottom-up unit economics modeling and top-down defense budget allocation analysis were cross-triangulated to establish market sizing boundaries.
Segment-level value outputs emerged from modeling across product type, guidance technology modality, mission application profile, and end-user budget authority dimensions throughout the forecast period. CAGRs were derived through regression analysis of historical procurement cycle patterns and projected Indo-Pacific inventory modernization trajectories. Key forecast inputs included PLA Rocket Force expansion timelines, EU embedded defense procurement sustainability criteria implementation schedules, and autonomous-engagement policy boundary evolution scenarios.
The model holds under sustained NATO alliance cohesion and continued US-China strategic competition; deviation in multilateral export control regime alignment or breakthroughs in quantum navigation would shift demand trajectories for GPS-alternative seeker technologies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Aircraft Weapons Market