
 Automatic Weapons Market | 2026-2036
Automatic Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Weapons Market Intelligence
Buyer concentration among national defense ministries is shifting toward multi-year framework contracts that bundle automatic weapons with training and sustainment packages. BAE Systems plc leverages its supply relationships with the British Ministry of Defence to anchor long-term service agreements alongside hardware deliveries. Rheinmetall AG competes through its manufacturing scale in Germany and expanded ammunition integration capabilities. Israel Weapon Industries specializes in compact assault rifle platforms optimized for urban counterterrorism operations.
Automatic weapons are firearms capable of sustained automatic or burst fire using intermediate or full-power cartridges, typically cycling through gas-operated or recoil-operated mechanisms at rates exceeding 600 rounds per minute. These systems serve military and security forces requiring suppressive fire capability in infantry, vehicle-mounted, and special operations roles. Assault rifles and light machine guns together constitute the core procurement volume, with gas-operated technology dominating fielded inventories due to proven reliability in adverse conditions. Electronically controlled firing systems represent an emerging segment where margin pools concentrate, though bolt-action and blowback designs retain niche applications in specialized law enforcement and paramilitary contexts.
The U.S. State Department's ITAR regulations and Germany's KBA licensing requirements shape market access by restricting technology transfer and end-user verification for automatic weapons exports. EU Green Deal carbon accounting rules and REACH chemical restrictions are beginning to influence ammunition propellant formulations and barrel manufacturing processes. Stakeholders must monitor how NATO standardization agreements interact with national industrial base protection policies when positioning for upcoming defense procurement cycles.
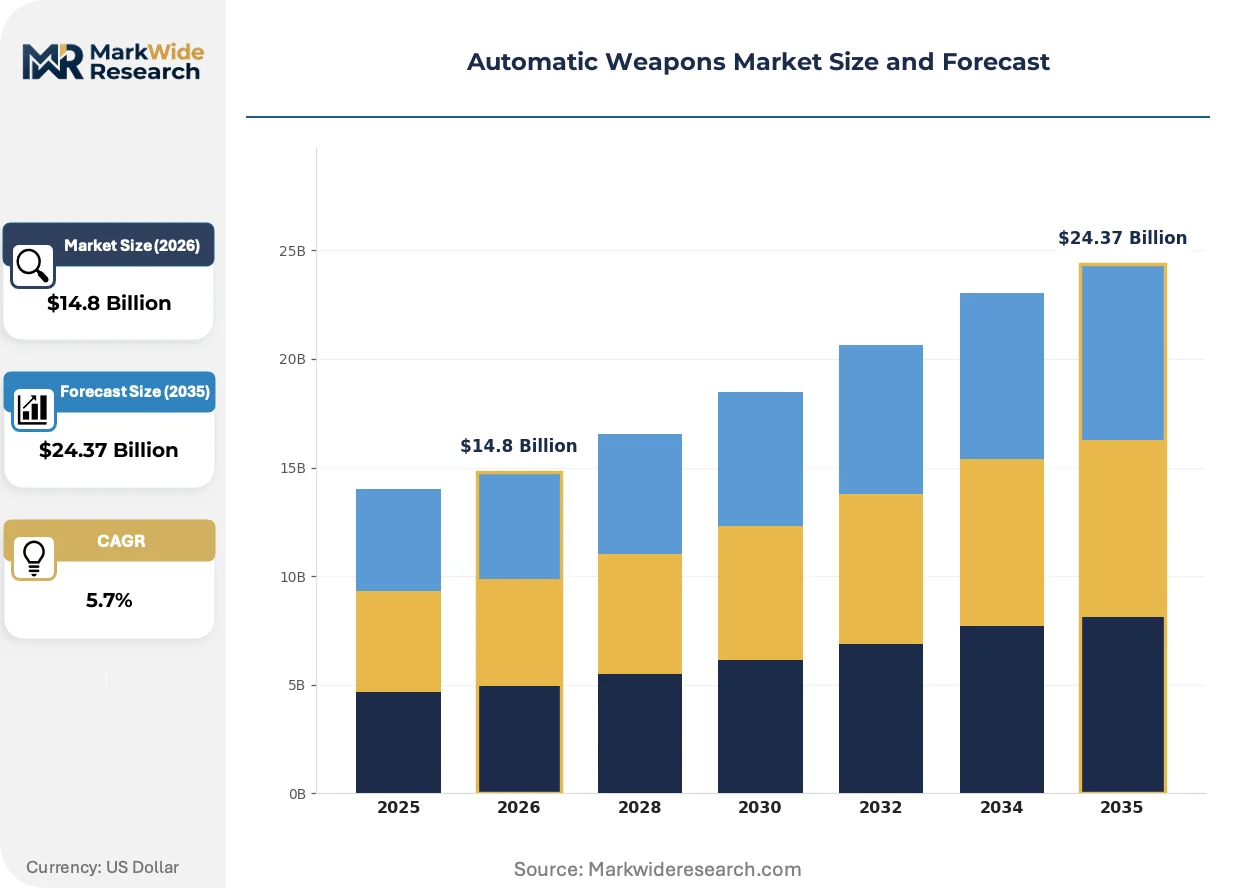
Market Dynamics
Defense procurement officers across NATO member states are consolidating automatic weapons purchases into multi-year framework contracts that bundle hardware, training, and sustainment into single vendor relationships, compressing traditional spot-buying cycles and favoring suppliers with integrated service capabilities.
Growth Catalysts
- ITAR modernization:The U.S. State Department's updated International Traffic in Arms Regulations are streamlining end-user verification protocols for allied nations, reducing licensing delays for NATO-standard automatic weapons transfers.
- Urban counterterrorism doctrine:Special operations forces in Western Europe and the Middle East are driving demand for compact assault rifle platforms optimized for close-quarters battle environments.
- Gas-operated reliability:Proven performance of gas-piston systems in adverse desert and maritime conditions is accelerating replacement of legacy direct-impingement rifles in Indo-Pacific force structures.
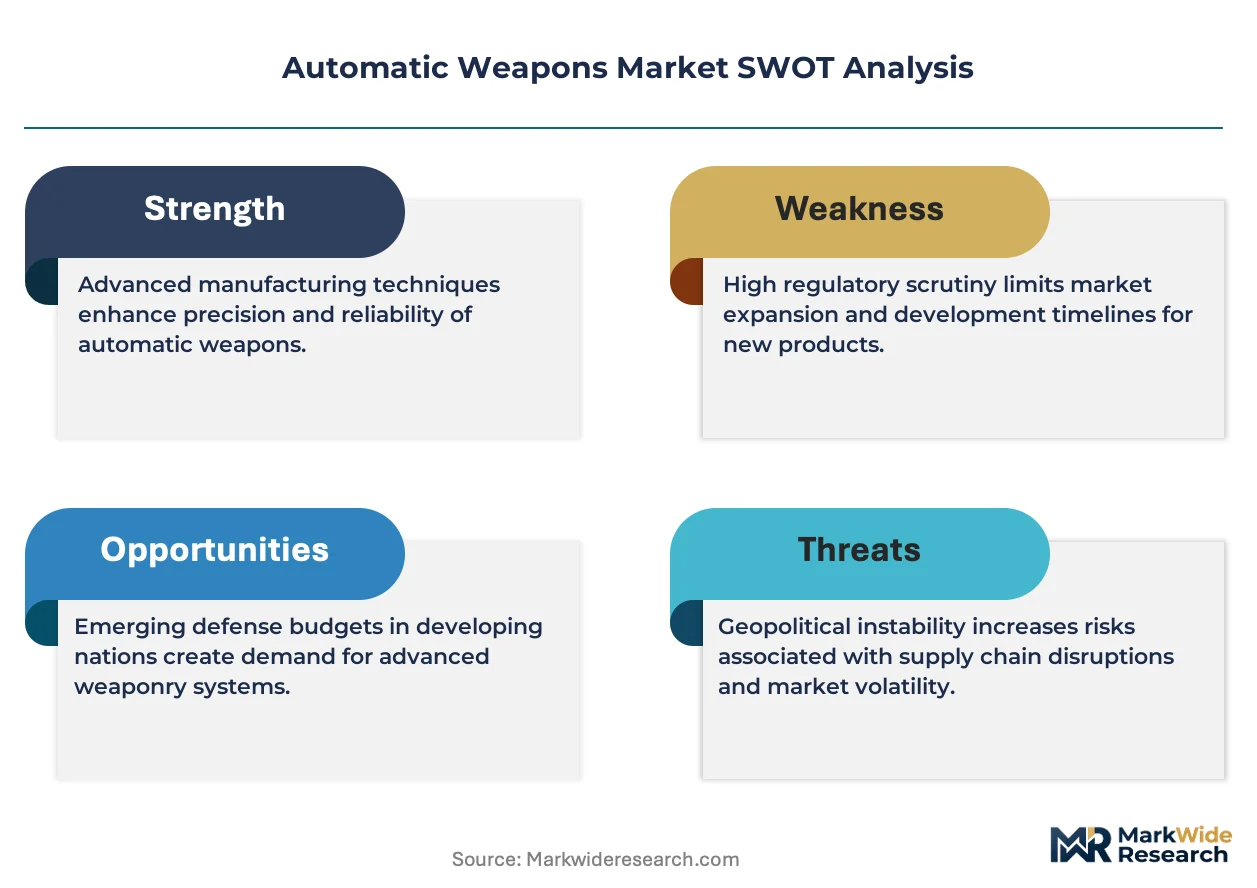
Market Restraints
- Export licensing friction:Germany's KBA and the U.S. State Department maintain divergent end-user certification standards, creating compliance complexity for dual-source suppliers.
- Barrel steel supply concentration:Premium chrome-molybdenum and stainless barrel blanks rely on a limited supplier base in Central Europe, exposing manufacturers to input volatility.
- Substitution by unmanned systems:Loitering munitions and armed unmanned ground vehicles are displacing manned automatic weapons in static defensive positions.
Strategic Opportunities
- Electronic firing control:Convergence of solid-state ignition systems with programmable rate-of-fire modules is opening margin pools in precision infantry weapons.
- India's Make in India defense offset:Foreign original equipment manufacturers can establish licensed production through joint ventures with Indian private sector partners to meet domestic procurement mandates.
- REACH propellant reformulation:EU chemical restrictions are creating first-mover advantage for ammunition suppliers developing reduced-toxicity nitrocellulose alternatives.
Industry Challenges
- ITAR compliance talent scarcity:Defense exporters face acute shortages of licensing specialists capable of navigating concurrent U.S., German, and national export control frameworks.
- Legacy system integration:Next-generation electronically controlled firing mechanisms must interface with existing NATO-standard rail systems and optical mounting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Weapons Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Assault Rifles, Submachine Guns, Light Machine Guns, Battle Rifles, Heavy Machine Guns Technology: Gas-Operated, Recoil Operated, Bolt-Action, Blowback, Electronically Controlled End Use: Military Forces, Law Enforcement Agencies, Paramilitary Groups, Private Security Firms Deployment Mode: Infantry, Vehicle Mounted, Airborne, Naval, Special Operations |
| Companies Covered | BAE Systems plc, Northrop Grumman Corporation, General Dynamics Corporation, FN Herstal, Rheinmetall AG, Lockheed Martin Corporation, Israel Weapon Industries, Kalashnikov Concern, Heckler & Koch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Weapons Market Strategic Shifts & Innovations
Automatic weapons development is pivoting from incremental mechanical refinement toward digital integration, with programmable firing systems and embedded diagnostics displacing purely analog designs in frontline procurement specifications.
Solid-state ignition technology is rewriting reliability standards for sustained automatic fire. These systems eliminate traditional firing pins and mechanical sears, replacing them with electrically initiated primers controlled by microprocessor logic. Special operations units in Australia and the United Kingdom are field-testing programmable burst modes and ammunition counters. This convergence is compressing maintenance intervals while enabling real-time weapon diagnostics that were previously impossible in field conditions.
EU Green Deal carbon accounting rules are forcing propellant chemistry reformulation across European ammunition supply chains. The European Chemicals Agency's REACH restrictions on heavy metals and persistent organic pollutants are banning traditional stabilizers in nitrocellulose formulations. German and French ammunition plants are retooling for nitrogen-rich energetics with cleaner combustion profiles. Barrel manufacturing is simultaneously adapting to reduced-corrosion propellants that alter heat erosion patterns in chrome-lined bores.
Bundled service contracts are displacing discrete hardware purchases in major defense procurement cycles. British and Australian defense ministries now require ten-year availability guarantees with automatic weapons deliveries, transferring obsolescence risk to original equipment manufacturers. This shift is visible most acutely in the Indo-Pacific, where Japan's Ministry of Defense and India's Ministry of Defence are both structuring rifle tenders around total cost-of-ownership rather than unit acquisition price.
Automatic Weapons Market Segmentation
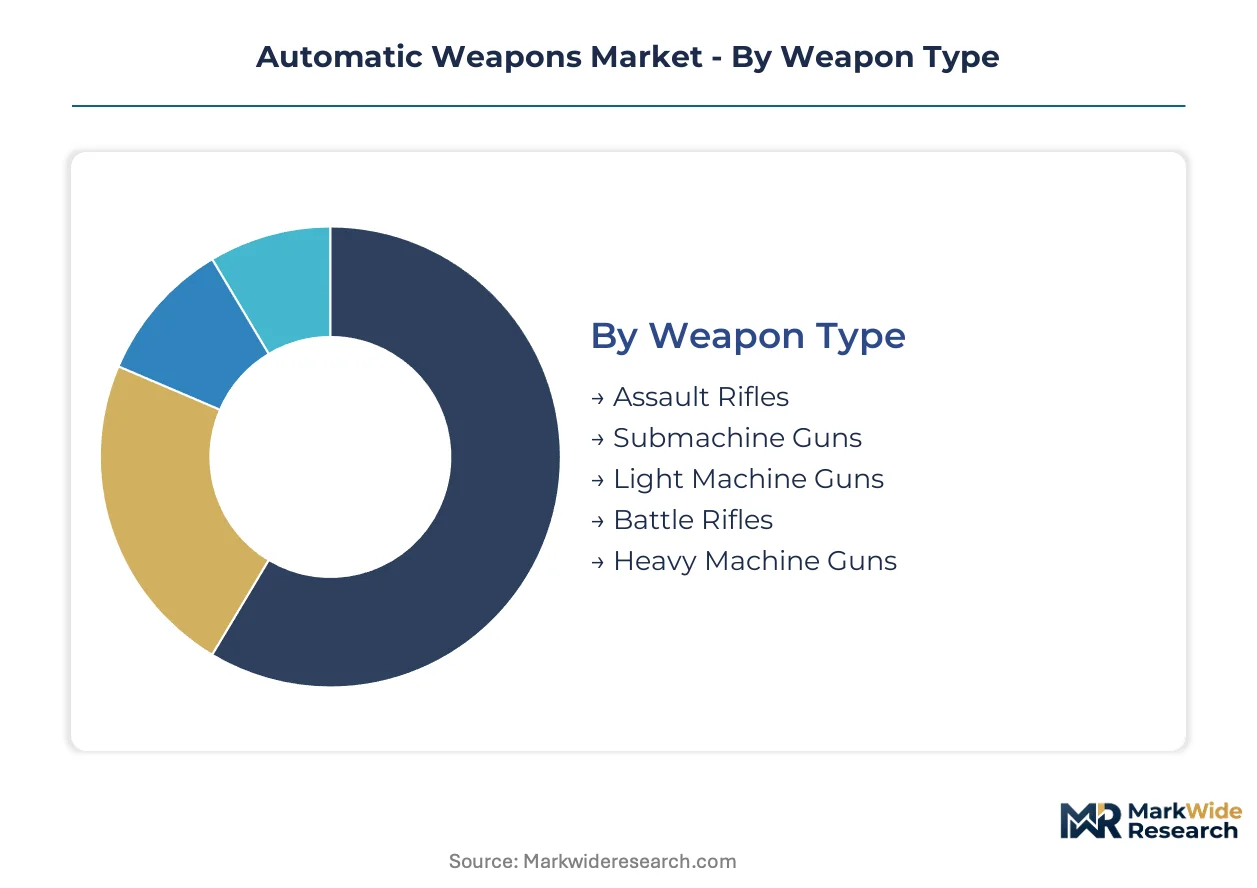
Automatic weapons procurement decisions hinge on mission profile, operating environment, and lifecycle cost rather than unit price alone. Defense ministries evaluate weapon type, firing mechanism, and deployment mode as interdependent variables within integrated infantry system architectures. This segmentation reveals how procurement officers balance immediate operational requirements against long-term sustainment obligations across diverse force structures.
Weapon Type:
Infantry commanders prioritize ammunition commonality and suppressive fire volume when selecting primary small arms for squad-level deployment.
- Assault Rifles:Intermediate-cartridge selective-fire weapons chambering 5.56mm or 7.62mm rounds form the backbone of modern infantry squads. NATO standardization agreements drive convergence around 5.56mm platforms for interoperability, though India's Ministry of Defence is evaluating larger calibers for Himalayan terrain penetration.
- Light Machine Guns:Belt-fed or magazine-fed automatic weapons delivering sustained fire at 600-1,000 rounds per minute anchor squad automatic weapon roles. Australian Defence Force procurement emphasizes gas-piston reliability for maritime and desert environments under the LAND 159 program.
- Submachine Guns:Compact pistol-caliber automatic weapons serve close protection and vehicle crew roles where space constraints dominate.
- Battle Rifles:Full-power cartridge rifles address designated marksman requirements and barrier penetration scenarios beyond standard assault rifle effective range.
- Heavy Machine Guns:.50 caliber or 12.7mm systems provide vehicle-mounted and static defensive suppressive capability against light armor and materiel targets.
Volume sits with Assault Rifles; growth tilts toward Light Machine Guns as squad firepower distribution evolves.
Technology:
Reliability under contamination and maintenance interval requirements determine mechanism selection for adverse-condition deployments.
- Gas-Operated:Piston-driven or direct-impingement systems using propellant gases to cycle the action dominate military inventories due to proven performance in sand, dust, and maritime corrosion. The U.S. Marine Corps and British Army both specify gas-piston variants for reduced maintenance burden in expeditionary operations.
- Electronically Controlled:Solid-state ignition and microprocessor-managed firing sequences enable programmable burst modes, ammunition counting, and diagnostic telemetry. Australian Special Operations Command and UK Special Forces are field-testing these systems for precision engagement requirements.
- Recoil Operated:Mechanisms harnessing backward force from cartridge discharge cycle the action in heavier platforms where gas system complexity adds unacceptable weight.
- Blowback:Simple delayed or direct blowback designs persist in submachine guns and compact automatic weapons where lower chamber pressures permit simplified manufacturing.
- Bolt-Action:Manual cycling retains niche application in precision sniper systems and certain law enforcement contexts requiring absolute mechanical simplicity.
Procurement volume concentrates in Gas-Operated systems; Electronically Controlled platforms are climbing the fastest as digitization penetrates infantry equipment.
End Use:
Rules of engagement, training depth, and accountability frameworks create divergent specification requirements across user categories.
- Military Forces:National defense ministries procure automatic weapons through multi-year framework contracts bundling hardware, training, and decade-long sustainment. Germany's KBA and the U.S. State Department ITAR frameworks govern transfer authorization for these end users.
- Law Enforcement Agencies:Police tactical units and border security organizations require selective-fire capability with strict accountability protocols and reduced collateral damage profiles. EU member states increasingly mandate REACH-compliant propellants for domestic security ammunition.
- Paramilitary Groups:State-sponsored irregular forces operate under varying degrees of formal oversight, creating inconsistent end-user certification complexity for exporters.
- Private Security Firms:Commercial protective services face the most restrictive licensing regimes, with many jurisdictions prohibiting automatic weapons entirely or limiting procurement to semi-automatic variants.
Military Forces command the dominant procurement volume; Law Enforcement Agencies represent the steepest expansion trajectory as urban counterterrorism capabilities proliferate.
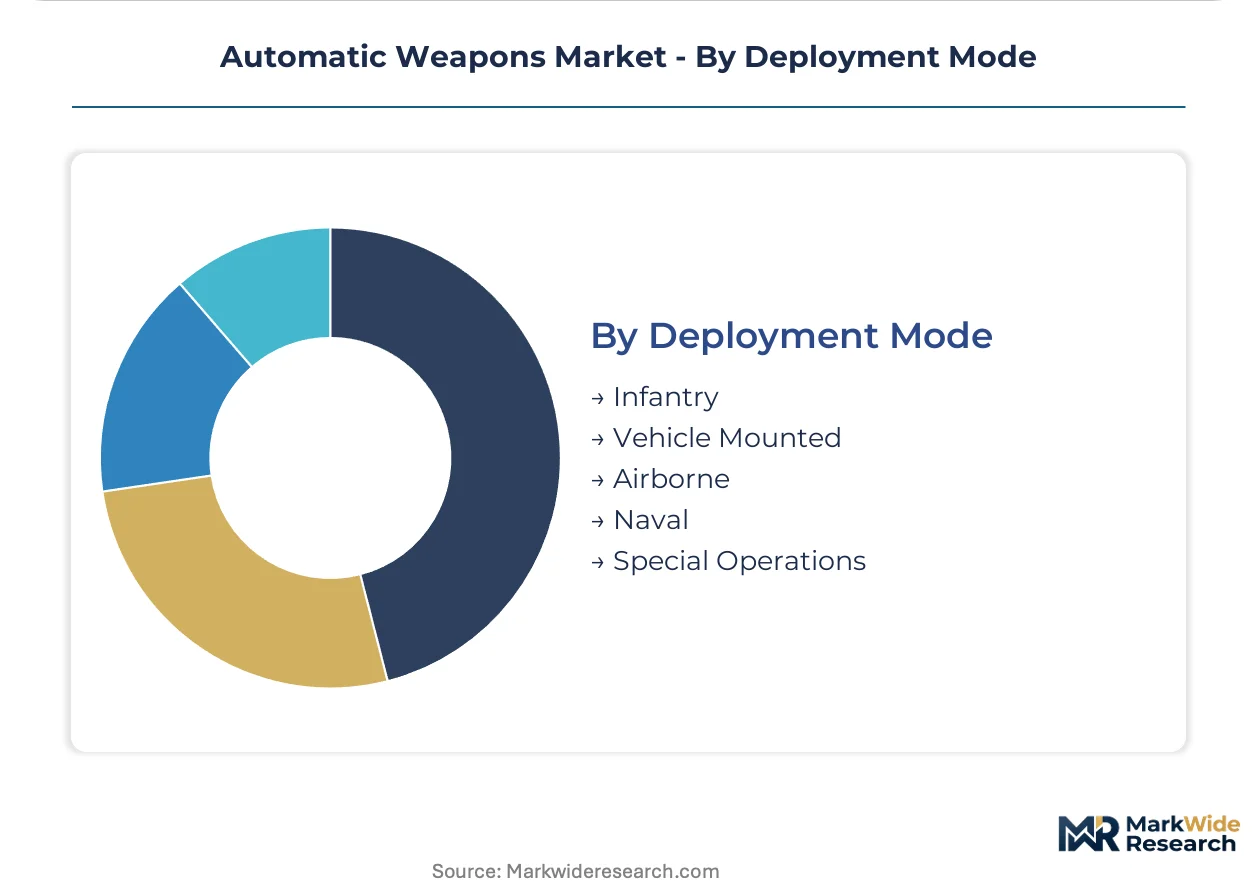
Deployment Mode:
Platform integration requirements dictate weight, dimensional, and interface specifications before individual weapon characteristics.
- Infantry:Individual and crew-served weapons carried by dismounted soldiers prioritize reliability, ammunition weight efficiency, and rail system compatibility with optical and laser aiming devices.
- Vehicle Mounted:Turret- and pintle-mounted systems require remote firing capability, stabilization interfaces, and integration with vehicle power and communication architectures.
- Special Operations:Modular weapon systems enabling rapid caliber and configuration changes dominate special forces procurement, with suppressor compatibility and compact folded dimensions as non-negotiable requirements.
- Airborne:Paratroop and air assault units impose strict weight and length constraints for jump compatibility and confined space maneuverability.
- Naval:Maritime boarding parties and shipboard security require enhanced corrosion resistance and operational reliability after saltwater immersion.
Infantry deployment absorbs the greatest procurement volume; Special Operations specifications are gaining share fastest as elite unit equipment standards diffuse to conventional forces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chrome-molybdenum and stainless barrel blanks from Central European forges supply precision components to assemblers across NATO arsenals. Defense procurement officers in Germany, the United States, India, Australia, and Japan structure multi-year framework contracts bundling hardware with decade-long sustainment obligations.
United States
Marine Corps expeditionary requirements and Army Next Generation Squad Weapon programs drive gas-piston platform adoption. The State Department's ITAR modernization streamlines end-user verification for allied transfers. Connecticut and South Carolina host final assembly clusters where prime contractors integrate electronically controlled firing systems with NATO-standard rail architectures.
Germany
Bundeswehr infantry modernization and export licensing under KBA jurisdiction shape procurement velocity. The KBA maintains divergent end-user certification standards from U.S. ITAR, creating compliance complexity for dual-source suppliers. North Rhine-Westphalia and Bavaria concentrate precision barrel manufacturing and ammunition propellant formulation under REACH chemical restrictions.
India
Himalayan terrain penetration requirements and Make in India defense offset mandates redirect procurement toward licensed domestic production. The Ministry of Defence evaluates larger calibers beyond standard 5.56mm NATO for high-altitude engagement. Uttar Pradesh and Tamil Nadu host emerging joint ventures between foreign original equipment manufacturers and Indian private sector partners.
Australia
LAND 159 program specifications prioritize gas-piston reliability for maritime and desert expeditionary operations. The Australian Defence Force structures rifle tenders around total cost-of-ownership rather than unit acquisition price. Victoria and Queensland maintain special operations testing facilities for programmable burst mode and ammunition counter systems.
Japan
Ministry of Defense framework contracts bundle automatic weapons with ten-year availability guarantees transferring obsolescence risk to manufacturers. Territorial tensions in adjacent waters accelerate infantry system refresh cycles. Yokohama and Nagoya industrial zones adapt manufacturing processes for reduced-toxicity propellant compatibility with chrome-lined bore specifications.
Automatic Weapons Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electronically controlled firing integration and bundled service contracts. Market structure concentrates around defense primes with existing ministry relationships and integrated sustainment capabilities. Three archetypes dominate: scale-driven manufacturers with ammunition integration, compact platform specialists for urban operations, and digitally integrated system architects. Competitive moves center on multi-year framework contract capture and REACH-compliant propellant chemistry first-mover positioning.
Among British and German fabricators, BAE Systems plc and Rheinmetall AG occupy positions anchoring long-term service agreements alongside hardware deliveries. Israel Weapon Industries exemplifies the compact assault rifle archetype optimized for special operations requirements. These three represent distinct competitive vectors: integrated sustainment bundling, manufacturing scale with ammunition verticality, and urban counterterrorism platform specialization.
| Leading Market Players |
|---|
| BAE Systems plc |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| FN Herstal |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Israel Weapon Industries |
| Kalashnikov Concern |
| Heckler & Koch |
| Others |
Cost & Logistics Intelligence
NATO defense ministry procurement officers concentrate buying power through multi-year framework contracts that compress spot-market transactions and anchor pricing around total cost-of-ownership rather than unit acquisition cost. This buyer consolidation shifts margin capture toward integrated service bundling and away from discrete hardware markups.
Pricing Analysis
High-volume assault rifle and light machine gun procurement runs through contract-based long-term offtake agreements with decade-long availability guarantees, while electronically controlled firing systems command premium positioning through performance differentiation. Price differentiation separates NATO-standard platforms from non-aligned nation specifications, with certification under ITAR and KBA frameworks adding compliance premiums. Pricing pressure stems from bundled sustainment obligations transferring obsolescence risk to manufacturers. Military forces exhibit lowest price sensitivity given mission-critical requirements; private security firms face highest sensitivity due to licensing restrictions limiting procurement options.
Supply Chain Analysis
Regional distribution centers in Germany, Belgium, and the United States coordinate hub-and-spoke patterns for barrel blanks, propellant chemicals, and finished weapon systems. Manufacturing draws from chrome-molybdenum steel forgings in Central Europe, nitrocellulose propellant formulations in France and Germany, and precision machining clusters in Connecticut and Bavaria. Single-source vulnerability concentrates in premium barrel blank suppliers, exposing assemblers to input volatility. Distribution runs through defense ministry direct procurement channels with limited aftermarket intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrel steel supply concentration in Central European forges constrains manufacturing expansion, propping pricing power for integrated producers with captive metallurgical capabilities.
For Market Incumbents: Cement multi-year framework contract capture through ammunition vertical integration and licensed production joint ventures in India. Electronic firing control specialists threaten traditional gas-operated margins; counter by deepening captive supply of precision ignition components and REACH-compliant propellant chemistry. For New Entrants and Emerging Players: Domestic Indian private sector partners offer the most penetrable channel for licensed assembly under Make in India offset mandates. Target urban counterterrorism platform specialization where compact assault rifle specifications outpace incumbent development cycles. Enter through joint venture structures that satisfy end-user certification requirements without direct export licensing exposure. For Investors and Strategic Acquirers: The window for entry favors ammunition suppliers with propellant reformulation capabilities ahead of REACH enforcement tightening. Long-term viability hinges on backward integration into barrel manufacturing and electronic firing module development. Watch Indo-Pacific defense budget acceleration as the signal for contract award inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Production Joint Venture | Indian Ministry of Defence offsets mandate domestic assembly partnerships for foreign OEM market access. |
| REACH-Compliant Propellant Development | European Chemicals Agency restrictions force nitrocellulose reformulation ahead of competitor retooling. |
| Electronic Firing Control Integration | Solid-state ignition systems enable programmable burst modes demanded by Australian and UK special operations. |
| Multi-Year Framework Contract Capture | British and Australian defense ministries bundle hardware with ten-year sustainment obligations. |
| Barrel Manufacturing Backward Integration | Central European chrome-molybdenum supply concentration rewards captive metallurgical capabilities. |
Research Approach
Multi-period observation of defense procurement award patterns, export licensing volumes, and ammunition production capacity anchored the trend analysis, supplemented by interviews with defense procurement officers, export compliance specialists, barrel manufacturing plant managers, and ammunition R&D directors. Secondary validation drew from U.S. State Department ITAR disclosure filings, German KBA licensing registers, EU REACH regulatory updates, and NATO standardization agreement documentation. Bottom-up platform deployment estimates triangulated against top-down defense budget appropriation analysis.
Segment-weighting across weapon type, firing mechanism technology, end-use category, and deployment mode informed volume distribution modeling throughout the forecast period. CAGRs derived from procurement cycle timing, replacement rate assumptions, and technology transition curves. Industry-specific inputs included Indo-Pacific territorial tension escalation indices and NATO member state modernization program commitment levels.
Several conditions sit outside the modeled scope, including classified special operations procurement volumes, paramilitary group acquisitions lacking end-user certification, and potential unmanned systems substitution effects beyond static defensive positions. Forecasts reflect documented assumptions around regulatory continuity and alliance procurement coordination. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Medium Caliber Ammunition Market