
 US Perforating Gun Market | 2026-2036
US Perforating Gun Market Size, Share, and Industry Trends Forecast 2026-2036
US Perforating Gun Market Intelligence
Aftermarket refurbishment and charge reloading revenue is reconfiguring margin pools away from one-time hardware sales across the US perforating gun value chain. Baker Hughes Company leverages its integrated well construction portfolio to bundle perforating services with logging and completion tools. SLB anchors its position through proprietary shaped-charge metallurgy and downhole telemetry integration. Hunting PLC specializes in manufacturing-scale production of gun carriers and detonator systems from its US-based facilities.
A perforating gun is a specialized downhole tool assembly containing explosive shaped charges arranged to create controlled fractures in well casing, cement, and formation rock, typically rated for pressures exceeding 15,000 psi and temperatures above 350°F. Its primary purpose is to establish communication between the wellbore and hydrocarbon-bearing formations during completion operations. Wireline-conveyed systems dominate deployment frequency in onshore US basins due to speed and cost efficiency in plug-and-perf operations. Electric detonation technology is displacing legacy mechanical systems as operators pursue precise depth correlation and reduced misfire rates in extended-reach laterals. Coiled tubing deployment competes most directly in re-entry and workover applications where wellbore geometry limits conventional conveyance.
The Bureau of Safety and Environmental Enforcement (BSEE) mandates stringent well control and barrier verification standards for offshore perforating operations, while the EPA's New Source Performance Standards impose methane monitoring requirements that favor gun systems enabling tighter zonal isolation. OSHA's Process Safety Management rules govern explosive handling and storage protocols at manufacturing and field service facilities. Stakeholders must monitor evolving state-level setback regulations and emerging carbon intensity scoring mechanisms that could restructure completion economics across the most active US basins.
Market Dynamics
EPA methane emissions rules and BSEE well integrity standards are forcing a wholesale redesign of perforating gun pressure ratings and zonal isolation capabilities across US unconventional basins.
Growth Catalysts
- Extended-reach laterals:Permian and Bakken operators now routinely drill 15,000-foot laterals requiring multi-stage perforating systems. Gun carriers rated for higher shot densities capture incremental demand from independent producers.
- OSHA Process Safety Management:Stricter explosive handling protocols at manufacturing facilities are accelerating consolidation toward specialized domestic producers with certified storage infrastructure.
- Electric detonation systems:Wireline-deployed electric firing heads are replacing mechanical systems, enabling precise depth correlation and reduced misfire rates in Appalachian shale completions.
Market Restraints
- Copper and tungsten supply concentration:Shaped-charge liner materials face price volatility from limited North American smelter capacity, compressing margins for gun system assemblers.
- Offshore regulatory friction:BSEE barrier verification requirements add 15-20% to offshore gun system certification costs, deterring smaller service companies from Gulf of Mexico entry.
- Plug-and-perf substitution limits:Ball-activated sliding sleeve systems compete in factory-completed wells, constraining addressable market growth in certain Delaware Basin acreage.
Strategic Opportunities
- Aftermarket charge reloading:Refurbishment revenue streams are emerging as operators extend gun carrier life cycles across multiple wells, shifting margin pools from hardware sales to recurring services.
- Coiled tubing convergence:Integration of real-time telemetry with CT-deployed guns opens re-entry workover markets where wellbore geometry limits conventional wireline access.
- Texas Railroad Commission flaring rules:Tighter zonal isolation mandates favor gun systems enabling stage-specific pressure containment, creating premium pricing tiers for certified products.
Industry Challenges
- Explosives handling certification delays:ATF licensing timelines for new manufacturing facilities stretch 18-24 months, constraining capacity expansion for emerging regional suppliers.
- Legacy mechanical inventory obsolescence:Service companies face stranded asset risk as electric detonation becomes standard, requiring costly retrofit programs or write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Perforating Gun Market |
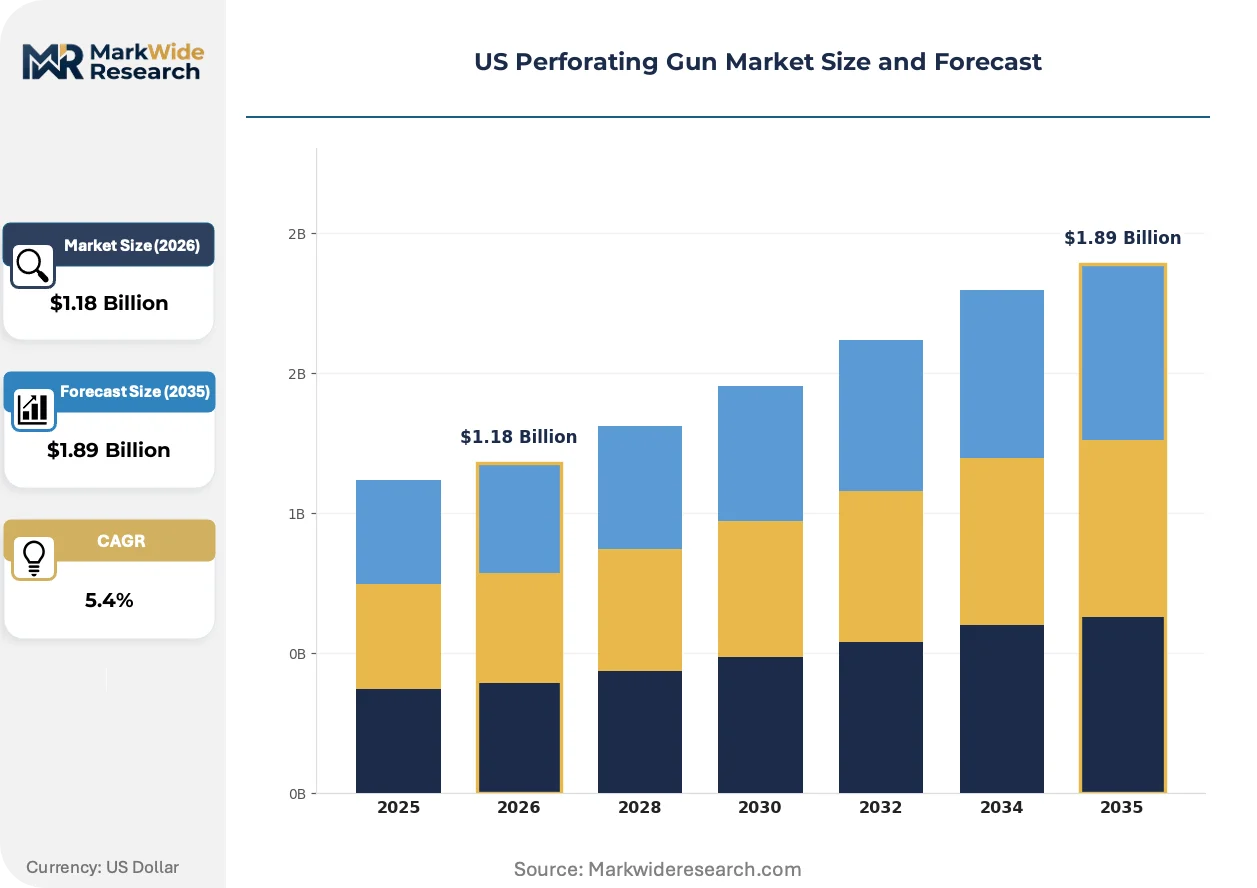
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wireline, Tubing, Coiled Tubing, Conventional Application: Onshore, Offshore, Well Completion, Workover End User: Oil & Gas Companies, Service Providers, Independents, Operators Technology: Mechanical, Electric, Hydraulic, Hybrid |
| Companies Covered | Baker Hughes Company, SLB, Halliburton Company, Weatherford International plc, NOV Inc., DMC Global Inc., Hunting PLC, DynaEnergetics, G&H Diversified Manufacturing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Perforating Gun Market Strategic Shifts & Innovations
Downhole telemetry integration and automated firing control systems are compressing operational cycle times while enabling real-time perforation optimization across US shale plays.
Addressable switch technology is digitizing perforating gun firing sequences through microprocessor-controlled detonation timing. Permian Basin operators deploying these systems achieve sub-foot depth correlation accuracy. The technology is digitizing legacy wireline operations by replacing mechanical firing pins with programmable electronic triggers.
EPA New Source Performance Standards for methane monitoring are mandating tighter zonal isolation verification in completion operations. Gun systems must now demonstrate post-perforation pressure integrity to satisfy emissions compliance documentation. Offshore Gulf of Mexico deployments face the most stringent documentation requirements, driving adoption of integrated pressure-test subassemblies.
Service contract unbundling is fragmenting traditional bundled perforating offerings into discrete component procurement. Independent operators in the Bakken now separately source gun carriers, shaped charges, and firing systems through direct manufacturer relationships. This pattern concentrates most visibly among cash-flow-focused producers seeking line-item cost transparency in multi-well pad developments.
US Perforating Gun Market Segmentation
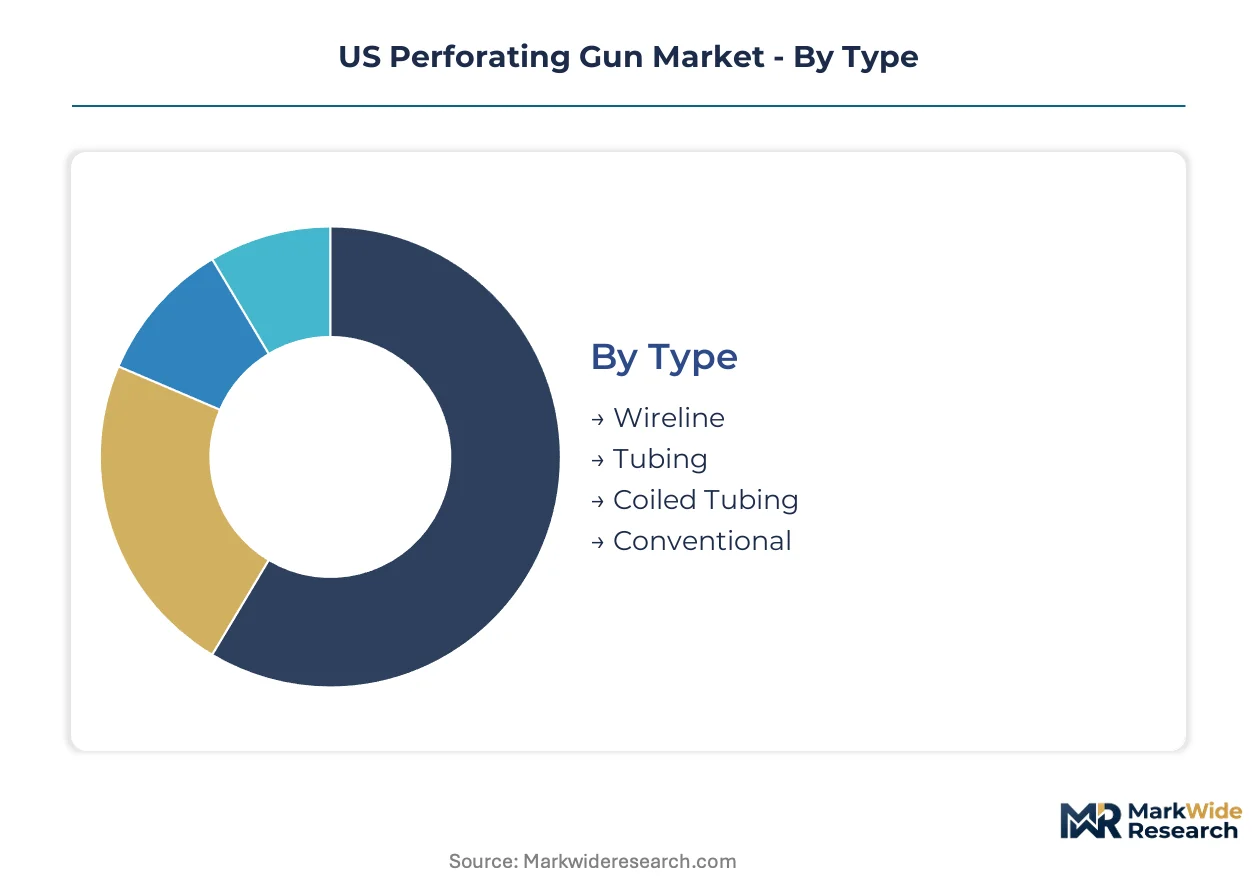
Perforating gun segmentation reveals how deployment methods, pressure environments, and operator economics fragment procurement patterns across US unconventional basins. Category boundaries increasingly blur as electric detonation and telemetry integration reshape traditional type and technology distinctions.
Type:
Mature wireline systems anchor volume while emerging coiled tubing configurations capture re-entry and extended-reach applications.
- Wireline:Conveyance via single-conductor or multi-conductor cable enables rapid plug-and-perf sequences in multi-stage horizontal completions. Permian Basin independents favor wireline for its 30-40% cost advantage over tubing-deployed alternatives in standard lateral geometries.
- Tubing:Conventional tubing-conveyed perforating (TCP) supports high-pressure deepwater and HPHT onshore applications where wireline ratings prove insufficient. Gulf of Mexico operators specify tubing systems for BSEE-mandated barrier verification in subsea completions.
- Coiled Tubing:CT-deployed guns access highly deviated wellbores where wireline reach fails.
- Conventional:Legacy through-tubing systems persist in vertical well workovers.
Wireline handles the majority of throughput; coiled tubing is the fastest mover on share.
Application:
Cost tier differentiation separates high-specification offshore systems from standardized onshore plug-and-perf hardware.
- Onshore:Multi-stage horizontal completions in shale basins drive repetitive deployment of disposable gun carriers rated for 15,000 psi. Bakken and Appalachian operators prioritize speed over reuse, compressing stage-to-stage cycle times below 45 minutes.
- Offshore:Subsea and platform-based completions demand redundant firing systems and integrated pressure-test subassemblies. BSEE well control standards add certification layers that inflate system costs 40-60% above comparable onshore specifications.
- Well Completion:Primary perforating during initial completion establishes formation communication.
- Workover:Remedial perforating repairs damaged casing or re-enters depleted zones.
Onshore commands absolute volume; offshore is climbing the fastest on margin contribution per system.
End User:
Customer type fragmentation concentrates procurement authority differently across integrated majors, independents, and service intermediaries.
- Oil & Gas Companies:Integrated majors and large independents with captive engineering staff specify gun systems directly. ExxonMobil and Chevron maintain approved vendor lists that lock out second-tier assemblers from their Permian and Gulf of Mexico programs.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes bundle perforating into integrated completion contracts. Their purchasing power forces gun component suppliers into multi-year framework agreements with 15-20% volume discounts.
- Independents:Privately held producers below 50,000 boe/day increasingly unbundle procurement.
- Operators:Lease operators and non-op working interest holders typically defer to drilling contractors.
Service providers handle the majority of throughput; independents are gaining share fastest through direct manufacturer relationships.
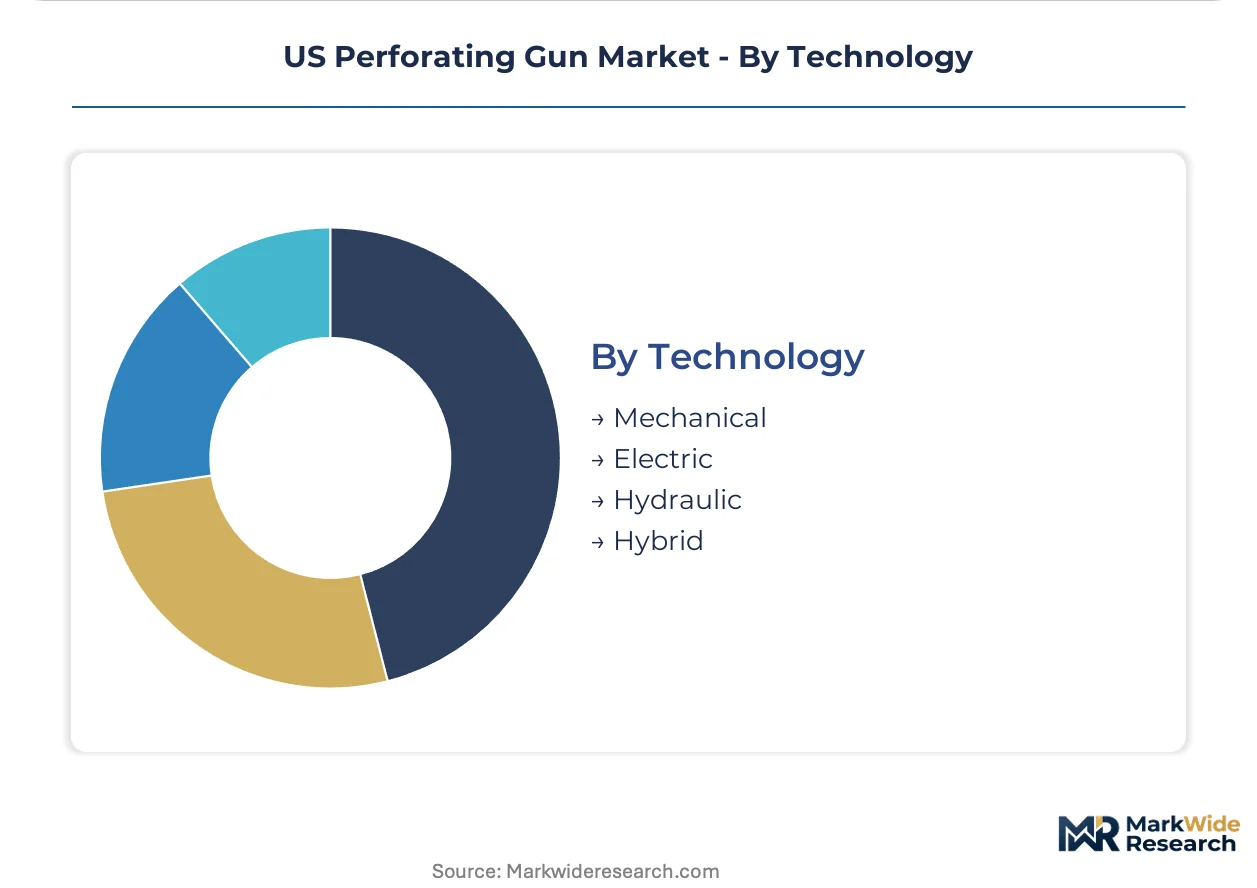
Technology:
Supply concentration among specialized detonation component producers shapes competitive access to electric and hybrid firing systems.
- Mechanical:Pressure-activated firing heads using bar drop or annulus pressure cycles face obsolescence as operators abandon imprecise depth correlation. Legacy inventory write-downs strand service companies with $20-40 million in non-electric gun stocks.
- Electric:Microprocessor-controlled addressable switches enable programmable firing sequences with sub-foot depth accuracy. Permian operators deploying electric systems report 60% reduction in misfire rates compared to mechanical alternatives.
- Hydraulic:Fluid-activated detonation persists in high-temperature environments above 400°F.
- Hybrid:Dual-redundancy systems combining electric primary with mechanical backup address regulatory risk in critical offshore applications.
Electric handles the majority of newbuild demand; hybrid is expanding most quickly in offshore safety-critical installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across US basins, with Permian independents driving hard on per-stage costs while Gulf of Mexico majors absorb 40-60% premiums for certified systems. The analysis maps five sub-regions where deployment economics diverge.
Permian Basin
Multi-stage plug-and-perf operations consume disposable gun carriers at unmatched scale. Texas Railroad Commission flaring rules tighten zonal isolation mandates. Midland-Odessa service yards cluster reloading infrastructure within 50 miles of active pads.
Gulf of Mexico
Subsea completions demand redundant firing systems and integrated pressure-test subassemblies. BSEE barrier verification requirements inflate certification costs substantially. Houma-New Orleans corridor hosts specialized offshore gun system fabricators.
Bakken Formation
Extended-reach laterals exceeding 15,000 feet strain mechanical firing reliability. North Dakota Industrial Commission well integrity standards shape procurement specifications. Williston Basin service providers maintain rapid-deployment inventory for 24-hour stage cycles.
Appalachian Basin
Electric detonation systems capture share as operators abandon imprecise depth correlation. Pennsylvania Department of Environmental Protection methane monitoring rules favor tighter stage isolation. Pittsburgh-area engineering offices specify addressable switch technology for Marcellus completions.
Rocky Mountain Region
Higher-pressure formations in Wyoming and Colorado test conventional gun ratings. BLM venting and flaring regulations impose documentation burdens on federal lease operators. Denver-Julesburg Basin concentration drives regional logistics optimization for gun carrier delivery.
US Perforating Gun Market Key Industry Players
Capability concentration sits with specialized charge metallurgy producers; scale advantage sits with integrated service conglomerates bundling perforating into completion contracts. The market structures around three tiers: diversified energy majors with captive manufacturing, specialized gun system assemblers with ATF-certified infrastructure, and regional reload service providers capturing aftermarket revenue. Consolidation pressure intensifies as electric detonation standardization raises R&D minimums. Strategic moves center on backward integration into shaped-charge liner supply and geographic expansion of certified reloading facilities.
Within the integrated service tier, Baker Hughes Company, SLB, and Halliburton Company exemplify scale-driven positioning. These entities anchor procurement leverage through multi-year framework agreements forcing 15-20% volume discounts on component suppliers. Their captive engineering resources lock second-tier assemblers out of approved vendor lists for major Permian and Gulf of Mexico programs. Regional specialists occupy positions between these scale leaders and pure reload operators, typically serving independents below 50,000 boe/day with unbundled component sourcing.
| Leading Market Players |
|---|
| Baker Hughes Company |
| SLB |
| Halliburton Company |
| Weatherford International plc |
| NOV Inc. |
| DMC Global Inc. |
| Hunting PLC |
| DynaEnergetics |
| G&H Diversified Manufacturing |
| Others |
Cost & Logistics Intelligence
Undercapacity in domestic shaped-charge liner smelting drives supplier pricing power toward specialized metallurgy producers while forcing gun system assemblers toward long-term offtake commitments. Texas Railroad Commission flaring compliance costs and BSEE certification requirements fragment pricing tiers across onshore independents and offshore majors.
Pricing Analysis
Aftermarket charge reloading and refurbishment services now capture the dominant share of lifetime customer value, displacing one-time hardware margins. Three-tier pricing structure across premium certified systems, standard wireline configurations, and economy disposable carriers separates Gulf of Mexico operators from Permian independents and Bakken workover specialists. Pricing pressure stems from copper and tungsten input volatility as North American smelter constraints tighten raw material availability. Independent operators below 50,000 boe/day exhibit acute price sensitivity, driving unbundled component procurement, while integrated majors absorb premium tiers for BSEE-compliant barrier verification systems.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate supplier-finance arrangements as tier-one service companies leverage procurement scale against component assemblers. Shaped-charge liner production draws from China, Russia, and limited domestic specialty alloy foundries; gun carrier machining centers on Texas, Oklahoma, and Louisiana manufacturing corridors. Single-source vulnerability concentrates in tungsten powder supply for high-performance charges. Distribution runs through Midland-Odessa, Houma-New Orleans, and Williston Basin service yards that cluster reloading infrastructure within 50 miles of active drilling pads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric detonation standardization and EPA methane monitoring mandates are compressing legacy mechanical inventory values while opening premium pricing tiers for telemetry-integrated systems. This technological-regulatory inflection restructures competitive positioning across the value chain.
For Market Incumbents: Pre-empt stranded asset risk by accelerating electric firing head retrofit programs before mechanical inventory obsolescence deepens. Secure captive supply of shaped-charge liner capacity through backward integration or long-term offtake with domestic specialty alloy producers. ATF-certified storage infrastructure represents a defendable moat against emerging regional competitors facing 18-24 month licensing timelines.
For New Entrants and Emerging Players: Establish a beachhead in coiled tubing-deployed gun systems for re-entry workover applications where wellbore geometry limits incumbent wireline dominance. Target Appalachian Basin independents adopting addressable switch technology for Marcellus completions, where electric detonation penetration remains below Permian adoption curves. A direct manufacturer relationship model bypasses service company bundling and captures unbundled procurement flow from cash-flow-focused producers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional reload service providers with ATF-certified infrastructure and established relationships with sub-50,000 boe/day independents. Long-term viability hinges on exposure to extended-reach lateral growth rather than commodity price cyclicality. Watch Texas Railroad Commission enforcement patterns on flaring compliance as the signal for accelerated zonal isolation premium tier adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shaped-Charge Liner Supply | Captive metallurgy capacity insulates margins from copper-tungsten volatility and Chinese supply concentration. |
| ATF-Certified Reloading Facility Expansion | Geographic proximity to Permian and Bakken pads captures recurring refurbishment revenue from extended carrier life cycles. |
| Electric Detonation Technology Licensing | Addressable switch IP monetization accelerates displacement of mechanical firing systems across Appalachian shale. |
| Telemetry Integration Partnership | Real-time perforation optimization bundling with SLB or Baker Hughes completion contracts defends service provider channel access. |
| Hybrid Redundancy System Certification | BSEE-mandated barrier verification compliance opens Gulf of Mexico premium pricing tiers with 40-60% margin elevation. |
Research Approach
A spread of perspectives from completion engineers at Permian independents, wireline operations managers, ATF-licensed manufacturing facility directors, and BSEE regulatory compliance officers converged on the working assumptions. Primary field interviews combined with secondary validation from EIA drilling productivity reports, Texas Railroad Commission flaring enforcement records, BSEE well control incident databases, and SEC 10-K disclosures from listed service companies. Bottom-up rig-count and stage-count modeling triangulated against top-down market size estimates from trade association shipment data.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation across deployment type, pressure rating tier, detonation technology, and basin-specific regulatory cluster. CAGRs derived from production growth trajectories in the Permian, Bakken, and Appalachian basins layered against stage intensity per well and gun system replacement rates. Forecast inputs incorporated EPA methane rule implementation timing and electric detonation adoption curves by operator size class.
Stress conditions across copper-tungsten price volatility, ATF licensing approval delays, and BSEE regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about lateral length extension rates and stage count growth. Macroeconomic oil price deviation, accelerated electrification mandates, or breakthrough perforating alternative technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Recoilless Rifle Market