
 Weapon Night Sight Market | 2026-2036
Weapon Night Sight Market Size, Share, and Industry Trends Forecast 2026-2036
Weapon Night Sight Market Outlook
Aftermarket sensor calibration and tube refurbishment is tilting margin pools away from original equipment manufacturing. L3Harris Technologies leverages captive supply chains for image intensifier tubes to sustain pricing power in military contracts. Elbit Systems anchors its position through backward integration into thermal core production. Teledyne FLIR competes on detector array scale, dominating cooled and uncooled thermal sensor output for weapon-mounted applications.
A weapon night sight is an electro-optical aiming device that amplifies ambient light or detects infrared radiation to enable target acquisition in near-total darkness, typically employing gallium arsenide photocathodes or vanadium oxide microbolometers operating at refresh rates exceeding 50 Hz for dynamic engagement scenarios. Thermal optics command premium positioning due to their passive operation and all-weather utility, while image intensification retains volume leadership in infantry rifle applications where weight and power constraints dominate. Digital night vision represents the fastest-expanding technology segment as solid-state sensors displace vacuum tube architectures in law enforcement and civilian shooter channels.
ITAR controls in the United States, the EU Green Deal's emerging restrictions on hazardous substances in optical components, and ISO 9001 quality management certifications collectively shape product standards and cross-border market access for night sight manufacturers. Procurement officers must weigh thermal versus image intensification trade-offs against evolving export control classifications and sustainability compliance mandates as they structure multi-year acquisition programs.
Market Dynamics
The weapon night sight market pivots on vacuum tube supply scarcity, which is forcing procurement officers toward solid-state thermal and digital architectures faster than planned obsolescence cycles would naturally dictate.
Growth Catalysts
- NATO Defense Acquisition Frameworks:Revised procurement protocols across alliance member states mandate thermal optics integration for infantry modernization programs, creating institutional demand pull.
- EU Green Deal Restrictions:Emerging hazardous substance limits on optical component manufacturing are accelerating investment in mercury-free photocathode alternatives and lead-free solder processes.
- Gallium Arsenide Photocathodes:Extended wavelength sensitivity in third-generation image intensification is preserving relevance for special operations units requiring passive night vision without thermal signature.
Market Restraints
- Image Intensifier Tube Concentration:Manufacturing capacity clusters in the United States, Germany, and Israel create single-source vulnerability for NATO-aligned militaries.
- ITAR Classification Friction:United States export controls on thermal core technology delay foreign military sales by 12-18 months, compressing contract award velocity.
- Vanadium Oxide Microbolometer Cost Structure:Uncooled thermal detector substrates remain 3-4x the unit cost of legacy image intensification tubes at equivalent resolution tiers.
Strategic Opportunities
- Law Enforcement Digital Transition:Civilian and police channels in Germany and France show underpenetrated demand for solid-state night vision as tube refurbishment costs escalate.
- Convergence of Augmented Reality Overlays:Integration of ballistic calculators and range-finding data streams into thermal weapon sights creates premium positioning for integrated fire-control ecosystems.
- Indian PLI Scheme Alignment:Production-linked incentives for defense electronics manufacturing attract foreign OEMs to establish local thermal core assembly for export to Southeast Asian militaries.
Industry Challenges
- ISO 9001 Certification Bottlenecks:Quality management audit backlogs at accredited bodies delay supplier qualification for multi-year military contracts by 6-9 months.
- Legacy System Integration Complexity:Digital night sight retrofit into existing weapon platforms requires mechanical interface redesign, driving non-recurring engineering costs that erode margin on initial production lots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapon Night Sight Market |
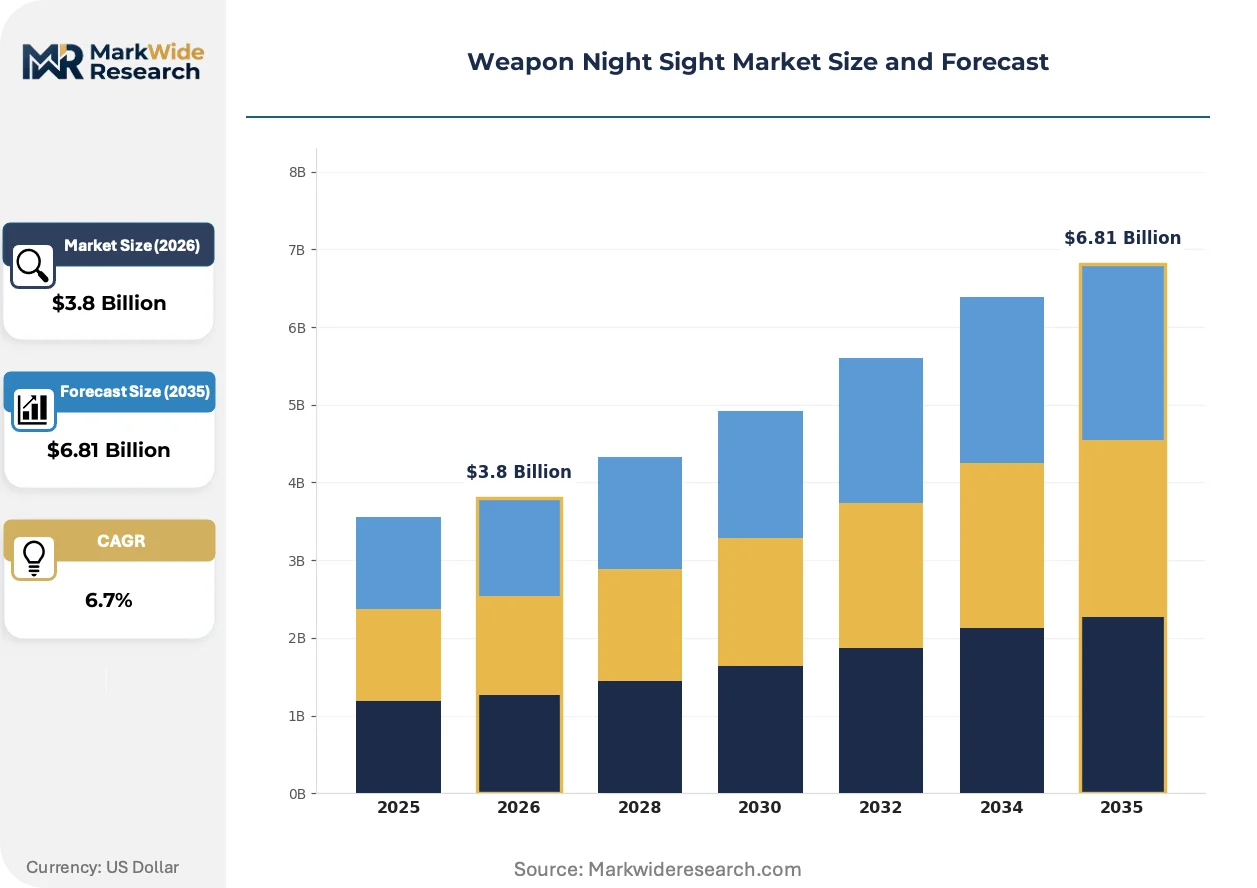
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Dot Sight, Scope, Laser Sight, Thermal Optics Technology: Infrared, Digital, Image Intensification, Night Vision End User: Military, Law Enforcement, Hunters, Civilian Shooters Distribution Channel: Retail Stores, Online Sales, Direct Sales, Distributors |
| Companies Covered | L3Harris Technologies, Inc., BAE Systems Plc, Thales Group, Elbit Systems Ltd., Raytheon Technologies Corporation, Teledyne FLIR LLC, Excelitas Technologies Corp., Rheinmetall AG, Trijicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapon Night Sight Market Strategic Shifts
Solid-state sensor architectures are compressing technology generations from decade-long cycles to 3-4 year refresh intervals, while regulatory sustainability mandates and procurement model fragmentation reshape competitive positioning.
Digital night vision based on CMOS and sCMOS sensors is rendering obsolete vacuum tube image intensification in law enforcement and civilian precision shooting applications. Police tactical units in the United States and Germany are accelerating adoption despite higher upfront unit costs. The shift is compressing aftermarket refurbishment revenue pools that historically sustained tube manufacturers between replacement cycles.
REACH and RoHS substance restrictions in Europe are forcing reformulation of optical glass dopants and photocathode deposition chemistries. Manufacturers serving NATO markets must dual-source compliant and non-compliant supply chains. German and French defense primes are responding by vertically integrating optical component production to isolate regulatory risk.
Multi-year performance-based sustainment contracts are displacing transactional spare parts purchasing in military channels. United States Army and Marine Corps procurement offices now bundle sensor calibration, tube replacement, and firmware updates into single-vendor agreements. This consolidation favors suppliers with captive service networks over component specialists lacking forward deployment capabilities.
Weapon Night Sight Market Segmentation
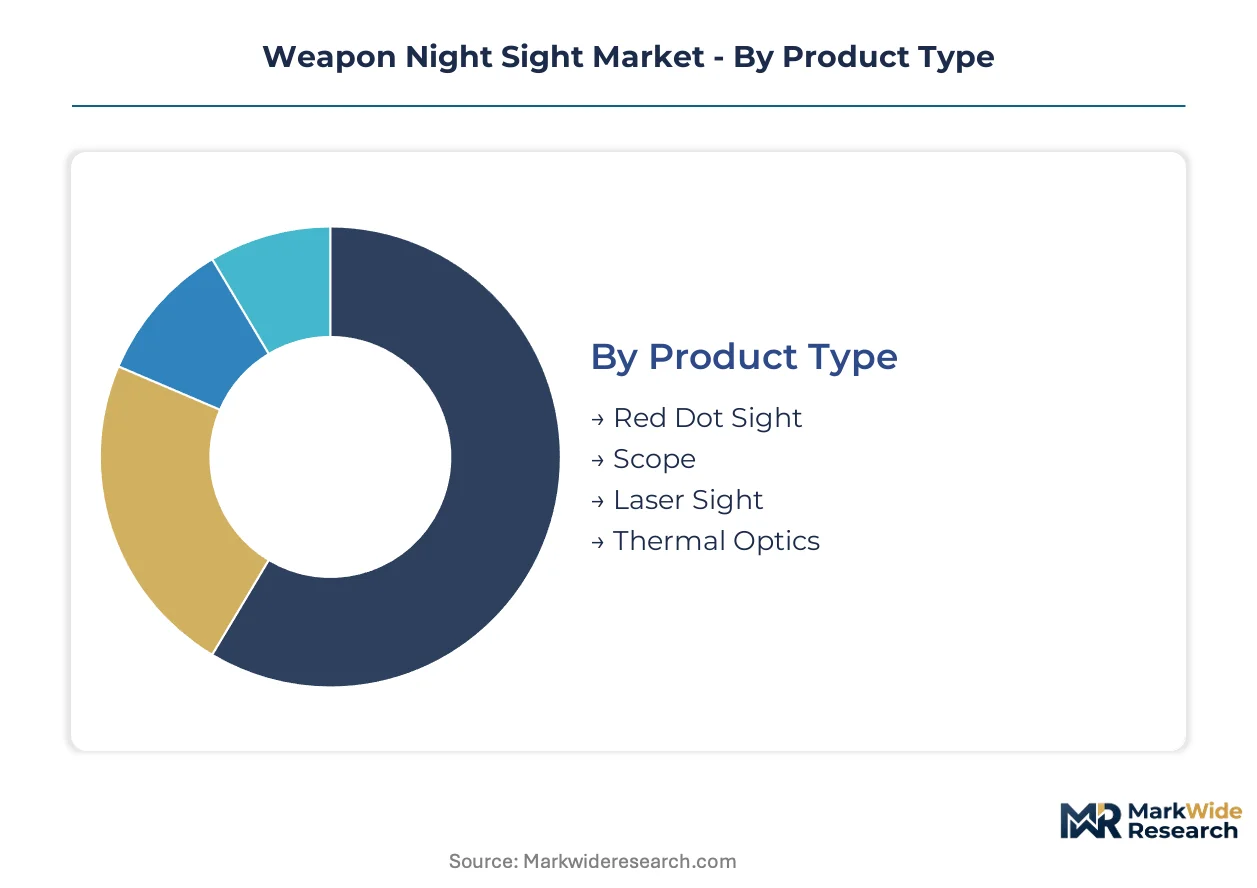
Weapon night sight procurement divides sharply between institutional buyers with decade-long replacement cycles and civilian channels where technology turnover compresses to 3-4 years. Understanding these velocity differentials shapes inventory positioning and R&D resource allocation across manufacturer portfolios.
Product Type:
Thermal optics and legacy scopes operate on 8-12 year military refresh schedules, while red dot sights and laser sights turn over fastest in law enforcement channels as battery and emitter technologies improve.
- Thermal Optics:Vanadium oxide microbolometer arrays detect infrared radiation without active illumination, enabling passive target engagement in complete darkness. NATO infantry modernization programs in Germany, France, and Poland are concentrating procurement volumes here despite 3-4x cost premiums over image intensification, driven by all-weather reliability mandates.
- Scope:Variable-magnification optical platforms integrate image intensifier tubes or digital sensors for precision rifle applications. The United States Marine Corps and British Army sustain replacement demand through sniper system upgrades, though tube supply constraints are elongating lead times.
- Red Dot Sight:LED-illuminated reflex optics dominate close-quarters combat configurations with sub-200 gram weight profiles and 50,000-hour battery life.
- Laser Sight:Visible and infrared aiming modules attach to pistol and carbine rails for rapid target acquisition in urban environments.
Thermal optics dominate installed base value. Red dot sights are where expansion concentrates in volume terms.
Technology:
Cost tier stratification separates vacuum tube architectures from solid-state alternatives, with digital sensors commanding premium positioning in law enforcement while image intensification retains economy-tier military volume.
- Image Intensification:Gallium arsenide photocathodes amplify ambient light through multi-stage vacuum tubes, achieving 2,000+ f-stop equivalent gain. United States and Israeli manufacturing clusters supply NATO militaries under ITAR-controlled frameworks, with refurbishment demand sustaining aftermarket revenue pools.
- Digital:CMOS and sCMOS sensors capture near-infrared wavelengths with onboard image processing for contrast enhancement. German and French police tactical units are driving adoption despite higher unit costs, as solid-state reliability eliminates tube replacement logistics.
- Infrared:Active illumination systems project near-infrared light invisible to unaided human vision.
- Night Vision:Broad category encompassing both image intensification and digital architectures in consumer-facing nomenclature.
Image intensification dominates installed base. Digital technology is climbing the fastest in law enforcement procurement.
End User:
Customer type determines specification rigor, with military buyers demanding MIL-STD-810G environmental certification while civilian shooters prioritize weight minimization and smartphone integration.
- Military:Infantry modernization programs across NATO specify thermal optics for squad-level distribution, with multi-year performance-based sustainment contracts bundling calibration, tube replacement, and firmware updates. United States Army procurement offices now require vendor-managed inventory for forward-deployed units.
- Law Enforcement:SWAT and counter-terrorism units in Germany and France are accelerating solid-state adoption as tube refurbishment costs escalate and liability concerns mount around mercury-containing photocathodes under REACH restrictions.
- Hunters:Game management regulations in multiple jurisdictions restrict infrared illumination, channeling demand toward passive technologies.
- Civilian Shooters:Precision rifle competitors and home defense purchasers drive volume in digital night vision through online channels.
Military end users dominate installed base. Law enforcement is gaining share fastest as digital reliability eliminates maintenance burden.
Distribution Channel:
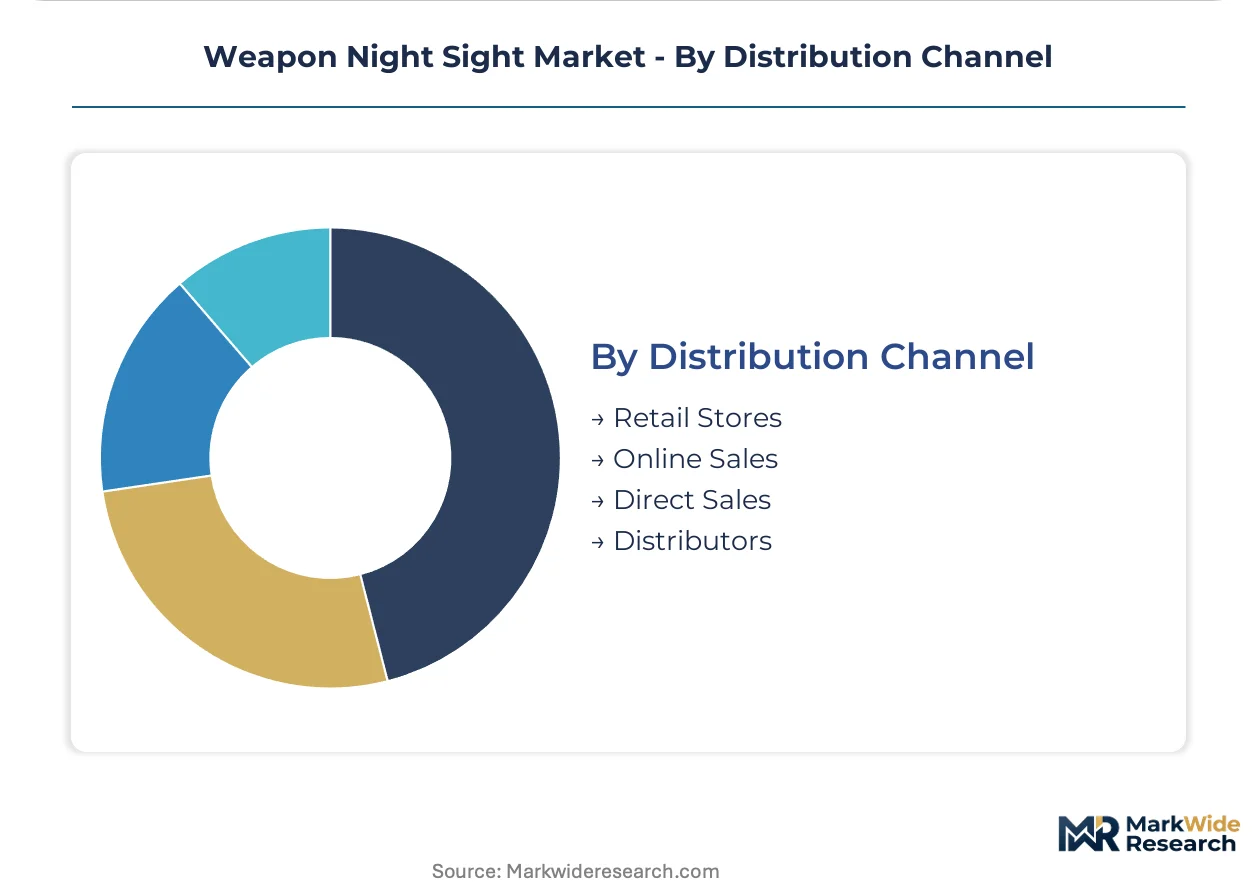
Supply concentration varies by channel, with direct sales capturing institutional program value while online platforms fragment civilian price discovery.
- Direct Sales:Prime contractors negotiate multi-year framework agreements with defense ministries, embedding sensor calibration and technical refresh cycles into single-vendor relationships. L3Harris Technologies and Elbit Systems anchor this channel through captive service networks.
- Distributors:Regional defense specialists manage ITAR compliance and local certification for foreign military sales, absorbing 12-18 month export control delays.
- Online Sales:E-commerce platforms serve law enforcement and civilian segments with rapid fulfillment.
- Retail Stores:Specialty firearms dealers provide hands-on evaluation for hunting and recreational shooting customers.
Direct sales dominate installed base value. Online channels are expanding most quickly in civilian and law enforcement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. NATO militaries prioritize thermal optics for all-weather reliability, while law enforcement in Western Europe accelerates digital adoption to circumvent tube refurbishment logistics.
United States
Army and Marine Corps infantry modernization programs drive thermal optics procurement under multi-year performance-based sustainment contracts. ITAR classification frameworks delay foreign military sales by 12-18 months, compressing contract velocity. Huntsville, Alabama and Dallas-Fort Worth host concentrated defense electronics manufacturing clusters serving domestic demand.
Germany
Bundeswehr sniper system upgrades and police SWAT unit procurement sustain replacement demand for precision rifle optics. REACH substance restrictions on mercury-containing photocathodes accelerate investment in mercury-free alternatives. Oberkochen and Wetzlar anchor optical component production with vertically integrated supply chains isolating regulatory risk.
Israel
Special operations units demand gallium arsenide photocathodes for passive night vision without thermal signature. Ministry of Defense procurement frameworks emphasize backward integration into thermal core production. Haifa and Beersheba concentrate electro-optics manufacturing serving domestic and export markets.
India
Army infantry modernization and counter-insurgency operations generate institutional demand for weapon-mounted thermal sights. Production-linked incentive schemes for defense electronics attract foreign OEMs to establish local thermal core assembly. Bengaluru and Hyderabad emerge as assembly hubs for Southeast Asian military exports.
France
Gendarmerie and police tactical units accelerate solid-state adoption as tube refurbishment costs escalate under emerging hazardous substance limits. ANSM oversight shapes quality management certification requirements for defense suppliers. Paris-Saclay and Grenoble host research clusters advancing CMOS sensor architectures for law enforcement applications.
Weapon Night Sight Market Competitive Environment
Capability concentration sits with tube manufacturing specialists; scale advantage sits with thermal detector array producers. The market structures around three tiers: defense primes with captive service networks, component specialists with ISO 9001 bottlenecks, and emerging digital entrants. Dominant competitive moves include backward integration into thermal core production and consolidation of aftermarket calibration services into single-vendor agreements.
Within the defense prime tier, L3Harris Technologies, Inc. and Elbit Systems Ltd. exemplify contrasting supply chain strategies. L3Harris anchors its position through captive supply of image intensifier tubes, sustaining pricing power in military contracts. Elbit Systems occupies a position emphasizing in-house production of thermal cores. Teledyne FLIR LLC represents the scale-driven archetype, dominating cooled and uncooled thermal sensor output for weapon-mounted applications through detector array manufacturing scale.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| BAE Systems Plc |
| Thales Group |
| Elbit Systems Ltd. |
| Raytheon Technologies Corporation |
| Teledyne FLIR LLC |
| Excelitas Technologies Corp. |
| Rheinmetall AG |
| Trijicon |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on gallium arsenide photocathode manufacturing in the United States, Germany, and Israel compresses pricing power toward tube suppliers while forcing procurement officers into multi-year offtake commitments that widen tier spreads between captive-integrated primes and component-dependent specialists.
Pricing Analysis
Long-term performance-based sustainment contracts dominate military procurement, bundling sensor calibration, tube refurbishment, and firmware refresh cycles into single-vendor agreements that compress spot-market liquidity. Price differentiation rests on ISO 9001 certification tier and captive service network coverage, with uncooled thermal arrays commanding 3-4x premiums over legacy image intensification at equivalent resolution tiers. Cost compression in law enforcement digital segments is intensifying because solid-state reliability eliminates maintenance burden, making police buyers more price-sensitive than military procurement offices.
Supply Chain Analysis
Tariff exposure between the United States and NATO-aligned European militaries dominates supply chain risk through ITAR-controlled thermal core technology that delays foreign military sales. Manufacturing gravity centers on Huntsville, Dallas-Fort Worth, Oberkochen, Wetzlar, Haifa, and Beersheba for image intensifier tubes and thermal detector arrays. Raw material dependencies span gallium arsenide substrates, vanadium oxide microbolometer wafers, and mercury-free photocathode chemistries responding to REACH restrictions. Distribution runs through prime contractor direct sales for institutional buyers and regional defense distributors managing export compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket sensor calibration and tube refurbishment is expanding faster than original equipment manufacturing, converting hardware transactions into recurring revenue streams that reward captive service infrastructure.
For Market Incumbents:Entrench position by deepening backward integration into thermal core production and consolidating ISO 9001-certified refurbishment capacity into forward-deployed service networks. Digital night vision entrants threaten tube-dependent revenue pools; respond by locking military buyers into decade-long sustainment contracts with vendor-managed inventory clauses.
For New Entrants and Emerging Players:Pursue white-space opportunity in German and French law enforcement digital night vision procurement, where REACH-driven mercury photocathode restrictions and escalating refurbishment costs create substitution demand. Target police SWAT units through solid-state reliability messaging and rapid fulfillment via online channels with domestic certification support.
For Investors and Strategic Acquirers:Component specialists with captive gallium arsenide tube supply or vanadium oxide microbolometer fabrication represent the priority acquisition archetype, as manufacturing scarcity concentrates margin capture upstream. Watch for Indian PLI scheme alignment announcements as inflection indicators for Southeast Asian export hub formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Core Production | Elbit Systems and L3Harris anchor military pricing power through in-house vanadium oxide and photocathode supply. |
| Performance-Based Sustainment Contracting | United States Army and Marine Corps bundle calibration and firmware updates, displacing transactional spare parts purchasing. |
| Mercury-Free Photocathode Development | German and French primes isolate REACH regulatory risk through vertically integrated optical component reformulation. |
| Digital Night Vision Platform Launch | CMOS and sCMOS sensor architectures displace vacuum tubes in law enforcement channels with 3-4 year refresh cycles. |
| Indian PLI Scheme Manufacturing Footprint | Foreign OEMs establish Bengaluru and Hyderabad assembly hubs for Southeast Asian military export qualification. |
Study Parameters
Operator-level perspectives from military procurement officers, defense prime contract managers, thermal core manufacturing engineers, and law enforcement equipment coordinators anchored the qualitative base. Primary interview insights combined with secondary validation from NATO defense acquisition framework documents, ITAR classification bulletins, EU Green Deal substance restriction drafts, and ISO 9001 accreditation body records. Bottom-up unit economics for tube refurbishment and thermal detector array production triangulated against top-down military budget allocation data.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling technology substitution curves between image intensification and digital architectures alongside end-user segmentation by military, law enforcement, and civilian channels. CAGRs derived from procurement cycle analysis and technology refresh interval compression. Industry-specific forecast inputs included gallium arsenide photocathode manufacturing capacity constraints and REACH-compliant optical glass dopant availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state sensor entrants or rapid ITAR classification relaxation would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market