
 Precision Guided Munition Market | 2026-2036
Precision Guided Munition Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Guided Munition Market Analysis
Export-credit-backed leasing arrangements for precision munition production lines are reshaping which defense contractors can sustain long-term manufacturing commitments. Lockheed Martin leverages captive financing structures to anchor multi-year guided artillery contracts without immediate capital outlay. RTX Corporation sustains competitive positioning through backward integration into seeker manufacturing. Boeing navigates tighter foreign military sale credit windows by partnering with host-nation infrastructure banks.
Precision guided munitions are weapons that incorporate terminal guidance subsystems—typically combining GPS receivers, laser seekers, or inertial measurement units with aerodynamic control surfaces—to achieve circular error probable below ten meters against designated coordinates. These systems serve the primary purpose of reducing collateral damage while enabling single-sortie destruction of hardened or time-sensitive targets. The weapon type dimension shows air-to-ground missiles retaining the largest revenue share due to fighter-bomber fleet modernization cycles, while guided artillery munitions represent the fastest-expanding category as armies replenish depleted stockpiles. Within guidance technology, GPS guidance dominates procurement volumes but imaging infrared systems command premium pricing for all-weather precision requirements.
The U.S. Department of Defense, NATO Standardization Office, and the U.S. State Department's Directorate of Defense Trade Controls collectively shape market access through end-use monitoring agreements and technology transfer protocols. ITAR compliance requirements restrict component sourcing and foreign partnership structures for non-U.S. entities. Stakeholders must monitor evolving congressional export control amendments and allied burden-sharing agreements to anticipate production allocation shifts between domestic and co-development programs.
Market Dynamics
Defense ministries are compressing procurement cycles for GPS-guided artillery shells after stockpile depletion revealed vulnerabilities in sustained precision strike capacity.
Growth Catalysts
- ITAR modernization protocols:The U.S. State Department's Directorate of Defense Trade Controls streamlined licensing for allied co-production, accelerating technology transfer to NATO partners.
- Artillery stockpile replenishment:European armies are procuring guided 155mm rounds at volumes unseen since the Cold War, driven by operational lessons from Eastern Europe.
- Dual-mode seeker fusion:Imaging infrared plus GPS guidance combinations are displacing single-mode systems in all-weather strike missions.
Market Restraints
- Seeker component concentration:U.S. and Israeli suppliers control 90% of precision seeker manufacturing, creating chokepoints for non-allied nations.
- Rare earth magnet dependency:Chinese processing dominance for neodymium and dysprosium exposes guidance actuator supply chains to export restriction risk.
- End-use monitoring requirements:Congressional amendments to the Arms Export Control Act impose custody-chain documentation burdens that extend contract negotiation timelines.
Strategic Opportunities
- Indigenous production incentives:Poland's technical modernization fund subsidizes domestic guided munition assembly lines, reducing import dependency.
- Loitering munition convergence:Turbojet propulsion plus electro-optical guidance integration creates a new category between missiles and drones.
- Export-credit leasing structures:Host-nation infrastructure banks now back production line investments, lowering capital barriers for emerging suppliers.
Industry Challenges
- Seeker calibration technician shortage:Precision optics alignment requires specialized labor pools concentrated in three U.S. defense clusters.
- ITAR compliance audit complexity:Multi-tier supplier networks trigger documentation requirements that extend program milestone approvals.
- Legacy fuse integration friction:New guidance electronics must interface with Vietnam-era bomb bodies, creating software-hardware mismatch risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Guided Munition Market |
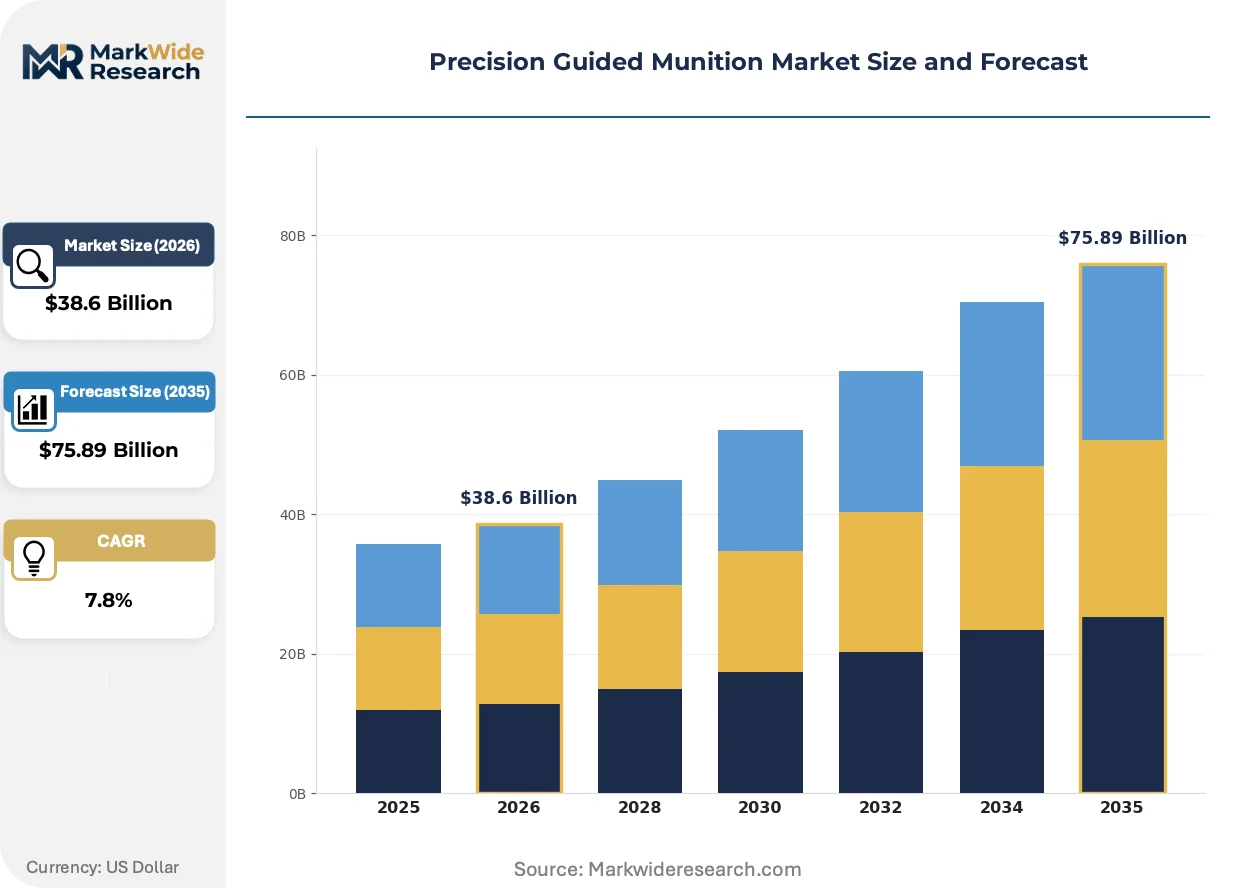
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Air-to-Ground Missiles, Precision-Guided Bombs, Naval Strike Weapons, Guided Artillery Munitions End User: Military Forces, Defense Contractors, Government Agencies, Law Enforcement Guidance Technology: GPS Guidance, Laser Guidance, Inertial Navigation, Imaging Infrared Platform: Aircraft, Naval Vessels, Ground Vehicles, Drones |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, Boeing, General Dynamics Corporation, BAE Systems, MBDA, Israel Aerospace Industries, Aselsan AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Guided Munition Market Emerging Trajectories
Terminal guidance architectures are fragmenting across mission profiles, with seeker technology migrating from single-sensor dependence toward fused multi-mode systems.
Multi-spectral seeker technology is migrating from laboratory demonstration to operational deployment. Fighter-bomber squadrons in the United States and United Kingdom are fielding combined GPS-laser-infrared systems for contested electromagnetic environments. This convergence is compressing the circular error probable threshold below three meters while complicating countermeasure design for adversary air defense networks.
REACH chemical restrictions and EU conflict minerals regulations are forcing seeker manufacturers to document supply chain provenance for tantalum capacitors and germanium lenses. German and French defense contractors face compliance deadlines that accelerate substitution of Chinese-sourced rare earth components. The guided artillery segment bears the highest compliance burden due to volume procurement and multi-national assembly requirements.
Buyer concentration among NATO procurement agencies is consolidating contract awards into multi-year framework agreements. Small-batch testing orders are disappearing as ministries commit to decade-long stockpile rotations. This pattern is most pronounced in the United States, where congressional defense appropriations now prioritize munitions industrial base capacity over platform acquisition.
Precision Guided Munition Market Segmentation
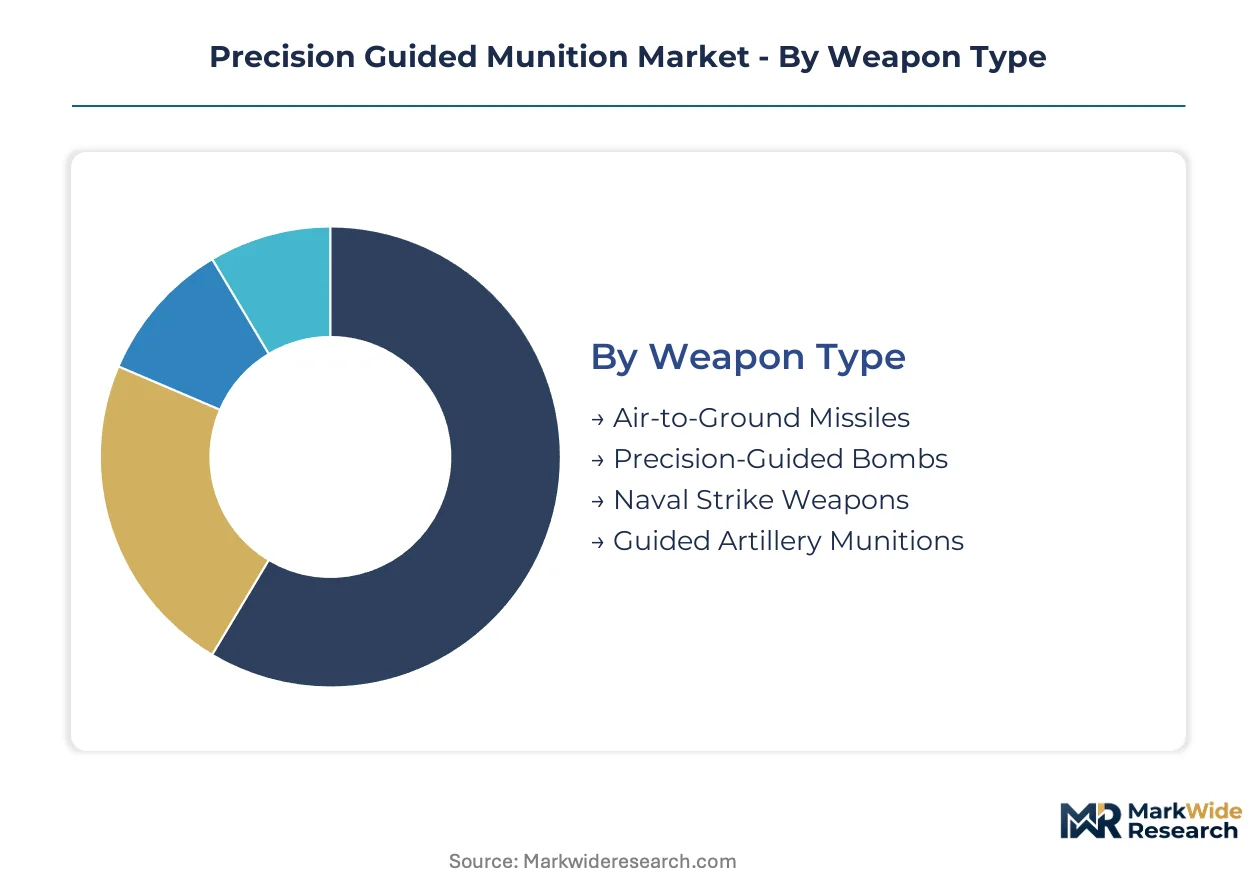
Precision guided munition procurement patterns diverge sharply across weapon categories, guidance architectures, and operational platforms. Defense ministries allocate budgets differently when replenishing artillery stockpiles versus modernizing fighter-bomber arsenals. Understanding these segment boundaries clarifies where manufacturing capacity constraints and technology transfer bottlenecks concentrate.
Weapon Type:
Cost tier stratification separates volume artillery procurement from premium missile systems requiring seeker miniaturization.
- Air-to-Ground Missiles:These weapons integrate multi-mode seekers with turbojet or rocket propulsion for standoff engagement of hardened targets. Fighter-bomber fleet modernization cycles in the United States and United Kingdom concentrate demand for extended-range variants with data-link midcourse updates.
- Guided Artillery Munitions:GPS-guided 155mm rounds and rocket-assisted projectiles now dominate European procurement budgets following Eastern European operational lessons. Volume requirements strain seeker manufacturing capacity across NATO supply chains.
- Precision-Guided Bombs:JDAM-class kits retrofitting Vietnam-era bomb bodies represent the lowest unit-cost precision strike option. Integration friction between legacy fuses and modern guidance electronics creates software-hardware mismatch risks in field deployment.
- Naval Strike Weapons:Anti-ship and land-attack cruise missiles for surface combatants require all-weather seekers and over-the-horizon targeting architectures. Procurement concentrates in Pacific-facing navies prioritizing contested maritime environment capabilities.
Air-to-Ground Missiles holds installed capacity. Guided Artillery Munitions is rotating up the share rankings.
End User:
Customer type determines contract structure complexity, from ITAR-governed foreign military sales to domestic law enforcement procurement waivers.
- Military Forces:Army, air force, and naval aviation units across NATO member states drive volume demand for replenished stockpiles and next-generation precision systems. Congressional defense appropriations in the United States prioritize munitions industrial base capacity over platform acquisition.
- Defense Contractors:Prime integrators and subsystem suppliers procure guidance kits and seeker components for assembly into complete weapon systems. RTX Corporation maintains backward integration into seeker manufacturing to secure component supply.
- Government Agencies:National laboratories and test ranges acquire precision munitions for evaluation, demilitarization research, and counter-proliferation technology assessment. End-use monitoring requirements impose custody-chain documentation burdens extending contract timelines.
- Law Enforcement:Specialized tactical units procure limited quantities of precision breaching and standoff engagement systems under restricted licensing protocols. ITAR compliance audits for small-batch orders often exceed the administrative cost of the procurement itself.
Military Forces command the procurement volume. Defense Contractors is climbing the fastest as co-production arrangements expand.
Guidance Technology:
Application environment dictates seeker architecture selection, from open-sky GPS dependence to contested electromagnetic spectrum operations.
- GPS Guidance:Satellite-dependent navigation with anti-jam processing dominates procurement volumes for artillery and general-purpose bomb kits. Chinese rare earth processing dominance for guidance actuator magnets exposes supply chains to export restriction risk.
- Imaging Infrared:Passive thermal imaging seekers command premium pricing for all-weather precision requirements and countermeasure-resistant terminal engagement. Fighter-bomber squadrons field combined GPS-laser-infrared systems for contested electromagnetic environments.
- Laser Guidance:Semi-active laser seekers require target designation from airborne or ground-based designators, limiting employment to clear-weather scenarios with line-of-sight constraints. Designator platform availability restricts operational flexibility compared to autonomous GPS modes.
- Inertial Navigation:Self-contained gyroscopic and accelerometer-based guidance provides GPS-denied backup navigation and short-duration precision for high-g maneuvers. Seeker calibration technician shortages concentrated in three United States defense clusters constrain production scaling.
GPS Guidance holds installed capacity. Imaging Infrared is gaining share fastest as multi-mode fusion architectures proliferate.
Platform:
Volume deployment scales differently across air, surface, and unmanned platforms, with payload weight and launch dynamics shaping seeker specifications.
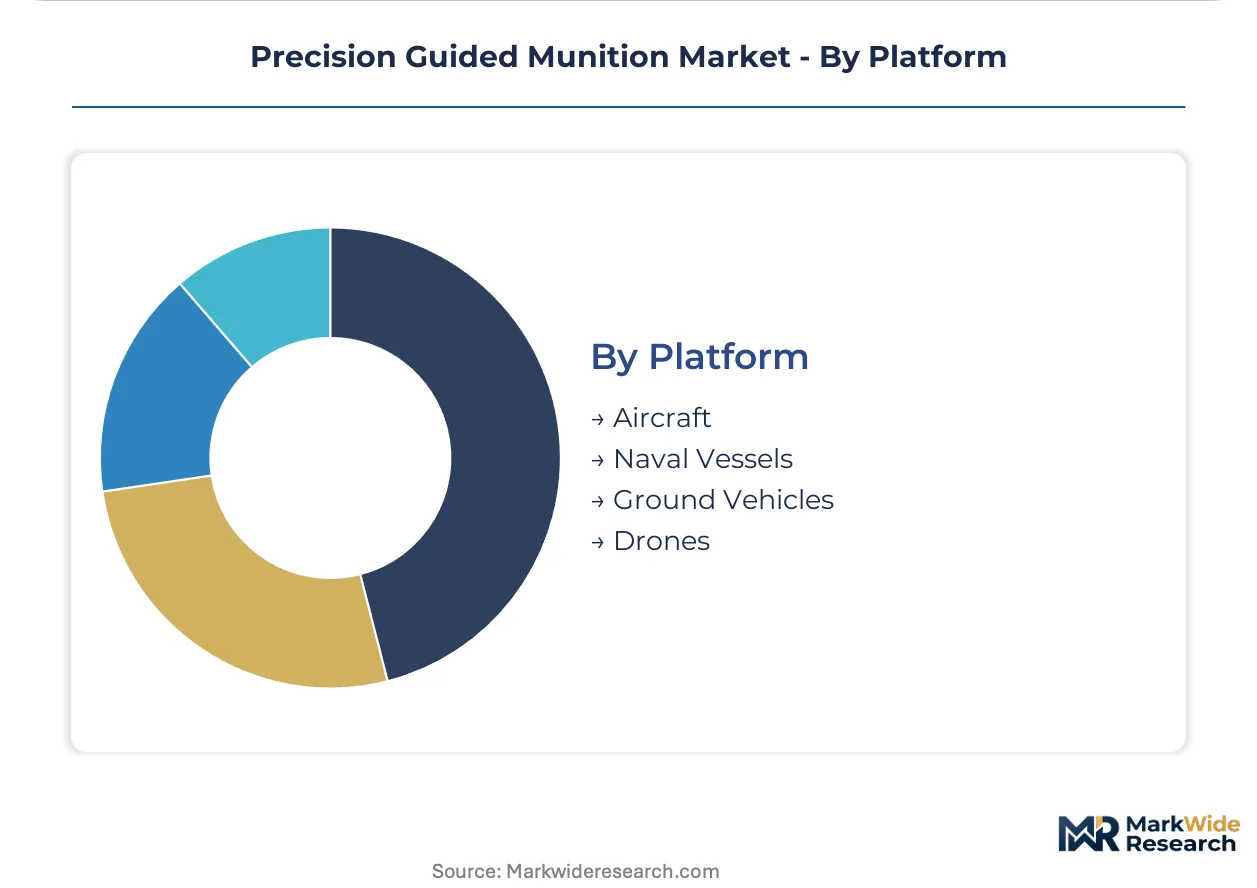
- Aircraft:Manned fighter-bombers and attack aircraft remain the primary deployment platform for air-to-ground missiles and precision-guided bombs. Payload capacity and cockpit integration requirements drive form-factor standardization across NATO air forces.
- Drones:Remotely piloted aircraft and autonomous systems are expanding precision munition carriage for persistent surveillance-strike operations. Loitering munition convergence between missiles and drones creates a new category with turbojet propulsion plus electro-optical guidance.
- Ground Vehicles:Self-propelled howitzers and multiple launch rocket systems deploy guided artillery munitions with automated loading and fire-control integration. Polish technical modernization fund subsidies now support domestic guided munition assembly lines reducing import dependency.
- Naval Vessels:Surface combatants and submarines employ vertical launch and deck-mounted systems for naval strike weapons with over-the-horizon targeting. Magazine capacity constraints favor compact seekers and booster-separated configurations.
Aircraft holds installed capacity. Drones is rotating up the share rankings as autonomous engagement architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States defense procurement, where congressional appropriations prioritize munitions industrial base capacity, while European buyers face compressed negotiation timelines amid urgent stockpile replenishment demands.
United States
The Department of Defense accelerates precision strike modernization mandates through multi-year framework agreements. The Directorate of Defense Trade Controls streamlines ITAR licensing for allied co-production. Defense clusters in Arizona, Florida, and Texas anchor seeker calibration technician pools concentrated across three metropolitan areas.
Germany
The Bundeswehr procures guided 155mm rounds at Cold War-era volumes following Eastern European operational assessments. REACH chemical restrictions and EU conflict minerals regulations force documentation of tantalum capacitor provenance. Industrial concentration in Bavaria and Baden-Württemberg hosts subsystem integrators adapting to rare earth substitution deadlines.
Poland
The technical modernization fund subsidizes domestic guided munition assembly lines to reduce NATO import dependency. National procurement agencies commit to decade-long stockpile rotations rather than small-batch testing orders. Manufacturing investment clusters around Warsaw and the Silesian industrial corridor under host-nation infrastructure bank backing.
United Kingdom
Fighter-bomber squadrons field combined GPS-laser-infrared systems for contested electromagnetic environments. The UK Ministry of Defence participates in NATO Standardization Office protocols for seeker technology interoperability. Defense engineering capacity concentrates in Bristol and the Home Counties, supporting imaging infrared premium pricing for all-weather requirements.
Israel
Israeli suppliers control precision seeker manufacturing alongside United States entities, creating dual-source chokepoints for guidance component supply. Domestic procurement prioritizes dual-mode seeker fusion for countermeasure-resistant terminal engagement. Industrial activity clusters in Haifa and the central coastal plain, with captive financing structures enabling multi-year manufacturing commitments.
Precision Guided Munition Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in seeker manufacturing and guidance electronics. The vendor base concentrates around prime contractors with backward integration into critical subsystems, while smaller specialists occupy calibration and testing niches. Three archetypes dominate: vertically integrated primes with captive financing, seeker manufacturers with multi-mode fusion capabilities, and kit integrators bridging legacy ordnance with modern guidance. Competitive moves center on capacity expansion for artillery stockpile replenishment and strategic partnerships with host-nation infrastructure banks.
Among United States-based primes, Lockheed Martin Corporation and RTX Corporation exemplify contrasting integration strategies. Lockheed Martin leverages captive financing structures to anchor multi-year contracts without immediate capital outlay. RTX Corporation sustains competitive positioning through in-house production of seeker components. Boeing navigates tighter foreign military sale credit windows through partnerships with host-nation infrastructure banks, occupying a position between full integration and kit assembly.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| Boeing |
| General Dynamics Corporation |
| BAE Systems |
| MBDA |
| Israel Aerospace Industries |
| Aselsan AS |
| Others |
Supply Flow & Price Mechanics
Chinese processing dominance for neodymium and dysprosium funnels margin capture toward guidance actuator manufacturers with captive rare earth sourcing, while downstream integrators absorb volatility through multi-year framework agreements. This upstream chokepoint forces NATO procurement agencies into premium pricing for imaging infrared seekers with documented supply chain provenance.
Pricing Analysis
Configured-to-order pricing for multi-mode seeker systems commands spreads exceeding standard GPS-guided artillery kits by factors reflecting calibration labor scarcity and ITAR compliance documentation. Three-tier pricing structure across imaging infrared premium, dual-mode standard, and GPS-economy levels segments buyer budgets by mission criticality. Cost compression in guided artillery runs through volume procurement mandates as European armies consolidate decade-long stockpile rotations. Defense contractors show least price sensitivity for seeker miniaturization programs, while law enforcement tactical units face administrative costs exceeding hardware value on small-batch orders.
Supply Chain Analysis
Lockheed Martin, RTX Corporation, and Northrop Grumman hold captive seeker manufacturing capacity across Arizona, Florida, and Texas defense clusters. Component sourcing draws from Israeli precision optics suppliers and German tantalum capacitor fabricators subject to REACH compliance deadlines. Single-source vulnerability concentrates in U.S. and Israeli seeker manufacturing controlling ninety percent of precision guidance component supply. Distribution runs through Directorate of Defense Trade Controls licensing protocols for foreign military sales and NATO co-production arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as loitering munition convergence between missiles and drones creates subsystem supplier niches beyond traditional prime integrator dominance. Artillery stockpile replenishment demands are diversifying procurement channels beyond legacy framework agreements.
For Market Incumbents: Build captive financing moats through export-credit-backed leasing structures that anchor multi-year guided artillery contracts without immediate capital outlay. Add seeker calibration capacity in Warsaw and Silesian corridors to offset technician concentration risk in U.S. defense clusters. Lockheed Martin's captive financing approach and RTX Corporation's backward integration into seeker manufacturing illustrate defensive positioning against emerging kit integrators from Polish domestic production subsidies. For New Entrants and Emerging Players: Build out loitering munition subsystem supply targeting turbojet propulsion plus electro-optical guidance integration gaps between established missile and drone categories. Polish technical modernization fund subsidies represent the most penetrable entry point, with host-nation infrastructure bank backing lowering capital barriers for domestic assembly line investment. Partner with Bundeswehr procurement channels seeking rare earth substitution compliance for REACH-regulated tantalum capacitors. For Investors and Strategic Acquirers: Capital is best deployed toward seeker calibration specialists with multi-mode fusion capabilities and documented ITAR compliance infrastructure. Long-term viability hinges on positioning upstream of artillery stockpile replenishment cycles and dual-mode seeker displacement of single-mode systems. Monitor congressional export control amendments to the Arms Export Control Act as inflection indicators for production allocation shifts between domestic and co-development programs.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Mode Seeker Fusion Development | Combined GPS-laser-infrared systems command premium pricing from U.S. and UK fighter-bomber squadrons. |
| Backward Integration into Seeker Manufacturing | RTX Corporation's in-house component production secures supply against U.S.-Israeli supplier chokepoints. |
| Host-Nation Infrastructure Bank Partnerships | Boeing's credit window navigation enables foreign military sale execution amid tighter financing conditions. |
| Domestic Assembly Line Subsidization | Poland's technical modernization fund reduces NATO import dependency for guided 155mm round procurement. |
| REACH Compliance Substitution Programs | German and French contractors accelerate Chinese rare earth component replacement ahead of regulatory deadlines. |
Methodological Framework
A spread of perspectives from precision munition program managers, seeker calibration technicians, Directorate of Defense Trade Controls licensing officers, and NATO Standardization Office protocol engineers converged on the working assumptions. Secondary validation drew from congressional defense appropriations records, EU conflict minerals regulatory filings, SEC 10-K disclosures from prime contractors, and customs trade data for rare earth magnet flows. Bottom-up procurement volume estimates triangulated against top-down defense budget allocation analysis across the analysis window.
Demand-supply-balance framing modeled artillery stockpile replenishment rates against seeker manufacturing capacity constraints, with segmentation across weapon type, guidance technology, platform, and end user dimensions. CAGRs were derived from procurement commitment trajectories and production scaling limitations throughout the forecast period. Industry-specific inputs included ITAR licensing velocity, REACH chemical restriction phase-in schedules, and rare earth export policy sensitivity.
Sensitivities concentrate around congressional export control amendments, Chinese rare earth processing restrictions, and seeker calibration technician pool expansion rates. Forecasts reflect documented procurement commitments and announced capacity investments rather than speculative technology adoption curves. Quarterly review of Bundeswehr and Polish technical modernization fund disbursement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Anti-Tank Missile System Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Enclosed Smokeless Flares Market