
 Military Fuze Market | 2026-2036
Military Fuze Market Size, Share, and Industry Trends Forecast 2026-2036
Military Fuze Market Foresight
Defense procurement channels is fragmenting across multiple national stockpiles and bilateral offset agreements. L3Harris Technologies leverages its vertically integrated electronics foundry to sustain long-term supply contracts with US armed forces. Northrop Grumman anchors its position through advanced guidance integration for missile fuzes. JUNGHANS Microtec GmbH specializes in precision mechanical and electronic timing mechanisms for European ordnance programs.
A military fuze is an electromechanical or pyrotechnic device that initiates detonation of an explosive payload upon satisfying predetermined arming and firing conditions, typically incorporating accelerometers, radar proximity sensors, or mechanical clockwork with millisecond accuracy tolerances. Its primary purpose is to ensure weapon safety during handling and transport while delivering optimal lethality against hardened or area targets. Electronic fuzes command the dominant margin pool due to software-defined arming logic and compatibility with network-centric warfare architectures. Mechanical fuzes retain substantial volume in artillery shells where cost constraints and electromagnetic hardening requirements persist. Smart fuze technology represents the fastest-expanding segment as militaries demand programmable detonation heights and target discrimination capabilities.
US DoD insensitive munitions directives and NATO STANAG protocols shape fuze design mandates, forcing manufacturers to reformulate energetic materials and redundant safety interlocks. US Army ARDEC and Naval Surface Warfare Center Crane Division enforce qualification testing that extends development cycles but raises barriers to unauthorized market entry. Stakeholders must monitor evolving export control classifications under the US International Traffic in Arms Regulations and corresponding EU dual-use frameworks, as reclassification of smart fuze components could reroute supplier access across allied defense industrial bases.
Market Dynamics
Precision-guided munitions programs across NATO member states are accelerating procurement of electronic and smart fuze systems, while tightening safety standards under NATO STANAG agreements and US DoD insensitive munitions directives reshape supplier qualification requirements.
Growth Catalysts
- Electronic fuze adoption:Software-defined arming logic and compatibility with network-centric warfare architectures drive replacement of mechanical systems in artillery and missile applications.
- NATO STANAG protocols:Standardized safety and interoperability mandates compel allied defense ministries to modernize legacy fuze inventories.
- Artillery modernization:US Army and Navy budgets prioritize next-generation fuzing for extended-range precision fires.
Market Restraints
- Qualification timeline compression:US Army ARDEC and Naval Surface Warfare Center Crane Division testing extends development cycles, raising capital barriers for new entrants.
- Energetic material reformulation:Insensitive munitions directives force costly redevelopment of pyrotechnic compounds and redundant safety interlocks.
- Export control friction:US International Traffic in Arms Regulations and EU dual-use frameworks create compliance complexity for cross-border component flows.
Strategic Opportunities
- Smart fuze integration:Programmable detonation heights and target discrimination capabilities open new mission profiles for loitering munitions and counter-UAS systems.
- Network-centric architectures:Convergence of radar proximity sensors with software-defined radios enables real-time fuze retasking in contested electromagnetic environments.
- Indo-Pacific demand:Bilateral offset agreements with Australia, Japan, and South Korea create localized production pathways outside traditional NATO supply chains.
Industry Challenges
- Electromagnetic hardening expertise:Scarce talent pools for designing fuzes that survive high-altitude nuclear events and directed-energy threats constrain development throughput.
- Legacy system integration:Mechanical fuzes retained in artillery shells for cost and hardening reasons create interoperability friction with digital fire control networks.
- Supply chain reconfiguration:Semiconductor foundry concentration in East Asia forces Western fuze manufacturers to qualify alternative chip sources under ITAR constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Fuze Market |
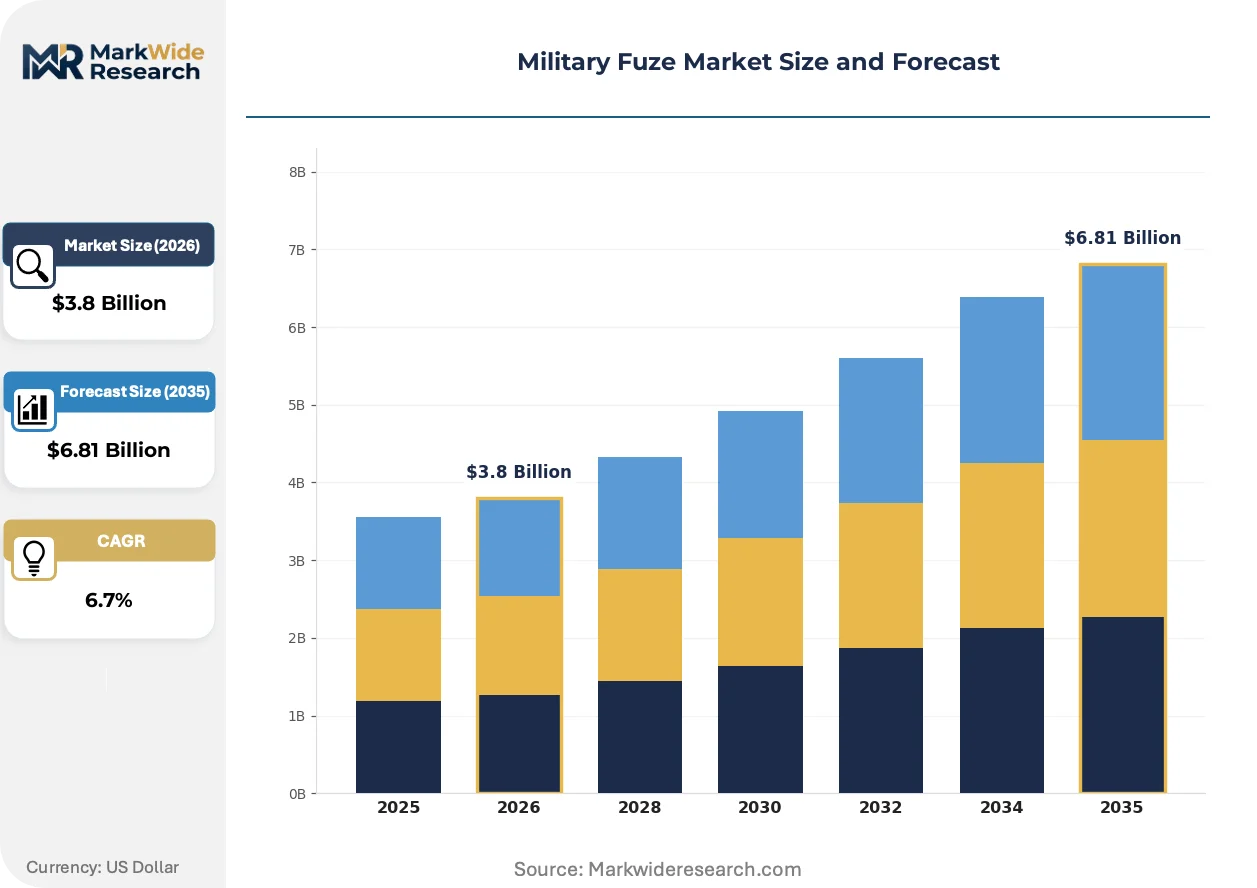
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Fuzes, Electronic Fuzes, Proximity Fuzes, Timer Fuzes Application: Missiles, Artillery, Bombs, Grenades Technology: Smart Fuze, Hybrid Fuze, Safety Mechanism, Guidance System End User: Military, Defense Contractors, Government Agencies, Research Organizations |
| Companies Covered | Expal, Reutech Fuchs Electronics, L3Harris Technologies, Anhui Great Wall Military Industry, DIXI Microtechniques, Northrop Grumman, JUNGHANS Microtec GmbH, Sandeep Metalcraft, Kaman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Fuze Market Shifts & Advancements
Active reshaping of the military fuze market centers on three vectors: the convergence of mechanical reliability with electronic intelligence, regulatory mandates forcing material and design overhauls, and procurement models that fragment traditional single-source relationships.
Multi-mode fuze technology is hybridizing mechanical backup safing with electronic proximity and point-detonation logic. Naval strike missile programs and anti-ship artillery batteries are adopting these systems to ensure kill-chain completion in GPS-denied environments. The technology is compressing the traditional trade-off between cost and mission assurance.
REACH and RoHS substance restrictions in Europe are forcing reformulation of lead-based primers and mercury fulminate initiators. Manufacturers serving NATO supply chains must now qualify alternative energetic materials that satisfy both performance and environmental compliance. Artillery fuze suppliers with European ordnance contracts face the steepest reformulation timelines.
Defense ministries are unbundling fuze procurement from prime contractor weapon systems, creating direct vendor relationships for electronic safety and arming devices. This disintermediation fragments long-standing supply hierarchies and exposes component manufacturers to end-user qualification requirements previously managed by primes. The United States exhibits the most advanced unbundling, with Army ARDEC issuing standalone fuze development contracts.
Military Fuze Market Segmentation
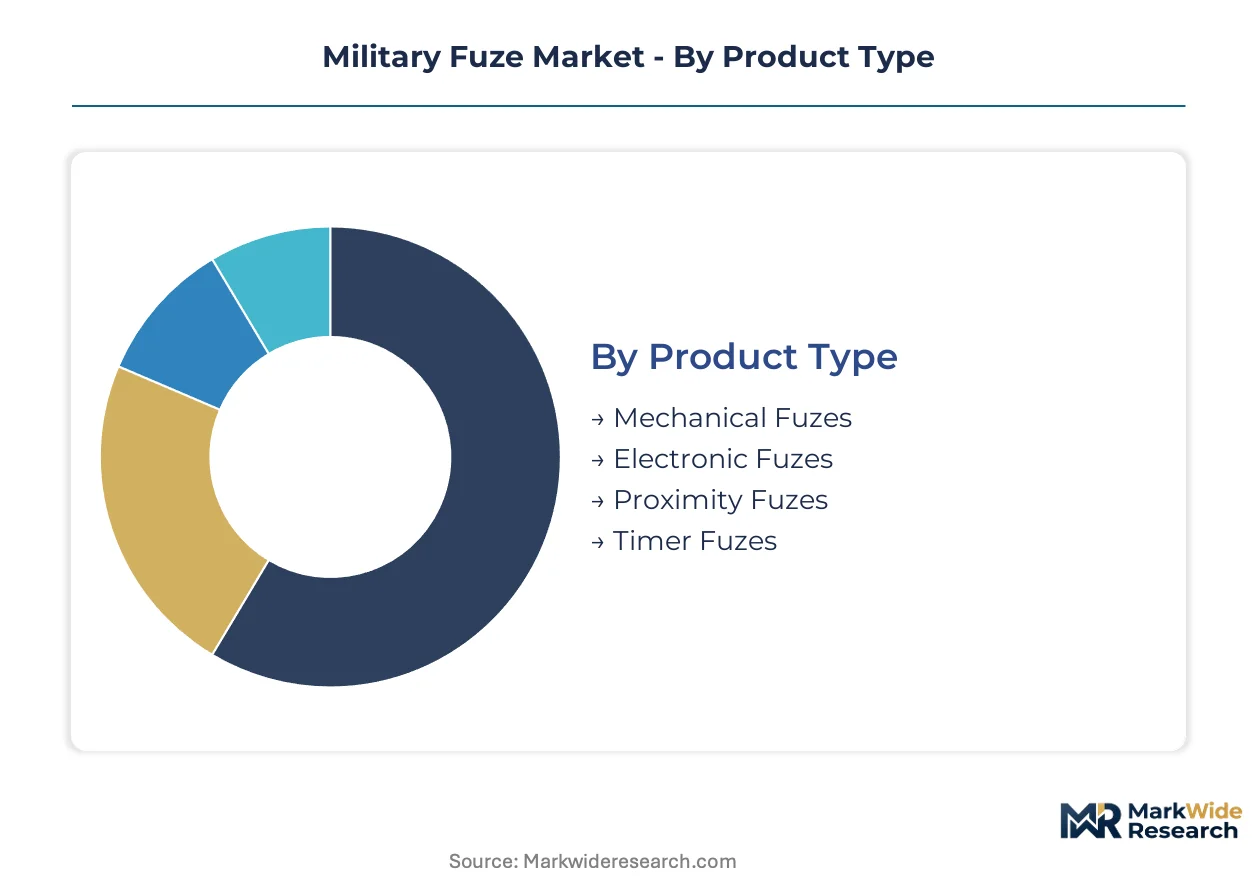
Military fuze procurement patterns diverge sharply across product architectures and mission profiles, with each segment demanding distinct qualification pathways and aftermarket support infrastructure. Segment boundaries increasingly blur as multi-mode designs integrate mechanical backup with electronic intelligence.
Product Type:
After-sales service intensity varies dramatically across fuze categories, with electronic systems requiring firmware updates and sensor recalibration versus mechanical units needing only periodic inspection.
- Electronic Fuzes:Semiconductor-based arming circuits with software-defined logic and millisecond-precision timing. Demand concentrates in US Army extended-range artillery programs where network-centric fire control mandates digital interfaces. NATO STANAG interoperability requirements accelerate replacement of legacy mechanical inventory.
- Proximity Fuzes:Radar or laser-based detonation triggers using Doppler sensing for airburst optimization. Naval strike missile programs and anti-ship batteries drive procurement as kill-chain assurance against GPS-denied environments. Electromagnetic hardening requirements extend development timelines but command premium pricing.
- Mechanical Fuzes:Clockwork or inertia-driven safing devices retained in cost-constrained artillery shells.
- Timer Fuzes:Pyrotechnic delay elements for demolition and specialized ordnance applications.
By volume, mechanical fuzes lead. By growth pace, electronic variants are expanding most quickly.
Application:
Cost tier stratification separates precision-strike systems from area-effect weapons, with fuzing sophistication directly tracking munition unit economics.
- Missiles:Multi-mode fuzing with radar proximity, impact, and self-destruct logic integrated into guidance sections. US Navy Standard Missile and Army Patriot modernization programs concentrate procurement. Kill-chain redundancy requirements drive adoption of hybrid mechanical-electronic architectures.
- Artillery:Point-detonation and proximity options for 155mm and extended-range shells. US Army Long-Range Precision Fires initiative prioritizes electronic fuzing with programmable height-of-burst. Cost constraints preserve mechanical alternatives in high-volume training rounds.
- Bombs:Air-delivered munitions requiring multi-option fuzing for tactical flexibility.
- Grenades:Hand-thrown and launcher systems with simplified impact or time-delay mechanisms.
Artillery applications dominate unit volume. Missile fuzing delivers the steepest value expansion trajectory.
Technology:
Supply concentration for semiconductor components and precision sensors shapes competitive access within each technology tier.
- Smart Fuze:Programmable detonation parameters with target discrimination algorithms and in-flight retasking capability. Loitering munitions and counter-UAS systems drive demand as mission flexibility becomes decisive. Software-defined radios enable real-time fuze reconfiguration in contested spectrum.
- Hybrid Fuze:Mechanical backup safing layered with electronic primary arming for mission assurance. Naval programs adopt these systems where electromagnetic pulse resilience is non-negotiable. Design complexity raises qualification barriers but reduces field failure rates.
- Safety Mechanism:Redundant interlocks and environmental sensing for handling and transport protection.
- Guidance System:Integrated fuze-guidance packages for precision terminal effects.
Safety mechanisms anchor volume across all applications. Smart fuze technology is gaining share fastest.
End User:
Customer type determines procurement channel structure, with direct military acquisition creating different qualification demands than prime-contractor integration.
- Military:Direct procurement by armed forces for depot-level maintenance and field replacement. US Army ARDEC and Naval Surface Warfare Center Crane Division issue standalone fuze development contracts, disintermediating traditional prime relationships. Inventory modernization cycles drive predictable demand patterns.
- Defense Contractors:Prime weapon system integrators sourcing fuzes as subassemblies. Raytheon and Lockheed Martin missile programs require vendor qualification to prime specifications. Offset agreements with Australia, Japan, and South Korea create localized sourcing mandates.
- Government Agencies:National stockpile managers and strategic reserve programs.
- Research Organizations:Developmental testing and advanced concept validation units.
Military end users dominate procurement volume. Defense contractor channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's defense logistics infrastructure underwrites Western Europe's ordnance distribution capacity, while the US inland waterway system connects Army arsenals to Gulf Coast testing ranges. These transport arteries shape where fuze qualification facilities and precision manufacturing clusters concentrate.
United States
US Army Long-Range Precision Fires and Navy next-generation missile programs drive electronic fuze procurement at scale. Army ARDEC at Picatinny Arsenal and Naval Surface Warfare Center Crane Division enforce ITAR-compliant qualification testing that extends development timelines. Huntsville, Alabama anchors missile defense fuze development, while Crane, Indiana hosts the Navy's primary fuze integration facility.
Germany
Bundeswehr artillery modernization and NATO STANAG standardization mandates accelerate replacement of legacy mechanical inventory. REACH and RoHS substance restrictions force reformulation of lead-based primers and mercury fulminate initiators. Diehl Defence in Röthenbach an der Pegnitz and Rheinmetall's precision ordnance operations in Unterlüß concentrate European smart fuze engineering expertise.
United Kingdom
Ministry of Defence Complex Weapons programs and Trident warhead modernization sustain demand for multi-mode fuzing with electromagnetic pulse resilience. UK Defence Standards and NATO interoperability requirements shape procurement specifications. Stevenage and Bristol host missile systems integration clusters where fuze-guidance packaging occurs.
South Korea
Korea Defense Acquisition Program Administration investments in indigenous missile systems and counter-battery artillery drive smart fuze adoption. Offset agreements with US primes create localized production mandates for electronic safety and arming devices. Seongnam and Changwon concentrate precision ordnance manufacturing with government-funded semiconductor foundry access.
Australia
AUKUS submarine and long-range strike capabilities generate demand for naval missile fuzing with GPS-denied mission assurance. Defence Strategic Review procurement reforms unbundle fuze acquisition from prime contractor weapon systems. Edinburgh Defence Precinct in South Australia hosts emerging ordnance integration facilities supporting Indo-Pacific supply chain reconfiguration.
Military Fuze Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with qualification-dependent access. The supplier base concentrates around three strategic archetypes: vertically integrated electronics houses with captive semiconductor fabrication, precision mechanical specialists with heritage clockwork expertise, and hybrid manufacturers bridging both domains. Consolidation pressure intensifies as defense ministries unbundle fuze procurement from prime weapon systems, forcing component vendors to absorb end-user qualification requirements previously managed by Raytheon or Lockheed Martin. Geographic expansion through bilateral offset agreements and technology licensing for insensitive munitions compliance represent the dominant competitive vectors.
Among US-based electronics houses, L3Harris Technologies and Northrop Grumman occupy positions anchoring the integrated systems tier, while JUNGHANS Microtec GmbH exemplifies European mechanical-electronic hybrid specialists. These three entities represent distinct competitive archetypes: the electronics foundry-integrated prime, the guidance-integrated missile systems supplier, and the precision timing heritage specialist serving NATO ordnance programs.
| Leading Market Players |
|---|
| Expal |
| Reutech Fuchs Electronics |
| L3Harris Technologies |
| Anhui Great Wall Military Industry |
| DIXI Microtechniques |
| Northrop Grumman |
| JUNGHANS Microtec GmbH |
| Sandeep Metalcraft |
| Kaman |
| Others |
Supply & Pricing Matrix
The US inland waterway system connecting Army arsenals to Gulf Coast testing ranges imposes freight cost differentials that concentrate precision manufacturing near Crane, Indiana and Huntsville, Alabama, amplifying supplier pricing power for ITAR-compliant electronic fuzes while forcing cost-sensitive mechanical alternatives toward standardized contract structures.
Pricing Analysis
Volume-discount tiering structures separate multi-year Army ARDEC procurement contracts from spot purchases by allied defense ministries, with electronic smart fuzes commanding premium positioning due to software-defined arming logic and electromagnetic hardening certification. Price differentiation hinges on NATO STANAG qualification status and after-sales firmware support bundling. Cost compression in mechanical artillery fuzes is intensifying because REACH-mandated energetic material reformulation raises production expenses. Training round buyers exhibit highest price sensitivity; missile program integrators show lowest.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates semiconductor sourcing risk for fuze manufacturers qualifying alternative foundries under ITAR constraints. Component supply concentrates in Taiwan, South Korea, and domestic US captive fabrication. Pyrotechnic compounds and precision timing mechanisms draw from German and South Korean specialty chemical suppliers. Single-source vulnerability persists for radiation-hardened microcontrollers. Distribution runs through prime contractor integration channels and direct military depot procurement, with bilateral offset agreements fragmenting traditional NATO supply hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military fuze demand sits in early-cycle expansion as precision-guided munitions programs across NATO allies displace legacy mechanical inventories with network-centric electronic systems.
For Market Incumbents: Harden electromagnetic hardening expertise pools through targeted acquisition of radiation-effects engineering specialists in Huntsville and Crane corridor clusters. Deepen backward integration into semiconductor packaging to mitigate Taiwan foundry concentration risk. Absorb end-user qualification requirements directly from Army ARDEC as procurement unbundling accelerates.
For New Entrants and Emerging Players: Build out insensitive munitions compliance capabilities to exploit reformulation-driven supplier turnover in European artillery programs. Target Australian AUKUS-related naval missile fuzing as the most penetrable geography given Defence Strategic Review procurement reforms. Pursue technology licensing partnerships with established primes for rapid NATO STANAG qualification.
For Investors and Strategic Acquirers: Precision mechanical-electronic hybrid specialists with heritage clockwork expertise and existing NATO ordnance contracts represent the priority acquisition archetype. Long-term viability frames around decade-long modernization cycles insensitive to near-term defense budget fluctuations. Monitor Indo-Pacific bilateral offset agreement announcements as inflection signals for supply chain reconfiguration velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munitions Certification Investment | REACH and US DoD directives force energetic material reformulation, raising barriers for non-compliant suppliers. |
| Semiconductor Foundry Qualification Program | ITAR-compliant chip sourcing outside Taiwan reduces single-point vulnerability for smart fuze production. |
| Direct Military Procurement Relationship | Army ARDEC standalone contracts disintermediate primes and expose component vendors to end-user specifications. |
| Electromagnetic Hardening Talent Acquisition | Scarce expertise for nuclear event survivability constrains development throughput across missile programs. |
| Indo-Pacific Offset Agreement Localization | Australia, Japan, and South Korea mandates create production pathways outside traditional NATO supply chains. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Army ARDEC program managers, Naval Surface Warfare Center Crane Division engineers, prime contractor procurement leads, and European ordnance specialists; and secondary validation against NATO STANAG documentation, US DoD budget justification materials, EU REACH regulatory filings, and customs trade data. Bottom-up segment sizing triangulated with top-down defense expenditure allocation models.
Forecast inputs considered product architecture evolution, mission profile digitization rates, and regulatory compliance timeline compression across the projection horizon. Segmentation dimensions modeled include fuze technology tier, application platform, end-user procurement channel, and regional defense industrial base configuration. CAGRs derived from historical procurement pattern analysis adjusted for modernization cycle phasing and bilateral offset agreement implementation velocity.
Stress conditions across semiconductor supply disruption, REACH enforcement stringency, and Indo-Pacific alliance restructuring were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Ballistic Composite Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Missile Seekers Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market