
 Less Lethal Ammunition Market | 2026-2036
Less Lethal Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Less Lethal Ammunition Market Analysis
The EU AI Act is recalibrating the cost-of-entry calculus for manufacturers integrating smart targeting systems into less lethal platforms. Federal Ammunition leverages its domestic manufacturing scale to sustain supply chain control across North American law enforcement channels. Rheinmetall AG anchors European defense and security demand through specialized non-lethal ordnance programs. Axon Enterprise Inc. differentiates via vertical integration from conducted electrical weapons to compatible kinetic payloads.
Less lethal ammunition encompasses kinetic and chemical projectiles designed to incapacitate or deter without causing fatal trauma, typically operating at muzzle energies below lethal thresholds and utilizing rubber composites, stabilized fabric pouches, or oleoresin capsicum formulations. These systems serve riot containment, suspect apprehension, and perimeter security functions where rules of engagement restrict conventional firearms. Rubber bullets and bean bag rounds occupy mature, high-volume positions in law enforcement procurement, while foam rounds represent a faster-growing niche driven by reduced injury liability profiles. Delivery method segmentation shows shotguns dominating current inventory compatibility, though launcher-based systems are gaining share as standalone less lethal platforms proliferate.
National regulators including the US Department of Defense Non-Lethal Weapons Program, Germany's Federal Criminal Police Office equipment standards, and the UK's Home Office Scientific Development Branch collectively shape product certification, field testing protocols, and cross-border sales permissions. ISO 9001 quality management and NATO standardization agreements further constrain market access for uncertified suppliers. Stakeholders must monitor evolving rules on kinetic energy thresholds and autonomous engagement capabilities as these will determine which product architectures retain legal deployability.
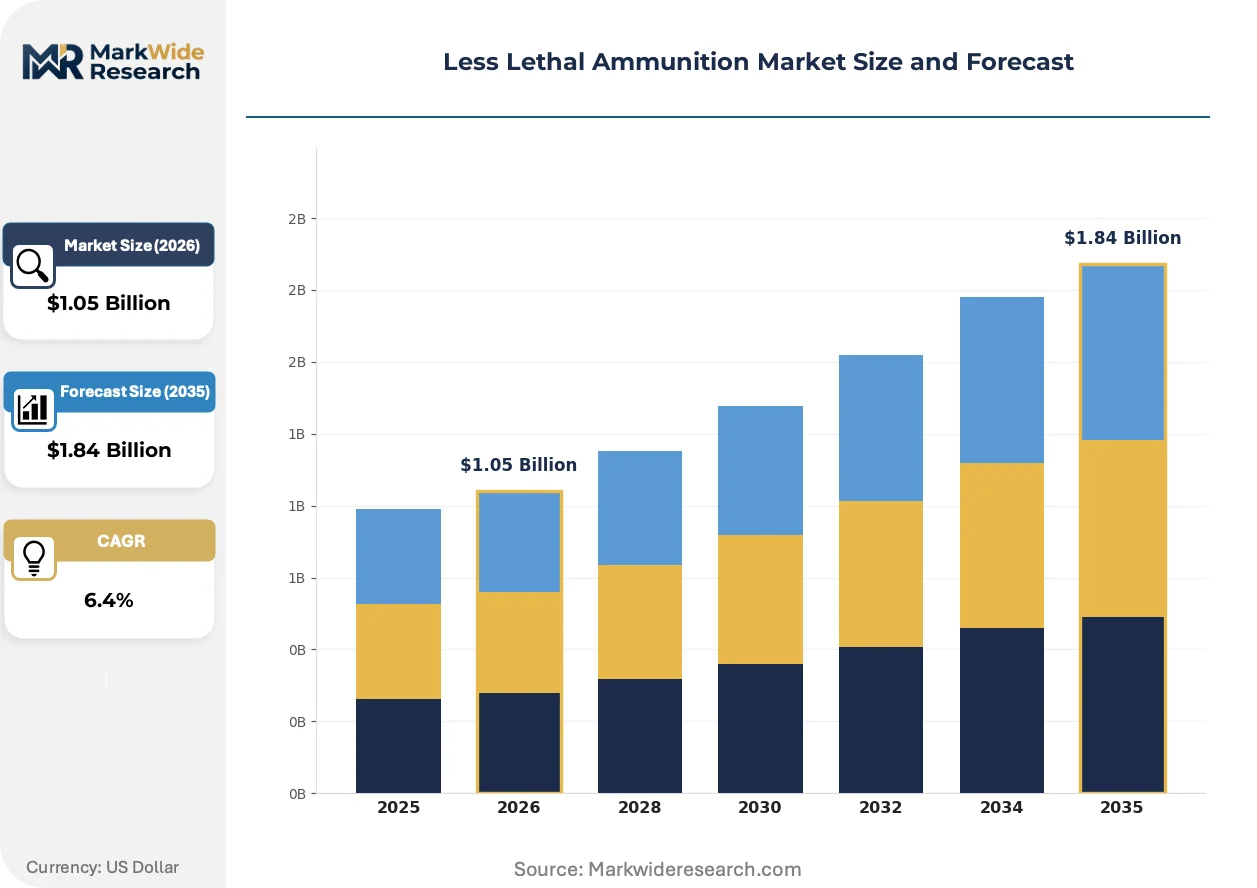
Market Dynamics
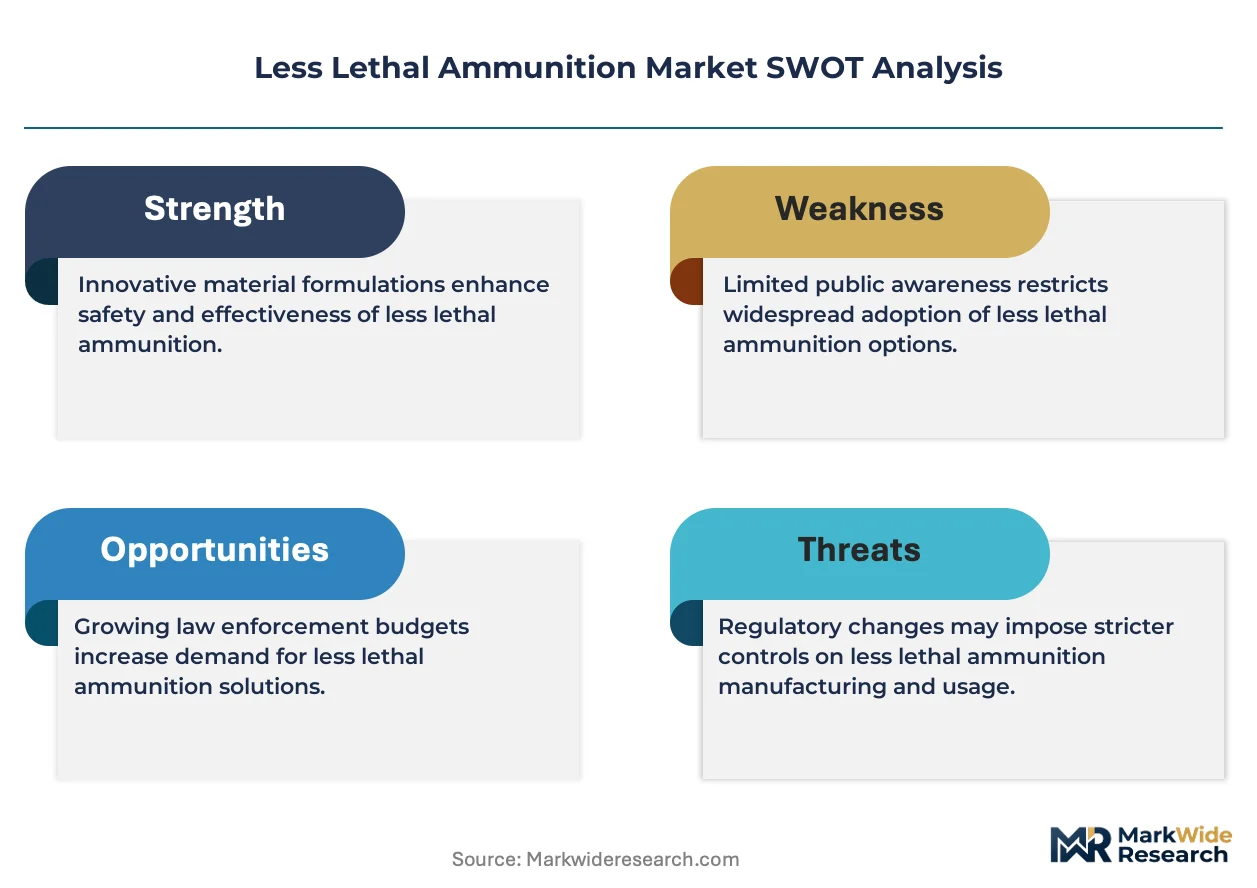
EU AI Act compliance requirements are forcing manufacturers to redesign smart targeting architectures in less lethal platforms, recalibrating R&D budgets and certification timelines across the supply base.
Growth Catalysts
- Urban Law Enforcement Modernization:Police departments in metropolitan Germany are replacing legacy lethal force protocols with kinetic non-lethal systems, driving procurement volume through federal equipment standardization programs.
- REACH Chemical Compliance:Reformulated oleoresin capsicum payloads meeting ECHA toxicity thresholds are expanding addressable market access across European security channels previously blocked by substance restrictions.
- Foam Round Injury Liability Reduction:Stabilized fabric pouch projectiles with sub-lethal kinetic profiles are displacing rubber composite alternatives in riot containment scenarios where civil liability exposure constrains equipment selection.
Market Restraints
- Rubber Composite Input Volatility:Petroleum-derived synthetic rubber feedstock costs fluctuate with crude pricing, compressing margin stability for kinetic projectile manufacturers lacking backward integration into polymer supply.
- German Supply Concentration Risk:Rheinmetall AG's dominance in specialized non-lethal ordnance creates single-source dependency for NATO-standard less lethal ammunition procurement.
- Kinetic Energy Threshold Variability:Divergent national standards on maximum permissible muzzle energy fragment addressable demand and force redundant product line engineering.
Strategic Opportunities
- Launcher-Based Platform Proliferation:Standalone less lethal delivery systems are gaining inventory share against shotgun-compatible rounds, opening white space for purpose-built launcher manufacturers.
- EU AI Act Autonomous Targeting Tailwind:Early certification of human-in-the-loop engagement systems creates first-mover positioning for compliant smart ammunition architectures.
- Perimeter Security Vertical Expansion:Critical infrastructure protection units at airports and power facilities are adopting less lethal systems for zone denial, extending demand beyond traditional law enforcement channels.
Industry Challenges
- ISO 9001 Certification Timeline Compression:Quality management audits for NATO standardization agreements require 18-24 month validation cycles, delaying market entry for new suppliers.
- Legacy Shotgun Inventory Integration Friction:Launcher-based less lethal platforms face adoption resistance from agencies with sunk investment in 12-gauge ammunition logistics and training infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Less Lethal Ammunition Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bullets, Bean Bag Rounds, Liquid Chemical Agents, Foam Rounds End User: Law Enforcement, Military, Private Security, Civilian Usage Frequency: Training, Crowd Control, Riot Control, Animal Control Delivery Method: Handguns, Launchers, Shotguns, Specialty Weapons |
| Companies Covered | Federal Ammunition, Axon Enterprise Inc., Rheinmetall AG, ALS Technologies, Lightfield Ammunition Corporation, Safariland, Nonlethal Technologies Inc., Chemring Group Plc, Combined Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Less Lethal Ammunition Market Emerging Trajectories
Smart targeting systems are rewriting competitive positioning in less lethal ammunition, while regulatory frameworks on autonomous engagement and chemical payloads reshape product architecture requirements.
Precision-guided kinetic projectiles with embedded micro-sensors are rewriting engagement accuracy standards for urban riot scenarios. German federal police units are field-testing these systems at accelerated procurement cycles. The technology is compressing acceptable margin-of-error thresholds and displacing unguided rubber bullet inventories in high-liability deployment contexts.
EU AI Act human oversight mandates are constraining autonomous targeting algorithm deployment in less lethal platforms. Manufacturers must now engineer mandatory operator confirmation loops into smart ammunition guidance systems. European law enforcement procurement specifications are prioritizing compliant architectures, creating certification-driven supplier selection.
Agency purchasing departments are consolidating vendor relationships through multi-year framework agreements that bundle ammunition supply with training and liability coverage. Traditional spot-buying through regional distributors is losing share to integrated service contracts. This consolidation is most visible in German state police modernization programs, where Rheinmetall AG anchors bundled procurement.
Less Lethal Ammunition Market Segmentation
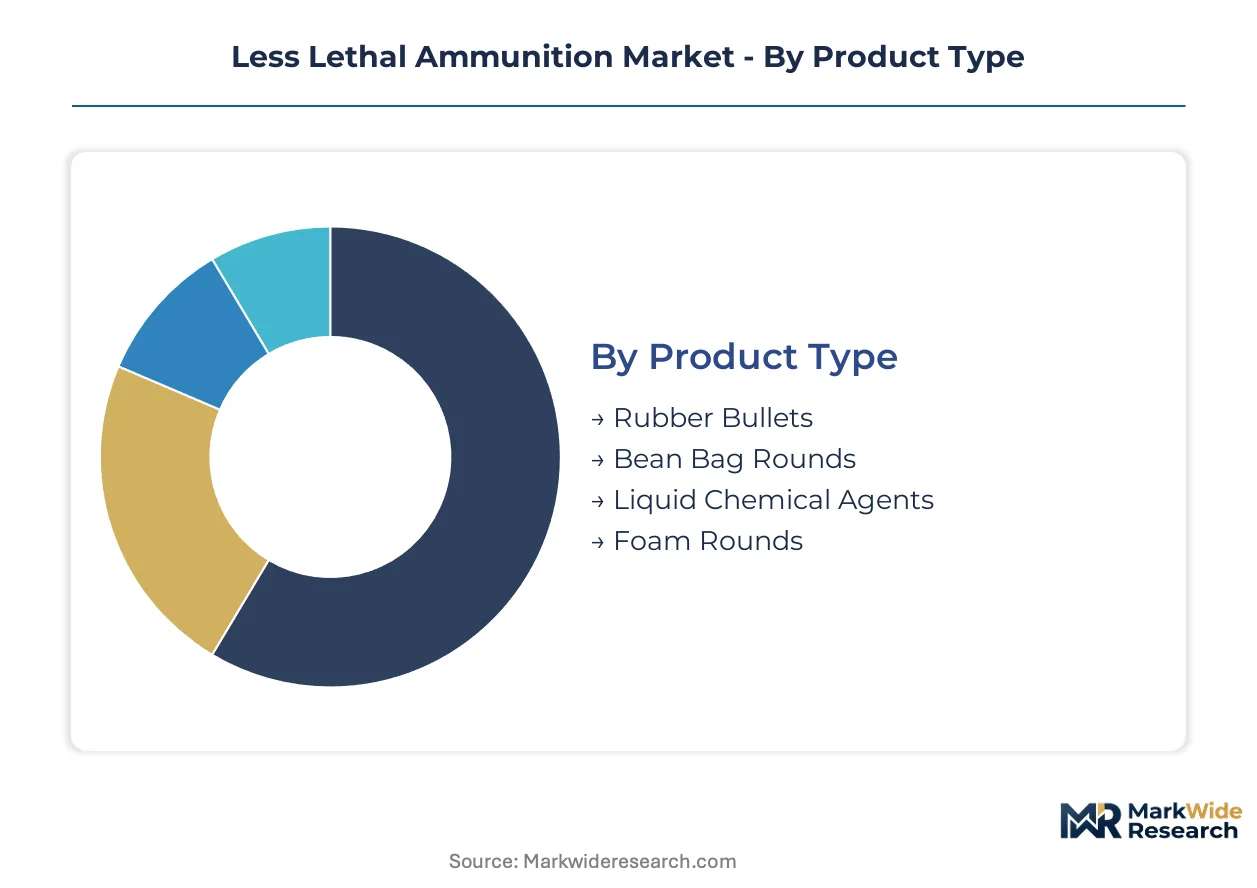
Segmentation in less lethal ammunition reveals divergent engineering requirements across kinetic, chemical, and smart projectile categories. Procurement patterns vary sharply between institutional buyers with certification mandates and private channels with lower compliance thresholds.
Product Type:
Standardization dominates rubber and bean bag formats where NATO interoperability drives specification uniformity, while foam and liquid chemical agents permit greater formulation customization for liability-sensitive deployments.
- Rubber Bullets:Composite polymer projectiles delivering kinetic incapacitation through 12-gauge and 37mm platforms. German federal police units deploy these in metropolitan riot containment where injury liability protocols restrict conventional firearms.
- Bean Bag Rounds:Stabilized fabric pouches containing lead shot or synthetic fill, designed to flatten on impact and distribute force across broader surface areas. These dominate North American law enforcement training programs and active deployment inventories due to established judicial precedent on use-of-force standards.
- Liquid Chemical Agents:Oleoresin capsicum and tear gas formulations meeting ECHA toxicity thresholds for European distribution. REACH compliance requirements constrain supplier pools to reformulated payloads with reduced dermal irritation profiles.
- Foam Rounds:Low-density projectiles engineered for sub-lethal kinetic profiles. Private security contractors at German critical infrastructure sites are adopting these for perimeter denial scenarios where civil litigation exposure constrains equipment selection.
Most installed capacity flows through rubber bullets. Expansion is steepest in foam rounds.
End User:
Volume concentration sits with institutional buyers possessing dedicated procurement budgets and liability coverage frameworks, while civilian channels operate through fragmented retail distribution with higher price sensitivity.
- Law Enforcement:Municipal, state, and federal police agencies with standardized training protocols and multi-year framework agreements. These buyers prioritize NATO certification and ISO 9001 quality management compliance in vendor selection.
- Military:Armed forces units engaged in peacekeeping, base security, and counter-insurgency operations with restrictive rules of engagement. Procurement flows through defense ministry ordnance programs with extended validation cycles.
- Private Security:Corporate protection units, critical infrastructure guards, and contracted facility security. German airport authorities and power generation facilities represent concentrated demand for zone denial capabilities.
- Civilian:Individual purchasers through licensed firearms dealers and specialty distributors. Regulatory fragmentation across German federal states creates uneven market access depending on local weapons authority classifications.
Law enforcement commands the largest procurement volumes. Private security is climbing the fastest as critical infrastructure protection expands beyond traditional state channels.
Usage Frequency:
Training applications require repetitive consumption with lower per-unit performance specifications, while riot and crowd control deployments demand maximum reliability under stress conditions.
- Training:High-volume consumption for officer certification and recertification programs. These rounds prioritize cost efficiency over terminal performance, with reduced propellant loads and reusable target systems.
- Crowd Control:Deployment against organized demonstrations and public disturbances. German metropolitan police units specify kinetic projectiles with calibrated energy thresholds to satisfy judicial review standards on proportional response.
- Riot Control:Sustained engagement scenarios requiring ammunition reserves and rapid reload capability. Chemical payloads in this category face stricter deployment authorization protocols than kinetic alternatives.
- Animal Control:Wildlife management and agricultural protection applications. These deployments favor longer-range launcher systems with specialized projectile aerodynamics for humane dispatch.
Training consumes the highest round counts per officer. Riot control applications are gaining share fastest as urban disorder response protocols expand across European municipal forces.
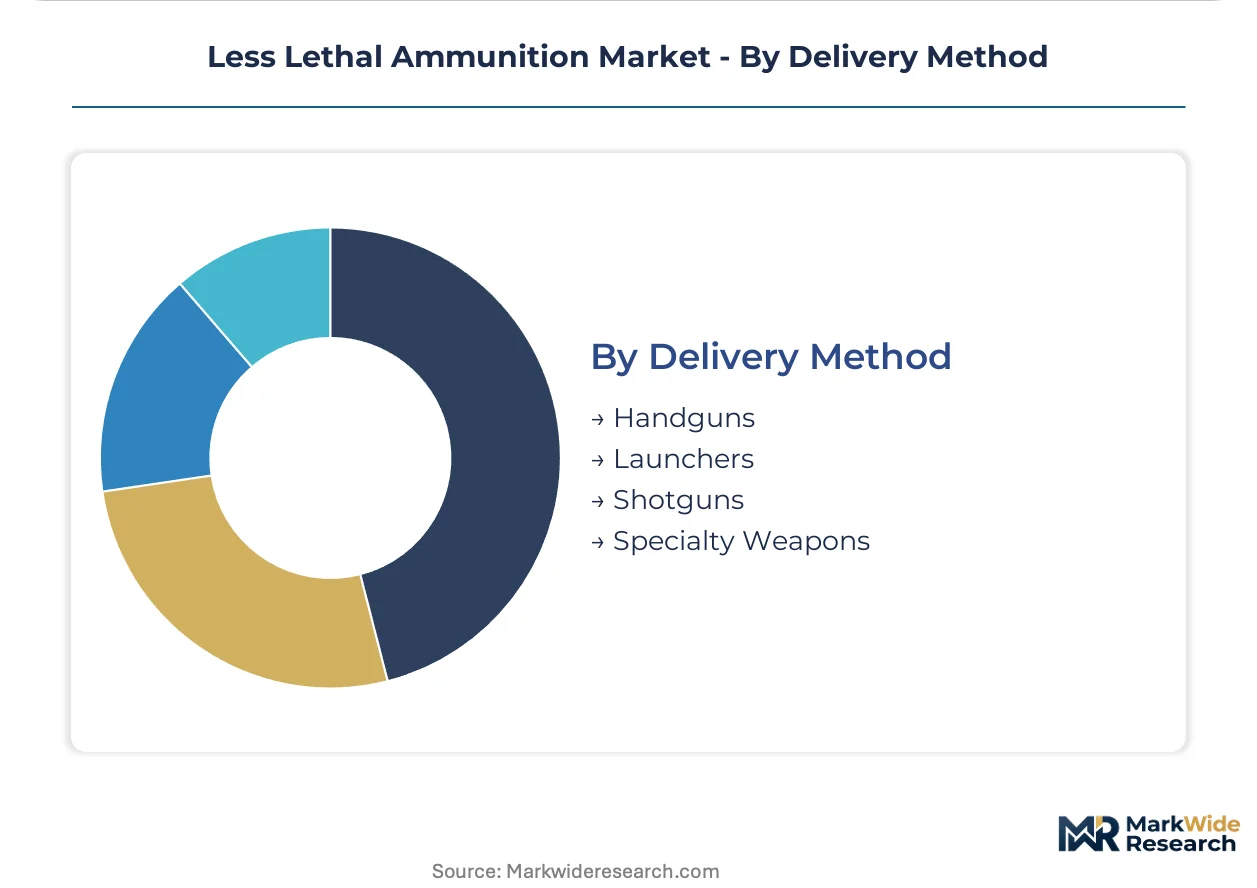
Delivery Method:
Shotgun compatibility leverages existing law enforcement armory infrastructure, while purpose-built launcher systems enable performance optimization at the cost of dedicated logistics investment.
- Handguns:Compact platforms for close-quarters engagement and plainclothes officer concealment. These systems face kinetic energy limitations due to reduced propellant capacity and shorter barrel lengths.
- Launchers:Dedicated less lethal platforms with adjustable power settings and integrated sighting systems. German federal police field trials of smart targeting launchers are validating autonomous engagement architectures ahead of EU AI Act compliance deadlines.
- Shotguns:Modified 12-gauge firearms with barrel porting and reduced-power cartridges. Existing training infrastructure and ammunition logistics dominate procurement preferences among budget-constrained municipal departments.
- Specialty Weapons:Multi-launch systems, aerial deployment platforms, and vehicle-mounted dispersal units. Critical infrastructure protection contracts in Germany are driving adoption of perimeter denial systems with automated targeting capabilities.
Shotguns retain the largest installed base. Launcher systems are expanding most quickly as standalone less lethal platforms proliferate in specialized unit procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ordnance engineers and defense procurement officers cluster in Germany's Ruhr industrial belt and around federal police training academies in Bavaria, anchoring European demand concentration for kinetic non-lethal systems.
Germany
Metropolitan police departments in Berlin and Hamburg are replacing legacy firearms protocols with bean bag and foam round systems under federal equipment standardization programs. The Federal Criminal Police Office (BKA) maintains strict kinetic energy thresholds that shape NATO-standard certification requirements. Rheinmetall AG anchors specialized non-lethal ordnance production in Düsseldorf, supplying state police modernization initiatives across North Rhine-Westphalia and Bavaria.
United States
Municipal police departments in Los Angeles, Chicago, and New York City drive procurement volumes through multi-year framework agreements bundling ammunition with training and liability coverage. The Department of Defense Non-Lethal Weapons Program sets field testing protocols that constrain cross-border sales permissions. Federal Ammunition leverages domestic manufacturing scale in Minnesota to sustain supply chain control across North American law enforcement channels.
United Kingdom
The Home Office Scientific Development Branch shapes product certification and deployment authorization protocols for metropolitan police units in London and Manchester. REACH chemical compliance requirements constrain oleoresin capsicum supplier pools to reformulated payloads with reduced dermal irritation profiles. Critical infrastructure protection contracts at Heathrow Airport and Thames Barrier facilities are expanding demand beyond traditional police channels into private security verticals.
France
Riot containment units in Paris and Marseille are field-testing precision-guided kinetic projectiles with embedded micro-sensors under accelerated procurement cycles. The EU AI Act human oversight mandates are constraining autonomous targeting algorithm deployment in less lethal platforms fielded by Gendarmerie nationale. ANSM and CNIL guidance on smart ammunition data handling is recalibrating vendor selection criteria for digital engagement systems.
Australia
State police forces in New South Wales and Victoria are adopting launcher-based platforms as standalone less lethal systems proliferate in specialized unit procurement. The Therapeutic Goods Administration (TGA) regulates chemical payload formulations while state weapons authorities classify kinetic projectile access. Critical infrastructure operators at Sydney Airport and Port Botany are expanding perimeter security applications for zone denial capabilities.
Less Lethal Ammunition Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates procurement authority in institutional buyers with NATO certification requirements. Tiering emerges between scale-driven manufacturers with backward integration into polymer supply and niche specialists engineering purpose-built launcher systems. Three archetypes dominate: defense conglomerates with ordnance divisions, law enforcement technology integrators, and standalone less lethal ammunition specialists. M&A activity targets certification-carrying assets while geographic expansion focuses on EU AI Act compliance positioning.
Among defense-industrial conglomerates, Rheinmetall AG exemplifies the European anchor position through its specialized non-lethal ordnance programs. Federal Ammunition occupies a scale-driven position leveraging domestic manufacturing infrastructure. Axon Enterprise Inc. represents the vertical integration archetype spanning conducted electrical weapons to compatible kinetic payloads.
| Leading Market Players |
|---|
| Federal Ammunition |
| Axon Enterprise Inc. |
| Rheinmetall AG |
| ALS Technologies |
| Lightfield Ammunition Corporation |
| Safariland |
| Nonlethal Technologies Inc. |
| Chemring Group Plc |
| Combined Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Smart targeting system integration into less lethal platforms is simultaneously elevating R&D cost structures and concentrating procurement leverage among NATO-certified manufacturers with compliant architectures. This technological shift compresses margin flexibility for uncertified suppliers while amplifying pricing power for incumbents meeting EU AI Act human-in-the-loop mandates.
Pricing Analysis
Bundled service contracts versus unbundled spot purchasing defines the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels separates AI-compliant smart ammunition from legacy rubber projectiles and training-grade reduced-load rounds. Price differentiation rests on ISO 9001 certification tier and after-sales liability coverage inclusion. Cost compression in standard-grade kinetic projectiles is intensifying because petroleum-derived synthetic rubber feedstock volatility squeezes polymer-dependent manufacturers. Municipal police departments with sunk shotgun infrastructure investment exhibit highest price sensitivity; specialized federal units procuring launcher-based smart systems show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German ordnance production anchoring NATO-standard less lethal procurement. Geographic supply concentration clusters in Germany, the United States, and the United Kingdom where defense-industrial bases maintain specialized non-lethal manufacturing. Raw material dependencies draw from petroleum-derived synthetic rubber composites, stabilized fabric pouch textiles, and reformulated oleoresin capsicum meeting ECHA toxicity thresholds. Tariff exposure on cross-border chemical payload shipments constitutes the dominant structural risk. Distribution runs through multi-year framework agreements bundling ammunition supply with training and liability coverage, displacing regional distributor spot-buying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act compliance deadlines are accelerating procurement cycles for certified smart ammunition architectures.
For Market Incumbents: Extend certification-carrying asset portfolios through targeted acquisition of launcher-system specialists lacking NATO standardization agreements. Capacity addition in Bavaria and North Rhine-Westphalia federal police supply corridors reinforces geographic anchoring against emerging platform competitors. Backward integration into captive polymer supply mitigates petroleum feedstock margin volatility threatening rubber composite producers. For New Entrants and Emerging Players: Direct-to-law-enforcement digital procurement portals offer the lowest-friction route past entrenched distributor relationships. Private security contractors at German critical infrastructure sites represent the most penetrable white-space segment, with perimeter denial applications outpacing traditional police channel growth. Purpose-built foam round engineering for liability-sensitive zone denial deployments provides differentiated go-to-market positioning against legacy rubber bullet incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone less lethal ammunition specialists lacking vertical integration into conducted electrical weapons or smart targeting platforms. Long-term viability over the mid-term projection horizon favors acquisition targets with EU AI Act pre-certification and existing German federal police framework agreements. The signal to monitor is accelerated procurement authorization for human-in-the-loop engagement systems in French Gendarmerie nationale field trials.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Human-in-the-loop architecture validation creates first-mover procurement advantage in German federal police modernization. |
| Backward Integration into Polymer Supply | Captive synthetic rubber production insulates margin stability against petroleum feedstock price volatility. |
| Launcher-Based Platform Development | Standalone less lethal systems displace shotgun-compatible rounds in specialized unit procurement. |
| Critical Infrastructure Vertical Expansion | Perimeter security contracts at German airports and power facilities extend demand beyond law enforcement channels. |
| REACH-Compliant Chemical Payload Reformulation | ECHA toxicity threshold alignment unlocks European distribution previously blocked by substance restrictions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged ordnance procurement officers at German state police modernization programs, technical directors at specialized non-lethal manufacturers, private security contractors at critical infrastructure sites, and regulatory affairs leads navigating EU AI Act implementation. Secondary validation drew from NATO standardization agreement documentation, BKA equipment certification protocols, ECHA substance restriction databases, and customs trade data on less lethal ammunition cross-border flows. Bottom-up product-line volume builds and top-down defense procurement budget allocations were triangulated for consistency.
Comparable-period anchoring linked forward projections to historical procurement cycles across German federal equipment standardization programs. Segmentation modeling spanned product type, end-user archetype, delivery method, and regional regulatory cluster dimensions. CAGRs were derived from weighted average growth across these segments calibrated to institutional buyer budget trajectories. Forecast inputs incorporated EU AI Act compliance timeline assumptions and kinetic energy threshold standardization momentum.
Regulatory enforcement variance, autonomous targeting algorithm validation delays, and petroleum feedstock price shocks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on procurement authorization timelines and certification pathway completion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market