
 Smart Weapons Market | 2026-2036
Smart Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Weapons Market Analysis
Airborne operations is hardening as the dominant end-use vertical, displacing traditional land warfare procurement patterns across NATO and Indo-Pacific defense budgets. Lockheed Martin Corporation leverages its JASSM franchise to anchor long-range strike contracts with the US Air Force. RTX Corporation sustains precision seeker production lines that supply multiple allied nations. Thales Group competes through European sovereign capacity in guided munitions, particularly within French and British supply chains.
Smart weapons integrate guidance systems, sensor fusion, and networked targeting to deliver precision effects against moving or fixed objectives with circular error probable measured in single-digit meters. Guided missiles lead the type category due to standoff range requirements and platform integration maturity, while autonomous systems within the technology dimension represent the fastest-growing structural segment as rules of engagement evolve for unmanned kill chains. Precision munitions occupy established margin pools in rotary-wing and close-air-support missions where inventory turnover rates exceed strategic systems.
The US Department of Defense, NATO Standardization Office, and Israel's Ministry of Defense shape demand through interoperability mandates and technology release protocols that govern cross-border system integration. The US International Traffic in Arms Regulations and NATO STANAG frameworks restrict market access for non-aligned suppliers, concentrating procurement within cleared industrial bases. Stakeholders must monitor evolving autonomous engagement policies, as ethical and legal frameworks for machine-initiated targeting remain unresolved across major defense ministries and will determine which technology segments achieve operational deployment at scale.
Market Dynamics
The migration toward autonomous engagement architectures is restructuring competitive positioning across defense industrial bases, as rules of engagement evolve to accommodate machine-initiated kill chains within NATO and Indo-Pacific procurement frameworks.
Growth Catalysts
- Standoff Range Requirements:Air forces prioritize munitions that deliver precision effects outside contested air defense envelopes, accelerating guided missile procurement cycles.
- NATO STANAG Interoperability Mandates:Standardization frameworks compel allied nations to harmonize smart munitions interfaces, creating cross-border demand pull.
- Sensor Fusion Maturation:Multi-spectral seeker technologies enable engagement of moving targets in degraded visual environments, expanding addressable mission sets.
Market Restraints
- ITAR Export Controls:US International Traffic in Arms Regulations restrict technology transfer to non-cleared industrial bases, segmenting supply access by political alignment.
- Seeker Component Concentration:Precision guidance subsystems depend on specialized semiconductor foundries concentrated in East Asian manufacturing clusters.
- Autonomous Engagement Policy Vacuum:Absence of resolved legal frameworks for machine-initiated targeting delays operational deployment of fully autonomous systems.
Strategic Opportunities
- Indian Munitions Modernization:India's Ministry of Defense accelerates indigenous smart weapons programs under technology transfer agreements with cleared foreign suppliers.
- Networked Kill Chain Integration:Convergence of satellite communications and edge computing enables real-time retargeting of in-flight munitions.
- Rotary-Wing Precision Gap:Attack helicopter fleets lack sufficient inventory of all-weather precision munitions, creating replacement demand for close-air-support missions.
Industry Challenges
- Autonomous Systems Engineering Talent:Shortage of specialists in machine learning for embedded weapons systems extends development timelines for next-generation seekers.
- Multi-National Certification Complexity:Munitions must satisfy divergent national safety and performance standards before achieving operational clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Weapons Market |
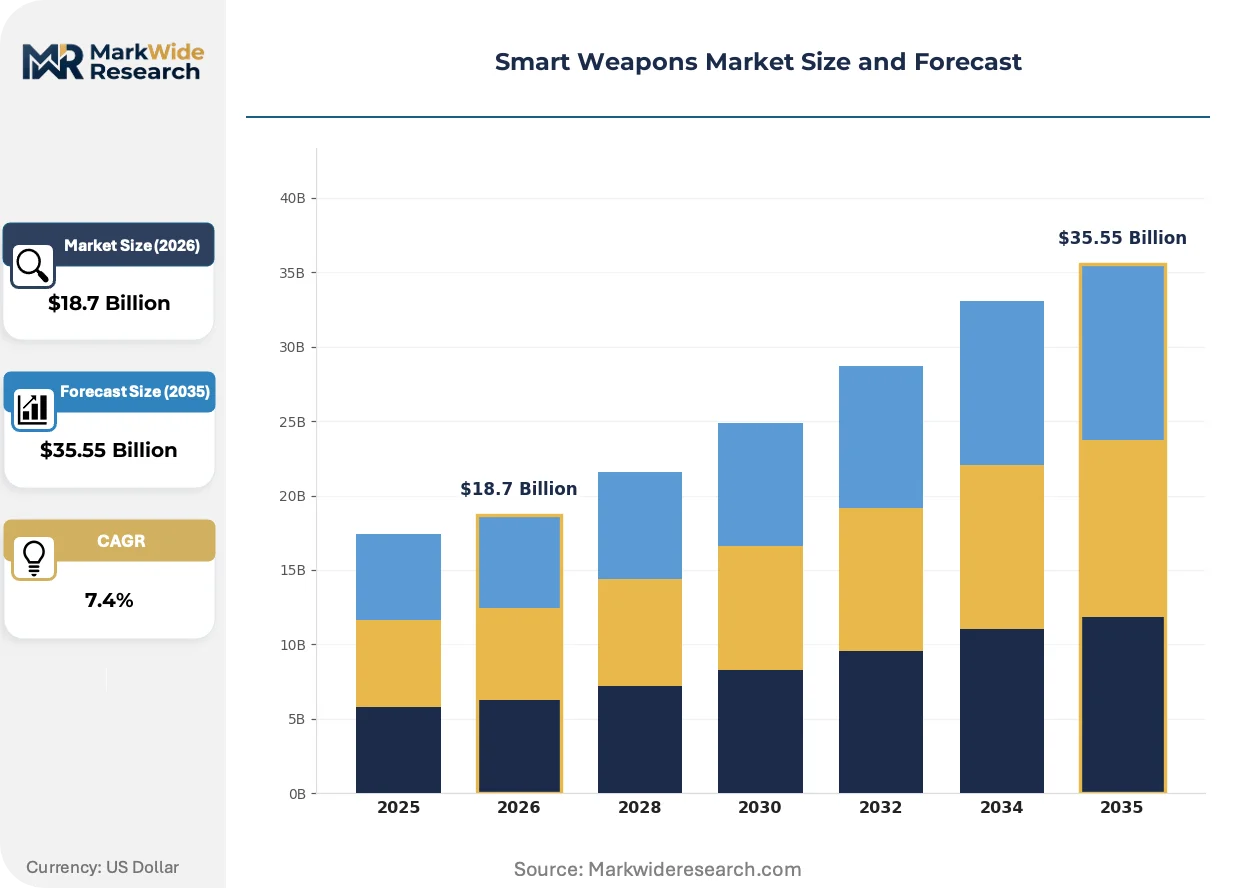
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Guided Missiles, Precision Munitions, Smart Bombs, Laser Weapons Technology: Electromagnetic, Kinetic Energy, Cyber Warfare, Autonomous Systems Application: Land Warfare, Airborne Operations, Naval Engagements, Counter-Terrorism End User: Military Forces, Defense Contractors, Government Agencies, Private Security |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, The Boeing Company, Northrop Grumman Corporation, BAE Systems plc, General Dynamics Corporation, Raytheon Technologies Corporation, Thales Group, MBDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Weapons Market Emerging Trajectories
Active development of unmanned kill chain architectures is compressing decision timelines and reshaping platform-munitions integration requirements across major defense procurement programs.
Multi-domain targeting software is consolidating command authority across air, space, and cyber domains into unified fire-control architectures. US Air Force Research Laboratory programs demonstrate real-time sensor-to-shooter links that compress engagement timelines from minutes to seconds. This capability is consolidating traditional stovepiped weapons systems into networked effects chains that demand new integration standards from prime contractors.
EU AI Act risk classification frameworks are imposing algorithmic transparency requirements on autonomous targeting systems exported to European defense forces. French and German procurement offices now mandate explainability documentation for machine-learning-based seeker logic. Systems lacking interpretable decision pathways face exclusion from contested European tenders regardless of technical performance.
Defense ministries are unbundling sustainment contracts from initial platform awards, creating standalone service revenue pools for precision munitions lifecycle management. Israeli and Australian forces now contract separately for inventory monitoring, seeker recalibration, and software updates. This pattern is most visible in Indo-Pacific markets where rotational deployment models demand continuous readiness verification without permanent technical presence.
Smart Weapons Market Segmentation
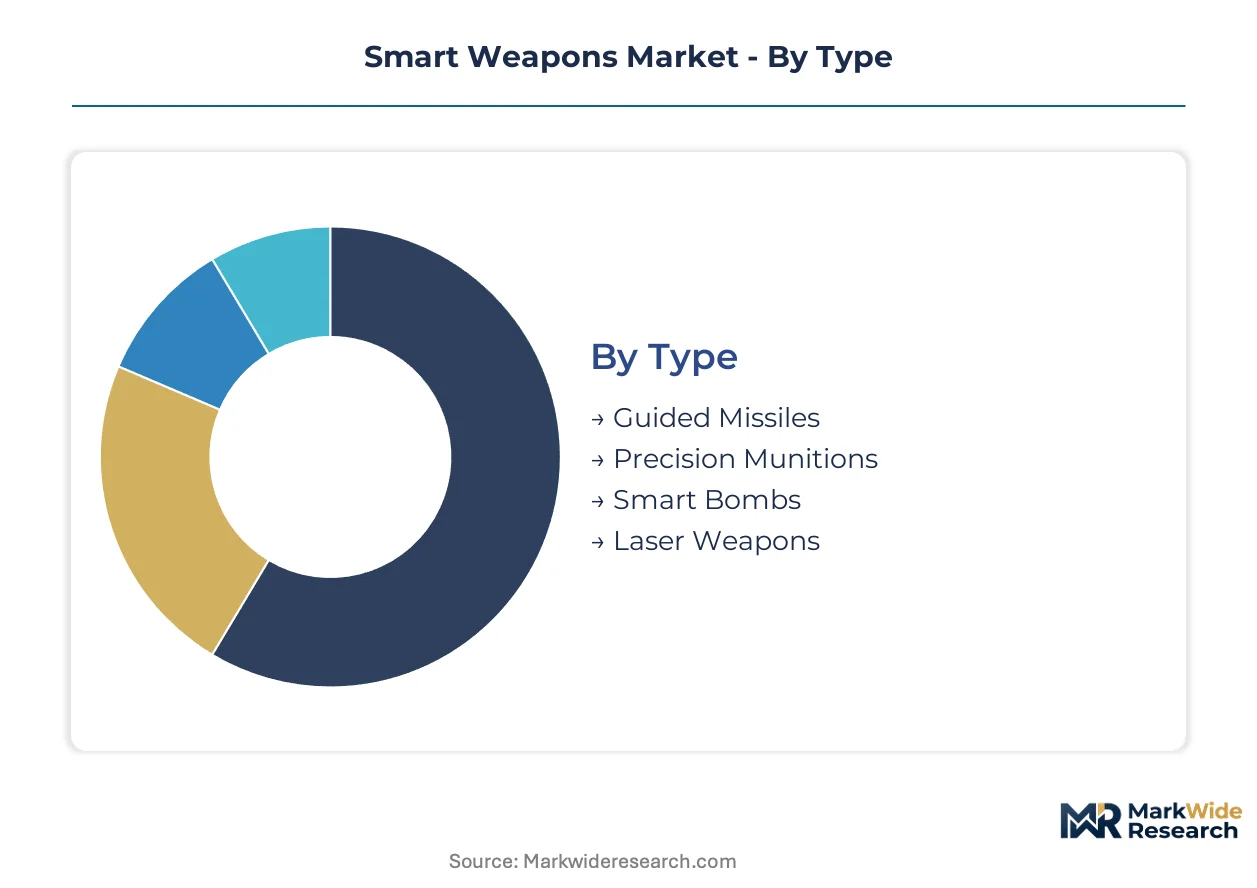
Smart weapons segmentation reveals how precision strike requirements fragment procurement across platform types, engagement technologies, and operational domains. Defense ministries allocate budgets distinctly between standoff systems and close-combat munitions, with technology release protocols governing cross-border transfers.
Type:
Guidance architecture and standoff range specifications define procurement priorities across air, land, and naval force modernization programs.
- Guided Missiles:Multi-spectral seekers and jet turbine propulsion enable engagement of moving targets beyond visual range. US Air Force and Israeli Defense Forces concentrate procurement here due to contested air defense penetration requirements.
- Precision Munitions:GPS-aided inertial guidance with terminal laser designation delivers sub-meter accuracy against fixed coordinates. Rotary-wing attack squadrons in India and Australia drive inventory turnover for close-air-support missions.
- Smart Bombs:Glide kits and precision guidance kits retrofit legacy gravity bombs for standoff delivery.
- Laser Weapons:Directed energy systems engage low-cost drones and mortar rounds at speed-of-light engagement timelines.
Guided missiles lead on scale; laser weapons lead on momentum.
Technology:
Energy delivery mechanisms and target engagement autonomy determine system complexity, certification timelines, and operational deployment boundaries.
- Electromagnetic:Railgun and coilgun technologies accelerate projectiles using magnetic fields rather than chemical propellants. US Navy surface warfare programs and Chinese naval research institutes concentrate development here for hypersonic velocity without explosive payloads.
- Autonomous Systems:Machine-learning seekers enable target identification and engagement without human-in-the-loop authorization. NATO Standardization Office and Israel's Ministry of Defense shape procurement frameworks as rules of engagement evolve for unmanned kill chains.
- Kinetic Energy:Hypervelocity impactors destroy targets through mass-velocity mechanics alone.
- Cyber Warfare:Embedded code exploits disrupt adversary command networks and navigation systems.
Electromagnetic systems anchor current procurement volume; autonomous systems are climbing the fastest as ethical frameworks mature.
Application:
Operational domain dictates platform integration requirements, environmental specifications, and kill chain compression priorities.
- Airborne Operations:Standoff munitions integrate with fighter-bomber and unmanned combat air vehicle hardpoints for beyond-envelope strikes. US Air Force, Royal Air Force, and Indian Air Force harden procurement as precision requirements intensify across NATO and Indo-Pacific theaters.
- Counter-Terrorism:Low-collateral-damage munitions enable precision engagement in urban environments with strict rules of engagement. Israeli and British special operations forces drive demand for miniaturized guided systems with reduced blast radii.
- Land Warfare:Artillery-launched precision rounds and loitering munitions support maneuver formations.
- Naval Engagements:Anti-ship missiles and layered defense systems protect surface fleets and project power ashore.
Airborne operations dominate procurement value; counter-terrorism applications gain share fastest as urban engagement protocols proliferate.
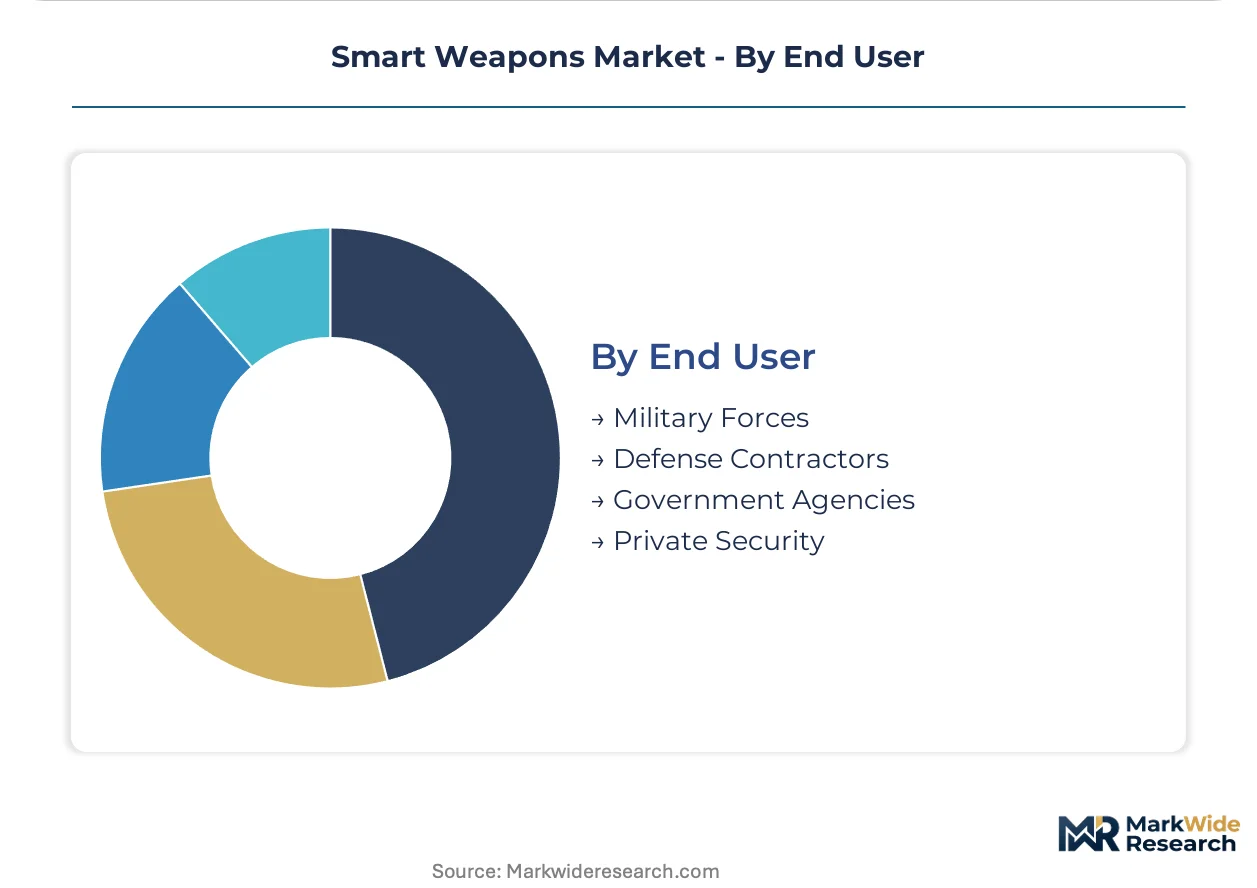
End User:
Institutional buyer type determines funding mechanisms, technology access tiers, and sustainment contract structures.
- Military Forces:Uniformed services operate the full spectrum of smart weapons through national defense budgets and alliance pooled procurement. United States, Israel, and India accelerate modernization through foreign military sales and indigenous production partnerships.
- Defense Contractors:Prime systems integrators and tier-one suppliers maintain development pipelines and precision seeker production lines. RTX Corporation and Thales Group sustain manufacturing capacity across cleared industrial bases.
- Government Agencies:Intelligence and paramilitary organizations procure specialized systems outside standard military acquisition channels.
- Private Security:Maritime protection and critical infrastructure defense contractors access limited precision munitions categories under strict export licensing.
Military forces command absolute procurement scale; defense contractors capture expanding sustainment revenue as lifecycle management unbundles from initial awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping smart weapons manufacturing footprints, with defense primes relocating precision seeker production to jurisdictions offering streamlined export licensing and sovereign capacity incentives. Compliance cost differentials between ITAR-cleared US facilities and emerging European-Israeli industrial partnerships are accelerating facility investments outside traditional American defense corridors.
United States
The US Department of Defense sustains the world's largest precision munitions procurement budget, with the Air Force Research Laboratory driving multi-domain targeting software development. ITAR frameworks restrict technology transfer to cleared industrial bases, segmenting supply access by political alignment. Huntsville, Alabama and Tucson, Arizona anchor concentrated manufacturing clusters for guided missile propulsion and seeker calibration.
Israel
Israel's Ministry of Defense accelerates indigenous smart weapons programs through technology transfer agreements with cleared foreign suppliers, particularly for loitering munitions and autonomous targeting systems. Israeli defense procurement offices mandate interoperability with NATO STANAG frameworks while preserving sovereign algorithmic control. Haifa and Be'er Sheva host dense concentrations of precision seeker engineering talent and unmanned systems integration facilities.
India
India's Ministry of Defense pursues indigenous smart munitions modernization under Make in India defense manufacturing incentives, with foreign military sales partnerships enabling technology absorption. DGFT export licensing and offset requirements govern cross-border system integration for precision guidance subsystems. Bengaluru and Hyderabad emerging as dual-use aerospace clusters where state-owned ordnance factories collaborate with private sector integrators on guided missile development.
United Kingdom
The UK Ministry of Defence prioritizes sovereign guided munitions capacity through BAE Systems-led supply chains, with Royal Air Force procurement hardening for standoff strike requirements. UK Strategic Command interoperability mandates align with NATO STANAG frameworks while preserving national safety certification authority. Stevenage and Bolton host established precision weapons engineering centers supporting Eurofighter Typhoon and F-35 integration programs.
Germany
Germany's Federal Ministry of Defence channels procurement through MBDA Deutschland and Rheinmetall partnerships, with emphasis on autonomous systems explainability under emerging EU AI Act risk classifications. KBA defense export licensing and end-use monitoring restrict technology diversion to non-allied destinations. Schrobenhausen and Unterlüß concentrate precision munitions manufacturing and artillery systems integration for European pooled procurement frameworks.
Smart Weapons Market Vendor Landscape
Capacity expansion dominates the current landscape as defense primes scale precision seeker production lines to meet compressed NATO and Indo-Pacific procurement timelines. Market structure concentrates around tier-one systems integrators with cleared industrial base access, supplemented by sovereign European and Israeli specialists serving national procurement mandates. Three archetypes define competitive positioning: US-based primes with ITAR-governed export franchises, European consortium entities leveraging pooled R&D funding, and Israeli specialists in autonomous targeting and loitering munitions. M&A activity and strategic partnerships represent the dominant competitive vectors, with technology licensing agreements enabling market access for non-aligned suppliers.
Within the US prime contractor tier, Lockheed Martin Corporation and RTX Corporation exemplify scale-driven positioning through long-range strike franchise maintenance and precision seeker production line sustainment. RTX Corporation and Thales Group occupy complementary positions across transatlantic supply chains, with the French conglomerate representing European sovereign capacity in guided munitions integration. These entities anchor competitive dynamics through manufacturing presence in cleared industrial bases and alignment with national technology release protocols.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| The Boeing Company |
| Northrop Grumman Corporation |
| BAE Systems plc |
| General Dynamics Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| MBDA |
| Others |
Supply Flow & Price Mechanics
EU AI Act risk classification frameworks for algorithmic transparency in autonomous targeting systems gate qualified supply access and premium-tier pricing for defense contractors serving European procurement offices. Compliance documentation requirements for machine-learning-based seeker logic segment suppliers into cleared tiers, with explainability-certified systems commanding pricing premiums over opaque alternatives.
Pricing Analysis
Direct-to-OEM contracting with national defense ministries dominates pricing structures, bypassing distributor markups through foreign military sales frameworks and indigenous production partnerships. Pricing stratifies across ITAR-cleared, NATO STANAG-compliant, and non-aligned tiers based on technology release protocols and interoperability certification levels. Cost compression in precision seeker subsystems intensifies as semiconductor foundry capacity constraints ease. State-owned ordnance factories in India exhibit highest price sensitivity due to Make in India offset requirements, while US Air Force procurement demonstrates lowest sensitivity for standoff strike systems.
Supply Chain Analysis
ITAR clearance certification gates supplier participation, concentrating precision seeker manufacturing in cleared US facilities, Israeli sovereign capacity zones, and emerging European industrial partnerships. Specialized semiconductor foundries in Taiwan and South Korea feed multi-spectral seeker production lines, while rare earth magnet suppliers in China anchor electromagnetic propulsion subsystems. Single-source vulnerability concentrates in East Asian semiconductor manufacturing clusters. Distribution runs through national defense procurement channels with foreign military sales intermediaries, supplemented by technology transfer agreements enabling licensed production in recipient nations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as unresolved autonomous engagement policies across NATO defense ministries accelerate procurement of explainable AI systems ahead of formal legal frameworks.
For Market Incumbents: Extend precision seeker production capacity in ITAR-cleared and NATO-aligned jurisdictions to capture Indo-Pacific modernization cycles. Deepen backward integration into semiconductor packaging to offset East Asian foundry concentration risk. Lockheed Martin and RTX Corporation anchor positions through JASSM franchise maintenance and cross-allied supply chain sustainment. For New Entrants and Emerging Players: Launch via technology licensing agreements with Israeli or Indian defense ministries seeking sovereign algorithmic control over loitering munitions. Rotary-wing precision munitions for attack helicopter fleets present the most penetrable white space, with Australian and British close-air-support procurement cycles offering near-term contract windows. For Investors and Strategic Acquirers: Roll-up economics work for precision seeker engineering specialists because autonomous systems engineering talent scarcity extends development timelines for prime contractors. Five-to-ten-year viability hinges on regulatory clarity for machine-initiated targeting. Monitor NATO Standardization Office policy evolution as the primary inflection signal for autonomous segment deployment scale.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR-Cleared Facility Expansion | US Department of Defense procurement mandates restrict supply access to cleared industrial bases, concentrating contract awards. |
| Autonomous Systems Certification Investment | EU AI Act explainability requirements govern European defense tenders, excluding opaque machine-learning seekers from contested awards. |
| Technology Transfer Partnership | India's Ministry of Defense offsets foreign military sales through indigenous production licensing, enabling market access for non-US primes. |
| Multi-Domain Targeting Software Development | US Air Force Research Laboratory programs compress sensor-to-shooter timelines, demanding new integration standards from contractors. |
| Sustainment Contract Unbundling | Israeli and Australian forces now separate lifecycle management from initial platform awards, creating standalone service revenue pools. |
Methodological Framework
Multiple input streams — defense procurement database tracking, primary interviews with program managers at national ministries, and secondary validation through NATO STANAG documentation — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged precision weapons program executives, seeker engineering specialists, foreign military sales coordinators, and defense attaché liaison officers across cleared industrial bases. Secondary sources included US Department of Defense budget justification materials, Israel Ministry of Defense procurement disclosures, and Indian DGFT export licensing records. Bottom-up platform-munitions integration assessments and top-down national defense budget allocation analysis were triangulated for consistency.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to derive volume and value outputs. Modeled dimensions spanned weapon type, guidance technology autonomy level, operational domain application, and national procurement framework alignment. CAGRs emerged from fitted growth curves anchored to disclosed contract awards and announced modernization program timelines. Forecast inputs incorporated foreign military sales pipeline visibility, indigenous production partnership ramp schedules, and evolving autonomous engagement policy milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed regulatory clarity for machine-initiated targeting or accelerated Indo-Pacific conflict scenarios. Deviation in NATO Standardization Office autonomous systems certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market