
 Asia-Pacific Ammunition Market | 2026-2036
Asia-Pacific Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ammunition Market Outlook
Aftermarket service revenue for ammunition lifecycle management is fragmenting across the Asia-Pacific as defense ministries extend platform longevity. Poongsan Corporation leverages its integrated brass and propellant operations to dominate South Korean military supply. Hanwha Corporation anchors regional naval gun ammunition through its shipyard partnerships. Rheinmetall AG competes on 120mm smoothbore tank rounds via technology transfer arrangements with Australian Munitions.
Asia-Pacific ammunition encompasses projectiles, propellants, primers, and casings engineered to precise chamber pressure and ballistic coefficient specifications for lethal or training effect. Small caliber rounds serve individual weapons and close-quarters engagement, while medium and large caliber systems address vehicle-mounted and artillery applications with higher unit value and longer procurement cycles. The military end-user segment commands the dominant procurement volume, though training application demand is expanding as regional forces increase live-fire exercise tempo. Specialty ammunition for precision engagement represents the fastest-growing caliber category as guided mortar and sniper systems proliferate.
India's CEA and DGFT regulate explosive imports through licensing frameworks that constrain foreign supply without local partnership. Australia's sovereign munitions standards, administered through national defense procurement protocols, mandate domestic content thresholds for critical ordnance. China's GB standards and MIIT directives govern propellant chemistry and environmental discharge parameters. Stakeholders must monitor how evolving bilateral defense agreements reshape cross-border ammunition trade eligibility and local production requirements.
Market Dynamics
Defense ministries across Southeast Asia are accelerating precision-guided munitions procurement while India's PLI scheme redirects supply chains toward domestic brass and propellant manufacturing, compressing import dependency timelines.
Growth Catalysts
- Precision-Guided Mortar Systems:Regional militaries in Thailand and Indonesia are fielding laser-guided 81mm and 120mm mortar rounds for urban engagement scenarios, pulling demand toward higher-unit-value specialty ammunition.
- Australia's Sovereign Munitions Mandate:National defense procurement protocols require domestic content thresholds for critical ordnance, stimulating capital flows into local propellant blending and case manufacturing capacity.
- Live-Fire Exercise Tempo:The Five Power Defence Arrangements and bilateral training rotations between Australia, Singapore, and Malaysia are consuming training ammunition stocks at rates exceeding peacetime replenishment cycles.
Market Restraints
- Nitrocellulose Supply Concentration:China controls approximately 70% of global cotton linters processing for military-grade propellant feedstock, exposing regional manufacturers to export license volatility.
- CEA Licensing Friction:India's explosive import licensing frameworks constrain foreign ammunition supply without local partnership, extending procurement lead times for non-domestic producers.
- Environmental Chemistry Constraints:China's MIIT discharge parameters for propellant manufacturing are tightening solvent recovery requirements, elevating compliance capital intensity for existing facilities.
Strategic Opportunities
- Vietnam's Underpenetrated Naval Gun Market:The Vietnam People's Navy is modernizing frigate-mounted 76mm and 100mm naval artillery, creating first-mover advantage for propellant suppliers with NATO-standard compatibility.
- Dual-Use Civilian-Military Propellant Lines:Convergence of sporting ammunition chemistry with military specifications allows manufacturers to amortize R&D across commercial hunting and defense contracts.
- Japan's Defense Equipment Transfer Revisions:METI and Ministry of Defense policy shifts are loosening post-war export restrictions on finished ammunition, opening previously closed regional supply relationships.
Industry Challenges
- Ballisticians and Propellant Chemists Scarcity:The specialized workforce for internal ballistics modeling and nitrocellulose formulation is aging across Australia and South Korea without adequate university pipeline replacement.
- Legacy Artillery System Integration:New precision-guided rounds must maintain interoperability with 1960s-era 105mm and 155mm towed howitzers still fielded by Philippine and Indonesian ground forces, constraining electronics packaging and guidance architecture options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ammunition Market |
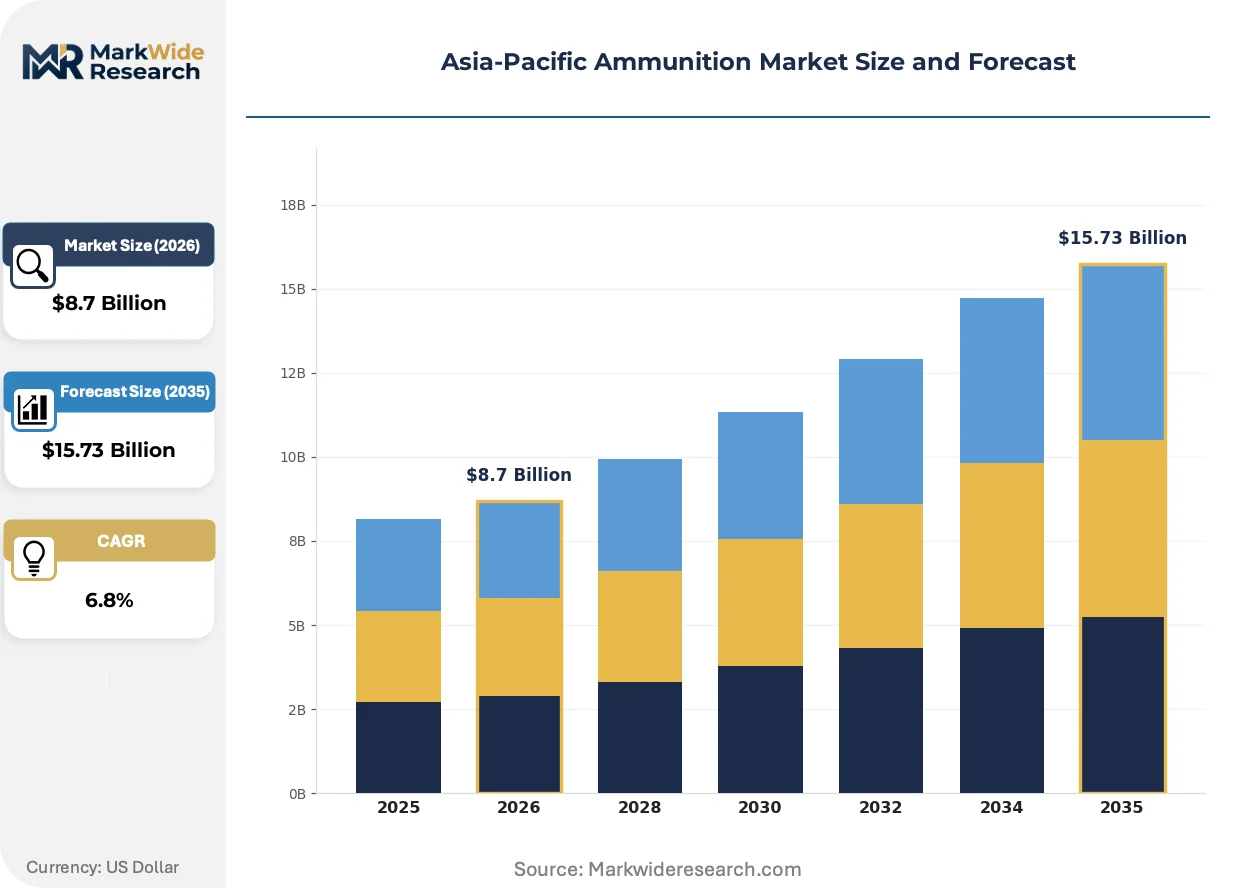
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullets, Shells, Cartridges, Blanks End User: Military, Law Enforcement, Civilian, Security Forces Application: Defense, Sports Shooting, Hunting, Training Caliber: Small Caliber, Medium Caliber, Large Caliber, Specialty Ammunition |
| Companies Covered | Poongsan Corporation, Hanwha Corporation, BAE Systems, General Dynamics Corporation, Rheinmetall AG, Singapore Technologies Engineering Ltd, Munitions India Limited, NORINCO, Australian Munitions, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ammunition Market Strategic Shifts
Electronics miniaturization and additive manufacturing are compressing development cycles for guided munitions while regulatory frameworks scramble to address autonomous targeting algorithms and environmental propellant chemistry.
Insensitive munitions formulations incorporating polymer-bonded explosives and reduced vulnerability propellants are collapsing the safety-versus-performance tradeoff that previously separated training and combat stocks. The Australian Defence Force and Japan Ground Self-Defense Force are mandating IM compliance for all new ammunition acquisitions, forcing reformulation of legacy TNT-based fill compositions. This chemistry shift is collapsing the distinction between storage, transport, and tactical employment hazard classifications, enabling ammunition to transit commercial logistics networks previously restricted to inert cargo.
China's GB standards for propellant environmental discharge and Australia's sovereign munitions procurement protocols are converging on trace chemistry disclosure requirements that previously applied only to civilian industrial chemicals. The MIIT directives now mandate third-party verification of solvent recovery rates in nitrocellulose production, while Canberra's domestic content thresholds require audit trails for raw material provenance. Medium-caliber naval and artillery ammunition is experiencing the steepest compliance cost escalation as these dual regulatory frameworks apply simultaneously to export-bound and domestically consumed stocks.
Bundled lifecycle service contracts are displacing transactional ammunition procurement across Southeast Asian defense ministries. Singapore's Ministry of Defence and the Royal Thai Armed Forces are negotiating decade-long availability agreements that wrap storage, inspection, renovation, and disposal into per-round pricing, transferring obsolescence risk to suppliers. This model is most visible in precision-guided mortar and anti-armor systems where electronics degradation timelines complicate traditional stockpile management.
Asia-Pacific Ammunition Market Segmentation
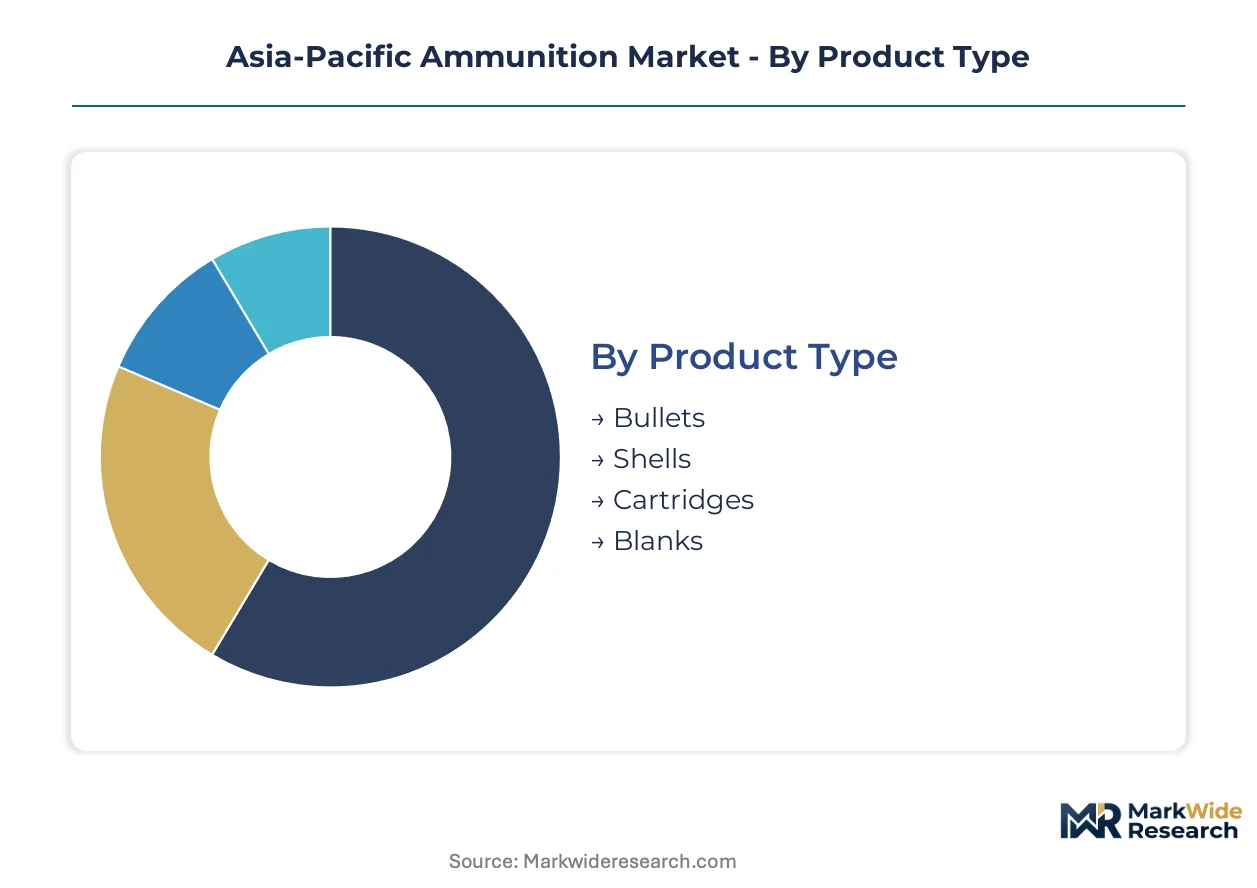
Segmentation in the Asia-Pacific ammunition market reveals how procurement priorities diverge across defense modernization cycles, sovereign manufacturing mandates, and live-fire training intensification. Each dimension exposes distinct supply chain configurations and regulatory exposure points that reshape competitive positioning.
Product Type:
Mature brass-cased systems coexist with emerging polymer and caseless technologies as propellant chemistry evolves under environmental compliance pressure.
- Shells:Artillery and mortar shells incorporate precision guidance electronics that elevate unit value while demanding specialized propellant blending capabilities. Australia's sovereign munitions programs and India's PLI scheme are redirecting capital toward domestic shell forging and filling capacity.
- Cartridges:Complete round assemblies integrate brass casings, propellant charges, primers, and projectiles to precise chamber pressure specifications. Southeast Asian militaries are accelerating orders for NATO-standard intermediate cartridges through technology transfer arrangements with Australian Munitions.
- Bullets:Projectile cores range from lead-ballast conventional designs to tungsten penetrators and polymer-tipped match variants.
- Blanks:Propellant-only configurations for force-on-force training and ceremonial use carry reduced hazardous material classifications.
Cartridges handle the majority of throughput; shells are gaining share fastest on precision-guided demand.
End User:
Procurement concentration varies sharply by budget scale and import licensing friction across the region's defense ministries.
- Military:National armed forces dominate volume through multi-year ammunition acquisition programs covering small arms through naval artillery. India's CEA licensing frameworks and Australia's domestic content thresholds constrain foreign participation without local partnership.
- Law Enforcement:Police and paramilitary units require expanding quantities of less-lethal and duty ammunition for urban security operations. Indonesia's National Police and Royal Malaysia Police are modernizing sidearm inventories with hollow-point defensive rounds.
- Security Forces:Private and government-contracted protection services operate under lighter regulatory oversight with faster procurement cycles.
- Civilian:Sporting and hunting demand concentrates in Australia and New Zealand with strict licensing regimes.
Military commands the procurement volume; law enforcement is expanding most quickly on internal security prioritization.
Application:
Volume distribution reflects the tension between operational readiness requirements and peacetime training economy.
- Defense:Combat-configured ammunition with full-fuzing and terminal effects specifications carries highest unit value and longest development timelines. The Five Power Defence Arrangements and bilateral Australia-Singapore-Malaysia rotations are depleting war reserve stocks.
- Training:Reduced-range and practice projectiles allow higher live-fire tempo without range infrastructure expansion. Philippine and Indonesian forces are consuming 105mm and 155mm training rounds at rates exceeding peacetime replenishment cycles.
- Sports Shooting:Precision rifle and pistol competition ammunition demands lot-to-lot consistency for scoring reliability.
- Hunting:Controlled-expansion projectiles for commercial game harvesting face declining demand as military procurement crowds out propellant supply.
Defense absorbs the dominant procurement value; training is climbing the fastest on exercise tempo escalation.
Caliber:
Size classification determines manufacturing equipment scale, propellant load, and guidance electronics packaging constraints.
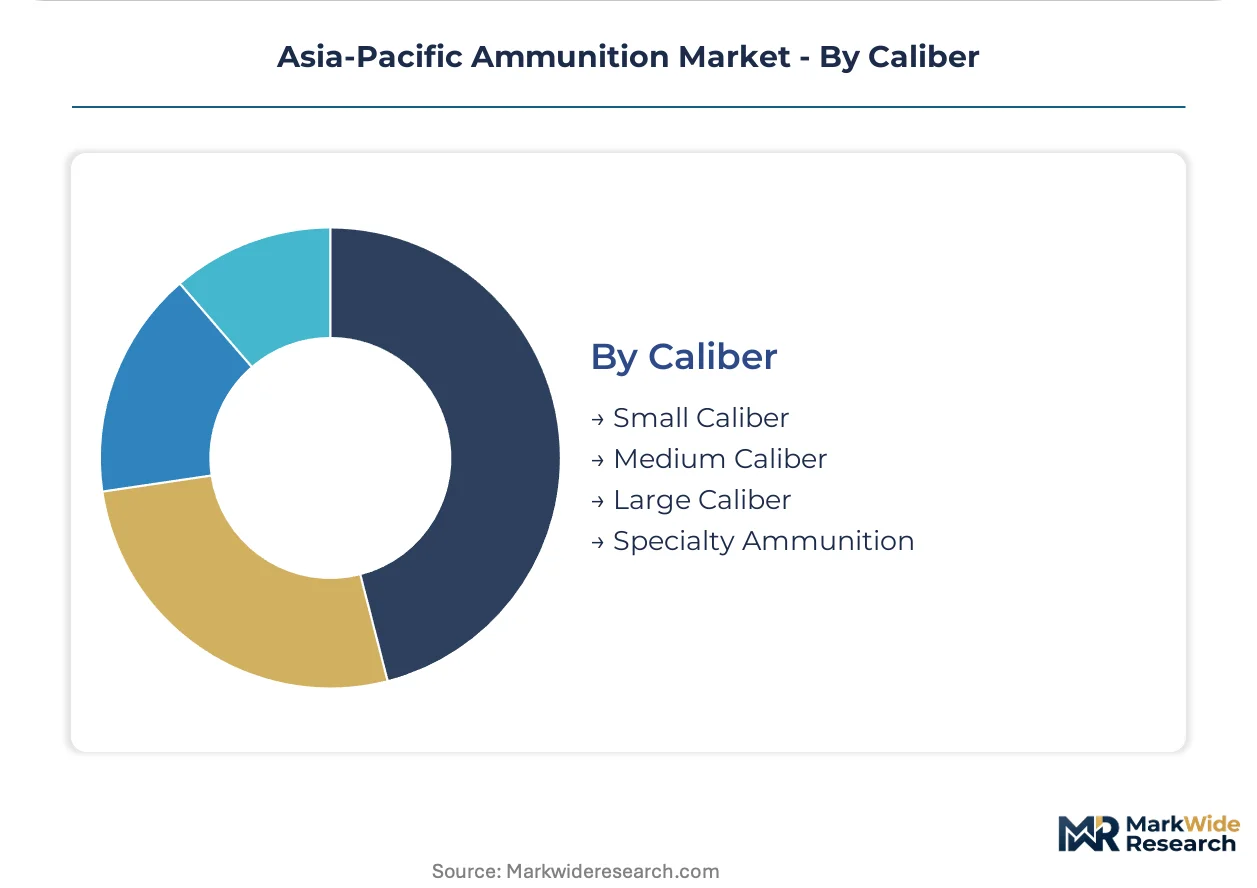
- Specialty Ammunition:Laser-guided mortar rounds, extended-range artillery projectiles, and sniper match ammunition incorporate miniaturized seekers and aerodynamic enhancements. Thailand and Indonesia are fielding 81mm and 120mm precision mortar systems for urban engagement scenarios.
- Small Caliber:Individual weapon rounds from pistol through light machine gun constitute the highest production volume with thinnest margins. Poongsan Corporation's integrated brass and propellant operations dominate South Korean military supply.
- Medium Caliber:Vehicle-mounted automatic cannon and naval gun ammunition bridges individual and artillery applications with moderate batch sizes.
- Large Caliber:Heavy artillery and naval main gun rounds require specialized forging presses and slow-burning propellant formulations.
Small caliber moves the highest round count; specialty ammunition shows the steepest expansion trajectory on precision engagement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Australia and Singapore exhibit the lowest price elasticity, absorbing premium costs for sovereign production and precision-guided systems. Indonesian and Philippine defense ministries operate under tighter fiscal constraints, prioritizing training ammunition volume over unit sophistication.
Australia
The Australian Defence Force's sovereign munitions mandate drives capital into domestic propellant blending and case manufacturing. National defense procurement protocols require domestic content thresholds for critical ordnance, restricting foreign participation without local partnership. Benalla in Victoria hosts Australian Munitions' forging and filling operations, expanding capacity to supply regional training exercises under the Five Power Defence Arrangements.
India
India's PLI scheme redirects supply chains toward domestic brass and propellant manufacturing, compressing import dependency timelines for artillery and small arms ammunition. The CEA and DGFT regulate explosive imports through licensing frameworks that constrain foreign supply without local partnership. The Ordnance Factory Board restructuring and private sector entry concentrate new capacity in Maharashtra and Uttar Pradesh, with Munitions India Limited anchoring state-owned production.
South Korea
Poongsan Corporation's integrated brass and propellant operations dominate military supply, leveraging backward integration into raw material processing. Defense Acquisition Program Administration procurement rules favor domestic sources for ammunition meeting NATO interoperability standards. The Changwon industrial cluster in Gyeongsangnam-do houses Hanwha Corporation's naval gun ammunition production, feeding shipyard partnerships for frigate and destroyer programs.
Japan
Japan Ground Self-Defense Force mandates for insensitive munitions compliance force reformulation of legacy TNT-based fill compositions, elevating procurement costs for domestic and imported stocks. METI and Ministry of Defense policy shifts are loosening post-war export restrictions on finished ammunition, opening previously closed regional supply relationships. The Nammo Lapua partnership and domestic propellant research in the Kanto region position Japanese suppliers for expanded regional role.
Vietnam
The Vietnam People's Navy modernization of frigate-mounted 76mm and 100mm naval artillery creates first-mover advantage for propellant suppliers with NATO-standard compatibility. State-controlled defense procurement channels limit foreign direct sales, requiring technology transfer or joint venture structures. The Z189 shipyard in Hai Phong and associated industrial zones in northern Vietnam concentrate naval ammunition demand as fleet expansion accelerates.
Asia-Pacific Ammunition Market Competitive Environment
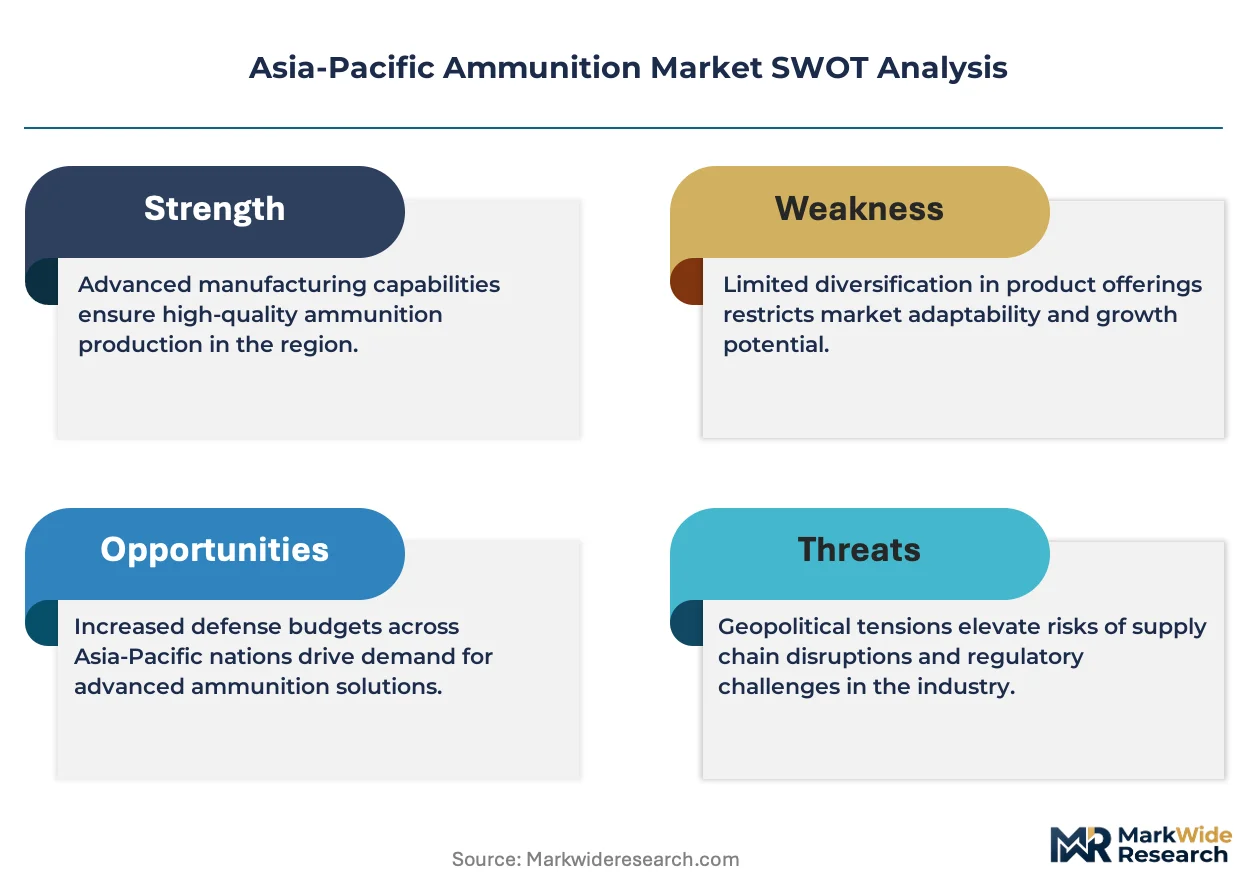
Integrated defense conglomerates and state-owned ordnance enterprises split the market, with the former controlling precision-guided and naval systems while the latter dominate volume production for small and medium calibers. The competitive terrain tilts toward technology licensing arrangements and sovereign production partnerships rather than direct export competition. Three archetypes prevail: vertically integrated Korean and Australian suppliers with captive raw material streams; European defense primes competing via technology transfer; and Chinese state-owned entities leveraging feedstock dominance in nitrocellulose supply. Capacity expansion in domestic propellant blending and strategic partnerships for guided munitions electronics represent the dominant competitive moves.
Among Asia-Pacific-based suppliers, Poongsan Corporation and Hanwha Corporation exemplify the integrated conglomerate archetype, combining metals processing with propellant chemistry. Rheinmetall AG occupies a position as the European technology-transfer anchor, competing through arrangements with Australian Munitions for regional 120mm smoothbore tank round supply. These three entities represent distinct strategic postures: Korean integration, Australian sovereign capacity, and German licensing reach.
| Leading Market Players |
|---|
| Poongsan Corporation |
| Hanwha Corporation |
| BAE Systems |
| General Dynamics Corporation |
| Rheinmetall AG |
| Singapore Technologies Engineering Ltd |
| Munitions India Limited |
| NORINCO |
| Australian Munitions |
| Others |
Value Chain & Pricing Dynamics
China's grip on cotton linters processing for military-grade nitrocellulose funnels margin downstream toward propellant blenders in South Korea and Australia who command premium pricing for sovereign-certified output. Buyers in Southeast Asia face compressed negotiation leverage as feedstock concentration collides with India's PLI-driven import substitution and Australia's domestic content mandates.
Pricing Analysis
Lifecycle service contracts spanning storage, inspection, and disposal now drive lifetime value beyond per-round transactional pricing. Three-tier pricing structure across premium, standard, and economy levels separates precision-guided mortar systems from bulk training ammunition and legacy artillery stocks. Cost compression in small-caliber cartridges is intensifying because Poongsan's integrated brass operations undercut regional competitors on volume tenders. Law enforcement agencies in Indonesia and Malaysia exhibit highest price sensitivity, while Australia's Defence Force absorbs sovereign production premiums without volume elasticity.
Supply Chain Analysis
Tariff exposure between China and regional propellant manufacturers dominates supply chain risk planning across the Asia-Pacific. Nitrocellulose feedstock draws from Chinese cotton linter processors, brass billet supply rests on Australian and South Korean smelters, and guidance electronics sources from Japanese component houses. Single-source vulnerability in Chinese feedstock creates chokepoint exposure for all regional manufacturers outside India's PLI-insulated domestic chain. Distribution runs through national ordnance depots with direct military procurement protocols bypassing commercial logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision-guided munitions proliferation represents a high-growth disruption as electronics miniaturization collapses development cycles and sovereign manufacturing mandates reshape competitive access. India's PLI scheme and Australia's domestic content thresholds constitute the regulatory inflection compressing import-dependent business models.
For Market Incumbents: Build captive propellant chemistry capabilities as the defensive moat. Hanwha Corporation's shipyard partnerships demonstrate how naval ammunition suppliers lock out competitors through platform-integrated supply agreements. Poongsan must deepen backward integration into nitrocellulose precursor processing before Chinese export license volatility disrupts Korean military supply. Certification investment in insensitive munitions formulations represents the priority lever as Australian and Japanese forces mandate IM compliance for all new acquisitions. For New Entrants and Emerging Players: Vietnam's underpenetrated naval gun market for 76mm and 100mm frigate ammunition represents the most penetrable entry point for NATO-standard propellant suppliers. Technology transfer arrangements with Z189 shipyard in Hai Phong bypass state-controlled procurement channel restrictions. Dual-use civilian-military propellant lines offer the optimal go-to-market angle, amortizing R&D across Australian sporting ammunition demand while qualifying for defense contracts. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated suppliers with captive raw material streams and sovereign production partnerships. The 5-to-10-year viability window favors entities controlling brass forging, propellant blending, and filling capacity within single national jurisdictions. Acquisition targets should display established relationships with defense procurement agencies and technology transfer frameworks. The signal to watch is bilateral defense agreement expansion between Australia, Japan, and Southeast Asian partners that loosens historical export restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Chemistry Backward Integration | Captive nitrocellulose supply insulates against Chinese export license volatility. |
| Insensitive Munitions Certification | Australian Defence Force and Japan Ground Self-Defense Force mandates create compliance barrier. |
| Naval Gun Platform Partnerships | Hanwha's shipyard integration locks competitors out of frigate and destroyer programs. |
| Lifecycle Service Contract Bundling | Singapore's Ministry of Defence decade-long availability agreements transfer obsolescence risk. |
| Technology Transfer Arrangements | Rheinmetall's Australian Munitions partnership enables regional 120mm tank round supply. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, propellant chemists, ordnance factory managers, and military logistics coordinators; and secondary validation through customs trade records, national defense budget disclosures, CEA and DGFT regulatory filings, and MIIT environmental compliance directives. Bottom-up triangulation across ammunition production capacity, propellant feedstock flows, and military acquisition program announcements anchored volume estimates. Top-down cross-checks against national defense expenditure patterns and regional training exercise tempo validated demand-side assumptions.
Forecast inputs considered product type segmentation across shells, cartridges, bullets, and blanks; end-user concentration in military, law enforcement, and security forces; application splits between defense and training; and caliber tiering from small arms through specialty precision-guided systems. CAGRs were derived from modeled procurement cycle timelines, platform modernization schedules, and sovereign manufacturing capacity buildout trajectories across the analysis window. Industry-specific inputs included nitrocellulose supply elasticity, bilateral defense agreement expansion patterns, and insensitive munitions compliance adoption curves.
Practitioners should monitor Chinese export license volatility, Indian PLI scheme expansion scope, and Japanese defense equipment transfer policy revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market