
 Global Shoulder-Fired Weapons Market | 2026-2036
Global Shoulder-Fired Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shoulder-Fired Weapons Market Foresight
The direct government procurement channel is narrowing as sole-source contracts give way to competitive multi-vendor frameworks. Lockheed Martin leverages its Javelin production infrastructure to sustain dominance in anti-tank missile supply. Rheinmetall AG anchors European supply security through expanded German and Dutch manufacturing lines.
Shoulder-fired weapons encompass man-portable launch systems typically under 25 kilograms, employing disposable or reloadable tubes to deliver warheads against armor, aircraft, or fortified positions using unguided, command-guided, or homing trajectories. Anti-tank missiles lead product type revenue due to sustained land warfare preparedness in Eastern Europe and the Middle East, while man-portable air defense systems represent the fastest-expanding technology segment driven by drone proliferation. Infrared homing platforms capture premium margins from seekers requiring cryogenic cooling and precision focal plane arrays, whereas wire guidance occupies cost-sensitive procurement tiers.
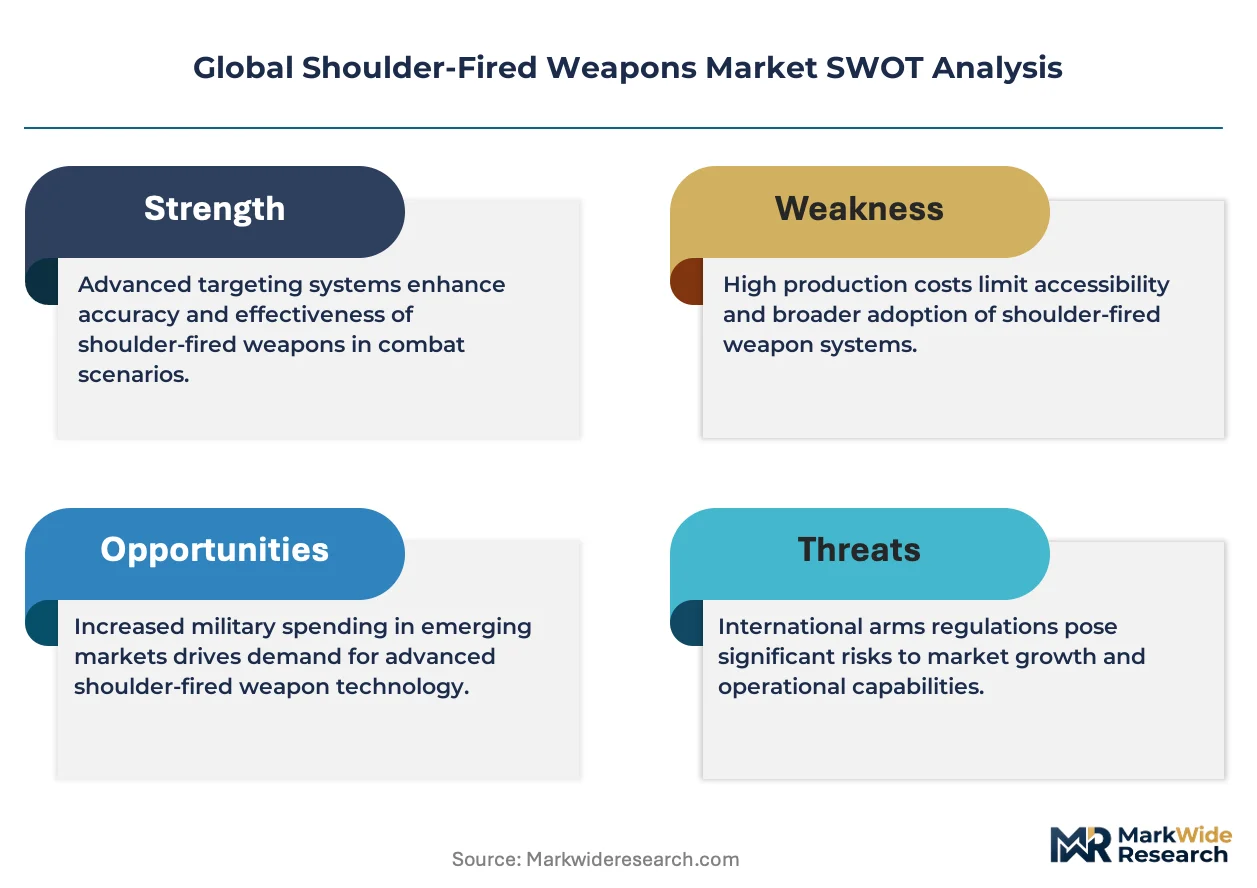
The US Department of State's Directorate of Defense Trade Controls, NATO's Standardization Office, and the Wassenaar Arrangement collectively shape export licensing, interoperability mandates, and technology transfer restrictions governing cross-border shoulder-fired weapons commerce. These frameworks compel manufacturers to maintain dual-use compliance documentation and end-user certification chains for every unit shipped. Stakeholders must monitor evolving counter-UAS doctrine in allied defense ministries to align product roadmaps with emerging engagement scenarios against small unmanned systems.
Market Dynamics
Counter-UAS doctrine across NATO defense ministries is compressing development cycles for infrared homing seekers while redirecting procurement budgets from legacy wire-guided platforms toward precision focal plane array technologies.
Growth Catalysts
- Drone Proliferation Threats:Small unmanned system incidents near military installations in Poland and Australia are accelerating man-portable air defense system orders. Defense ministries now prioritize rapid-deployment countermeasures against low-altitude aerial threats.
- NATO Standardization Office Mandates:Interoperability requirements for ammunition calibers and firing platforms are harmonizing procurement specifications across member states. Manufacturers gain scale advantages through unified technical standards.
- Infantry Modernization Programs:The US Army's Next Generation Squad Weapon initiative and comparable Dutch and German restructuring are replacing aging disposable launchers with reloadable precision systems.
Market Restraints
- Cryogenic Cooler Supply Concentration:Infrared seeker production depends on miniature Stirling cooler imports from a limited supplier base in Germany and the United States. Disruptions cascade into six-month delivery delays for precision-guided units.
- Wassenaar Arrangement Licensing:Dual-use classification of focal plane array technology triggers multi-month export approval processes. End-user certification chains require documentation at each transfer point, constraining rapid fulfillment.
- Wire-Guided Platform Obsolescence:Existing inventory of MCLOS and SACLOS systems faces accelerated depreciation as forces retire training pipelines. Write-down pressures strain defense budgets in fiscally constrained periods.
Strategic Opportunities
- Poland's Eastern Border Consolidation:Territorial defense force expansion creates demand for distributed anti-tank capabilities across dispersed infantry formations. Domestic offset requirements favor co-production arrangements with established suppliers.
- Laser-Guided Convergence:Integration of semi-active laser seekers with existing command launch units enables precision strike without cryogenic cooling. This hybrid architecture reduces unit cost while maintaining accuracy against moving armor.
- Competitive Multi-Vendor Frameworks:Sole-source contract erosion opens qualification pathways for second-tier manufacturers. Australia's defense procurement reforms demonstrate how technical evaluation criteria can diversify supplier pools.
Industry Challenges
- Seeker Calibration Expertise Scarcity:Precision focal plane array alignment requires technicians trained in cryogenic test protocols. Military maintenance depots and contractor facilities compete for this limited talent pool.
- Legacy System Integration Complexity:New infrared homing platforms must interface with existing command and control networks. Software architecture incompatibilities extend fielding timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shoulder-Fired Weapons Market |
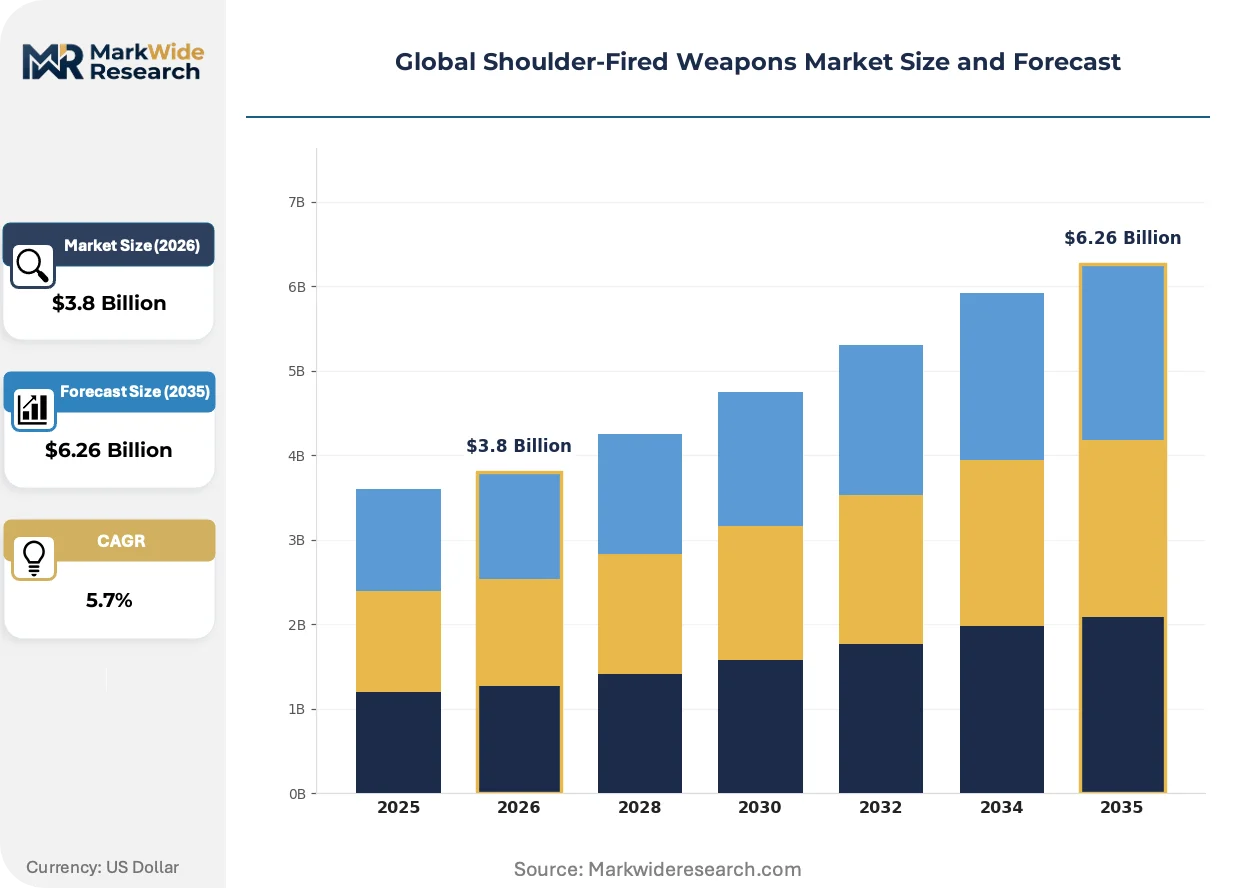
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rocket Launchers, Anti-Tank Missiles, Man-Portable Air Defense Systems, Recoilless Rifles, Grenade Launchers Technology: Infrared Homing, Laser Guidance, Wire Guidance, Command Guidance, Optical Tracking Application: Infantry, Special Forces, Peacekeeping, Counterterrorism, Border Security End User: Defense Forces, Paramilitary Units, Law Enforcement Agencies, Security Contractors, Tactical Teams |
| Companies Covered | MBDA, Thales Group, Lockheed Martin Corporation, General Dynamics Corporation, BAE Systems plc, RTX Corporation, Rafael Advanced Defense Systems Ltd., Rheinmetall AG, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shoulder-Fired Weapons Market Shifts & Advancements
Digital seeker architectures are displacing analog signal processing in next-generation shoulder-fired systems, compressing target acquisition timelines while enabling firmware updates that extend platform service lives without hardware replacement.
Software-defined seeker processing is virtualizing traditional hardware functions within man-portable air defense systems. The US Department of Defense's counter-UAS program office is accelerating adoption through rapid prototyping contracts. This virtualization is enabling post-manufacture capability upgrades via encrypted firmware distribution rather than physical retrofits.
EU F-Gas Regulation restrictions on hydrofluorocarbon coolants are forcing infrared seeker manufacturers toward closed-cycle sterling engines and thermoelectric alternatives. Industrial consequence includes redesign of focal plane array thermal management subsystems. European procurement agencies now specify coolant-free operation in technical requirements, disadvantaging legacy cryogenic architectures.
Defense ministries are unbundling training and logistics support from weapon system procurement, creating discrete service contract markets. Prime contractors now compete separately on instruction system design and field maintenance provision. Australia's infantry modernization program exhibits this most visibly through standalone technical manual and simulator acquisition tracks.
Global Shoulder-Fired Weapons Market Segmentation
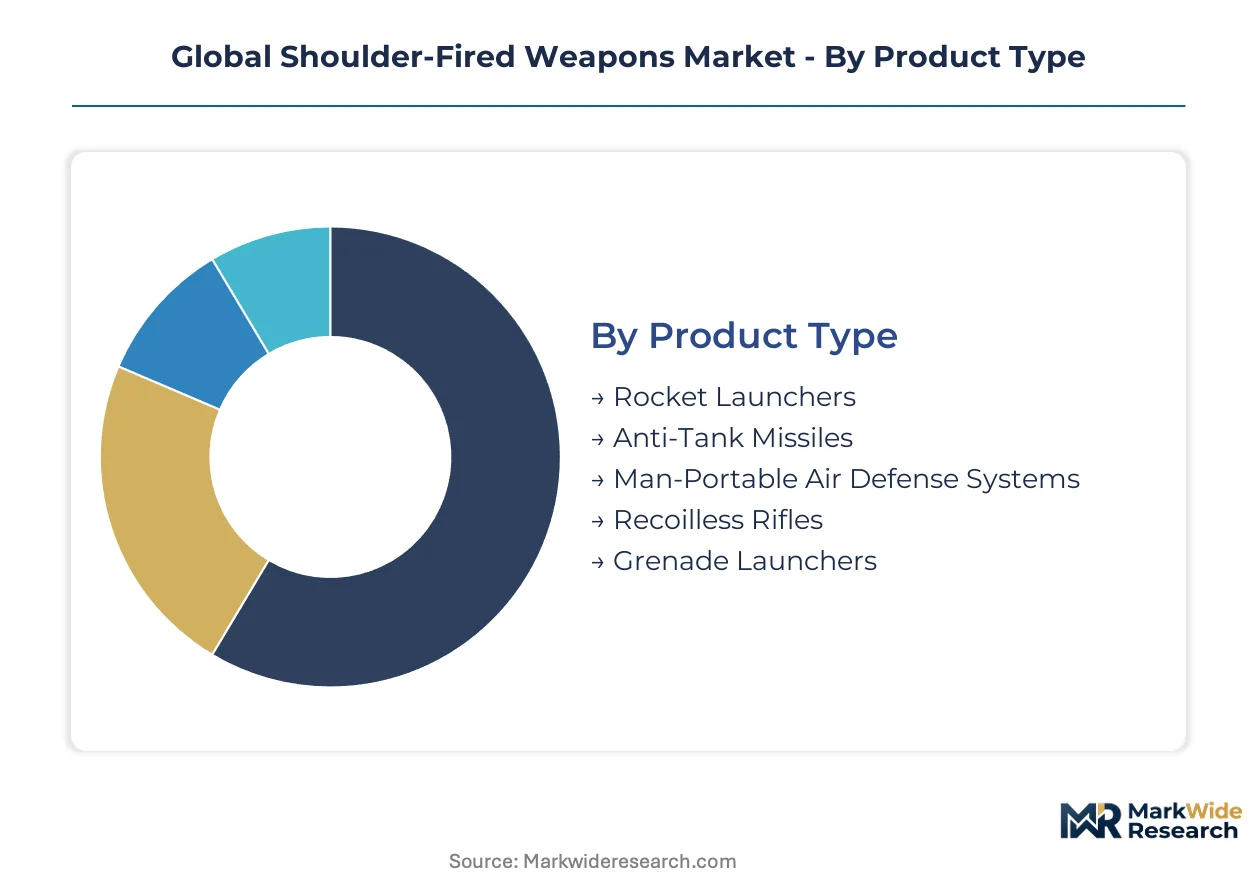
Segmentation of the Global Shoulder-Fired Weapons Market reveals distinct procurement patterns across product architectures, guidance technologies, and operational end-uses. Each dimension carries divergent after-sales-service intensities, from disposable launcher disposal protocols to precision seeker recalibration contracts spanning decades.
Product Type:
After-sales-service intensity varies sharply across launcher categories, with reloadable precision systems demanding sustained depot maintenance while disposable tubes require only decommissioning logistics.
- Anti-Tank Missiles:Reloadable tube-launch systems with tandem warhead configurations penetrate reactive armor through precursor charges. Demand concentrates in Poland and Germany as NATO's eastern flank consolidates territorial defense formations against mechanized threats.
- Man-Portable Air Defense Systems:Lightweight launchers with infrared or laser seeker integration engage low-altitude aircraft and unmanned systems. Australia's infantry modernization program is accelerating procurement amid drone proliferation incidents near military installations.
- Rocket Launchers:Unguided or fin-stabilized projectile systems deliver high-explosive fragmentation against fortified positions.
- Recoilless Rifles:Smoothbore or rifled man-portable guns firing shaped-charge or high-explosive projectiles without significant backblast.
- Grenade Launchers:Single-shot or multi-shot systems propelling 40mm or smaller munitions for area suppression.
By volume, Rocket Launchers lead. By growth pace, Man-Portable Air Defense Systems are climbing the fastest.
Technology:
Cost tier stratification separates cryogenically cooled precision seekers from command-guided alternatives, with unit price differentials exceeding an order of magnitude between infrared homing and wire-guided platforms.
- Infrared Homing:Cryogenically cooled focal plane array seekers detect thermal signatures through miniature Stirling cooler subsystems. Germany's supplier concentration for these coolers creates six-month delivery delays when disruptions occur.
- Laser Guidance:Semi-active laser seekers receive reflected energy from designated targets without onboard cooling requirements. The US Department of Defense's counter-UAS program office is accelerating adoption through rapid prototyping contracts.
- Wire Guidance:Command-to-line-of-sight systems transmit steering commands via trailing fiber optic or copper wires.
- Command Guidance:Operator-controlled trajectory correction through joystick or trackball interfaces with optical sighting.
- Optical Tracking:Unguided platforms relying on ballistic calculation and visual alignment for target engagement.
By revenue capture, Infrared Homing dominates. By expansion trajectory, Laser Guidance is gaining share fastest.
Application:
Volume concentration in conventional infantry formations contrasts with premium pricing commanded by specialized units requiring reduced-signature launch signatures and rapid deployment capabilities.
- Infantry:Standard mechanized and light infantry formations employ shoulder-fired weapons for organic anti-armor and air defense capabilities. Polish territorial defense force expansion is distributing launchers across dispersed formations without dedicated air defense attachments.
- Special Forces:Covert insertion teams prioritize collapsible launchers with reduced thermal and acoustic signatures. Dutch special operations command structures specify man-portable systems compatible with maritime infiltration craft.
- Peacekeeping:Multinational stabilization missions deploy deterrent capabilities without rules-of-engagement authorization for offensive employment.
- Counterterrorism:Urban intervention units require minimum-safe-distance calculations for confined-space employment.
- Border Security:Static and mobile patrol elements along contested frontiers maintain area denial against low-altitude incursions.
By procurement volume, Infantry leads. By capability premium, Special Forces commands the steepest unit pricing.
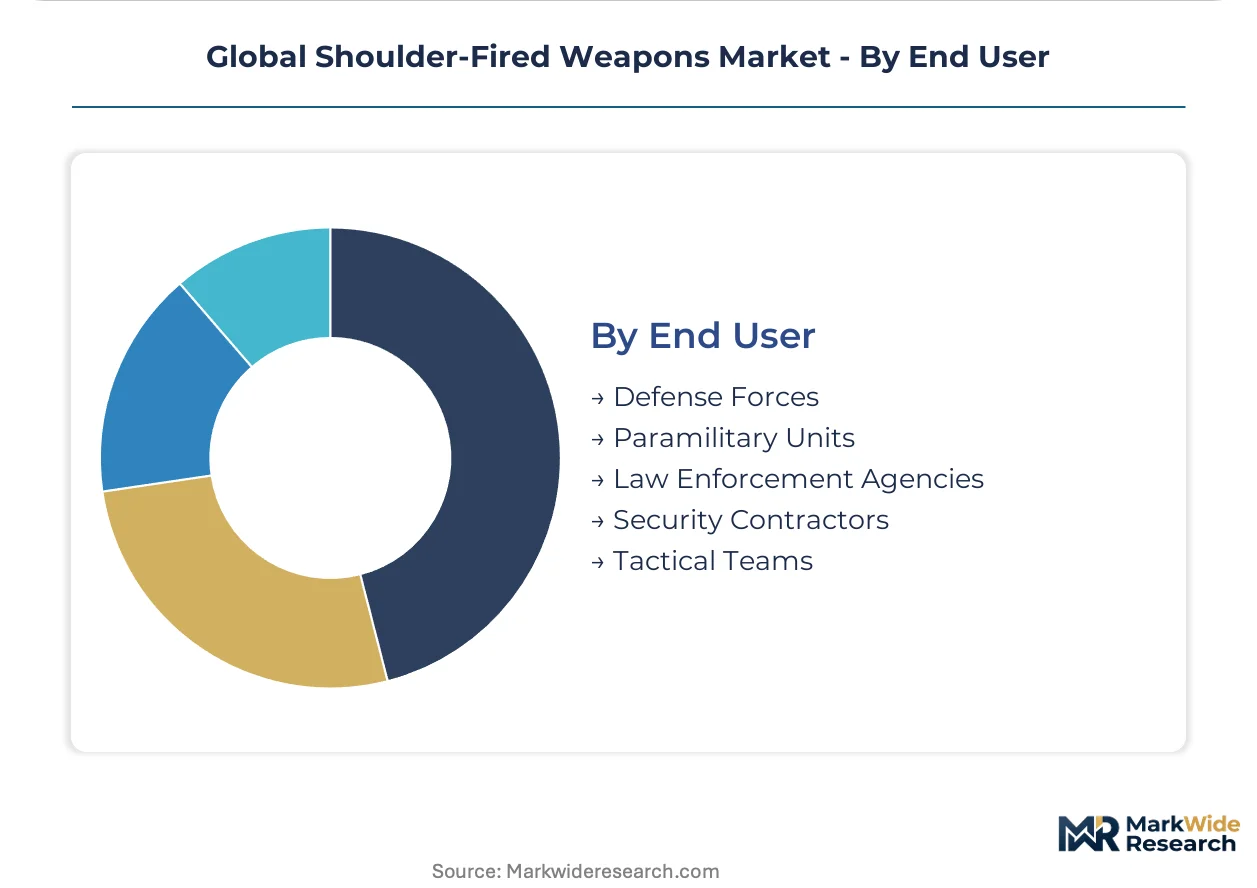
End User:
Customer-type segmentation separates sovereign defense procurement with full certification chains from security contractor acquisitions facing Wassenaar Arrangement licensing constraints.
- Defense Forces:National military services with standing procurement authority and technical evaluation infrastructure. The US Army's Next Generation Squad Weapon initiative exemplifies multi-year modernization with reloadable precision system requirements.
- Paramilitary Units:Gendarmerie, coast guard, and internal security formations with overlapping defense and law enforcement mandates. Australia's defense procurement reforms demonstrate how technical evaluation criteria can diversify supplier pools for these units.
- Law Enforcement Agencies:Police tactical teams with limited authorization for high-explosive munitions deployment.
- Security Contractors:Private military companies operating under government contract with restricted end-user certification pathways.
- Tactical Teams:Specialized intervention units within prison services, nuclear security, or critical infrastructure protection.
By contract value, Defense Forces lead. By procurement reform velocity, Paramilitary Units are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement reforms across NATO member states are redistributing manufacturing capacity toward eastern flank nations. The Wassenaar Arrangement continues to shape export licensing timelines for precision-guided systems.
United States
The US Army's Next Generation Squad Weapon initiative drives reloadable precision launcher requirements. The Department of State's Directorate of Defense Trade Controls administers multi-month export approval processes for focal plane array technology. Production clusters concentrate in Arizona and Texas, where prime contractors maintain cryogenic cooler integration facilities.
Poland
Territorial defense force expansion creates distributed demand for anti-tank capabilities across dispersed infantry formations. Domestic offset requirements under the Ministry of National Defense favor co-production arrangements with established European suppliers. Industrial activity clusters in Warsaw and the Silesian Voivodeship, where assembly partnerships with German manufacturers are advancing.
Germany
Rheinmetall AG anchors European supply security through expanded manufacturing lines in Unterlüß and Düsseldorf. The EU F-Gas Regulation restricts hydrofluorocarbon coolants, forcing redesign of focal plane array thermal management. Bavaria hosts precision seeker calibration facilities competing for scarce technician talent with military maintenance depots.
Australia
Drone proliferation incidents near military installations accelerate man-portable air defense system orders through the Department of Defence's infantry modernization program. Competitive multi-vendor frameworks under the 2020 Defence Strategic Update diversify supplier pools beyond traditional sole-source channels. Procurement activity concentrates in Canberra and Victoria, where technical evaluation criteria are being rewritten.
Netherlands
Special operations command structures specify man-portable systems compatible with maritime infiltration craft. NATO Standardization Office mandates harmonize ammunition calibers across Dutch-German joint procurement frameworks. The Eindhoven region hosts integration facilities for laser-guided convergence architectures.
Global Shoulder-Fired Weapons Market Competitive Landscape
On the supply side, the industry is consolidating around defense primes with captive seeker production capabilities and reloadable launcher manufacturing infrastructure. Tiered competition separates cryogenically cooled precision platforms from command-guided alternatives with order-of-magnitude unit price differentials. Strategic archetypes include integrated system primes, seeker subsystem specialists, and tube fabrication contractors. Dominant competitive moves encompass strategic partnerships for offset compliance and capacity expansion into eastern NATO markets.
Within the integrated prime tier, Lockheed Martin Corporation and Rheinmetall AG exemplify divergent geographic anchoring strategies. RTX Corporation occupies a position bridging precision seeker development with reloadable launcher production. MBDA represents the European collaborative model, sitting within a multi-national shareholder structure that shapes export licensing pathways.
| Leading Market Players |
|---|
| MBDA |
| Thales Group |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| BAE Systems plc |
| RTX Corporation |
| Rafael Advanced Defense Systems Ltd. |
| Rheinmetall AG |
| Saab AB |
| Others |
Supply & Pricing Matrix
German and US miniature Stirling cooler production concentrates precision-guided platform margins in cryogenically cooled seeker tiers, while wire-guided alternatives compete on unit cost without thermal management dependencies. This upstream bottleneck shapes downstream pricing power across NATO procurement frameworks.
Pricing Analysis
Volume-discount tiering structures separate multi-year framework agreements for defense forces from spot procurement by paramilitary units. Price differentiation rests on certification grade—Wassenaar-compliant focal plane arrays command premiums against command-guided alternatives—and after-sales service bundling. Cost compression in wire-guided tiers intensifies as forces accelerate obsolescence write-downs. Paramilitary units exhibit highest price sensitivity; special forces commands accept steepest premiums for reduced-signature platforms.
Supply Chain Analysis
Wassenaar Arrangement dual-use classifications constrain focal plane array flows from Germany and the United States into end-user certification chains. Raw material dependencies center on indium antimonide detector substrates, sapphire window assemblies, and rare-earth magnet components for Stirling cooler motors. Single-source vulnerability concentrates in Bavarian precision seeker calibration facilities. Distribution runs through prime contractor integration sites in Arizona, Texas, and Unterlüß before military depot handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in seeker recalibration and firmware upgrade contracts are expanding faster than hardware procurement as software-defined architectures extend platform lifecycles without tube replacement.
For Market Incumbents: Build captive seeker production moats through backward integration into focal plane array manufacturing. Expand calibration facility capacity in Poland to satisfy eastern flank offset requirements. Lockheed Martin's Javelin infrastructure demonstrates how reloadable launcher dominance resists modular substitute threats from laser-guided convergence architectures. For New Entrants and Emerging Players: Australia's competitive multi-vendor frameworks under the 2020 Defence Strategic Update represent the most penetrable entry point for second-tier manufacturers lacking Wassenaar certification histories. Polish territorial defense force co-production arrangements offer offset-compliant partnership pathways. Pursue standalone simulator and technical manual acquisition tracks unbundled from prime weapon system contracts. For Investors and Strategic Acquirers: Capital is best deployed toward seeker subsystem specialists with cryogenic test protocol expertise and software-defined processing capabilities. Long-term viability hinges on counter-UAS doctrine alignment across NATO defense ministries. Monitor US Department of Defense rapid prototyping contract awards as inflection indicators for laser-guided platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Production Partnership | Polish offset requirements under Ministry of National Defense directives favor German manufacturing alliances. |
| Software-Defined Seeker Development | US Department of Defense counter-UAS program office rapid prototyping accelerates firmware-upgradeable platform adoption. |
| Calibration Facility Expansion | Bavarian and Arizona sites compete for scarce cryogenic test protocol technicians against military depots. |
| Laser-Guided Convergence Investment | Semi-active laser seekers bypass EU F-Gas Regulation coolant restrictions while maintaining precision strike accuracy. |
| Multi-Vendor Framework Qualification | Australian technical evaluation criteria diversification opens supplier pools beyond traditional sole-source channels. |
Research Methodology
Cross-validation between defense procurement officer interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork encompassed program managers at NATO Standardization Office, export licensing specialists at the US Department of State's Directorate of Defense Trade Controls, prime contractor business development leads, and territorial defense force procurement coordinators. Secondary sources included Wassenaar Arrangement control list updates, EU F-Gas Regulation implementation guidance, national defense white papers, and customs trade data for focal plane array component flows. Bottom-up unit shipment estimates triangulate against top-down defense budget allocation analysis.
Calibration against historical procurement cycles and announced modernization program timelines shapes the projection framework across the analysis window. Segmentation dimensions encompass product architecture, guidance technology tier, operational application, and end-user certification pathway. CAGRs derive from weighted average growth assumptions across infrared homing, laser guidance, and command-guided technology trajectories. Forecast inputs integrate drone proliferation incident frequency data and counter-UAS doctrine evolution signals from allied defense ministries.
Practitioners should monitor cryogenic cooler supply disruptions, Wassenaar licensing timeline extensions, and counter-UAS program office funding reallocations for early signals. Forecasts reflect documented assumptions regarding NATO eastern flank consolidation pace and infantry modernization program execution. Material shifts in EU F-Gas Regulation enforcement severity or US export control classification revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Anti-Tank Missile System Market