
 Levant Power Cable Market | 2026-2036
Levant Power Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Levant Power Cable Market Analysis
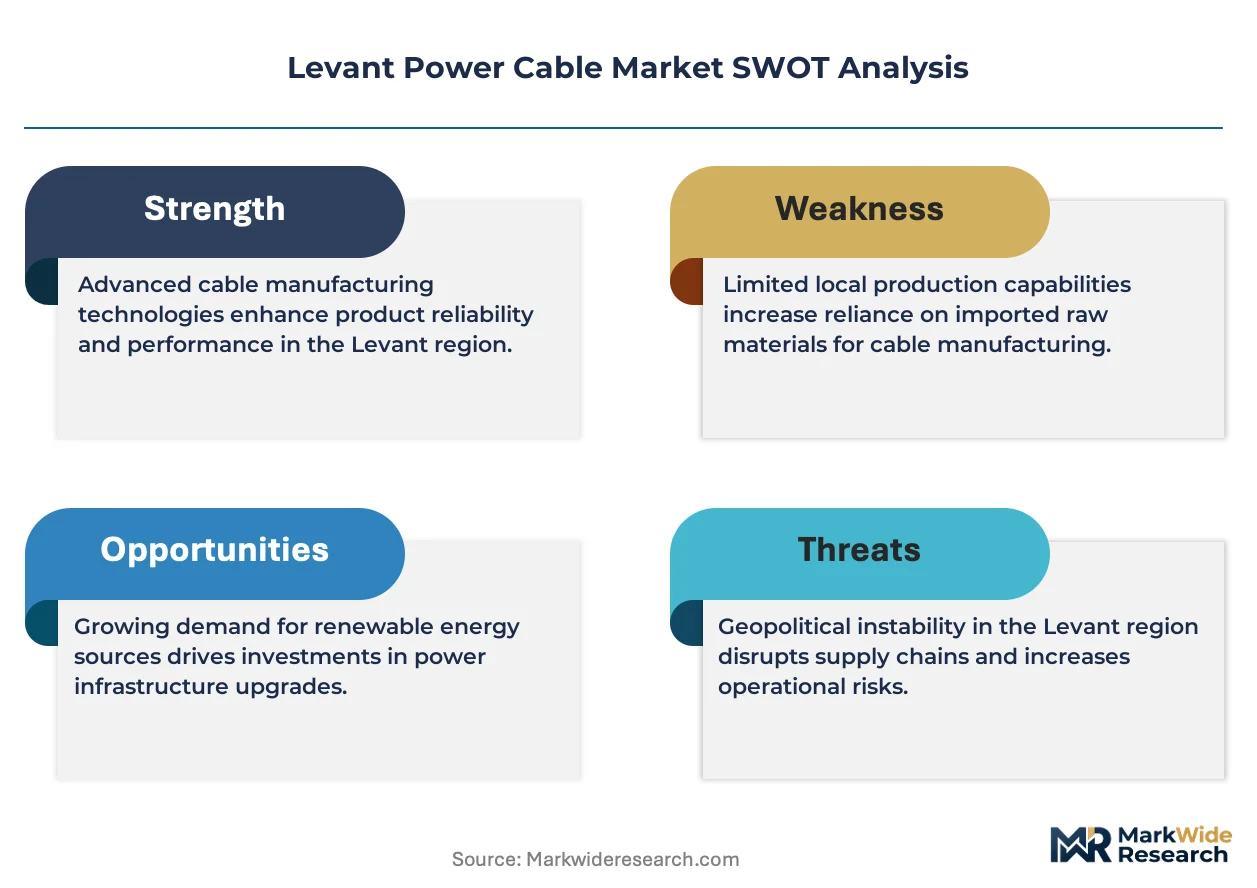
Levant cable manufacturing is consolidating around integrated producers with captive copper drawing and compounding capabilities. El-Sewedy Cables leverages its Egyptian production base to supply cross-border medium voltage projects across Jordan and Lebanon. Liban Cables anchors domestic demand through specialized low voltage distribution lines serving Beirut's rebuilding commercial sector. Prysmian Group competes on high voltage submarine and land cable technology for interconnection schemes linking Levant grids to neighboring systems.
Levant power cables are insulated conductive assemblies rated from 0.6/1 kV through 220 kV, manufactured via continuous vulcanization of cross-linked polyethylene or ethylene propylene rubber over stranded copper or aluminum conductors, designed to transmit electrical energy across transmission networks, distribution grids, and facility interconnections in climates with high thermal cycling and saline exposure. Medium voltage cables dominate procurement volumes as utilities replace aged overhead networks with underground infrastructure in Amman, Damascus, and coastal Lebanese cities. Specialty cables represent the fastest-expanding product category, driven by offshore wind export corridors and solar farm collector systems requiring flame-retardant, halogen-free sheathing compounds. Underground installation commands premium positioning due to civil engineering complexity and regulatory mandates for aesthetic and safety compliance in urban cores.
Jordan's Ministry of Energy and Mineral Resources enforces IEEE 404 and IEC 60502 compliance for all utility procurement, while Lebanon's Order of Engineers mandates French NF C 33-226 standards for public distribution cables, creating dual certification burdens for regional suppliers. Syria's General Organization for Textile Industries and Electrical Industries maintains state-controlled import licensing for copper and aluminum feedstock, constraining private cable production scaling. Stakeholders must monitor how Gulf interconnection agreements and potential harmonization with GCC electrical standards could reshape certification requirements and supplier qualification protocols across the Levant.
Market Dynamics
Grid undergrounding mandates across Jordan and Lebanon are forcing utilities to replace decades-old overhead infrastructure with XLPE-insulated medium voltage cables, compressing installation timelines and rewiring procurement specifications toward fire-resistant sheathing compounds.
Growth Catalysts
- IEEE 404 Compliance Mandates:Jordan's Ministry of Energy and Mineral Resources enforces rigorous testing protocols for utility procurement, disqualifying non-certified suppliers and elevating technical barriers that favor established compounders with in-house vulcanization lines.
- Amman-Irbid Industrial Corridor:Dense manufacturing clusters are driving 33 kV distribution upgrades as textile and pharmaceutical facilities demand redundant feeder reliability for continuous production cycles.
- Halogen-Free Sheathing Chemistry:Lebanese coastal cities are specifying low-smoke zero-halogen compounds for underground installations in Beirut's rebuilt commercial districts, creating material specification premiums for compliant cable stock.
Market Restraints
- Copper Feedstock Licensing:Syria's state-controlled import permits for copper cathode constrain private cable manufacturers from scaling continuous casting operations, forcing reliance on scrap-fed rod breakdown mills with higher resistivity variance.
- Dual Certification Burden:Suppliers serving both Jordan and Lebanon must maintain parallel testing regimens under IEEE 404 and NF C 33-226 standards, inflating qualification costs and extending tender pre-approval cycles.
- Aluminum Conductor Substitution:Distribution utilities in cost-constrained segments are specifying all-aluminum alloy conductors for low-voltage secondary networks, compressing copper-intensive cable demand in residential electrification projects.
Strategic Opportunities
- Solar Farm Collector Systems:Jordan's renewable integration targets are creating demand for 1.8/3 kV DC-rated flexible cables with UV-resistant sheathing for photovoltaic string wiring in Ma'an and Tafila governorates.
- GCC Interconnection Alignment:Potential harmonization with Gulf Cooperation Council electrical standards would streamline supplier qualification protocols, enabling Egyptian and Turkish manufacturers to bid Levant tenders without redundant factory audits.
- Offshore Wind Export Corridors:Lebanese coastal waters present early-stage potential for submarine cable landing stations, requiring 132 kV three-core XLPE designs with lead alloy sheathing for submarine burial.
Industry Challenges
- Compounder Technician Shortage:Levant universities produce insufficient polymer chemists trained in peroxide cross-linking kinetics, forcing cable plants to recruit from Egyptian and Turkish labor pools with higher relocation premiums.
- Legacy Overhead Integration:Damascus utilities face complex phasing challenges when splicing new underground XLPE circuits into existing oil-paper insulated overhead networks with mismatched impedance characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Levant Power Cable Market |
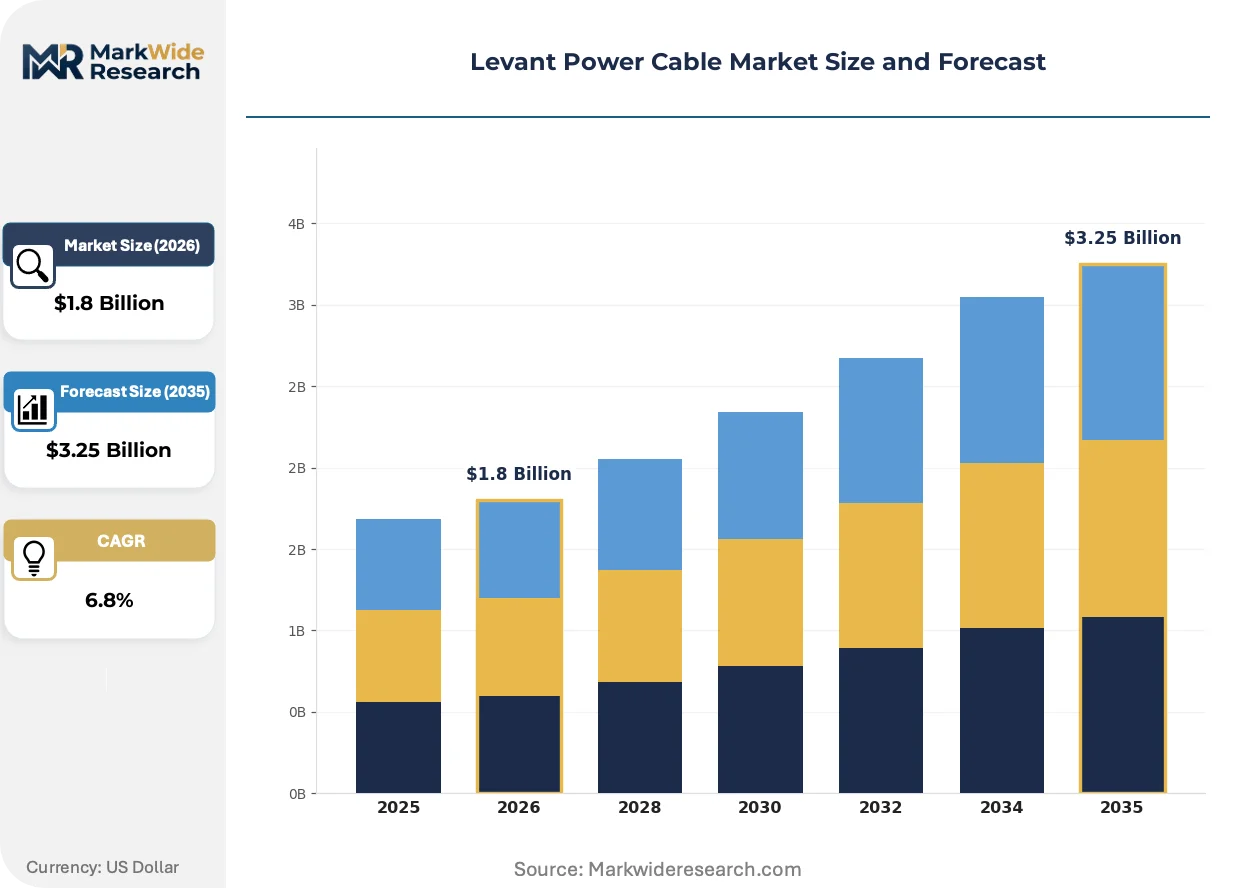
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage Cables, Medium Voltage Cables, High Voltage Cables, Specialty Cables Application: Industrial Applications, Residential Installations, Commercial Buildings, Renewable Energy Material: Copper, Aluminum, Fiber Optic, PVC Installation: Underground, Overhead, Indoor, Outdoor |
| Companies Covered | Prysmian Group, Southwire Company, Liban Cables, Riyadh Cables, DUCAB Cables, El-Sewedy Cables, Nexans, Bahra Advanced Cable Manufacture, MESC Jordan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Levant Power Cable Market Emerging Trajectories
Material science advances and procurement digitization are compressing traditional cable specification cycles while elevating performance thresholds for thermal cycling resistance in saline environments.
Cross-linked polyethylene compounding with triple-layer extrusion is decentralizing manufacturing footprints across the Levant. Jordanian utilities are adopting this technology for 11 kV distribution rebuilds in Zarqa and Aqaba. The shift is decentralizing supply chain control from integrated Egyptian producers toward localized joint ventures with European technology licensors.
Lebanon's Order of Engineers has tightened NF C 33-226 fire propagation testing for public distribution cables. The regulation mandates additional smoke density measurements and halogen content verification for all Beirut municipality tenders. Low-voltage residential cable suppliers are responding by reformulating PVC compounds with calcium-zinc stabilizers replacing lead-based alternatives.
Utility procurement teams are consolidating vendor panels through pre-qualified framework agreements rather than project-by-project tendering. Jordan's National Electric Power Company has compressed its approved supplier list from twelve to four cable manufacturers for medium voltage categories. This consolidation is most visible in Amman, where engineering consultants now specify exclusively from framework-approved stock lists.
Levant Power Cable Market Segmentation
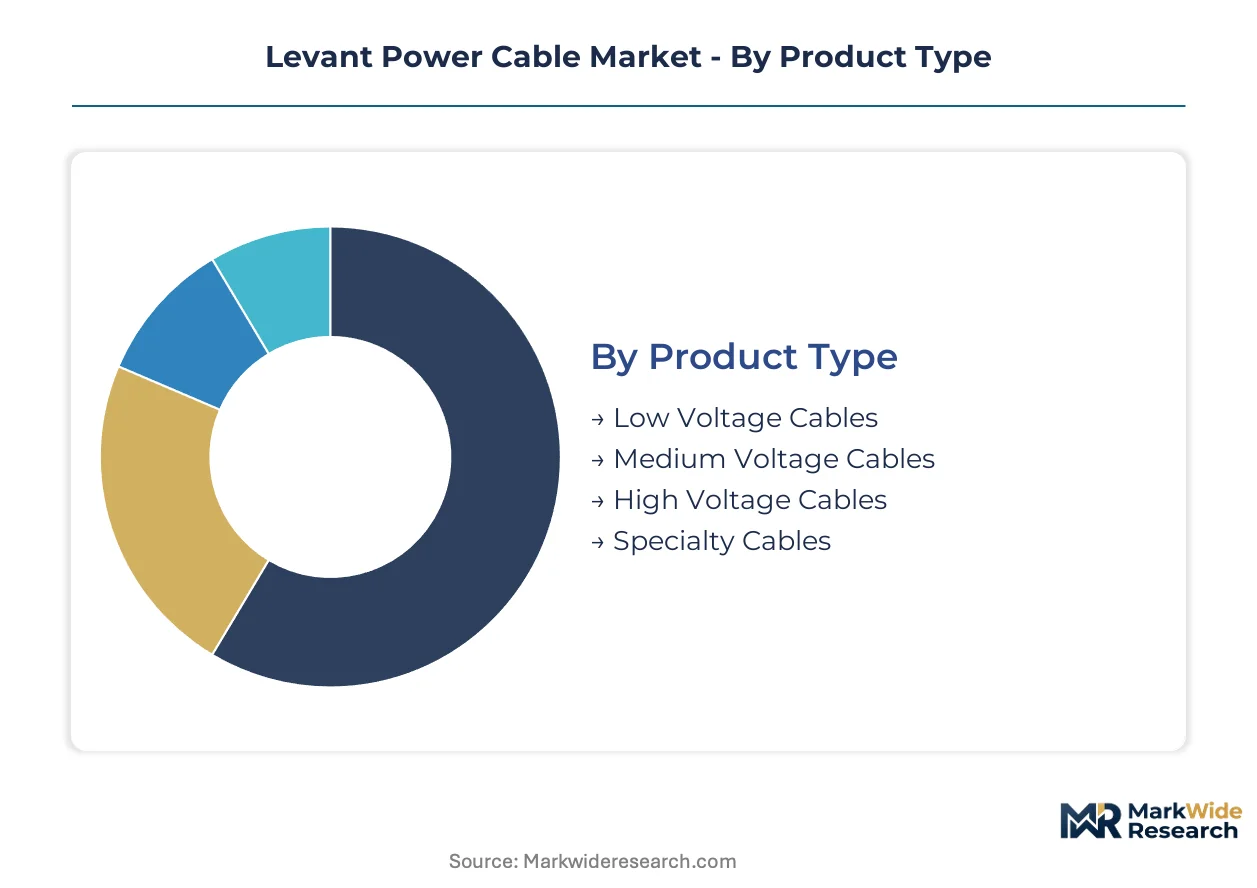
Procurement specifications across Jordan, Lebanon, and Syria fragment cable demand across four intersecting dimensions. Product voltage ratings, end-use applications, conductor materials, and installation methods each impose distinct certification burdens and margin profiles on regional suppliers.
Product Type:
Supply concentration favors integrated compounders with captive vulcanization lines serving utility procurement panels.
- Medium Voltage Cables:These XLPE-insulated assemblies rated 6/10 kV through 33 kV dominate utility procurement volumes as Jordan's National Electric Power Company replaces overhead networks in Amman and Zarqa. IEEE 404 compliance mandates compress supplier qualification to four framework-approved manufacturers.
- Specialty Cables:Halogen-free sheathing compounds and UV-resistant designs for solar farm collector systems are expanding most quickly in Ma'an and Tafila governorates where renewable integration targets reshape material specifications.
- Low Voltage Cables:PVC-sheathed 0.6/1 kV distribution lines serve Beirut's rebuilt commercial sector under tightened NF C 33-226 fire propagation standards.
- High Voltage Cables:132 kV three-core XLPE designs with lead alloy sheathing target submarine burial for potential Lebanese offshore wind export corridors.
Today's leader: Medium Voltage Cables. Tomorrow's challenger: Specialty Cables.
Application:
Cost tier segmentation separates premium-specification industrial demand from price-sensitive residential electrification.
- Industrial Applications:Textile and pharmaceutical facilities along Jordan's Amman-Irbid corridor demand redundant 33 kV feeder reliability with continuous production cycle protection. Halogen-free specifications command material premiums in Lebanese coastal manufacturing zones.
- Renewable Energy:Photovoltaic string wiring in Jordan's southern governorates requires 1.8/3 kV DC-rated flexible cables with UV-resistant sheathing compounds.
- Commercial Buildings:Beirut municipality tenders mandate smoke density measurements and calcium-zinc stabilized PVC replacing lead-based alternatives.
- Residential Installations:Cost-constrained distribution utilities specify all-aluminum alloy conductors for low-voltage secondary networks, compressing copper-intensive cable demand.
Industrial Applications anchor current procurement value. Renewable Energy climbs the fastest as Jordan's Ministry of Energy and Mineral Resources accelerates solar farm interconnection.
Material:
Volume concentration tilts toward copper-intensive specifications where IEEE 404 and NF C 33-226 certification barriers protect qualified suppliers.
- Copper:Stranded copper conductors dominate medium voltage utility procurement despite Syria's state-controlled import licensing constraining private manufacturer scaling from continuous casting operations.
- Aluminum:All-aluminum alloy conductors gain share in cost-constrained low-voltage residential segments as utilities optimize procurement spend.
- PVC:Reformulated compounds with calcium-zinc stabilizers replace lead-based alternatives under Lebanese Order of Engineers mandates for public distribution cables.
- Fiber Optic:Composite power-communication hybrid cables integrate into smart grid pilot programs across Amman's undergrounding rebuilds.
Copper maintains certification-protected dominance. Aluminum gains share fastest in price-sensitive secondary distribution.
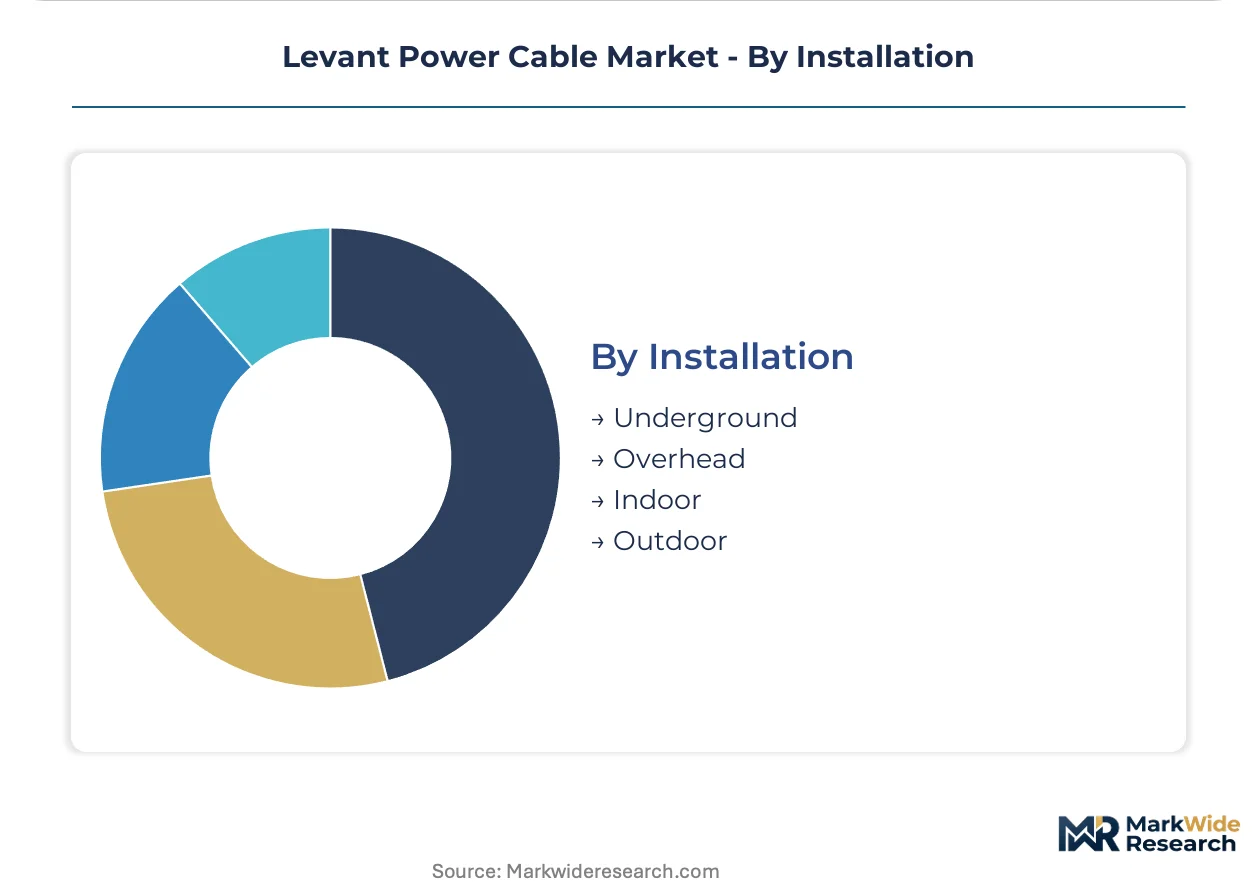
Installation:
Margin structure separates underground premium positioning from overhead commodity pricing.
- Underground:Civil engineering complexity and regulatory mandates for aesthetic compliance in dense urban cores command premium positioning across Amman, Damascus, and coastal Lebanese cities.
- Overhead:Legacy oil-paper insulated networks in Syria face complex phasing challenges when splicing into new underground XLPE circuits with mismatched impedance characteristics.
- Indoor:Low-smoke zero-halogen specifications dominate Beirut's rebuilt commercial districts under tightened fire safety codes.
- Outdoor:UV-resistant sheathing compounds protect photovoltaic string wiring exposed to high thermal cycling in Jordan's southern desert governorates.
Underground installation captures premium margins. Outdoor specifications expand most quickly alongside renewable energy deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cable production geography across the Levant as manufacturers migrate toward jurisdictions with streamlined certification regimes and lower compliance costs.
Jordan
The Amman-Irbid industrial corridor drives procurement of 33 kV distribution infrastructure as textile and pharmaceutical facilities demand redundant feeder reliability. Jordan's Ministry of Energy and Mineral Resources enforces IEEE 404 compliance mandates that compress supplier qualification to four framework-approved manufacturers. Zarqa and Aqaba host localized joint ventures with European technology licensors adopting triple-layer extrusion for 11 kV distribution rebuilds.
Lebanon
Beirut's rebuilt commercial sector anchors demand for low-voltage distribution lines with halogen-free sheathing compounds. The Order of Engineers mandates NF C 33-226 fire propagation testing with additional smoke density measurements for all municipality tenders. Coastal manufacturing zones specify low-smoke zero-halogen materials, creating material specification premiums for compliant cable stock.
Syria
Damascus utilities face complex phasing challenges when integrating new underground XLPE circuits into legacy oil-paper insulated overhead networks. The General Organization for Textile Industries and Electrical Industries maintains state-controlled import licensing for copper and aluminum feedstock. Private cable manufacturers rely on scrap-fed rod breakdown mills with higher resistivity variance, constraining production scaling.
Iraq
Reconstruction-driven electrification projects in Baghdad and Basra are creating demand for medium voltage cable infrastructure to replace war-damaged distribution networks. The Ministry of Electricity operates centralized procurement with limited technical specification enforcement. Cross-border supply from Turkish and Iranian manufacturers fills procurement gaps where domestic production remains underdeveloped.
Palestinian Territories
Gaza and West Bank distribution utilities operate under dual regulatory frameworks with limited standard harmonization between Palestinian Authority and Israeli Civil Administration jurisdictions. Industrial zones in Jenin and Hebron require low-voltage infrastructure upgrades for manufacturing cluster electrification. Import dependency through Israeli ports creates logistics premiums that inflate landed cable costs.
Levant Power Cable Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty sheathing and renewable integration segments where certification barriers remain lower. The market structures around integrated compounders with captive vulcanization capabilities, regional distributors with cross-border logistics networks, and technology licensors enabling localized production joint ventures. Consolidation pressures favor backward integration into copper drawing and compounding operations. Competitive moves center on framework agreement positioning with national utilities and European technology licensing for triple-layer extrusion capabilities.
Among Egyptian and Gulf-based integrated producers, El-Sewedy Cables and DUCAB Cables exemplify the scale-driven archetype with cross-border supply capabilities. Lebanese specialist Liban Cables occupies a position within the domestic-market-focused tier. Prysmian Group represents the technology-licensor archetype competing on high voltage submarine and land cable designs. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Prysmian Group |
| Southwire Company |
| Liban Cables |
| Riyadh Cables |
| DUCAB Cables |
| El-Sewedy Cables |
| Nexans |
| Bahra Advanced Cable Manufacture |
| MESC Jordan |
| Others |
Supply Flow & Price Mechanics
Halogen-free sheathing mandates from Lebanon's Order of Engineers gate qualified supply and premium-tier pricing access, compressing vendor panels to compounders with captive vulcanization and dual IEEE 404 and NF C 33-226 certification. Jordan's National Electric Power Company framework agreements concentrate procurement among four approved manufacturers, amplifying pricing power for integrated producers with backward integration into copper drawing.
Pricing Analysis
Distributor margins in cross-border Egyptian supply compress landed costs for Jordanian utilities by 12-18 percent versus European direct import. Three-tier pricing structure across premium, standard, and economy levels separates IEEE 404-certified medium voltage cable from scrap-fed rod production and aluminum alloy secondary distribution. Price differentiation hinges on certification grade and volume scale, with industrial offtake commanding 15-20 percent premiums over residential electrification. Cost compression in low-voltage residential tiers is intensifying because aluminum conductor substitution displaces copper-intensive specifications.
Supply Chain Analysis
Single-source vulnerability sits with Egyptian integrated producers for cross-border medium voltage supply to Jordan and Lebanon. Geographic concentration centers on Egypt, Turkey, and domestic Lebanese compounding for qualified cable stock. Raw material dependencies rest on copper cathode, cross-linkable polyethylene resin, and peroxide initiator chemicals. Regulatory restriction risk from Syria's state-controlled import licensing constrains private manufacturer scaling. Distribution runs through national utility framework agreements and EPC contractor procurement panels rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Levant cable market stems from aluminum alloy substitution compressing input costs in residential tiers while halogen-free sheathing premiums expand in Lebanese coastal reconstruction. The shift from project-by-project tendering to framework agreements concentrates volume with qualified compounders.
For Market Incumbents: Lock in framework agreement positioning with Jordan's National Electric Power Company and Lebanon's Electricite du Liban by investing in triple-layer extrusion licensing from European technology providers. Defend against Egyptian cross-border supply by deepening captive copper drawing capacity in Zarqa industrial zones. Certification investment in dual IEEE 404 and NF C 33-226 compliance creates switching costs for utility procurement panels.
For New Entrants and Emerging Players: Triple-layer extrusion technology for 11 kV distribution rebuilds offers a technology-first wedge into Jordan's decentralized manufacturing shift away from Egyptian supply. Target solar farm collector systems in Ma'an and Tafila governorates where renewable integration targets reshape material specifications and certification barriers remain lower. Go-to-market through EPC contractor partnerships rather than direct utility qualification accelerates initial offtake.
For Investors and Strategic Acquirers: Roll-up economics work for regional cable compounders because framework agreement consolidation compresses the qualified supplier base to four manufacturers in Jordan. Long-term viability centers on backward integration into copper cathode sourcing and captive vulcanization capabilities. Acquisition target archetype: Lebanese or Jordanian compounders with dual certification and European technology licenses. Watch GCC interconnection harmonization negotiations as the inflection signal for cross-border supply regime shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Layer Extrusion Licensing | European technology transfer enables localized 11 kV production in Zarqa and Aqaba joint ventures. |
| Halogen-Free Compound Reformulation | Calcium-zinc stabilizer substitution meets Lebanese Order of Engineers smoke density mandates for Beirut tenders. |
| Copper Drawing Backward Integration | Captive continuous casting reduces feedstock dependency on Egyptian cross-border supply and scrap-fed rod variance. |
| Framework Agreement Consolidation | Jordan's National Electric Power Company vendor panel compression from twelve to four manufacturers concentrates volume. |
| Solar Farm Collector Cable Development | 1.8/3 kV DC-rated UV-resistant designs capture renewable integration procurement in southern Jordan governorates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, cable plant managers, EPC contractor project directors, and polymer compounder R&D leads with secondary validation. Secondary sources included Jordanian Ministry of Energy procurement disclosures, Lebanese Order of Engineers regulatory filings, customs trade data for copper cathode and cable imports, and utility framework agreement announcements. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-weighting across voltage rating, end-use application, conductor material, and installation method drove analytical framework construction over the projection horizon. Modeled dimensions included product type tier, utility versus industrial versus renewable customer segment, copper versus aluminum conductor specification, and underground versus overhead installation method. CAGRs derived from utility capital expenditure trajectories, renewable interconnection targets, and grid undergrounding mandate timelines. Industry-specific inputs encompassed IEEE 404 and NF C 33-226 certification pipeline data and European technology licensing transaction patterns.
The model holds under continued framework agreement consolidation and stable copper-aluminum price spreads; deviation in GCC interconnection harmonization or Syrian feedstock licensing liberalization would shift competitive positioning and supply geography. Forecasts reflect documented assumptions about regulatory enforcement continuity and utility procurement centralization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Qatar Power EPC Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
US Power EPC Market
Power Equipment
Australia Power EPC Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Chad Power EPC Market
Power Equipment
United States Power Rental Market
Power Equipment
Magnetic Bearing Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Natural Gas Turbine Market