
 North America Exhaust Heat Recovery System Market | 2026-2036
North America Exhaust Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Exhaust Heat Recovery System Market Insights
Mexico's industrial heartland is fragmenting as exhaust heat recovery manufacturing disperses beyond traditional Midwest strongholds. BorgWarner Inc. anchors thermal management R&D for automotive applications across the Great Lakes region. Continental AG competes through integrated powertrain solutions that bundle exhaust energy recovery with electrification modules. Denso Corporation leverages its Tennessee operations to supply heat exchanger assemblies for North American OEM programs.
An exhaust heat recovery system captures thermal energy from engine exhaust streams and converts it into usable power through turbocompounding, thermoelectric generation, or organic Rankine cycle architectures operating at exhaust temperatures between 300°C and 700°C. These systems primarily serve industrial and transportation sectors seeking to improve thermal efficiency and reduce fuel consumption. Heat exchangers occupy the largest product category as foundational components in both automotive and stationary applications, while waste heat recovery technology leads growth due to expanding deployment in data centers seeking to offset cooling loads. Combined heat and power installations command premium margins in manufacturing facilities where simultaneous thermal and electrical output maximizes capital utilization.
The EPA enforces emissions thresholds that effectively mandate waste heat recovery integration in heavy-duty diesel platforms, while NHTSA coordinates fuel economy standards with CARB's zero-emission vehicle framework to create overlapping compliance obligations. The Department of Energy funds demonstration projects for industrial heat-to-power conversion that de-risk adoption for early commercial deployers. Stakeholders must track how evolving EPA Phase 3 greenhouse gas rules and state-level building decarbonization codes reshape addressable demand across automotive and stationary segments.
Market Dynamics
The North America Exhaust Heat Recovery System Market pivots on EPA Phase 3 greenhouse gas regulations forcing heavy-duty diesel OEMs to integrate waste heat recovery as a compliance pathway rather than optional efficiency upgrade.
Growth Catalysts
- Corporate Average Fuel Economy standards:NHTSA mandates compel Class 8 truck manufacturers to recover exhaust thermal energy for measurable fuel economy gains.
- Data center cooling offset programs:Hyperscale facilities in Northern Virginia and Phoenix deploy organic Rankine cycle systems to convert server waste heat into electricity for chiller load reduction.
- Thermoelectric generator materials:Bismuth telluride and skutterudite compounds achieve higher conversion efficiency at 300-500°C exhaust temperatures, expanding viable application range.
Market Restraints
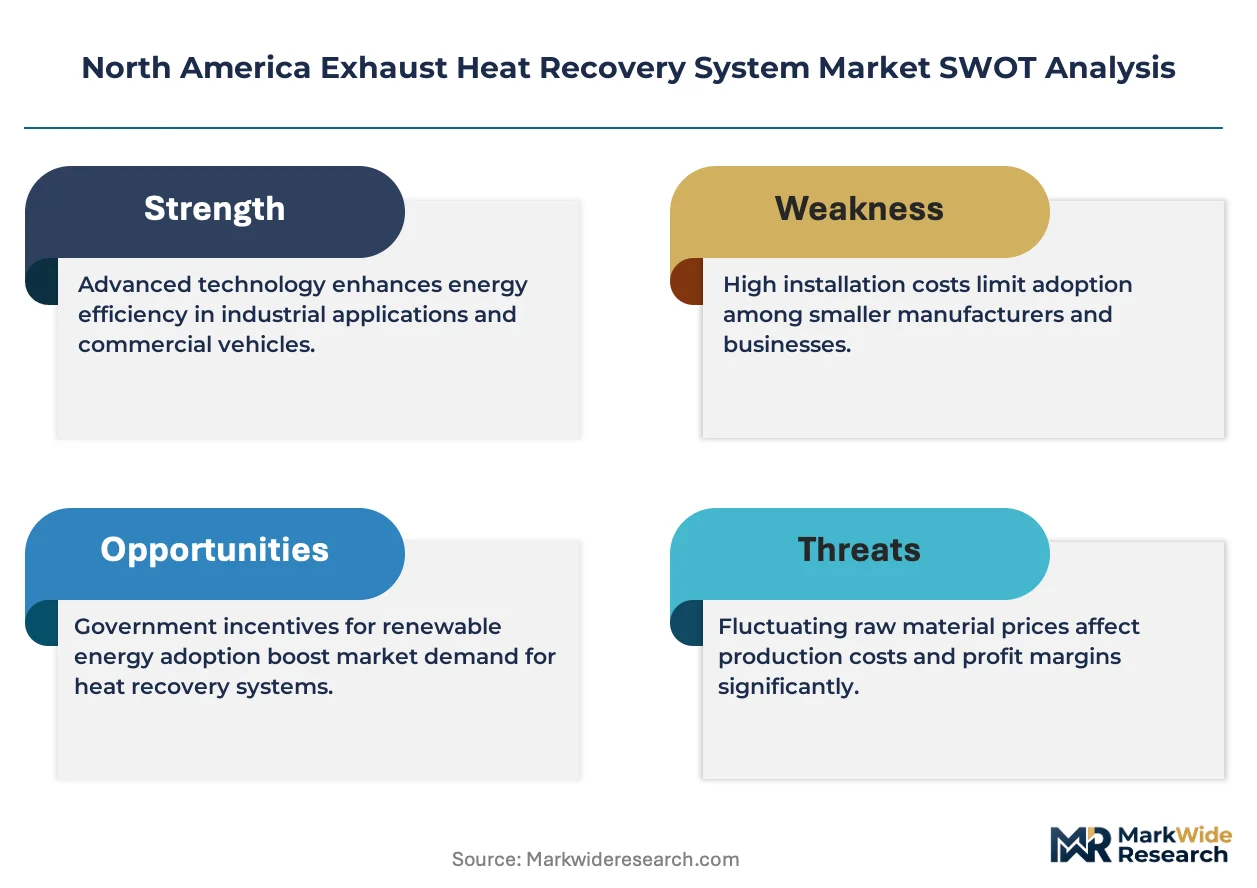
- Heat exchanger alloy costs:Inconel and stainless steel price volatility compresses OEM margins on exhaust gas recirculation-integrated recovery modules.
- Great Lakes supplier concentration:Michigan and Ontario host 60% of North American thermal management manufacturing, creating hurricane and labor disruption exposure.
- Turbocompounding packaging constraints:Crankshaft-connected turbocompound units require engine block redesigns incompatible with legacy diesel platform retooling schedules.
Strategic Opportunities
- Mexico industrial corridor expansion:Querétaro and Guanajuato states attract heat exchanger assembly investments as OEMs diversify beyond Midwest production clusters.
- Industrial combined heat and power:Petrochemical facilities in Texas and Louisiana pursue waste heat-to-power installations qualifying for Department of Energy demonstration grants.
- Electrification convergence:Hybrid electric powertrains pair exhaust recovery with battery thermal management, creating bundled thermal system procurement.
Industry Challenges
- Thermoelectric module integration engineering:OEMs lack in-house expertise marrying semiconductor physics with exhaust system durability requirements.
- EPA certification timeline compression:Phase 3 compliance deadlines force simultaneous validation of heat recovery hardware and engine control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Exhaust Heat Recovery System Market |
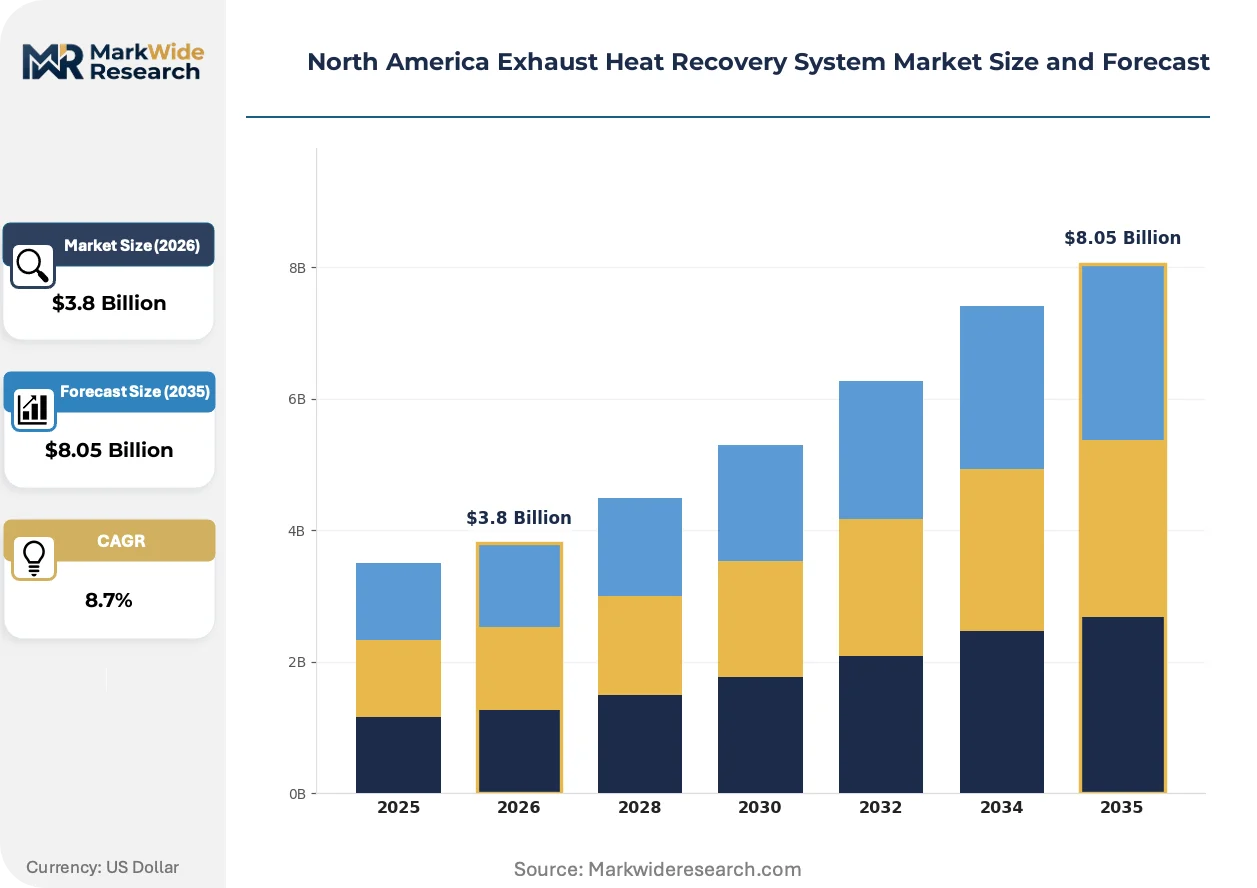
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Boilers, Fans, Condensers Technology: Thermal Energy Storage, Heat Pumps, Waste Heat Recovery, Combined Heat and Power End User: Manufacturing Facilities, Data Centers, Commercial Buildings, Power Plants Installation: Onsite, Retrofit, New Construction, Modular |
| Companies Covered | GE Vernova, Siemens Energy, ABB, Bosch Industriekessel GmbH, Cleaver-Brooks, Continental AG, BorgWarner Inc., Denso Corporation, Ormat Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Exhaust Heat Recovery System Market Trends and Innovations
Exhaust heat recovery architecture is migrating from mechanical turbocompounding toward solid-state thermoelectric and organic Rankine cycle platforms. This shift reconfigures supplier relationships and R&D investment priorities across the value chain.
Organic Rankine cycle systems using R245fa or pentane working fluids capture low-grade exhaust heat below 350°C. Food and beverage processing plants in California and Wisconsin adopt these units for combined heat and power. The technology is migrating from stationary industrial applications into long-haul trucking auxiliary power units, compressing the historical separation between automotive and stationary thermal recovery markets.
EPA Phase 3 greenhouse gas standards tighten CO2 limits for model year 2027 heavy-duty vehicles. Engine manufacturers must achieve 4-6% fuel economy improvement through waste heat recovery or face penalties. California Air Resources Board coordinates with EPA through its Advanced Clean Trucks rule, creating overlapping compliance obligations that favor integrated thermal-electric powertrain development.
Fleet procurement teams now specify total cost of ownership metrics rather than upfront hardware pricing. Large trucking operators in the Midwest negotiate performance-based contracts tying supplier payments to verified fuel savings. This purchasing model shift pressures heat recovery vendors to guarantee efficiency outcomes, transferring technical risk from buyers to equipment providers.
North America Exhaust Heat Recovery System Market Segmentation
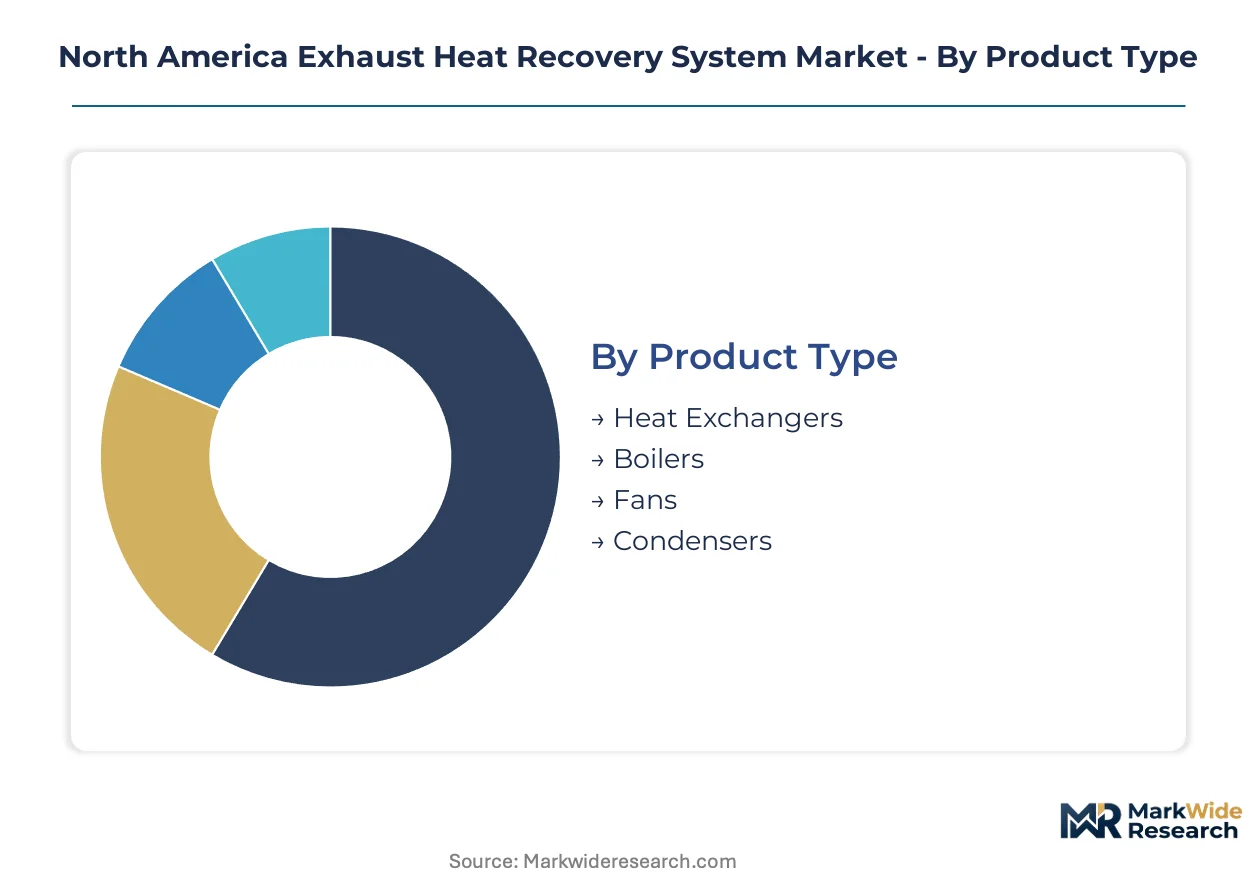
Exhaust heat recovery systems serve divergent thermal profiles across transportation and stationary energy applications. Segment boundaries blur as automotive turbocompounding converges with industrial organic Rankine cycle architectures. Procurement patterns differ sharply between EPA-mandated heavy-duty truck retrofits and voluntary data center efficiency upgrades.
Product Type:
Mature hardware categories dominate installed base while emerging component designs penetrate next-generation platforms.
- Heat Exchangers:Shell-and-tube and plate-fin configurations transfer thermal energy between exhaust gas streams and working fluids or coolant circuits. Demand concentrates in Michigan and Ontario automotive supplier corridors where EPA Phase 3 compliance deadlines force OEM integration. Inconel alloy sourcing constraints compress margins on high-temperature EGR-integrated designs.
- Boilers:Waste heat boilers generate steam from exhaust streams between 400°C and 700°C for industrial process heat or power generation. Petrochemical facilities in Texas and Louisiana deploy these units for combined heat and power under Department of Energy demonstration grants. Pressure vessel certification timelines extend procurement cycles.
- Fans:Forced-draft and induced-draft configurations optimize exhaust flow rates across heat recovery surfaces. Data center cooling offset programs in Northern Virginia specify variable-speed designs for organic Rankine cycle integration.
- Condensers:Shell-and-coil and air-cooled units condense working fluids in closed-loop thermal cycles. Food processing plants in California adopt compact designs for low-grade heat recovery below 350°C.
Heat exchangers retain volume leadership; boilers hold the steepest expansion curve.
Technology:
Cost tier stratification separates proven mechanical systems from emerging solid-state and thermodynamic platforms requiring substantial R&D investment.
- Waste Heat Recovery:Organic Rankine cycle and turbocompounding architectures capture exhaust thermal energy for electricity or mechanical power. Heavy-duty trucking fleets across the Midwest expand adoption to meet NHTSA fuel economy mandates. R245fa and pentane working fluids enable low-grade heat capture below 350°C.
- Combined Heat and Power:Cogeneration systems simultaneously produce electricity and thermal output from single fuel sources. Manufacturing facilities in the Great Lakes region pursue these installations for capital utilization maximization. EPA emissions thresholds effectively mandate integration in stationary diesel platforms.
- Thermal Energy Storage:Sensible and latent heat storage buffers temporal mismatches between exhaust availability and thermal demand. Commercial buildings in California integrate these systems with state-level building decarbonization codes.
- Heat Pumps:Vapor-compression and absorption cycles upgrade low-grade exhaust heat to higher temperatures for process applications. District heating networks in Ontario evaluate these units for waste heat distribution.
Waste heat recovery dominates capital deployment; combined heat and power commands premium margins.
End User:
Application diversity spans heavy industrial baseload operations to intermittent commercial thermal loads with divergent payback requirements.
- Manufacturing Facilities:Steel, cement, and chemical plants deploy exhaust recovery for process heat and power generation. Great Lakes industrial corridor installations face hurricane and labor disruption exposure from supplier concentration. Continuous operation profiles justify high capital intensity.
- Data Centers:Hyperscale facilities in Phoenix and Northern Virginia convert server waste heat into electricity for chiller load reduction. Procurement teams specify total cost of ownership metrics rather than upfront hardware pricing.
- Power Plants:Combined cycle and simple cycle gas turbine installations recover exhaust energy for bottoming cycles. Texas and Louisiana petrochemical complexes anchor regional demand.
- Commercial Buildings:District heating systems and on-site generation serve thermal loads in urban cores. California building decarbonization codes reshape addressable demand.
Manufacturing facilities retain volume leadership; data centers hold the steepest expansion curve.
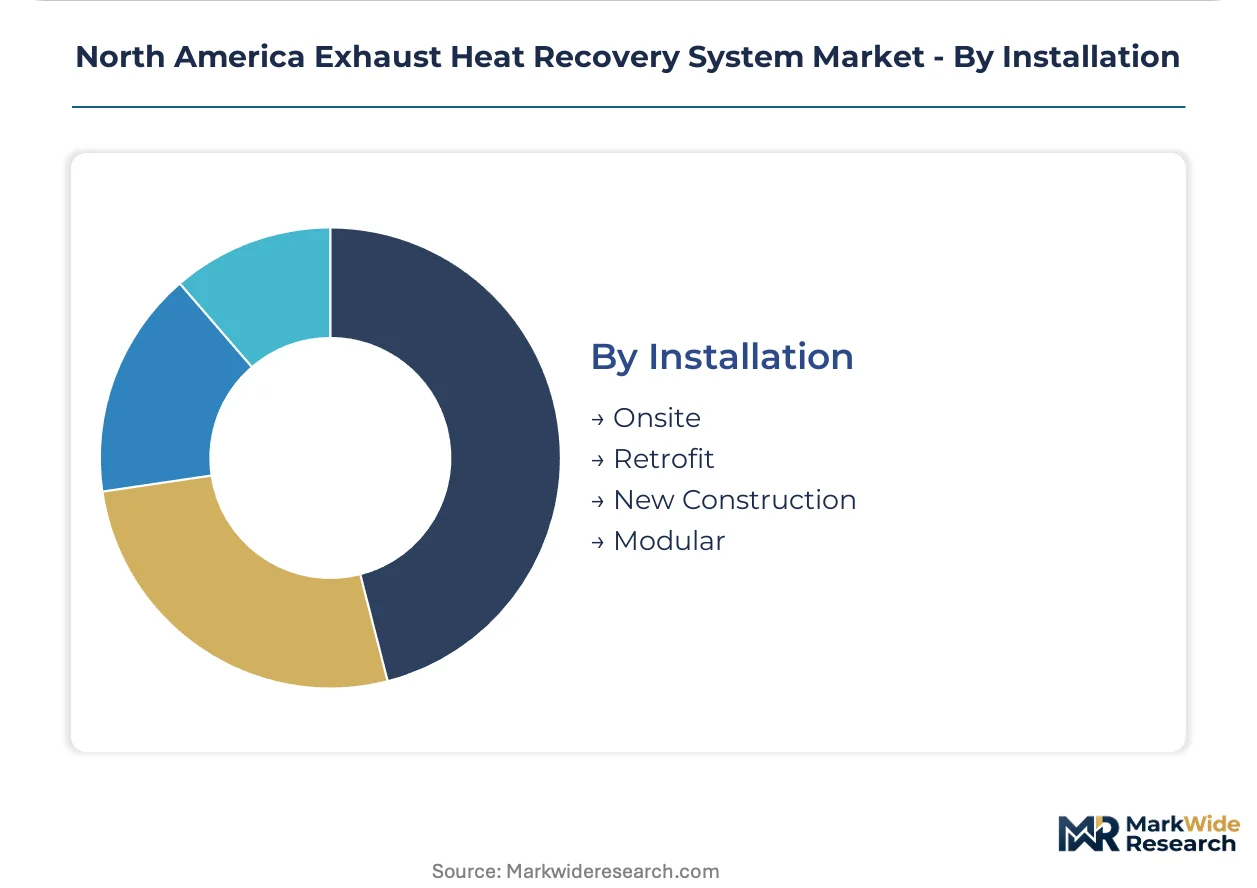
Installation:
Customer type segmentation separates greenfield project developers from legacy asset operators with constrained shutdown windows.
- Retrofit:Exhaust heat recovery hardware integrates with existing engine and industrial systems without platform replacement. Class 8 truck manufacturers face compressed EPA certification timelines for simultaneous hardware and software validation. Legacy diesel platform retooling schedules limit turbocompounding penetration.
- New Construction:Integrated thermal system design optimizes heat recovery from project inception. OEM bundled procurement pairs exhaust recovery with battery thermal management in hybrid electric powertrains.
- Onsite:Project-specific engineering addresses unique exhaust profiles and thermal demand patterns. Querétaro and Guanajuato states attract assembly investments as OEMs diversify beyond Midwest clusters.
- Modular:Skid-mounted and containerized units reduce field installation duration for time-constrained industrial outages. Food and beverage processing plants in Wisconsin adopt standardized designs.
Retrofit retains volume leadership; modular holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal management manufacturing concentrates heavily in the Great Lakes corridor, creating geographic vulnerability that OEMs now address through deliberate supply base diversification into Mexico's industrial heartland.
United States
Heavy-duty trucking fleets across the Midwest expand exhaust heat recovery adoption to meet NHTSA fuel economy mandates. EPA Phase 3 greenhouse gas regulations force Class 8 manufacturers to integrate waste heat recovery as a compliance pathway. Michigan and Ohio anchor automotive supplier corridors where BorgWarner and Denso operate thermal management facilities.
Canada
Ontario's automotive manufacturing belt hosts concentrated heat exchanger production serving cross-border OEM programs. Provincial clean air mandates align with EPA emissions thresholds, creating overlapping compliance obligations. Toronto-Windsor corridor facilities face hurricane and labor disruption exposure from geographic clustering.
Mexico
Querétaro and Guanajuato states attract heat exchanger assembly investments as manufacturers diversify beyond Midwest production clusters. Federal energy efficiency programs support industrial waste heat-to-power demonstrations. Mexico City Metro serves as procurement coordination hub for North American thermal system integration.
North America Exhaust Heat Recovery System Market Competitive Landscape
Integrated powertrain conglomerates and specialized thermal component suppliers split the market between bundled electrification modules and standalone exhaust recovery hardware. Tier-1 automotive suppliers dominate automotive applications through OEM-direct relationships, while industrial equipment specialists anchor stationary energy recovery installations. Two strategic archetypes prevail: full-system integrators pursuing electrification convergence, and component specialists defending heat exchanger technology positions. Competitive dynamics center on geographic diversification beyond Great Lakes clusters and vertical integration into semiconductor materials for thermoelectric generators.
Within the integrated powertrain tier, Continental AG and BorgWarner Inc. exemplify full-system strategies that bundle exhaust energy recovery with battery thermal management. Denso Corporation represents the Japanese multinational archetype leveraging Tennessee operations to supply North American OEM programs. Among industrial energy recovery specialists, Ormat Technologies Inc. occupies a position in organic Rankine cycle deployments for stationary applications.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| ABB |
| Bosch Industriekessel GmbH |
| Cleaver-Brooks |
| Continental AG |
| BorgWarner Inc. |
| Denso Corporation |
| Ormat Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
Inconel alloy price volatility from nickel supply disruptions determines both the spread between premium heat exchanger tiers and the geographic dispersal of assembly operations beyond Great Lakes clusters. OEM procurement teams now negotiate performance-based contracts that transfer alloy cost risk to equipment suppliers, compressing margins on standard-grade modules while insulating premium EGR-integrated designs.
Pricing Analysis
EPA Phase 3 greenhouse gas standards dictate the pricing tier structure across exhaust heat recovery hardware. Three-tier pricing stratifies across premium Inconel-based EGR-integrated modules, standard stainless steel shell-and-tube configurations, and economy-grade aluminum-fin designs for aftermarket retrofits. Price differentiation hinges on alloy grade certification and thermal durability warranties. Cost compression in the standard tier is intensifying because NHTSA fuel economy mandates force simultaneous hardware and software validation timelines. Fleet procurement teams demonstrate highest price sensitivity, while data center operators prioritize total cost of ownership metrics over upfront capital expenditure.
Supply Chain Analysis
Specialty alloy feedstock draws from mining operations in Indonesia, nickel processing in Russia, and refining capacity in Canada. Heat exchanger manufacturing rests on Inconel sheet supply, brazing equipment, and thermoelectric semiconductor materials. Single-source vulnerability concentrates in Great Lakes thermal management corridors where 60% of North American capacity clusters. Distribution runs through OEM-direct channels for automotive applications and industrial EPC contractors for stationary energy recovery installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against solid-state battery thermal management systems that could displace exhaust-based recovery in electrified powertrains. Incumbents must navigate the convergence of electrification architectures that bundle competing thermal technologies.
For Market Incumbents: Insulate core heat exchanger positions through backward integration into Inconel alloy supply and captive semiconductor production for thermoelectric generators. Secure long-term offtake agreements with Midwest heavy-duty truck OEMs before EPA Phase 3 certification deadlines compress procurement windows. Prioritize R&D investment in organic Rankine cycle architectures that maintain relevance across hybrid electric platforms. For New Entrants and Emerging Players: Mexico's Querétaro and Guanajuato industrial corridors offer white-space assembly capacity with lower labor costs and tariff-advantaged access to US OEM programs. Target data center cooling offset installations in Northern Virginia and Phoenix where procurement teams seek modular organic Rankine cycle suppliers outside incumbent automotive supply chains. Lead with performance-guaranteed contracting models that transfer fuel savings verification risk from buyers to equipment providers. For Investors and Strategic Acquirers: EPA Phase 3 implementation reshapes the acquisition landscape toward thermal management specialists with validated heavy-duty diesel platform integration. Long-term viability centers on suppliers capable of bridging automotive and stationary energy recovery applications as segment boundaries blur. Target acquisition candidates with demonstrated organic Rankine cycle deployments and established OEM certification relationships. Monitor NHTSA fuel economy credit trading prices as the inflection signal for heat recovery hardware demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captive Inconel supply insulates margins against nickel price volatility from Indonesian mining disruptions. |
| Modular Organic Rankine Cycle Platform Launch | Standardized skid-mounted designs penetrate data center cooling offset programs in Northern Virginia and Phoenix. |
| Joint Venture with Thermoelectric Materials Specialist | Bismuth telluride and skutterudite partnerships accelerate solid-state generator commercialization for 300-500°C exhaust applications. |
| Geographic Manufacturing Footprint Expansion | Querétaro and Guanajuato assembly investments diversify beyond hurricane-exposed Great Lakes supplier clusters. |
| Performance-Based Service Contract Model | Fuel savings guarantees transfer technical risk from Midwest fleet procurement teams to equipment vendors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with heavy-duty truck fleet managers, thermal management procurement leads at Tier 1 automotive suppliers, data center facility engineers, and industrial EPC contractors. Secondary validation drew from EPA regulatory filings, NHTSA fuel economy compliance databases, Department of Energy demonstration project records, and SEC 10-K disclosures from publicly traded thermal component manufacturers. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, and end-user dimensions.
Calibration anchored installed base estimates against vehicle production databases and industrial boiler registration records. The analytical framework modeled volume and value outputs across the projection horizon through vehicle class segmentation, propulsion architecture differentiation, content per vehicle assumptions, and regional production cluster dynamics. CAGRs were derived from regression analysis of historical adoption curves against regulatory milestone timing. Forecast inputs incorporated EPA Phase 3 compliance cost modeling and thermoelectric conversion efficiency improvement trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese thermal component manufacturers or accelerated solid-state battery deployment would shift outcomes beyond modeled ranges. Cross-checking against NHTSA fuel economy credit market pricing and EPA certification timeline announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Power Analyzers Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Japan Power EPC Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Germany Power EPC Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
ASEAN Power EPC Market