
 Photovoltaic Solar Kits Market | 2026-2036
Photovoltaic Solar Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic Solar Kits Market Insights
Residential buyer fragmentation is expanding as individual homeowners, remote cabin operators, and small agricultural businesses replace traditional utility-scale developers as the dominant procurement channel. Jinko Solar leverages its integrated wafer-to-module production to serve cost-sensitive DIY segments. LONGi anchors premium rooftop deployments through high-efficiency monocrystalline cell architectures. Canadian Solar competes across hybrid storage-integrated kits with vertically controlled inverter partnerships.
Photovoltaic solar kits are pre-engineered assemblies comprising solar panels, inverters, battery storage units, and charge controllers designed for rapid deployment without custom engineering. These systems convert incident solar radiation into direct-current electricity, condition it through maximum power point tracking algorithms, and store surplus energy in lithium iron phosphate or lead-acid battery banks for dispatch during non-generating hours. Roof-mounted systems dominate value capture in established markets where permitting streamlines residential attachment, while portable kits represent the fastest-expanding margin pool among recreational vehicle owners and disaster relief organizations. Battery storage components command disproportionate margin contribution as customers prioritize energy autonomy over simple grid-tied generation.
US installations must comply with IEEE 1547 interconnection standards and NEC Article 690 grounding requirements enforced by local authorities having jurisdiction. Germany's Bundesnetzagentur administers EEG feed-in tariff eligibility for kit-integrated systems under 30 kilowatts. Australia's Clean Energy Council accredits components under the Small-scale Renewable Energy Scheme, directly influencing product eligibility for certificate creation. Stakeholders must monitor evolving inverter efficiency mandates and battery recycling directives across multiple jurisdictions to maintain market access.
Market Dynamics
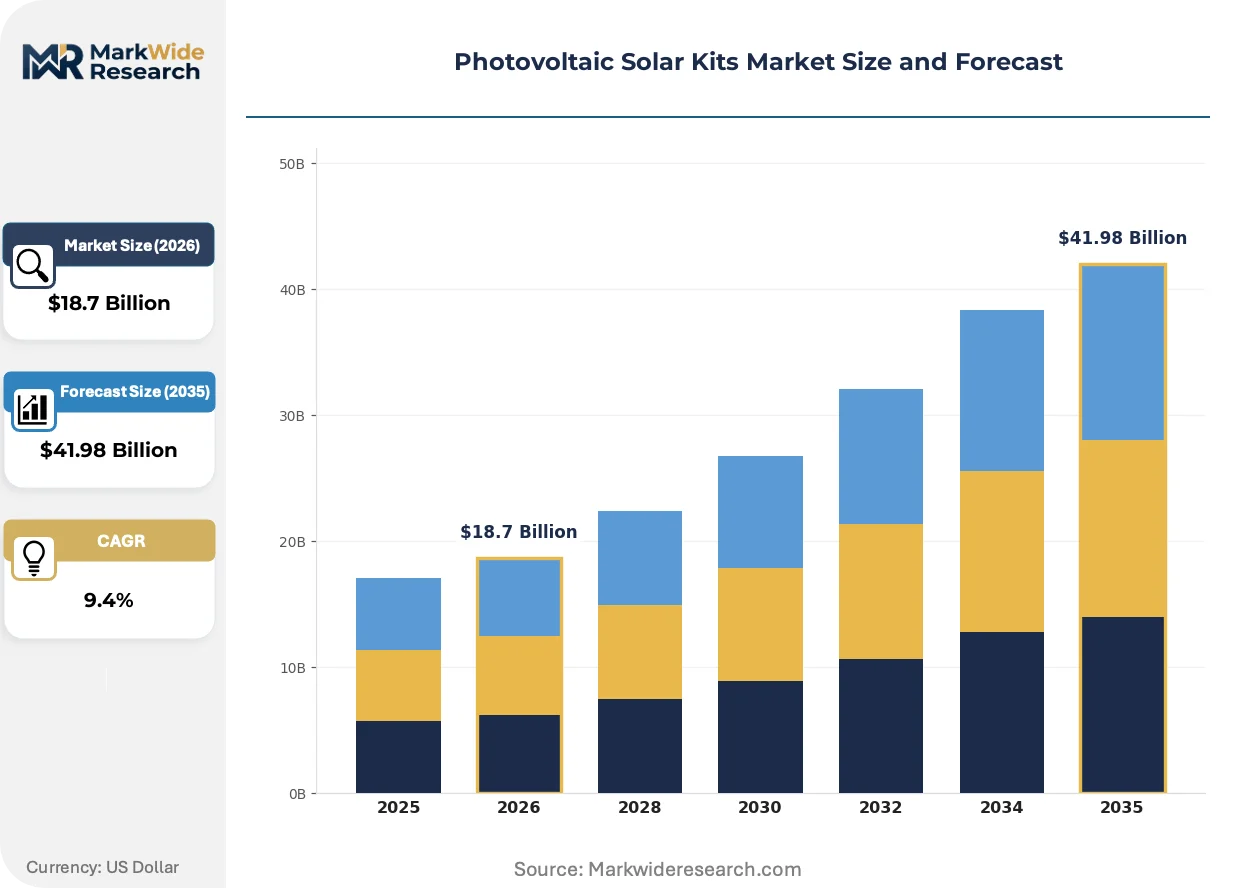
The residential solar kit market is experiencing a structural pivot from utility-scale procurement to distributed generation, driven by lithium-ion battery cost compression and net metering policy arbitrage across suburban jurisdictions. This shift is fragmenting buyer concentration while elevating inverter-battery integration as the primary value capture point.
Growth Catalysts
- Net Metering Policy Arbitrage:Favorable interconnection standards in the United States and Australia enable surplus electricity sell-back to grids, accelerating payback periods for residential installations.
- Battery Chemistry Evolution:Lithium iron phosphate cell architectures are displacing lead-acid storage in mid-tier kits, extending cycle life and reducing thermal runaway risks for DIY installers.
- Rural Electrification Gaps:Off-grid cabin operators and small agricultural facilities in Australia and Germany are bypassing traditional utility infrastructure entirely.
Market Restraints
- Polysilicon Supply Concentration:Wafer production gravity in China creates input cost volatility and tariff exposure for module assemblers serving price-sensitive segments.
- Permitting Heterogeneity:Local authorities having jurisdiction in the United States enforce divergent NEC Article 690 interpretations, elongating deployment timelines.
- Grid Interconnection Queues:Utility backlogs for IEEE 1547 compliance testing delay revenue recognition for hybrid storage-integrated kit vendors.
Strategic Opportunities
- Recreational Vehicle Electrification:Portable kit demand among disaster relief organizations and remote workers is expanding addressable market beyond fixed rooftop installations.
- Feed-in Tariff Optimization:Germany's Bundesnetzagentur EEG eligibility for sub-30kW systems creates certificate revenue streams that subsidize upfront capital costs.
- Charge Controller-Inverter Convergence:MPPT algorithm integration with hybrid inverters is compressing component count and installation labor for residential contractors.
Industry Challenges
- Electrical Contractor Shortage:Qualified installers capable of NEC Article 690 grounding compliance are scarce in rapidly growing suburban markets.
- Component Certification Lag:Australia's Clean Energy Council accreditation timelines delay product eligibility for Small-scale Renewable Energy Scheme certificate creation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic Solar Kits Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Kits, Roof-mounted Systems, Ground-mounted Systems, Hybrid Solutions Usage Scenario: Residential Use, Commercial Use, Off-grid Applications, Backup Power Component: Solar Panels, Inverters, Battery Storage, Charge Controllers Market Type: DIY Kits, Professional Installation, Maintenance Packages, Integrated Solutions |
| Companies Covered | First Solar, Canadian Solar, Hanwha Qcells, Jinko Solar, Trinasolar, JA Solar Technology Co., Ltd., LONGi, Silfab Solar, Hyperion Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic Solar Kits Market Trends and Innovations
Module-level power electronics and solid-state battery architectures are actively compressing system complexity while elevating energy autonomy as the primary purchase driver over simple grid-tied generation.
Module-level power electronics (MLPE) technology is converging with rapid shutdown safety requirements to create all-in-one junction boxes that eliminate separate string inverter purchases. Residential contractors in California and Arizona are specifying MLPE-integrated panels for 80% of new rooftop deployments. This convergence is compressing balance-of-system costs and reducing installation labor hours by consolidating three discrete components into single SKUs.
The United States Inflation Reduction Act's domestic content bonus credits are reshaping supply chain geography for kit assemblers serving the residential segment. Manufacturers must now source 40% of manufactured products from North American facilities to qualify for enhanced tax credits. Battery storage-integrated kits are most affected, with vendors reconfiguring lithium iron phosphate cell sourcing to capture the full incentive stack.
Buyer preference is migrating from equipment ownership to performance-guaranteed service contracts among agricultural and remote commercial facilities. Third-party financiers are displacing traditional distributor channels in Australia's regional markets, offering zero-down installations with 20-year energy output warranties. This behavioral pivot is most visible in Queensland and Western Australia, where solar irradiance levels support aggressive PPA pricing.
Photovoltaic Solar Kits Market Segmentation
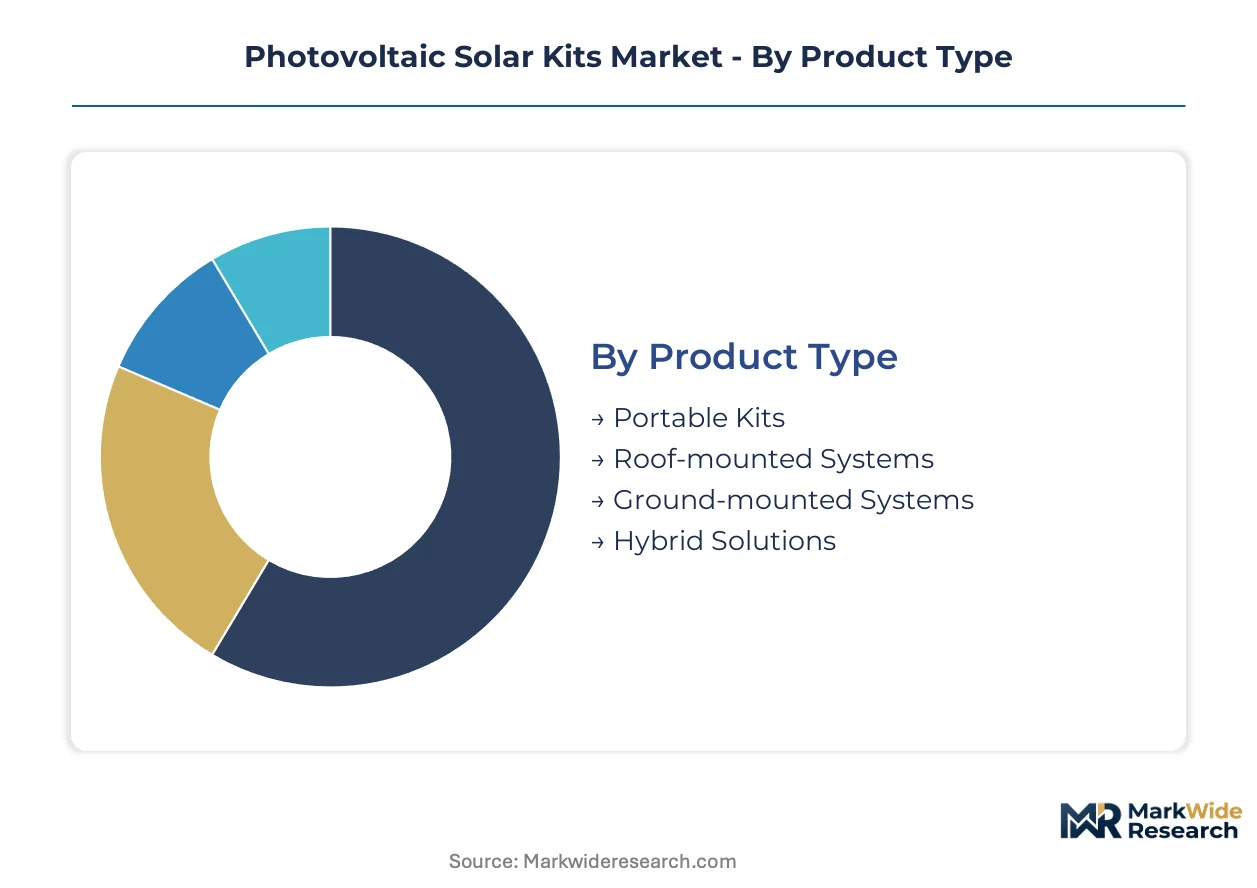
Segmentation in photovoltaic solar kits reveals how technical specifications, installation complexity, and buyer sophistication intersect to create distinct commercial pockets. Each category exposes different margin structures and competitive dynamics that vendors must navigate.
Product Type:
Customization intensity varies dramatically across this category, from mass-produced portable units to site-engineered ground-mounted arrays requiring structural engineering.
- Roof-mounted Systems:Fixed arrays attach directly to residential or commercial roofing structures using racking systems engineered for wind load and snow drift conditions. Permit streamlining in suburban United States jurisdictions concentrates demand here, though local NEC Article 690 interpretation heterogeneity creates installation friction.
- Portable Kits:Collapsible panel assemblies with integrated charge controllers and battery packs deploy without structural mounting. Disaster relief organizations and remote workers in Australia drive procurement, with recreational vehicle electrification expanding the addressable market beyond fixed infrastructure.
- Ground-mounted Systems:Elevated arrays on pile-driven or ballasted foundations suit properties with inadequate roof structural capacity or suboptimal solar orientation. Agricultural facilities in Germany favor these configurations for dual-use land applications.
- Hybrid Solutions:Pre-integrated packages combining photovoltaic generation with battery storage and grid-tie capability reduce component sourcing complexity for residential contractors. Inverter-battery convergence within single SKUs compresses balance-of-system costs.
Most installed capacity flows through Roof-mounted Systems. Expansion is steepest in Portable Kits.
Usage Scenario:
Application context determines whether buyers prioritize energy autonomy, grid arbitrage, or backup resilience—each with distinct technical requirements and price sensitivity profiles.
- Residential Use:Single-family homeowners in suburban United States markets deploy rooftop systems to capture net metering credits and hedge against utility rate inflation. Battery storage integration is accelerating as lithium iron phosphate costs compress.
- Off-grid Applications:Remote cabin operators and rural agricultural facilities bypass utility infrastructure entirely, sizing systems for 100% energy autonomy with oversized battery banks. Australia's regional electrification gaps sustain this segment.
- Commercial Use:Small businesses and agricultural processors install mid-scale arrays to offset operational electricity loads. Third-party financiers in Queensland and Western Australia displace traditional distributor channels with performance-guaranteed service contracts.
- Backup Power:Grid-tied systems with islanding capability maintain critical loads during utility outages. California's rapid shutdown safety requirements have elevated module-level power electronics specification rates.
Residential Use captures the largest share of annual deployments. Off-grid Applications are climbing the fastest as rural electrification gaps persist.
Component:
Supply chain concentration and technology evolution vary by component, creating divergent margin profiles and sourcing risks across the bill of materials.
- Solar Panels:Wafer-based modules convert incident solar radiation into direct-current electricity. Polysilicon supply concentration in China creates input cost volatility for module assemblers serving price-sensitive segments.
- Battery Storage:Lithium iron phosphate cell architectures displace lead-acid alternatives, extending cycle life and reducing thermal runaway risks. This component commands disproportionate margin contribution as autonomy prioritization overtakes simple generation.
- Inverters:Power electronics condition direct-current output to grid-compliant alternating current, with maximum power point tracking algorithms optimizing energy harvest. IEEE 1547 interconnection compliance testing backlogs delay revenue recognition for hybrid storage-integrated kit vendors.
- Charge Controllers:Regulators manage battery charging profiles to prevent overcharge damage and optimize storage longevity. MPPT algorithm integration with hybrid inverters is compressing standalone controller demand in premium kit configurations.
Solar Panels represent the highest volume component category. Battery Storage is gaining share fastest as storage-integrated kits displace pure grid-tied systems.
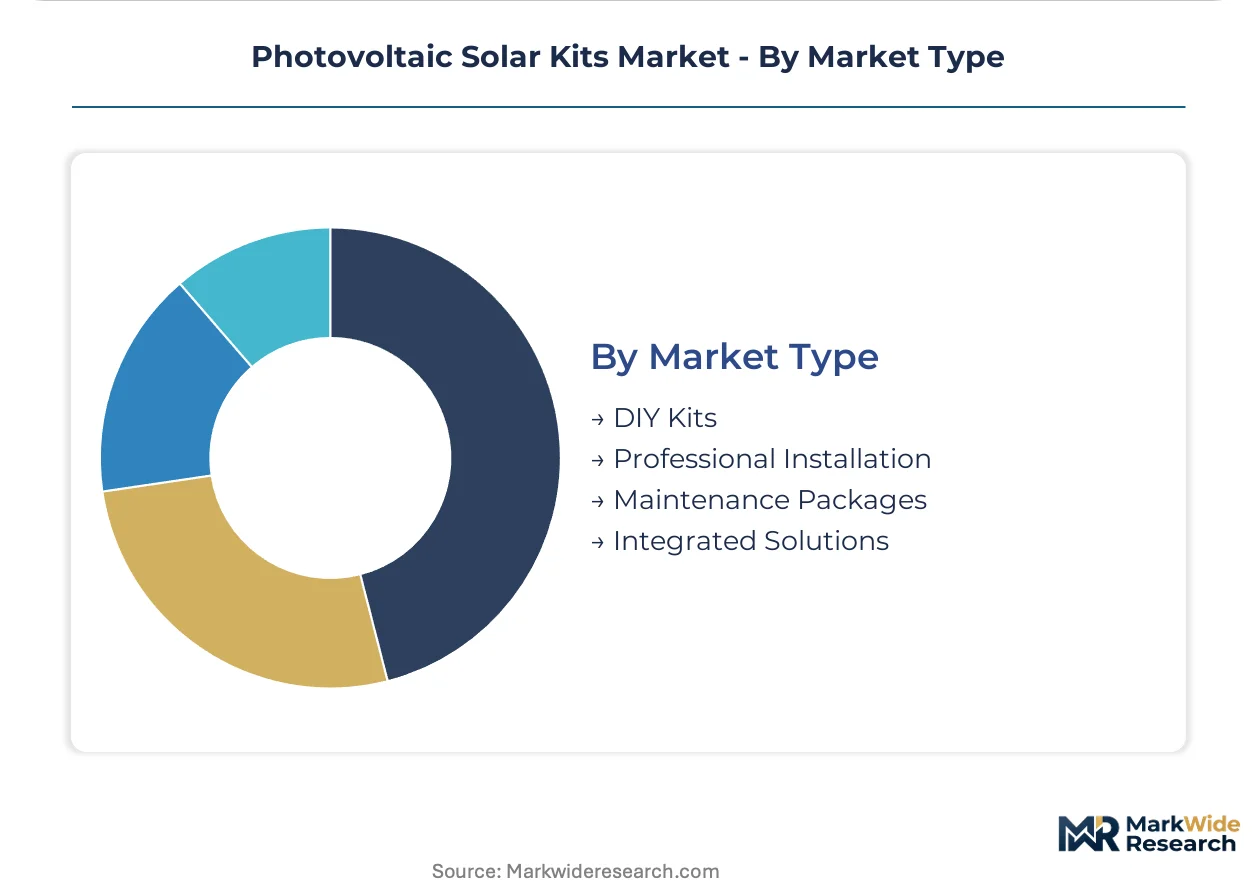
Market Type:
Channel structure reflects buyer technical confidence, with DIY segments demanding simplified interfaces and professional channels requiring contractor training and support infrastructure.
- DIY Kits:Pre-engineered assemblies with plug-and-play connectivity target homeowners capable of self-installation without electrical contractor engagement. Jinko Solar's integrated wafer-to-module production serves this cost-sensitive segment.
- Professional Installation:Kits distributed through certified contractor networks ensure NEC Article 690 grounding compliance and local authority permitting. Qualified installer scarcity in rapidly growing suburban markets constrains segment expansion.
- Integrated Solutions:Turnkey packages spanning equipment, installation, financing, and long-term performance monitoring. LONGi anchors premium rooftop deployments through high-efficiency monocrystalline cell architectures in this channel.
- Maintenance Packages:Service contracts covering inverter replacement, panel cleaning, and battery capacity degradation monitoring. Third-party financiers in Australia's regional markets bundle these with zero-down installation offerings.
Professional Installation channels process the majority of system value. DIY Kits are expanding most quickly as simplified interfaces reduce technical barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential solar kit deployment in Australia outpaces Germany on a per-capita basis, yet both markets remain dwarfed by absolute installation volumes across the United States where suburban electrification drives procurement.
United States
Net metering arbitrage in California and Arizona accelerates payback periods for rooftop systems. The Inflation Reduction Act's domestic content bonus credits require 40% North American sourcing for enhanced tax eligibility. Phoenix and Dallas-Fort Worth metro areas concentrate contractor networks serving DIY-adjacent professional installation channels.
Germany
Feed-in tariff optimization through EEG eligibility for sub-30kW systems subsidizes upfront capital costs for rural agricultural facilities. Bundesnetzagentur administration of tariff schedules directly influences kit-integrated system economics. Bavaria and Baden-Württemberg host dense distributions of ground-mounted dual-use land applications.
Australia
Regional electrification gaps in Queensland and Western Australia sustain off-grid cabin operator demand bypassing traditional utility infrastructure. Clean Energy Council component accreditation determines Small-scale Renewable Energy Scheme certificate eligibility. Perth and Brisbane anchor third-party financier networks offering zero-down performance-guaranteed service contracts.
China
Polysilicon supply concentration creates input cost volatility for module assemblers serving export markets. MIIT inverter efficiency mandates and evolving battery recycling directives shape product qualification requirements. Yangtze River Delta manufacturing clusters control wafer-to-module production integration for cost-sensitive kit segments.
Photovoltaic Solar Kits Market Competitive Landscape
Chinese producers anchor the volume tier; North American and European specialists hold premium positioning through regulatory compliance and localized service infrastructure. Market structure fragments across three distinct tiers: integrated wafer-to-module manufacturers, hybrid storage-integrated kit assemblers, and regional contractors bundling installation with financing. Strategic moves concentrate on backward integration into polysilicon refining and inverter-battery convergence within single SKUs.
Within the integrated manufacturing tier, Jinko Solar and LONGi exemplify divergent positioning archetypes—one serving cost-optimized DIY channels through captive wafer supply, the other anchoring premium rooftop deployments via high-efficiency monocrystalline architectures. Canadian Solar occupies a hybrid position across storage-integrated configurations. Silfab Solar represents North American fabrication specialists navigating domestic content credit requirements.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar |
| Hanwha Qcells |
| Jinko Solar |
| Trinasolar |
| JA Solar Technology Co., Ltd. |
| LONGi |
| Silfab Solar |
| Hyperion Solar |
| Others |
Pricing and Supply Chain Analysis
Residential preference for battery-autonomy over simple grid-tied generation is forcing module assemblers to absorb lithium iron phosphate cell cost volatility while competing for price-sensitive DIY segments. This demand pivot concentrates margin pressure on storage-integrated kit configurations where inverter-battery convergence within single SKUs has become the primary cost engineering target.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for wafer-to-module production serving export markets. Pricing stratifies across premium rooftop deployments, standard contractor-channel kits, and economy DIY segments differentiated by certification grade and after-sales bundling. Cost compression in the economy tier is intensifying because Jinko Solar's captive polysilicon supply anchors aggressive positioning. Agricultural facilities in Australia's regional markets exhibit lowest price sensitivity due to third-party financier absorption of upfront capital.
Supply Chain Analysis
Skilled technician availability constraints in China's Jiangsu and Zhejiang provinces are elevating automation investment requirements for module assembly lines. Manufacturing gravity centers on China for wafer production, Vietnam for module assembly serving tariff-sensitive export markets, and the United States for domestic content bonus credit compliance. The supply chain draws from polysilicon feedstock, lithium iron phosphate cells, and aluminum racking systems. Single-source vulnerability in Chinese polysilicon refining creates input cost volatility for price-sensitive segments. Distribution runs through certified contractor networks in established markets and direct-to-consumer e-commerce in DIY channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Inflation Reduction Act's domestic content bonus credits function as a regulatory compounder, accelerating supply chain reconfiguration toward North American assembly and subsidizing residential procurement decisions.
For Market Incumbents: Anticipate inverter-battery convergence compressing standalone component margins and eroding pure-play charge controller vendors. Backward integration into lithium iron phosphate cell sourcing defends positioning in storage-integrated configurations. NEC Article 690 permitting heterogeneity across United States jurisdictions demands localized contractor training infrastructure investment. For New Entrants and Emerging Players: Recreational vehicle electrification and disaster relief procurement represent the most penetrable white-space segments, with portable kit demand expanding fastest among remote workers in Australia. Third-party financier partnerships in Queensland and Western Australia offer zero-down installation channels bypassing traditional distributor relationships. Specification simplicity and plug-and-play connectivity anchor effective go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid storage-integrated kit assemblers possessing inverter-battery convergence capabilities and Clean Energy Council accreditation for Australian certificate eligibility. Long-term viability over the mid-decade horizon hinges on domestic content credit capture and polysilicon supply security. Watch for IEEE 1547 interconnection queue clearance rates as inflection indicator for hybrid system revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Iron Phosphate Cells | Captures Inflation Reduction Act domestic content bonus credits for storage-integrated kits. |
| Inverter-Battery Convergence within Single SKUs | Compresses balance-of-system costs and installation labor for residential contractors. |
| Clean Energy Council Component Accreditation | Unlocks Small-scale Renewable Energy Scheme certificate revenue streams in Australia. |
| Recreational Vehicle Channel Partnership | Expands addressable market beyond fixed rooftop installations into fastest-growing portable segment. |
| Third-Party Financier Network Development | Displaces traditional distributor channels with performance-guaranteed service contracts in regional markets. |
Research Methodology
Direct dialogue with residential solar contractors, EPC project developers, utility interconnection officers, and lithium iron phosphate cell procurement managers grounded qualitative assessment in operational reality. Secondary validation drew from EIA installation databases, IEA renewable energy reports, FERC interconnection filings, and Clean Energy Council accreditation records. Bottom-up and top-down triangulation reconciled installer-reported deployment volumes with customs-tracked module import flows.
Bottom-up modeling segmented the analysis window by product type, usage scenario, component category, and channel structure. Capacity additions, feed-in tariff schedules, and net metering policy evolution served as industry-specific forecast inputs. CAGRs emerged from reconciling historical deployment trajectories with projected policy incentive trajectories and battery chemistry cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon supply disruption, inverter efficiency mandate acceleration, and battery recycling directive implementation. Forecasts reflect assumptions around lithium iron phosphate cost compression continuity and residential autonomy preference persistence. Material deviation in IRA domestic content credit enforcement or Bundesnetzagentur EEG tariff revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Australia Solar Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market