
 Power Cables Market | 2026-2036
Power Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Power Cables Market Intelligence
Project-based procurement through large engineering, procurement, and construction firms is rewriting the traditional distribution model for high-voltage cables. Prysmian Group leverages its extensive manufacturing scale to secure large-scale infrastructure contracts. Nexans specializes in submarine and high-voltage direct current systems for offshore wind interconnections. Meanwhile, Southwire Company dominates the residential and commercial construction segments in North America.
Power cables are assemblies of one or more electrical conductors, typically made of copper or aluminum, held together with an overall sheath. Their primary function is the transmission of electrical power, with insulation materials like cross-linked polyethylene determining voltage capacity and operational safety. High-voltage and extra-high-voltage cables command the highest margins, driven by demand from utility providers for grid upgrades. The renewable energy application segment, particularly for submarine installations, represents the fastest-growing category.
Product standards are governed by bodies like the International Electrotechnical Commission and national frameworks such as China's GB standards. Environmental regulations, including Europe's RoHS directive and rules from the US EPA on material disposal, influence conductor and insulation material selection. Navigating the complex landscape of regional grid interconnection standards and local content requirements remains a critical challenge for manufacturers.
Market Dynamics
The central force shaping the power cable market is the global energy transition, which mandates massive investment in grid modernization and new renewable energy interconnections, shifting demand toward high-specification, project-based cable systems.
Growth Catalysts
- Grid Modernization Mandates:Policies like the EU Green Deal compel utilities to upgrade networks with high-capacity cables to support renewable energy integration and enhance grid stability.
- Renewable Energy Expansion:Offshore wind and large-scale solar projects require specialized high-voltage submarine and terrestrial cables for grid interconnection and power transmission.
- Emerging Market Urbanization:Rapid industrial growth in Southeast Asia fuels demand for new power transmission and distribution infrastructure to support economic expansion.
Market Restraints
- Commodity Price Volatility:Fluctuations in copper and aluminum prices on the London Metal Exchange directly impact manufacturing costs and create significant margin pressure.
- Divergent Technical Standards:Conflicting national grid codes, like IEC versus China's GB standards, complicate cross-border projects and increase compliance burdens for manufacturers.
- Manufacturing Bottlenecks:The long lead times required for producing specialized high-voltage submarine cables create significant delays for large-scale offshore energy projects.
Strategic Opportunities
- High-Temperature Superconductors (HTS):Developing HTS cables presents an opportunity for ultra-high-capacity, low-loss transmission lines needed for dense urban grids.
- Data Center Infrastructure:The growth of hyperscale data centers creates demand for high-reliability, high-voltage power distribution systems within large campuses.
- Clean Energy Policy Tailwinds:Legislation like the US Inflation Reduction Act (IRA) accelerates renewable projects, creating derived demand for grid interconnection cables.
Industry Challenges
- Specialized Labor Shortages:A lack of trained technicians for high-voltage cable jointing and termination, particularly for submarine applications, constrains project execution schedules.
- Environmental Compliance Burden:Navigating multiple material rules, from Europe's RoHS directive to US EPA regulations, increases operational costs and design complexity.
- Capital-Intensive Manufacturing:Expanding production for extra-high-voltage and submarine cables requires massive capital investment, limiting supply-side agility and responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Cables Market |
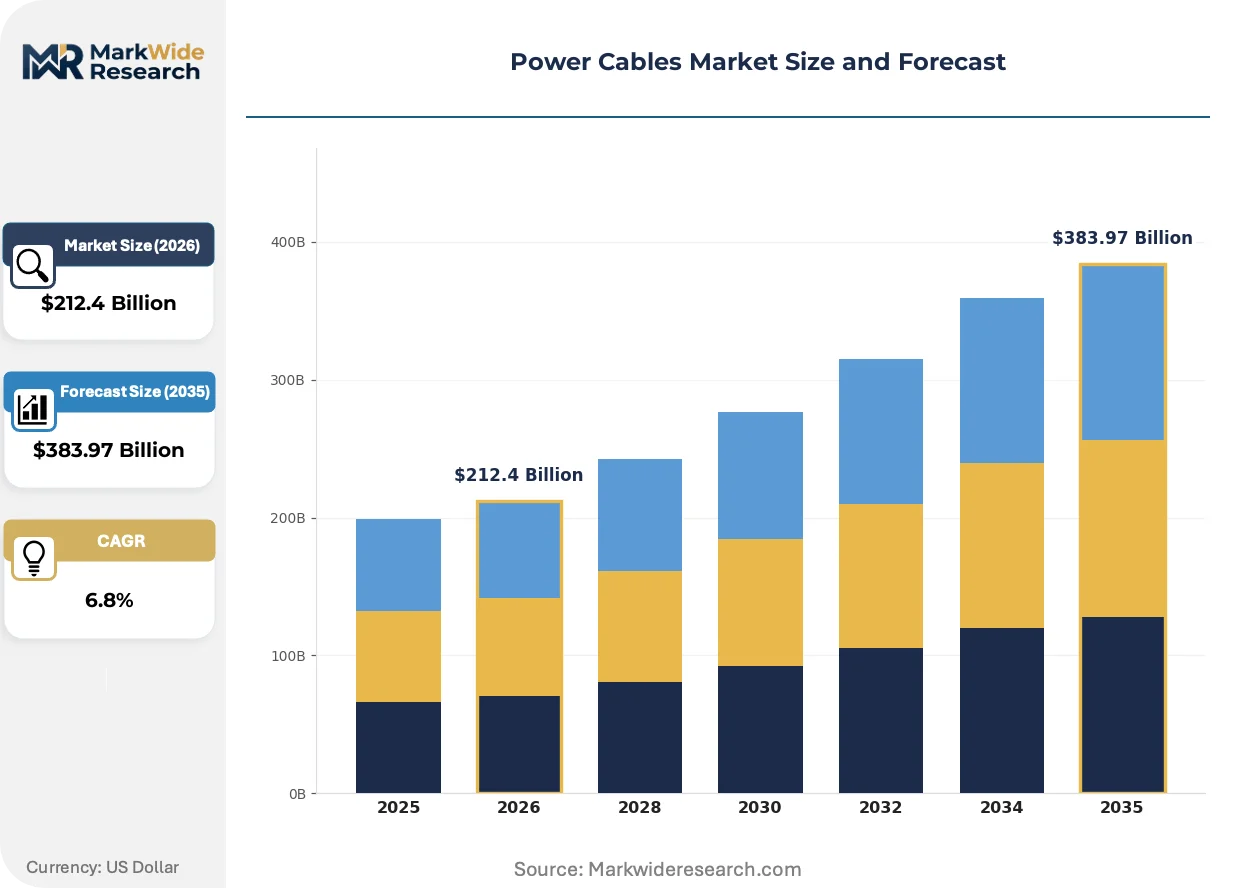
| Market Size in 2026 | $212.4 Billion |
| Market Size in 2035 | $383.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Application: Renewable Energy, Telecommunication Networks, Construction Projects, Data Centers, Public Infrastructure End User: Utility Providers, Residential Complexes, Commercial Facilities, Government Agencies Installation Type: Underground, Overhead, Submarine, Indoor, Direct Burial |
| Companies Covered | Prysmian Group, Nexans, NKT A/S, ABB Ltd, Sumitomo Electric Industries, Southwire Company, Belden, LS Cable & System, Fujikura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Cables Market Strategic Shifts & Innovations
Material science advancements and tightening environmental regulations are fundamentally re-architecting power cable design. This evolution prioritizes higher electrical performance, improved safety characteristics, and a reduced environmental footprint across the product lifecycle.
Cross-linked polyethylene (XLPE) is a thermoset polymer used as a high-performance electrical insulation material for power cables. Utility providers and renewable energy developers are specifying XLPE insulation for nearly all new medium- and high-voltage grid infrastructure. Its superior dielectric strength and thermal resistance at higher voltages is rendering obsolete older technologies like paper-insulated lead-covered cables in critical transmission applications.
Europe's Restriction of Hazardous Substances (RoHS) directive imposes strict limits on the use of lead, cadmium, and certain flame retardants. This regulation forces cable manufacturers to reformulate insulation and sheathing compounds, shifting development toward halogen-free, flame-retardant (HFFR) materials. The building wire and low-voltage cable segments are most directly impacted, requiring product redesigns to maintain market access within the EU.
A definitive shift from transactional component sales to integrated, project-based solutions is underway for large-scale infrastructure. This approach sees large engineering, procurement, and construction (EPC) firms contracting directly with manufacturers for complete cable systems, bypassing traditional distribution channels. This trend is most pronounced in the global offshore wind and cross-border grid interconnection markets where project complexity is highest.
Power Cables Market Segmentation
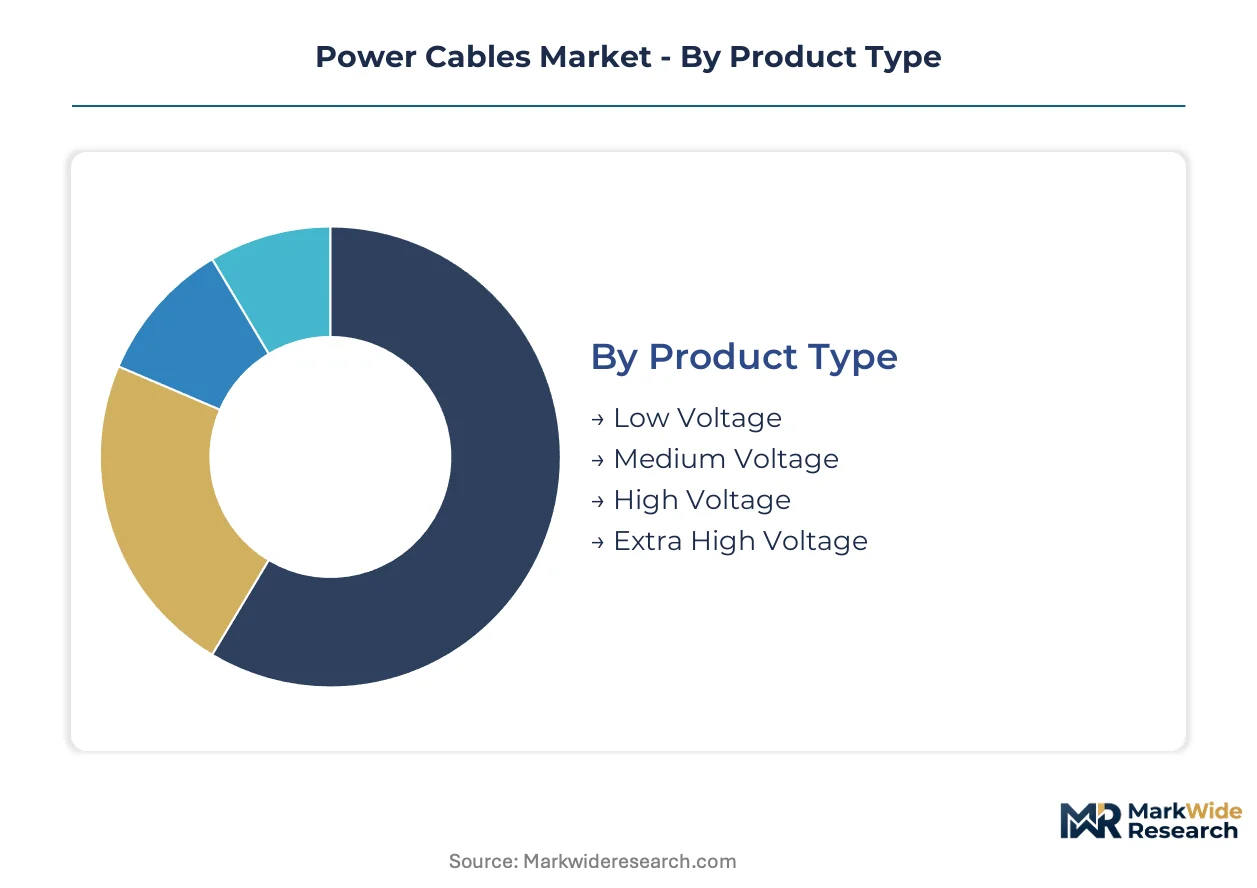
Segmentation provides a structured view of the power cables market, highlighting distinct product capabilities, application demands, and end-user requirements. Understanding these granular segments is essential for manufacturers to tailor product development, optimize distribution strategies, and navigate the complex regulatory landscape.
Product Type:
Power cable product types dictate varying levels of after-sales service intensity, reflecting installation complexity and operational criticality.
- Low Voltage:These cables operate up to 1 kV, primarily used for power distribution within residential and commercial buildings.
- Medium Voltage:Ranging from 1 kV to 69 kV, these cables serve local distribution networks and industrial power applications.
- High Voltage:These cables transmit power over long distances at voltages typically between 69 kV and 230 kV, often using XLPE insulation. Demand concentrates in utility grid modernization projects across Europe, driven by renewable energy integration mandates like the EU Green Deal.
- Extra High Voltage:Operating above 230 kV, these specialized cables are designed for bulk power transmission and intercontinental grid connections. Utility providers in developing economies like India require EHV systems for new industrial corridors and urban expansion.
High Voltage cables hold the largest share; momentum sits with Extra High Voltage for long-distance transmission.
Application:
The application segments for power cables reflect diverse operational criticality and specific technical requirements.
- Renewable Energy:This segment includes specialized cables for connecting solar farms, onshore wind turbines, and complex submarine cables for offshore wind projects. Demand is accelerating in the North Sea region, driven by large-scale offshore wind farm interconnections.
- Telecommunication Networks:Power cables support the infrastructure for telecommunication networks, including base stations and data transmission facilities.
- Construction Projects:This segment encompasses general wiring and power distribution for new residential and commercial building developments.
- Data Centers:Hyperscale data centers require robust, high-reliability power distribution systems within their campuses, often incorporating high-voltage solutions. The rapid expansion of cloud computing services in the US fuels this specific infrastructure demand.
- Public Infrastructure:Cables are essential for powering public services, including street lighting, transportation systems, and municipal utilities.
Renewable Energy applications exhibit the steepest expansion trajectory, while Construction Projects maintain a consistent baseline demand.
End User:
End user segments exhibit distinct procurement patterns, influencing cable specifications and contract structures.
- Utility Providers:These entities purchase high-capacity power cables for grid expansion, modernization, and maintenance of national transmission and distribution networks. Investment in Europe's grid infrastructure drives substantial procurement by utility companies.
- Residential Complexes:Cables for multi-unit dwellings and housing developments primarily involve low and medium voltage distribution systems.
- Commercial Facilities:This segment includes power cable installations for office buildings, retail centers, and industrial plants, requiring diverse voltage and fire safety ratings. Urbanization in Southeast Asia contributes to consistent demand for commercial facility power infrastructure.
- Government Agencies:Public sector entities procure cables for infrastructure projects, defense installations, and administrative buildings.
Utility Providers account for the highest value procurement due to specialized cable requirements, while Residential Complexes contribute significant volume.
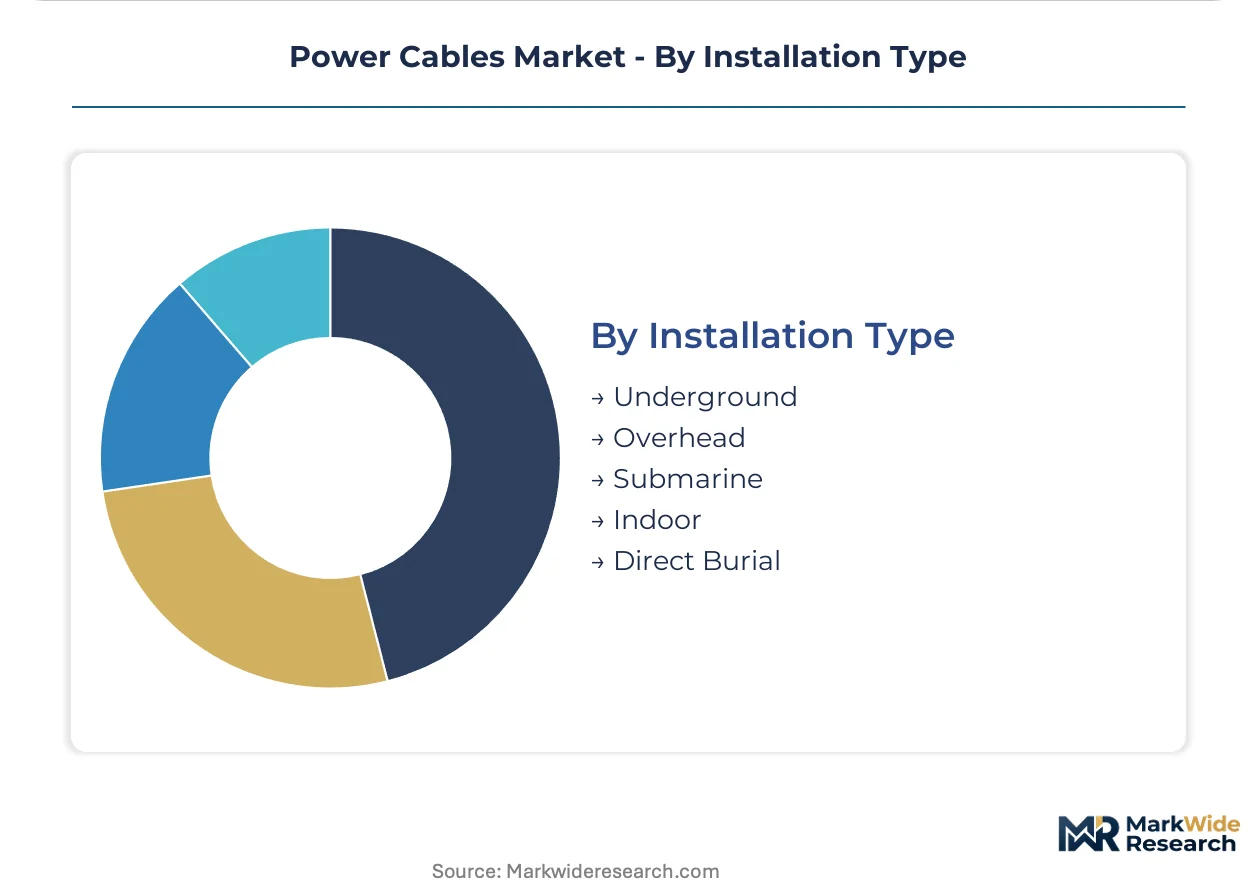
Installation Type:
Installation types face varying environmental impacts and regulatory burdens, shaping material selection and deployment methods.
- Underground:Buried cables offer aesthetic and safety advantages, commonly used in urban areas and for high-voltage transmission where overhead lines are impractical. Grid modernization initiatives in densely populated European cities favor underground cable deployment.
- Overhead:Traditional power lines supported by poles or towers, commonly used for long-distance transmission in rural and suburban areas.
- Submarine:These highly specialized cables transmit power under water, primarily connecting offshore wind farms to onshore grids or forming inter-country grid links. The expansion of offshore wind energy in the North Sea region drives significant demand for submarine cable projects.
- Indoor:Cables designed for internal building wiring and power distribution within enclosed structures.
- Direct Burial:Cables installed directly into the ground without conduits, requiring robust sheathing for protection.
Submarine installations represent the highest technological complexity, while Overhead remains a cost-effective solution for many regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global energy transition initiatives, including the EU Green Deal and the US Inflation Reduction Act, significantly reshape power cable demand. These policies mandate substantial investments in grid modernization and new renewable energy interconnections. Consequently, demand shifts towards high-specification, project-based cable systems across diverse geographies.
United States
The United States market sees robust demand for high-reliability power distribution systems within hyperscale data centers. The US Inflation Reduction Act accelerates renewable energy projects, creating derived demand for grid interconnection cables. Major data center hubs like those in Northern Virginia and Texas drive specialized cable procurement.
Germany
Germany's power cable demand is substantially influenced by the EU Green Deal's mandates for grid upgrades. Utilities prioritize high-capacity cables to integrate increasing renewable energy sources, particularly offshore wind. The North Sea region, with its extensive offshore wind development, necessitates complex submarine cable installations.
India
India requires substantial extra-high-voltage systems to support new industrial corridors and rapid urban expansion. The country's national grid modernization programs focus on enhancing transmission capacity for economic growth. Cities like Mumbai and Delhi are investing in robust underground infrastructure for reliable power delivery.
China
China's vast infrastructure development and industrial expansion drive significant power cable consumption. National frameworks, including GB standards, govern product specifications and material selection for widespread deployment. Major industrial zones in the Yangtze River Delta and Pearl River Delta fuel continuous demand for power transmission and distribution.
Vietnam
Vietnam experiences significant power cable demand due to rapid urbanization and industrial growth across Southeast Asia. Government initiatives support new power transmission and distribution infrastructure to sustain economic development. Industrial parks in provinces like Binh Duong and Dong Nai require extensive cabling for manufacturing operations.
Power Cables Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few global giants dominating high-value, specialized segments like extra-high-voltage and submarine cables. These large-scale manufacturers operate alongside numerous regional specialists and niche players focusing on specific applications. Strategic archetypes include integrated system providers, specialized technology developers, and regional volume producers. Dominant competitive moves involve significant capital investment in advanced manufacturing and strategic partnerships for complex project execution.
At the scale-driven end, Prysmian Group exemplifies extensive manufacturing scale, securing large-scale infrastructure contracts across various geographies. Nexans occupies a position as a specialist in submarine and high-voltage direct current systems, crucial for offshore wind interconnections and cross-border grid links. Southwire Company anchors the residential and commercial construction segments within North America, representing a strong regional focus for distribution and building wire. These entities highlight the diverse strategic orientations within the power cables market.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT A/S |
| ABB Ltd |
| Sumitomo Electric Industries |
| Southwire Company |
| Belden |
| LS Cable & System |
| Fujikura |
| Others |
Cost & Logistics Intelligence
Commodity price volatility on the London Metal Exchange determines both pricing tier spreads and the supply chain shape for power cables. This directly impacts manufacturing costs and margins across all voltage categories.
Pricing Analysis
Certification level, driven by IEC or China's GB standards, creates the primary pricing spread for power cables. Project-based procurement dominates high-voltage segments, while transactional per-unit sales characterize low-voltage cables. Price differentiation also stems from specialized after-sales service for complex installations like submarine cables, and geographic delivery costs. Pricing softness runs through standard low-voltage cables due to intense competition, while utility providers exhibit lower price sensitivity for mission-critical extra-high-voltage systems.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often underpin large-scale infrastructure projects, especially for high-value cable systems. Supply for power cables concentrates in China, Europe, and India, reflecting major manufacturing and demand hubs. Raw material dependencies center on copper and aluminum for conductors, alongside specialized polymers like XLPE and HFFR for insulation. Divergent technical standards, such as IEC versus GB, pose a structural risk to cross-border project execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power cables market faces significant project execution constraints due to a pronounced capability scarcity. A lack of trained technicians for high-voltage cable jointing and termination represents a critical skill gap.
For Market Incumbents: Entrench market leadership by investing heavily in extra-high-voltage and submarine cable manufacturing capacity, particularly in Europe's North Sea region. Form strategic partnerships with EPC firms to secure long-term project-based contracts and mitigate specialized labor shortages. Deepen control over critical raw material supply to counter commodity price volatility. Prioritize R&D into high-temperature superconductor cables to address future grid demands.
For New Entrants and Emerging Players: Residential and commercial construction segments in rapidly urbanizing Southeast Asian economies represent the most penetrable entry point for new power cable manufacturers. Focus on low-voltage and medium-voltage cables that comply with regional GB standards or HFFR material requirements for European export. Develop localized distribution networks and offer competitive pricing for volume-driven projects. Target data center infrastructure in the US with high-reliability power distribution solutions.
For Investors and Strategic Acquirers: The EU Green Deal and US Inflation Reduction Act reshape the acquisition landscape for power cable manufacturers, driving consolidation around high-specification capabilities. Long-term viability hinges on companies positioned to capitalize on global grid modernization and renewable energy interconnections over the next decade. Target specialized technology developers with expertise in submarine or extra-high-voltage systems. Watch for significant new project awards in offshore wind as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for EHV Cables | Addresses manufacturing bottlenecks for critical offshore wind and grid modernization projects. |
| R&D into HTS Cables | Enables ultra-high-capacity, low-loss transmission for future dense urban grids. |
| Strategic Partnerships with EPCs | Secures large-scale infrastructure contracts and streamlines complex project execution. |
| Material Reformulation for HFFR | Ensures compliance with Europe's RoHS directive and meets tightening environmental regulations. |
| Geographic Expansion in Southeast Asia | Capitalizes on rapid urbanization and industrial growth across developing economies. |
Research Approach
Findings reconcile primary fieldwork against secondary review of IEC standards, national GB standards, and US EPA regulations. This included interviews with utility planning officers, EPC contractors, and R&D directors at cable manufacturing firms. Bottom-up data collection from regional reports was triangulated with top-down market sizing for comprehensive validation. London Metal Exchange data informed commodity price impact assessments.
Forecast inputs considered global energy transition policies, grid modernization investment, and the offshore wind project pipeline across the analysis window. The analytical framework modeled product type, application, end-user, installation type, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected future demand. This approach captured shifts in high-specification cable systems.
Practitioners should monitor commodity price volatility and shifts in environmental regulations for early signals of market deviation. Forecasts reflect current assumptions regarding global energy policies and infrastructure investment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Egypt Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Turbine Governor Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Gas Turbine Compressor Market