
 Nigeria Power EPC Market | 2026-2036
Nigeria Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Power EPC Market Foresight
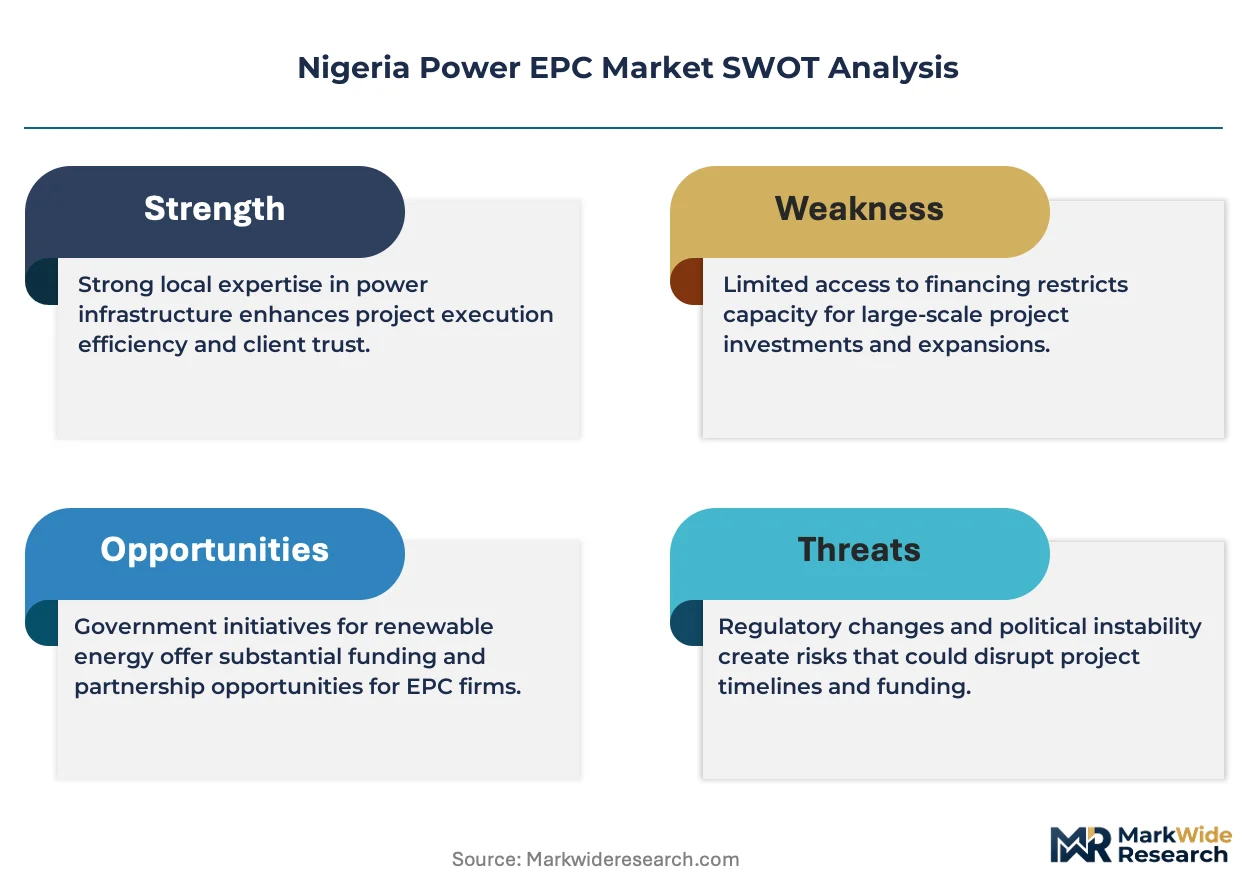
The Nigeria Power EPC market is restructuring around a sharp split between premium integrated solutions and commodity build-only contracts. Sinohydro leverages its dam construction heritage to dominate large-scale hydro installations. Sterling and Wilson Nigeria Limited anchors its position through end-to-end solar EPC capabilities spanning engineering to commissioning. Energo Nigeria Ltd. differentiates by specializing in biomass and captive power systems for industrial clusters.
Nigeria Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation, transmission, and distribution infrastructure, typically involving turbine-generator sets with 30-500 MW ratings, 132-330 kV transmission lines, and SCADA-integrated control systems designed to bridge a national grid gap exceeding 85,000 MW of unmet demand. Solar EPC services command premium margins as distributed generation accelerates, while hydro projects retain the largest absolute contract values due to federal funding pipelines. Construction services absorb the majority of labor allocation, though maintenance contracts are extending in duration as asset owners seek operational certainty over twenty-year horizons.
The Nigerian Electricity Regulatory Commission, Rural Electrification Agency, and Bureau of Public Procurement collectively shape market access through licensing tiers, rural electrification mandates, and domestic content requirements that favor local joint ventures. NERC's eligible customer regulations are redirecting industrial offtake toward bilateral power purchase agreements, bypassing distribution utilities. Stakeholders must track how the Central Bank of Nigeria's power sector intervention facility evolves, as foreign exchange liquidity constraints determine whether imported equipment flows or project pipelines stall.
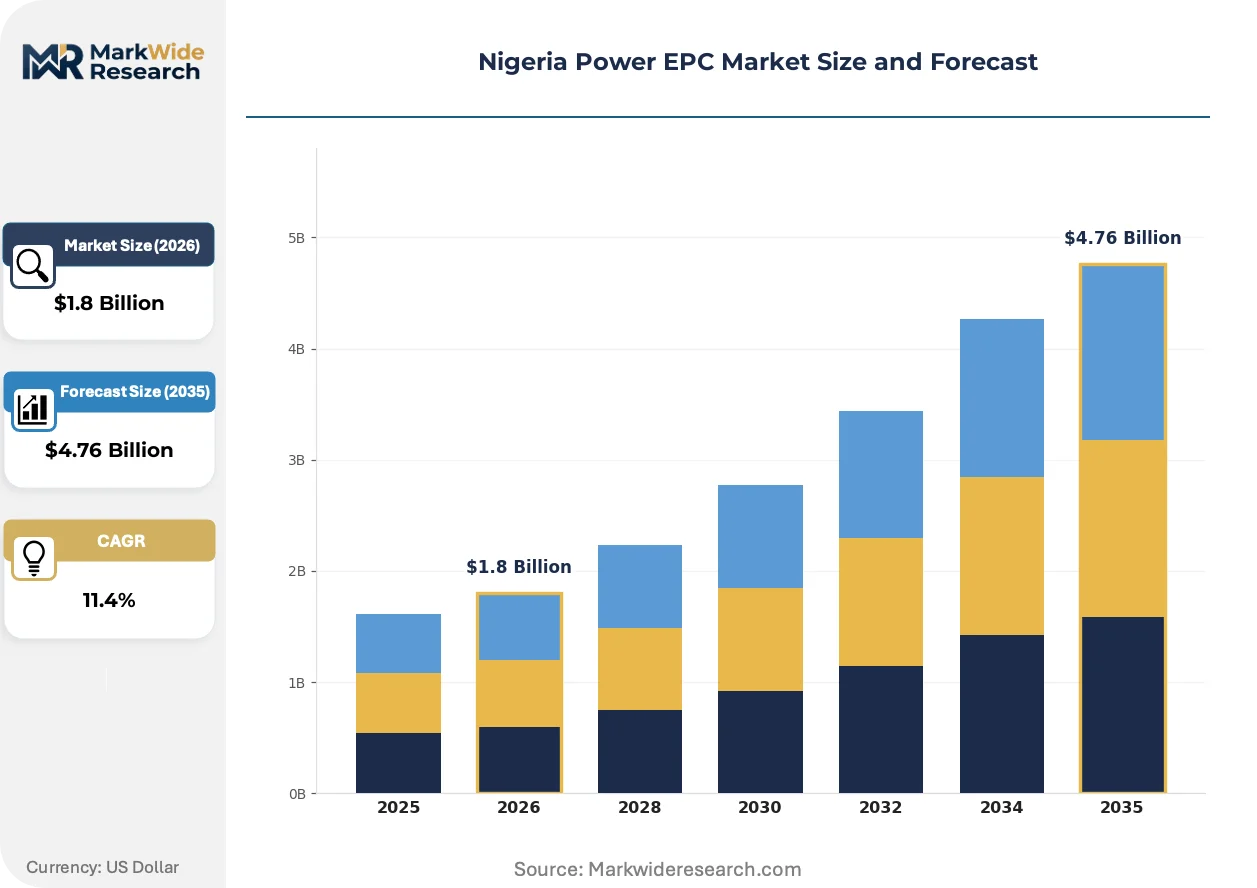
Market Dynamics
The Nigerian Electricity Regulatory Commission's Mini Grid Regulations are fragmenting centralized procurement into bilateral power purchase agreements, forcing EPC contractors to restructure around distributed generation clusters rather than transmission-scale projects.
Growth Catalysts
- NERC Eligible Customer Regulations:Industrial offtakers in cement and steel sectors now bypass distribution utilities through direct bilateral contracts, creating captive power demand that EPC contractors serve.
- Solar PV cost compression:Module price declines are enabling distributed generation deployments at industrial clusters previously dependent on diesel backup systems.
- Rural Electrification Agency mandates:Federal electrification targets are channeling development finance toward off-grid solar-hybrid mini-grids in unserved settlements.
Market Restraints
- Foreign exchange illiquidity:Central Bank of Nigeria intervention facility disbursement delays stall equipment imports for turbine-generator sets and SCADA systems.
- Domestic content thresholds:Bureau of Public Procurement local participation rules force joint venture structures that fragment project accountability.
- Gas supply intermittency:Pipeline vandalism in the Niger Delta corridor undermines thermal plant commissioning schedules and long-term service contracts.
Strategic Opportunities
- Biomass-to-power convergence:Agricultural residue feedstock availability in northern states enables EPC contractors to deploy combined heat and power systems for food processing clusters.
- Twenty-year maintenance contract extension:Asset owners seek operational certainty beyond standard defect liability periods, expanding recurring revenue pools.
- Lagos-Ibadan industrial corridor densification:Manufacturing relocation from congested Lagos ports creates concentrated demand for embedded generation infrastructure.
Industry Challenges
- Commissioning engineer scarcity:Specialized technicians for 132-330 kV substation energization are concentrated among legacy utility staff, constraining contractor scaling.
- Legacy grid synchronization:Distributed generation assets face technical barriers integrating with aging transmission infrastructure in the national grid.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Power EPC Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Installation, Maintenance, Consultation Technology: Solar, Wind, Biomass, Hydro End User: Utilities, Industrial Users, Government, Commercial Sector Project Size: Large Scale, Medium Scale, Small Scale, Micro Projects |
| Companies Covered | Sinohydro, Sterling and Wilson Nigeria Limited, Energo Nigeria Ltd., Siemens Energy Nigeria, JuNeng Nig Ltd., Gentec EPC Ltd., Alten Energías Renovables, Rensource Energy, Andritz AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Power EPC Market Shifts & Advancements
Digitalization is compressing engineering-to-commissioning cycles while regulatory fragmentation is spawning new contract structures that separate construction from long-term asset operation.
Containerized solar-plus-storage systems are unifying generation and frequency regulation in single modular footprints. Industrial estates in Kano and Ogun states are deploying these systems to isolate from grid instability. This convergence is unifying EPC scope definitions, forcing contractors to absorb battery integration and control system commissioning within standard solar construction contracts.
The Nigerian Electricity Regulatory Commission's Mini Grid Regulations are mandating standardized tariffs and licensing tiers for off-grid developers. This framework is compressing project development timelines by pre-approving technical specifications. Rural electrification projects in Sokoto and Kebbi states are responding through bulk procurement of pre-certified equipment packages.
Industrial offtakers are compressing supplier selection cycles from eighteen-month feasibility studies to six-month direct negotiations. Cement and steel producers in the Niger Delta corridor are bypassing traditional distribution utility channels entirely. This behavioral shift is most visible at Obajana and Ewekoro industrial complexes, where captive power EPC awards now prioritize construction speed over lowest capital cost.
Nigeria Power EPC Market Segmentation
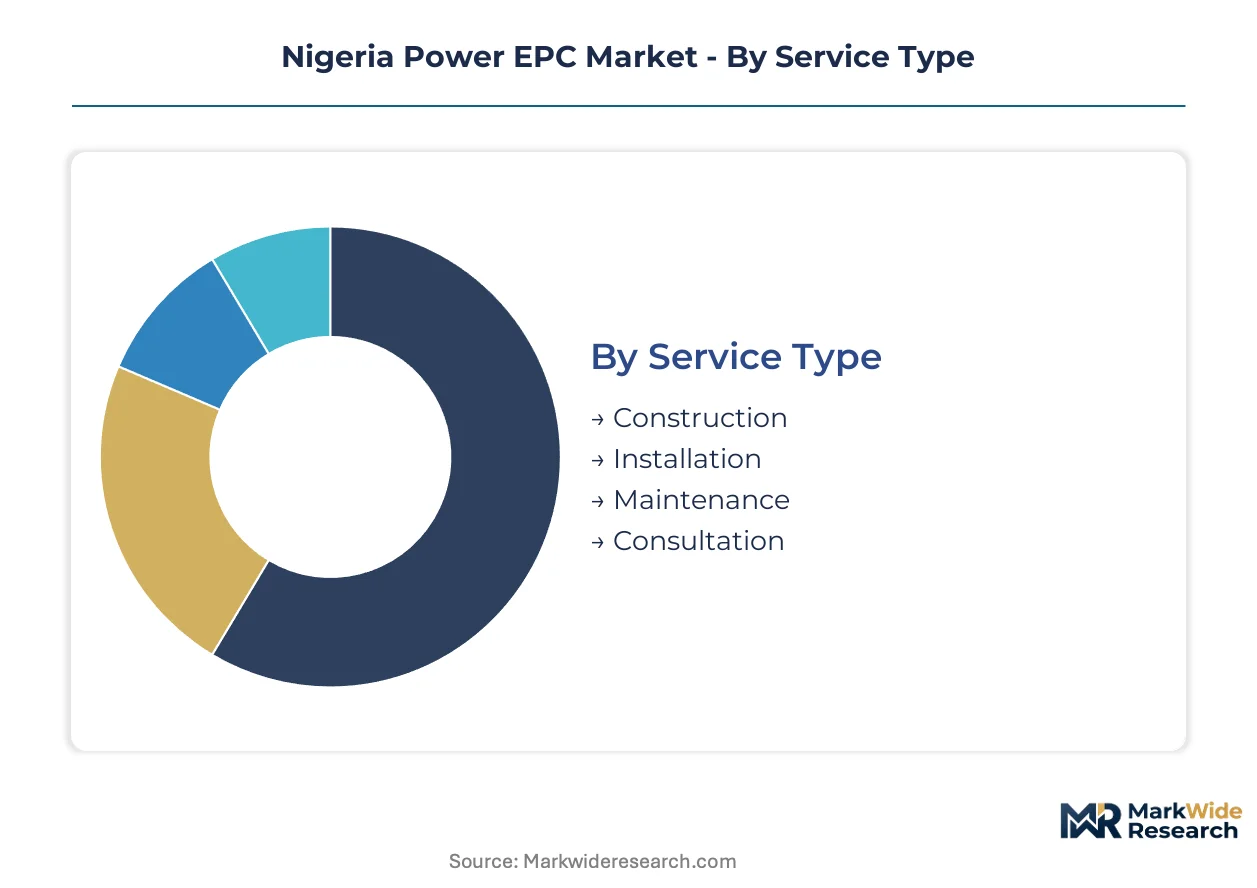
Nigeria Power EPC contractors structure pricing and capability investments around four distinct segmentation axes. Service scope determines margin profiles, while technology choice shapes equipment import dependencies and regulatory pathways.
Service Type:
Construction commands the largest labor allocation but compresses margins, while maintenance contracts extend revenue horizons across twenty-year asset lifecycles.
- Construction:Civil works, structural steel erection, and turbine-generator foundation installation absorb 60-70% of project man-hours. Cement and steel industrial clusters in the Niger Delta corridor drive demand as captive power investments accelerate.
- Installation:Mechanical assembly of 30-500 MW turbine-generator sets, 132-330 kV substation equipment, and SCADA control system integration demands specialized commissioning engineers concentrated among legacy utility staff.
- Maintenance:Asset owners seek operational certainty beyond standard defect liability periods, expanding recurring revenue pools through long-term service agreements.
- Consultation:Feasibility studies and grid integration planning navigate NERC licensing tiers and Bureau of Public Procurement domestic content thresholds.
Mature deployment sits with Construction. Newer deployment is concentrated in Maintenance.
Technology:
Solar EPC services command premium margins as distributed generation accelerates, while hydro projects retain the largest absolute contract values due to federal funding pipelines.
- Solar:Containerized solar-plus-storage systems unify generation and frequency regulation in single modular footprints for industrial estates in Kano and Ogun states. Rural Electrification Agency mandates channel development finance toward off-grid solar-hybrid mini-grids in Sokoto and Kebbi states.
- Hydro:Large-scale dam construction leverages federal funding pipelines and Sinohydro's heritage in turbine installation. Foreign exchange illiquidity from Central Bank of Nigeria intervention facility delays constrains equipment import flows.
- Biomass:Agricultural residue feedstock availability in northern states enables combined heat and power systems for food processing clusters.
- Wind:Limited deployment concentrates in coastal corridors with nascent resource assessment infrastructure.
Established capacity centers on Hydro. Climbing the fastest trajectory is Solar.
End User:
Industrial offtakers compress supplier selection cycles from eighteen-month feasibility studies to six-month direct negotiations, bypassing traditional distribution utility channels.
- Industrial Users:Cement and steel producers at Obajana and Ewekoro industrial complexes prioritize construction speed over lowest capital cost for captive power EPC awards. NERC Eligible Customer Regulations enable direct bilateral power purchase agreements.
- Utilities:Transmission-scale procurement fragments as Mini Grid Regulations redirect capital toward distributed generation clusters.
- Government:Rural electrification targets and Bureau of Public Procurement local participation rules force joint venture structures.
- Commercial Sector:Lagos-Ibadan industrial corridor densification creates concentrated demand for embedded generation infrastructure.
Procurement volume concentrates with Industrial Users. Emerging demand is shifting toward Commercial Sector.
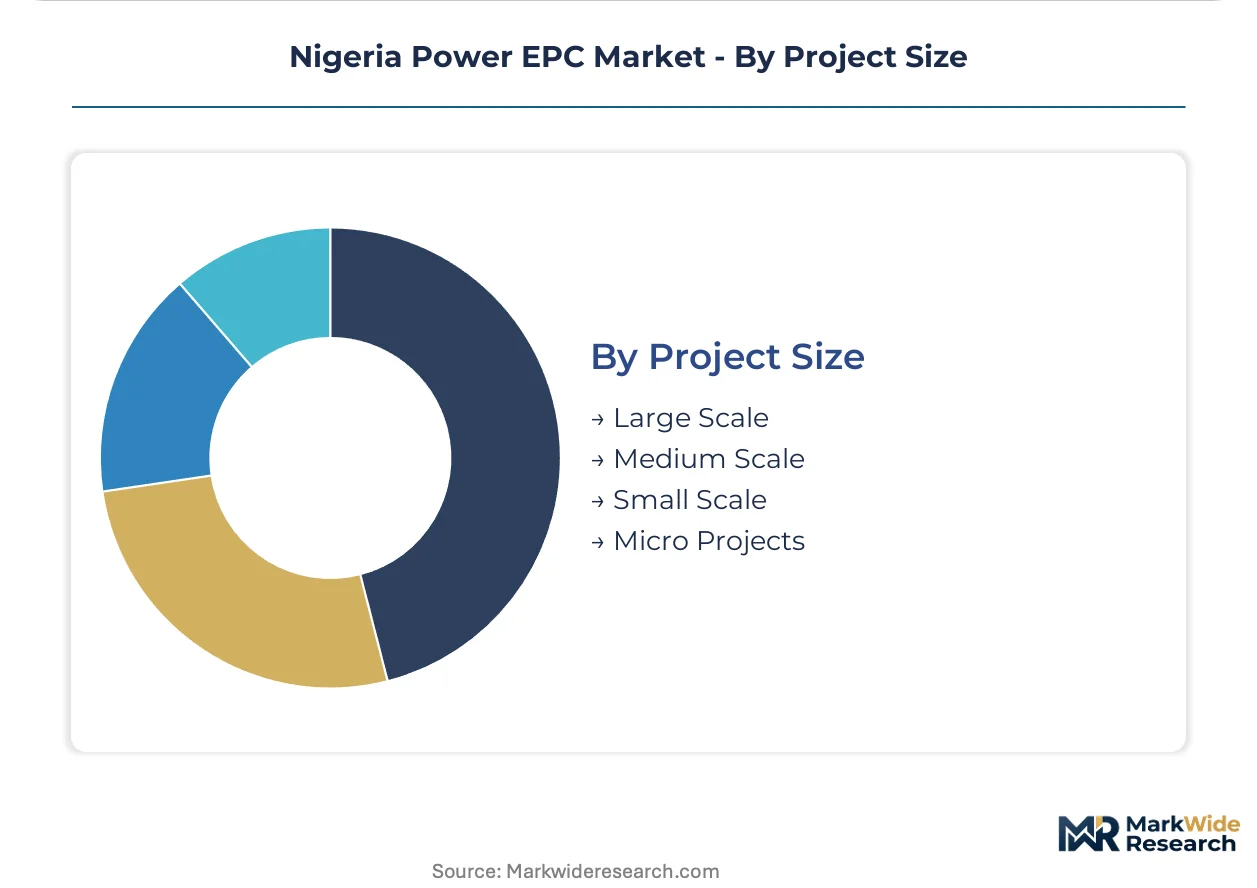
Project Size:
Contractor capability requirements and financing structures diverge sharply across scale tiers, with foreign exchange exposure concentrated in large-scale equipment imports.
- Large Scale:100+ MW thermal and hydro installations require integrated engineering-procurement-construction consortia. Gas supply intermittency from Niger Delta pipeline vandalism undermines commissioning schedules.
- Medium Scale:10-100 MW captive power systems serve manufacturing relocation from congested Lagos ports.
- Small Scale:Mini-grid deployments under NERC standardized tariffs compress project development timelines through pre-approved technical specifications.
- Micro Projects:Single-facility solar installations for rural health centers and schools operate outside centralized procurement frameworks.
Capital deployment concentrates in Large Scale. Steepest expansion trajectory is visible in Small Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos anchors Nigeria Power EPC activity through its congested port infrastructure and manufacturing relocation pressures. The Niger Delta industrial corridor concentrates cement and steel captive power investments. Federal electrification mandates channel development finance toward northern agricultural processing clusters.
Lagos and Southwest Corridor
Cement producers at Ewekoro and Ibese complexes drive captive power demand as grid instability forces diesel displacement. Nigerian Electricity Regulatory Commission eligible customer regulations enable direct bilateral contracts bypassing distribution utilities. The Lagos-Ibadan expressway industrial zone concentrates embedded generation infrastructure for manufacturing relocation from congested Apapa ports.
Niger Delta Region
Pipeline vandalism in Bayelsa and Rivers states undermines thermal plant commissioning schedules for gas-fired installations. Bureau of Public Procurement domestic content thresholds force joint venture structures that fragment large-scale hydro accountability. Obajana cement complex exemplifies industrial offtakers compressing supplier selection cycles to six-month direct negotiations.
Northwest Agricultural Belt
Sokoto and Kebbi states channel Rural Electrification Agency mandates toward off-grid solar-hybrid mini-grids for unserved settlements. Agricultural residue feedstock availability enables biomass-to-power combined heat and power systems for food processing clusters. Central Bank of Nigeria intervention facility disbursement delays constrain equipment import flows for turbine-generator sets.
North Central Industrial Zone
Kano and Ogun state industrial estates deploy containerized solar-plus-storage systems to isolate from grid instability. Nigerian Electricity Regulatory Commission mini-grid regulations compress project development timelines through pre-approved technical specifications. Manufacturing densification around Otta and Agbara corridors creates concentrated demand for modular generation infrastructure.
Southeast Urban Centers
Enugu and Aba commercial clusters seek operational certainty through twenty-year maintenance contract extensions beyond standard defect liability periods. Legacy grid synchronization barriers constrain distributed generation asset integration with aging transmission infrastructure. Federal funding pipelines for Mambilla plateau hydro development remain stalled by foreign exchange illiquidity.
Nigeria Power EPC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization depth and federal project access. Sinohydro leverages dam construction heritage to dominate large-scale hydro installations with integrated engineering-procurement-construction consortia. Sterling and Wilson Nigeria Limited anchors end-to-end solar EPC capabilities spanning engineering to commissioning. Three strategic archetypes define positioning: heritage hydro contractors, solar specialists with storage integration, and biomass-captive power industrial cluster specialists. Dominant competitive moves include joint venture formation to satisfy Bureau of Public Procurement local participation rules and maintenance contract duration extension to capture recurring revenue pools.
Within the heritage hydro tier, Sinohydro exemplifies federal funding pipeline access through large-scale dam construction. Among solar-specialist operators, Sterling and Wilson Nigeria Limited occupies a position spanning distributed generation to utility-scale deployment. On the industrial captive power vector, Energo Nigeria Ltd. sits within the biomass and food processing cluster specialization. These three anchors represent the technology-driven segmentation reshaping contractor capability investments and margin profiles across the forecast window.
| Leading Market Players |
|---|
| Sinohydro |
| Sterling and Wilson Nigeria Limited |
| Energo Nigeria Ltd. |
| Siemens Energy Nigeria |
| JuNeng Nig Ltd. |
| Gentec EPC Ltd. |
| Alten Energías Renovables |
| Rensource Energy |
| Andritz AG |
| Others |
Supply & Pricing Matrix
Industrial offtakers compressing supplier selection cycles from eighteen-month feasibility studies to six-month direct negotiations force EPC contractors to absorb equipment import risks and compress working capital cycles, driving margin bifurcation between integrated solution providers and commodity construction firms.
Pricing Analysis
Outcome-based pricing anchored to plant availability and generation uptime separates premium EPC contractors from commodity competitors. Three-tier pricing structure across integrated EPC, construction-only, and maintenance-service levels reflects capability depth and federal project access. Cost compression in solar module imports intensifies competitive pressure on standardized installations, while captive power contracts for cement and steel producers command premium margins due to construction speed premiums.
Supply Chain Analysis
Freight costs from Chinese turbine-generator manufacturers and European SCADA specialists concentrate foreign exchange exposure in large-scale hydro and thermal projects. Equipment sourcing draws from China, Germany, and India for turbine components, electrical switchgear, and control systems respectively. Single-source vulnerability in 132-330 kV transformer manufacturing creates commissioning bottlenecks. Distribution runs through Lagos port infrastructure with inland haulage to Niger Delta and northern industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over long-term maintenance revenue and captive equipment supply determines sustainable margin capture.
For Market Incumbents: Acquire commissioning engineer teams and specialized substation energization capabilities to counter scarcity constraints that limit contractor scaling. Lock in twenty-year maintenance contract extensions with cement and steel producers at Obajana and Ewekoro complexes before bilateral PPA fragmentation accelerates. Form joint ventures with local fabrication shops to satisfy Bureau of Public Procurement domestic content thresholds without fragmenting project accountability.
For New Entrants and Emerging Players: The gap between premium integrated EPC pricing and economy-tier construction-only rates creates entry space for solar-plus-storage specialists targeting Kano and Ogun state industrial estates. Penetrate the biomass-to-power segment in northern agricultural processing clusters where feedstock availability exceeds incumbent capability deployment. Lead with containerized modular systems that compress engineering-to-commissioning cycles below incumbent timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with solar EPC specialists possessing storage integration capabilities given Rural Electrification Agency mandate acceleration and mini-grid regulatory compression. Long-term viability hinges on recurring maintenance revenue pools extending across twenty-year asset lifecycles rather than one-time construction margins. Watch Central Bank of Nigeria intervention facility disbursement velocity as the inflection signal for equipment import flow resumption and project pipeline unlocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Equipment Supply | Captive sourcing of turbine-generator components mitigates foreign exchange illiquidity exposure from CBN facility delays. |
| Long-term Service Agreement Extension | Twenty-year maintenance contracts with Niger Delta industrial users lock recurring revenue beyond standard defect liability periods. |
| Joint Venture Formation | Local partnership structures satisfy Bureau of Public Procurement domestic content rules while preserving technical accountability. |
| Solar-Plus-Storage Capability Buildout | Containerized system integration captures premium margins from Kano and Ogun state manufacturing densification. |
| Biomass Feedstock Supply Lock | Agricultural residue agreements in Sokoto and Kebbi states enable combined heat and power deployment ahead of incumbent entry. |
Research Methodology
Multi-period observation of NERC regulatory filings, REA project pipelines, and CBN intervention facility disbursement patterns anchored the trend analysis, supplemented by interviews with IPP project developers, EPC contractors, utility planning officers, and industrial procurement leads at cement and steel complexes. Secondary validation drew from FERC-style regulatory databases, federal electrification mandate tracking, customs equipment import records, and integrated energy project development registries. Bottom-up project pipeline aggregation and top-down macroeconomic scenario weighting provided triangulation.
Segment-weighting across service type, technology choice, end-user category, and project capacity tier shaped the analytical framework throughout the forecast period. CAGRs were derived from regression-based demand modeling incorporating industrial electrification rates, captive power investment cycles, and distributed generation adoption curves. Forecast inputs included gas supply intermittency scenarios for Niger Delta thermal projects and solar module cost compression trajectories.
Inputs from NERC licensing databases and REA project registries were available through the study window; gaps in real-time CBN foreign exchange disbursement data introduce uncertainty bands around equipment import timing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
AC Power Sources Market
Power Equipment
Process Air Heater Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
US Power EPC Market