
 Magnetic Bearing Market | 2026-2036
Magnetic Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Bearing Market Outlook
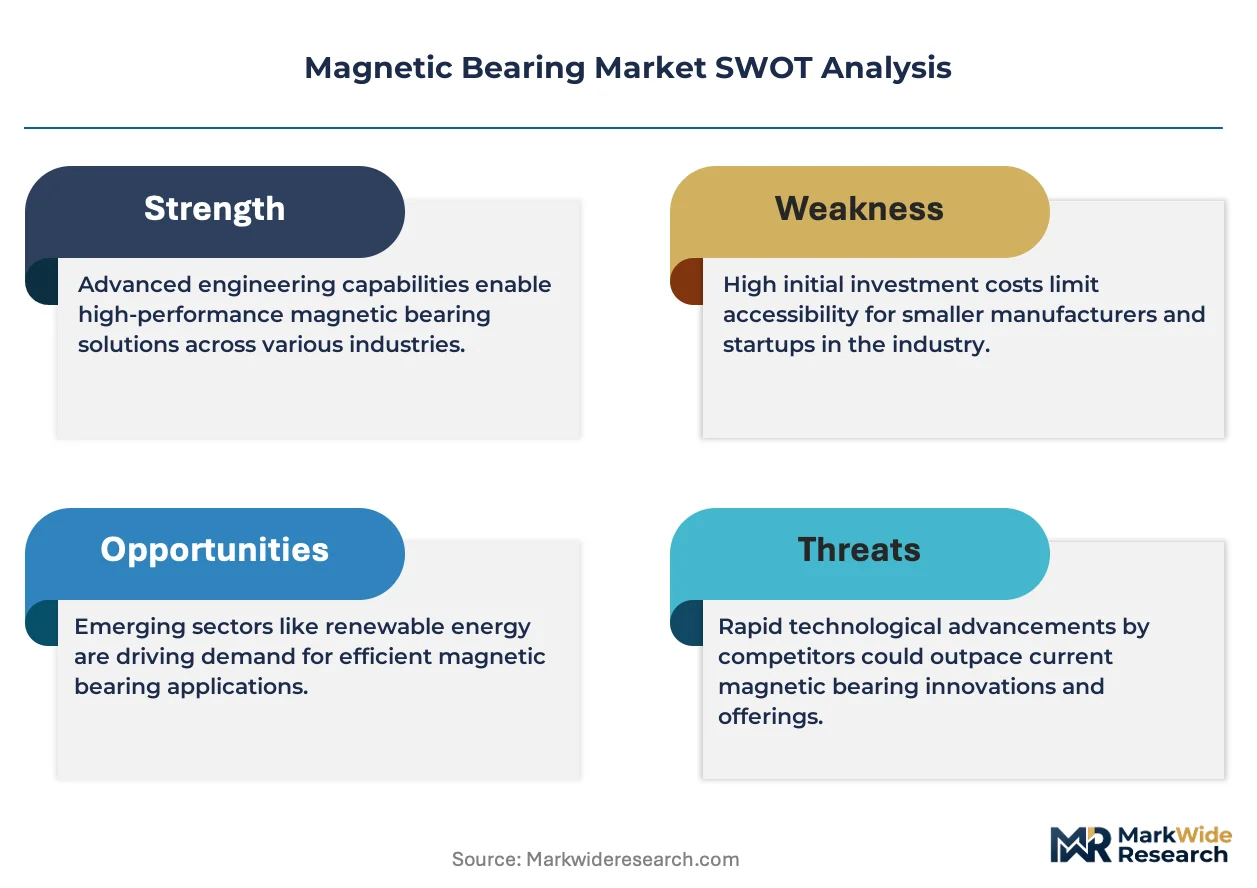
Permanent magnet alloys containing rare-earth elements are repositioning cost structures across active magnetic bearing assemblies. SKF leverages decades of rotating equipment expertise to anchor European aftermarket service networks. Calnetix specializes in high-speed motor-bearing integration for industrial gas compressors. Synchrony competes on defense-aerospace qualification depth that civilian vendors rarely match.
Magnetic bearings employ electromagnetic or permanent-magnet fields to levitate a rotor without mechanical contact, typically achieving rotational speeds above 50,000 RPM with positional tolerances under 10 micrometers. Their primary purpose is to eliminate friction, lubrication systems, and mechanical wear in high-performance rotating machinery. Active magnetic bearings dominate revenue due to their real-time controllability in turbo machinery applications, while hybrid configurations represent the fastest-expanding category as plant operators seek retrofit compatibility with existing auxiliary bearing infrastructure. Digital controller technology now sits at the margin center, with advanced algorithm subsets commanding premium pricing for vibration suppression in electric motor drives.
The EPA enforces methane leakage thresholds that effectively mandate contactless bearing seals in new compressor installations, while ISO 14839 vibration standards govern magnetic bearing commissioning protocols worldwide. Germany's KBA and Japan's METI both reference IEC 60034 performance benchmarks in domestic turbomachinery certification. Stakeholders must monitor rare-earth supply chain concentration in China against dual carbon policy export licensing, as magnet material access determines manufacturing cost trajectories more directly than any single engineering innovation.
Market Dynamics
Active magnetic bearing systems are displacing conventional oil-lubricated designs in subsea compression trains as methane emission controls tighten across North American and European offshore operations.
Growth Catalysts
- EPA Methane Rules:The EPA's tightened leakage thresholds for compressor seals are mandating contactless bearing installations in new US onshore and offshore facilities.
- Permanent Magnet Materials:Rare-earth alloy advances are reducing electromagnetic coil mass in active bearing assemblies while maintaining load capacity.
- Oil and Gas Specification:Major operators now write active magnetic bearings into subsea compression train procurement standards to eliminate lubricant contamination risks.
Market Restraints
- Rare-Earth Supply Concentration:Magnet material access depends on Chinese export licensing under dual carbon policy frameworks, creating input cost volatility.
- Controller Hardware Costs:Digital signal processors and power amplifiers account for disproportionate share of system bill-of-materials versus mechanical bearing alternatives.
- Retrofit Infrastructure Incompatibility:Existing auxiliary bearing housings and seismic mounting systems require complete replacement rather than component upgrade.
Strategic Opportunities
- Hybrid Configuration Adoption:Plant operators seeking partial retrofit compatibility are driving fastest-expanding product category combining electromagnetic levitation with mechanical backup bearings.
- Defense-Aerospace Qualification:Civilian industrial vendors can leverage military certification depth to access nuclear power generation and satellite momentum wheel applications.
- Aftermarket Service Networks:SKF's rotating equipment expertise anchors European maintenance infrastructure that third-party specialists can target for controller calibration and sensor replacement contracts.
Industry Challenges
- ISO 14839 Commissioning Complexity:Vibration standard compliance requires specialized technician training and extended site acceptance testing timelines.
- Digital Controller Integration:Advanced algorithm subsets for vibration suppression demand firmware customization that stretches project delivery schedules.
- Legacy Turbomachinery Retrofit:Existing compressor trains require rotor redesign to accommodate magnetic bearing load paths and position sensor mounting geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Bearing Market |
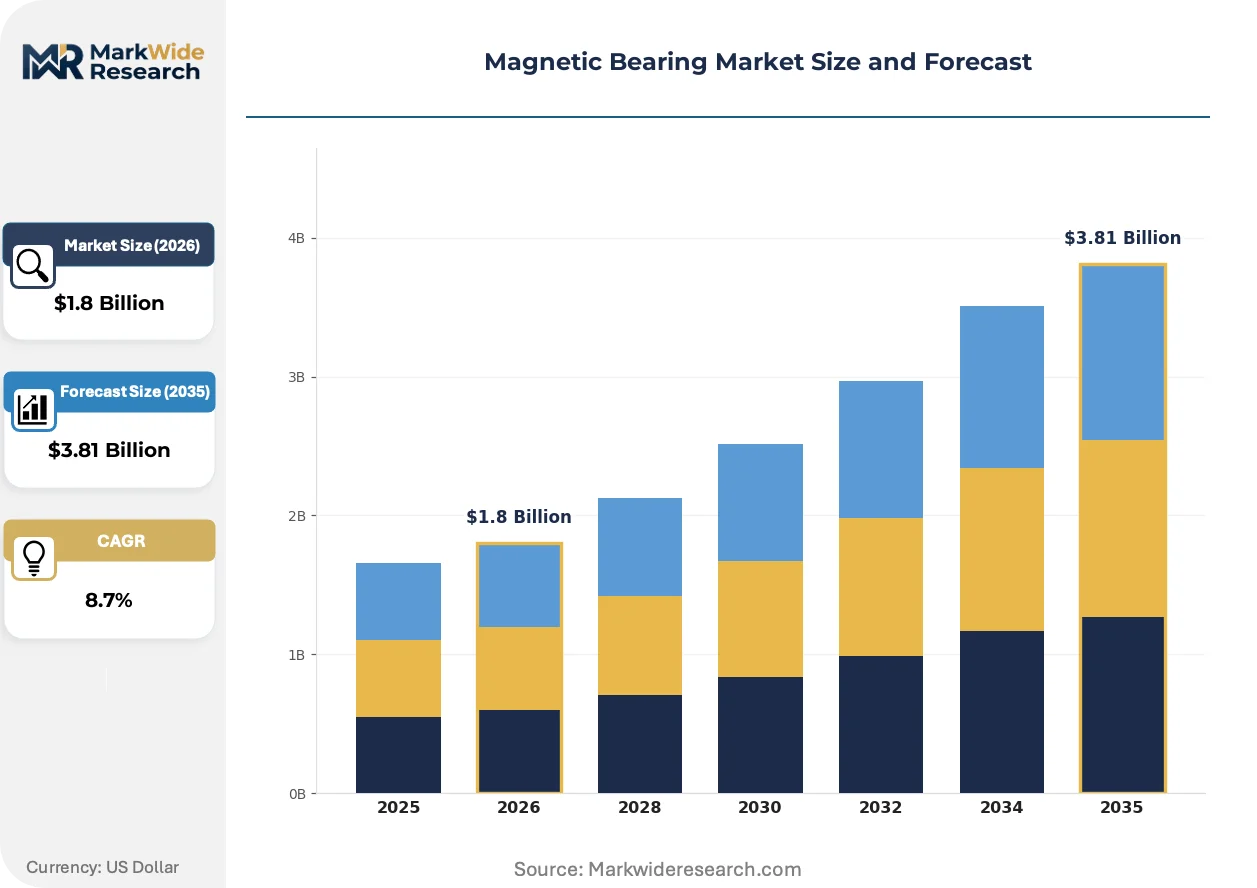
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Magnetic Bearings, Passive Magnetic Bearings, Hybrid Magnetic Bearings, Electromagnetic Bearings End User: Aerospace, Oil & Gas, Power Generation, Industrial Machinery Application: Turbo Machinery, Electric Motors, Compressors, Generators Technology: Contactless, Self-Sensing, Digital Controllers, Advanced Algorithms |
| Companies Covered | MECOS, Levitronix, SKF, Zeitlos, Synchrony, Schaeffler, Calnetix, LTi, Waukesha Bearings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Bearing Market Strategic Shifts
Digital controller technology sits at the margin center of magnetic bearing value creation, with algorithmic vibration suppression commanding premium positioning in high-speed motor drive applications.
Permanent magnet alloys containing rare-earth elements are converging with high-speed motor-bearing integration architectures. Industrial gas compressor OEMs are adopting these integrated assemblies to eliminate separate bearing housings. The structural consequence is compressing supplier tiers as motor and bearing functions consolidate under single-source procurement.
REACH substance restrictions and EU F-Gas Regulation are phasing out conventional lubricants in hermetic compressor designs. Magnetic bearing systems eliminate seal oil entirely, satisfying environmental compliance without alternative fluid research. German turbomachinery certification through KBA references IEC 60034 benchmarks that magnetic bearing suppliers must document for grid-connected equipment approval.
Service contract unbundling is fragmenting traditional OEM aftermarket relationships. End-users are separating controller calibration, sensor replacement, and power amplifier maintenance across specialized third-party providers. This pattern concentrates in German industrial clusters where Siemens Energy and MAN Energy Solutions anchor dense service technician networks.
Magnetic Bearing Market Segmentation
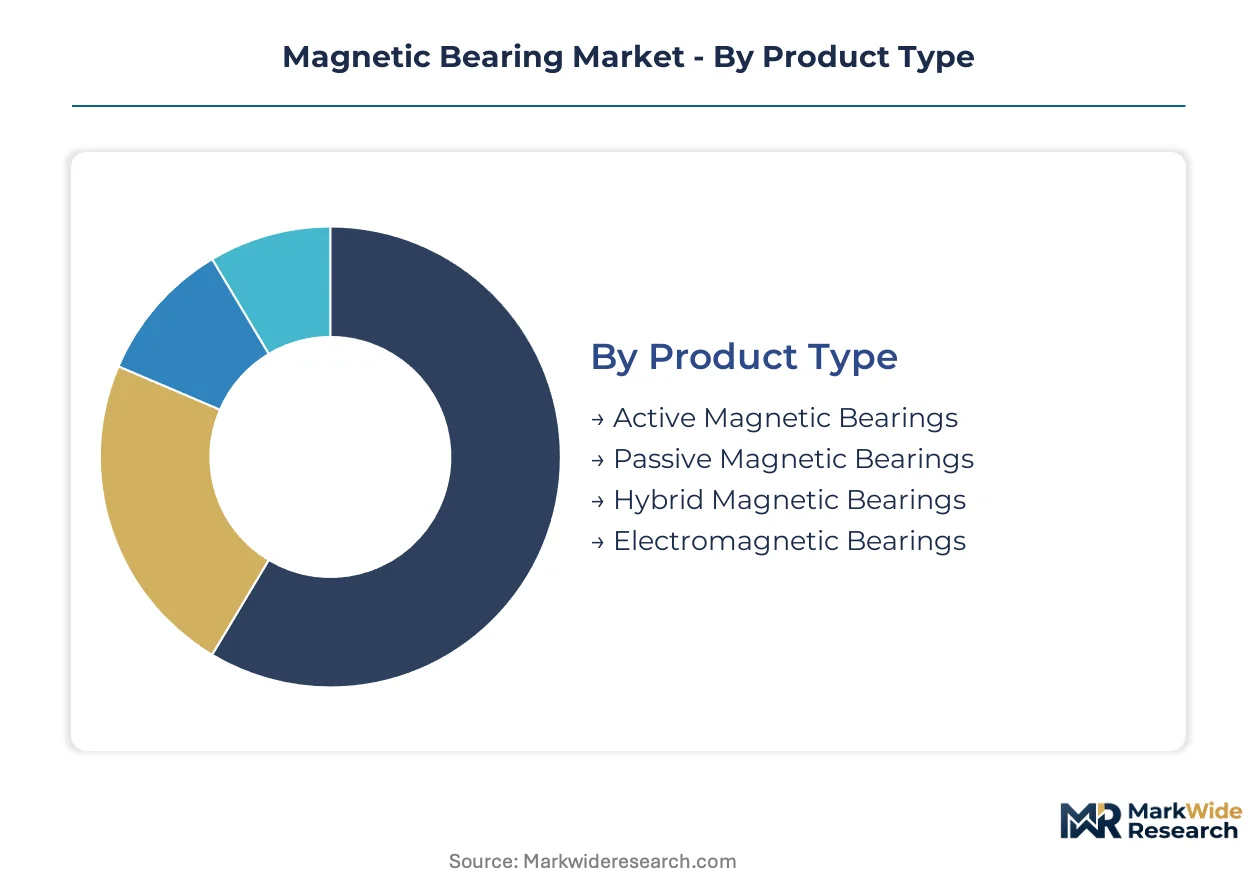
Magnetic bearing procurement splits sharply between premium active systems for new turbomachinery and cost-optimized hybrid configurations for retrofit installations. Understanding these segment boundaries clarifies where controller technology versus magnet materials drive purchasing decisions.
Product Type:
Active magnetic bearings command premium positioning through real-time controllability, while hybrid designs bridge cost tiers for operators retaining mechanical backup infrastructure.
- Active Magnetic Bearings:Electromagnetic coil arrays with position sensors enable real-time rotor levitation adjustments above 50,000 RPM. Demand concentrates in Siemens Energy and MAN Energy Solutions turbomachinery supply chains across Germany, driven by EPA methane rules mandating contactless seals in new compressor trains.
- Hybrid Magnetic Bearings:Combines electromagnetic levitation with mechanical auxiliary bearings for partial retrofit compatibility. Plant operators in North American offshore operations specify these to phase capital expenditure while meeting tightening emission thresholds.
- Passive Magnetic Bearings:Permanent-magnet arrays provide levitation without external power, suited for satellite momentum wheels where controller mass is prohibitive.
- Electromagnetic Bearings:Simplified coil-based designs without position feedback loops serve lower-speed industrial applications where tolerances exceed 50 micrometers.
Mature deployment sits with active magnetic bearings in grid-connected turbomachinery. Newer deployment is concentrated in hybrid configurations for subsea compression retrofits.
End User:
Application maturity varies by sector certification depth and maintenance infrastructure density.
- Oil & Gas:Subsea compression trains and onshore processing facilities specify active magnetic bearings to eliminate lubricant contamination risks. Major operators now write these into procurement standards for methane emission compliance under EPA and EU F-Gas Regulation frameworks.
- Power Generation:Nuclear turbine retrofits and grid-connected gas turbines demand ISO 14839 vibration compliance with extended commissioning timelines. German KBA certification through IEC 60034 benchmarks anchors European procurement.
- Aerospace:Defense qualification depth from Synchrony and civilian vendors enables satellite momentum wheel and aircraft engine applications where mechanical bearing failure modes are unacceptable.
- Industrial Machinery:High-speed spindles and precision manufacturing equipment adopt self-sensing magnetic bearings to reduce maintenance intervals in continuous production environments.
Established demand centers on oil and gas compression infrastructure. Expanding deployment is accelerating in power generation turbine retrofits.
Application:
Rotational speed requirements and vibration tolerance specifications determine technology selection across machinery categories.
- Turbo Machinery:Centrifugal and axial compressors in subsea environments require active magnetic bearing systems with positional tolerances under 10 micrometers. REACH substance restrictions and lubricant phase-outs position these as the default for hermetic designs.
- Electric Motors:High-speed motor-bearing integration architectures from Calnetix and SKF consolidate supplier tiers by eliminating separate bearing housings in industrial gas compressor OEM specifications.
- Compressors:Refrigeration and process gas compression applications adopt hybrid configurations to balance emission compliance with existing auxiliary bearing infrastructure.
- Generators:Grid-connected equipment requires KBA and METI certification referencing IEC 60034 performance benchmarks for magnetic bearing commissioning protocols.
Volume concentration rests with turbo machinery in offshore oil and gas. Technology migration is advancing fastest in electric motor integration architectures.
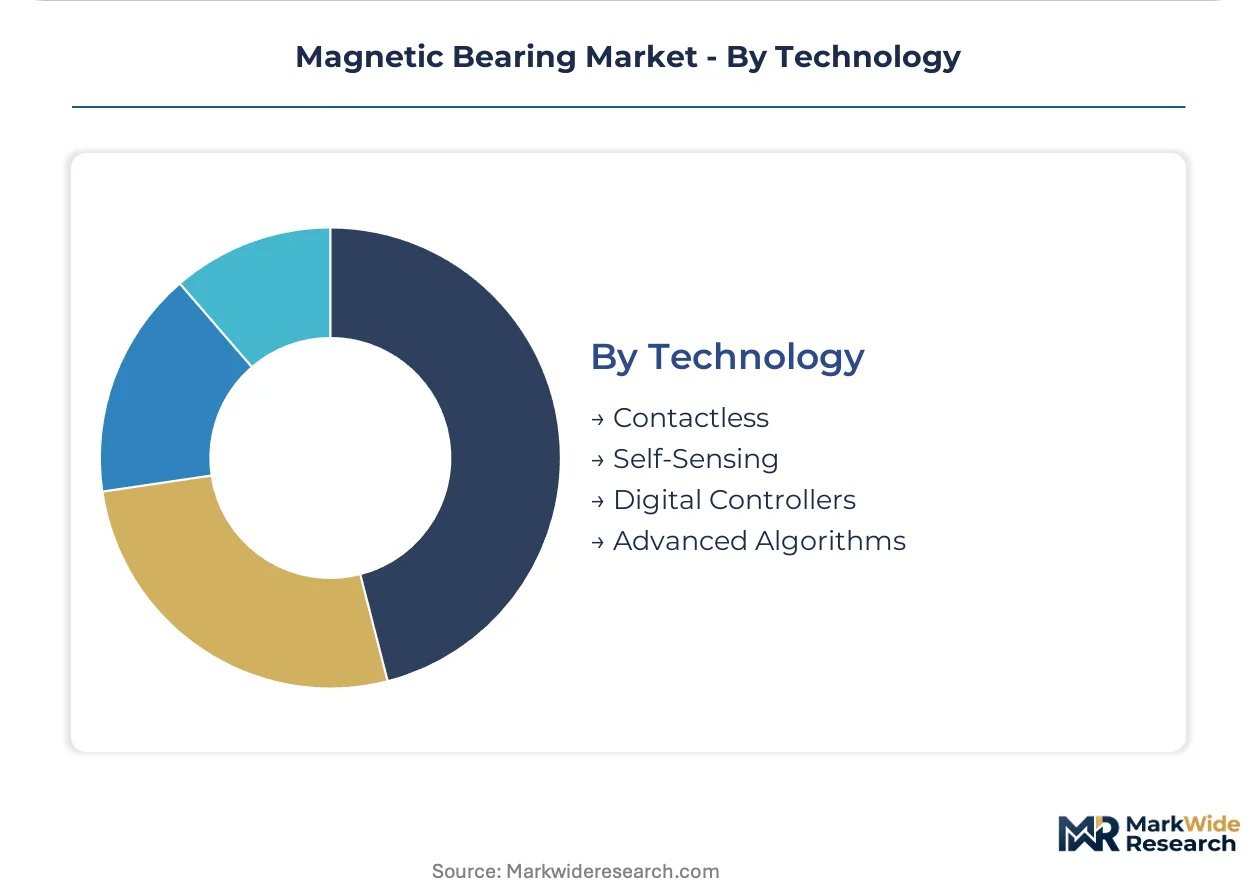
Technology:
Digital capability layers separate premium system pricing from commodity electromagnetic alternatives.
- Digital Controllers:Signal processors and power amplifiers with firmware customization for vibration suppression command premium positioning. Extended project delivery schedules result from algorithm subset tailoring for specific rotor dynamics.
- Advanced Algorithms:Model predictive control and adaptive filtering enable real-time disturbance rejection in high-speed motor drives. These differentiate SKF and Calnetix offerings in European aftermarket service networks.
- Self-Sensing:Eliminates discrete position sensors by extracting rotor position from coil current measurements, reducing component count in cost-sensitive industrial machinery.
- Contactless:Fundamental levitation principle underlying all magnetic bearing categories, with seal oil elimination satisfying environmental compliance without alternative fluid research.
Proven deployment resides with contactless levitation fundamentals. Capability investment is concentrating in advanced algorithm development for vibration suppression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for magnetic bearings concentrates most visibly in Germany, where Siemens Energy and MAN Energy Solutions anchor turbomachinery supply chains. The EPA's tightened methane emission rules in the United States are accelerating retrofits of conventional bearing systems. Oil and gas operators across multiple geographies now specify active magnetic bearings for subsea compression trains.
United States
Offshore oil and gas operators drive specification of active magnetic bearings for subsea compression trains. The EPA enforces methane leakage thresholds that mandate contactless bearing seals in new compressor installations. Houston anchors the densest concentration of turbomachinery procurement teams writing these standards into contracts.
Germany
Siemens Energy and MAN Energy Solutions anchor European turbomachinery supply chains with integrated magnetic bearing procurement. The KBA references IEC 60034 performance benchmarks in domestic certification protocols for grid-connected equipment. Industrial clusters around Munich and Berlin host dense service technician networks for controller calibration and sensor replacement.
China
Rare-earth magnet material processing determines manufacturing cost trajectories for magnetic bearing assemblies. Export licensing under dual carbon policy frameworks creates input cost volatility for international suppliers. Manufacturing concentration in the Yangtze River Delta shapes global supply availability for permanent magnet alloys.
Japan
METI references IEC 60034 benchmarks in domestic turbomachinery certification, aligning with German and US standards. Precision manufacturing equipment suppliers adopt self-sensing magnetic bearings for continuous production environments. The Nagoya industrial corridor concentrates high-speed spindle applications requiring positional tolerances under 10 micrometers.
United Kingdom
North Sea offshore operators specify active magnetic bearings to eliminate lubricant contamination risks in subsea environments. REACH substance restrictions and EU F-Gas Regulation phase out conventional lubricants in hermetic compressor designs. Aberdeen hosts procurement teams integrating these environmental compliance requirements into compression train specifications.
Magnetic Bearing Market Competitive Environment
Technology licensing dominates the current landscape as specialist controller developers partner with established rotating equipment manufacturers. The vendor base organizes around three strategic archetypes: integrated turbomachinery OEMs, dedicated magnetic bearing specialists, and aftermarket service network operators. Consolidation pressures favor partnerships over acquisitions due to the specialized firmware and algorithm expertise required. Geographic expansion and portfolio diversification represent the two dominant competitive moves as suppliers seek to anchor regional service infrastructure.
Within the specialist tier, MECOS, SKF, and Calnetix occupy positions that exemplify different competitive approaches. MECOS represents the dedicated magnetic bearing pure-play archetype with focused electromagnetic levitation expertise. SKF anchors the aftermarket service network model, leveraging decades of rotating equipment presence to capture controller calibration and sensor replacement contracts. Calnetix exemplifies the high-speed motor-bearing integration specialist, consolidating supplier tiers by eliminating separate bearing housings in OEM specifications.
| Leading Market Players |
|---|
| MECOS |
| Levitronix |
| SKF |
| Zeitlos |
| Synchrony |
| Schaeffler |
| Calnetix |
| LTi |
| Waukesha Bearings |
| Others |
Value Chain & Pricing Dynamics
Neodymium oxide price indices cascade through magnetic bearing supply chains, compressing margins for active system manufacturers while amplifying cost advantages for hybrid configurations that minimize rare-earth magnet mass. Chinese export licensing under dual carbon policy frameworks introduces volatility that propagates into three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Volume concentrates in mid-tier hybrid configurations while margins pool in premium active systems with advanced algorithm customization. Price differentiation stems from ISO 14839 certification grade and firmware customization depth for vibration suppression. Pricing pressure stems from rare-earth input cost volatility as Chinese export quotas tighten. Oil and gas procurement teams show lowest price sensitivity given methane compliance mandates, while industrial machinery buyers prioritize cost-optimized self-sensing alternatives.
Supply Chain Analysis
Domestic content mandates in German KBA certification protocols and US EPA procurement guidelines are reshaping sourcing patterns toward regional magnet processing capabilities. Manufacturing gravity centers on China for rare-earth alloy refining, Germany for precision controller assembly, and Japan for high-speed motor integration. Supply chains draw from neodymium-iron-boron magnets, silicon steel laminations, and digital signal processors. Single-source vulnerability concentrates in Chinese rare-earth oxide separation capacity. Distribution runs through turbomachinery OEM direct channels and specialized aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active magnetic bearing systems are displacing oil-lubricated designs across subsea compression infrastructure, with digital controller algorithms replacing mechanical seal maintenance as the core value driver.
For Market Incumbents: Hedge against rare-earth supply disruption by anchoring captive magnet processing partnerships in Australia or Vietnam. Deepen firmware customization capabilities to defend margin position against controller hardware commoditization. Lock in long-term service contracts with Siemens Energy and MAN Energy Solutions procurement teams before third-party specialists fragment aftermarket relationships. For New Entrants and Emerging Players: Self-sensing magnetic bearing architectures offer the most penetrable wedge for industrial machinery applications where positional tolerances exceed 50 micrometers. Target precision manufacturing equipment suppliers in Japan's Nagoya corridor seeking reduced maintenance intervals. Pursue technology licensing partnerships with established motor OEMs rather than direct turbomachinery competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor aftermarket service network operators in Germany's Munich-Berlin industrial cluster amid controller calibration unbundling trends. Five-to-ten-year viability hinges on algorithmic differentiation moats rather than hardware manufacturing scale. Monitor Chinese dual carbon policy export license issuance volumes as the critical inflection signal for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Processing | Captive neodymium supply secures cost predictability against Chinese export licensing volatility. |
| Advanced Algorithm Development Partnership | Model predictive control differentiation commands premium positioning in SKF and Calnetix service networks. |
| Hybrid Configuration Portfolio Expansion | Retrofit compatibility captures North American offshore operators phasing capital expenditure. |
| Defense-Aerospace Qualification Investment | Military certification depth from Synchrony unlocks nuclear turbine and satellite momentum wheel applications. |
| Aftermarket Service Network Unbundling | Third-party controller calibration contracts fragment traditional OEM relationships in German industrial clusters. |
Study Parameters
Trade publications, customs filings, and IEC certification databases formed the secondary backbone, supplemented by primary interviews with turbomachinery procurement directors, plant maintenance engineers, magnetic bearing R&D leads, and aftermarket service technicians. Bottom-up unit deployment estimates triangulated against top-down OEM revenue disclosures to anchor market sizing.
Historical trendline analysis across active, hybrid, and passive bearing categories informed growth trajectory modeling over the projection horizon. Segmentation dimensions included product architecture, end-use sector certification depth, rotational speed tier, and regional regulatory framework. CAGRs derived from interpolating technology substitution curves against methane emission compliance deadlines and rare-earth supply elasticity assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to EPA methane thresholds and abrupt Chinese export license suspensions under dual carbon enforcement. Forecasts reflect documented assumptions about technology adoption pacing and supply chain reshoring timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Chad Power EPC Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
Power Analyzers Market
Power Equipment
Power Cables Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Induction Heating System Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Wind Turbine Bolts Market