
 High Voltage Motor Sleeve Bearing Market | 2026-2036
High Voltage Motor Sleeve Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Motor Sleeve Bearing Market Analytics
Aftermarket service revenue is rewriting margin capture across the High Voltage Motor Sleeve Bearing landscape. RENK AG leverages its captive repair network across European power corridors to lock in long-term service contracts. Shenke Sliding Bearing Group anchors its position through backward integration into babbitt casting and precision machining operations. Schaeffler Group competes on sensor-integrated bearing systems that extend predictive maintenance intervals for utility customers.
High voltage motor sleeve bearings are cylindrical journal bearings, typically lined with tin-based or lead-based babbitt alloy, designed to support rotor shafts in motors operating above 6.6 kV by maintaining a hydrodynamic oil film under radial loads. Their primary purpose is to ensure vibration dampening, shaft alignment tolerance, and thermal stability in continuous-duty industrial rotating equipment. Sleeve bearings within the Product Type category retain the dominant installed base in thermal power plants due to superior load capacity and self-aligning properties versus antifriction alternatives. The Power Generation vertical channels the majority of specification-driven demand, while Maintenance Providers among End Users represent the fastest-growing procurement segment as asset life extension programs displace greenfield capital expenditure.
ISO 7919 and API 684 establish vibration and bearing housing specifications that OEMs and utilities must satisfy for turbine-generator commissioning in most regulated jurisdictions. China's GB standards and NMPA-equivalent machinery safety frameworks enforce localized testing protocols for imported sleeve bearing assemblies. Germany's KBA and TÜV-affiliated inspection bodies influence European acceptance criteria for critical rotating equipment. Stakeholders must monitor how carbon-border adjustment mechanisms and embodied-carbon tracking reshape supplier qualification thresholds for babbitt sourcing and foundry energy intensity.
Market Dynamics
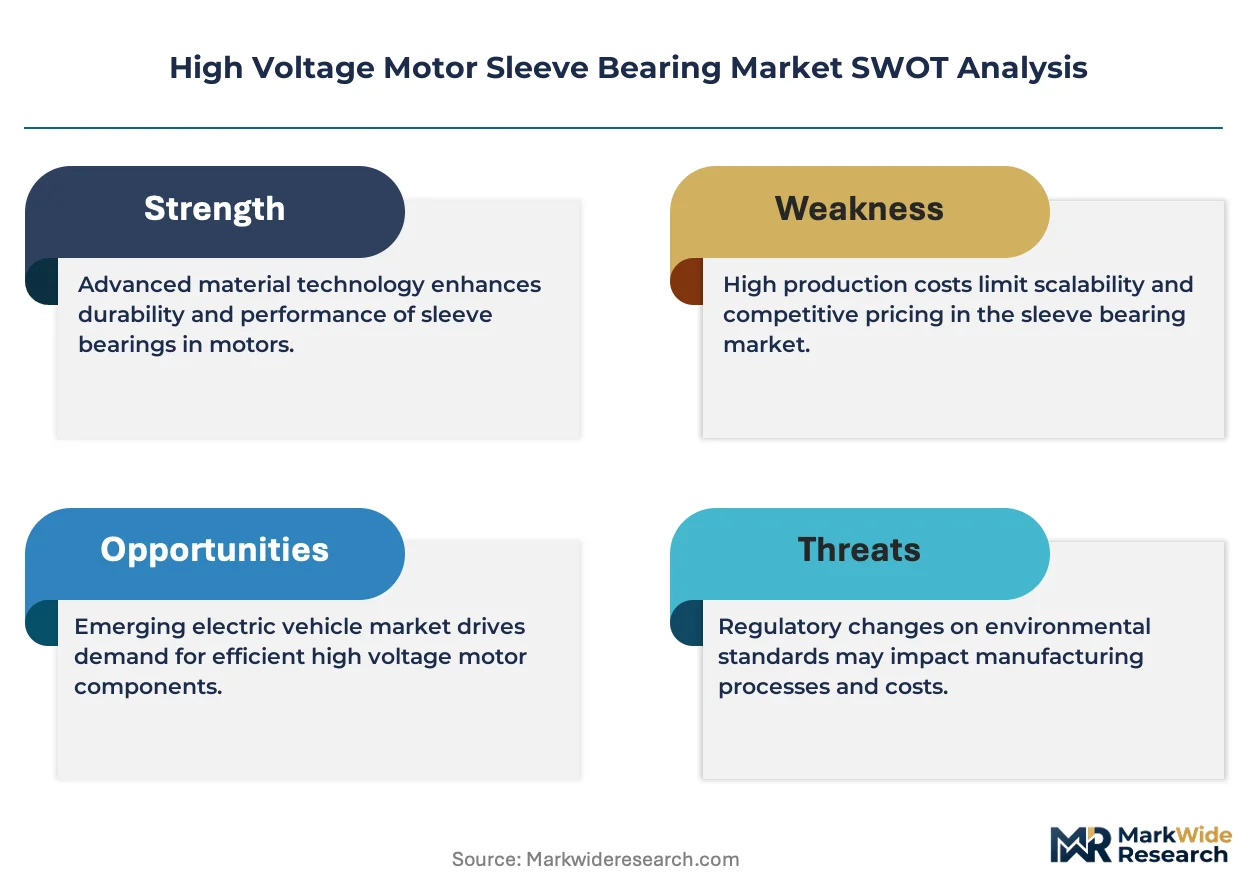
Power generation utilities are compressing replacement cycles for turbine-generator sleeve bearings as grid reliability mandates tighten across regulated jurisdictions. This structural pressure is reshaping procurement specifications toward ISO precision standards and sensor-integrated monitoring systems.
Growth Catalysts
- ISO 7919 vibration mandates:Commissioning protocols for critical rotating equipment now require continuous shaft vibration monitoring, forcing utilities to upgrade legacy bearing installations with instrumented assemblies that support predictive maintenance workflows.
- China's state-backed modernization:Central government-directed power plant retrofits are accelerating replacement demand for babbitt-lined sleeve bearings in thermal generation fleets across provincial grid operators.
- Babbitt alloy innovations:Tin-based and lead-free formulations with enhanced fatigue resistance are extending bearing service intervals, reducing lifecycle costs for continuous-duty industrial motors.
Market Restraints
- Specialized foundry concentration:Precision babbitt casting capacity clusters with a limited supplier base in Germany and Japan, creating supply vulnerability for OEMs requiring ISO-certified bearing liners.
- Antifriction bearing substitution:Rolling-element alternatives are capturing applications below 10 MW where maintenance access permits more frequent replacement cycles.
- REACH substance restrictions:European chemical regulations are complicating lead-based babbitt formulations, forcing reformulation investments that compress margins for legacy product lines.
Strategic Opportunities
- India's thermal expansion:National power capacity additions under CEA planning frameworks are creating specification windows for imported sleeve bearing assemblies in new turbine-generator installations.
- Sensor-telemetry convergence:Integration of vibration sensors with edge computing platforms is enabling condition-based service contracts that capture recurring revenue streams from utility asset managers.
- Aftermarket service unbundling:Independent maintenance providers are building captive repair capabilities that bypass OEM service networks, creating channel fragmentation for bearing refurbishment.
Industry Challenges
- Precision machining skill scarcity:ISO tolerance grinding for hydrodynamic bearing surfaces requires specialized technician training that outpaces vocational pipeline output in mature industrial economies.
- Legacy system integration:Retrofitting instrumented bearings into existing turbine-generator housings demands custom engineering that extends project timelines and inflates commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Motor Sleeve Bearing Market |
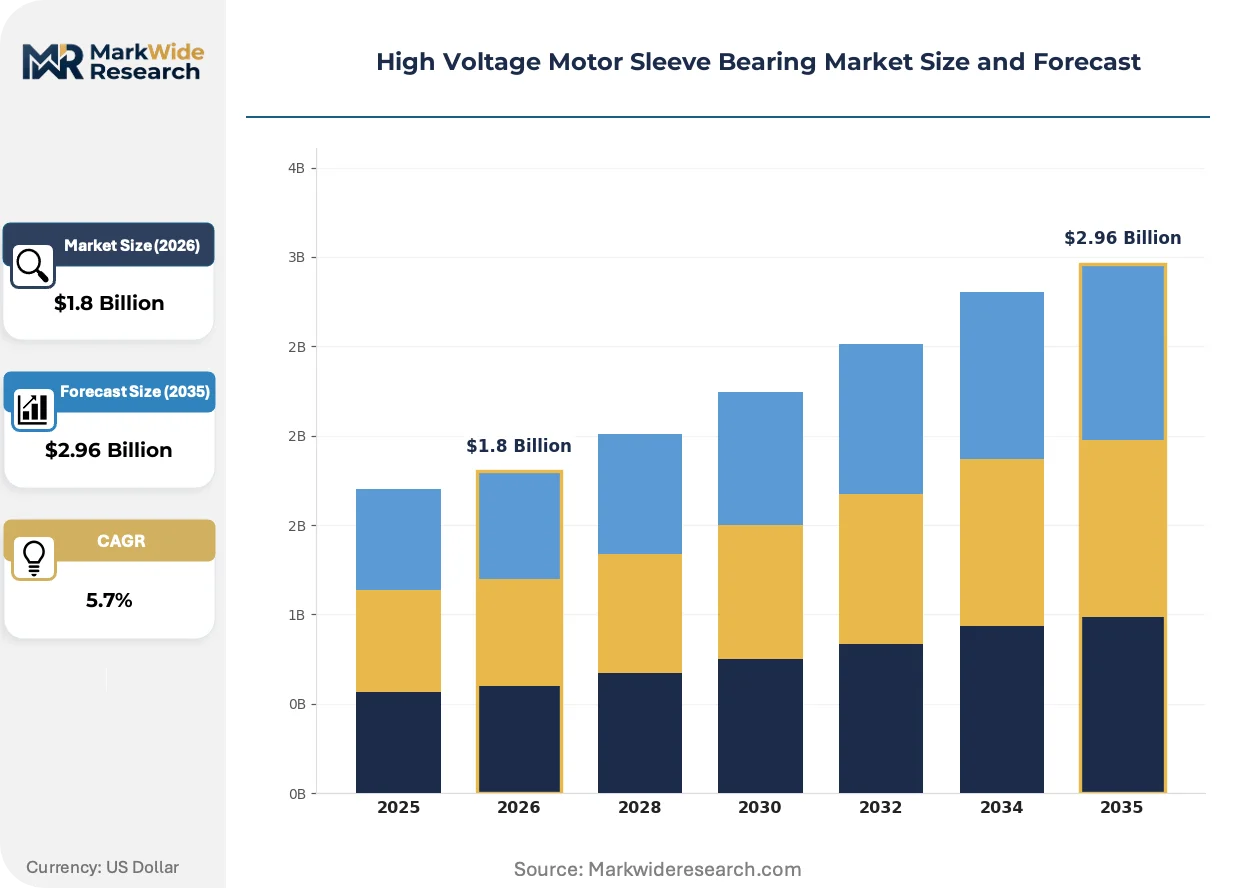
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Sleeve Bearings, Fluid Bearings Industry Vertical: Marine, Aerospace, Power Generation, Mining End User: Manufacturers, OEMs, Maintenance Providers, Utilities Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | RENK AG, Shenke Sliding Bearing Group, Hunan SUND Industrial & Technological Co., Ltd, AB SKF, Schaeffler Group, The Timken Company, NTN Corporation, Miba AG, ZHEJIANG BHS JOURNAL BEARING CO.,LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Motor Sleeve Bearing Market Evolving Landscape
Digital condition monitoring and material science advances are restructuring how sleeve bearing value is captured across the power generation supply chain. These shifts are compressing traditional maintenance intervals while elevating specification complexity.
Embedded fiber-optic temperature and vibration sensors within bearing liners are enabling real-time oil film monitoring. Utilities operating combined-cycle plants are adopting these instrumented assemblies fastest, prioritizing unplanned outage prevention over upfront hardware premiums. Continuous telemetry is rendering obsolete scheduled disassembly inspections that previously drove planned maintenance calendars.
China's GB standards and NMPA-equivalent machinery safety frameworks are mandating localized testing protocols for imported sleeve bearing assemblies. These requirements are fragmenting supplier qualification pathways, forcing foreign manufacturers to establish domestic calibration partnerships. European OEMs serving Chinese power projects are restructuring certification workflows to accommodate parallel testing regimes.
Asset life extension programs are displacing greenfield capital expenditure across OECD power markets. Utility procurement teams are unbundling bearing supply from installation and commissioning services, awarding maintenance contracts to specialized providers with captive repair infrastructure. This behavior is most pronounced in Germany and Japan where nuclear phase-out policies are accelerating thermal fleet sweating.
High Voltage Motor Sleeve Bearing Market Segmentation
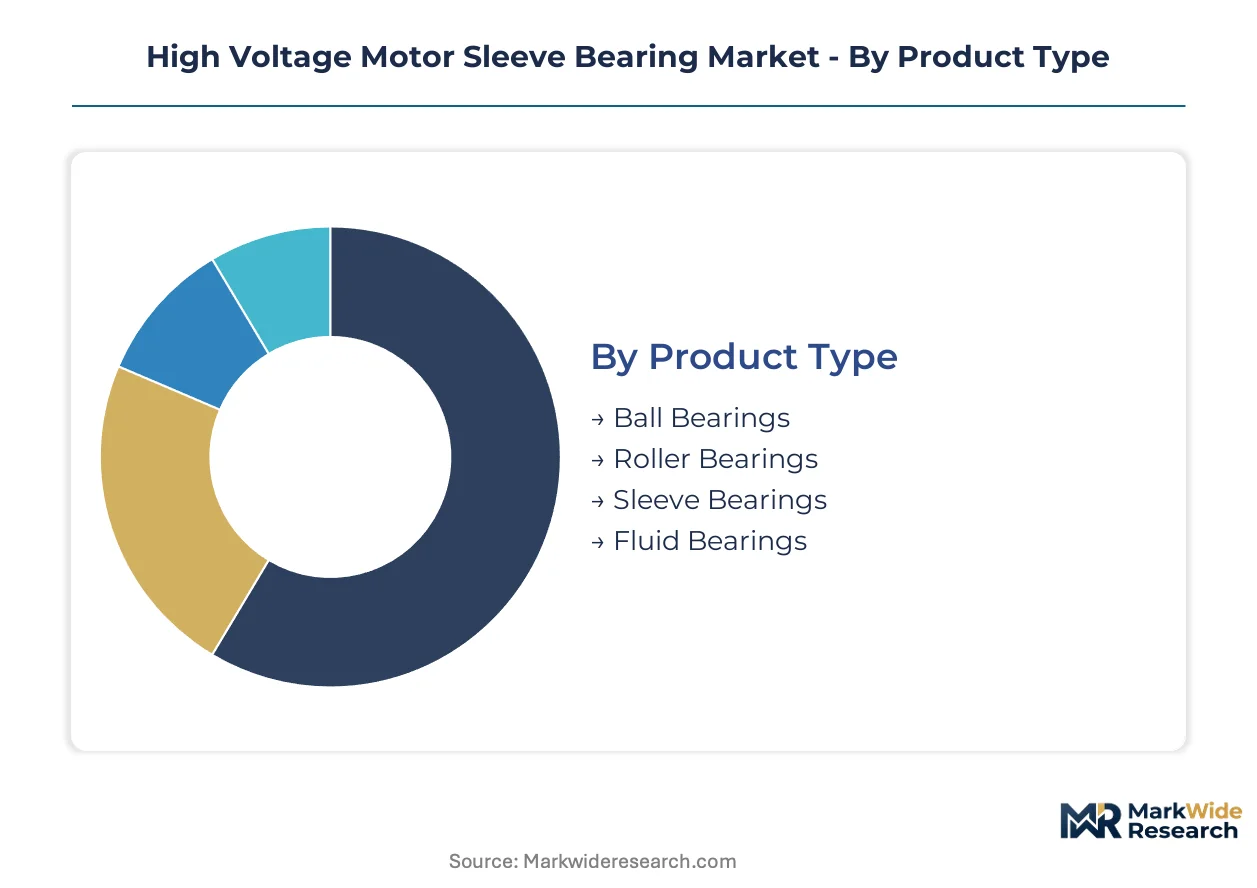
Segmentation in the High Voltage Motor Sleeve Bearing Market reveals how procurement specifications diverge across duty cycles, regulatory environments, and asset ownership models. Understanding these splits exposes where margin concentrates and which technology platforms are gaining specification share.
Product Type:
Mature hydrodynamic designs dominate heavy-duty continuous operation, while emerging alternatives challenge in intermittent or space-constrained applications.
- Sleeve Bearings:Babbitt-lined cylindrical journal bearings maintain hydrodynamic oil films under radial loads above 6.6 kV. Power generation utilities in China specify these for turbine-generator sets where grid reliability mandates demand vibration dampening and thermal stability across decades of continuous duty.
- Fluid Bearings:Externally pressurized oil or gas film designs eliminate metal-to-metal contact for ultra-precision applications. Aerospace test rigs and specialized marine propulsion systems in Germany specify these where sub-micron shaft positioning tolerance overrides cost considerations.
- Ball Bearings:Rolling-element designs capture maintenance-accessible applications below 10 MW where replacement cycle frequency permits antifriction substitution.
- Roller Bearings:Cylindrical and tapered variants serve intermittent-duty industrial motors where load capacity requirements fall below sleeve bearing economic thresholds.
Sleeve bearings handle the majority of throughput; fluid bearings are gaining share fastest in precision-critical niches.
Industry Vertical:
Cost tier separation runs from capital-intensive greenfield projects to sweating legacy assets with compressed maintenance budgets.
- Power Generation:Thermal and combined-cycle plants drive specification-driven procurement for ISO 7919-compliant bearing assemblies. State-backed modernization programs across Chinese provincial grid operators are accelerating replacement cycles for babbitt-lined components in turbine-generator sets.
- Mining:Harsh-environment operations demand sealed bearing housings with extended lubrication intervals. Australian iron ore operations and Chilean copper concentrators specify heavy-duty sleeve bearings for mill drives where contamination resistance overrides precision requirements.
- Marine:Classification society rules from Lloyd's Register and DNV govern bearing specifications for propulsion shafts and auxiliary generators. Slow-speed two-stroke engines retain sleeve bearing dominance while medium-speed four-stroke alternatives permit rolling-element substitution.
- Aerospace:Airframe and engine test facilities require instrumented bearing systems with real-time telemetry for rotating component validation. Defense procurement in the US and France sustains limited-volume demand for specialized fluid bearing platforms.
Power generation commands the premium tier on specification complexity; mining expands most quickly as commodity price recovery funds fleet renewal.
End User:
Customer type determines whether procurement bundles installation and commissioning or unbundles supply from service.
- Utilities:Grid operators and independent power producers specify bearing assemblies for turbine-generator maintenance and life extension programs. Asset sweating strategies across German and Japanese thermal fleets are displacing greenfield capital expenditure with targeted component replacement.
- Maintenance Providers:Independent service companies with captive repair infrastructure are capturing unbundled procurement for bearing refurbishment. European power corridors and North American merchant generators award multi-year service contracts that bypass OEM networks.
- OEMs:Original equipment manufacturers integrate sleeve bearings into new turbine-generator packages for export markets. Chinese domestic suppliers and European exporters compete on GB standard certification pathways for state-backed power projects.
- Manufacturers:Industrial motor producers specify bearings for standardized product lines serving general-purpose applications below critical rotating equipment thresholds.
Utilities anchor volume demand; maintenance providers are climbing the fastest as asset life extension programs restructure procurement workflows.
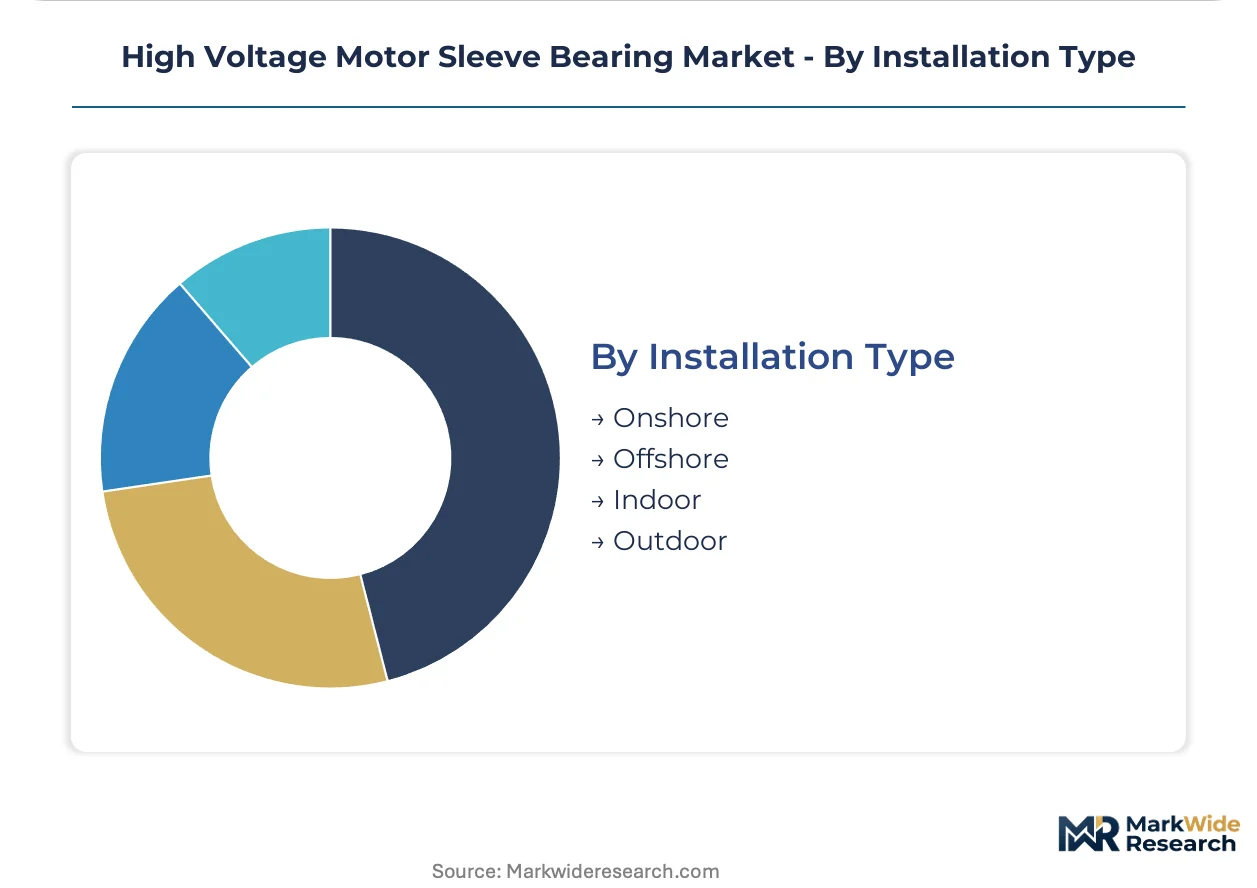
Installation Type:
Geography and exposure conditions dictate housing design, sealing systems, and maintenance access planning.
- Indoor:Climate-controlled turbine halls and motor rooms permit standard bearing housings with scheduled inspection access. European nuclear phase-out policies are accelerating indoor thermal fleet sweating with compressed replacement cycles.
- Onshore:Exposed industrial sites require enhanced sealing against particulate contamination and thermal cycling. Indian national power capacity additions under CEA planning frameworks are creating specification windows for onshore turbine-generator installations.
- Outdoor:Unprotected installations demand robust housings with extended lubrication intervals and corrosion-resistant finishes. Mining and heavy industrial applications in Australia and Brazil specify these for remote site reliability.
- Offshore:Marine environments impose salt spray, humidity, and platform access constraints on bearing system design. North Sea decommissioning timelines and Gulf of Mexico maintenance cycles sustain specialized demand for sealed, remotely monitorable assemblies.
Indoor installations retain the dominant installed base; offshore specifications are expanding most quickly as remote monitoring capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese utilities demonstrate the lowest price elasticity as state-backed procurement prioritizes grid reliability over unit economics, while European independent power producers exhibit acute cost sensitivity amid thermal fleet sweating strategies.
China
Provincial grid operators under State Grid and China Southern Power are accelerating replacement cycles for turbine-generator sleeve bearings through central government-directed modernization programs. GB standards and NMPA-equivalent machinery safety frameworks mandate localized testing protocols that fragment supplier qualification pathways for foreign manufacturers. The Yangtze River Delta cluster around Shanghai hosts captive repair infrastructure serving domestic OEM supply chains.
Germany
Utility asset managers at Uniper and RWE are compressing maintenance intervals for thermal fleet components ahead of nuclear phase-out deadlines. KBA and TÜV-affiliated inspection bodies enforce acceptance criteria for critical rotating equipment that elevate specification complexity. The Ruhr industrial corridor sustains precision babbitt casting capacity concentrated with limited ISO-certified foundry operations.
United States
Merchant generators and regulated utilities are unbundling bearing procurement from OEM service networks to capture aftermarket margin through independent maintenance providers. FERC reliability standards and NERC grid mandates tighten commissioning protocols for turbine-generator sets. The Gulf Coast petrochemical and power generation cluster drives specification demand for corrosion-resistant bearing housings.
India
Central Electricity Authority planning frameworks are creating procurement windows for imported sleeve bearing assemblies in national power capacity additions. BIS certification requirements and domestic content preferences complicate foreign supplier market access. The Gujarat and Maharashtra industrial corridors concentrate thermal generation buildout with specification-driven demand for ISO 7919-compliant installations.
Japan
Utility asset sweating strategies at JERA and regional power companies are displacing greenfield capital expenditure with targeted component replacement programs. METI energy security directives and JIS standards govern bearing specifications for critical infrastructure. The Keihin industrial zone between Tokyo and Yokohama maintains specialized precision machining capacity for hydrodynamic bearing surfaces.
High Voltage Motor Sleeve Bearing Market Competitive Landscape
Capability concentration sits with European and Japanese precision foundry specialists; scale advantage sits with Chinese integrated manufacturers serving domestic power sector procurement. The vendor base organizes around three strategic archetypes: captive repair network operators, backward-integrated babbitt casters, and sensor-telemetry integrators. Consolidation pressure is accelerating through M&A activity targeting aftermarket service capabilities and strategic partnerships for localized certification compliance.
Within the integrated manufacturing tier, Shenke Sliding Bearing Group exemplifies backward integration into babbitt casting and precision machining operations. RENK AG occupies a position representing European captive repair network strategies across power corridor service contracts. Schaeffler Group anchors the sensor-integrated systems vector that extends predictive maintenance intervals for utility customers. These three patterns illustrate how competitive positioning diverges across capability investment versus geographic scale priorities.
| Leading Market Players |
|---|
| RENK AG |
| Shenke Sliding Bearing Group |
| Hunan SUND Industrial & Technological Co., Ltd |
| AB SKF |
| Schaeffler Group |
| The Timken Company |
| NTN Corporation |
| Miba AG |
| ZHEJIANG BHS JOURNAL BEARING CO.,LTD |
| Others |
Value Network & Pricing Analysis
Precision babbitt casting capacity clusters in Germany and Japan feed downstream margin pools toward aftermarket service networks and instrumented bearing assemblies. OEMs and utilities face divergent cost pressures depending on whether procurement bundles installation or unbundles supply from commissioning.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture more than initial hardware sales. Pricing stratifies across ISO 7919-certified instrumented assemblies, standard hydrodynamic designs, and economy-grade replacement liners. Cost compression in economy tiers intensifies because REACH substance restrictions force lead-free reformulation investments. Utilities in China demonstrate the lowest price sensitivity as state-backed procurement prioritizes grid reliability, while European independent power producers exhibit acute cost consciousness amid thermal fleet sweating strategies.
Supply Chain Analysis
Tin and antimony feedstock sourcing concentrates in China, Indonesia, and Bolivia for babbitt alloy production. Precision machining operations draw from specialized foundry output in Germany and Japan, with final assembly distributed across regional OEM facilities. Single-source vulnerability runs through ISO-certified liner suppliers for turbine-generator commissioning. Distribution runs through captive repair networks for utility customers and independent maintenance providers for unbundled procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antifriction bearing substitution threatens sleeve bearing incumbents in applications below 10 MW, forcing defensive capability investments to preserve specification share in critical rotating equipment.
For Market Incumbents: Entrench specification control by deepening backward integration into babbitt casting and precision machining operations. Lock in long-term service contracts across European power corridors before independent maintenance providers build captive repair capabilities. Sensor-telemetry integration represents the critical lever for extending predictive maintenance intervals and capturing recurring revenue streams. For New Entrants and Emerging Players: Establish a beachhead in India's thermal expansion under CEA planning frameworks, where imported sleeve bearing assemblies face specification windows in national power capacity additions. Target aftermarket refurbishment for mining mill drives in Australia and Chile, where contamination resistance requirements create differentiation space outside ISO 7919 turbine-generator standards. Partner with domestic calibration facilities in China to satisfy GB standards and NMPA-equivalent testing protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European captive repair network operators and Japanese precision machining specialists that lack scale to serve Chinese state-backed procurement. Long-term viability hinges on sensor-telemetry convergence and condition-based service contract penetration. Watch for carbon-border adjustment mechanisms reshaping supplier qualification thresholds as the inflection indicator for babbitt sourcing and foundry energy intensity requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Babbitt Casting | Captive supply of precision liners insulates against ISO-certified foundry concentration in Germany and Japan. |
| Sensor-Telemetry Platform Development | Edge computing integration enables condition-based contracts that displace scheduled maintenance calendars for utilities. |
| Localized Certification Partnerships | Domestic calibration facilities in China satisfy GB standards and fragment foreign supplier qualification pathways. |
| Aftermarket Service Network Expansion | Independent repair infrastructure captures unbundled procurement from asset life extension programs across OECD power markets. |
| Lead-Free Alloy Formulation Investment | REACH compliance for European chemical regulations preserves market access while reformulation costs compress legacy margins. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with utility maintenance directors, OEM procurement teams, aftermarket service heads, and precision foundry operations managers; and secondary validation through customs trade data, SEC filings from listed bearing manufacturers, ISO certification registries, and power sector procurement databases. Bottom-up unit demand estimates from turbine-generator installation and replacement cycles were triangulated against top-down market sizing from babbitt alloy consumption and bearing housing shipment data.
Forecast inputs considered power generation capacity additions, grid reliability mandate evolution, and antifriction substitution thresholds across the projection horizon. Segmentation dimensions modeled include product type, industry vertical, end user archetype, and installation environment. CAGRs were derived from replacement cycle compression rates and asset life extension program penetration. Industry-specific inputs incorporated ISO 7919 commissioning protocol adoption and Chinese provincial grid operator modernization schedules.
Stress conditions across babbitt alloy price volatility, REACH regulatory expansion, and sensor-telemetry adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about grid reliability mandate tightening and thermal fleet sweating persistence. Cross-checking against power generation EPC contractor order backlogs and utility capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
United States DC Motor Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Power Scraper Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Smart Motors Market