
 United States Power Rental Market | 2026-2036
United States Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
United States Power Rental Market Intelligence
The EPA Tier 4 Final emissions standard is decoupling legacy diesel generator economics from new fleet investment decisions. United Rentals leverages its national branch network to sustain equipment availability across hurricane-prone Gulf Coast markets. Caterpillar anchors its position through captive engine manufacturing that controls cost structures for rental-ready generator packages. Aggreko competes with modular gas turbine solutions that differentiate its offering from conventional diesel-centric fleets.
United States power rental encompasses the temporary provision of mobile generation, transformation, and distribution equipment rated from 20 kVA to 1000 kVA for grid supplementation or isolated load service. Diesel and natural gas reciprocating engines dominate prime mover configurations, with exhaust aftertreatment systems required for EPA compliance in non-emergency applications. Generators command the largest product type share due to universal applicability across construction sites and utility outage response. Short-term rental generates the highest revenue velocity in the service type dimension, though long-term rental produces superior margin stability through multi-year data center and industrial contracts. The 500 kVA and 1000 kVA power rating brackets attract disproportionate investment as data center and manufacturing loads escalate.
EPA enforcement of Tier 4 Final and upcoming NOx regulations shapes fleet composition and replacement cycles for rental providers nationwide. OSHA electrical safety standards and NFPA 110 emergency power requirements influence installation service scope and maintenance service intervals. State-level renewable portfolio standards in California and New York are expanding hybrid rental configurations that pair battery storage with conventional generation. Stakeholders must monitor FERC interconnection queue backlogs and state utility commission demand response programs to anticipate where rental power transitions from contingency to structural grid need.
Market Dynamics
EPA Tier 4 Final emissions compliance is forcing rental fleet operators to retire legacy diesel generator sets and absorb higher capital costs for exhaust aftertreatment systems. This regulatory compression is reshaping competitive economics between incumbent diesel providers and emerging natural gas alternatives.
Growth Catalysts
- Data Center Load Expansion:Hyperscale facility construction in Northern Virginia and Dallas-Fort Worth is generating multi-year rental contracts for 500 kVA and 1000 kVA backup power systems. These installations require immediate operational availability without permanent infrastructure commitment.
- Grid Reliability Deficits:ERCOT interconnection instability and California Public Utilities Commission rolling outage protocols are compelling industrial facilities to secure temporary generation capacity. Manufacturing and healthcare end-users prioritize rental solutions over capital deployment.
- Natural Gas Infrastructure:Permian Basin pipeline expansion and Texas intrastate distribution networks are enabling gas-fired rental units to compete on fuel cost and emissions profile. This fuel accessibility is accelerating fleet diversification beyond diesel dependency.
Market Restraints
- Engine Block Supply Concentration:Domestic production of EPA-certified prime movers concentrates among three Midwest manufacturing clusters. Any disruption to these captive supply sources compresses rental fleet availability nationwide.
- Aftertreatment Cost Inflation:Diesel oxidation catalysts and selective catalytic reduction systems now constitute 35-45 percent of new generator package cost. This input cost escalation narrows rental provider margin structures on short-term contracts.
- Permitting Timeline Friction:Local air quality management districts in California and Northeast corridor states impose multi-week approval processes for temporary generator installation. These regulatory delays constrain emergency response velocity.
Strategic Opportunities
- Hybrid Storage Integration:Battery energy storage systems paired with conventional generation are qualifying for California Self-Generation Incentive Program credits. This technology convergence opens rental configurations previously restricted to permanent installation economics.
- Gulf Coast Hurricane Response:Louisiana and Florida utility reconstruction protocols now specify pre-positioned rental generation assets. This geographic white space rewards providers with logistics infrastructure in Houston and Miami metropolitan zones.
- Industrial Electrification Backstop:Department of Energy industrial decarbonization grants are accelerating facility electrification projects that require temporary power during grid interconnection delays. Rental providers can capture this transitional demand.
Industry Challenges
- EPA Certification Lag:New engine platform validation for Tier 4 Final compliance requires 18-24 month testing cycles. This certification timeline compresses product refresh rates and extends capital recovery periods.
- Technician Specialization Gap:Exhaust aftertreatment diagnostics and high-voltage interconnection protocols demand training investments that outpace workforce pipeline development. Rental operators face service quality risk during peak demand events.
- Fleet Utilization Volatility:Hurricane season concentration and data center construction cyclicality create asymmetric load factors. Providers must absorb carrying costs for underutilized assets during extended low-demand intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Power Rental Market |
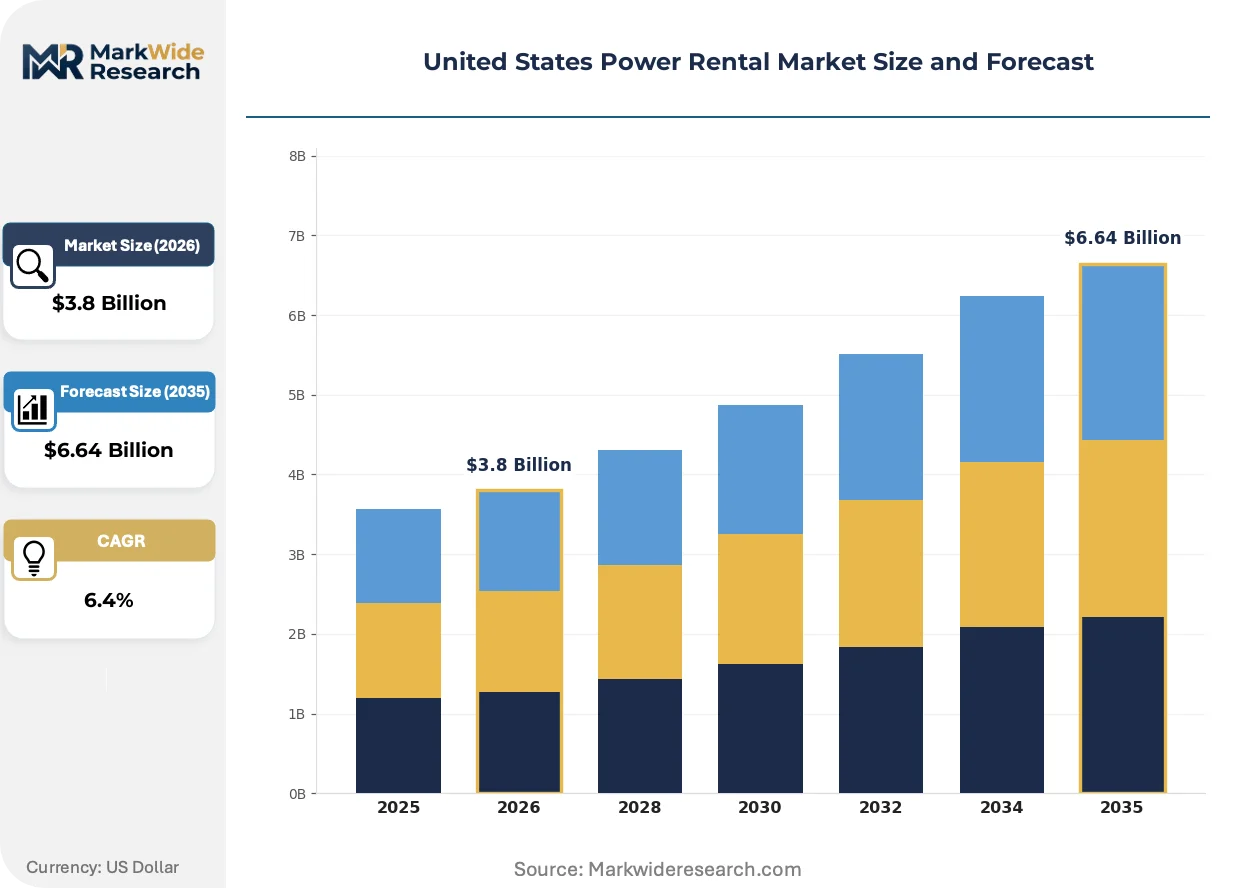
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, Transformers, Distribution Panels, Load Banks End User: Construction, Events, Utilities, Industrial Service Type: Short-Term Rental, Long-Term Rental, Maintenance Services, Installation Services Power Rating: 20 kVA, 100 kVA, 500 kVA, 1000 kVA |
| Companies Covered | United Rentals, Sunbelt Rentals, Herc Rentals, Aggreko, Caterpillar, Atlas Copco, Cummins, Kohler, Generac, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Power Rental Market Strategic Shifts & Innovations
Modular power architecture and digital telemetry integration are compressing deployment timelines and enabling predictive maintenance models. These capabilities are shifting competitive differentiation from equipment availability toward operational intelligence.
Containerized natural gas generator sets with integrated heat recovery are consolidating prime mover selection for data center and industrial applications. Hyperscale operators in Texas and Virginia are specifying these configurations for 72-hour continuous runtime requirements. This technology is consolidating market share previously distributed across multiple diesel unit deployments.
EPA enforcement of Tier 4 Final and anticipated NOx regulations is accelerating fleet turnover toward cleaner reciprocating engines. Rental providers face stranded asset risk for pre-2015 diesel inventory that cannot be redeployed to non-attainment areas. The PJM Interconnection corridor and California South Coast Air Basin are most affected, with providers retiring legacy units ahead of regulatory deadlines.
Power-as-a-service contracting is replacing traditional equipment rental for mission-critical loads. Data center operators in Northern Virginia are purchasing guaranteed availability rather than generator hours, transferring operational risk to rental providers. This model is most visible among colocation facilities with SLA-driven uptime requirements and limited on-site technical staff.
United States Power Rental Market Segmentation
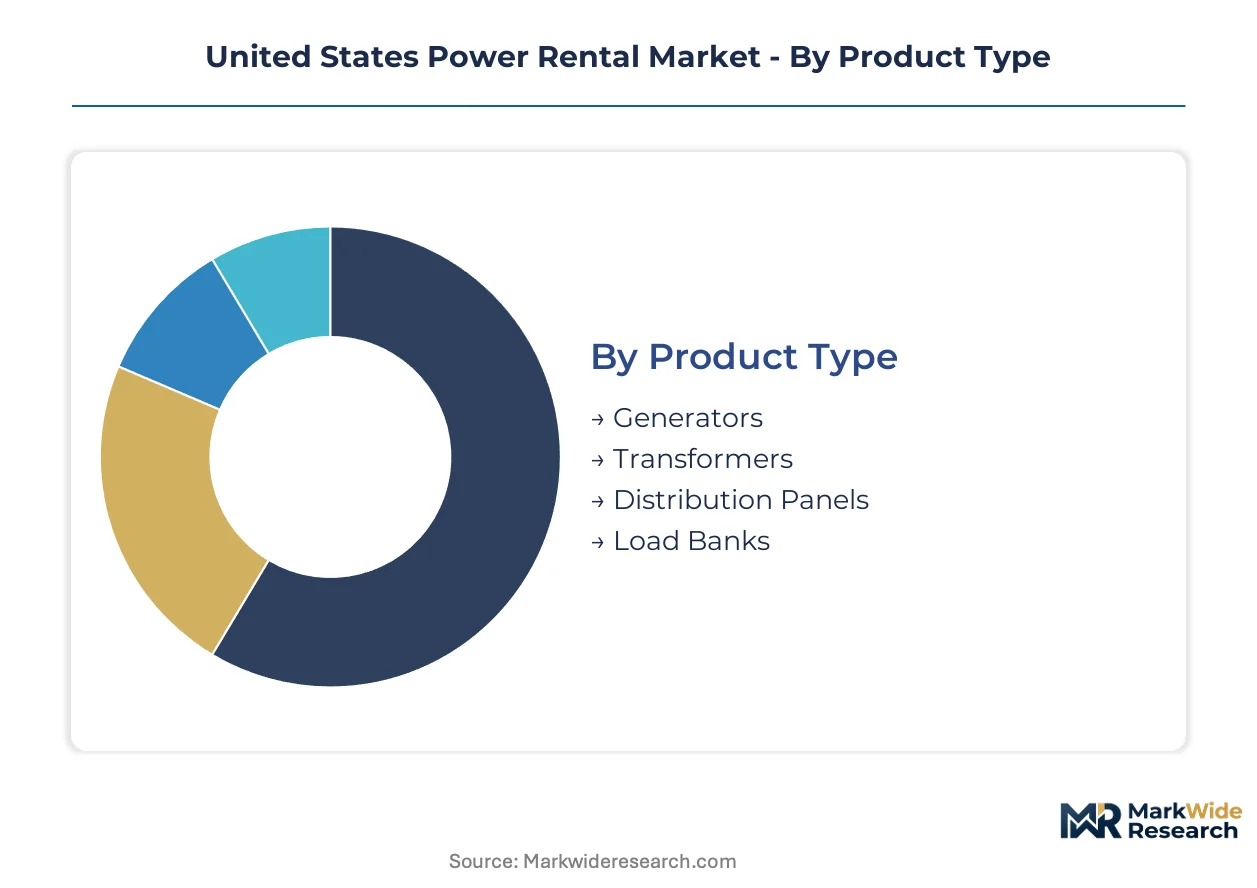
Power rental segmentation reveals how capital deployment, regulatory exposure, and contract duration shape provider economics. Each dimension carries distinct margin profiles and fleet utilization patterns that determine competitive positioning across the United States.
Product Type:
Generators command the highest capital intensity per unit, with EPA Tier 4 Final aftertreatment systems adding substantial upfront cost. Transformers and distribution equipment require lower initial investment but face longer depreciation cycles.
- Generators:Diesel and natural gas reciprocating engines rated from 20 kVA to 1000 kVA constitute the core rental fleet. Demand concentrates in Texas and Northern Virginia where data center construction drives procurement of 500 kVA and 1000 kVA units for backup power redundancy.
- Transformers:Mobile step-up and step-down units enable voltage matching between rental generation and facility distribution systems. California utilities deploy these assets during wildfire-related grid de-energization events to restore service to critical loads.
- Distribution Panels:Temporary switchgear and breaker assemblies extend rental power to multiple load points. Gulf Coast hurricane response protocols specify pre-staged panel configurations to accelerate restoration timelines.
- Load Banks:Resistive and reactive testing equipment validates generator performance before permanent installation. Data center commissioning procedures in Dallas-Fort Worth require resistive load bank verification for Tier III and Tier IV facility certification.
Most installed capacity flows through Generators. Expansion is steepest in Transformers as grid hardening investments accelerate temporary interconnection demand.
End User:
Contract duration and technical sophistication vary sharply across user categories, with industrial and utility segments demanding multi-year agreements while construction and events drive spot market volatility.
- Construction:General contractors and specialty trades rent generators for site electrification during early-phase development. Texas highway and infrastructure projects sustain consistent demand for 100 kVA and 500 kVA diesel units.
- Events:Music festivals, sporting events, and corporate gatherings require silent-canopy generators with rapid deployment capability. Los Angeles and Miami metropolitan areas generate seasonal peaks tied to entertainment industry calendars.
- Utilities:Investor-owned and municipal utilities procure rental generation for planned maintenance and emergency restoration. PJM Interconnection members maintain standby contracts for transmission substation backup during peak load events.
- Industrial:Manufacturing, petrochemical, and healthcare facilities secure long-term rental for process continuity. Louisiana refineries specify natural gas generator sets with 72-hour continuous runtime for hurricane season resilience.
Industrial contracts generate the highest margin stability. Construction delivers the steepest volume expansion as infrastructure spending accelerates across the Southeast.
Service Type:
Revenue recognition and operational risk transfer distinguish service models, with long-term rentals and power-as-a-service contracts shifting maintenance burden to providers.
- Short-Term Rental:Daily and weekly agreements for emergency response and event power. Hurricane season concentration in Florida and Louisiana creates utilization spikes that strain logistics networks.
- Long-Term Rental:Multi-year contracts spanning data center construction and industrial facility commissioning. Northern Virginia colocation providers favor these agreements to defer permanent infrastructure investment.
- Maintenance Services:Scheduled inspection, fluid analysis, and component replacement programs. EPA Tier 4 Final compliance mandates specialized exhaust aftertreatment servicing that commands premium pricing.
- Installation Services:Electrical interconnection, fuel plumbing, and control system integration. California Air Resources Board permitting requirements extend installation timelines and expand service scope.
Long-Term Rental captures the largest revenue share. Maintenance Services are expanding most quickly as fleet complexity drives outsourcing demand.
Power Rating:
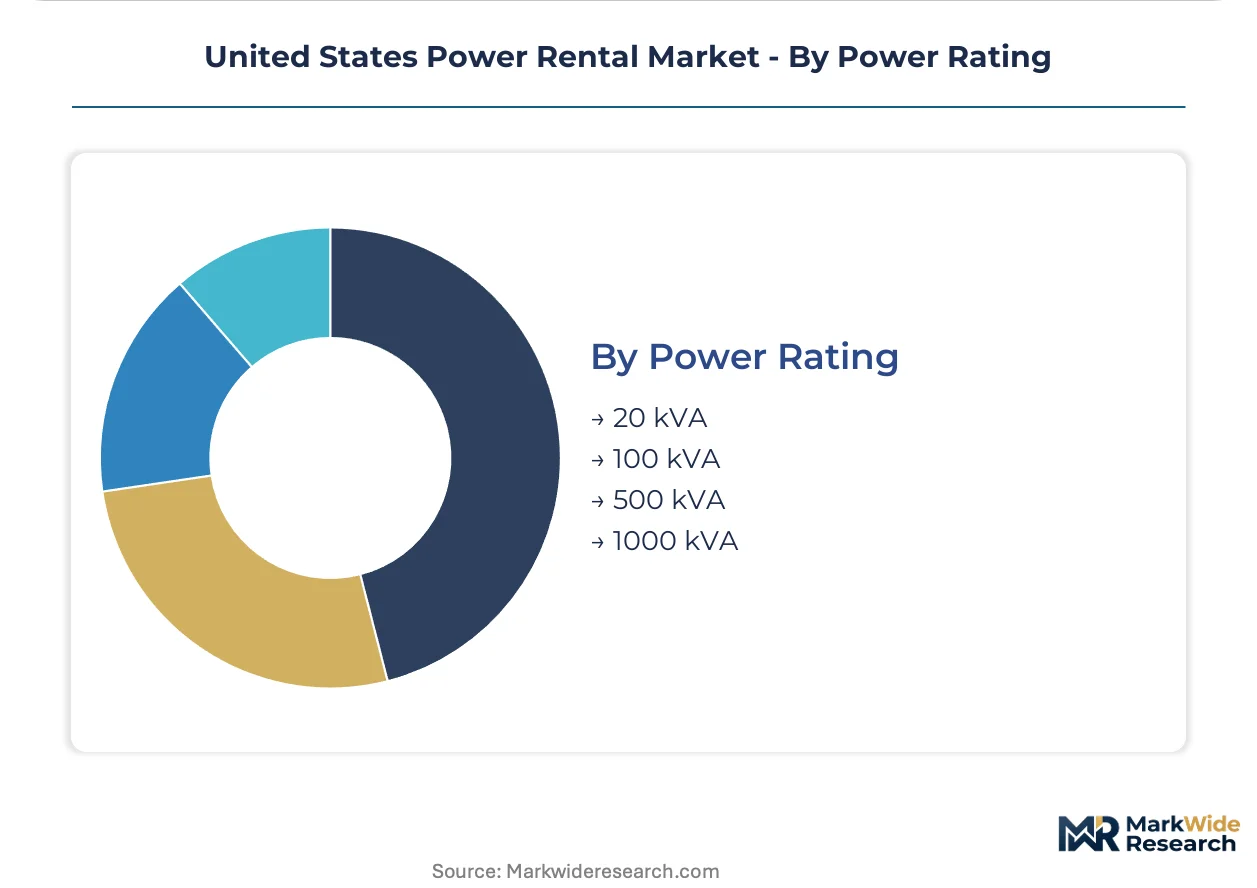
Unit economics scale non-linearly with power rating, with 500 kVA and 1000 kVA brackets requiring specialized transport and foundation preparation that smaller units avoid.
- 20 kVA:Compact portable units serve small commercial loads and residential backup applications. Retail and restaurant chains in California deploy these for rolling outage protection.
- 100 kVA:Mid-range capacity supports construction trailers and medium-sized events. Texas oilfield service operations specify these for remote wellsite electrification.
- 500 kVA:Industrial-grade generators address manufacturing lines and data center halls. Hyperscale facility construction in Ashburn, Virginia drives sustained procurement for phased power commissioning.
- 1000 kVA:Maximum standard rental capacity serves critical infrastructure and large industrial campuses. Dallas-Fort Worth data center clusters specify containerized natural gas configurations for emissions compliance.
The 500 kVA bracket moves the most unit volume. 1000 kVA deployments are gaining share fastest as data center power density requirements escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technician pools in Houston, Dallas-Fort Worth, and Northern Virginia anchor fleet deployment capacity for emergency response and data center commissioning contracts.
Texas
ERCOT grid instability and Permian Basin pipeline expansion drive procurement of natural gas generator sets for industrial backup. Texas Commission on Environmental Quality air permits enable rapid deployment of temporary generation for oilfield electrification. Dallas-Fort Worth data center construction sustains multi-year rental contracts for 1000 kVA containerized units.
California
CPUC rolling outage protocols and wildfire-related PSPS events compel healthcare and retail chains to secure rental power. California Air Resources Board NOx regulations accelerate fleet turnover toward Tier 4 Final compliant diesel and hybrid storage configurations. Los Angeles metropolitan entertainment industry generates seasonal demand for silent-canopy generators at production facilities and outdoor venues.
Virginia
Hyperscale data center construction in Loudoun and Prince William counties creates sustained demand for 500 kVA and 1000 kVA backup systems. Virginia Department of Environmental Quality permitting aligns with federal EPA standards for non-emergency generator operation. Ashburn colocation facilities favor power-as-a-service contracts that transfer operational risk to rental providers.
Louisiana
Gulf Coast hurricane reconstruction protocols and petrochemical facility resilience requirements sustain demand for 72-hour continuous runtime natural gas units. Louisiana Department of Environmental Quality coastal zone management regulations influence temporary generator siting for refinery backup power. Baton Rouge and Lake Charles industrial corridors specify pre-positioned rental assets for storm season readiness.
Florida
Florida Public Service Commission utility restoration standards mandate rapid deployment capability for post-hurricane grid reconstruction. Miami-Dade County air quality regulations govern temporary generator permitting for events and emergency response. Orlando and Tampa metropolitan entertainment and hospitality sectors drive seasonal procurement for festival and convention power.
United States Power Rental Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across equipment rental and manufacturer-direct service models. Market structure concentrates among national branch network operators with Gulf Coast logistics infrastructure and captive engine manufacturing capabilities. Three archetypes dominate: integrated equipment lessors with multi-state presence, engine manufacturers with rental-ready packaging operations, and modular gas turbine specialists. Competitive moves center on fleet diversification beyond diesel dependency and pre-positioned asset staging for hurricane response velocity.
Within the integrated lessor tier, United Rentals and Sunbelt Rentals occupy positions defined by national branch density and logistics infrastructure. Aggreko represents the modular gas turbine specialist archetype with differentiated fuel flexibility. Among engine manufacturers with captive rental packaging, Caterpillar anchors manufacturing cost control for generator set deployment. These three companies exemplify how scale, technology specialization, and vertical manufacturing integration shape competitive positioning across EPA compliance and data center commissioning segments.
| Leading Market Players |
|---|
| United Rentals |
| Sunbelt Rentals |
| Herc Rentals |
| Aggreko |
| Caterpillar |
| Atlas Copco |
| Cummins |
| Kohler |
| Generac |
| Others |
Cost & Logistics Intelligence
Data center operators in Northern Virginia and Texas anchor procurement volume and negotiate power-as-a-service contracts that bundle equipment, fuel, and maintenance into availability-based fees. This buyer concentration rewards providers with captive engine manufacturing and Gulf Coast logistics infrastructure.
Pricing Analysis
Bundled power-as-a-service contracts dominate mission-critical applications while unbundled equipment-only rentals persist in construction and event markets. Price differentiation rests on EPA Tier 4 Final certification status and aftertreatment service bundling. Cost compression in short-term diesel rentals is intensifying because exhaust aftertreatment systems now constitute 35-45 percent of new generator package cost. Construction contractors exhibit highest price sensitivity; data center operators prioritize guaranteed availability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from major rental providers mandate EPA-certified engine qualification across at least two Midwest manufacturing clusters. Domestic production of prime movers concentrates in Illinois, Wisconsin, and Ohio. Raw material dependencies include steel castings for engine blocks, exhaust catalyst substrates, and copper windings for alternators. Single-source vulnerability exists for selective catalytic reduction system suppliers. Distribution runs through national branch networks with pre-positioned hurricane response assets in Houston and Miami metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States power rental market functions as a stable compounder where data center load expansion and grid reliability deficits generate recurring multi-year contract revenue. EPA regulatory compression sustains replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Deploy hybrid storage integration to capture California Self-Generation Incentive Program credits and differentiate from diesel-centric competitors. Consolidate technician training investments to close the exhaust aftertreatment diagnostics gap that threatens service quality during peak demand events. Natural gas fleet diversification defends margin position against Tier 4 Final aftertreatment cost inflation.
For New Entrants and Emerging Players: Digital telemetry platforms enable remote monitoring services that penetrate the industrial electrification backstop segment where Department of Energy grants accelerate facility upgrades. Target Louisiana and Florida hurricane response protocols that specify pre-positioned rental generation assets. White space exists in modular gas turbine solutions for 72-hour continuous runtime requirements.
For Investors and Strategic Acquirers: Engine manufacturers with captive rental packaging are the most active acquirer in this space, seeking branch network density in Texas and Virginia. Long-term viability rests on fleet turnover velocity driven by EPA enforcement timelines. Acquisition target archetype: regional lessors with Gulf Coast logistics infrastructure and underutilized Tier 4 Final certified inventory. Deviation in FERC interconnection queue clearance rates would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Natural Gas Fleet Diversification | Permian Basin pipeline expansion enables fuel cost competitiveness against diesel in Texas markets. |
| Hybrid Storage Integration | California SGIP credits unlock rental configurations previously restricted to permanent installations. |
| Hurricane Response Pre-Positioning | Louisiana utility reconstruction protocols reward providers with Houston and Miami logistics hubs. |
| Power-as-a-Service Contracting | Northern Virginia data centers transfer operational risk to rental providers through availability guarantees. |
| EPA Tier 4 Final Fleet Refresh | Regulatory deadlines in California and PJM corridor force legacy diesel retirement ahead of schedule. |
Research Approach
Bottom-up data center and industrial load modeling reconciled against top-down rental fleet capacity tracking forms the analytical core. Primary interviews with utility planning officers, data center facility directors, rental fleet managers, and EPA compliance specialists combined with secondary validation from EIA generation data, FERC interconnection filings, state utility commission procurement records, and equipment manufacturer production disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map generator deployment by power rating bracket against end-use demand curves across the projection horizon. Segmentation dimensions include fuel source, service type, power rating tier, and regional grid reliability profile. CAGRs derive from equipment replacement cycles, data center construction pipelines, and regulatory compliance timelines. Forecast inputs incorporate EPA certification lag periods and hurricane season concentration patterns.
The model assumes a particular technology adoption path; alternative pathways for battery-gas hybrid systems would alter the outlook. Forecasts reflect assumptions about ERCOT grid stability and California PSPS event frequency. Deviation in EPA NOx regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
United Arab Emirates Power Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
AC Power Sources Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Germany Power EPC Market
Power Equipment
Europe Power Rental Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Power Equipment Testing Market