
 North America Power Plant Boiler Market | 2026-2036
North America Power Plant Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
North America Power Plant Boiler Market Analytics
Long-term service agreements for boiler lifecycle management is pivoting vendor relationships from equipment sales to performance contracts. General Electric leverages its digital power plant platform to sustain aftermarket revenue across installed North American units. Babcock & Wilcox Enterprises anchors its position through specialized boiler refurbishment capabilities for coal-to-gas conversion projects. Siemens AG competes on supercritical technology leadership for new combined-cycle installations.
A power plant boiler is a closed vessel engineered to convert water into high-pressure steam through combustion heat transfer, typically operating at temperatures exceeding 540°C and pressures above 240 bar for utility-scale generation. Water-tube designs dominate new construction across North American utilities due to higher thermal efficiency and supercritical steam compatibility. Natural gas fuel sourcing is expanding fastest among fuel source categories as coal retirements accelerate under environmental compliance timelines. Supercritical and ultra-supercritical technology segments command premium positioning where utilities prioritize heat rate optimization and carbon intensity reduction.
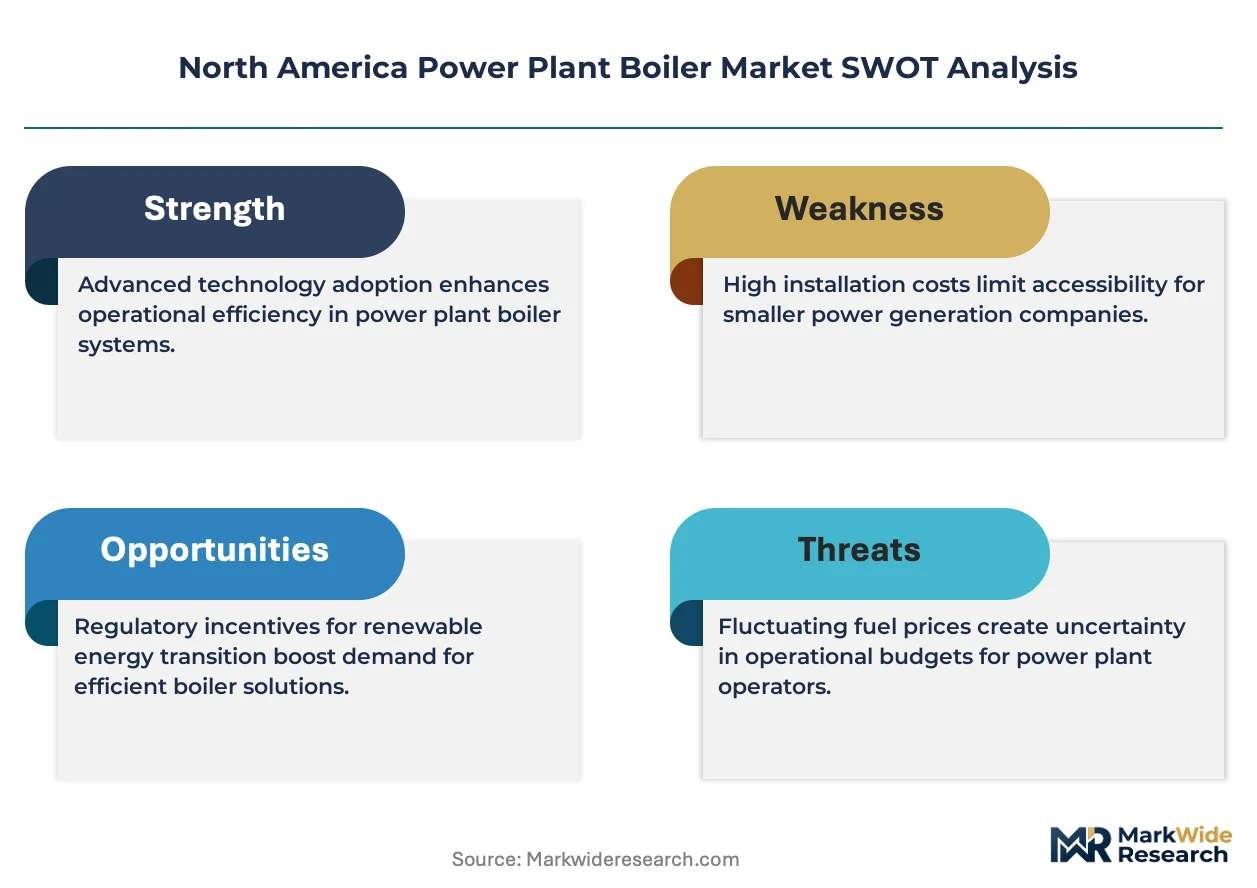
The EPA enforces Maximum Achievable Control Technology standards that mandate selective catalytic retrofit installation on existing coal-fired boilers, directly shaping equipment procurement cycles. NHTSA and OSHA coordinate on boiler safety inspection protocols that influence maintenance scheduling and outage planning for industrial operators. State-level renewable portfolio standards in California and New York are forcing hybrid boiler configurations that co-fire biomass with fossil fuels. Stakeholders must weigh stranded asset risk against retrofit economics as federal emission thresholds tighten without guaranteed technology-neutral treatment for natural gas infrastructure.
Market Dynamics
Utilities across the United States are accelerating coal-to-gas conversion timelines as EPA Mercury and Air Toxics Standards force emission control retrofits on aging boiler fleets, compressing equipment procurement cycles and reshaping vendor relationships toward lifecycle service contracts.
Growth Catalysts
- EPA Compliance Mandates:Maximum Achievable Control Technology standards require selective catalytic reduction retrofits on existing coal-fired units, triggering replacement demand for emission control systems and auxiliary boiler components.
- Texas-Louisiana Gulf Coast Corridor:Petrochemical and power cogeneration clusters concentrate demand for high-pressure steam generation, driving supercritical boiler installations across industrial utility complexes.
- Natural Gas Infrastructure:Pipeline network expansion and domestic shale supply abundance enable rapid fuel switching from coal, positioning gas-fired water-tube designs as the dominant new construction technology.
Market Restraints
- Specialized Alloy Input Costs:Supercritical and ultra-supercritical boilers require advanced nickel-based alloys and specialized tubing that face supply concentration among limited specialty steel producers.
- Stranded Asset Risk:Federal emission thresholds tighten without guaranteed technology-neutral treatment for natural gas infrastructure, creating regulatory uncertainty around long-term asset valuations.
- Renewable Portfolio Standards:State-level mandates in California and New York force hybrid configurations that co-fire biomass, introducing operational complexity and fuel handling limitations for traditional boiler designs.
Strategic Opportunities
- Coal-to-Gas Conversion Services:Boiler refurbishment capabilities for fuel switching projects represent expanding white space as utilities seek to extend asset life rather than greenfield construction.
- Digital Power Plant Platforms:Integration of predictive maintenance analytics with existing installed bases enables performance-based service contracts replacing traditional equipment sales models.
- Hybrid Biomass Co-firing:State renewable mandates create retrofit opportunities for existing fossil units to incorporate biomass feedstocks, requiring combustion system modifications and fuel handling upgrades.
Industry Challenges
- Welding and Metallurgical Expertise Shortage:Supercritical boiler fabrication and field erection require certified high-pressure welding specialists and thermal engineering expertise that utilities struggle to source.
- Outage Coordination Complexity:NHTSA and OSHA safety inspection protocols influence maintenance scheduling, forcing extended downtime windows that compress revenue-generating operating hours.
- Legacy Control System Integration:Digital platform deployment across aging installed units faces compatibility barriers with analog distributed control systems and proprietary vendor architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Power Plant Boiler Market |
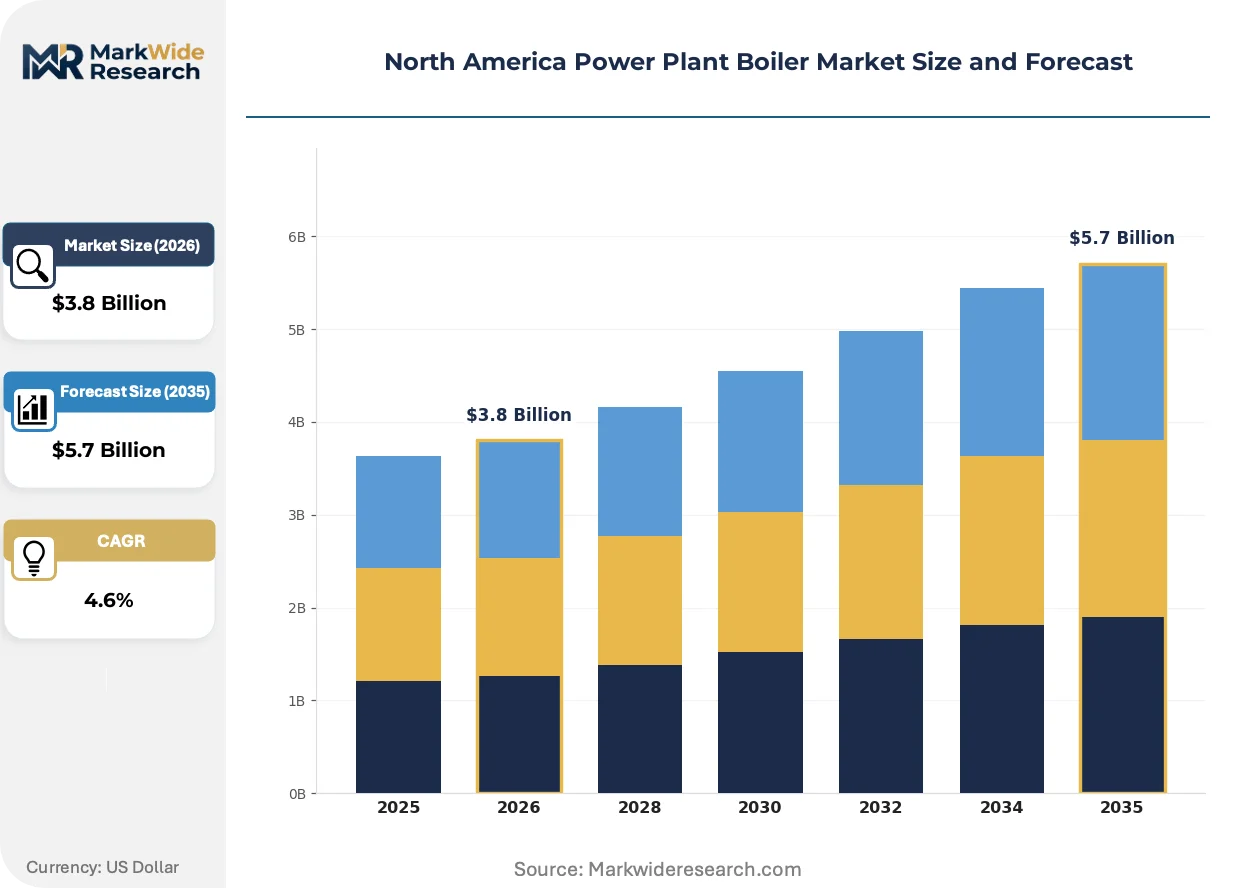
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boiler Type: Fire-Tube, Water-Tube, Hybrid, Steam Fuel Source: Natural Gas, Coal, Biomass, Oil End User: Utilities, Industrial Facilities, Manufacturing Plants, Power Generation Technology: Condensation, Supercritical, Subcritical, Circulating Fluidized Bed |
| Companies Covered | Siemens AG, Dongfang Electric Corporation, General Electric, John Wood Group, IHI Corporation, Babcock & Wilcox Enterprises, Doosan Heavy Industries & Construction, Bharat Heavy Electrical Limited, Mitsubishi Hitachi Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Power Plant Boiler Market Evolving Landscape
Boiler technology evolution centers on thermal efficiency optimization and operational flexibility, with supercritical steam conditions and modular system architectures displacing conventional subcritical designs across North American utility procurement.
Once-through supercritical boiler technology is modularizing plant-scale deployment, enabling utilities to right-size generation capacity in incremental blocks rather than single large baseload units. Mid-size independent power producers adopt these configurations fastest, shaving construction timelines and reducing capital-at-risk during demand uncertainty. This architecture compresses the traditional economies-of-scale advantage held by massive pulverized coal stations.
The EPA enforces Maximum Achievable Control Technology standards that mandate selective catalytic reduction and fabric filter installation on existing coal-fired boilers. Industrial consequence includes forced capital allocation toward emission control retrofits rather than core generation efficiency upgrades. Coal-dependent utilities in the Ohio River Valley and Appalachian regions face the steepest compliance burden, accelerating asset retirement decisions.
Long-term service agreements are displacing transactional equipment sales across the vendor-customer interface, unbundling aftermarket revenue from initial capital contracts. General Electric and Babcock & Wilcox anchor this pivot through performance-guaranteed maintenance programs. This shift concentrates most visibly among Texas and Louisiana petrochemical operators seeking operational cost predictability.
North America Power Plant Boiler Market Segmentation
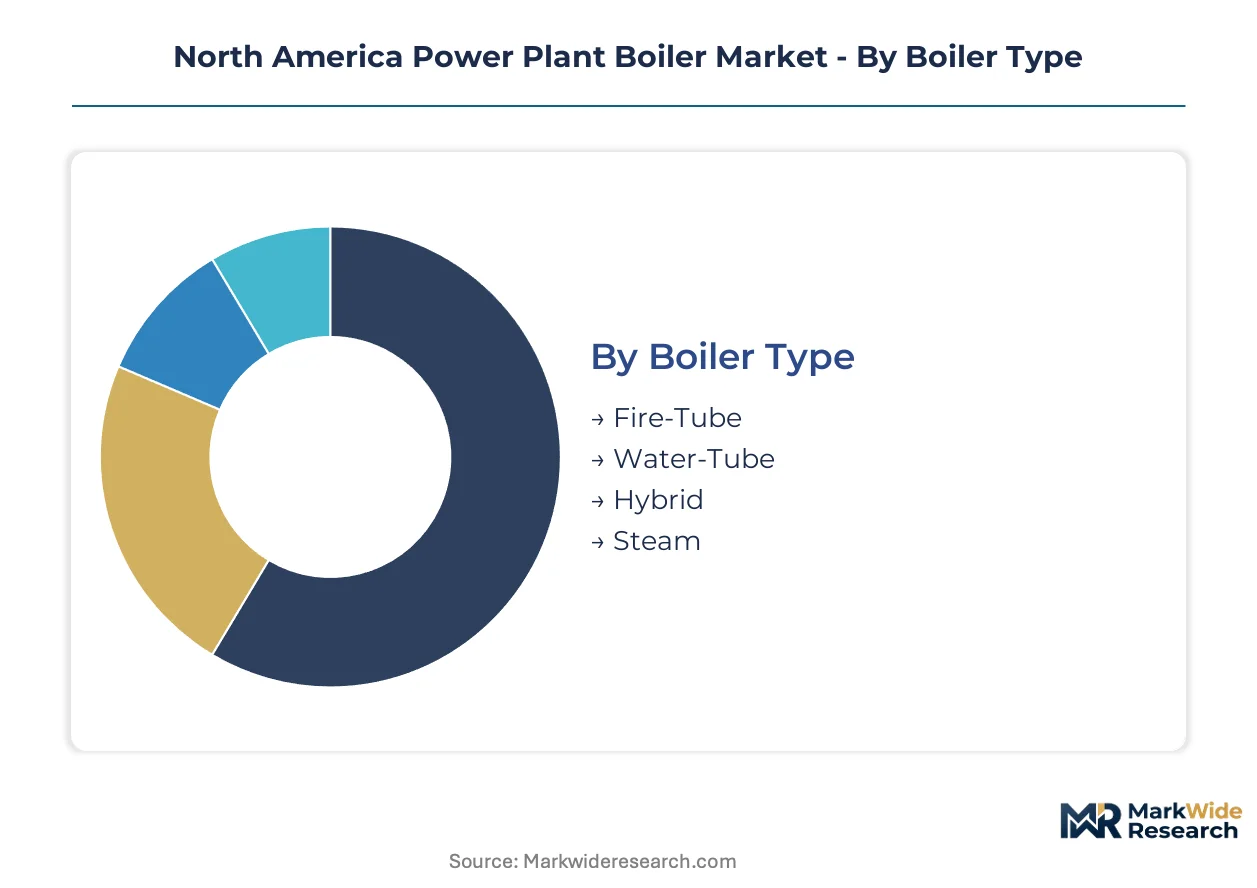
Segmentation in the North America power plant boiler market reveals distinct procurement patterns across technology maturity, fuel transition economics, and operational scale requirements. Each category maps to specific regulatory compliance timelines and asset lifecycle strategies that utilities must navigate.
Boiler Type:
Customization intensity spans from standardized fire-tube units for industrial steam loads to engineered water-tube systems for utility supercritical service.
- Water-Tube:High-pressure designs circulate water through tubes exposed to combustion gases, enabling supercritical steam conditions above 374°C. Texas-Louisiana petrochemical complexes specify these for combined-cycle cogeneration where thermal efficiency directly impacts operating economics.
- Fire-Tube:Combustion gases pass through tubes immersed in a water shell, limiting pressure capability but reducing capital cost and footprint. Manufacturing plants in Ohio and Pennsylvania deploy these for process steam below 20 bar where load cycling frequency is moderate.
- Hybrid:Configurations combine fire-tube and water-tube elements to balance cost and pressure capability for mid-size industrial applications.
- Steam:Dedicated steam generators bypass feedwater heating stages for direct steam injection or specialized process requirements.
Leading the category by volume: Water-Tube. Expanding most quickly: Hybrid configurations for biomass co-firing retrofits.
Fuel Source:
Procurement patterns track the regional availability of pipeline infrastructure and emission compliance cost differentials across state jurisdictions.
- Natural Gas:Cleanest fossil combustion profile enables simplified emission control retrofits and faster permitting in EPA non-attainment zones. Appalachian shale proximity and expanded Gulf Coast pipeline networks position this as the default replacement fuel for retired coal units.
- Coal:Existing fleet requires selective catalytic reduction and fabric filter installation under Maximum Achievable Control Technology standards. Ohio River Valley utilities face accelerated retirement decisions as retrofit economics deteriorate against gas-fired alternatives.
- Biomass:Agricultural residues and wood pellets satisfy renewable portfolio standards in California and New York through co-firing modifications.
- Oil:Distillate and residual fuel oils serve peaking applications and remote locations lacking gas pipeline access.
Natural Gas dominates current procurement. Biomass co-firing climbs the fastest under state-level renewable mandates.
End User:
Customer scale determines engineering complexity, with utility procurement emphasizing grid reliability and industrial buyers prioritizing thermal cost predictability.
- Utilities:Investor-owned and municipal power systems operate baseload and intermediate generation subject to FERC interconnection standards and NERC reliability criteria. These customers specify supercritical technology and demand long-term service agreements for outage risk transfer.
- Industrial Facilities:Petrochemical, refining, and pulp and paper operations require high-pressure steam for process heat and power cogeneration. Gulf Coast chemical producers represent the most concentrated demand cluster for ultra-supercritical installations.
- Manufacturing Plants:Discrete manufacturing and food processing operations consume lower-pressure steam for sterilization, drying, and space heating.
- Power Generation:Independent power producers and merchant generators focus on heat rate optimization and dispatch flexibility for competitive wholesale markets.
Utilities anchor the category by installed capacity. Industrial Facilities gain share fastest through on-site cogeneration expansion.
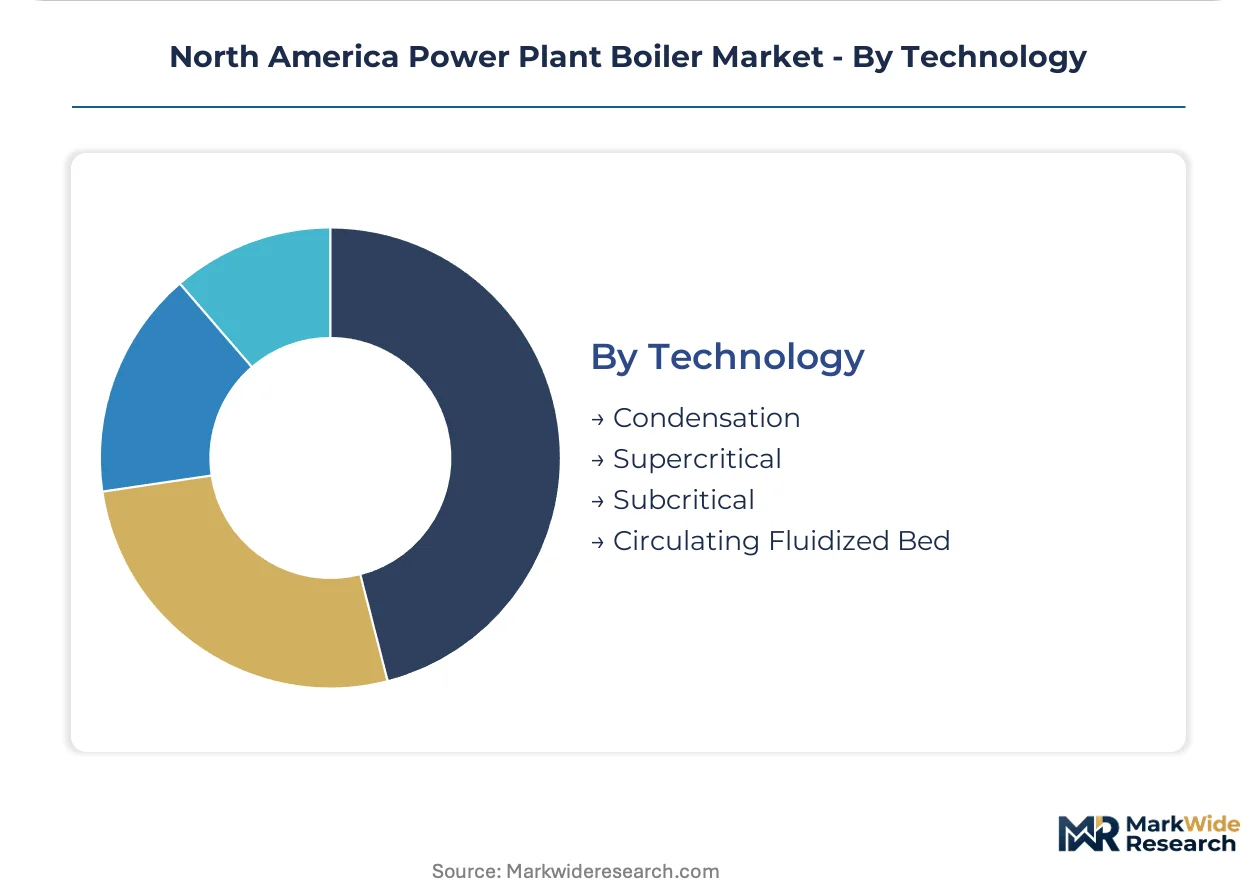
Technology:
Capital intensity and operating margin potential stratify across thermodynamic efficiency thresholds and emission control integration requirements.
- Supercritical:Steam conditions exceed water's critical point, eliminating phase separation and enabling single-pass boiler designs with heat rates below 10,000 Btu/kWh. New combined-cycle installations across Texas and Louisiana specify these for carbon intensity reduction.
- Subcritical:Drum-type boilers operating below critical pressure dominate the existing installed base, particularly in coal-dependent Midwestern states where retirement timelines remain uncertain.
- Condensation:Heat recovery configurations capture latent energy from exhaust gases, improving net efficiency for gas-fired applications.
- Circulating Fluidized Bed:Suspended combustion of low-grade fuels including high-ash coal and biomass enables fuel flexibility for waste-to-energy and co-firing projects.
Subcritical technology retains the largest installed base. Supercritical systems show the steepest expansion trajectory in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boiler manufacturing concentrates in the United States, while Canadian utilities and Mexican industrial parks absorb cross-border equipment flows. Regional demand patterns track EPA compliance timelines, pipeline infrastructure density, and petrochemical cluster expansion.
United States
Texas-Louisiana Gulf Coast petrochemical complexes drive supercritical boiler procurement for combined-cycle cogeneration. EPA Maximum Achievable Control Technology standards force selective catalytic reduction retrofits on Ohio River Valley coal units. Appalachian shale proximity and expanded pipeline networks position natural gas as the dominant replacement fuel across Midwestern utility fleets.
Canada
Alberta oil sands operators require high-pressure steam generation for enhanced recovery operations, sustaining demand for water-tube designs. Provincial carbon pricing mechanisms in British Columbia and Alberta accelerate coal phase-out timelines. Ontario's nuclear baseload dominance limits new boiler construction to industrial cogeneration sites in the Sarnia chemical corridor.
Mexico
Energy reform liberalization attracts independent power producers to the Tula-Vito-Apaxco industrial corridor north of Mexico City. Federal electricity commission procurement favors combined-cycle configurations for grid reliability expansion. Northern border states leverage cross-border gas pipeline access to serve maquiladora manufacturing steam loads.
North America Power Plant Boiler Market Competitive Landscape
Top-tier vendors anchor the supercritical technology segment, while mid-tier fabricators compete on coal-to-gas conversion services and regional aftermarket presence. Market structure tilts toward consolidated equipment supply for utility-scale projects, with fragmentation in industrial boiler refurbishment. Strategic archetypes include integrated technology conglomerates, specialized boiler engineering houses, and lifecycle service providers. Dominant competitive moves center on long-term service agreement expansion and digital platform integration across installed bases.
Within the integrated technology tier, Siemens AG and General Electric exemplify full-stack power plant solution providers spanning turbine-generator-boiler systems. Babcock & Wilcox Enterprises occupies a position as a specialized boiler engineering house with deep refurbishment capabilities for fuel switching projects. These three anchors represent distinct competitive vectors: European technology leadership, American digital platform scale, and dedicated boiler lifecycle expertise.
| Leading Market Players |
|---|
| Siemens AG |
| Dongfang Electric Corporation |
| General Electric |
| John Wood Group |
| IHI Corporation |
| Babcock & Wilcox Enterprises |
| Doosan Heavy Industries & Construction |
| Bharat Heavy Electrical Limited |
| Mitsubishi Hitachi Power Systems |
| Others |
Value Network & Pricing Analysis
EPA Maximum Achievable Control Technology mandates for selective catalytic reduction retrofits are compressing procurement timelines across Ohio River Valley utilities, forcing suppliers to expedite specialized alloy sourcing and eroding price negotiation leverage for buyers facing compliance deadlines.
Pricing Analysis
Margin tightening in supercritical boiler tiers reflects nickel-based alloy supply concentration among limited specialty steel producers. Project-based long-term contracting dominates, with price differentiation hinging on ASME certification grade and volume scale. Cost compression accelerates in subcritical refurbishment segments as coal-to-gas conversion demand outstrips certified welding capacity. Industrial facilities exhibit highest price sensitivity; utility buyers prioritize performance guarantees over unit cost.
Supply Chain Analysis
ASME Section I certification requirements gate entry for pressure vessel fabrication, concentrating qualified supply among United States, Germany, and Japan. Nickel-based superalloys, high-pressure tubing, and specialized welding consumables anchor raw material dependencies. Single-source vulnerability persists for advanced alloy melts from specialty steel producers. Distribution runs through EPC contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized welding and metallurgical expertise scarcity props pricing power for certified fabricators, constraining capacity expansion and sustaining margin structures across the supercritical segment.
For Market Incumbents: Hedge stranded asset exposure in coal-dependent legacy fleets by accelerating digital platform deployment for predictive maintenance contracts. Secure backward integration into nickel alloy supply through offtake agreements with specialty steel producers. EPA compliance timeline compression threatens equipment margins; lifecycle service revenue provides buffer. For New Entrants and Emerging Players: State renewable portfolio standards in California and New York open a window for biomass co-firing retrofit specialists. Target mid-size independent power producers in Texas-Louisiana corridor seeking modular supercritical configurations. Lead with combustion system modification expertise rather than greenfield construction capability. For Investors and Strategic Acquirers: The window for entry favors boiler refurbishment specialists with certified coal-to-gas conversion track records. Long-term viability hinges on service contract recurrence rather than equipment sale cyclicality. Watch for FERC interconnection queue acceleration as signal for new construction inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Expansion | General Electric and Babcock & Wilcox anchor revenue predictability through performance-guaranteed maintenance programs. |
| Digital Platform Integration | Predictive analytics deployment across installed bases enables outage risk transfer to vendors. |
| Coal-to-Gas Conversion Services | Refurbishment capabilities for fuel switching projects extend asset life without greenfield capital commitment. |
| Specialized Alloy Supply Security | Upstream control over nickel-based materials mitigates fabrication bottlenecks for supercritical units. |
| Hybrid Biomass Co-firing Development | Combustion system modifications address California and New York renewable portfolio compliance requirements. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, and aftermarket service heads underwrites the qualitative findings. Primary interviews with boiler procurement managers at investor-owned utilities and petrochemical operators combined with secondary validation from EIA generation data, FERC interconnection filings, and EPA compliance tracking systems. Bottom-up project pipeline assessment and top-down capacity utilization analysis triangulate market sizing.
Rate-of-change decomposition across fuel source transitions, technology upgrade cycles, and regulatory compliance timelines structures the analytical framework. Segmentation dimensions span boiler type, fuel source, end user category, and technology tier. CAGRs derive from capacity addition schedules and retirement timelines. Forecast inputs incorporate pipeline infrastructure expansion rates and state-level renewable mandate stringency indices.
The model assumes a particular technology adoption path; alternative pathways for carbon capture integration would alter the outlook. Forecasts reflect assumptions regarding EPA enforcement consistency and natural gas price stability. A model refresh is warranted upon material change in federal emission threshold stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
US Power EPC Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Europe Power Rental Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Uzbekistan Power EPC Market