
 US Power EPC Market | 2026-2036
US Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
US Power EPC Market Analytics
NABCEP certification for solar installation supervisors is reorganizing contractor eligibility for utility-scale photovoltaic builds. Bechtel Corporation leverages its nuclear construction heritage to compete for advanced reactor EPC contracts. Kiewit Corporation anchors its position through self-perform capabilities in heavy civil and transmission infrastructure. Fluor Corporation differentiates via modular fabrication strategies that reduce field labor exposure on remote generation sites.
US Power EPC encompasses the integrated engineering, procurement, and construction of electricity generation, transmission, and distribution infrastructure, typically executed under lump-sum turnkey or cost-reimbursable contracts with performance guarantees spanning 20-30 year asset lifecycles. Procurement services command disproportionate margin pools as equipment lead times for large transformers and gas turbines extend beyond 24 months, while solar and wind technology segments absorb the fastest-growing share of contracted gigawatts as developer pipelines shift from thermal baseload to variable renewable resources. Mega projects exceeding 1,000 MW dominate capital deployment volumes, though small and medium scale distributed solar plus storage configurations are expanding order frequency among corporate off-takers seeking behind-the-meter solutions.
FERC Order 2023 interconnection queue reforms and EPA greenhouse gas performance standards for new gas-fired plants are tightening project development timelines and technology selection criteria for EPC bidders. NERC CIP cybersecurity standards and OSHA 1926 construction safety protocols add compliance layers that favor contractors with established regulatory affairs infrastructure over emergent market entrants. Stakeholders must monitor interconnection cost allocation rulings and state-level renewable portfolio standard accelerations to anticipate where EPC backlog quality will concentrate.
Market Dynamics
Interconnection queue congestion and transformer lead-time extension are compressing project delivery schedules and forcing EPC contractors to pre-position procurement resources before final investment decisions close.
Growth Catalysts
- Inflation Reduction Act production tax credits:Domestic content bonuses redirect developer capital toward US-manufactured solar modules and battery cells, expanding contractor backlogs for integrated clean energy builds.
- Data center load growth in Northern Virginia and Dallas-Fort Worth:Hyperscale operators commit to multi-gigawatt capacity additions requiring dedicated substations and transmission upgrades.
- Modular construction methods:Off-site fabrication of power island components reduces field labor exposure and accelerates commissioning timelines for remote generation sites.
Market Restraints
- Large power transformer supply concentration:Domestic manufacturing capacity for 500 kV+ units remains constrained to three qualified suppliers, extending delivery windows beyond thirty months.
- Copper and electrical steel price volatility:Raw material input swings compress fixed-price contract margins before procurement hedges activate.
- EPA greenhouse gas performance standards:New source performance limits for gas-fired baseload plants restrict technology selection and extend environmental permitting timelines.
Strategic Opportunities
- Advanced reactor EPC specialization:SMR and microreactor demonstration programs create first-mover positioning for contractors with nuclear construction heritage and NRC licensing experience.
- Texas ERCOT interconnection reform:FERC Order 2023 implementation accelerates queue processing for battery storage hybrids, opening fast-cycle EPC awards.
- Behind-the-meter corporate procurement:Distributed solar-plus-storage configurations for industrial off-takers expand order frequency outside traditional utility-scale channels.
Industry Challenges
- NABCEP-certified solar installation supervisor scarcity:Utility-scale photovoltaic workforce gaps delay field mobilization and quality assurance sign-offs.
- NERC CIP cybersecurity compliance integration:Critical infrastructure protection standards add design-review layers that extend engineering schedules and require specialized contractor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Power EPC Market |
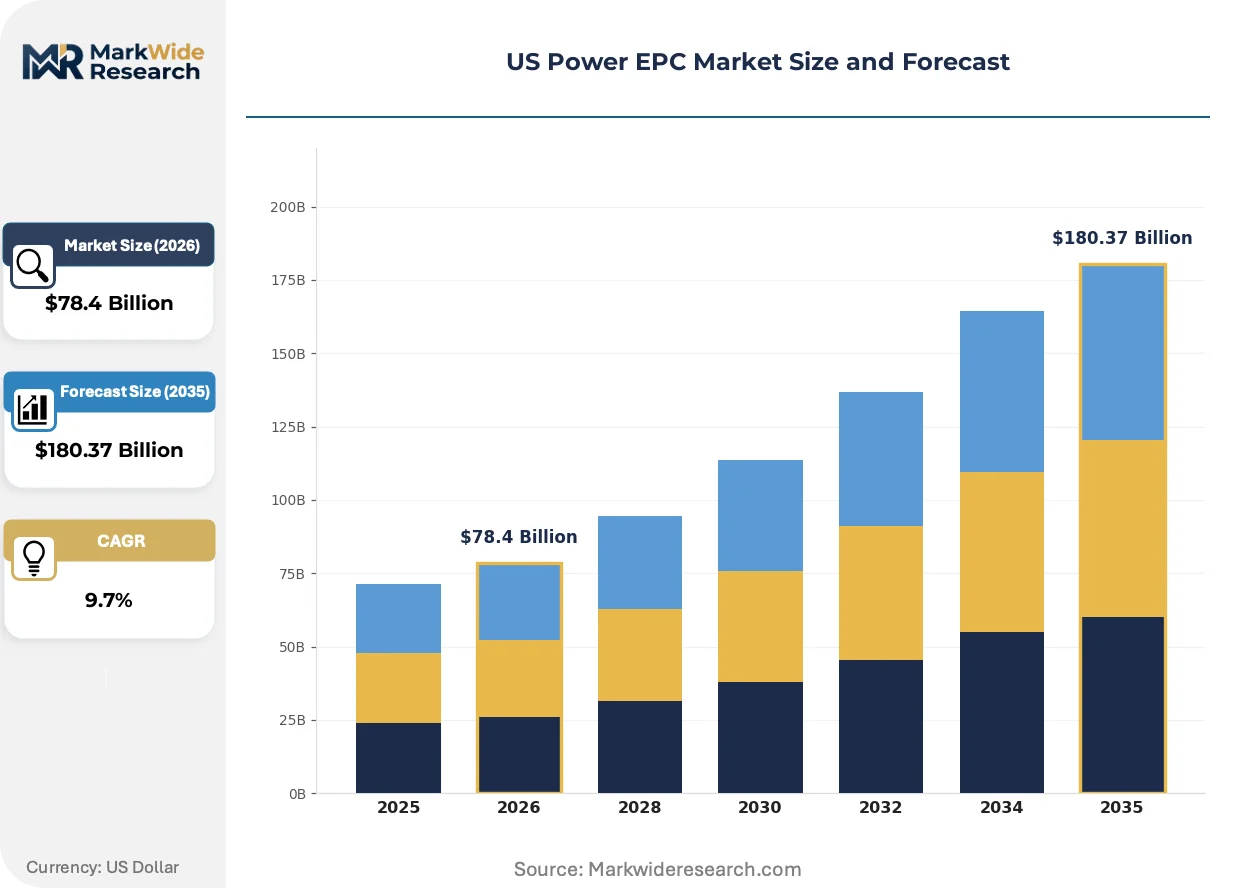
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Technology: Solar, Wind, Hydro, Thermal End User: Utilities, Corporations, Governments, Independent Power Producers |
| Companies Covered | Siemens Energy, AECOM, Bechtel Corporation, Burns & McDonnell, Black & Veatch Holdings, Fluor Corporation, Kiewit Corporation, John Wood Group, Jacobs Engineering Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Power EPC Market Evolving Landscape
Digital twin modeling and predictive maintenance platforms are compressing commissioning timelines and reshaping how EPC contractors guarantee long-term asset performance.
Prefabricated electrical buildings (e-houses) equipped with medium-voltage switchgear and control systems are supplanting traditional stick-built substation construction. Data center developers in Virginia and Texas specify factory-integrated packages to compress site schedules. This technology is supplanting conventional civil-intensive approaches and enabling parallel workstreams that reduce critical path duration by forty percent.
FERC Order 2023 mandates cluster study reforms and cost allocation transparency for interconnection requests. The rule compresses queue processing timelines but requires developers to post higher financial commitments earlier. PJM-interconnected projects face the most significant procedural adaptation as the regional transmission organization implements new readiness criteria.
Corporate off-takers now procure engineering and construction services separately from equipment supply, unbundling the traditional lump-sum turnkey model. This pattern concentrates risk with balance-sheet buyers while EPC contractors compete on construction-only scopes. The shift is most visible in Texas ERCOT and California CAISO territories where sophisticated energy buyers dominate renewable procurement.
US Power EPC Market Segmentation
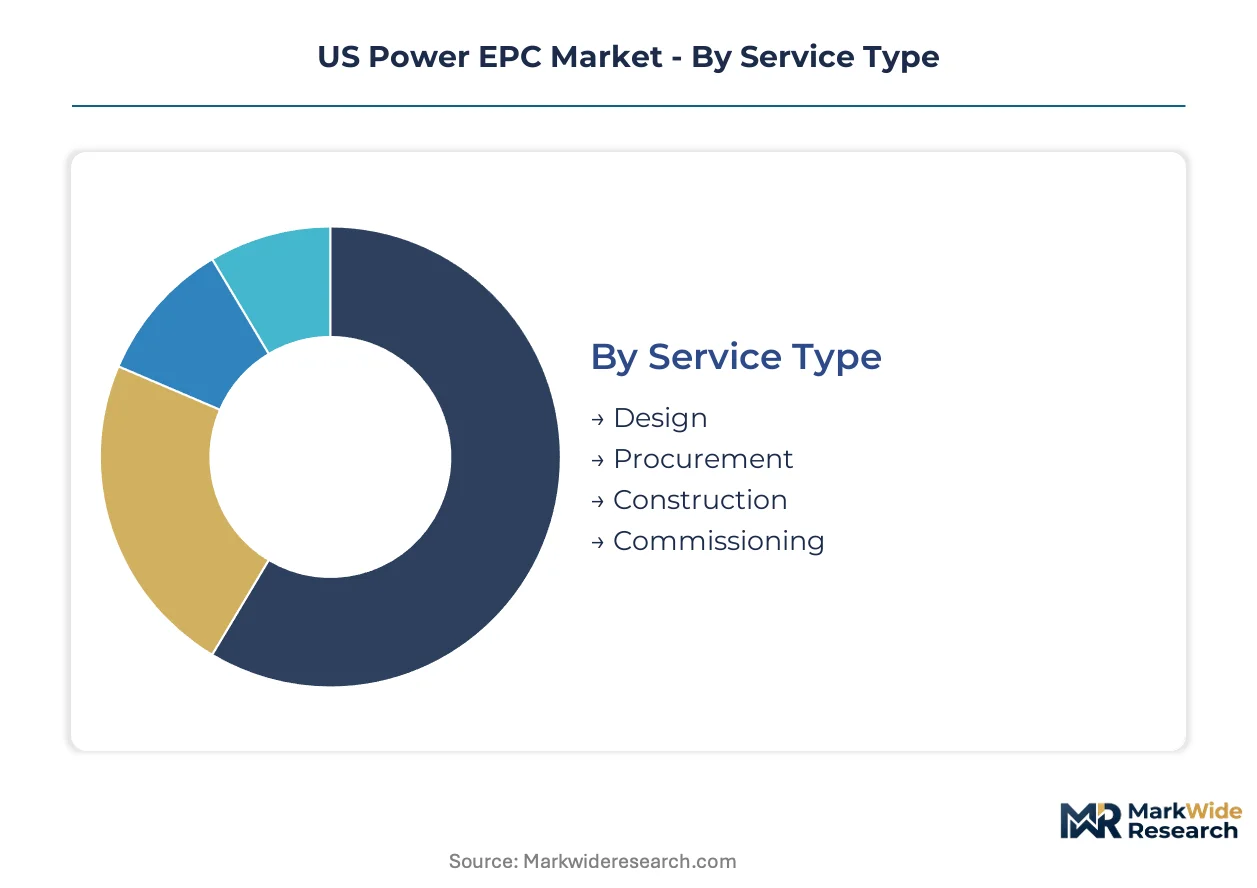
US Power EPC contractors configure service delivery and risk allocation differently across segment boundaries. Procurement-heavy scopes concentrate margin in design-build channels, while construction-only awards dominate in unbundled corporate procurement. Understanding segment-specific contracting patterns clarifies where backlog quality and pricing power concentrate.
Service Type:
Channel mix varies sharply across service categories, with procurement functions capturing disproportionate margin pools due to equipment lead-time risk and supplier relationship leverage.
- Design:Front-end engineering packages establish performance guarantees and technology selection criteria that cascade through subsequent construction phases. Front-end engineering concentrates in ERCOT and PJM territories where interconnection studies require specialized transmission modeling.
- Procurement:Equipment sourcing commands extended delivery windows for large transformers and gas turbines, with domestic content bonuses under IRA production tax credits redirecting supplier selection toward US-manufactured solar modules and battery cells. Procurement services absorb the greatest margin compression risk under fixed-price contracts.
- Construction:Field execution scales with project size and technology type, with solar photovoltaic installation facing NABCEP-certified supervisor constraints that delay mobilization timelines. Self-perform capabilities in heavy civil and transmission infrastructure differentiate contractor competitiveness.
- Commissioning:System integration and performance testing validates 20-30 year asset guarantees, with digital twin modeling compressing acceptance protocols. Cybersecurity validation under NERC CIP standards adds compliance layers that favor established regulatory affairs infrastructure.
Procurement dominates installed base margin capture. Commissioning is where technology differentiation and long-term service attachment concentrate.
Project Size:
Cost tier stratification determines contractor eligibility, with balance sheet requirements and bonding capacity filtering participation across scale thresholds.
- Small Scale:Distributed solar-plus-storage configurations for industrial off-takers, typically sub-10 MW. Corporate procurement unbundling expands order frequency outside traditional utility channels in Texas ERCOT and California CAISO territories.
- Medium Scale:Commercial and industrial behind-the-meter solutions requiring dedicated substations but not transmission-level interconnection. Medium-scale projects face compressed development timelines as hyperscale data center load growth accelerates procurement cycles in Northern Virginia and Dallas-Fort Worth.
- Large Scale:Utility-scale generation and transmission infrastructure exceeding 100 MW, executed under lump-sum turnkey or cost-reimbursable contracts with performance guarantees. Large-scale thermal projects confront EPA greenhouse gas performance standards that restrict technology selection and extend environmental permitting timelines.
- Mega Projects:Multi-gigawatt developments exceeding 1,000 MW that dominate capital deployment volumes and require consortium structures to distribute execution risk. Mega project awards concentrate among contractors with nuclear construction heritage and NRC licensing experience for advanced reactor opportunities.
Mega projects dominate capital deployment volumes. Small and medium scale distributed configurations are expanding order frequency fastest among corporate off-takers.
Technology:
Application-driven segmentation aligns contractor capabilities with technology-specific engineering requirements and regulatory frameworks.
- Solar:Utility-scale photovoltaic builds absorb the fastest-growing share of contracted gigawatts as developer pipelines shift from thermal baseload to variable renewable resources. NABCEP certification requirements for installation supervisors create workforce bottlenecks that delay field mobilization and quality assurance sign-offs.
- Wind:Onshore and offshore turbine installation requiring specialized heavy-lift equipment and marine logistics coordination. Wind EPC faces extended environmental permitting timelines and avian impact assessments that compress construction windows.
- Hydro:Conventional and pumped storage development constrained by federal licensing requirements and environmental review protocols. Hydro construction leverages civil engineering capabilities transferable from heavy infrastructure portfolios.
- Thermal:Gas-fired peaking and baseload plants facing EPA new source performance limits that restrict technology selection and extend development timelines. Combined cycle configurations require long-lead procurement of gas turbines with delivery windows exceeding twenty-four months.
Thermal dominates legacy installed base. Solar and wind are climbing the fastest as IRA production tax credits redirect developer capital toward clean energy construction.
End User:
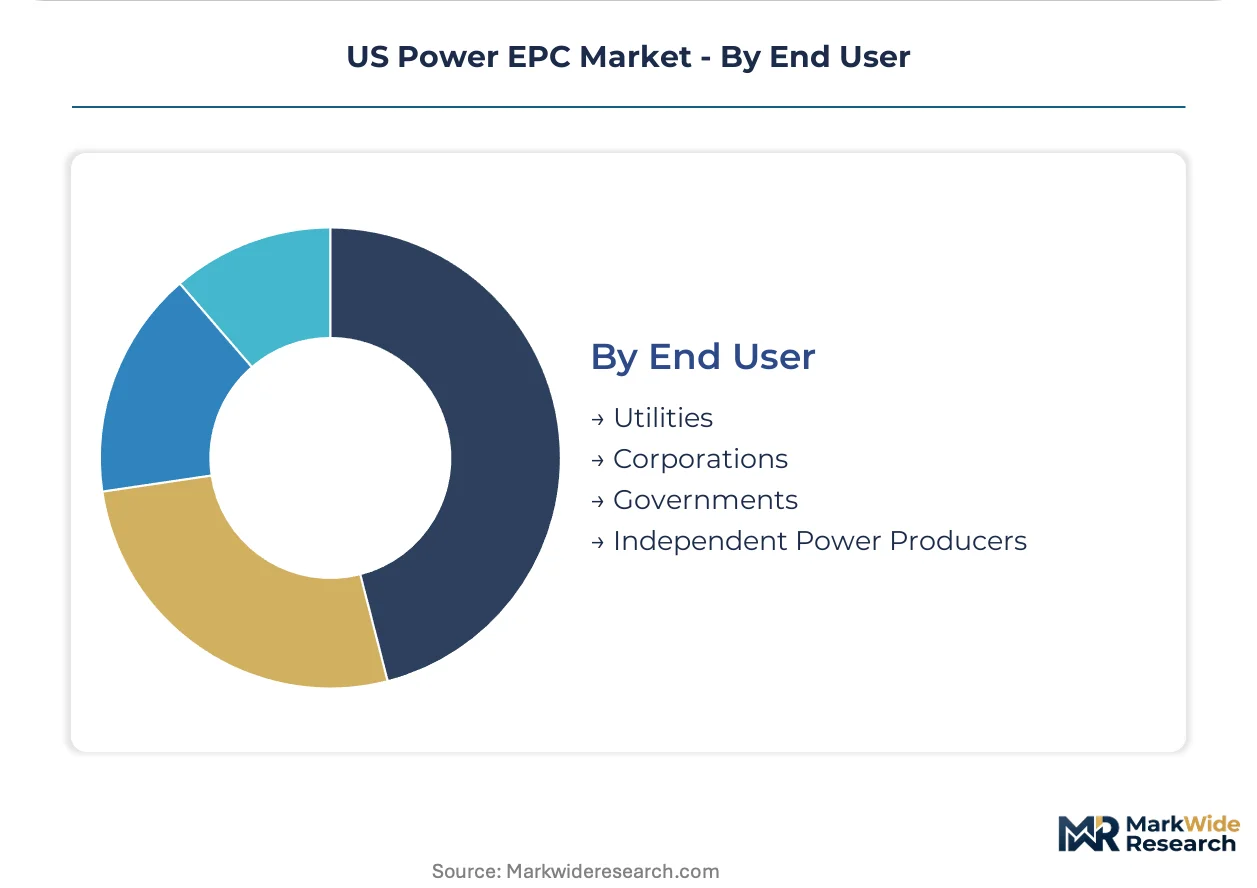
Customer type determines contracting structure, with balance sheet strength and procurement sophistication shaping risk allocation between EPC and offtake parties.
- Utilities:Investor-owned and public power entities executing integrated resource plan mandates under state renewable portfolio standards. Utility procurement favors established contractors with demonstrated regulatory compliance infrastructure and NERC CIP cybersecurity capabilities.
- Corporations:Hyperscale data center operators and industrial off-takers procuring dedicated generation and transmission capacity to meet sustainability commitments and load growth. Corporate buyers in Northern Virginia and Dallas-Fort Worth now unbundle engineering and construction services from equipment supply, concentrating construction risk with EPC contractors.
- Governments:Federal, state, and municipal entities procuring public power infrastructure with prevailing wage and domestic content requirements. Government awards prioritize contractors with established safety protocols and OSHA 1926 compliance track records.
- Independent Power Producers:Merchant developers and financial sponsors executing project finance structures that transfer completion risk to EPC counterparties. IPP procurement concentrates in ERCOT-served Texas where interconnection queue reform under FERC Order 2023 accelerates battery storage hybrid awards.
Utilities dominate traditional procurement volumes. Corporations are gaining share fastest as data center load growth and unbundled contracting expand addressable market scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA production tax credits and FERC interconnection reforms are redrawing capital deployment patterns across US sub-regions, concentrating EPC award velocity in states with streamlined permitting and transmission access.
Texas
ERCOT interconnection queue reform under FERC Order 2023 accelerates battery storage hybrid approvals. The state lacks a traditional renewable portfolio standard, yet IRA domestic content bonuses attract multi-gigawatt solar-plus-storage developments. Dallas-Fort Worth anchors data center load growth requiring dedicated substations and 345 kV transmission loops.
Virginia
PJM interconnection studies create specialized demand for transmission modeling expertise. The Virginia Clean Economy Act mandates carbon-free electricity by 2050, compressing utility procurement timelines. Northern Virginia's Loudoun and Prince William counties host hyperscale data center clusters driving substation and switching station construction.
California
CAISO resource adequacy requirements and distributed solar mandates expand behind-the-meter EPC opportunities. The California Energy Commission enforces Title 24 building energy codes that integrate battery storage into new commercial construction. The Central Valley and Imperial Valley concentrate utility-scale photovoltaic development on retired agricultural land.
Southeast
Georgia Power's integrated resource plan and Duke Energy's carbon reduction targets redirect capital toward solar and storage. State public service commissions in Georgia, North Carolina, and South Carolina approve accelerated renewable procurement schedules. The Savannah River Valley and Piedmont Crescent emerge as data center expansion corridors requiring 500 kV transmission upgrades.
Southwest
Arizona and New Mexico renewable portfolio standards and federal land access for utility-scale solar concentrate EPC activity. The Bureau of Land Management's Western Solar Plan streamlines permitting on designated development zones. Maricopa County and Doña Ana County host the fastest-growing utility-scale photovoltaic pipelines outside California and Texas.
US Power EPC Market Competitive Landscape
Player mix skews toward integrated engineering-construction conglomerates with self-perform capabilities in heavy civil and transmission infrastructure. The vendor base separates into three tiers: full-service EPCs with nuclear construction heritage, mid-scale specialists in renewable integration, and construction-only contractors serving unbundled corporate procurement. Dominant competitive moves include modular fabrication investments and strategic partnerships with domestic transformer manufacturers.
Among full-service EPCs with nuclear construction heritage, Bechtel Corporation, Fluor Corporation, and Kiewit Corporation exemplify the archetype positioning for advanced reactor and utility-scale renewable opportunities. These contractors anchor their market presence through established regulatory affairs infrastructure, NERC CIP cybersecurity compliance capabilities, and demonstrated performance under lump-sum turnkey contracts with 20-30 year asset guarantees. Their positioning reflects decades of federal project execution and self-perform labor force scale that emergent competitors cannot readily replicate.
| Leading Market Players |
|---|
| Siemens Energy |
| AECOM |
| Bechtel Corporation |
| Burns & McDonnell |
| Black & Veatch Holdings |
| Fluor Corporation |
| Kiewit Corporation |
| John Wood Group |
| Jacobs Engineering Group |
| Others |
Value Network & Pricing Analysis
Thirty-month delivery windows for 500 kV+ transformers compress procurement timelines and concentrate pricing power among three domestic suppliers, while copper and electrical steel volatility feeds directly into fixed-price contract renegotiation cycles.
Pricing Analysis
Project scale and NABCEP certification density create the primary spread between premium EPC rates and construction-only bids. Lump-sum turnkey contracts for mega projects command substantial risk premiums over unbundled corporate procurement, where sophisticated data center buyers in Northern Virginia and Dallas-Fort Worth now separate engineering from construction scopes. Pricing pressure stems from raw material input swings before procurement hedges activate, with independent power producers in ERCOT territories exhibiting greatest price sensitivity due to merchant exposure.
Supply Chain Analysis
Extended transformer lead times force EPC contractors to pre-position procurement resources before financial close. Large power equipment manufacturing concentrates in the United States, Germany, and Japan, while solar module sourcing draws from Southeast Asian facilities qualifying for IRA domestic content bonuses. Single-source vulnerability runs through 500 kV+ transformer supply, with distribution flowing through manufacturer-direct and authorized distributor channels to project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unbundled corporate procurement and FERC Order 2023 interconnection reforms fragment traditional utility-scale channels, creating specialized niches for contractors with modular fabrication capabilities and NRC licensing experience.
For Market Incumbents: Consolidate self-perform capabilities in heavy civil and transmission infrastructure to defend against mid-scale specialists capturing renewable integration awards. Anchor procurement relationships with domestic transformer manufacturers to secure allocation priority during supply crunches. Deepen regulatory affairs infrastructure around NERC CIP cybersecurity compliance as a differentiator against emergent entrants lacking federal project execution track records. For New Entrants and Emerging Players: Anchor in behind-the-meter distributed solar-plus-storage configurations for industrial off-takers in Texas ERCOT and California CAISO territories, where unbundled procurement patterns lower barriers to construction-only participation. Target NABCEP-certified workforce development partnerships as a go-to-market angle to accelerate field mobilization timelines that delay incumbent project starts. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because IRA production tax credits and data center load growth sustain capital deployment velocity through interconnection queue cycles. Acquisition candidates with modular fabrication investments and established OSHA 1926 safety protocols offer defensive positioning. Watch FERC cost allocation rulings as the signal for where backlog quality will concentrate.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Investment | Off-site power island construction reduces field labor exposure and compresses commissioning timelines for remote generation sites. |
| Domestic Transformer Supply Agreement | Long-term allocation contracts with qualified 500 kV+ manufacturers secure delivery priority during extended lead-time periods. |
| NRC Licensing Partnership | Collaboration with advanced reactor developers positions contractors for SMR and microreactor demonstration program awards. |
| NABCEP Workforce Development | Certified solar installation supervisor pipelines accelerate utility-scale photovoltaic field mobilization and quality assurance sign-offs. |
| Digital Twin Platform Integration | Predictive maintenance capabilities reshape long-term asset performance guarantees and service attachment revenue streams. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions after combining primary interviews with secondary validation through EIA data, FERC filings, IEA reports, and project development databases. Bottom-up capacity build estimates and top-down capital deployment assessments were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled include fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type across the analysis window. CAGRs were derived from installed base evolution and replacement demand patterns, incorporating interconnection queue velocity, IRA production tax credit uptake curves, and data center load growth trajectories as energy-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained interconnection reform implementation and stable raw material pricing; material deviation would warrant model refresh. Specific project timing, regulatory delays, or supply chain disruptions could revise trajectories substantially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Induction Heating System Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Air Preheater Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Romania Power EPC Market