
 South America Nuclear Power Plant Equipment Market | 2026-2036
South America Nuclear Power Plant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nuclear Power Plant Equipment Market Analytics
The specialized welding and reactor vessel fabrication labor pool is bifurcating between legacy fossil-energy technicians and certified nuclear-grade specialists. GE Hitachi Nuclear Energy leverages its BWR technology portfolio to sustain engineering partnerships across Argentine and Brazilian utilities. Centrais Elétricas Brasileiras anchors domestic demand through its stewardship of the Angra complex and planned capacity additions. Mitsubishi Heavy Industries competes on steam turbine generator integration for Latin American retrofit campaigns.
South America nuclear power plant equipment encompasses reactor pressure vessels, steam generators, control rod drive mechanisms, and containment structures engineered to ASME Section III and RCC-M standards with design pressures exceeding 17 MPa and radiation tolerance thresholds. This equipment sustains baseload electricity generation while enabling isotope production for medical and industrial applications. Pressurized Water Reactor systems dominate installed capacity and capture the bulk of maintenance expenditure across the region's operating fleet. Safety Systems segments attract accelerated investment following post-Fukushima regulatory upgrades. Control Systems represent the fastest-growing category as digital instrumentation and control retrofits replace analog architectures in aging Brazilian and Argentine units.
Argentina's Autoridad Regulatoria Nuclear enforces construction and operating license standards that shape vendor qualification timelines, while Brazil's Comissão Nacional de Energia Nuclear mandates quality assurance protocols for fuel handling and radioactive waste equipment. International Atomic Energy Agency safeguards and ISO 19443 nuclear quality standards further condition procurement eligibility for foreign suppliers. Stakeholders must monitor regulatory divergence between Mercosur member states as Argentina pursues SMR development and Brazil evaluates large-scale reactor completion.
Market Dynamics
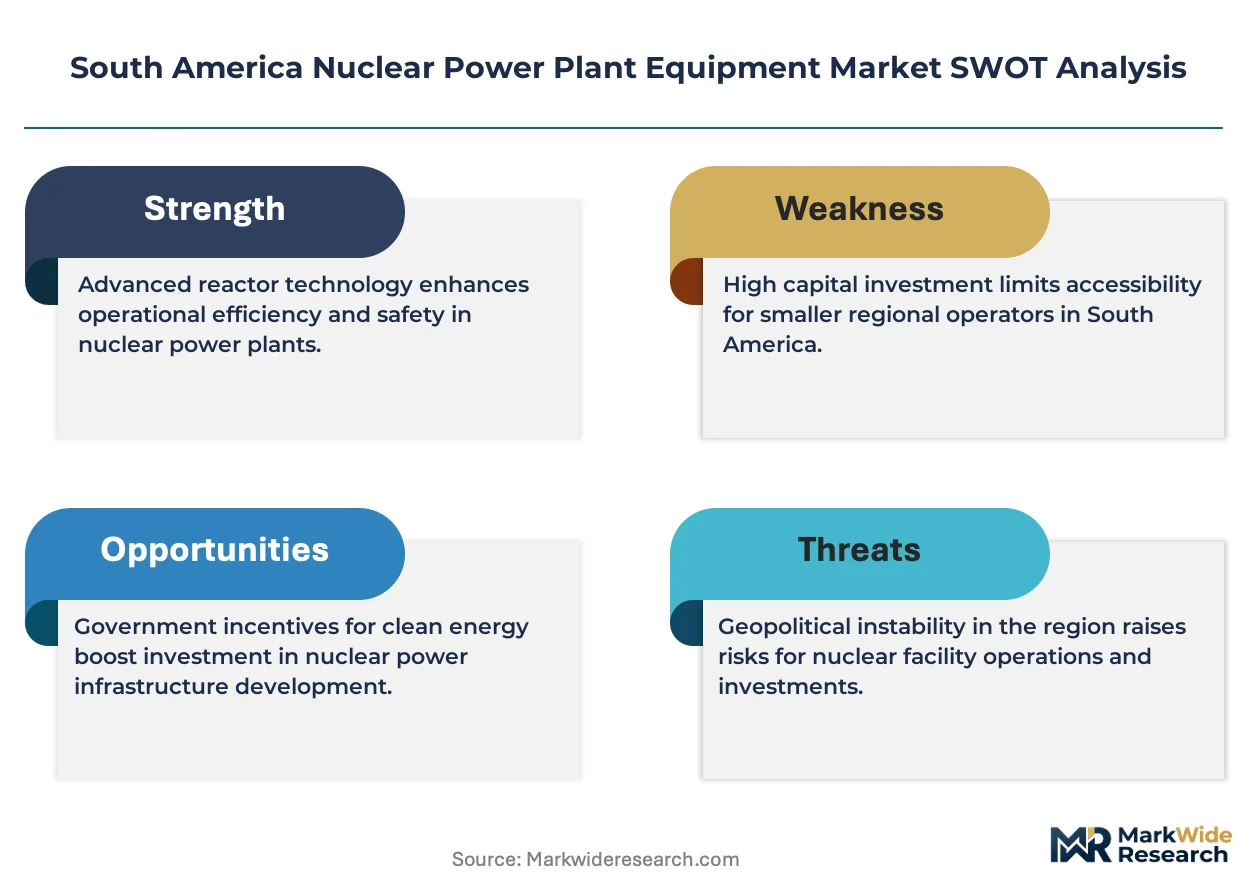
Argentina's Autoridad Regulatoria Nuclear is accelerating small modular reactor licensing frameworks while Brazil's Comissão Nacional de Energia Nuclear evaluates completion of Angra Unit 3, creating divergent procurement timelines across Mercosur nuclear programs.
Growth Catalysts
- SMR Regulatory Pathways:Argentina's national nuclear regulator has established construction permit frameworks for CAREM-25 small modular reactors, enabling domestic fabrication opportunities for pressure vessel suppliers.
- Industrial Decarbonization Mandates:Brazil's southeastern manufacturing corridor faces carbon intensity caps from state environmental agencies, directing steel and petrochemical facilities toward nuclear-powered process heat.
- Isotope Production Infrastructure:Argentina's INVAP and Brazil's IPEN are expanding research reactor fleets to capture global medical isotope supply gaps, requiring specialized target handling equipment.
Market Restraints
- Specialized Alloy Supply Concentration:SA508 Grade 3 forged steel for reactor pressure vessels depends on mills in Japan, France, and South Korea, exposing Argentine and Brazilian projects to 18-24 month lead times.
- Foreign Exchange Volatility:Equipment contracts denominated in euros and yen create procurement cost uncertainty for Centrais Elétricas Brasileiras and Nucleoeléctrica Argentina amid peso and real depreciation cycles.
- Legacy Grid Interconnection:Brazil's transmission infrastructure in the northeast lacks capacity to evacuate power from prospective nuclear sites, constraining greenfield development outside the existing Angra corridor.
Strategic Opportunities
- Chilean Market Entry:Chile's Ministry of Energy has commissioned feasibility studies for nuclear deployment by 2035, creating first-mover positioning for Argentine SMR vendors with regional licensing familiarity.
- Digital Instrumentation Retrofit:Brazil's aging Angra I and II units require replacement of analog control systems with digital architectures, opening upgrade contracts for reactor protection system integrators.
- Heavy Manufacturing Localization:Argentina's Industria Argentina nuclear component certification program offers tariff advantages for domestic fabrication of steam generator tube sheets and pressurizer vessels.
Industry Challenges
- ASME Section III Welder Certification:The pool of qualified nuclear-grade welders in São Paulo and Buenos Aires provinces remains insufficient for concurrent construction campaigns, forcing utilities to import Brazilian-Argentine dual-national technicians from overseas projects.
- IAEA Safeguards Integration:Equipment vendors must reconcile Argentina's bilateral safeguards agreements with Brazil's quadripartite accounting protocols, complicating cross-border component tracking for shared reactor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nuclear Power Plant Equipment Market |
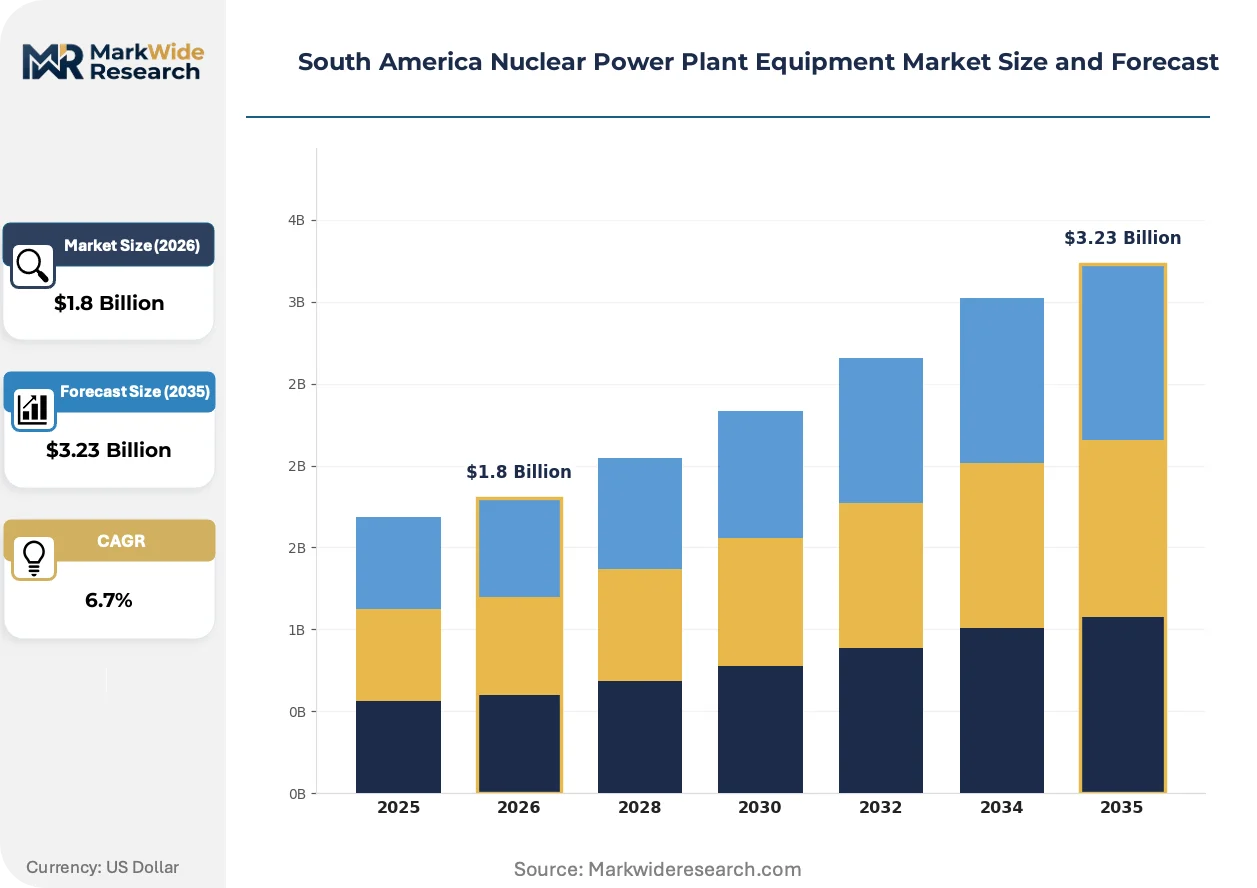
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Reactor Systems, Turbine Generators, Safety Systems, Control Systems Application: Power Generation, Research, Medical, Industrial End User: Utility Companies, Government Agencies, Research Institutions, Industrial Facilities Technology: Pressurized Water Reactor, Boiling Water Reactor, Fast Breeder Reactor, Advanced Gas-cooled Reactor |
| Companies Covered | Dongfang Electric Corporation, GE Hitachi Nuclear Energy, China National Nuclear Corporation, BWX Technologies, Mitsubishi Heavy Industries, Rosatom State Atomic Energy Corporation, Centrais Elétricas Brasileiras, ALSTOM, Westinghouse Electric Company, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nuclear Power Plant Equipment Market Evolving Landscape
Digital twin deployment is compressing reactor commissioning schedules while modular construction techniques reshape site logistics. Vendors are repositioning around integrated plant delivery models that bundle engineering with long-term fuel services.
Small modular reactor technology is miniaturizing. CAREM-25 units under development in Argentina employ integrated primary system designs that eliminate large-bore piping. Argentine utilities are evaluating these configurations for distributed deployment in Patagonia's isolated grid zones. The technology is miniaturizing capital requirements per megawatt, enabling provincial governments to sponsor nuclear projects without federal treasury guarantees.
Brazil's Comissão Nacional de Energia Nuclear has mandated digital instrumentation and control upgrades for all operating pressurized water reactors by 2028. This regulatory pressure is forcing analog system obsolescence across Angra I and II. Control system integrators are responding with phased retrofit architectures that maintain reactor availability during transition periods.
Utility procurement departments are consolidating vendor qualification under single-source framework agreements. Brazilian and Argentine operators are replacing transaction-based equipment purchasing with decade-long maintenance and modification contracts. This consolidation is most visible in steam generator tube bundle replacement campaigns, where Centrais Elétricas Brasileiras has shifted from competitive tendering to sole-source partnerships with qualified fabricators.
South America Nuclear Power Plant Equipment Market Segmentation
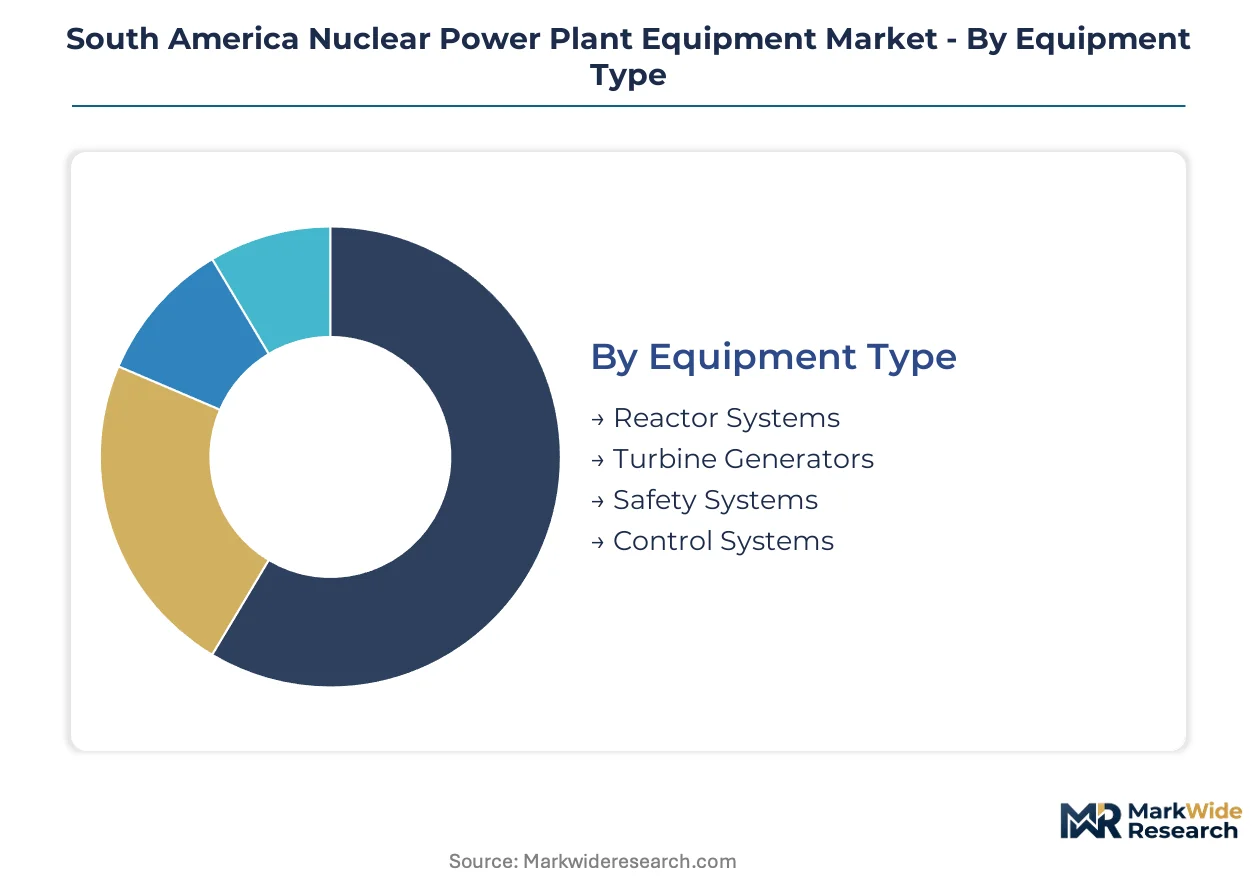
Equipment procurement patterns in South America diverge sharply between regulated utility frameworks and research-driven institutional buyers. Understanding these channel distinctions enables vendors to align certification investments with actual purchase authority and technical specifications.
Equipment Type:
Reactor pressure vessels and steam generators move through long-cycle utility procurement channels requiring ASME Section III stamping, while digital control systems increasingly route through specialized system integrators serving retrofit campaigns.
- Reactor Systems:Reactor pressure vessels, core internals, and vessel head assemblies fabricated from SA508 Grade 3 forged steel with design pressures exceeding 17 MPa. Demand concentrates at Brazil's Angra complex and Argentina's Atucha facility where capacity expansion drives replacement schedules for steam generators and pressurizers.
- Turbine Generators:High-pressure and low-pressure turbine rotors, generator stators, and excitation systems converting thermal energy to grid-synchronous electricity. Procurement flows through Mitsubishi Heavy Industries and GE partnerships at Brazilian utilities, with Argentine operators favoring European turbine suppliers for CAREM-25 integration.
- Safety Systems:Emergency core cooling systems and containment isolation equipment.
- Control Systems:Digital instrumentation and reactor protection platforms replacing analog architectures.
Reactor Systems dominate installed base. Control Systems is where expansion concentrates.
Application:
Cost tiers separate baseload power generation requiring full ASME certification from research and medical applications operating under reduced pressure boundaries.
- Power Generation:Grid-connected electricity production from pressurized and boiling water reactor configurations. Brazil's southeastern industrial corridor anchors regional demand through Centrais Elétricas Brasileiras operations at Angra, with carbon intensity mandates from state environmental agencies directing steel and petrochemical facilities toward nuclear process heat.
- Research:Materials testing, neutron scattering, and reactor physics studies at IPEN and INVAP facilities. Argentina's Bariloche and Buenos Aires research clusters drive specialized target handling equipment procurement for radioisotope precursor production.
- Medical:Molybdenum-99 and iodine-131 production for diagnostic imaging and radiotherapy.
- Industrial:Sterilization, food irradiation, and tracer applications.
Power Generation commands capital expenditure scale. Medical isotope production is expanding most quickly.
End User:
Customer type determines contracting structure — utilities deploy decade-long framework agreements while government agencies operate through sovereign procurement windows.
- Utility Companies:Centrais Elétricas Brasileiras and Nucleoeléctrica Argentina operating commercial reactor fleets under national regulatory supervision. These entities consolidate vendor qualification under single-source partnerships for steam generator tube bundle replacements and digital control retrofits.
- Government Agencies:National nuclear commissions and defense-related atomic energy directorates. Argentina's Comisión Nacional de Energía Atómica channels procurement for CAREM-25 development through domestic fabrication incentives under Industria Argentina certification.
- Research Institutions:IPEN in Brazil and INVAP in Argentina expanding research reactor fleets.
- Industrial Facilities:Mining and petrochemical operations evaluating process heat applications.
Utility Companies anchor procurement volume. Research Institutions are gaining share fastest.
Technology:
Maturity curves separate proven pressurized water designs from developmental small modular configurations requiring modified supply chains.
- Pressurized Water Reactor:Primary coolant systems operating at 15.5 MPa with pressurizers maintaining water inventory. Brazil's Angra I and II units and Argentina's Atucha I and II define regional installed capacity, with Comissão Nacional de Energia Nuclear mandating digital instrumentation upgrades by 2028.
- Boiling Water Reactor:Direct-cycle steam generation eliminating steam generators. GE Hitachi Nuclear Energy sustains engineering partnerships across Argentine utilities for potential BWR deployments, though no operating units exist in South America.
- Fast Breeder Reactor:Sodium-cooled configurations with plutonium breeding blankets.
- Advanced Gas-cooled Reactor:CO2-cooled graphite-moderated designs with limited regional relevance.
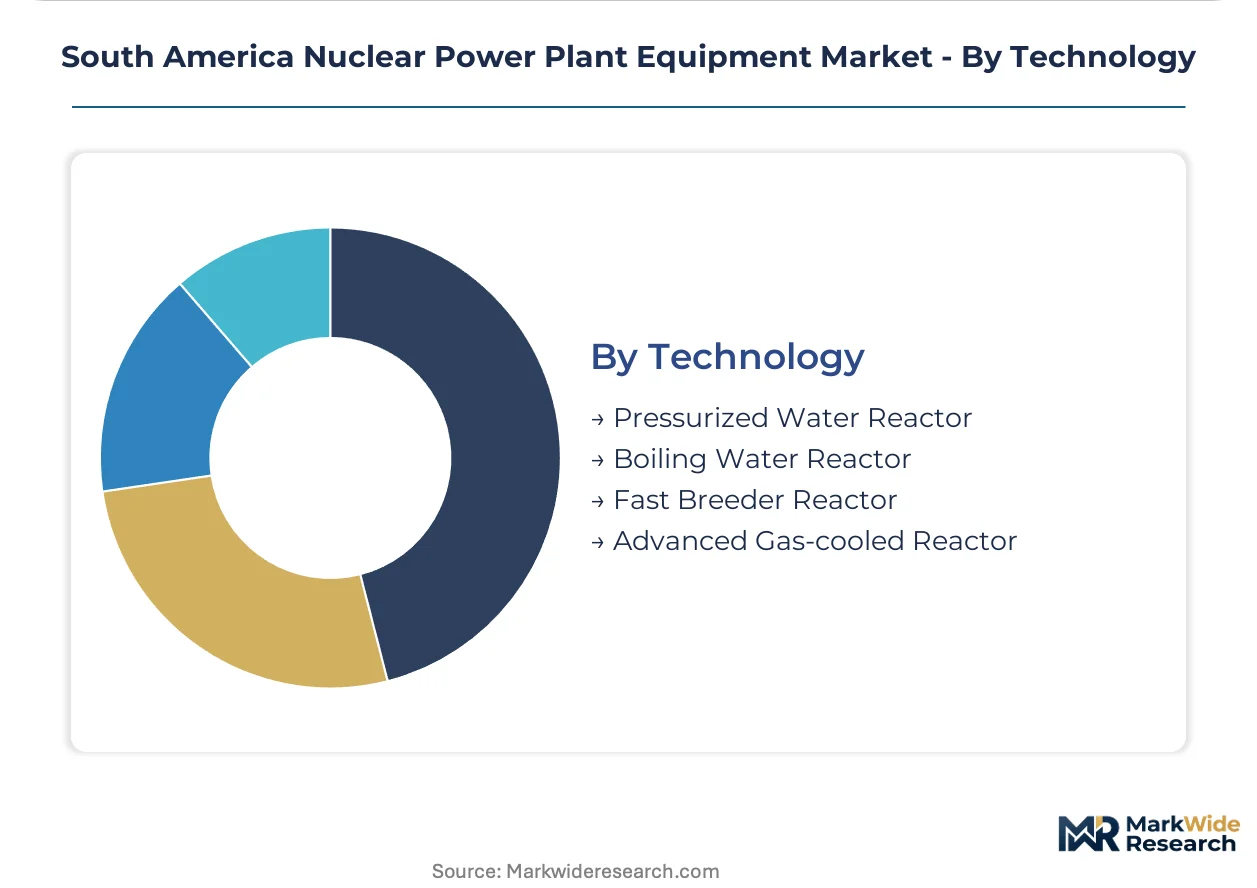
Pressurized Water Reactor dominates installed base. Fast Breeder Reactor is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Comissão Nacional de Energia Nuclear shapes procurement frameworks across Brazil's southeastern industrial corridor, where reactor expansion drives equipment demand. Argentina's Autoridad Regulatoria Nuclear advances parallel licensing pathways for small modular configurations. Chile and Uruguay evaluate nuclear feasibility studies, while Paraguay monitors regional grid integration developments.
Brazil
Centrais Elétricas Brasileiras governs reactor fleet expansion at the Angra complex, with Angra Unit 3 completion under regulatory review. Comissão Nacional de Energia Nuclear mandates digital instrumentation upgrades by 2028, forcing control system replacements across aging pressurized water units. The São Paulo-Rio de Janeiro industrial corridor concentrates fabrication demand for steam generator tube bundles and reactor vessel components.
Argentina
Autoridad Regulatoria Nuclear established construction permit frameworks for CAREM-25 small modular reactors, enabling domestic pressure vessel fabrication. The Industria Argentina certification program channels procurement toward local suppliers for nuclear-grade components. Bariloche and Buenos Aires research clusters anchor isotope production infrastructure expansion, requiring specialized target handling equipment from INVAP facilities.
Chile
Chile's Ministry of Energy commissioned nuclear deployment feasibility studies targeting 2035 operational dates. The national energy commission evaluates grid interconnection requirements for prospective reactor sites in the northern mining regions. Antofagasta and Tarapacá provinces concentrate copper extraction operations that carbon intensity regulations may redirect toward nuclear process heat applications.
Uruguay
Uruguay's national energy directorate assesses bilateral grid integration with Argentine nuclear generation capacity. The state power utility evaluates small modular reactor configurations for baseload supplementation of wind-dominated generation mix. Montevideo anchors policy coordination with Mercosur nuclear regulators on cross-border electricity trade frameworks.
Paraguay
Paraguay's national electricity administration monitors Itaipú Dam output fluctuations and evaluates nuclear baseload alternatives. The public works ministry coordinates with Brazilian regulators on transmission infrastructure planning for regional power pooling. Asunción concentrates administrative capacity for Mercosur energy market integration negotiations.
South America Nuclear Power Plant Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with reactor system vendors and component fabricators occupying distinct competitive positions. The market structure bifurcates between full-scope plant deliverers and qualified suppliers of pressure vessels, steam generators, and digital control platforms. Strategic archetypes include state-backed integrated energy corporations, specialized heavy manufacturing conglomerates, and nuclear technology licensing specialists. Competitive positioning depends on forging decade-long maintenance partnerships and securing regulatory qualification across multiple national frameworks.
Within the state-backed integrated tier, China National Nuclear Corporation and Rosatom State Atomic Energy Corporation represent vertically organized atomic energy complexes with full-scope reactor delivery capabilities. GE Hitachi Nuclear Energy occupies a licensing-focused position, leveraging boiling water reactor technology portfolios to sustain engineering relationships across Latin American utilities. Mitsubishi Heavy Industries exemplifies the heavy manufacturing specialist archetype, competing on steam turbine generator integration for regional retrofit campaigns.
| Leading Market Players |
|---|
| Dongfang Electric Corporation |
| GE Hitachi Nuclear Energy |
| China National Nuclear Corporation |
| BWX Technologies |
| Mitsubishi Heavy Industries |
| Rosatom State Atomic Energy Corporation |
| Centrais Elétricas Brasileiras |
| ALSTOM |
| Westinghouse Electric Company |
| Others |
Value Network & Pricing Analysis
Domestic SA508 Grade 3 forged steel substitution for Japanese and European reactor pressure vessel imports is simultaneously redrawing procurement geography and compressing capital cost structures for Argentine and Brazilian utilities. This input replacement dynamic is forcing equipment vendors to recalibrate margin expectations while national regulators tighten local content thresholds under Industria Argentina certification.
Pricing Analysis
Long-term framework agreements dominate equipment procurement, with Centrais Elétricas Brasileiras and Nucleoeléctrica Argentina consolidating steam generator and control system purchases under decade-long sole-source partnerships rather than competitive tendering. Price differentiation rests on ASME Section III certification tier and after-sales service bundling, with fully certified vendors commanding substantial premiums over qualified-but-unstamped fabricators. Cost compression in digital control retrofits is intensifying because Brazilian regulatory mandates are accelerating analog replacement timelines. Research institutions exhibit highest price sensitivity due to sovereign budget cycles, while utility companies absorb premium pricing for regulatory compliance certainty.
Supply Chain Analysis
Inventory positions for specialized alloy forgings stretch eighteen to twenty-four months, exposing Argentine CAREM-25 and Brazilian Angra Unit 3 timelines to mill scheduling bottlenecks in Japan, France, and South Korea. Raw material flows draw from SA508 Grade 3 steel, Inconel steam generator tubing, and digital control platform semiconductors. Single-source vulnerability concentrates in heavy forging capacity, where only three qualified mills serve global nuclear demand. Distribution runs through national utility procurement departments with direct vendor qualification, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from post-Fukushima procurement freezes, with reactor fleet expansion in Brazil and SMR licensing acceleration in Argentina driving equipment demand cyclically upward.
For Market Incumbents: Compound regulatory qualification advantages by securing dual-framework agreements across Brazilian and Argentine licensing jurisdictions before SMR construction permits finalize. Deepen backward integration into SA508 Grade 3 forging partnerships to offset Japanese and European mill lead time risks. Prioritize digital control system retrofit capacity expansion to capture Angra I and II analog replacement mandates from Comissão Nacional de Energia Nuclear. For New Entrants and Emerging Players: ASME Section III fast-track certification for welders and fabricators opens entry pathways into Argentina's Industria Argentina tariff-advantaged procurement channel. Target Chilean feasibility study phases with SMR-appropriate pressure vessel offerings before 2035 operational targets harden into committed procurement. Lead with integrated digital twin commissioning capabilities to differentiate from legacy analog-era incumbents in Brazilian retrofit campaigns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European heavy manufacturing conglomerates seeking to divest non-core nuclear component divisions amid energy transition portfolio rebalancing. Five-to-ten-year viability hinges on SMR commercialization timelines rather than large-reactor completion economics. Monitor Autoridad Regulatoria Nuclear construction permit issuance velocity as the decisive inflection signal for Argentine fabrication demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Section III Certification Investment | Enables vendor qualification for Brazilian Angra complex and Argentine Atucha expansion procurement. |
| Digital Twin Platform Deployment | Compresses reactor commissioning schedules for CAREM-25 SMR projects in Patagonia. |
| Domestic Forging Partnership | Secures SA508 Grade 3 steel supply under Industria Argentina local content incentives. |
| Long-Term Framework Agreement | Locks in steam generator replacement cycles with Centrais Elétricas Brasileiras. |
| SMR Licensing Pre-Qualification | Positions vendors for Argentine Autoridad Regulatoria Nuclear construction permit awards. |
Research Methodology
Operator-level perspectives from utility procurement officers, nuclear regulatory affairs directors, EPC project managers, and heavy manufacturing fabrication heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through IAEA safeguard implementation reports, national nuclear commission licensing databases, and customs trade records for SA508 Grade 3 steel imports. Bottom-up equipment demand modeling triangulated against top-down national energy plan projections.
Sensitivity analysis tested forecast robustness across SMR deployment scenarios and large-reactor completion alternatives over the projection horizon. Segmentation modeling incorporated equipment type, reactor technology maturity, end-user contracting structure, and national regulatory framework dimensions. CAGRs derived from installed base replacement schedules, capacity expansion announcements, and isotope production infrastructure investments.
The analysis sits within stated boundaries; outcomes outside sustained Argentine-Brazilian regulatory coordination or prolonged alloy supply disruption would require recalibration. Forecasts reflect documented assumptions regarding SMR commercialization timelines and digital retrofit regulatory adherence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
US Power EPC Market
Power Equipment
Qatar Power EPC Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Romania Power EPC Market
Power Equipment
Europe Power Rental Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Germany Power EPC Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Australia Power EPC Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Induction Heating System Market
Power Equipment
Power Equipment Testing Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
Process Air Heater Market