
 Ecuador Power EPC Market | 2026-2036
Ecuador Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Power EPC Market Foresight
Long-term operations and maintenance contracts are decoupling from initial construction bids across Ecuador's power infrastructure sector. Wärtsilä Oyj Abp leverages its thermal technology portfolio to anchor recurring service revenue streams. Siemens AG competes through integrated digital twin platforms that extend plant lifecycle value. Power Construction Corporation of China dominates hydroelectric turnkey delivery through captive engineering resources.
Ecuador Power EPC encompasses the complete engineering, procurement, and construction of electricity generation facilities, typically spanning feasibility studies through commissioning with performance guarantees tied to installed capacity and grid-code compliance. The primary purpose is delivering utility-scale infrastructure under lump-sum contracts with defined completion milestones and operational handover protocols. Hydroelectric installations retain the largest share of awarded contracts given Ecuador's Andean river basin geography, while solar procurement is expanding fastest among technology segments as irradiation mapping improves in coastal provinces. Government end-user contracts command premium pricing due to sovereign guarantee structures, whereas commercial buyers negotiate harder on equipment sourcing transparency.
Ecuador's Ministry of Electricity and Renewable Energy and the National Electricity Regulatory Agency set tariff benchmarks and environmental licensing thresholds that directly determine project bankability timelines. International financing entities impose Equator Principles and IFC performance standards that reshape contractor qualification requirements for cross-border EPC awards. Stakeholders must monitor how proposed amendments to the Public-Private Partnership Law alter risk allocation between foreign constructors and domestic transmission operators.
Market Dynamics
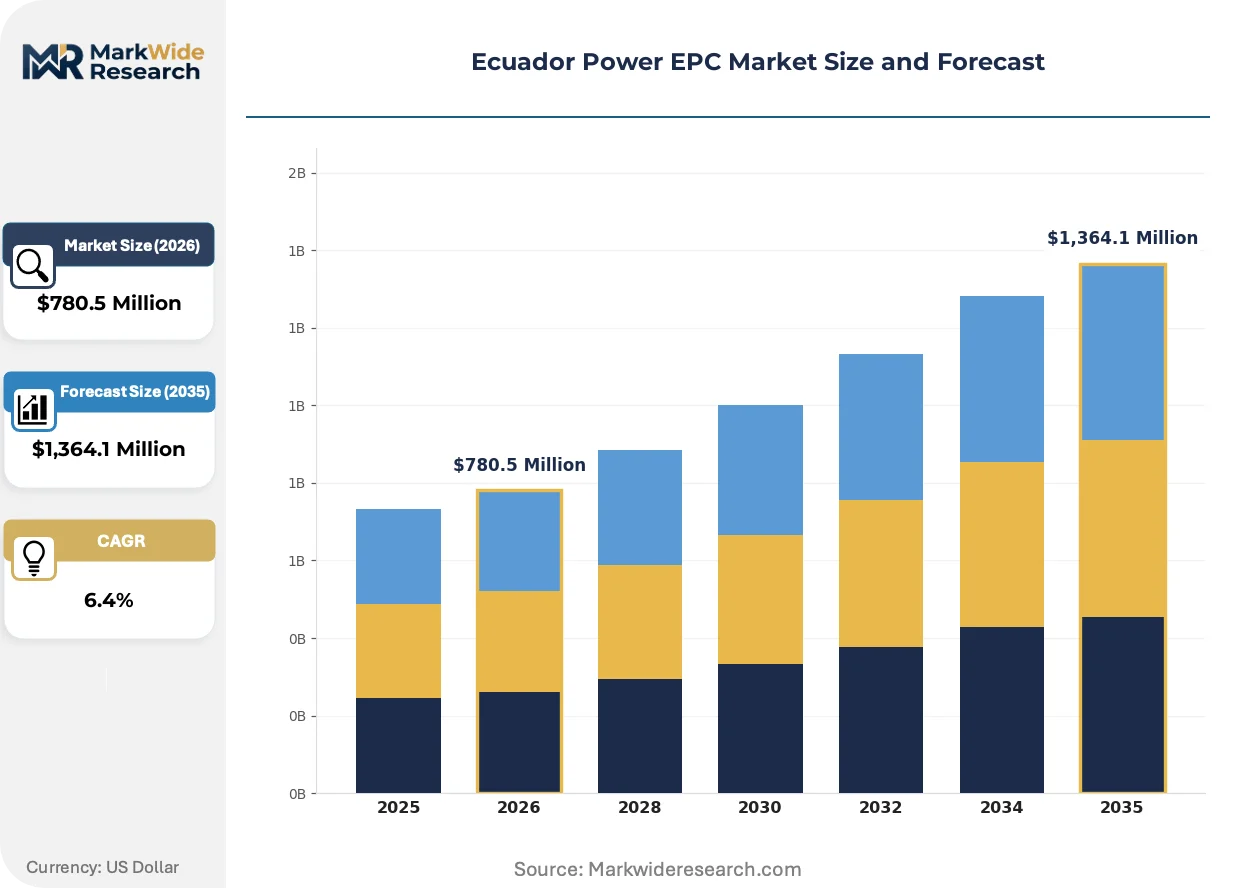
Ecuador's power EPC sector is compressing around state-mandated renewable procurement timelines, with hydroelectric diversification mandates from the Ministry of Electricity and Renewable Energy forcing contractors to restructure delivery models around sovereign-backed payment guarantees rather than commercial risk allocation.
Growth Catalysts
- Coastal Solar Irradiation Mapping:Improved satellite-based resource assessment in Guayas and Santa Elena provinces is unlocking bankable solar EPC pipelines previously classified as marginal. Developers now secure financing against verified capacity factors.
- Public-Private Partnership Law Amendments:Proposed risk-sharing frameworks between foreign constructors and domestic transmission operators reduce sovereign guarantee dependency. International lenders are revising Equator Principles compliance thresholds accordingly.
- Andean Hydroelectric Basins:Ecuador's river geography sustains turnkey demand for run-of-river installations. Captive engineering resources from Chinese contractors dominate this segment through integrated feasibility-to-commissioning delivery.
Market Restraints
- Copper and Steel Input Volatility:Transmission infrastructure and turbine manufacturing face margin compression from London Metal Exchange price swings. EPC lump-sum contracts lack effective pass-through mechanisms for conductor and structural steel.
- Single-Source Turbine Supply:Hydroelectric runners and generators concentrate among European and Chinese original equipment manufacturers. Domestic contractors lack alternative sourcing for Francis and Kaplan turbine specifications.
- Grid-Code Compliance Timelines:National Electricity Regulatory Agency certification protocols extend commissioning schedules. Frequency response and reactive power testing create bottlenecks at substation interconnection points.
Strategic Opportunities
- Amazon Basin Mini-Grid Deployment:Off-grid settlements in Morona Santiago and Zamora Chinchipe provinces require modular solar-diesel hybrid EPC. Remote geography excludes centralized transmission extension.
- Battery Storage Co-Location:Lithium-ion integration with existing thermal and renewable assets addresses evening peak demand. Regulatory frameworks for ancillary services procurement remain under development.
- Digital Twin Lifecycle Contracts:Siemens AG's integrated platform model demonstrates recurring revenue potential beyond construction handover. State utilities are piloting performance-based maintenance agreements.
Industry Challenges
- Specialized Welding and Hydro-Mechanical Installation:Penstock fabrication and turbine assembly require certified technicians. Ecuador's technical training infrastructure produces insufficient pipeline welders and heavy-lift rigging specialists.
- Environmental Licensing Sequencing:Ministry of Environment water-use permits and Ministry of Electricity grid-connection approvals operate on non-synchronized calendars. Project finance drawdown schedules misalign with regulatory milestone achievement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Power EPC Market |
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,364.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning End User: Utilities, Industrial Facilities, Commercial, Government Technology: Hydroelectric, Solar, Wind, Thermal Installation Type: Onshore, Offshore, Grid-Connected, Isolated |
| Companies Covered | Wärtsilä Oyj Abp, Power Construction Corporation of China, Grupo Techint, CEYM International EPC company, SANTOS CMI S.A., Saipem SpA, Bechtel Corporation, Fluor Corporation, Siemens AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Power EPC Market Shifts & Advancements
Digital instrumentation and modular construction methods are compressing EPC delivery timelines while fragmenting traditional turnkey contracts into separable engineering, procurement, and commissioning packages.
Advanced inverter control systems with grid-forming capability are rewriting interconnection standards for variable renewable assets. State utility CNEL EP is mandating these specifications for new solar EPC awards in coastal provinces. The technology is enabling higher renewable penetration without synchronous spinning reserve dependency.
Ecuador's Ministry of Electricity and Renewable Energy is tightening environmental licensing thresholds for hydroelectric diversions. Project developers must now demonstrate minimum ecological flow guarantees through real-time monitoring infrastructure. Run-of-river EPC contracts in the Andean region are absorbing these instrumentation costs into base construction pricing.
Long-term service agreements are decoupling from initial construction bids across government and commercial buyer segments. CNEL EP and regional distribution companies now tender operations and maintenance separately from turnkey EPC, compressing constructor margins on initial awards while extending contract visibility for qualified service providers. This pattern concentrates in Guayaquil corridor solar projects where performance guarantees extend 15-20 years post-commissioning.
Ecuador Power EPC Market Segmentation

Ecuador's power EPC market fragments across service delivery phases, end-user risk profiles, generation technologies, and grid integration architectures. Each dimension reshapes contractor qualification requirements and sovereign guarantee structures.
Service Type:
Supply concentration varies sharply across the EPC value chain, with specialized engineering firms controlling feasibility and design while construction labor pools remain fragmented.
- Design:Front-end engineering packages require hydrological modeling for Andean hydroelectric sites and irradiation mapping for coastal solar corridors. CNEL EP tenders these separately from construction to de-risk project bankability. International engineering consultancies dominate this segment through proprietary simulation software.
- Procurement:Equipment sourcing concentrates among Chinese turbine manufacturers for hydroelectric runners and European inverter suppliers for solar photovoltaic systems. Lump-sum EPC contracts absorb currency hedging costs for imported electromechanical packages.
- Construction:Civil works for dam infrastructure and solar mounting structures draw on regional contractor networks. Penstock welding certification requirements limit qualified bidders for hydroelectric pressure tunnel segments.
- Commissioning:Grid-code compliance testing and performance guarantee validation require certified technicians. National Electricity Regulatory Agency protocols extend handover timelines for frequency response verification.
Construction absorbs the bulk of installed capacity; commissioning is expanding most quickly as performance guarantees decouple from initial build contracts.
End User:
Customer type determines payment guarantee structures and risk allocation frameworks across Ecuador's power infrastructure procurement.
- Utilities:State-owned CNEL EP and regional distribution companies command premium pricing through sovereign-backed payment guarantees. These entities mandate 15-20 year performance guarantees for coastal solar corridor projects.
- Industrial Facilities:Mining operations in the Andean highlands and agro-industrial processors in Guayas province procure captive generation. Commercial risk allocation shifts entirely to contractors without government payment backing.
- Commercial:Shopping centers and logistics facilities in Guayaquil negotiate hard on equipment sourcing transparency. These buyers favor modular solar installations with shorter commissioning windows.
- Government:Ministry of Electricity and Renewable Energy mandates drive hydroelectric diversification in river basins. Public-Private Partnership Law amendments are reshaping risk-sharing between foreign constructors and domestic transmission operators.
Utilities absorb the bulk of installed capacity; industrial facilities are gaining share fastest as mining sector energy demand intensifies.
Technology:
Technology selection tracks Ecuador's river geography and improving coastal irradiation data, with contractor capabilities fragmenting by generation type.
- Hydroelectric:Run-of-river installations dominate awarded contracts given Andean river basin geography. Chinese contractors anchor this segment through integrated feasibility-to-commissioning delivery with captive engineering resources.
- Solar:Photovoltaic procurement is climbing the fastest as satellite-based resource assessment unlocks bankable pipelines in Guayas and Santa Elena provinces. CNEL EP mandates grid-forming inverter specifications for new awards.
- Wind:Onshore wind development remains marginal due to limited wind resource mapping in viable corridors. Early-stage projects concentrate in southern highland provinces with preliminary meteorological tower data.
- Thermal:Natural gas and diesel reciprocating engines address grid stability and isolated settlement demand. Wärtsilä Oyj Abp leverages thermal technology portfolios to anchor recurring service revenue streams beyond initial construction.
Hydroelectric retains the dominant share of historical installed capacity; solar is expanding most rapidly as financing structures mature for coastal corridor development.
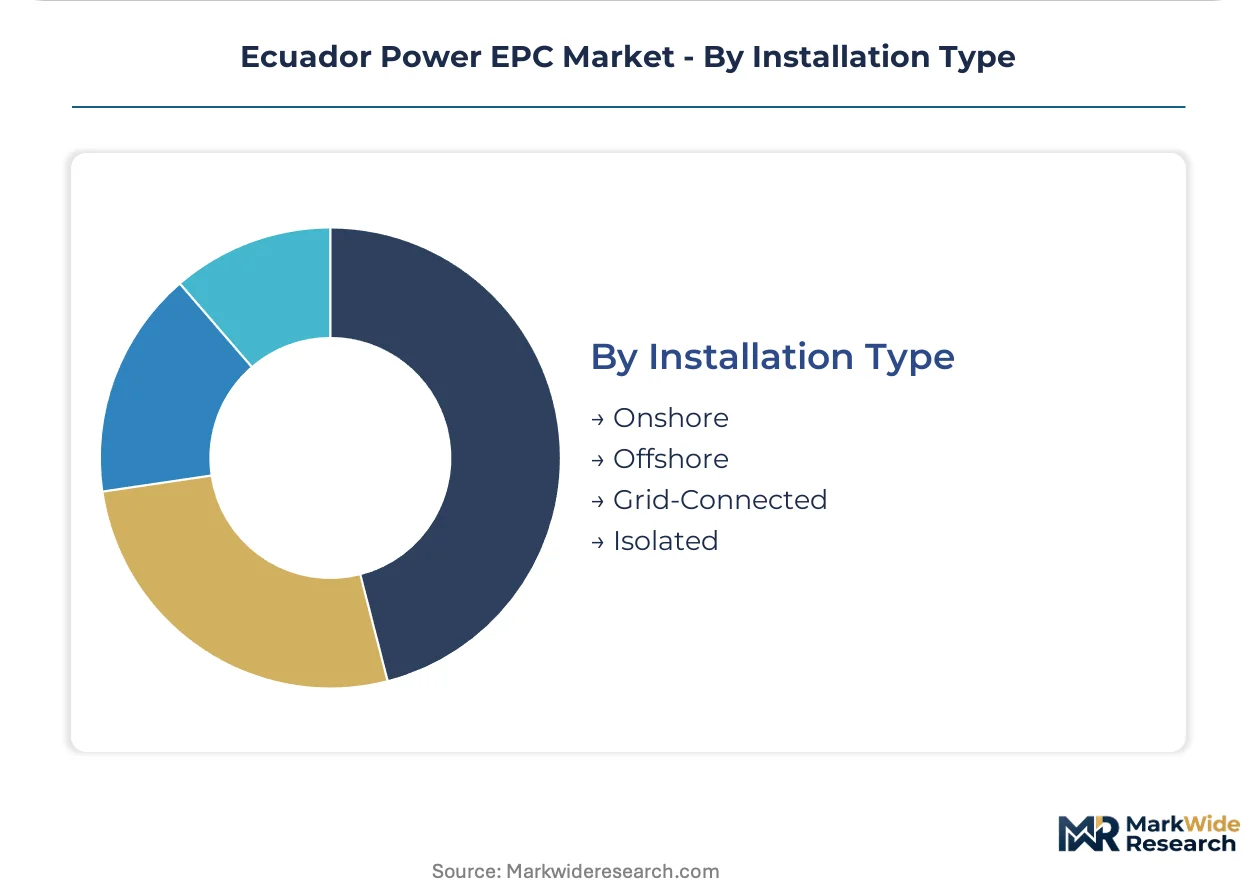
Installation Type:
Grid integration architecture determines transmission access costs and regulatory milestone sequencing for EPC contractors.
- Onshore:Land-based generation facilities comprise the overwhelming majority of Ecuador's power EPC pipeline. Andean hydroelectric sites and coastal solar arrays both fall within this classification.
- Offshore:Marine-based generation remains absent from Ecuador's power infrastructure planning. No active procurement or resource assessment targets offshore wind or tidal technologies.
- Grid-Connected:Centralized transmission interconnection dominates utility-scale procurement. National Electricity Regulatory Agency certification protocols create bottlenecks at substation interconnection points for frequency response testing.
- Isolated:Off-grid settlements in Morona Santiago and Zamora Chinchipe provinces require modular solar-diesel hybrid systems. Remote geography excludes centralized transmission extension and demands self-contained EPC delivery models.
Grid-connected installations absorb the bulk of capacity additions; isolated systems are expanding most quickly as Amazon basin electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecuador generates surplus hydroelectric power from Andean river basins yet concentrates demand growth along coastal corridors where solar irradiation mapping now supports bankable projects. This production-consumption geography shapes contractor deployment patterns across the national territory.
Guayas Province and Guayaquil Metropolitan Area
Coastal solar corridor projects absorb the fastest-growing share of EPC procurement as improved satellite-based resource assessment unlocks financing for utility-scale photovoltaic installations. CNEL EP mandates grid-forming inverter specifications for all new awards in this zone. The Port of Guayaquil logistics cluster supports equipment importation for electromechanical packages serving both solar and thermal generation assets.
Pichincha Province and Quito-Cotopaxi Axis
Transmission infrastructure upgrades dominate EPC activity as the capital region integrates renewable generation from peripheral provinces. The Ministry of Electricity and Renewable Energy directs grid-code compliance testing through the National Electricity Regulatory Agency certification protocols. Heavy electrical equipment fabrication in the Quito industrial zone supplies substation components for voltage transformation projects.
Azuay Province and Cuenca Highlands
Run-of-river hydroelectric feasibility studies concentrate in this Andean basin as Chinese contractors deploy captive engineering resources for integrated delivery models. Water-use permits from the Ministry of Environment operate on non-synchronized calendars with grid-connection approvals. The Cuenca technical services cluster hosts specialized consultancies for hydrological modeling and penstock welding certification.
Morona Santiago and Zamora Chinchipe Amazon Provinces
Isolated mini-grid deployment accelerates as remote geography excludes centralized transmission extension. Modular solar-diesel hybrid EPC contracts address off-grid settlement electrification programs. The provincial capitals of Macas and Zamora anchor logistics chains for self-contained generation systems serving dispersed populations.
Esmeraldas and Northern Coastal Zone
Thermal generation refurbishment supports grid stability as natural gas infrastructure expansion proceeds. Wärtsilä Oyj Abp leverages thermal technology portfolios to anchor recurring service revenue streams in this corridor. The Esmeraldas refinery and port complex creates demand for captive power systems serving industrial process loads.
Ecuador Power EPC Market Competitive Landscape
Top-tier vendors anchor sovereign-guaranteed utility contracts, while mid-tier regional specialists compete for commercial and industrial risk allocation. European and Chinese engineering groups dominate hydroelectric and thermal segments through integrated feasibility-to-commissioning delivery. Strategic archetypes include technology-anchored service providers, state-linked turnkey contractors, and modular solar specialists. Competitive moves center on long-term operations and maintenance decoupling from initial construction bids, plus digital twin platform licensing for lifecycle revenue extension.
Within the state-linked turnkey tier, Power Construction Corporation of China exemplifies integrated engineering resource deployment for Andean hydroelectric basins. Siemens AG occupies a position among technology-anchored service providers leveraging digital platforms. Wärtsilä Oyj Abp represents the thermal technology archetype with recurring revenue models. These three anchors illustrate how contractor qualification requirements fragment across Ecuador's technology segments and end-user risk profiles.
| Leading Market Players |
|---|
| Wärtsilä Oyj Abp |
| Power Construction Corporation of China |
| Grupo Techint |
| CEYM International EPC company |
| SANTOS CMI S.A. |
| Saipem SpA |
| Bechtel Corporation |
| Fluor Corporation |
| Siemens AG |
| Others |
Supply & Pricing Matrix
CNEL EP's mandated grid-forming inverter specifications for coastal solar corridor projects force contractors to absorb premium electromechanical costs into lump-sum bids, compressing margins on initial awards while extending contract visibility for qualified service providers.
Pricing Analysis
Margin tightening in utility-scale EPC contracts reflects sovereign guarantee dependency and extended performance guarantee timelines. Three-tier pricing structure across premium, standard, and economy levels segments by contractor qualification depth and technology integration scope. Price differentiation hinges on captive engineering resources and after-sales service bundling. State-owned utilities exhibit lowest price sensitivity due to sovereign-backed payment structures, while commercial buyers in Guayaquil negotiate hardest on equipment sourcing transparency.
Supply Chain Analysis
Direct-to-utility channels handle sovereign-guaranteed procurement volumes through lump-sum tender processes. Equipment sourcing concentrates in China for hydroelectric turbines and Europe for solar inverters. Raw material dependencies include copper for transmission infrastructure, structural steel for mounting systems, and lithium-ion cells for storage co-location. Single-source vulnerability persists for Francis and Kaplan turbine specifications. Distribution runs through the Port of Guayaquil for electromechanical imports serving coastal corridor projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ecuador's power EPC sector is transitioning from hydroelectric dominance toward solar-digital hybrid delivery models, with grid-forming inverter technology displacing legacy synchronous spinning reserve dependency.
For Market Incumbents: Extend long-term service agreement portfolios beyond construction handover to capture recurring revenue from CNEL EP's decoupled O&M procurement. Anchor defensive positioning through captive welding certification programs that address Ecuador's technician pipeline shortage. Deepen backward integration into digital twin platform licensing to match Siemens AG's lifecycle revenue model. For New Entrants and Emerging Players: Regional logistics providers in Guayaquil offer channel access to commercial solar buyers seeking modular installations with compressed commissioning windows. White-space targets include Amazon basin mini-grid deployment in Morona Santiago and Zamora Chinchipe provinces. The most penetrable segment is isolated solar-diesel hybrid systems where remote geography excludes incumbent turnkey contractors. For Investors and Strategic Acquirers: Re-rating potential sits with technology-anchored service providers given Ministry of Electricity mandates for real-time ecological flow monitoring infrastructure. Long-term viability favors contractors with integrated feasibility-to-commissioning capabilities across Andean hydroelectric and coastal solar segments. The signal to watch is regulatory framework finalization for battery storage ancillary services procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement Expansion | CNEL EP's decoupled O&M procurement creates recurring revenue visibility for qualified providers. |
| Grid-forming Inverter Integration | Ministry mandates for coastal solar corridors rewrite interconnection standards without spinning reserve dependency. |
| Amazon Mini-grid Deployment | Remote settlement electrification programs exclude centralized transmission extension competitors. |
| Digital Twin Platform Licensing | Siemens AG's integrated model demonstrates lifecycle revenue extension beyond construction handover. |
| Captive Welding Certification Investment | Penstock fabrication requirements limit qualified bidders for Andean hydroelectric pressure tunnel segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, EPC contractors, grid operators, and Ministry of Electricity officials combined with secondary validation from National Electricity Regulatory Agency protocols and CNEL EP tender documentation. Bottom-up project pipeline assessment and top-down macroeconomic triangulation shaped market sizing across the analysis window.
Data-stream reconciliation integrated capacity addition tracking with tariff benchmark modeling. Segmentation dimensions span service delivery phase, end-user risk profile, generation technology, and grid integration architecture. CAGRs were derived from project finance drawdown schedules and sovereign guarantee availability curves. Forecast inputs include hydrological variability assumptions for Andean basins and satellite-based irradiation validation for coastal provinces.
Several conditions sit outside the modeled scope, including proposed Public-Private Partnership Law amendment finalization and London Metal Exchange price trajectory for copper and structural steel. Forecasts reflect documented assumptions about regulatory milestone synchronization and environmental licensing calendar alignment. Periodic stress-testing of base assumptions is recommended given grid-code compliance timeline uncertainty and single-source turbine supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Power Analyzers Market
Power Equipment
France Power EPC Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Thailand Power Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Germany Power EPC Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Magnetic Bearing Market
Power Equipment
Global Medium Voltage AC Drives Market