
 Qatar Power EPC Market | 2026-2036
Qatar Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Power EPC Market Analytics
Turnkey-to-hybrid configuration unbundling is hardening buyer preference in Qatar's power EPC landscape. Samsung C&T Corporation anchors mega-project execution through integrated engineering-procurement muscle across Gulf utility builds. Larsen & Toubro Limited leverages its heavy fabrication scale to compete on concentrated solar power and substation packages. Siemens AG differentiates through digital grid integration and gas turbine technology leadership in Middle East power trains.
Power EPC denotes the full-cycle delivery of electricity generation, transmission, and distribution infrastructure encompassing engineering design, equipment procurement, construction management, and commissioning services with performance guarantees typically tied to output capacity and efficiency benchmarks. Qatar's market centers on gas-fired combined-cycle plants operating above 60% thermal efficiency alongside photovoltaic farms exceeding 800 MWac capacity. Commissioning services capture premium margin pools as owners demand operational readiness guarantees and warranty handovers. Turnkey deployment dominates government and utility segments where risk transfer to contractors simplifies state budgeting, while hybrid models gain traction among industrial off-takers seeking phased asset ownership.
Qatar's national power regulator and the Ministry of Environment and Climate Change enforce emissions benchmarks and grid code compliance that shape contractor qualification requirements. International Finance Corporation performance standards and Qatar National Vision 2030 sustainability targets mandate carbon intensity disclosures and renewable energy quotas in new build tenders. Stakeholders must monitor how green hydrogen co-firing mandates and battery storage co-location rules reshape procurement specifications and contractor capability requirements.
Market Dynamics
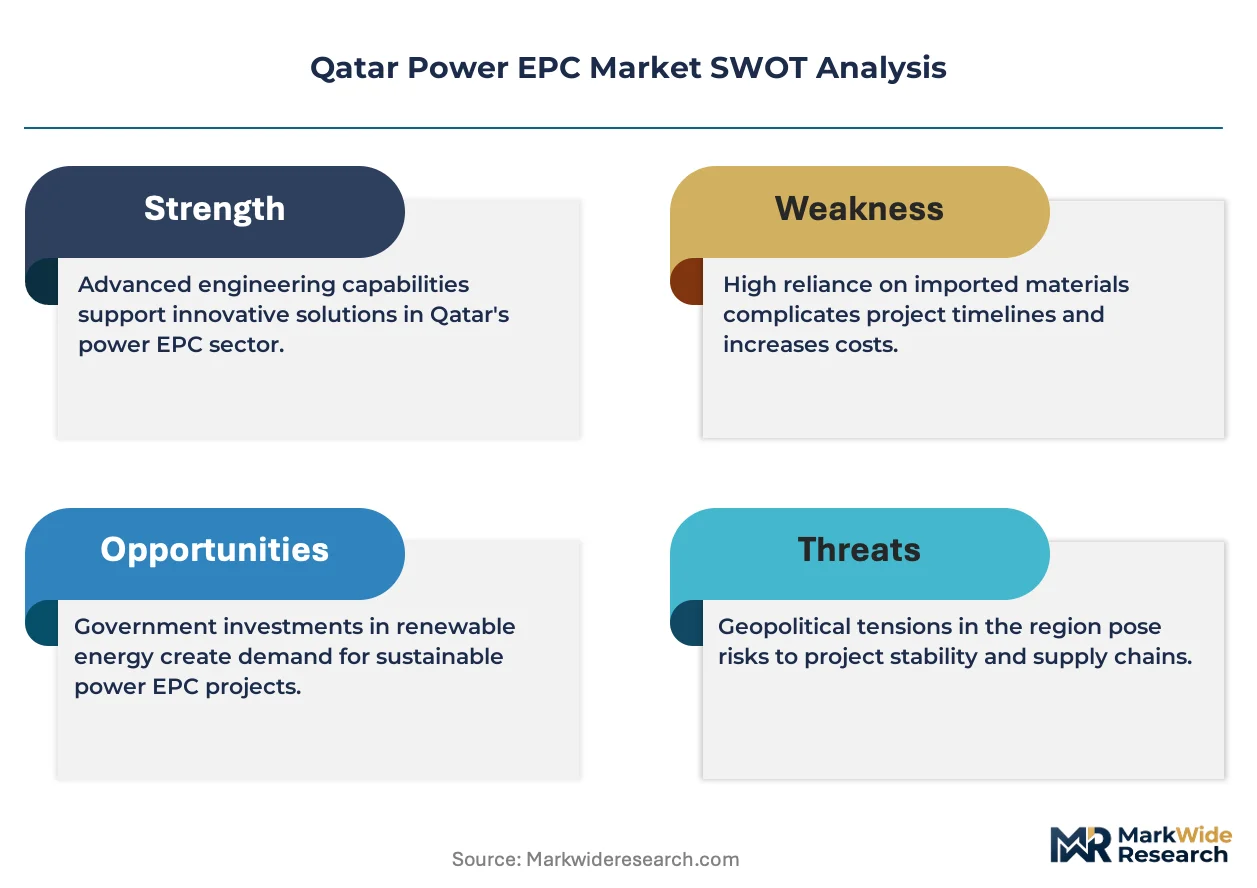
Qatar General Electricity and Water Corporation's unbundled tendering framework is fragmenting single-source mega-contracts into engineering, procurement, and construction lots. This structural shift rewards specialized contractors with fabrication depth or digital integration capabilities while penalizing pure-play generalists.
Growth Catalysts
- Qatar National Vision 2030:The sustainability framework mandates renewable energy quotas in new generation tenders, forcing utility-scale solar and co-fired gas plant investments.
- Combined-cycle efficiency thresholds:Ras Laffan industrial corridor operators demand turbine upgrades above 60% thermal efficiency, pulling advanced engineering services.
- Battery storage co-location rules:Grid code amendments require photovoltaic farms exceeding 500 MWac to integrate four-hour lithium-ion storage, expanding EPC scope.
Market Restraints
- Specialized labor scarcity:Commissioning engineers with large-frame gas turbine experience command premium wages, compressing contractor margins on fixed-price builds.
- Equipment import dependence:Heavy gas turbines and inverters concentrate manufacturing in Germany, Japan, and South Korea, exposing projects to currency and shipping volatility.
- Grid code compliance timelines:Qatar's national power regulator extends testing protocols for hybrid renewable-gas systems, delaying commercial operation dates.
Strategic Opportunities
- Green hydrogen co-firing mandates:Ministry of Environment and Climate Change proposals would require 30% hydrogen blending in new gas plants by the early 2030s, creating turbine retrofit demand.
- Doha district cooling integration:Combined heat and power configurations for urban cooling networks remain underdeveloped, offering turnkey thermal-cooling packages.
- Digital twin adoption:Asset operators seek predictive maintenance platforms, opening software-integrated EPC contracts beyond hardware delivery.
Industry Challenges
- Commissioning warranty exposure:Performance guarantees tied to output capacity and heat rate create long-tail liability for contractors beyond mechanical completion.
- Local content requirements:Kahramaa procurement rules mandate Qatari workforce quotas and domestic fabrication percentages that outstrip available skilled labor supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Power EPC Market |
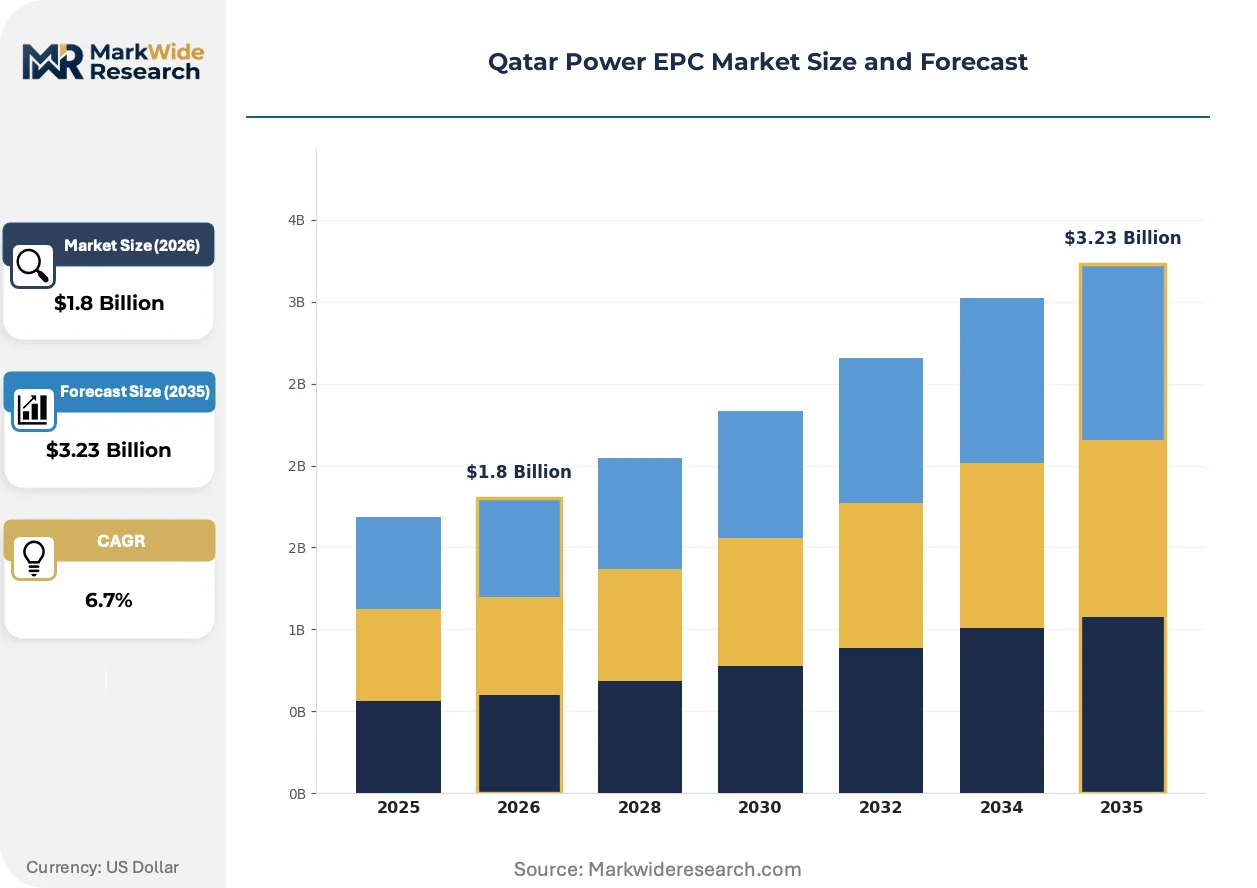
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Commissioning End User: Government, Industrial, Commercial, Utilities Deployment Model: Onshore, Offshore, Hybrid, Turnkey Technology: Renewables, Fossil Fuels, Hydro, Nuclear |
| Companies Covered | Samsung C&T Corporation, Siemens AG, El Sewedy Electric Co SAE, Larsen & Toubro Limited, Yokogawa Electric Corporation, Mitsubishi Electric Corporation, ABB Ltd, Chiyoda Corporation, Hyundai Engineering & Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Power EPC Market Evolving Landscape
Modular construction methods and digital commissioning tools are compressing project timelines while fragmenting traditional EPC risk structures. Contractors now compete on fabrication automation and software integration rather than construction labor scale alone.
Distributed energy resource management systems (DERMS) are decentralizing control architectures for Qatar's grid-connected solar farms. Kahramaa's transmission division is adopting these platforms for voltage regulation across the 800 MWac Al Kharsaah facility. The technology is decentralizing grid balancing responsibilities from central dispatch centers to plant-level control systems, reducing transmission upgrade capex.
Qatar National Vision 2030 carbon intensity disclosure rules are tightening procurement specifications for international contractors. The Ministry of Environment and Climate Change now requires embodied carbon reporting for steel and concrete inputs exceeding 10,000 tonnes. Industrial off-takers in Ras Laffan are responding by pre-qualifying EPC bidders with verified supply chain emissions data.
Industrial buyers are unbundling long-term service agreements from initial EPC contracts. Ras Laffan petrochemical operators now procure gas turbines and maintenance separately, compressing contractor aftermarket revenue pools. This pattern is most visible among private off-takers seeking operational flexibility, while government utilities retain bundled turnkey structures for budget certainty.
Qatar Power EPC Market Segmentation
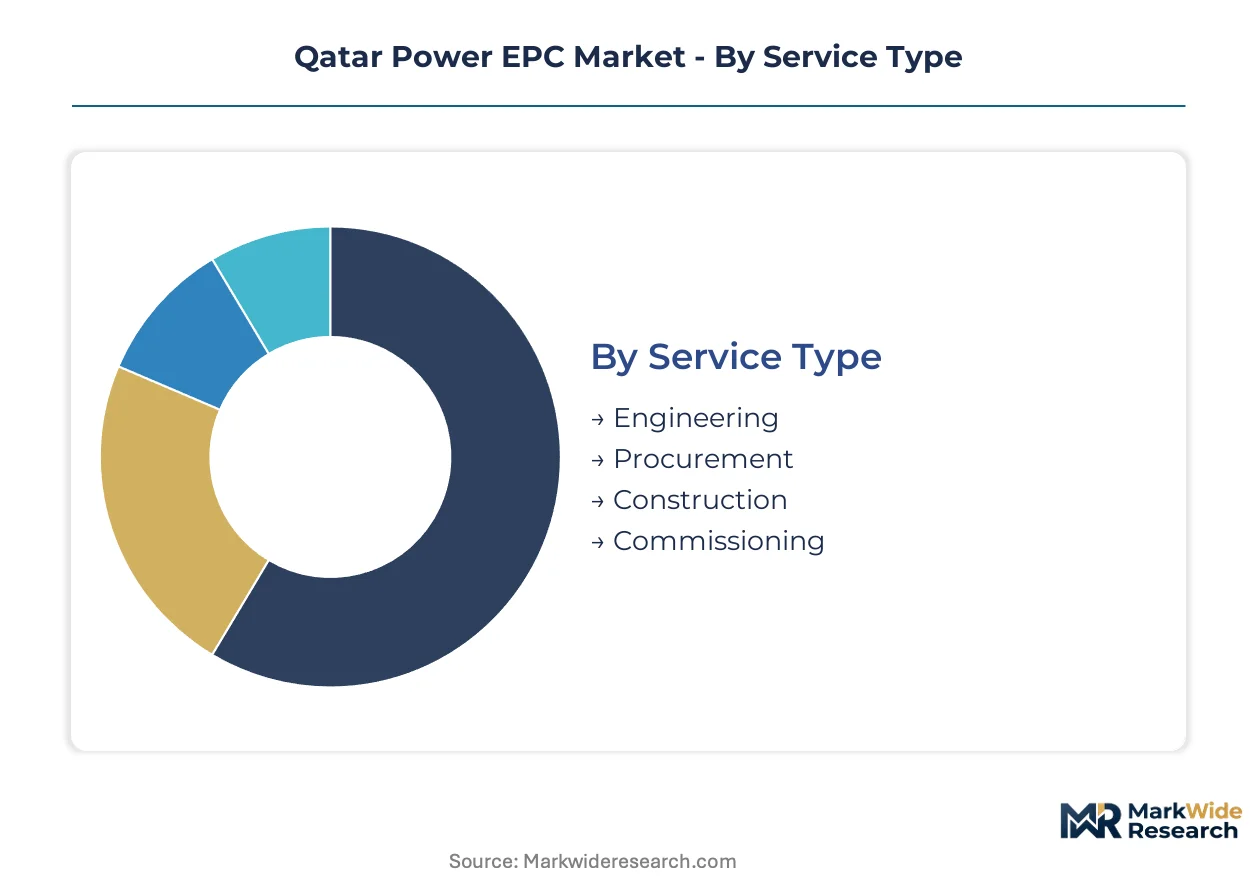
Qatar's power EPC procurement fragments across service specialization, end-user risk profiles, and technology mandates. Kahramaa's unbundled tendering rewards contractors with discrete capabilities rather than bundled generalists.
Service Type:
Engineering intensity versus field execution scale defines margin capture across this spectrum.
- Engineering:Front-end design and detailed engineering for combined-cycle configurations above 60% thermal efficiency. Demand concentrates with Ras Laffan industrial operators seeking heat rate optimization and hydrogen-ready turbine specifications.
- Procurement:Long-lead equipment sourcing for gas turbines and inverters manufactured in Germany, Japan, and South Korea. Currency volatility and shipping delays compress margins on fixed-price contracts.
- Construction:Field assembly and civil works for photovoltaic farms exceeding 800 MWac capacity. Local content requirements mandate Qatari workforce quotas that outstrip available skilled labor supply.
- Commissioning:Operational readiness verification with performance guarantees tied to output capacity. Premium pricing reflects long-tail liability exposure beyond mechanical completion.
Leading the category by volume: Construction. Growing fastest: Commissioning.
End User:
Risk allocation preferences separate state-backed utilities from private industrial offtakers.
- Government:Turnkey contracts with full risk transfer to contractors simplify state budgeting for Qatar National Vision 2030 infrastructure. Procurement favors established EPC consortia with balance sheet capacity for performance guarantees.
- Industrial:Ras Laffan petrochemical operators unbundle long-term service agreements from initial EPC awards. Operational flexibility demands separate turbine procurement and maintenance contracts.
- Commercial:Distributed solar and district cooling integration for Doha urban developments. Smaller scale limits contractor interest relative to utility-scale programs.
- Utilities:Kahramaa's centralized generation and transmission expansion drives the largest contract values. Renewable energy quotas mandate solar photovoltaic integration alongside gas-fired capacity.
Dominant by contract value: Utilities. Expanding most quickly: Industrial.
Deployment Model:
Location and contracting structure determine risk retention and financing complexity.
- Onshore:Land-based construction for Doha metropolitan zone and Ras Laffan industrial corridor projects. Grid connection infrastructure and land acquisition fall under contractor scope in turnkey arrangements.
- Offshore:Coastal and island installations for desalination-linked power generation. Limited applicability in Qatar's compact geography restricts segment scale.
- Hybrid:Phased asset ownership models allowing industrial offtakers to transition from EPC contractor operation to direct control. Gaining traction among private buyers seeking budget flexibility.
- Turnkey:Single-source delivery with fixed-price risk transfer. Government and utility segments retain this structure for procurement certainty despite contractor premium pricing.
Standard by volume: Turnkey. Climbing the fastest: Hybrid.
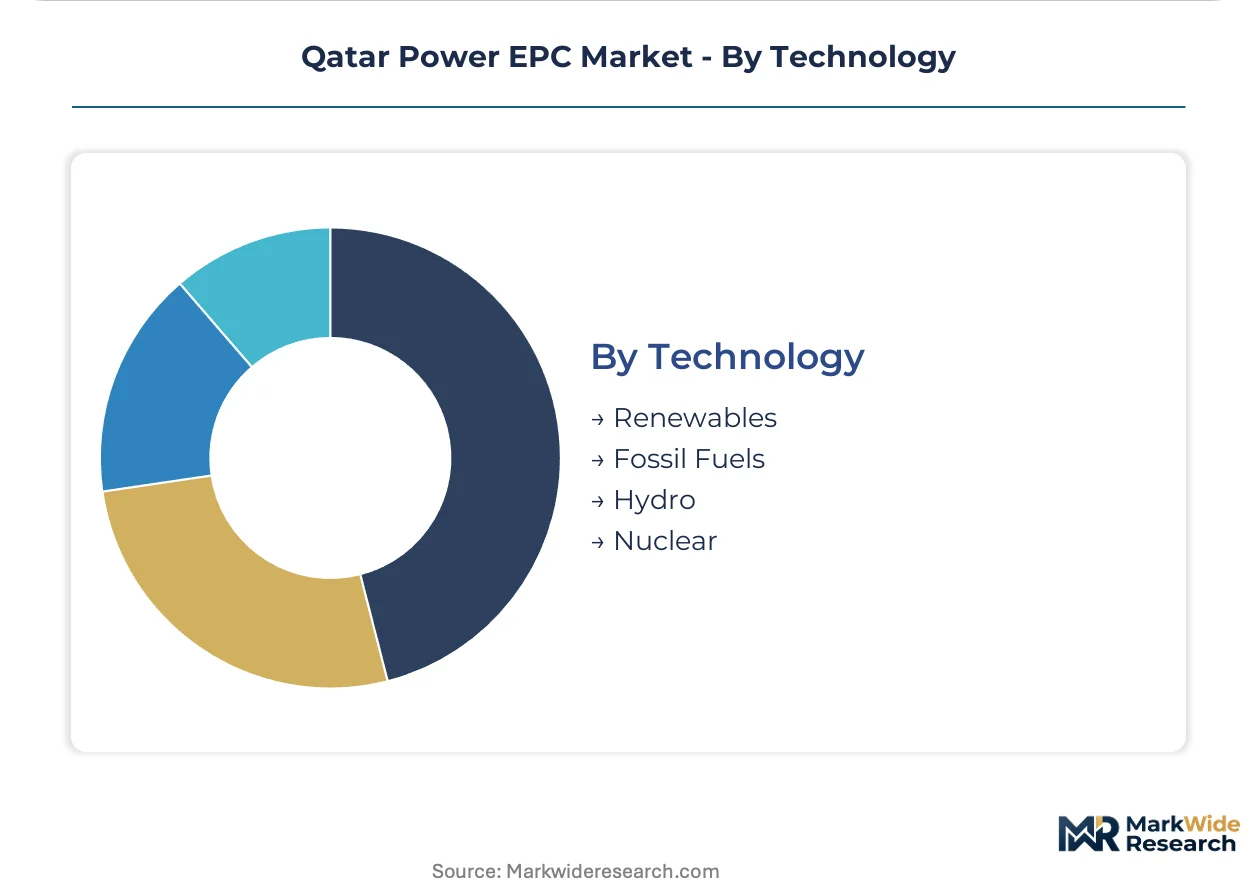
Technology:
Carbon intensity mandates and grid code compliance reshape technology qualification requirements.
- Renewables:Utility-scale solar photovoltaic with mandated four-hour battery storage for installations above 500 MWac. Al Kharsaah facility demonstrates distributed energy resource management system integration.
- Fossil Fuels:Combined-cycle gas turbine upgrades and newbuilds with hydrogen co-firing readiness. Ministry of Environment and Climate Change proposals target 30% hydrogen blending by the early 2030s.
- Hydro:Pumped storage and small-scale applications. Qatar's arid climate and flat topography eliminate meaningful deployment potential.
- Nuclear:No active program despite regional interest in small modular reactors elsewhere in the Gulf. Regulatory framework and water scarcity exclude this technology from Qatar's generation mix.
Leading investment: Fossil Fuels. Gaining share fastest: Renewables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's power generation capacity outstrips domestic consumption, creating an export-oriented infrastructure build cycle centered on industrial corridor expansion. The country's compact geography concentrates EPC activity in two primary zones. Regional demand patterns within Qatar vary by end-use concentration and regulatory jurisdiction.
Doha Metropolitan Zone
District cooling integration and urban solar deployment dominate EPC procurement in Qatar's capital. Kahramaa's transmission division mandates distributed energy resource management systems for grid-connected installations above 100 MWac. The Msheireb Downtown and Lusail City developments concentrate demand for combined heat and power configurations serving commercial cooling loads.
Ras Laffan Industrial Corridor
Petrochemical operators in this northeastern industrial zone drive demand for combined-cycle gas turbine upgrades above 60% thermal efficiency. The Ministry of Environment and Climate Change enforces emissions benchmarks that shape contractor qualification requirements for new build tenders. Ras Laffan's desalination-linked power generation creates specialized EPC scope for coastal infrastructure.
Al Kharsaah Solar Zone
The 800 MWac photovoltaic facility anchors utility-scale renewable EPC demand in western Qatar. Kahramaa's battery storage co-location rules require four-hour lithium-ion integration for installations exceeding 500 MWac. This zone demonstrates the grid code compliance timelines that extend testing protocols for hybrid renewable-gas systems.
Al Wakrah Southern Corridor
Industrial expansion and port-linked power infrastructure concentrate EPC activity in this southern municipality. Qatar National Vision 2030 sustainability targets mandate carbon intensity disclosures for steel and concrete inputs exceeding 10,000 tonnes. The Hamad Port expansion drives demand for dedicated generation capacity serving maritime logistics.
Umm Salal Central Belt
Transmission infrastructure and grid stabilization projects dominate this central zone between Doha and the northern industrial areas. Qatar General Electricity and Water Corporation's unbundled tendering framework fragments single-source mega-contracts into discrete engineering, procurement, and construction lots. Local content requirements for Qatari workforce quotas create execution challenges across substation and line construction packages.
Qatar Power EPC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Qatar's power EPC landscape. Korean and Japanese industrial groups leverage integrated engineering-procurement capabilities for mega-project execution, while European technology providers differentiate through digital grid integration and turbine efficiency leadership. Two strategic archetypes dominate: fabrication-scale heavy contractors and software-integrated technology licensors. Competitive positioning hinges on strategic partnerships for long-lead equipment sourcing and capacity expansion in commissioning services.
Within the integrated conglomerate tier, Samsung C&T Corporation and Hyundai Engineering & Construction represent Korean chaebol structures with Gulf utility build experience. Siemens AG anchors European technology positioning through digital grid and gas turbine capabilities. Larsen & Toubro Limited exemplifies Indian fabrication-scale contractors competing on concentrated solar power and substation packages. These three occupy positions spanning turnkey risk absorption and technology licensing, with each representing distinct geographic origin and structural approaches to Qatar's procurement environment.
| Leading Market Players |
|---|
| Samsung C&T Corporation |
| Siemens AG |
| El Sewedy Electric Co SAE |
| Larsen & Toubro Limited |
| Yokogawa Electric Corporation |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Chiyoda Corporation |
| Hyundai Engineering & Construction |
| Others |
Value Network & Pricing Analysis
Captive procurement of heavy gas turbines and inverters from Germany, Japan, and South Korea anchors contractor supply positions while constraining pricing power through currency exposure and long-lead vulnerability. Kahramaa's unbundled tendering framework fragments risk retention across engineering, procurement, and construction lots, compressing margins on fixed-price builds where equipment import dependence cannot be hedged.
Pricing Analysis
Margin tightening in commissioning services reflects long-tail liability exposure tied to output capacity guarantees and heat rate performance benchmarks. Project-based pricing dominates government and utility segments where turnkey risk transfer commands contractor premiums, while industrial off-takers unbundle long-term service agreements to capture operational flexibility. Price differentiation separates bundled turnkey contracts from hybrid phased-ownership structures. Fixed-price builds face acute cost-down pressure as specialized labor scarcity for large-frame gas turbine commissioning engineers compresses contractor margins. Government utilities exhibit lowest price sensitivity due to budget certainty requirements, while Ras Laffan petrochemical operators demonstrate highest sensitivity through unbundled procurement strategies.
Supply Chain Analysis
Dual-sourcing qualification requirements from Kahramaa mandate contractor validation across multiple equipment suppliers for critical path components. Manufacturing concentration in Germany, Japan, and South Korea for heavy gas turbines and inverters creates structural single-source vulnerability despite buyer mandates. Raw material dependencies span high-grade steel forgings, precision castings, and power electronics substrates. Logistics chokepoints through Strait of Hormuz shipping lanes amplify delivery risk. Distribution runs through EPC contractor-led procurement with direct OEM relationships, bypassing traditional distributor networks for long-lead equipment categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's power EPC market is consolidating around fabrication-scale contractors and digital-integrated technology licensors as unbundled tendering and specialized capability requirements force pure-play generalists toward exit or acquisition.
For Market Incumbents: Anticipate hydrogen-ready turbine specifications and battery storage co-location mandates reshaping procurement qualifications by investing in commissioning capacity expansion and digital twin integration capabilities. Defensive consolidation through backward integration into precision fabrication or captive supply of power electronics substrates will hedge equipment import dependence. The priority lever sits with pre-qualification for green hydrogen co-firing retrofit demand. For New Entrants and Emerging Players: Digital-first commissioning platforms and predictive maintenance software offer white-space entry points where asset operators seek operational readiness guarantees beyond mechanical completion. District cooling integration for Doha metropolitan developments represents the most penetrable segment given underdeveloped combined heat and power configurations. Go-to-market positioning should anchor on software-integrated EPC contracts that decouple from hardware delivery margin pools. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Korean and European industrial groups seeking Gulf utility build capabilities. Long-term viability favors contractors with verified supply chain emissions data and Kahramaa pre-qualification status. Acquisition target archetype: mid-scale engineering specialists with hydrogen-ready turbine design depth. The signal to watch is Ministry of Environment and Climate Change finalization of 30% hydrogen blending mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fabrication | Captive supply of high-grade steel forgings mitigates German and Japanese equipment lead time exposure. |
| Commissioning Capacity Expansion | Large-frame gas turbine operational readiness services capture premium pricing from Qatar General Electricity and Water Corporation. |
| Digital Twin Platform Development | Predictive maintenance software opens recurring revenue streams beyond hardware delivery completion. |
| Hydrogen-Ready Turbine Certification | Ministry of Environment and Climate Change alignment secures eligibility for 2030s co-firing retrofit tenders. |
| Battery Storage Co-Location Capability | Four-hour lithium-ion integration expertise qualifies contractors for photovoltaic farms exceeding 500 MWac. |
Research Methodology
Independent corroboration across utility planning officers, EPC contractors, IPP project developers, and grid operators underwrites the qualitative findings in this study. Primary interviews with Kahramaa procurement leads and Ras Laffan industrial operators combined with secondary validation from Qatar General Electricity and Water Corporation regulatory filings, International Finance Corporation performance standards, and project development databases. Bottom-up contract value aggregation and top-down infrastructure spend allocation triangulate market sizing across service type, end user, and technology segments.
Comparable-period anchoring to historical tender awards and commissioning completion timelines structured the projection horizon. The analytical framework models demand across engineering, procurement, construction, and commissioning service types; government, industrial, commercial, and utility end users; and renewables, fossil fuels, hydro, and nuclear technologies. CAGRs derive from capacity addition pipelines and efficiency upgrade cycles. Forecast inputs include Qatar National Vision 2030 renewable energy quotas and grid code amendment timelines for battery storage co-location.
Several conditions sit outside the modeled scope, including geopolitical disruption to equipment shipping lanes and abrupt shifts in green hydrogen blending mandate timing. Forecasts reflect assumptions regarding specialized labor supply elasticity and currency stability for equipment imports. Deviation in Ministry of Environment and Climate Change regulatory finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Clean Steam Separator Market
Power Equipment
Digital Power Conversion Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Global Transformerless UPS Market
Power Equipment
US Power EPC Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Australia Power EPC Market
Power Equipment
Air Preheater Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Saudi Arabia Power EPC Market