
 Natural Gas Turbine Market | 2026-2036
Natural Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Turbine Market Analytics
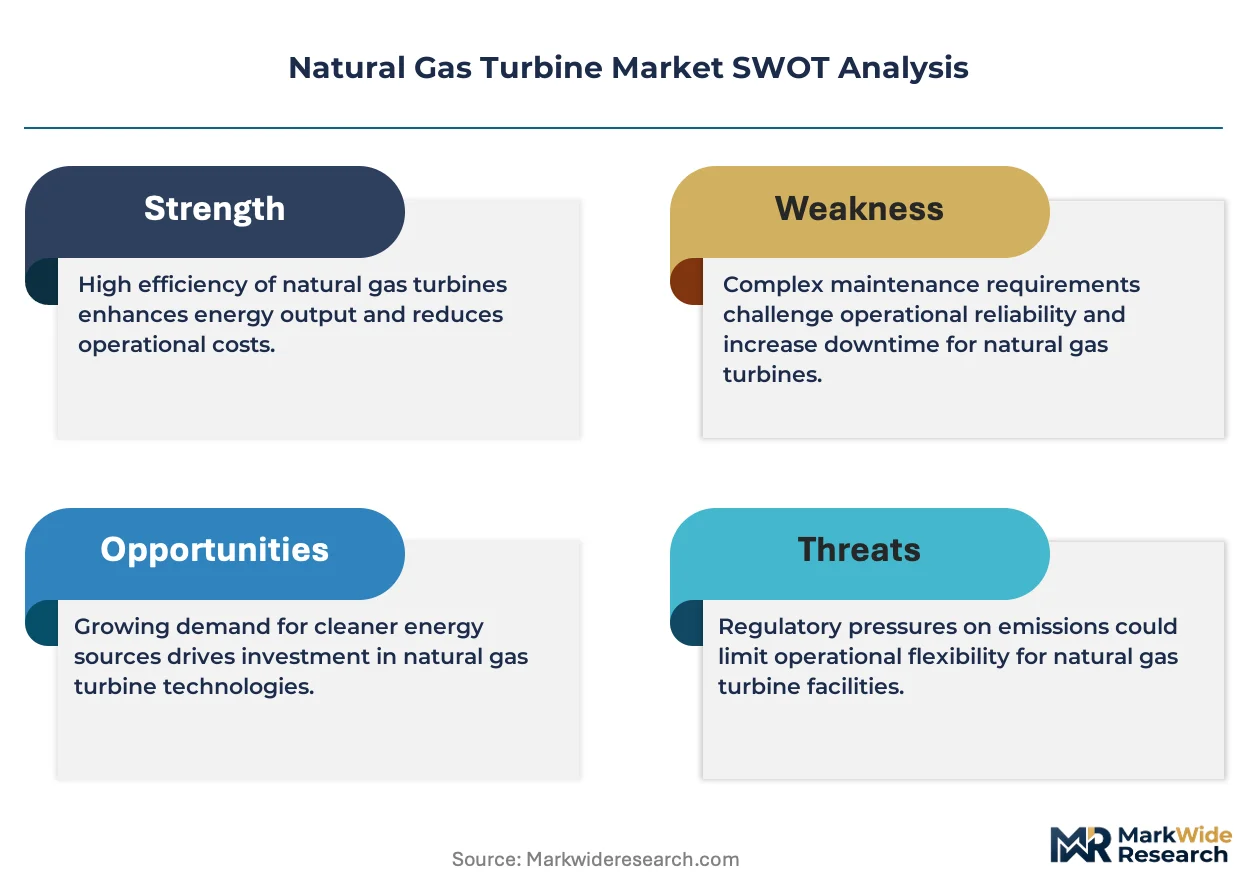
Aftermarket service revenue is reconfiguring margin distribution across the value chain. GE Vernova leverages its global installed base to capture long-term service contracts. Siemens Energy anchors European aftermarket presence through regional service hubs. Mitsubishi Power dominates Asia-Pacific refurbishment demand with localized technical teams.
A natural gas turbine converts the chemical energy of gaseous fuel into mechanical energy through controlled combustion and expansion across aerodynamic blades, with heavy-duty frames achieving firing temperatures exceeding 1,500°C and combined cycle efficiencies above 60%. Combined cycle configurations command the largest share of new orders due to superior thermal efficiency and lower carbon intensity per megawatt-hour. Aeroderivative turbines represent the fastest-expanding technology segment, driven by grid flexibility requirements and faster ramp rates. Simple cycle units retain relevance in peaking applications where capital cost and deployment speed outweigh efficiency optimization.
EPA regulations under the Clean Air Act and emerging hydrogen blending mandates from EU frameworks are tightening allowable emissions profiles and accelerating combustion system redesigns. China's MIIT efficiency standards and India's CEA grid codes are shaping product specifications for regional deployments. Stakeholders must monitor hydrogen readiness certifications and carbon border adjustment mechanisms to align capital allocation with evolving compliance thresholds.
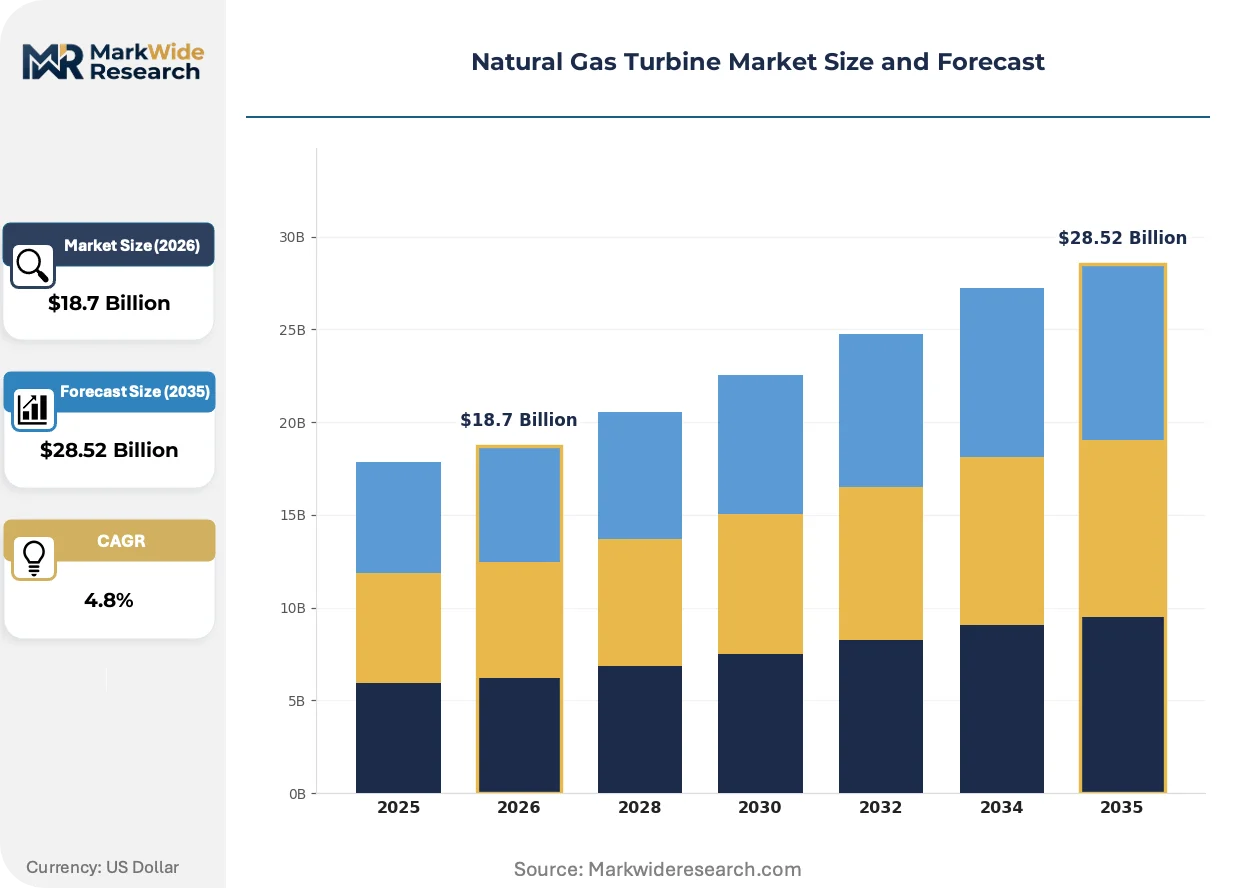
Market Dynamics
The transition from baseload gas generation to flexible grid-balancing assets is restructuring turbine procurement priorities, with hydrogen-readiness certifications now determining long-term asset valuation and financing terms.
Growth Catalysts
- Coal-to-gas switching mandates:China's MIIT efficiency standards and India's CEA grid codes are accelerating utility procurement of combined cycle units as baseload coal retirements outpace renewable buildouts.
- EU hydrogen blending frameworks:The EU Green Deal's hydrogen readiness certifications are creating guaranteed future demand for retrofittable combustion systems across European power portfolios.
- Data center load growth:Hyperscale facility expansion in Virginia, Texas, and Singapore is driving orders for aeroderivative turbines with sub-10-minute start capabilities.
Market Restraints
- Specialized alloy supply concentration:Single-source dependency for nickel-based superalloys from Russian and Chinese refiners creates input cost volatility and sanctions exposure.
- Interconnection queue delays:FERC interconnection backlogs in the US and grid code compliance timelines in Germany extend project commissioning by 18-36 months.
- Renewable-plus-storage substitution:Lithium-ion battery cost curves and solar PV efficiency gains are compressing the economic case for simple cycle peaking units.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea tourism developments require captive power with hydrogen transition pathways, favoring OEMs with localized technical teams.
- Ammonia co-firing retrofits:Japanese utilities under METI guidance are piloting 20% ammonia blends, creating aftermarket combustion system upgrade cycles.
- Digital twin service models:Predictive maintenance platforms are unbundling traditional service contracts, opening margin capture for independent software vendors and specialized analytics firms.
Industry Challenges
- Combustion engineering talent scarcity:The specialized workforce for high-temperature turbine blade design and repair is concentrated at a handful of OEM engineering centers, constraining refurbishment capacity expansion.
- Hydrogen certification timeline uncertainty:Absence of unified ISO standards for 100% hydrogen combustion is freezing final investment decisions on next-generation turbine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Turbine Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Combined Cycle, Simple Cycle, Cogeneration, Others Technology: Single-Shaft, Multi-Shaft, Aeroderivative, Heavy-Duty Application: Power Generation, Oil & Gas, Industrial Processes, Marine End User: Utilities, Independent Power Producers, Industrial Facilities, Commercial Users |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Power, Solar Turbines, Ansaldo Energia, Capstone Green Energy, Bharat Heavy Electricals Limited, Doosan Enerbility, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Turbine Market Evolving Landscape
Additive manufacturing of nickel superalloy turbine blades is compressing lead times for hot gas path components while enabling geometries impossible through conventional casting methods.
Dry low-emissions combustion architectures with axial fuel staging are rendering obsolete traditional diffusion flame systems in new heavy-duty orders. US independent power producers are specifying these systems in RFPs for combined cycle projects. The technology is compressing the viable market for non-DLE retrofit kits and shortening the depreciation schedules of installed conventional units.
EPA's updated New Source Performance Standards under the Clean Air Act are mandating carbon capture readiness assessments for gas turbines above 25 MW. The rule is forcing combustion system redesigns to accommodate post-combustion capture integration. Combined cycle projects in Texas and Louisiana are front-loading engineering for amine-based capture compatibility.
Utility procurement committees are unbundling long-term service agreements from initial equipment purchases, favoring competitive aftermarket bidding after warranty expiration. This behavior is fragmenting the service revenue pool and elevating independent service providers with specialized hot gas path expertise. The shift is most pronounced in Southeast Asian markets where state utilities face budget constraints and seek operational flexibility.
Natural Gas Turbine Market Segmentation
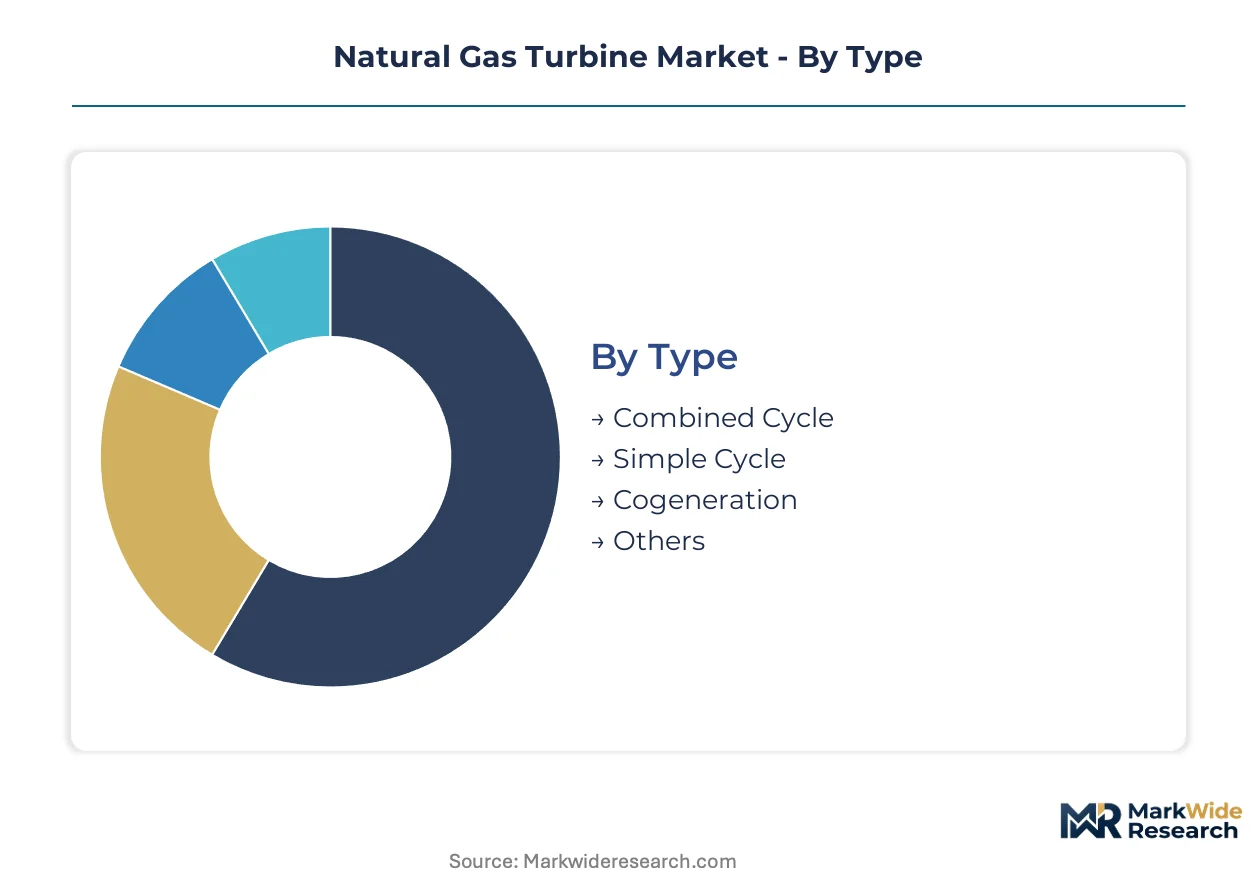
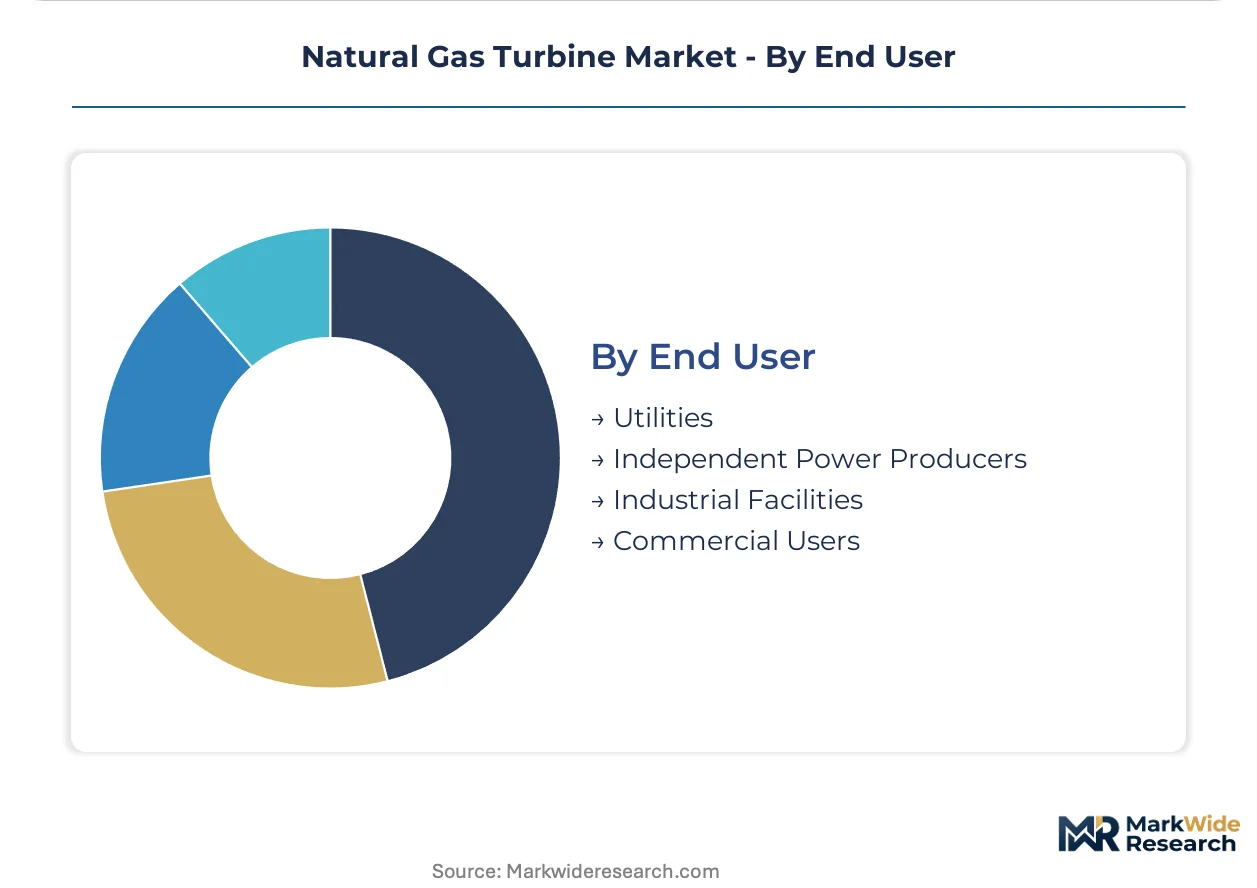
Technology configurations and end-user procurement patterns determine capital allocation, service revenue potential, and hydrogen transition readiness across the natural gas turbine value chain. Segment boundaries are blurring as utilities demand flexible assets that bridge current gas operations with future fuel blends.
Type:
Cost tier differentiation separates baseload-optimized systems from peaking units and thermal integration architectures.
- Combined Cycle:Integrates gas turbine exhaust heat recovery through steam turbine bottoming cycles, achieving thermal efficiencies above 60%. Chinese utilities under MIIT efficiency mandates and Indian CEA grid codes are prioritizing these configurations for coal replacement baseload.
- Simple Cycle:Standalone gas turbine operation without heat recovery, optimized for rapid deployment and lower capital intensity. Texas and Virginia data center developers specify aeroderivative simple cycle units for sub-10-minute emergency start capability.
- Cogeneration:Simultaneous electricity and useful thermal output from exhaust heat capture. Industrial facilities in Germany and the Netherlands deploy these for process steam and district heating integration under EU efficiency directives.
- Others:Specialized configurations including trigeneration and hybrid renewable-gas systems for niche commercial and institutional applications.
Combined Cycle commands the established base. The steepest expansion runs through Cogeneration as industrial decarbonization tightens.
Technology:
Architectural choices between shaft configuration and frame heritage determine ramp rates, maintenance intervals, and hydrogen blending compatibility.
- Single-Shaft:Gas and steam turbines mounted on one generator shaft, reducing footprint and simplifying control systems. Saudi giga-projects and Japanese combined cycle repowering favor this layout for operational simplicity.
- Multi-Shaft:Separate generators for gas and steam turbines, offering operational flexibility and partial load optimization. Indian IPPs prefer this architecture for grid-following renewable balancing duties.
- Aeroderivative:Aviation-derivative lightweight turbines with sub-10-minute start times and high cycling tolerance. Singapore and Texas hyperscale data centers drive procurement for emergency backup and grid services.
- Heavy-Duty:Purpose-designed industrial frames with firing temperatures exceeding 1,500°C and 30+ year design life. Chinese utilities anchor baseload procurement around these units for coal-to-gas switching programs.
Heavy-Duty frames command the established base. The steepest expansion runs through Aeroderivative technology as distributed generation and data center loads multiply.
Application:
End-use sector requirements dictate efficiency priorities, emissions thresholds, and fuel flexibility specifications.
- Power Generation:Grid-connected electricity production across utility and merchant plant configurations. Asia-Pacific utilities dominate orders as renewable intermittency creates firm capacity needs.
- Oil & Gas:Upstream, midstream, and downstream process power including mechanical drive for compressors and pumps. Middle East NOCs and Permian Basin operators specify hydrogen-ready units for field electrification.
- Industrial Processes:Cogeneration and on-site power for chemicals, refining, and manufacturing. EU carbon border adjustments are accelerating efficiency upgrades across German and Dutch industrial clusters.
- Marine:Propulsion and auxiliary power for LNG carriers and offshore vessels. Singapore and Houston shipyards specify dual-fuel configurations for IMO 2030 compliance pathways.
Power Generation commands the established base. The steepest expansion runs through Industrial Processes as on-site decarbonization tightens energy intensity requirements.
End User:
Customer type determines procurement sophistication, service contract structures, and technology risk tolerance.
- Utilities:Vertically integrated and transmission-connected generators with regulated cost recovery. State-owned utilities in China, India, and Japan anchor combined cycle demand through centralized procurement.
- Independent Power Producers:Merchant generators selling into competitive wholesale markets. US IPPs in Texas and PJM unbundle service contracts and specify dry low-emissions combustion for EPA compliance.
- Industrial Facilities:Captive power users with process steam and electricity needs. German chemical complexes and Saudi petrochemical sites prioritize cogeneration with hydrogen transition pathways.
- Commercial Users:District heating operators, hospitals, and universities with thermal and power requirements. Southeast Asian commercial developers favor smaller aeroderivative units for distributed energy resilience.
Utilities command the established base. The steepest expansion runs through Independent Power Producers as merchant market frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Merchant generators in Texas and Singapore absorb technology premiums for rapid-start aeroderivatives. State-owned utilities in China and India prioritize capital efficiency and domestic content requirements over performance specifications.
United States
Data center load growth in Virginia and Texas drives aeroderivative procurement for sub-10-minute emergency starts. EPA New Source Performance Standards under the Clean Air Act mandate carbon capture readiness assessments for units above 25 MW. The Permian Basin anchors oil and gas sector demand for hydrogen-ready mechanical drive turbines.
China
MIIT efficiency standards accelerate combined cycle deployment as baseload coal retirements outpace renewable buildouts. The country's dual carbon goals tighten emissions thresholds for new gas-fired capacity. Yangtze River Delta utilities concentrate procurement of heavy-duty frames for grid stabilization.
Germany
EU Green Deal hydrogen blending frameworks create guaranteed demand for retrofittable combustion systems. The F-Gas Regulation and national efficiency directives reshape cogeneration specifications for industrial clusters. North Rhine-Westphalia chemical complexes prioritize hydrogen transition pathways in captive power investments.
India
CEA grid codes and coal-to-gas switching mandates drive utility procurement of multi-shaft combined cycle units for renewable balancing. PLI scheme incentives support domestic manufacturing scale-up. Gujarat and Maharashtra industrial corridors anchor captive cogeneration demand under tightening energy intensity norms.
Saudi Arabia
NEOM and Red Sea tourism giga-projects require captive power with explicit hydrogen transition pathways. The country's national energy efficiency program tightens specifications for new industrial power assets. Eastern Province petrochemical sites concentrate demand for large-frame units with ammonia co-firing compatibility.
Natural Gas Turbine Market Competitive Landscape
Full-service OEMs and specialized technology licensors split the market along the service-contract boundary. Consolidation around heavy-duty frame manufacturing contrasts with fragmentation in aeroderivative and small-scale segments. Vertically integrated power equipment conglomerates and independent combustion technology specialists represent the dominant archetypes. Capacity expansion into hydrogen-ready combustion systems and geographic localization through regional service hubs constitute the primary competitive moves.
Within the full-service OEM tier, GE Vernova, Siemens Energy, and Mitsubishi Power exemplify divergent geographic anchoring strategies. GE Vernova leverages its North American installed base for long-term service contract capture. Siemens Energy anchors European aftermarket presence through regionalized technical infrastructure. Mitsubishi Power concentrates Asia-Pacific refurbishment demand with localized engineering teams.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Power |
| Solar Turbines |
| Ansaldo Energia |
| Capstone Green Energy |
| Bharat Heavy Electricals Limited |
| Doosan Enerbility |
| Kawasaki Heavy Industries |
| Others |
Value Network & Pricing Analysis
Single-source dependency for nickel-based superalloys from Russian and Chinese refiners determines both three-tier pricing spreads across premium, standard, and economy equipment tiers and the geographic shape of component sourcing networks. This concentration forces OEMs to absorb input volatility into long-term service contract pricing while accelerating qualification of alternative alloy suppliers.
Pricing Analysis
Aftermarket service revenue tiers—spanning spare parts, scheduled maintenance, and multi-year long-term service agreements—drive lifetime value capture for full-service OEMs. Project-based equipment sales with bundled commissioning support dominate new-order pricing, while price differentiation rests on firing temperature ratings and hydrogen-readiness certification levels. Cost compression in simple cycle peaking units intensifies as battery storage substitutes erode the economic case for emergency backup turbines. State-owned utilities in China and India exhibit highest price sensitivity through centralized procurement mandates, while US independent power producers absorb technology premiums for rapid-start aeroderivatives.
Supply Chain Analysis
Export-control restrictions on advanced casting technologies and superalloy processing equipment limit technology transfer to emerging manufacturing hubs. Supply concentrates in the United States, Germany, and Japan for precision-forged turbine disks and blades, while China dominates rare earth element processing for thermal barrier coatings. Raw material dependencies include nickel-cobalt superalloys, ceramic matrix composites, and specialized high-temperature coatings. Single-source vulnerability for vacuum induction melting capacity creates bottleneck risk for heavy-duty frame production. Distribution runs through OEM-direct sales for large utility projects and specialized EPC contractors for industrial cogeneration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as utility procurement committees unbundle equipment purchases from service agreements, creating entry points for independent combustion specialists and predictive analytics vendors.
For Market Incumbents: Pre-empt service contract fragmentation by locking in digital twin platform subscriptions before warranty expiration, while accelerating backward integration into nickel superalloy recycling to offset Russian refiner exposure. Hydrogen certification timeline uncertainty threatens to freeze next-generation platform investments; anchor defensive positioning through accelerated ISO standard engagement and pilot project partnerships with Japanese utilities on ammonia co-firing retrofits. For New Entrants and Emerging Players: Establish a beachhead in aeroderivative aftermarket hot gas path refurbishment, where OEM service unbundling creates immediate white-space for specialized repair shops with localized technical teams. Southeast Asian state utilities facing budget constraints represent the most penetrable customer segment for competitive service bidding. Target data center developers in Texas and Singapore with sub-10-minute start guarantee contracts as the specific go-to-market angle. For Investors and Strategic Acquirers: Independent combustion technology specialists with proprietary dry low-emissions retrofit kits command scarcity premia as EPA emissions standards tighten. Long-term viability across the analysis window hinges on hydrogen transition pathway credibility rather than current fuel flexibility alone. The signal to watch is final investment decision velocity on 100% hydrogen-ready turbine platforms, which will indicate whether certification uncertainty resolves or extends capital deployment freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Combustion System Development | EU Green Deal certification requirements and Japanese METI ammonia co-firing mandates create guaranteed retrofit demand. |
| Regional Service Hub Localization | Mitsubishi Power's Asia-Pacific engineering teams and Siemens Energy's European infrastructure demonstrate margin capture through proximity. |
| Digital Twin Platform Deployment | Predictive maintenance unbundling fragments traditional service contracts, opening software subscription revenue for analytics specialists. |
| Superalloy Supply Diversification | Qualifying non-Russian, non-Chinese nickel refiners reduces sanctions exposure and input cost volatility for turbine casting. |
| Carbon Capture Readiness Integration | EPA New Source Performance Standards mandate amine-based capture compatibility assessments for Texas and Louisiana projects. |
Research Methodology
The analysis maps combined cycle, simple cycle, cogeneration, and aeroderivative technology configurations, each validated through utility planning officers, independent power producer project developers, EPC contractors, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation against EIA project databases, IEA power sector reports, FERC interconnection filings, and OEM technical documentation established segment boundaries. Bottom-up order book analysis and top-down power sector investment forecasts were triangulated to anchor volume estimates.
Assumptions held fixed include current EPA emissions standards and EU hydrogen blending frameworks, while fuel price trajectories and renewable buildout rates were varied across scenarios. The analytical framework modeled technology type, capacity tier, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level investment flow projections calibrated to announced utility procurement programs. Forecast inputs included coal retirement schedules in China and India, data center load growth curves in Virginia and Texas, and interconnection queue clearance rates in PJM and ERCOT markets.
Stress conditions across nickel alloy price volatility, hydrogen certification timeline delays, and battery storage cost curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that unified ISO standards for 100% hydrogen combustion or abrupt FERC interconnection rule changes could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
United States Turbine Control Systems Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
South America Nuclear Power Plant Equipment Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Europe Power Rental Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Global Hydraulic Power Unit Market