
 Chad Power EPC Market | 2026-2036
Chad Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Chad Power EPC Market Outlook
Hybrid solar-diesel integration is fragmenting conventional thermal-only project design across Chad's power infrastructure landscape. Savannah Energy PLC leverages its upstream oil expertise to anchor gas-to-power development near existing hydrocarbon assets. China Energy Engineering Corporation Limited competes on turnkey delivery speed for transmission backbone projects. Larsen & Toubro Limited specializes in modular EPC execution that reduces deployment timelines for remote site installations.
Chad Power EPC encompasses the integrated engineering, procurement, and construction of electricity generation, transmission, and distribution infrastructure, typically involving 33kV to 132kV substation specifications and PV module mounting structures rated for Sahelian wind loads. Its primary purpose is delivering reliable grid-connected and off-grid capacity to serve a national electrification rate that remains among the lowest globally. Renewable Energy projects are attracting development finance institution capital faster than thermal alternatives, though Thermal Power retains near-term baseload relevance where gas pipeline access exists. Small Scale and Medium Scale installations dominate actual contract flow, while Mega Projects concentrate risk and tie up contractor balance sheets for multi-year periods.
Chad's Ministry of Energy and Petroleum sets licensing terms for independent power producers, while the African Development Bank's environmental and social safeguards shape eligibility for concessional project finance. The country's national regulator for electricity enforces grid code compliance and tariff structures that determine project bankability. Stakeholders must monitor how Chad's integration into the Central African Power Pool alters cross-border transmission priorities and contractor selection criteria.
Market Dynamics
Hybrid solar-diesel integration is collapsing the economic viability of pure thermal baseload design across Chad's power infrastructure, forcing EPC contractors to reengineer procurement and construction workflows around variable renewable penetration.
Growth Catalysts
- Rural Electrification Mandate:Chad's national electrification strategy prioritizes off-grid solar-diesel hybrid deployment in the Logone and Mayo-Kebbi regions, creating dedicated procurement pipelines for modular EPC contracts.
- Development Finance Institution Capital:The African Development Bank's environmental and social safeguards channel concessional financing toward renewable energy projects faster than thermal alternatives, improving project bankability for independent power producers.
- Sahelian Wind Load Engineering:PV module mounting structures rated for extreme wind conditions enable reliable solar generation in Chad's harsh climate, expanding viable project sites beyond previously accessible zones.
Market Restraints
- Diesel Fuel Price Volatility:Remote site operators face input cost instability that erodes hybrid project returns, particularly where gas pipeline access remains absent and liquid fuel must be trucked overland.
- Contractor Balance Sheet Concentration:Mega Projects tie up EPC firm capital for multi-year periods, limiting competitive capacity among mid-tier players and consolidating risk with a narrow supplier base.
- Grid Code Compliance Friction:Chad's national regulator for electricity enforces technical standards that increase commissioning timelines and certification costs for foreign-designed equipment.
Strategic Opportunities
- Central African Power Pool Integration:Chad's evolving cross-border transmission priorities create first-mover positioning for contractors capable of executing 132kV interconnection infrastructure to neighboring markets.
- Modular Execution Methods:Containerized substation and generation packages reduce deployment timelines for remote installations, opening contract flow currently dominated by conventional stick-built approaches.
- Gas-to-Power Pipeline Corridors:Hydrocarbon asset proximity in southern production zones enables thermal baseload development where gas infrastructure investment materializes, anchoring hybrid system design around firm generation capacity.
Industry Challenges
- Skilled Technician Scarcity:Local labor pools lack certified expertise in hybrid inverter commissioning and high-voltage protection relay configuration, forcing costly expatriate deployment or extended training programs.
- Equipment Integration Complexity:Synchronizing solar variability with diesel dispatch algorithms and battery storage management systems demands specialized control engineering that stretches EPC firm technical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chad Power EPC Market |
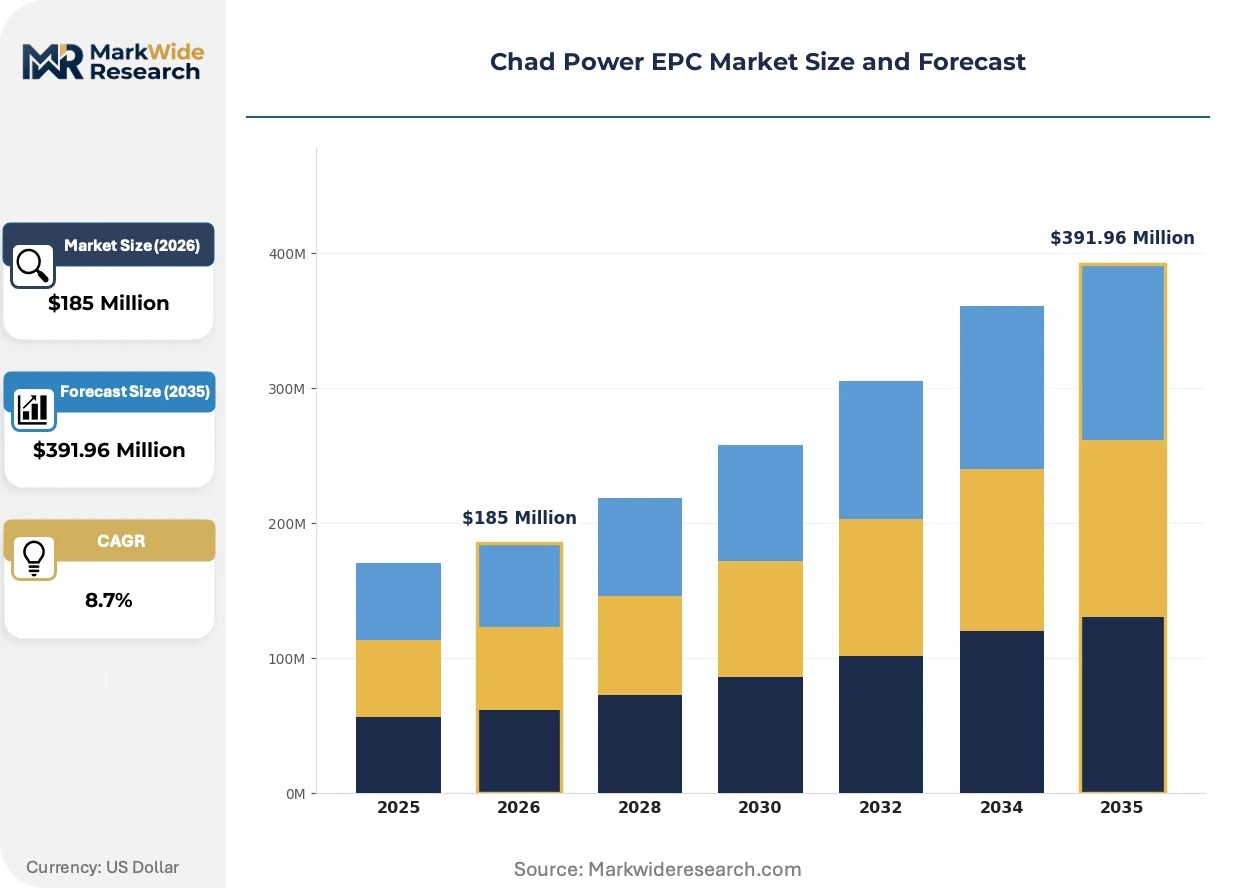
| Market Size in 2026 | $185 Million |
| Market Size in 2035 | $391.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management End User: Utilities, Government, Industrial Players, Commercial Sector Technology: Renewable Energy, Thermal Power, Transmission Systems, Smart Grids Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Savannah Energy PLC, General Electric Company, China Energy Engineering Corporation Limited, MAN Energy Solutions, Siemens AG, Bharat Heavy Electricals Limited, AMEA Power, Larsen & Toubro Limited, Vergnet SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chad Power EPC Market Strategic Shifts
Digital design-to-construction workflows and standardized equipment platforms are compressing project delivery cycles while regulatory pressure on carbon intensity reshapes technology selection criteria across Chad's procurement landscape.
Containerized solar-diesel-battery hybrid systems rated for Sahelian wind loads are collapsing the traditional separation between generation and distribution infrastructure design. Rural electrification agencies in the Mayo-Kebbi region now specify integrated packages that combine PV arrays, diesel gensets, and mini-grid distribution in single procurement lots. This convergence eliminates interface risk between separate EPC contracts and accelerates commissioning timelines for off-grid communities.
Chad's Ministry of Energy and Petroleum licensing terms now embed environmental impact thresholds that favor low-carbon generation technology in independent power producer concessions. The national electrification strategy's renewable energy targets create procurement preference for solar-hybrid configurations where development finance institution co-financing is sought. EPC contractors are responding by pre-qualifying equipment suppliers with verified carbon footprint documentation to maintain eligibility for concessional project pipelines.
Power purchase agreement structures are migrating from take-or-pay thermal contracts toward availability-based remuneration for hybrid systems with storage. Rural electrification fund administrators in the Logone region now unbundle construction financing from long-term service obligations, creating separate competitive tenders for EPC execution and multi-year O&M provision. This split forces contractors to build operational cost assumptions into initial bids rather than recovering margin through captive aftermarket revenue streams.
Chad Power EPC Market Segmentation
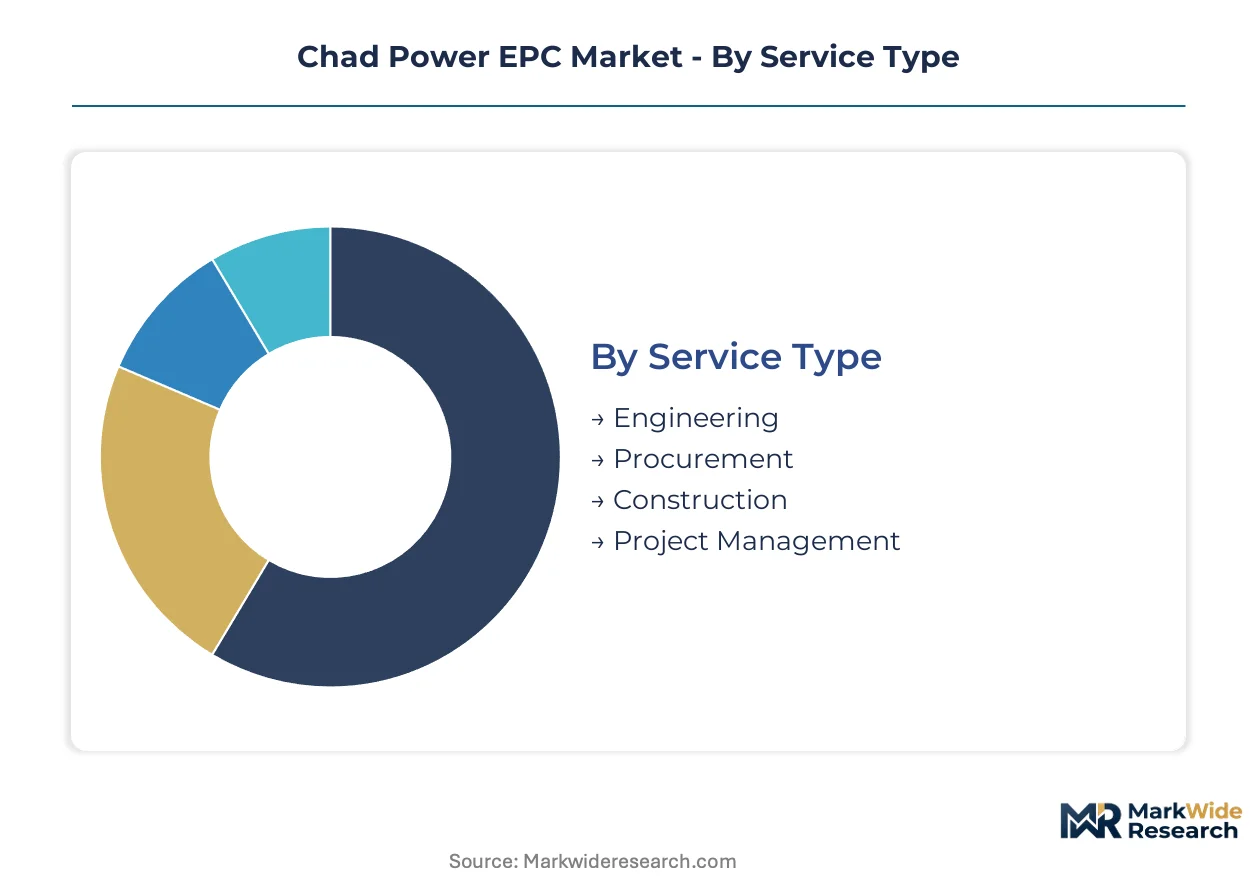
Segmentation in Chad's power EPC market reveals how contractor capabilities align with distinct procurement channels. Each dimension shapes risk profiles, financing structures, and technical competency requirements for project execution.
Service Type:
After-sales service intensity varies sharply across service categories, with long-term asset performance obligations driving contractor selection criteria for independent power producers.
- Engineering:Front-end design services encompass feasibility studies, grid integration modeling, and Sahelian wind load calculations for PV mounting structures. Demand concentrates among development finance institution-backed projects in the Logone region, where environmental impact thresholds mandate detailed technical documentation before financial close.
- Procurement:Equipment sourcing and supplier qualification workflows manage logistics for containerized hybrid systems and 132kV substation components. Remote site operators in Mayo-Kebbi prioritize procurement packages that bundle shipping, customs clearance, and inland transport to mitigate diesel fuel price volatility exposure.
- Construction:Field execution spans civil works, electrical installation, and commissioning for generation and transmission assets. Government electrification programs generate steady contract flow for modular construction methods that reduce deployment timelines in off-grid communities.
- Project Management:Integrated oversight coordinates multi-disciplinary teams across engineering, procurement, and construction phases. Mega Projects tie up management resources for extended periods, limiting mid-tier firm participation in concurrent tenders.
Construction holds the largest share; momentum sits with Project Management as complex hybrid integration demands tighter coordination.
End User:
Customer type determines financing mechanisms and technical specifications, with each end user segment imposing distinct contracting structures and performance guarantees.
- Utilities:State-owned grid operators procure transmission backbone and distribution infrastructure under regulated tariff frameworks. Procurement prioritizes 33kV to 132kV substation specifications that comply with national grid code requirements enforced by Chad's electricity regulator.
- Government:Rural electrification agencies tender off-grid solar-diesel hybrid systems for remote communities. The Ministry of Energy and Petroleum channels concessional financing toward public sector projects that advance national renewable energy targets.
- Industrial Players:Mining and hydrocarbon operators seek captive generation capacity near production assets. Savannah Energy PLC anchors gas-to-power development where pipeline infrastructure exists, favoring thermal baseload with hybrid backup configurations.
- Commercial Sector:Private enterprises contract distributed generation for reliability in grid-constrained zones. Availability-based power purchase agreement structures are displacing conventional take-or-pay contracts for commercial offtakers.
Utilities dominate contract value; commercial sector deployment is expanding most quickly as private capital seeks bankable off-grid opportunities.
Technology:
Technology selection shapes equipment supplier relationships and carbon intensity documentation requirements for concessional finance eligibility.
- Renewable Energy:Solar PV and hybrid systems integrate battery storage and diesel backup for variable generation management. The African Development Bank's environmental safeguards channel capital toward renewable projects faster than thermal alternatives.
- Thermal Power:Gas and diesel generation provides firm capacity where hydrocarbon infrastructure exists. Southern production zones anchor thermal development, though diesel fuel price volatility erodes returns in pipeline-constrained locations.
- Transmission Systems:132kV interconnection infrastructure supports Central African Power Pool integration and cross-border electricity trade. Chad's evolving transmission priorities create positioning for contractors capable of executing regional backbone projects.
- Smart Grids:Digital monitoring and control systems optimize dispatch for hybrid generation and mini-grid distribution. Rural electrification fund administrators increasingly specify smart grid components for remote site operability.
Renewable Energy commands the deepest project pipeline; Smart Grids are gaining share fastest as digital integration becomes standard in new procurement specifications.
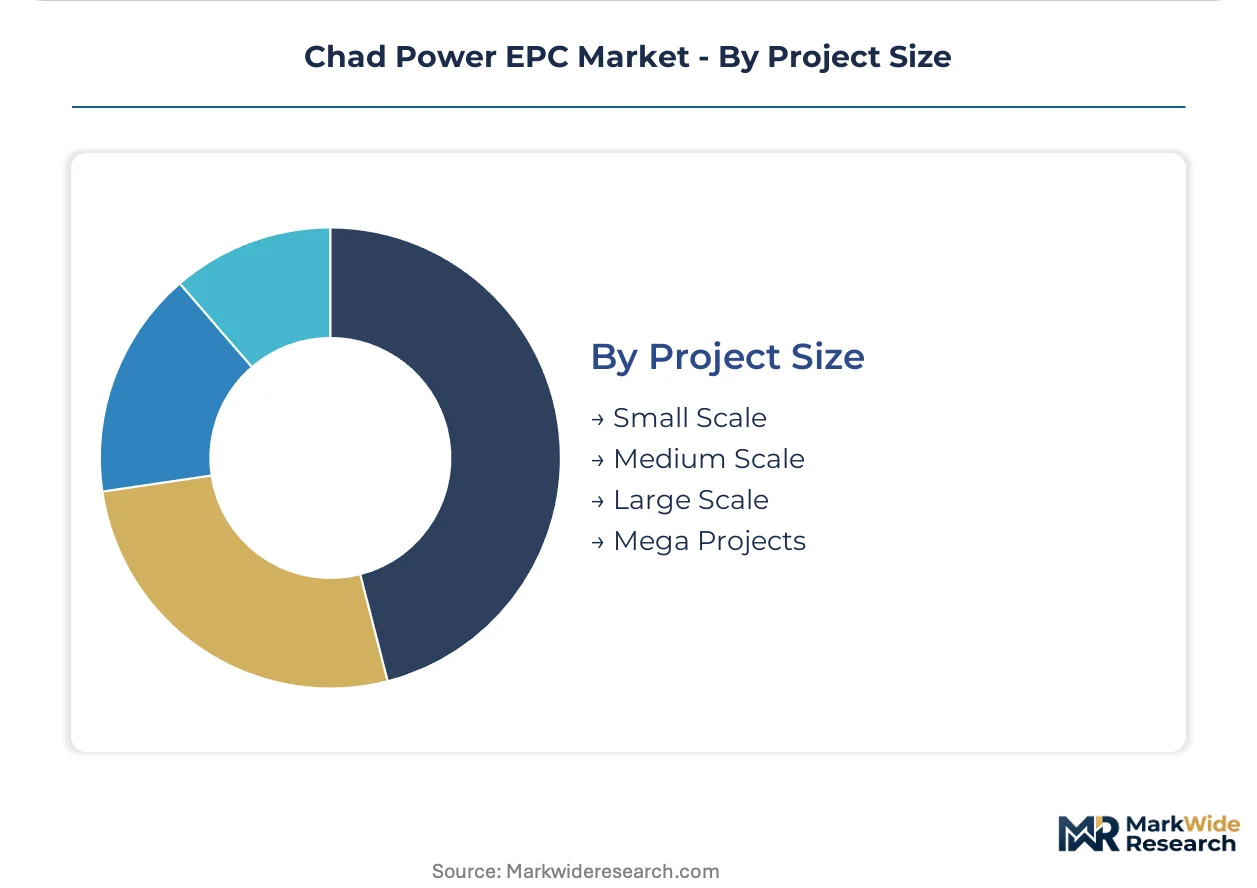
Project Size:
Scale tier determines contractor balance sheet requirements and risk concentration, with procurement patterns shifting toward modular execution methods.
- Small Scale:Containerized generation and distribution packages below 5MW serve isolated communities and commercial facilities. Mayo-Kebbi rural electrification agencies specify integrated procurement lots that collapse traditional design-build separations.
- Medium Scale:5-50MW hybrid installations balance capital efficiency with operational flexibility. Logone region developers favor medium scale projects that match development finance institution ticket sizes without excessive contractor concentration risk.
- Large Scale:50-200MW assets require extended construction timelines and multi-source financing. Grid code compliance friction increases commissioning costs for foreign-designed equipment at this scale.
- Mega Projects:Exceeding 200MW, these developments consolidate risk with narrow supplier bases and tie up EPC firm capital for multi-year periods. Contractor balance sheet constraints limit competitive capacity for mega project tenders.
Medium Scale projects hold the largest share; Small Scale deployment shows the steepest expansion trajectory as modular methods accelerate rural electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chadian EPC contractors source specialized equipment through regional trade corridors, with Nigerian distributors supplying diesel genset components and Chinese manufacturers dominating PV module procurement for southern hybrid installations.
Logone Region
Rural electrification agencies in Logone prioritize solar-diesel hybrid systems for off-grid communities. The Ministry of Energy and Petroleum channels concessional financing toward renewable energy targets through this zone. Moundou city anchors medium-scale project development where development finance institution-backed developers cluster.
Mayo-Kebbi Region
Containerized generation packages serve isolated agricultural processing facilities across Mayo-Kebbi. National electrification strategy mandates specify integrated procurement lots combining PV arrays with mini-grid distribution. Bongor and Pala sub-regions concentrate small-scale EPC contract flow for modular deployment methods.
N'Djamena Capital District
Transmission backbone upgrades and 132kV substation expansion dominate procurement in the capital zone. Chad's national regulator for electricity enforces grid code compliance that shapes equipment selection criteria. The city hosts the headquarters operations of utilities managing cross-border interconnection planning.
Southern Oil-Producing Zone
Gas-to-power development concentrates near Doba basin hydrocarbon assets where pipeline infrastructure exists. Savannah Energy PLC anchors thermal baseload projects with hybrid backup configurations. Kome and Miandoum fields anchor captive generation demand from extraction operators.
Chad Power EPC Market Competitive Environment
Channel-controlling players compete with product-specialist players across Chad's procurement landscape, yielding a tiered structure where integrated EPC firms capture utility-scale contracts and modular specialists dominate rural electrification lots. The market fragments across three strategic archetypes: oil-linked energy conglomerates leveraging upstream assets, Asian turnkey contractors optimizing delivery speed, and Indian modular execution specialists compressing remote site timelines. Competitive moves center on strategic partnerships with development finance institutions and portfolio diversification into hybrid system integration capabilities.
Within the oil-linked energy conglomerate tier, Savannah Energy PLC exemplifies upstream-to-power vertical positioning near southern hydrocarbon assets. Among Asian turnkey contractors, China Energy Engineering Corporation Limited occupies a position emphasizing transmission backbone execution speed. Indian modular specialists anchor the remote installation segment, with Larsen & Toubro Limited representing containerized deployment expertise for off-grid communities in Mayo-Kebbi and Logone regions.
| Leading Market Players |
|---|
| Savannah Energy PLC |
| General Electric Company |
| China Energy Engineering Corporation Limited |
| MAN Energy Solutions |
| Siemens AG |
| Bharat Heavy Electricals Limited |
| AMEA Power |
| Larsen & Toubro Limited |
| Vergnet SA |
| Others |
Value Chain & Pricing Dynamics
Douala-N'Djamena corridor freight costs cascade through Chad's power EPC procurement, amplifying price spreads between coastal-imported equipment and regionally sourced alternatives while compressing margins for contractors dependent on containerized hybrid systems.
Pricing Analysis
Cost-plus contracts with diesel fuel indexation dominate Chad's power EPC procurement, protecting contractors from input volatility while passing through logistics premiums to government and utility offtakers. Price differentiation hinges on Sahelian wind load certification tier and after-sales service bundling duration. Pricing pressure intensifies in the small-scale segment as modular execution methods attract new entrants. Rural electrification agencies exhibit highest price sensitivity, whereas mining operators in the southern oil-producing zone accept premium pricing for expedited commissioning.
Supply Chain Analysis
Contract manufacturing capacity for PV mounting structures and containerized substation enclosures concentrates in China, India, and Turkey, with Chinese suppliers holding dominant share for 132kV switchgear components. Chad's EPC contractors source diesel genset engines from Germany and Japan, drawing from established African distributor networks. Single-source vulnerability runs through Chinese inverter supply for hybrid systems. Distribution runs through Nigerian logistics hubs and Douala port clearance before inland trucking to N'Djamena and southern project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified hybrid control engineering expertise remains scarce across Chad's contractor base, constraining execution capacity for complex solar-diesel-battery integration and elevating premium pricing for qualified EPC firms.
For Market Incumbents: Pre-empt margin erosion in the small-scale segment by securing exclusive procurement relationships with Mayo-Kebbi rural electrification agencies before modular specialists establish beachheads. Anchor defensive positioning through backward integration into containerized equipment fabrication, reducing exposure to Douala-N'Djamena freight cost volatility. For New Entrants and Emerging Players: Establish a beachhead in the commercial sector distributed generation niche, where availability-based power purchase agreement structures favor agile contractors over incumbent utility-scale players. Target N'Djamena capital district commercial offtakers with standardized 500kW-2MW hybrid packages. Differentiate through digital monitoring platform integration bundled into construction financing. For Investors and Strategic Acquirers: Modular EPC specialists with proven Mayo-Kebbi and Logone execution track records represent the most attractive acquisition archetype, capturing rural electrification contract flow without mega-project balance sheet concentration. Monitor Central African Power Pool 132kV interconnection tender announcements as inflection signal for transmission backbone investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration Certification | African Development Bank environmental safeguards now mandate verified carbon footprint documentation for concessional finance eligibility. |
| Containerized Equipment Fabrication | In-house production of PV mounting structures rated for Sahelian wind loads compresses deployment timelines for remote Logone installations. |
| Development Finance Institution Partnership | Preferred contractor status with AfDB unlocks rural electrification pipeline in Mayo-Kebbi and Logone regions. |
| Gas-to-Power Pipeline Corridor Positioning | Proximity to Doba basin hydrocarbon assets anchors thermal baseload development where Savannah Energy PLC operates. |
| Cross-Border Transmission Capability Buildout | 132kV interconnection execution experience positions contractors for Central African Power Pool integration contracts. |
Study Parameters
A standing panel of EPC project managers, utility planning officers, rural electrification fund administrators, and diesel fuel procurement specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through AfDB project disclosure databases, Chad Ministry of Energy and Petroleum licensing records, and regional customs import data. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic scenario modeling.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning service type, end user category, technology class, and project scale tier. CAGRs were derived from installed capacity build-out trajectories and contract award velocity analysis. Forecast inputs incorporated diesel fuel price volatility bands and development finance institution commitment timelines specific to Chad's electrification strategy.
Macroeconomic conditions sit as an overlay; deviation in CFA franc stability, regional security conditions, or AfDB lending capacity would shift the trajectory. Forecasts reflect documented assumptions regarding grid code enforcement consistency and hybrid technology cost curves. Quarterly review of rural electrification agency tender announcements and cross-border transmission planning disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Europe Power Rental Market
Power Equipment
Thailand Power Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Power Conditioning Services Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Romania Power EPC Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Power Analyzers Market