
 Uzbekistan Power EPC Market | 2026-2036
Uzbekistan Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Power EPC Market Analytics
Project finance with sovereign guarantee structures is reconfiguring competitive entry in Uzbekistan's power EPC sector, enabling developers without balance-sheet depth to bid for gigawatt-scale generation assets. ACWA Power leverages its track record in Saudi-Issued project finance to anchor early-mover positioning in Uzbekistan's renewable auction program. Larsen & Toubro sustains engineering-procurement-construction capabilities across thermal and solar verticals through its Indian execution base. Sinohydro Co., Ltd competes on hydropower and civil infrastructure specialization inherited from its parent PowerChina portfolio.
Uzbekistan Power EPC encompasses the integrated engineering, procurement, and construction of power generation facilities, typically involving turbine-generator sets rated from 100 MW to 1,500 MW, balance-of-plant systems, and grid interconnection infrastructure designed to dispatch electricity into the national transmission network operated by the National Electric Grid of Uzbekistan. The construction segment captures the largest value pool given localized civil works, steel erection, and installation labor intensity, while commissioning commands premium margins due to scarcity of certified turbine start-up specialists. Solar PV technology leads new capacity additions under the renewable energy auction framework, though gas turbines retain structural importance for grid stability and winter peak-load coverage.
Uzbekistan's Ministry of Energy and the State Inspectorate for Energy Supervision enforce licensing and technical compliance for generation assets, while environmental permits issued by the State Committee for Ecology align project approvals with national decarbonization commitments. The central bank and finance ministry coordinate foreign-currency convertibility guarantees that determine which consortia can secure offshore project debt. Stakeholders must monitor auction round timing, local-content requirement tightening, and transmission bottleneck resolution in the southern regions to calibrate capital deployment and partnership structures.
Market Dynamics
The presidential renewable energy auction mechanism is redistributing capital flows from state-directed thermal builds toward competitive solar and wind procurement, compressing traditional EPC contracting timelines while elevating foreign developer participation.
Growth Catalysts
- Renewable Auction Framework:Uzbekistan's presidential decree establishing competitive tenders for solar and wind capacity is channeling Saudi, Emirati, and Turkish capital into utility-scale generation parks.
- Transmission Infrastructure Modernization:The National Electric Grid of Uzbekistan is prioritizing 500 kV backbone upgrades in Surkhandarya and Kashkadarya provinces to accommodate renewable dispatch.
- Combined-Cycle Gas Turbine Procurement:Uzbekenergo's sustained appetite for efficient CCGT blocks addresses winter peak-load deficits while stabilizing grid frequency for intermittent renewable integration.
Market Restraints
- Foreign Currency Convertibility Risk:The Central Bank of Uzbekistan's managed exchange-rate regime creates hedging costs that inflate project finance spreads for offshore lenders.
- Local Content Requirement Escalation:Tightening domestic procurement mandates under Ministry of Energy directives strain supply chains lacking certified Uzbek steel fabrication and high-voltage cable capacity.
- Grid Interconnection Queues:Transmission bottleneck resolution in southern regions lags generation construction timelines, forcing developers to absorb extended commissioning delays.
Strategic Opportunities
- Energy Storage Co-Location:Battery energy storage systems paired with solar PV parks in Navoi and Samarkand regions offer arbitrage revenue streams and grid stabilization services.
- Industrial Zone Cogeneration:Textile and chemical clusters in Fergana Valley present captive power demand for gas turbine and waste-heat recovery installations outside regulated utility tariffs.
- Green Hydrogen Pilot Development:The Ministry of Energy's nascent hydrogen roadmap creates early-mover positioning for electrolyzer EPC contractors targeting ammonia export corridors.
Industry Challenges
- Certified Turbine Commissioning Specialist Scarcity:The domestic labor pool lacks Siemens Energy and GE-trained start-up engineers, forcing reliance on fly-in-fly-out expatriate teams at premium cost.
- Legacy Soviet- Era Grid Architecture:Aging 220 kV substations and radial distribution networks require complete protection relay upgrades before accommodating bidirectional renewable flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Power EPC Market |
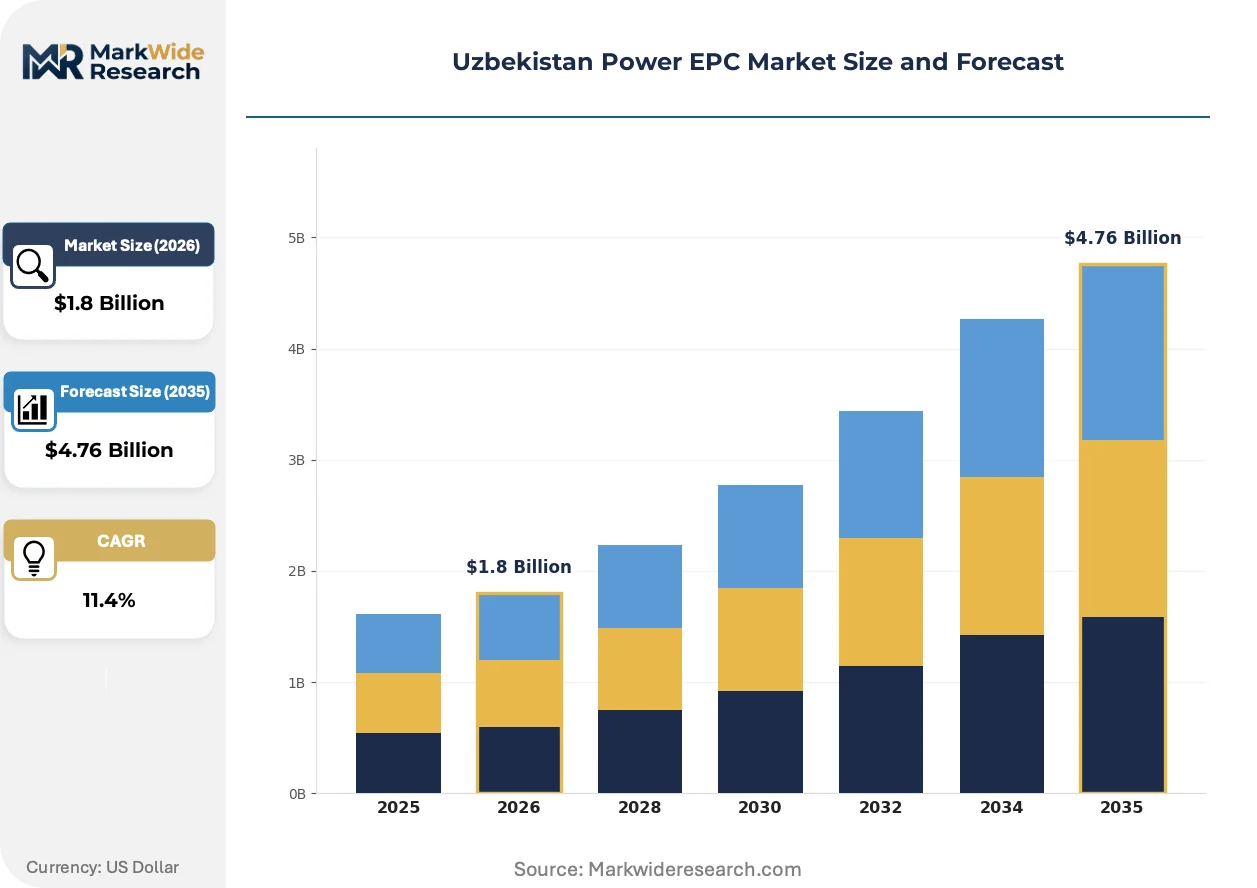
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Procurement, Construction, Commissioning Technology: Solar PV, Wind Turbines, Gas Turbines, Hydropower Power Source: Renewable, Natural Gas, Coal, Nuclear End User: Utilities, Industrial, Residential, Commercial |
| Companies Covered | Larsen & Toubro, Voltalia, ACWA Power, Siemens Energy, TotalEnergies, Masdar Clean Energy Company, Sinohydro Co., Ltd, Federal Hydro-Generating Co RusHydro PAO, Mitsubishi Heavy Industries Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Power EPC Market Evolving Landscape
Digital twin deployment and modular construction methods are compressing EPC schedules while sovereign-backed project finance structures are unlocking non-recourse debt for developers without utility balance sheets.
Solar PV technology is hybridizing with battery energy storage systems in Uzbekistan's auction pipeline, enabling developers to bid capacity factors that firm intermittent generation profiles. ACWA Power and Masdar are structuring 25-year power purchase agreements around DC-coupled solar-plus-storage configurations that dispatch into evening peak periods. This technology pairing is displacing standalone gas peaker economics in the Ministry of Energy's least-cost planning models.
The State Committee for Ecology has aligned environmental permitting timelines with national decarbonization commitments under presidential directive, compressing approval cycles for renewable projects while tightening emissions standards for thermal builds. Coal-fired project pipelines face de facto moratorium as the committee prioritizes air quality targets in Tashkent and industrial centers. Developers are responding by front-loading ecological impact assessments and community consultation phases.
Engineering-procurement-construction contracting is fragmentating into discrete work packages as foreign developers unbundle civil, mechanical, and electrical scopes to optimize local-content compliance. Uzbekenergo's traditional turnkey procurement model is yielding to multi-contractor structures that separate turbine supply from balance-of-plant installation. This unbundling is most visible in the Surkhandarya solar cluster, where Saudi-led consortia subcontract steel erection and cabling to Uzbek construction firms.
Uzbekistan Power EPC Market Segmentation
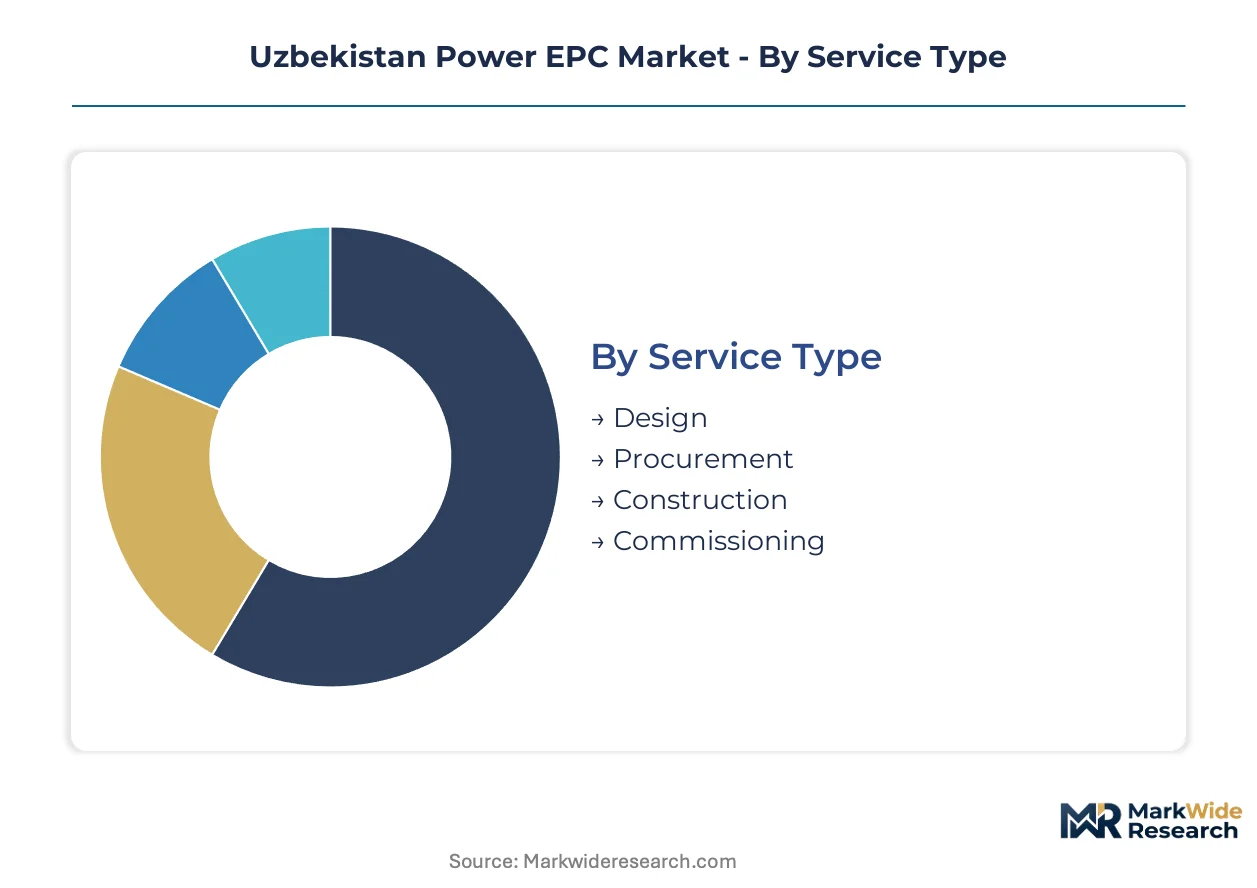
Segmentation in Uzbekistan's power EPC market reveals how contract structures, technology choices, and buyer profiles determine margin capture and partnership requirements. Each dimension shapes procurement patterns and competitive positioning differently.
Service Type:
After-sales-service intensity varies sharply across EPC phases, with commissioning commanding premium technical support while construction relies on localized labor deployment.
- Design:Front-end engineering packages specify turbine-generator configurations and grid interconnection architectures. Demand clusters around Tashkent engineering consultancies serving Uzbekenergo's procurement cycles, constrained by scarcity of certified substation designers familiar with 500 kV backbone standards.
- Procurement:Long-lead equipment sourcing spans gas turbines from Siemens Energy and GE, plus solar modules from Chinese tier-1 manufacturers. Surkhandarya solar developers are consolidating procurement under Saudi-led consortia to exploit scale economies in module and inverter purchasing.
- Construction:Civil works, steel erection, and installation labor dominate value capture. Uzbek construction firms are absorbing subcontractor roles in unbundled EPC structures, though steel fabrication capacity remains bottlenecked.
- Commissioning:Turbine start-up and grid synchronization require fly-in-fly-out specialist teams. Certified Siemens Energy and GE-trained engineers command premium day rates due to domestic capability gaps.
By volume, Construction leads. By growth pace, Commissioning is ahead.
Technology:
Technology selection in Uzbekistan tracks the presidential auction mechanism's technology-neutral bidding, with cost curves and grid stability requirements driving portfolio composition.
- Solar PV:Crystalline silicon modules deployed in utility-scale parks across Navoi and Samarkand regions. ACWA Power and Masdar are pairing DC-coupled configurations with battery storage to capture evening peak dispatch premiums.
- Wind Turbines:Onshore installations targeting Karakalpakstan and Bukhara corridor wind resources. Grid interconnection queues in southern regions delay project energization timelines.
- Gas Turbines:Combined-cycle blocks anchor winter peak-load coverage and frequency stabilization. Uzbekenergo's sustained procurement of efficient CCGT capacity supports renewable integration.
- Hydropower:Civil-intensive projects leverage Sinohydro's dam construction specialization. Mountainous terrain in eastern provinces constrains access logistics and seasonal construction windows.
By installed base, Gas Turbines dominate. By auction pipeline expansion, Solar PV is climbing fastest.
Power Source:
Power source segmentation reflects Uzbekistan's dual-track decarbonization: competitive renewable auctions displacing state-directed thermal procurement while preserving gas capacity for grid stability.
- Renewable:Solar and wind capacity procured through presidential decree auction framework. Foreign developers from Saudi Arabia, UAE, and Turkey dominate winning consortia.
- Natural Gas:CCGT and simple-cycle turbines addressing baseload and peaking requirements. Uzbekenergo's procurement sustains thermal EPC demand despite renewable auction growth.
- Coal:Existing plant maintenance and limited newbuild face de facto moratorium from State Committee for Ecology air quality enforcement. Tashkent emissions targets constrain project approvals.
- Nuclear:Rosatom-VVER technology under intergovernmental agreement. Specialized EPC requirements limit contractor pool to Russian-qualified nuclear construction firms.
By current capacity share, Natural Gas leads. By capital commitment trajectory, Renewable is expanding most quickly.
End User:
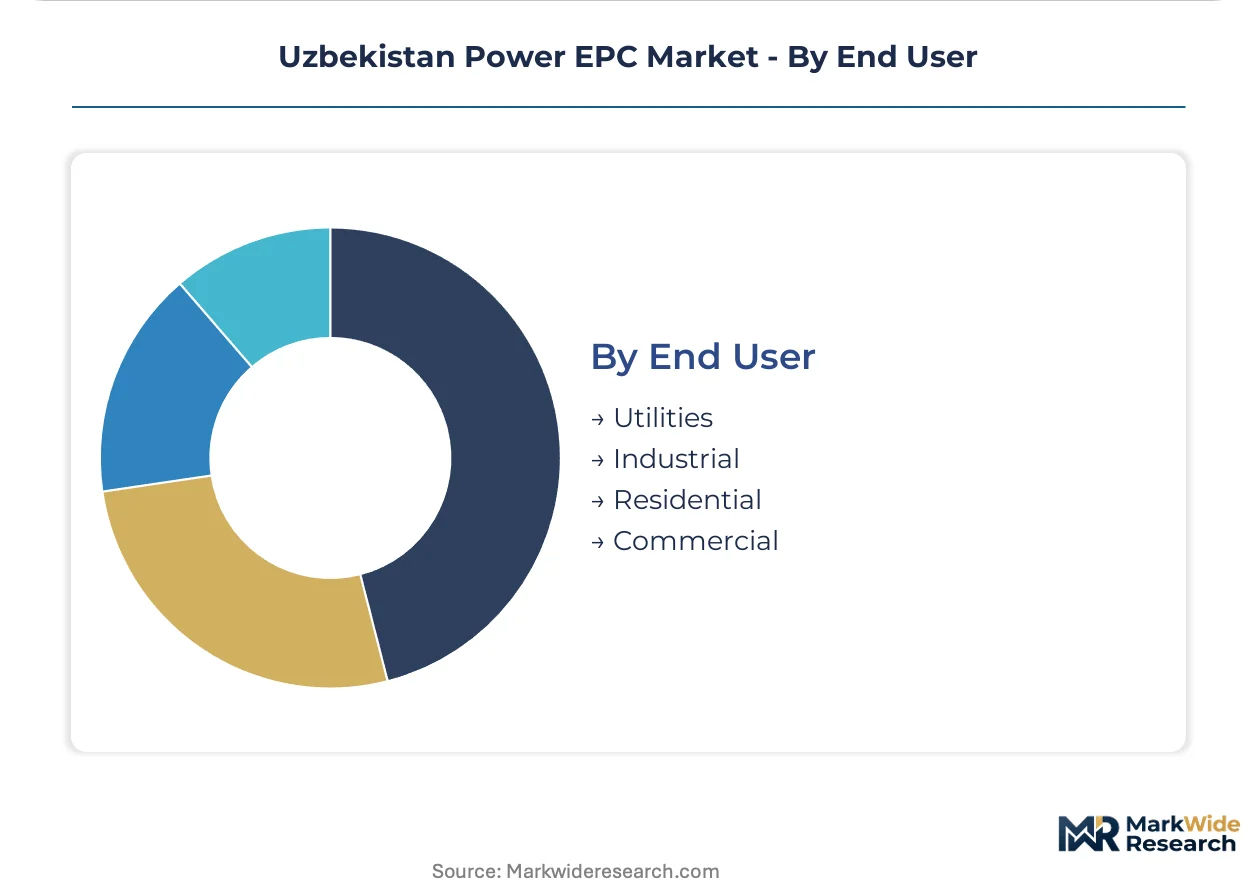
End user segmentation determines tariff structure, offtake security, and local-content compliance intensity across Uzbekistan's power EPC contracts.
- Utilities:Uzbekenergo and National Electric Grid of Uzbekistan procure generation and transmission assets under sovereign-backed project finance. Auction winners secure 25-year power purchase agreements.
- Industrial:Textile and chemical clusters in Fergana Valley pursue captive cogeneration outside regulated tariffs. Gas turbine and waste-heat recovery installations bypass grid interconnection queues.
- Residential:Limited direct EPC engagement given centralized utility procurement model. Distributed solar penetration remains marginal outside pilot programs.
- Commercial:Shopping centers and logistics facilities in Tashkent region trial rooftop solar behind-the-meter installations. Net metering regulations remain under Ministry of Energy development.
By contract value, Utilities dominate. By margin expansion potential, Industrial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Presidential decree auction mechanisms are redistributing capital across Central Asian power infrastructure. Uzbekistan's renewable procurement framework channels Saudi, Emirati, and Turkish investment into utility-scale solar and wind parks.
Tashkent Region
Uzbekenergo's headquarters concentration drives procurement decision-making for national grid assets. The Ministry of Energy coordinates 500 kV transmission upgrades through the National Electric Grid of Uzbekistan. Tashkent engineering consultancies cluster around front-end design packages for combined-cycle gas turbine specifications.
Surkhandarya Province
Solar park development concentrates in this southern corridor due to irradiation profiles and available land banks. ACWA Power and Masdar structure 25-year power purchase agreements for DC-coupled solar-plus-storage configurations. Grid interconnection bottlenecks in Surkhandarya delay project energization timelines relative to construction completion.
Navoi Region
Industrial load centers create captive demand for gas turbine cogeneration outside regulated utility tariffs. Battery energy storage co-location opportunities emerge alongside solar PV parks to capture evening peak dispatch premiums. The State Committee for Ecology prioritizes air quality permits for renewable projects over thermal builds in this industrial zone.
Samarkand Region
Historical infrastructure density complicates greenfield renewable siting but supports distributed generation pilots. Textile clusters in peripheral districts pursue behind-the-meter solar installations pending net metering regulation finalization by the Ministry of Energy. Transmission reinforcement from Surkhandarya substations enables renewable dispatch into Samarkand load centers.
Fergana Valley
Chemical and textile industrial zones present captive power demand for gas turbine and waste-heat recovery installations. Cogeneration projects bypass grid interconnection queues that constrain utility-scale renewable developers in southern provinces. Local-content requirements under Ministry of Energy directives strain supply chains for steel fabrication and high-voltage cable procurement.
Uzbekistan Power EPC Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Uzbekistan's bifurcated procurement environment. Sovereign-backed project finance structures favor developers with established relationships with Saudi and Emirati capital providers. Three archetypes dominate: integrated EPC contractors with thermal and renewable capabilities, renewable pure-plays leveraging auction mechanism familiarity, and equipment suppliers unbundling into balance-of-plant subcontractor roles. Competitive moves center on local-content compliance partnerships and commissioning specialist access.
Within the integrated contractor tier, Larsen & Toubro and Sinohydro Co., Ltd occupy positions anchored to execution capabilities across civil, mechanical, and electrical scopes. ACWA Power exemplifies the capital-anchored developer archetype, structuring project finance around sovereign guarantee mechanisms. Siemens Energy represents equipment-supplier positioning, with turbine supply and commissioning services commanding premium margins amid domestic specialist scarcity. These three patterns illustrate how procurement unbundling is fragmenting traditional turnkey contracting into discrete work packages.
| Leading Market Players |
|---|
| Larsen & Toubro |
| Voltalia |
| ACWA Power |
| Siemens Energy |
| TotalEnergies |
| Masdar Clean Energy Company |
| Sinohydro Co., Ltd |
| Federal Hydro-Generating Co RusHydro PAO |
| Mitsubishi Heavy Industries Ltd |
| Others |
Value Network & Pricing Analysis
Chinese tier-1 solar module manufacturers anchor equipment procurement for Uzbekistan's renewable auction pipeline, concentrating margin capture in module supply and inverter sourcing while compressing balance-of-plant contracting margins for local Uzbek construction firms. This upstream concentration forces EPC consortia to absorb currency hedging costs and local-content compliance premiums downstream.
Pricing Analysis
Certification level for turbine commissioning specialists creates the primary spread between premium and standard EPC bids, with Siemens Energy and GE-trained engineers commanding day-rate premiums that inflate project costs. Project-based long-term offtake structures dominate utility-scale procurement under 25-year power purchase agreements. Price differentiation rests on local-content compliance intensity and after-sales service bundling for grid synchronization support. Cost compression in civil works and steel erection is intensifying as Uzbek construction firms compete for subcontractor roles in unbundled EPC structures. Industrial captive power buyers in Fergana Valley exhibit highest price sensitivity due to tariff avoidance incentives, while utility procurement through sovereign-backed project finance shows lowest sensitivity to upfront capital costs.
Supply Chain Analysis
Tariff exposure between China and Uzbekistan dominates supply chain risk for solar module and inverter procurement, with logistics chokepoints at overland border crossings constraining just-in-time delivery for Surkhandarya solar park construction schedules. Equipment sourcing concentrates in China for crystalline silicon modules and power electronics, Germany for gas turbine generator sets, and South Korea for high-voltage switchgear. Raw material dependencies span polysilicon feedstock, specialized steel forgings for turbine rotors, and copper rod for high-voltage cable production. Distribution runs through Tashkent-based engineering consultancies that coordinate front-end design packages and subcontractor allocation to regional construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
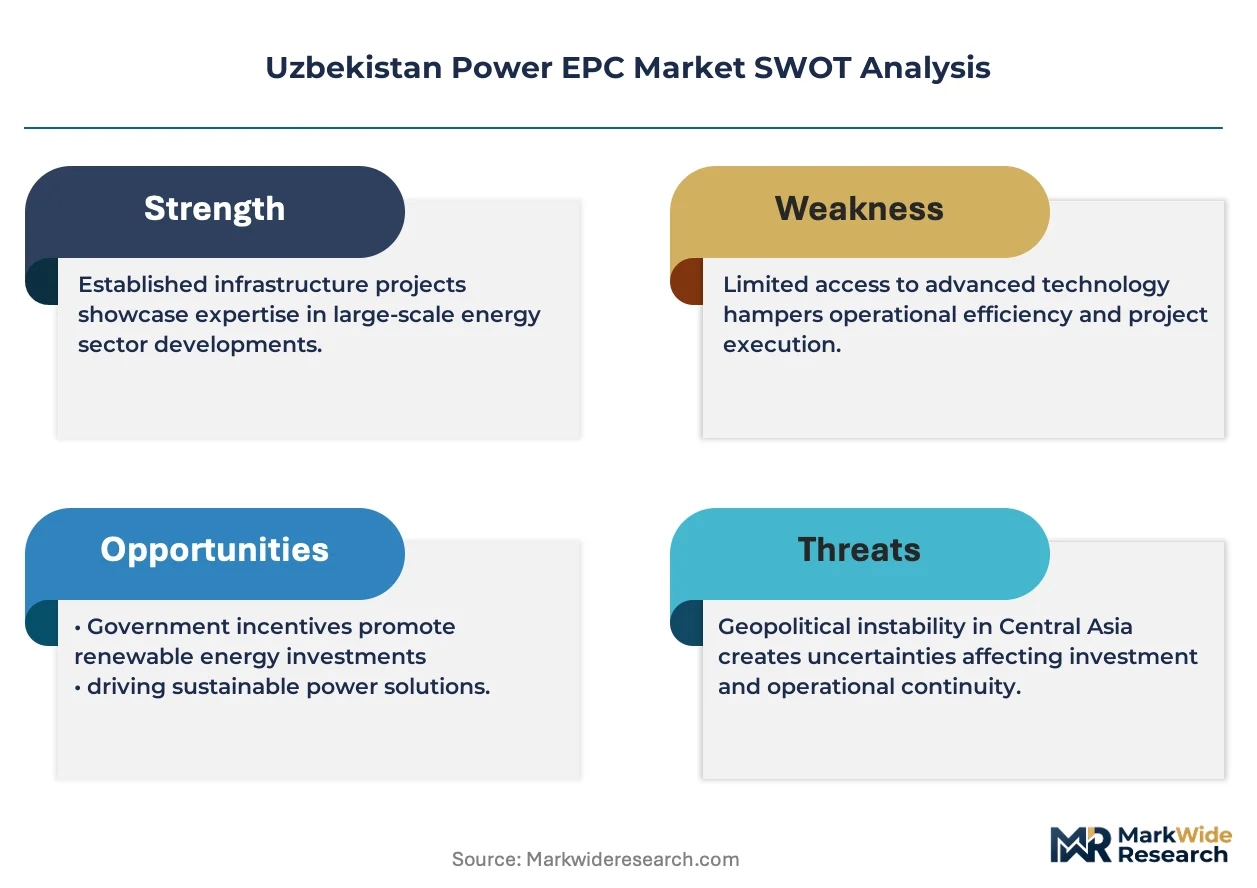
Uzbekistan's presidential renewable energy auction mechanism constitutes a regulatory inflection that is redirecting capital flows from state-directed thermal builds toward competitive procurement, creating high-growth disruption for EPC contractors capable of structuring sovereign-guaranteed project finance.
For Market Incumbents: Entrench positioning by deepening captive supply of certified turbine commissioning specialists through training partnerships with Siemens Energy and GE, insulating against fly-in-fly-out cost inflation that threatens margin compression. Fortify local-content compliance capabilities through backward integration into Uzbek steel fabrication capacity, preempting Ministry of Energy directive tightening that could disqualify foreign-led consortia from auction participation. For New Entrants and Emerging Players: Fergana Valley industrial cogeneration presents the most penetrable white-space target, with textile and chemical clusters seeking captive gas turbine installations outside regulated utility tariffs and grid interconnection queues. Battery energy storage co-location in Navoi and Samarkand regions offers second entry point, leveraging solar-plus-storage auction configurations to capture evening peak dispatch premiums. Go-to-market angle should emphasize modular construction methods that compress EPC schedules and reduce local-content compliance burden. For Investors and Strategic Acquirers: Capital is best deployed toward capital-anchored developer archetypes with established relationships to Saudi and Emirati sovereign wealth funds, given their early-mover positioning in Uzbekistan's renewable auction program. Long-term viability across the projection horizon hinges on transmission bottleneck resolution in southern provinces and auction round timing predictability. Signal to monitor: Ministry of Energy announcements regarding local-content requirement thresholds and foreign-currency convertibility guarantee availability.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | ACWA Power and Masdar leverage 25-year offtake terms to anchor project finance for solar-plus-storage configurations. |
| Local-Content Compliance Partnership | Saudi-led consortia subcontract steel erection to Uzbek construction firms, satisfying Ministry of Energy directives. |
| Commissioning Specialist Training Program | Siemens Energy and GE partnerships address domestic capability gaps that inflate turbine start-up costs. |
| Transmission Infrastructure Co-Investment | National Electric Grid of Uzbekistan prioritizes 500 kV backbone upgrades to accommodate renewable dispatch. |
| Battery Energy Storage Co-Location | DC-coupled configurations enable developers to bid capacity factors that firm intermittent generation profiles. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers at Uzbekenergo, IPP project developers participating in renewable auctions, EPC contractors executing Surkhandarya solar parks, and grid operators at the National Electric Grid of Uzbekistan, then refined through secondary validation against presidential decree texts, Ministry of Energy procurement announcements, State Committee for Ecology permitting databases, and Central Bank of Uzbekistan foreign-exchange policy circulars. Bottom-up project pipeline aggregation was cross-checked with top-down macroeconomic assumptions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from capacity addition trajectories and capital intensity assumptions. Forecast inputs incorporated auction round timing, local-content requirement evolution, and transmission bottleneck resolution schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-directed thermal developers or accelerated green hydrogen pilot deployment would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
India Power EPC Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Air Preheater Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Industrial Gas Turbine Ignition System Market