
 Global Exhaust Heat Recovery System Market | 2026-2036
Global Exhaust Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exhaust Heat Recovery System Market Analysis
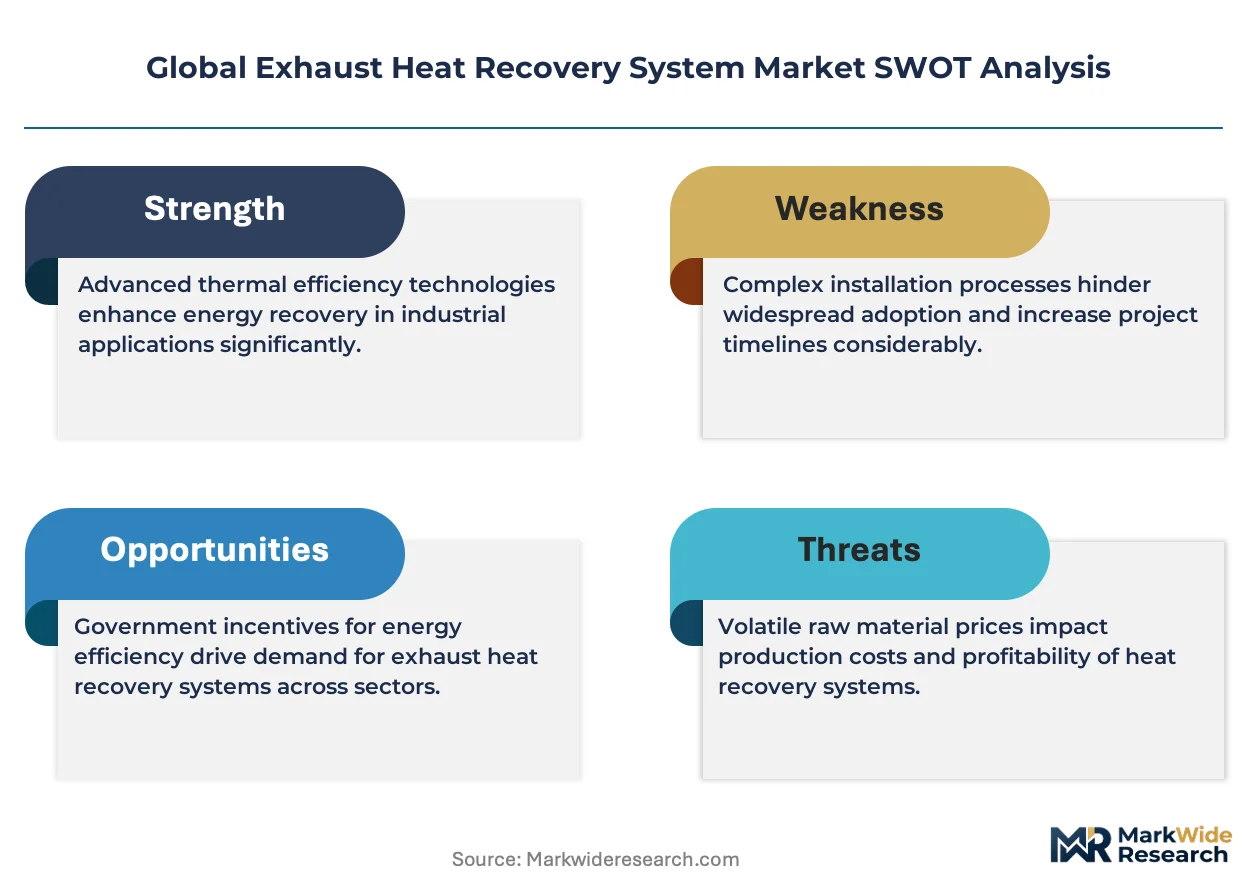
Aftermarket service revenue for thermoelectric module replacement and heat exchanger refurbishment is reshaping margin distribution across the value chain. BorgWarner Inc. leverages its turbocharger installed base to cross-sell exhaust energy recovery kits to commercial fleet operators. Denso Corporation anchors its position through captive thermal management R&D pipelines tied to Japanese automotive OEMs. Continental AG competes by extending its electronics integration capability into hybrid exhaust-to-electric architectures.
Exhaust heat recovery systems capture thermal energy from engine exhaust streams through thermoelectric generators, recuperative heat exchangers, or regenerative Rankine cycle expanders, typically operating at exhaust temperatures between 300°C and 700°C to convert otherwise wasted thermal energy into usable electrical or mechanical power. The primary industrial purpose centers on improving overall system efficiency and reducing fuel consumption in combustion-based powertrains and stationary industrial equipment. Thermoelectric product lines attract concentrated engineering investment due to their solid-state reliability and scalability across vehicle classes, while the automotive end user segment commands the largest absolute spend pool as OEMs face tightening fleet efficiency mandates. The power generation application area shows the steepest trajectory as data centers and distributed industrial facilities seek co-generation compatibility.
The EPA's greenhouse gas standards for heavy-duty engines and the EU F-Gas Regulation on fluorinated coolant containment directly shape product certification requirements and thermal fluid selection for system designers. Japan's METI enforces Top Runner standards that effectively mandate exhaust energy recovery in commercial vehicle platforms above defined weight thresholds. Stakeholders must monitor how China's MEE integrates carbon intensity benchmarks into environmental impact assessments for industrial boiler retrofits, as this will determine retrofit economics across the country's manufacturing base.
Market Dynamics
The EU Green Deal's tightened CO2 standards for commercial vehicles and Japan's METI efficiency mandates are compressing adoption timelines for integrated waste heat recovery architectures. Heavy-duty fleet operators now face compliance-driven procurement cycles that favor thermoelectric retrofits over incremental engine improvements.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated coolant containment rules are forcing thermal fluid selection toward exhaust-compatible working fluids in Rankine cycle systems. Commercial vehicle OEMs in Germany accelerate platform redesigns to accommodate integrated recovery.
- Steel and cement producers:China's NMPA emissions rules and provincial carbon caps in industrial corridor cities are mandating boiler retrofit programs. Waste heat recovery becomes the lowest-cost compliance pathway for facilities above 50MW thermal input.
- Thermoelectric generators:Solid-state reliability and scalability across vehicle weight classes attract concentrated R&D investment. Heavy-duty trucking fleets in Japan expand retrofit adoption ahead of Top Runner enforcement thresholds.
Market Restraints
- Input cost volatility:Bismuth telluride and skutterudite thermoelectric materials face concentrated supply from Chinese rare earth processors. Price swings compress module margins and deter long-term supply contracts.
- Technical limitation:Thermoelectric conversion efficiency remains capped below 8% for automotive temperature gradients. System designers must oversize heat exchanger surface area to hit power targets, adding mass and packaging constraints.
- Regulatory friction:EPA greenhouse gas standards for heavy-duty engines lack harmonized test cycles with EU CO2 protocols. Dual certification burdens delay product launches and fragment engineering resources.
Strategic Opportunities
- Data center co-generation:Distributed computing facilities seek exhaust-to-electric compatibility for on-site power resilience. Rankine expander suppliers target hyperscale campuses in Germany and Japan with modular containerized units.
- Hybrid exhaust-to-electric architectures:Electronics integration capability from automotive tier-1s converges with thermal management expertise. This convergence enables packaged solutions that combine thermoelectric modules with DC-DC conversion and battery buffering.
- Aftermarket channel expansion:Thermoelectric module replacement and heat exchanger refurbishment reshape margin distribution. Fleet operators in Japan favor service contracts that unbundle hardware from lifecycle maintenance.
Industry Challenges
- Thermal systems engineering talent:Cross-disciplinary expertise spanning heat transfer, semiconductor physics, and power electronics remains scarce. OEMs and suppliers compete for limited candidates with Rankine cycle or thermoelectric device experience.
- Integration complexity with legacy powertrains:Retrofit installations must accommodate variable exhaust backpressure constraints and existing aftertreatment positioning. Calibration conflicts with SCR and DPF regeneration cycles delay field deployment.
- Certification timeline compression:China's MEE integrates carbon intensity benchmarks into environmental impact assessments for industrial boiler retrofits. Engineering teams must accelerate validation protocols while maintaining safety margins for high-temperature operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exhaust Heat Recovery System Market |
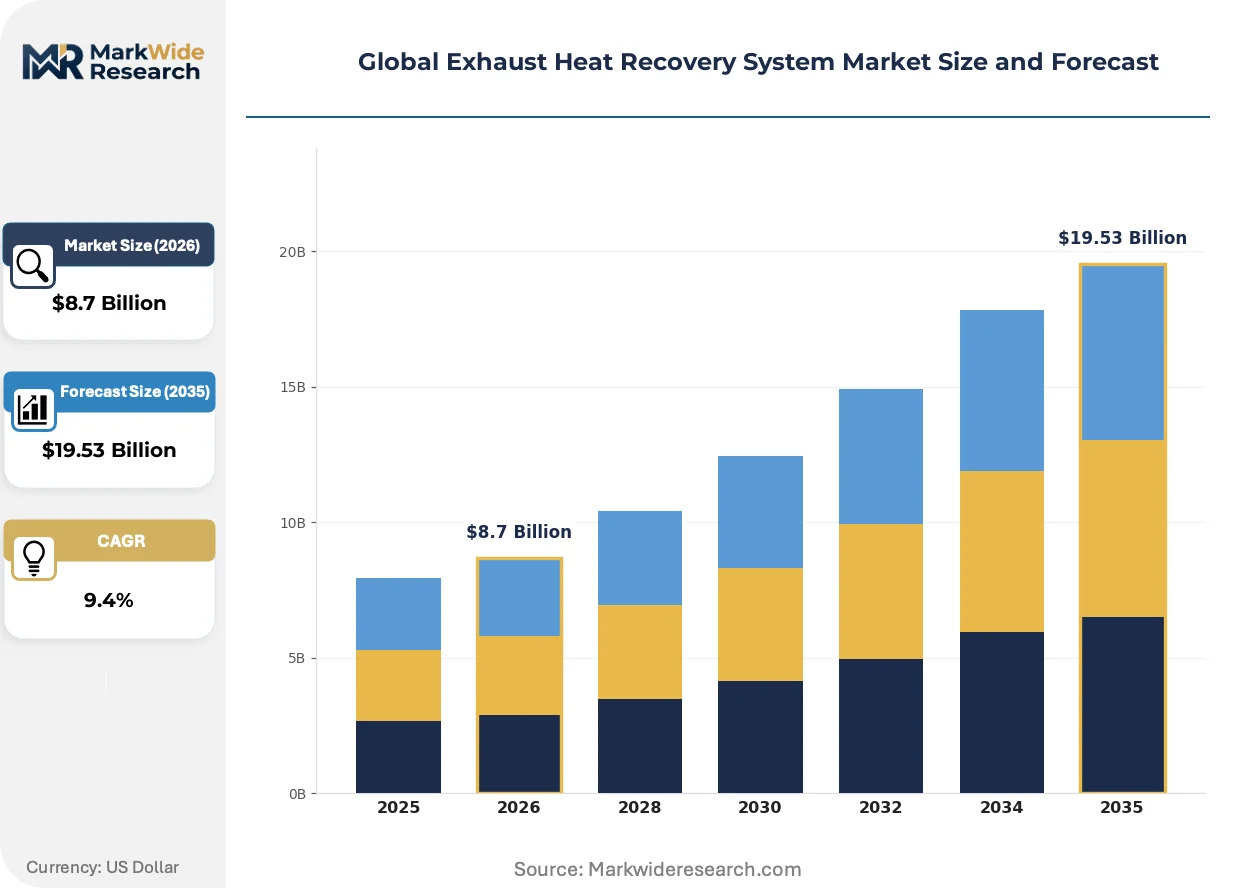
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regenerative, Recuperative, Thermoelectric, Heat Exchangers End User: Industrial, Automotive, Marine, Commercial Application: Power Generation, Waste Heat Recovery, HVAC, Process Heating Technology: Mechanical, Electrical, Hybrid, Solar |
| Companies Covered | BorgWarner Inc., Continental AG, Denso Corporation, Robert Bosch GmbH, Mitsubishi Heavy Industries Ltd., Faurecia, Cummins Inc., Mahle GmbH, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exhaust Heat Recovery System Market Emerging Trajectories
Solid-state thermoelectric architectures are collapsing the traditional trade-off between conversion efficiency and mechanical complexity. Three interconnected developments are compressing product development cycles and reshaping competitive positioning.
Segmented thermoelectric generator designs using functionally graded materials are collapsing the temperature mismatch between exhaust streams and semiconductor junctions. Heavy-duty truck OEMs in Germany and Japan adopt these architectures for 2027 platform launches. The technology is collapsing the historical 15-year gap between laboratory ZT improvements and fielded automotive products.
Japan's METI Top Runner standards now effectively mandate exhaust energy recovery in commercial vehicle platforms above defined weight thresholds. The regulation compresses product planning cycles for domestic OEMs and their captive suppliers. Japanese fleet operators respond by pre-committing to retrofit programs ahead of statutory deadlines.
Service unbundling is altering how fleet operators procure thermal recovery hardware. Direct contracting with module suppliers for replacement cycles is displacing bundled OEM service agreements in European commercial vehicle markets. Germany's independent truck service networks capture growing share of thermoelectric refurbishment revenue.
Global Exhaust Heat Recovery System Market Segmentation
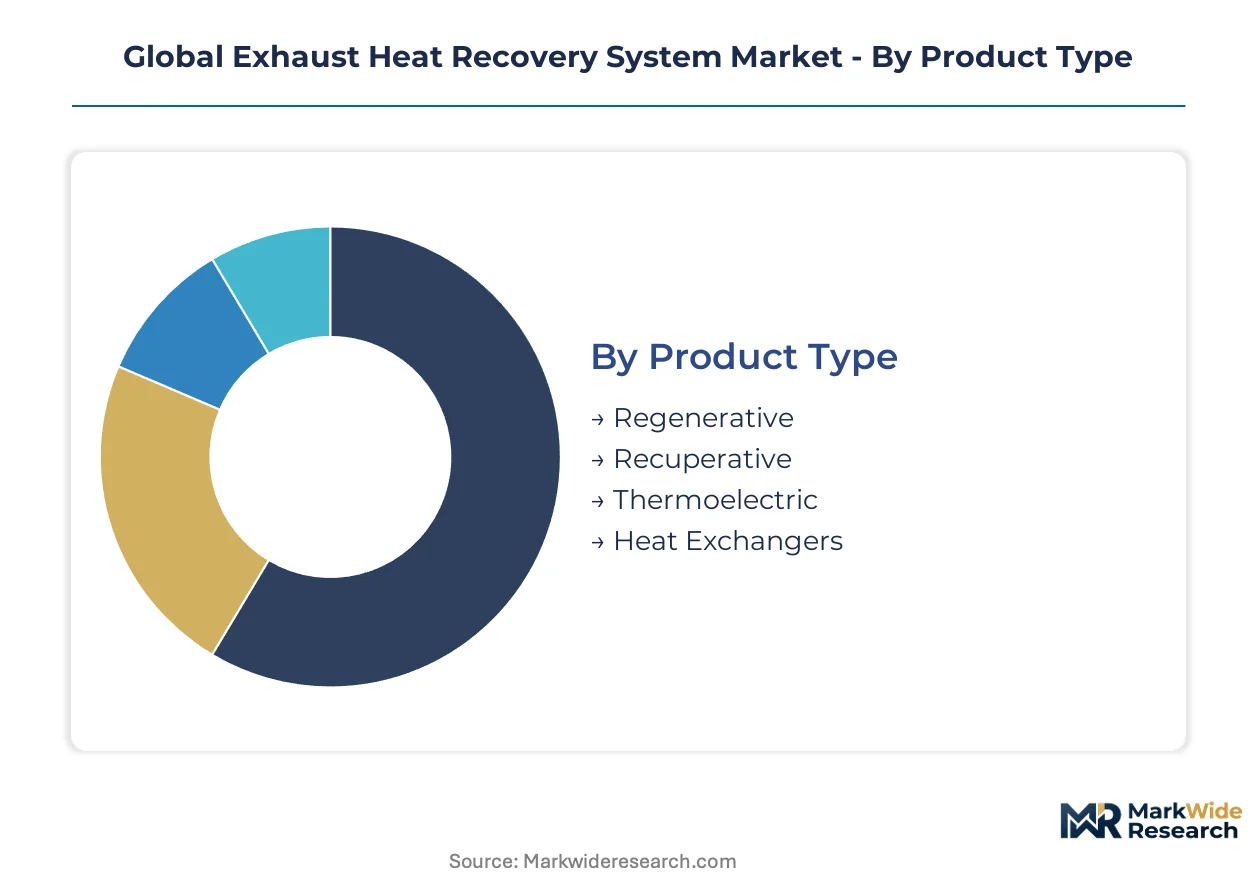
Technology selection in exhaust heat recovery hinges on temperature gradient, backpressure tolerance, and integration complexity. Product architecture determines whether systems serve as primary power augmentation or secondary efficiency gains. End-use segmentation reveals divergent procurement patterns between compliance-driven fleet operators and industrial facilities seeking co-generation economics.
Product Type:
Mature recuperative designs dominate installed base volumes while emerging thermoelectric architectures reshape R&D allocation across supplier portfolios.
- Thermoelectric:Solid-state semiconductor junctions convert thermal gradients directly to electrical output without moving parts. Japanese heavy-duty fleets pre-commit to retrofit programs ahead of METI Top Runner enforcement, favoring reliability over peak efficiency.
- Recuperative:Counter-flow heat exchangers transfer exhaust thermal energy to working fluids or intake air streams. German commercial vehicle OEMs accelerate platform redesigns under EU F-Gas Regulation pressure, integrating these systems with existing turbocharger architectures.
- Regenerative:Cyclic thermal storage media capture and release heat in batch processes. Steel producers in China's industrial corridor cities deploy these for batch furnace applications under NMPA emissions rules.
- Heat Exchangers:Shell-and-tube or plate-fin configurations manage thermal transfer rates. Marine operators favor these for salt-air corrosion resistance in exhaust stream environments.
Recuperative systems retain volume leadership; thermoelectric configurations hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive industrial deployments from fleet procurement cycles governed by regulatory compliance deadlines.
- Automotive:OEM integration of exhaust recovery modules with aftertreatment systems requires calibration coordination with SCR and DPF regeneration cycles. EU Green Deal CO2 standards compress adoption timelines for German and Japanese commercial vehicle platforms.
- Industrial:Steel and cement producers above 50MW thermal input face China's NMPA emissions rules and provincial carbon caps. Waste heat recovery offers the lowest-cost compliance pathway for boiler retrofit programs.
- Commercial:Distributed facilities and independent fleet operators procure through aftermarket channels. Service unbundling allows direct contracting with module suppliers for replacement cycles.
- Marine:Vessel operators prioritize salt-air corrosion resistance and packaging constraints in engine room environments. IMO efficiency standards drive adoption in deep-sea shipping routes.
Industrial end users command absolute spend levels; automotive applications are climbing the fastest.
Application:
Volume concentration centers on waste heat recovery while power generation applications attract the most rapid capacity additions.
- Power Generation:Rankine cycle expanders and thermoelectric modules produce electrical output for on-site consumption or grid export. Data centers in Germany and Japan seek exhaust-to-electric compatibility for resilience against utility disruptions.
- Waste Heat Recovery:Thermal energy recapture improves overall system efficiency in combustion-based processes. Cement kilns and steel blast furnaces represent the primary deployment sites under Chinese environmental enforcement.
- HVAC:Recovered thermal energy drives absorption chillers or preheats ventilation air streams. Commercial building operators in climate-intensive regions favor these for baseline load reduction.
- Process Heating:Direct thermal integration with industrial drying, curing, or chemical reaction stages. Food processing and paper manufacturing facilities deploy these for continuous thermal demand matching.
Waste heat recovery retains volume leadership; power generation applications hold the steepest expansion curve.
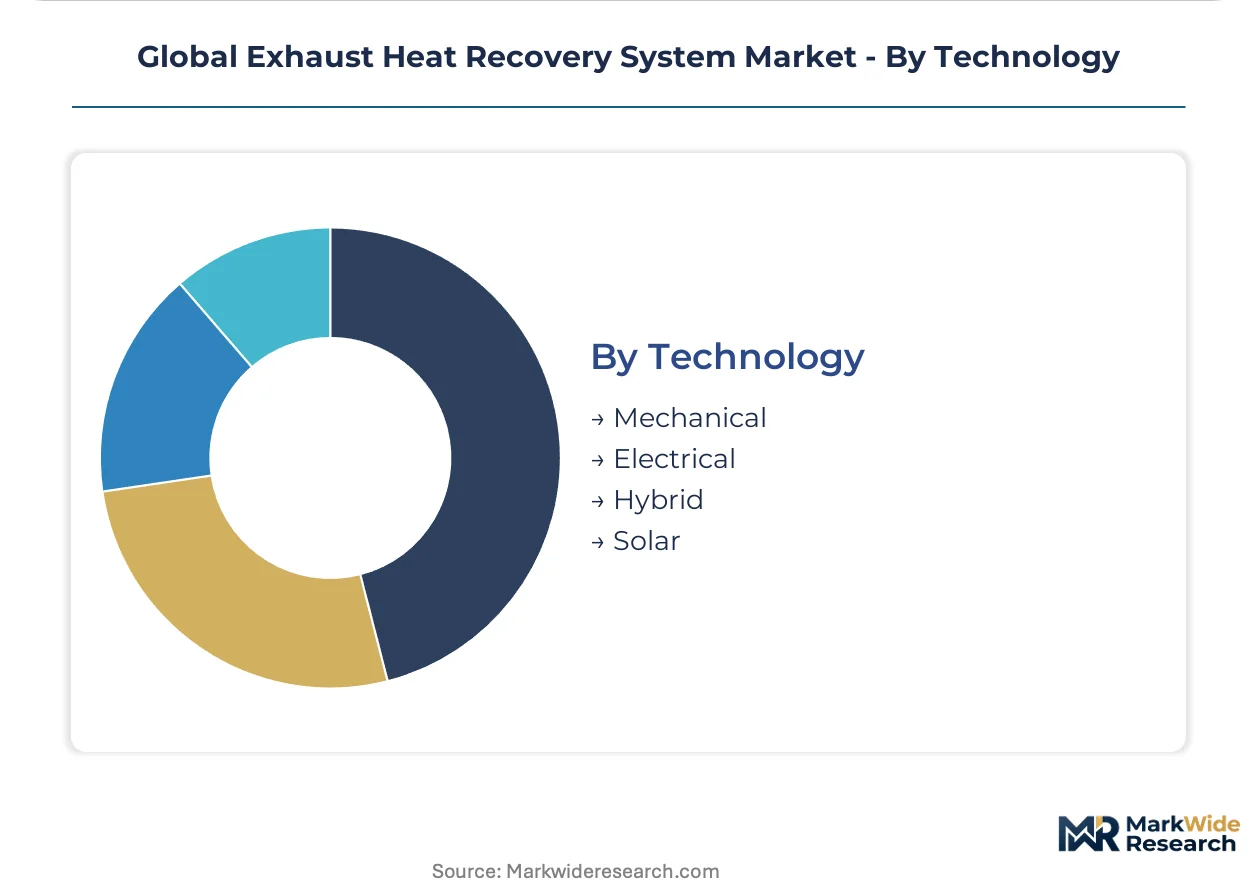
Technology:
Supply concentration in rare earth processing shapes material cost structures across electrical and hybrid system categories.
- Electrical:Thermoelectric generators and solid-state power conditioning eliminate mechanical wear components. Bismuth telluride and skutterudite supply concentration in Chinese processors creates input cost volatility for module manufacturers.
- Hybrid:Combined mechanical-electrical architectures integrate Rankine expanders with thermoelectric topping cycles. Japanese automotive OEMs and captive suppliers concentrate R&D investment here for 2027 platform launches.
- Mechanical:Turbo-compounding and Rankine cycle expanders convert thermal energy to rotational mechanical output. These configurations suit heavy-duty trucking applications where mechanical power take-off is preferred.
- Solar:Concentrated solar thermal integration with exhaust recovery for hybrid renewable-thermal systems. Industrial facilities in high-insolation regions pilot these for carbon-neutral process heat targets.
Electrical technology retains volume leadership; hybrid architectures hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators deploy thermoelectric retrofits primarily for CO2 compliance, while Japanese buyers prioritize reliability metrics ahead of METI deadlines. Chinese industrial procurement concentrates on boiler retrofit economics under provincial carbon caps.
United States
Heavy-duty trucking fleets in the Midwest and Southeast accelerate thermoelectric generator adoption ahead of EPA greenhouse gas enforcement phases. The EPA's greenhouse gas standards for heavy-duty engines compress procurement cycles for integrated waste heat recovery. Fleet concentration in Ohio and Michigan drives aftermarket service channel development for module replacement.
Germany
Commercial vehicle OEMs redesign platforms to accommodate exhaust energy recovery kits alongside existing turbocharger architectures. The EU F-Gas Regulation on fluorinated coolant containment shapes thermal fluid selection for Rankine cycle systems. Industrial clusters in North Rhine-Westphalia pilot Rankine expander installations for steel producer compliance.
Japan
Heavy-duty fleet operators pre-commit to retrofit programs ahead of METI Top Runner enforcement thresholds for commercial vehicles above defined weight limits. METI efficiency mandates effectively mandate exhaust energy recovery in domestic commercial vehicle platforms. Captive supplier relationships in the Nagoya industrial corridor concentrate R&D investment for 2027 platform launches.
China
Steel and cement producers in the Yangtze River Delta and Pearl River Delta face dual pressure from NMPA emissions rules and provincial carbon caps. The MEE integrates carbon intensity benchmarks into environmental impact assessments for industrial boiler retrofits. Manufacturing facilities above 50MW thermal input in Shandong and Hebei provinces select waste heat recovery as the lowest-cost compliance pathway.
South Korea
Automotive OEMs in the Seoul Capital Area develop hybrid exhaust-to-electric architectures combining thermoelectric modules with power electronics integration. Domestic efficiency standards for commercial vehicles tighten ahead of 2027 implementation. Busan-Ulsan industrial complexes deploy recuperative heat exchangers for marine engine applications under IMO efficiency standards.
Global Exhaust Heat Recovery System Market Vendor Landscape
Capability concentration sits with tier-1 automotive suppliers possessing captive thermal management R&D pipelines; scale advantage sits with diversified industrial conglomerates with cross-sector energy recovery portfolios. The market structures around three archetypes: turbocharger-anchored system integrators, captive automotive thermal specialists, and diversified industrial equipment suppliers. Competitive moves center on cross-selling exhaust energy recovery kits to existing installed bases and extending electronics integration capability into hybrid architectures.
Among German-based diversified suppliers, Continental AG and Robert Bosch GmbH occupy positions emphasizing electronics integration and powertrain system architecture. BorgWarner Inc. exemplifies the turbocharger-anchored archetype, leveraging existing commercial fleet relationships for aftermarket exhaust recovery kit penetration. Denso Corporation represents the captive automotive thermal specialist model, with R&D pipelines tied directly to Japanese OEM platform cycles.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Mitsubishi Heavy Industries Ltd. |
| Faurecia |
| Cummins Inc. |
| Mahle GmbH |
| Aptiv |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese rare earth processing facilities is compressing thermoelectric material margins while simultaneously creating procurement leverage for module assemblers in Germany and Japan. This utilization dynamic forces suppliers to absorb cost volatility through contract renegotiation rather than pass-through pricing.
Pricing Analysis
Long-term offtake contracts dominate procurement for bismuth telluride and skutterudite feedstock, insulating Japanese automotive OEMs from spot market swings. Price differentiation rests on certification grade for EU F-Gas Regulation compliance and volume scale for fleet retrofit programs. Cost compression in thermoelectric modules is intensifying because Chinese processors compete on throughput rather than margin. Aftermarket service providers exhibit highest price sensitivity due to unbundled procurement patterns.
Supply Chain Analysis
Export control regimes restricting advanced semiconductor manufacturing equipment have limited secondary processing capacity expansion outside China. Geographic supply concentration centers on Chinese rare earth extraction, Japanese precision metallurgy, and German heat exchanger fabrication. Raw material dependencies span bismuth telluride, skutterudite compounds, and high-grade aluminum alloys for heat exchanger cores. Single-source vulnerability in Chinese rare earth refining creates structural risk. Distribution runs through captive supplier networks for automotive OEMs and independent service channels for fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Exhaust Heat Recovery System Market is entering a cyclical recovery phase as heavy-duty fleet replacement cycles align with EU and Japanese regulatory enforcement windows. Capital expenditure timing for industrial boiler retrofits in China reinforces this cyclical upturn.
For Market Incumbents: Pre-empt margin erosion in thermoelectric modules by securing captive supply agreements for skutterudite feedstock ahead of Chinese export quota tightening. Extend electronics integration capability into hybrid architectures before Tier 2 suppliers consolidate power electronics competence. Channel control through aftermarket service contracts offers defensive positioning against unbundled procurement trends.
For New Entrants and Emerging Players: Southeast Asian marine engine retrofits represent the most penetrable white-space opportunity given limited incumbent presence and IMO efficiency standard enforcement. Target data center co-generation installations in Germany with modular Rankine container units where established automotive suppliers lack project development experience. Direct sales to independent fleet operators bypasses captive OEM supply relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket service providers with thermoelectric module replacement contracts. Long-term viability favors targets with cross-sector energy recovery portfolios spanning automotive and industrial applications rather than pure-play automotive exposure. Monitor EPA-EU regulatory harmonization progress as the inflection signal for accelerated product launch timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Thermal Material Supply | Backward integration into skutterudite processing insulates margins from Chinese quota volatility. |
| Hybrid Architecture Development | Electronics-thermal convergence enables packaged solutions combining thermoelectric modules with DC-DC conversion. |
| Aftermarket Service Unbundling | Direct fleet contracting for module replacement displaces bundled OEM agreements in European markets. |
| Data Center Co-Generation Partnership | Rankine expander suppliers target hyperscale campuses in Germany and Japan with modular containerized units. |
| Regulatory Certification Pre-Positioning | EU F-Gas Regulation compliance investment accelerates platform redesign cycles for commercial vehicle OEMs. |
Methodological Framework
A spread of perspectives from thermal systems engineers, fleet procurement managers, aftermarket service directors, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement timelines, EU F-Gas Regulation implementation guidance, METI Top Runner standard documentation, and Chinese MEE environmental impact assessment protocols. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, end-user industry, application area, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle timing. Industry-specific forecast inputs incorporated fleet turnover rates for heavy-duty trucking and industrial boiler retrofit economics under Chinese provincial carbon caps.
Practitioners should monitor regulatory harmonization progress between EPA and EU test cycles, Chinese rare earth export policy shifts, and thermoelectric conversion efficiency breakthroughs for early signals of forecast deviation. Forecasts reflect assumptions about enforcement timeline adherence and material cost stability. Material shifts in Sino-Japanese trade flows or METI mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Power System Simulator Market
Power Equipment
France Power EPC Market
Power Equipment
Power Analyzers Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Australia Power EPC Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Power Cables Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
United States Turbine Control Systems Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Steam Turbine Control System Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
United States Power Rental Market