
 Solar PV Panels Market | 2026-2036
Solar PV Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Panels Market Analytics
The split between premium N-type monocrystalline output and commodity-grade polycrystalline supply is rebalancing as module efficiency thresholds harden in utility tenders. JinkoSolar leverages vertical integration across polysilicon and cell stages to defend margin pools in high-efficiency segments. Trinasolar anchors its position through geographic diversification across emerging Asian and Latin American markets. LONGi Green Energy dominates the monocrystalline wafer layer, sustaining technology leadership through proprietary silicon pulling processes.
Solar PV panels are semiconductor devices that convert photon energy into direct-current electricity through p-n junction cells, typically fabricated from crystalline silicon ingots sliced into wafers with anti-reflective coatings and encapsulant layers. Their primary commercial purpose is to generate grid-connected or distributed renewable power at declining levelized cost of energy. Monocrystalline modules command the largest share of new capacity additions due to superior conversion efficiency in space-constrained applications. Thin-film technology occupies niche roles in utility-scale desert installations where temperature coefficients favor cadmium-telluride performance. Bifacial panels represent the fastest-expanding product category as tracking systems and albedo-optimized ground cover amplify energy yield per installed watt.
FERC interconnection standards in the United States, the EU Green Deal's renewable energy directives, and India's CEA grid codes collectively shape module certification requirements, inverter compatibility mandates, and domestic manufacturing incentives that determine market access. China's MIIT sets cell efficiency benchmarks and production capacity quotas that ripple through global supply availability. Stakeholders must monitor evolving carbon-border adjustment mechanisms and country-of-origin rules that threaten to fragment procurement strategies across major demand centers.
Market Dynamics
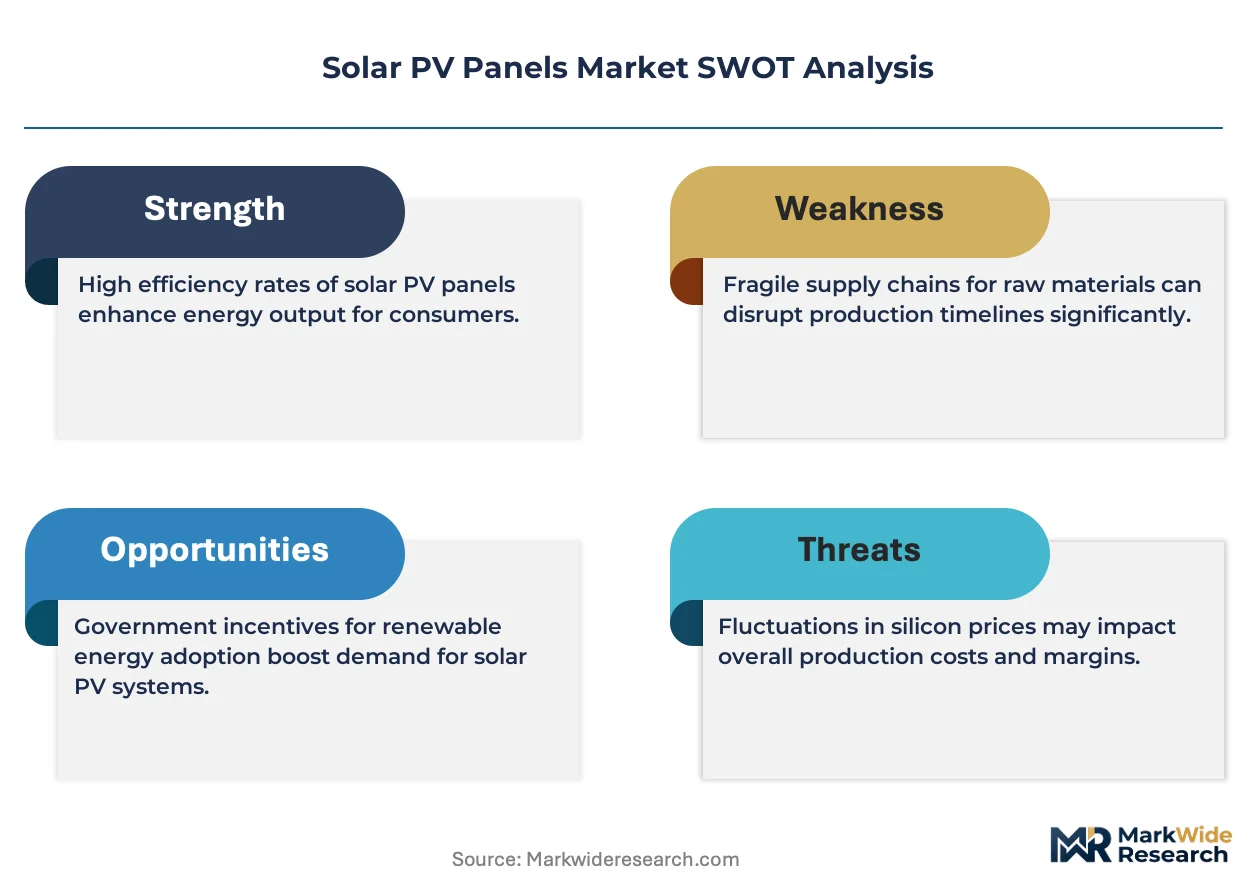
The bifacial module transition is compressing supply chains as albedo-optimized ground cover and tracking systems force efficiency thresholds upward, marginalizing legacy monofacial capacity and reshaping procurement specifications across utility-scale tenders.
Growth Catalysts
- EU Green Deal domestic content mandates:Renewable portfolio standards in multiple European jurisdictions tighten local manufacturing requirements, redirecting procurement toward certified European supply bases.
- Albedo-optimized desert installations:Utility developers in India's western desert states deploy bifacial panels with high-reflectivity ground cover to amplify yield per installed watt.
- CEA grid code harmonization:India's Central Electricity Authority mandates inverter compatibility standards that accelerate module certification convergence across state-level tenders.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based polysilicon production clusters expose downstream module assemblers to forced-labor scrutiny and carbon-border adjustment risks.
- Silver paste cost volatility:Metallization paste inputs for PERC and TOPCon cells fluctuate with precious metal markets, compressing cell-level margins.
- Interconnection queue bottlenecks:FERC standards in the United States create multi-year certification timelines that delay revenue recognition for utility-scale projects.
Strategic Opportunities
- Agrivoltaics in Brazil's agricultural belt:Dual-use installations combining grazing land with elevated bifacial arrays unlock underpenetrated rural electricity demand.
- MIIT efficiency quota convergence:China's Ministry of Industry and Information Technology benchmarks are accelerating n-type cell adoption, creating technology licensing opportunities for equipment suppliers.
- Corporate PPA direct procurement:Large energy consumers in Texas bypass traditional utility channels to contract directly with project developers for behind-the-meter supply.
Industry Challenges
- Cell metallization engineering talent scarcity:TOPCon and heterojunction process optimization requires specialized semiconductor fabrication expertise that outpaces vocational training pipelines.
- Module recycling infrastructure capex:End-of-life silicon recovery and encapsulant separation demand capital-intensive pyrolysis facilities not yet deployed at commercial scale.
- IEC 61215/61730 certification lag:Bifacial and n-type variants face extended testing protocols that delay product launch timelines relative to established p-type monofacial benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Panels Market |
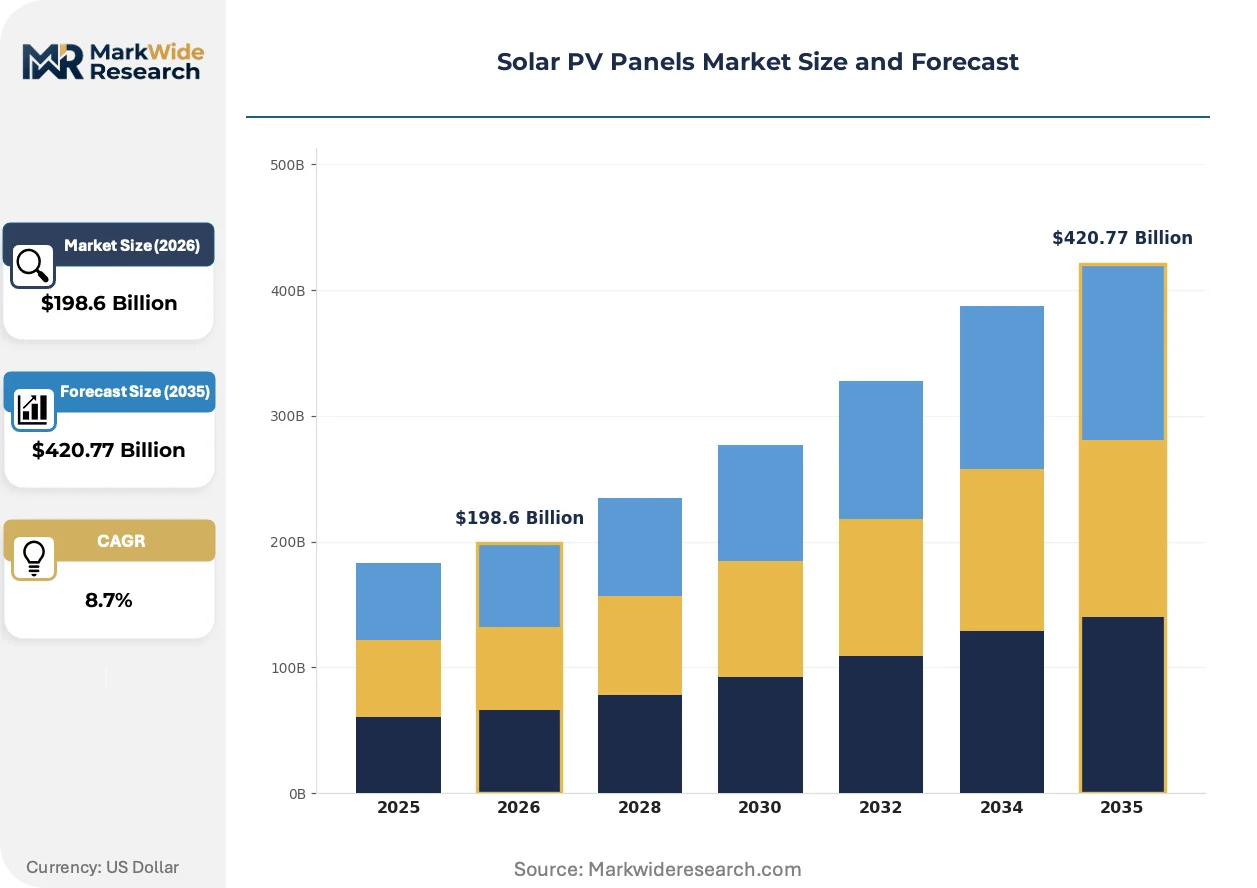
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $420.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: Photovoltaic Cells, Inverters, Charge Controllers, Mounting Systems End User: Residential, Commercial, Industrial, Utility Scale Installation Type: Grid-Tied, Off-Grid, Hybrid, Rooftop |
| Companies Covered | JinkoSolar, Trinasolar, JA Solar Technology Co., Ltd., LONGi Green Energy, Tongwei Co., Ltd., Canadian Solar, First Solar, Hanwha Qcells, Waaree Energies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Panels Market Evolving Landscape
Passivated contact architectures and tandem cell stacks are redefining efficiency frontiers while procurement specifications harden around carbon intensity metrics and domestic content verification protocols.
TOPCon cell architecture is converging with utility-scale procurement specifications as the technology's superior temperature coefficient and bifaciality gain traction. Developers in India's western desert states specify n-type modules for high-albedo installations where rear-side gain amplifies project IRR. The structural consequence compresses polysilicon-to-module margin pools as cell efficiency premiums commoditize faster than process equipment depreciates.
EU Green Deal carbon-border adjustment mechanisms are forcing module importers to document embodied emissions across polysilicon, wafer, and cell stages. The regulation's industrial consequence is a bifurcation between European-certified supply chains and export-oriented Chinese manufacturing bases. High-efficiency segments in Germany and the Netherlands absorb compliance costs through green premium contracting, while price-sensitive Mediterranean markets delay procurement.
Corporate offtake agreements now specify hourly matching rather than annual renewable energy certificates, compressing project developer risk profiles. Large technology and data center operators in Texas demand storage-coupled solar supply that shifts dispatch to evening peaks. This behavioral pivot is most visible in ERCOT-interconnected counties where nodal pricing volatility rewards dispatchable renewable configurations.
Solar PV Panels Market Segmentation
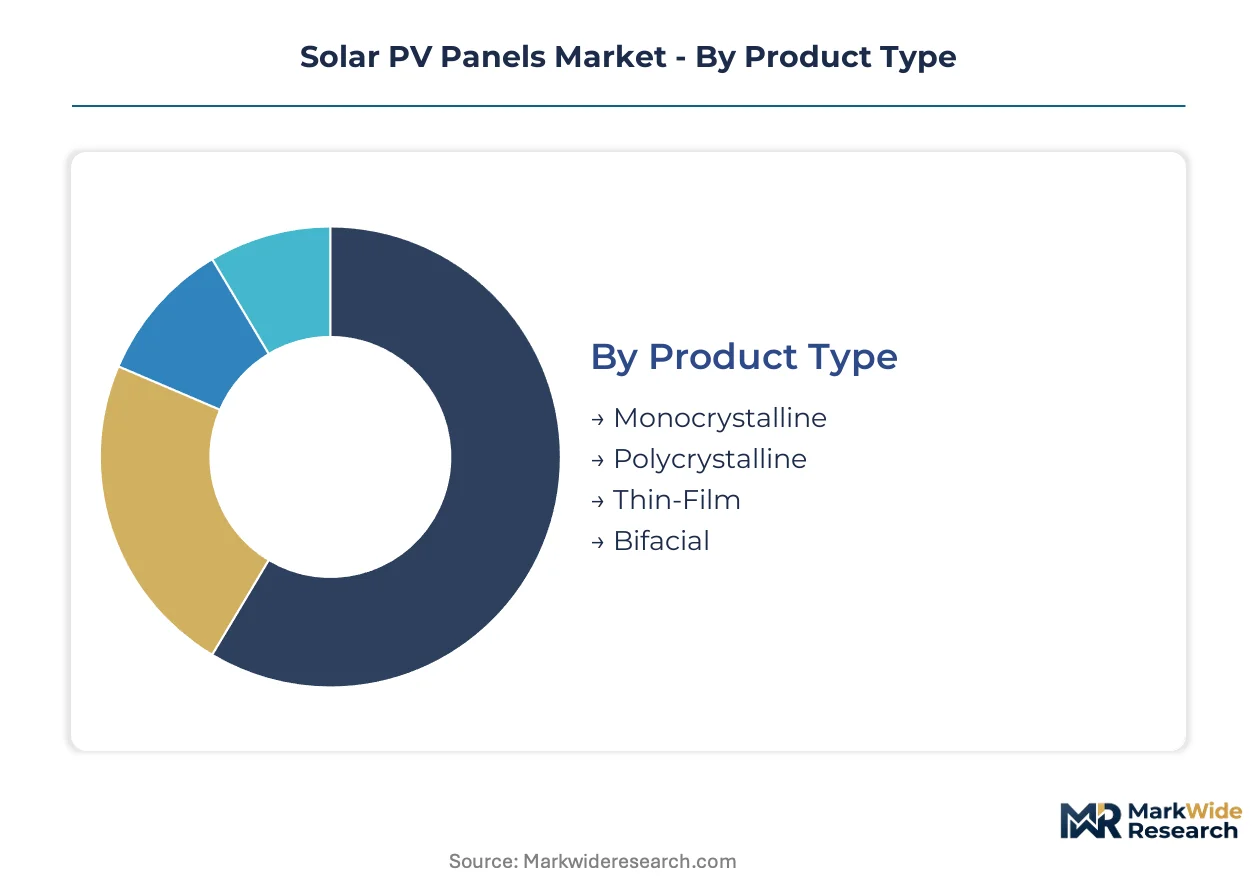
Module specification tiers determine procurement economics across divergent site conditions and regulatory environments. Technology choices cascade through balance-of-system costs, interconnection timelines, and carbon-intensity documentation requirements that now gate market access in major jurisdictions.
Product Type:
Cell crystallinity and light-harvesting architecture define efficiency thresholds, degradation curves, and manufacturing cost structures that segment procurement strategies.
- Monocrystalline:Single-crystal silicon ingots sliced into wafers yield the highest conversion efficiencies, typically exceeding 21% in commercial modules. Demand clusters in Germany and the Netherlands where rooftop area constraints and green premium contracting reward space-optimized output. EU Green Deal domestic content verification favors European-certified monocrystalline supply chains over import-dependent alternatives.
- Bifacial:Dual-glass construction captures direct and reflected irradiance, amplifying yield 10-20% over monofacial equivalents on high-albedo surfaces. Utility developers in India's western desert states deploy these with tracking systems and white gravel ground cover to maximize project IRR. Albedo-optimized installations represent the steepest expansion trajectory as procurement specifications harden around energy yield per installed watt.
- Polycrystalline:Multi-crystal silicon wafers trade efficiency for lower manufacturing energy intensity and capital cost. Price-sensitive Mediterranean markets and distributed residential segments in Brazil retain procurement interest where space constraints are minimal.
- Thin-Film:Cadmium-telluride and CIGS absorber layers exhibit favorable temperature coefficients for desert climates. Utility-scale installations in the southwestern United States specify these where heat-related efficiency losses would degrade crystalline alternatives.
Mature deployment sits with polycrystalline modules in cost-driven distributed segments. Newer deployment is concentrated in bifacial arrays for utility-scale desert installations.
Technology:
System component integration determines project bankability, grid compliance timelines, and operational flexibility across divergent dispatch requirements.
- Photovoltaic Cells:Semiconductor p-n junctions fabricated from doped silicon wafers constitute the core energy conversion layer. TOPCon and heterojunction architectures are displacing PERC in premium procurement channels as efficiency thresholds harden. India's CEA grid code mandates accelerate certification convergence for advanced cell technologies.
- Inverters:Power electronics convert DC module output to grid-synchronous AC, with string and central configurations segmenting by project scale. Texas ERCOT-interconnected projects specify storage-coupled inverters to shift dispatch toward evening peak pricing nodes.
- Charge Controllers:Battery management interfaces regulate DC coupling in off-grid and hybrid configurations. Rural electrification programs in Brazil's agricultural belt deploy these with elevated bifacial arrays for dual-use agrivoltaic installations.
- Mounting Systems:Structural hardware secures modules to rooftops, trackers, or ground-mount foundations. Single-axis trackers paired with bifacial panels dominate utility-scale procurement where terrain permits mechanical complexity.
Standardized procurement concentrates on string inverters and fixed-tilt mounting. Differentiated deployment favors integrated storage inverters and tracking systems for dispatch-optimized configurations.
End User:
Customer scale determines financing structures, offtake contract sophistication, and regulatory compliance burdens that segment channel economics.
- Utility Scale:Projects exceeding 50 MW capacity interconnect at transmission voltage and procure through competitive tenders. Developers in Texas and India's western desert states negotiate corporate PPAs with hourly matching requirements rather than annual certificate structures.
- Residential:Distributed rooftop installations under 20 kW capacity rely on net metering tariffs and simplified interconnection standards. Germany's EEG feed-in tariff legacy sustains retrofit demand despite declining subsidy levels.
- Commercial:Mid-scale rooftop and carport installations serve corporate sustainability mandates and behind-the-meter load offset. Netherlands tax incentives accelerate depreciation for commercial solar assets.
- Industrial:Large on-site arrays for manufacturing and data center loads combine with storage for peak demand management. Brazil's agricultural processing facilities deploy elevated bifacial arrays preserving grazing land underneath.
Established volume sits with utility-scale procurement through centralized tenders. Emerging volume concentrates in industrial direct procurement bypassing traditional utility channels.
Installation Type:
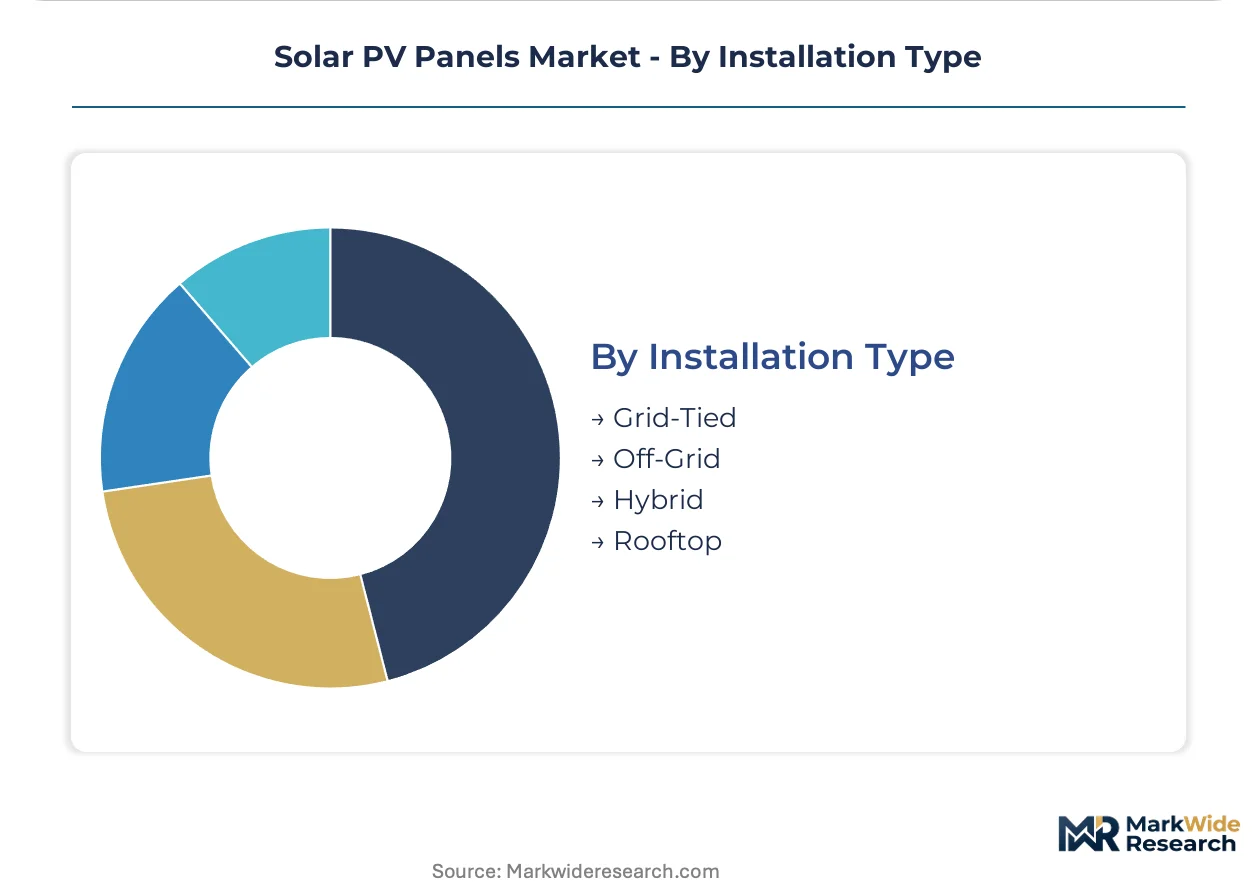
Grid interconnection architecture determines regulatory jurisdiction, storage integration requirements, and revenue stream diversification.
- Grid-Tied:Synchronous interconnection enables net metering and wholesale market participation. FERC standards in the United States create multi-year certification queues that delay revenue recognition for utility-scale projects.
- Hybrid:Battery-coupled configurations enable dispatch shifting and backup power during grid outages. Texas data center operators specify these for evening peak matching under nodal pricing volatility.
- Off-Grid:Standalone systems with storage serve remote loads without distribution infrastructure. Brazil's agricultural belt combines these with agrivoltaic arrays for underpenetrated rural electricity demand.
- Rooftop:Building-integrated and building-applied configurations optimize for available surface area and structural loading. Germany and Netherlands urban density constraints favor this deployment mode.
Conventional deployment centers on grid-tied configurations with standard interconnection. Accelerated deployment is concentrating in hybrid systems with storage coupling for dispatch-optimized revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's polysilicon corridor anchors upstream material supply for module assembly networks spanning three continents. Procurement clusters in China's manufacturing belt, India's western desert states, and Texas reshape competitive positioning through divergent regulatory and albedo-optimization requirements.
China
MIIT efficiency quotas and production capacity benchmarks accelerate n-type cell adoption across Jiangsu and Anhui manufacturing hubs. The Ministry of Industry and Information Technology sets cell efficiency thresholds that ripple through global supply availability. Xinjiang-based polysilicon clusters expose downstream assemblers to forced-labor scrutiny and carbon-border adjustment risks under EU Green Deal mechanisms.
India
CEA grid code harmonization mandates inverter compatibility standards that compress certification timelines across state-level tenders. The Central Electricity Authority's technical regulations accelerate module convergence for utility-scale developers. Rajasthan and Gujarat's western desert states deploy bifacial arrays with high-reflectivity ground cover to maximize project IRR.
United States
FERC interconnection standards create multi-year certification queues that delay revenue recognition for ERCOT-interconnected utility-scale projects. The Federal Energy Regulatory Commission's procedural requirements shape procurement risk profiles. Texas data center operators specify storage-coupled solar supply with hourly matching requirements rather than annual certificate structures.
Germany
EU Green Deal domestic content mandates redirect procurement toward certified European supply bases under tightening renewable portfolio standards. The European Commission's carbon-border adjustment mechanisms force module importers to document embodied emissions across polysilicon, wafer, and cell stages. EEG feed-in tariff legacy sustains rooftop retrofit demand in Bavaria and North Rhine-Westphalia despite declining subsidy levels.
Brazil
Agrivoltaic installations combining grazing land with elevated bifacial arrays unlock underpenetrated rural electricity demand across São Paulo and Minas Gerais agricultural belts. ANVISA-equivalent grid compliance requirements apply to distributed generation interconnection. Rural electrification programs deploy charge controllers with off-grid configurations for agricultural processing facilities.
Solar PV Panels Market Competitive Landscape
Premium-margin players sit above commodity-margin players across efficiency-tier and certification-grade dimensions. The vendor base stratifies into three tiers: integrated polysilicon-to-module manufacturers, pure-play cell and module assemblers, and thin-film technology specialists. Strategic archetypes include backward-integrated margin defenders, geographic diversifiers, and technology licensors. Dominant competitive moves encompass capacity expansion in n-type cell architectures and strategic partnerships for European supply chain certification.
Among China-based integrated manufacturers, JinkoSolar, LONGi Green Energy, and Trinasolar exemplify contrasting strategic positions. JinkoSolar occupies a position within the backward-integrated archetype spanning polysilicon and cell stages. LONGi Green Energy anchors the monocrystalline wafer specialization tier through proprietary process positioning. Trinasolar represents the geographic diversification archetype with emerging market exposure across Asia and Latin America. These three entities collectively illustrate how efficiency-premium capture, supply chain control, and market access breadth define competitive differentiation in procurement specifications hardening around carbon intensity and domestic content verification.
| Leading Market Players |
|---|
| JinkoSolar |
| Trinasolar |
| JA Solar Technology Co., Ltd. |
| LONGi Green Energy |
| Tongwei Co., Ltd. |
| Canadian Solar |
| First Solar |
| Hanwha Qcells |
| Waaree Energies |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon-border adjustment mechanisms gate qualified supply and premium-tier pricing access, forcing module importers to document embodied emissions across polysilicon, wafer, and cell stages or accept exclusion from certified procurement channels. Buyers in Germany and the Netherlands absorb compliance costs through green premium contracting while Mediterranean markets delay procurement pending price convergence.
Pricing Analysis
Yield-per-watt pricing anchors module procurement economics, with bifacial premiums tied to albedo-optimized energy output rather than manufacturing cost. Three-tier pricing structure across premium n-type, standard p-type monocrystalline, and economy polycrystalline levels segments by certification grade and domestic content verification. Cost compression in commodity-grade supply is intensifying because Xinjiang polysilicon faces forced-labor scrutiny. Utility-scale developers in India exhibit highest price sensitivity; corporate PPA offtakers in Texas show lowest sensitivity due to hourly matching requirements.
Supply Chain Analysis
Dual-sourcing requirements from European utility tenders mandate multi-supplier qualification, fragmenting procurement across certified Asian and emerging European cell assembly networks. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module stages; polysilicon production clusters in Xinjiang and Inner Mongolia. Silver paste, high-purity quartz crucibles, and ethylene-vinyl acetate encapsulant feed from precious metal and petrochemical supply chains. Single-source vulnerability in metallization paste exposes margins to commodity volatility. Distribution runs through EPC contractors and direct developer procurement with long-term offtake contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive polysilicon supply determines margin defense against carbon-border adjustment compliance costs. Players pursue upstream control over ingot and wafer stages to secure certified supply chain documentation.
For Market Incumbents: Extend backward integration into polysilicon and wafer stages to defend margin pools against EU Green Deal domestic content mandates. Accelerate n-type cell capacity in Jiangsu and Anhui manufacturing hubs to capture efficiency premiums before TOPCon commoditization. Certify European supply chain partnerships to maintain access to green premium contracting channels in Germany and the Netherlands. For New Entrants and Emerging Players: Agrivoltaic developers in Brazil's agricultural belt represent an underserved buyer archetype seeking elevated bifacial arrays with dual-use grazing compatibility. Target off-grid industrial installations in Minas Gerais processing facilities with integrated charge controller and storage configurations. Pursue technology licensing agreements with Chinese MIIT-compliant equipment suppliers to bypass capital-intensive cell fabrication entry barriers. For Investors and Strategic Acquirers: CEA grid code harmonization mandating inverter compatibility standards is the leading indicator that Indian utility-scale procurement will consolidate around certified module suppliers. Frame long-term viability around five-to-ten year technology licensing revenue streams rather than manufacturing asset ownership. Target acquisition of European supply chain certification specialists with documented polysilicon-to-module carbon intensity auditing capabilities. Watch MIIT efficiency quota announcements as the signal for n-type adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive Xinjiang-free supply secures EU Green Deal market access against carbon-border scrutiny. |
| N-Type Cell Capacity Expansion | TOPCon and heterojunction adoption in Jiangsu hubs captures efficiency premiums ahead of commoditization. |
| European Supply Chain Certification | Documented emissions auditing unlocks green premium contracting in Germany and Netherlands procurement. |
| Agrivoltaic Project Development | Elevated bifacial arrays in São Paulo agricultural belt unlock underpenetrated rural electricity demand segments. |
| Storage-Coupled Inverter Integration | Texas ERCOT-interconnected projects shift dispatch toward evening peak pricing nodes under hourly matching. |
Research Methodology
Document review covered FERC interconnection filings, EU Green Deal regulatory texts, CEA grid code amendments, and MIIT production capacity announcements, complemented by interviews with utility-scale project developers, EPC contractors, module procurement officers, and grid interconnection specialists. Secondary validation drew from IEA renewable energy databases, EIA electricity market data, and customs trade records across polysilicon and module categories. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment were cross-referenced for triangulation.
Historical capacity deployment patterns were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include cell crystallinity architecture, system component integration, end-user scale tier, and grid interconnection type. CAGRs were derived through slope analysis of technology adoption curves and regulatory mandate implementation timelines. Forecast inputs incorporated albedo-optimized yield assumptions for bifacial installations and carbon intensity documentation compliance thresholds.
Revisions become necessary when forced-labor scrutiny expands beyond Xinjiang polysilicon, silver paste price volatility exceeds historical bands, or FERC interconnection queue reforms materially accelerate certification timelines. Forecasts reflect assumptions around MIIT efficiency quota enforcement, EU Green Deal carbon-border phase-in schedules, and CEA grid code harmonization adoption rates. Deviation in any trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
Switzerland Solar Energy Market