
 Laser Cladding Equipment Market | 2026-2036
Laser Cladding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cladding Equipment Market Analysis
The gap between fiber laser and solid-state laser architectures is narrowing as power density and beam quality converge across commercial platforms. TRUMPF leverages its integrated source-to-system verticality to control specification pipelines for aerospace OEMs. IPG Photonics Corporation anchors the high-power fiber laser supply tier with proprietary diode and resonator designs. Coherent Corp. competes through differentiated beam delivery modules that extend wavelength flexibility for multi-material cladding.
Laser cladding equipment directs concentrated coherent energy to deposit metallic coatings onto substrates, typically achieving bond strengths exceeding those of thermal spray processes while limiting heat-affected zones to under two millimeters. The primary industrial purpose centers on dimensional restoration, wear resistance enhancement, and corrosion protection for high-value components in cyclic thermal or abrasive environments. Fiber laser systems lead installed capacity due to wall-plug efficiency and maintenance intervals, though disk laser configurations occupy premium positioning where beam parameter product fidelity determines microstructural outcomes. Cold laser processing segments are gaining traction in tool manufacturing applications where substrate distortion must remain negligible.
EPA emissions guidelines and EU Green Deal circular economy mandates are redirecting capital from new part procurement toward remanufacturing workflows that laser cladding enables. FDA device repair standards and FAA airworthiness directives further constrain acceptable restoration methods, effectively filtering market access to qualified equipment suppliers. Stakeholders must track how ISO 9001 and AS9100 certification requirements evolve for cladding service providers, as these quality frameworks increasingly determine OEM approval status and contract eligibility.
Market Dynamics
Remanufacturing mandates from EPA and EU Green Deal frameworks are redirecting capital flows from new component procurement toward laser cladding restoration workflows, compressing replacement cycles across aerospace and power generation sectors.
Growth Catalysts
- EU Green Deal circular economy mandates:Binding remanufacturing targets for industrial equipment are accelerating cladding adoption for turbine blade restoration in Germany and France.
- Fiber laser wall-plug efficiency:Operating cost advantages over CO₂ systems are pulling investment from thermal spray operations toward directed energy deposition in North American repair facilities.
- China's dual carbon goals:Domestic aviation MRO providers are scaling laser cladding capacity to reduce imported spare part dependency and associated embodied emissions.
Market Restraints
- Precious metal powder volatility:Nickel and cobalt feedstock price swings compress service provider margins and deter long-term contract pricing.
- Optics supply concentration:German and Japanese specialty lens manufacturers control beam delivery component supply, creating single-source vulnerability for system integrators.
- Heat-affected zone limitations:Substrate distortion constraints below two millimeters exclude laser cladding from certain thin-wall aerospace component categories.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic production incentives are opening localized equipment assembly and service hub development for South Asian remanufacturing demand.
- Cold laser processing convergence:Ultrafast pulse integration with traditional cladding heads is creating sub-millimeter precision capability for medical instrument repair.
- AS9100 certification acceleration:Streamlined aerospace quality approval pathways in the United States are reducing OEM qualification timelines for new cladding service entrants.
Industry Challenges
- Multi-axis path programming expertise:Shortages of CAM software specialists capable of complex geometry toolpath generation constrain job shop capacity expansion.
- ISO 9001 to AS9100D upgrade timelines:Eighteen-month certification cycles delay contract eligibility for tier-two suppliers targeting aerospace OEM approval.
- Legacy thermal spray workforce transition:Retraining programs for plasma spray technicians to operate laser cladding systems require sustained investment with uncertain retention outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cladding Equipment Market |
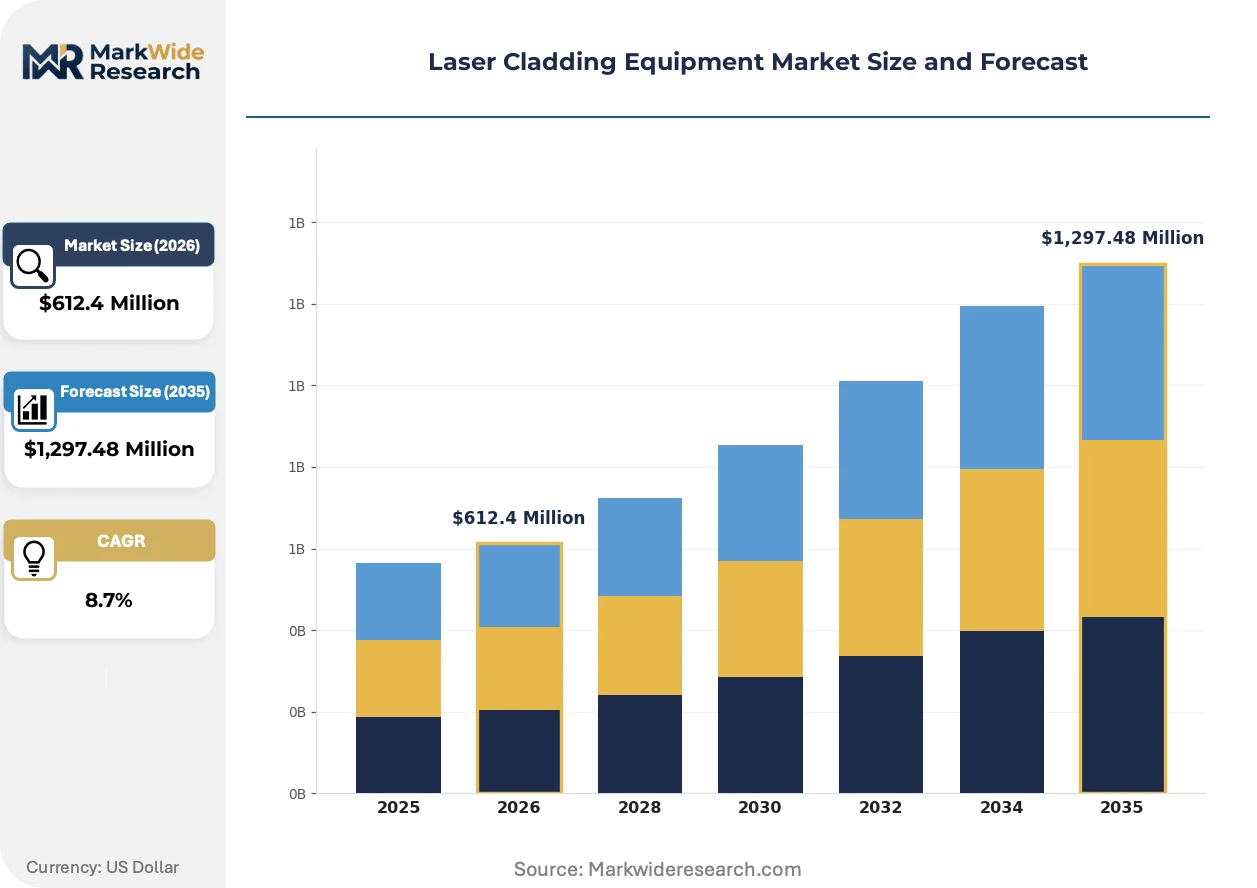
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Disk Laser, Solid-State Laser, CO2 Laser Technology: Cold Laser Processing, Hot Laser Cladding, Hybrid Laser Cladding, Laser Metal Deposition Application: Aerospace, Automotive Parts Repair, Oil & Gas Equipment, Tool Manufacturing End User: Manufacturers, Service Providers, Research Institutions, Energy Sector |
| Companies Covered | TRUMPF, OC Oerlikon Management AG, Coherent Corp., IPG Photonics Corporation, ALPHA LASER GmbH, Laserline GmbH, Jenoptik AG, Höganäs AB, Preco LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cladding Equipment Market Emerging Trajectories
Beam quality convergence between fiber and disk architectures is eroding traditional performance tiering, while regulatory remanufacturing mandates and service model unbundling are restructuring how equipment capability translates to contract value.
High-power fiber laser systems are collapsing the performance gap with solid-state disk alternatives through improved beam parameter product fidelity at multi-kilowatt outputs. Aerospace MRO providers in Germany and the United States are adopting these platforms for turbine blade restoration where microstructural consistency determines airworthiness approval. The technology compression is eliminating premium positioning for disk laser configurations outside extreme precision applications.
EU F-Gas Regulation phase-down schedules are restricting traditional thermal spray process gases, redirecting investment toward laser cladding as a fluorinated-gas-free alternative. Industrial operators in France and Italy face compliance deadlines that accelerate equipment replacement cycles. The policy pressure is most acute in heat exchanger remanufacturing, where coating thickness requirements previously favored plasma spray methods.
Equipment-as-service contracting is displacing capital purchase models among mid-size job shops with constrained balance sheets. German and Japanese system vendors are piloting throughput-based pricing arrangements where cladding head availability, not asset ownership, defines the commercial relationship. The shift is concentrated in automotive tool and die restoration, where seasonal demand volatility makes fixed asset commitments uneconomical.
Laser Cladding Equipment Market Segmentation
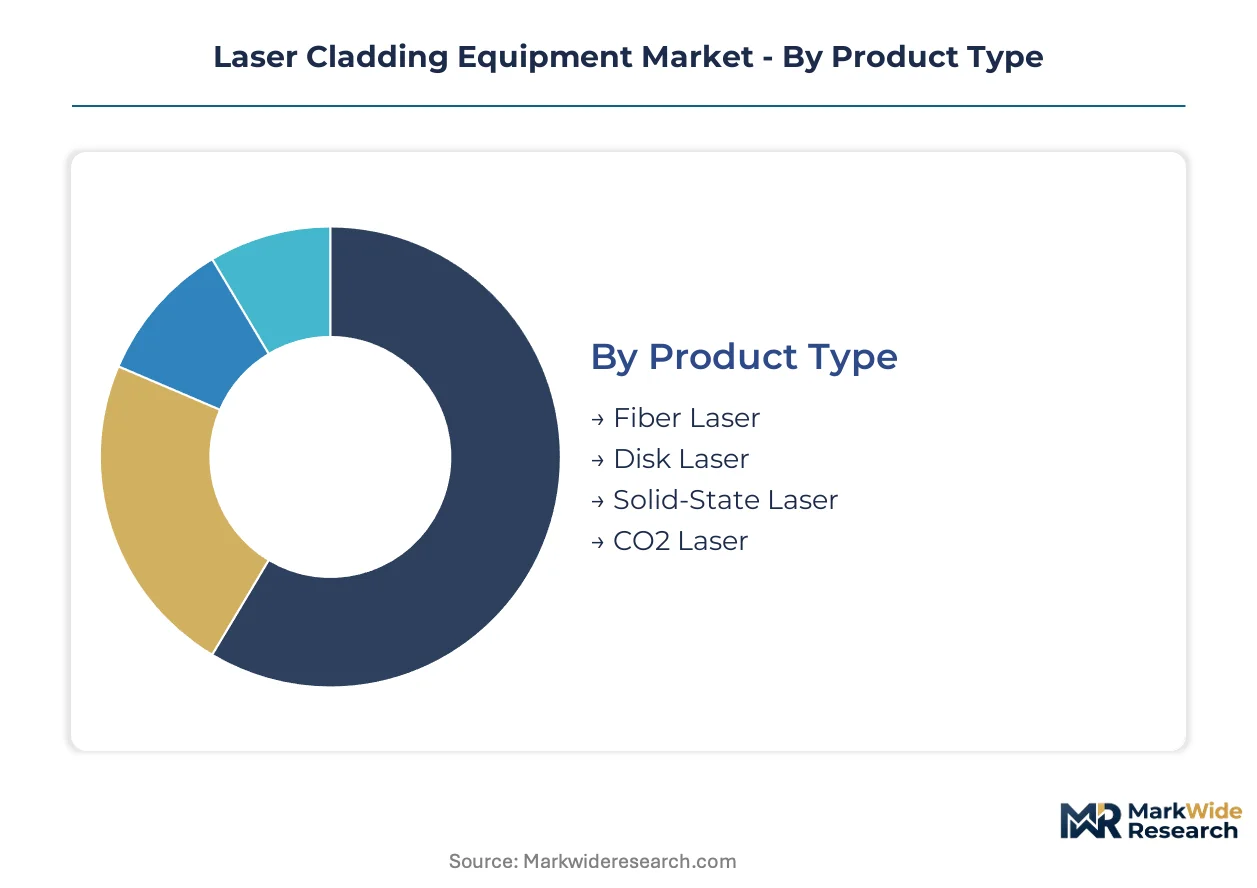
Segmentation in laser cladding equipment reveals how technology choices cascade through operational economics and regulatory compliance. Equipment buyers match laser architecture to substrate material constraints, while application-specific certification requirements filter vendor eligibility.
Product Type:
Fiber laser systems turn over fastest in installed base refresh cycles, while CO2 platforms linger longest in legacy repair facilities. Disk laser replacement intervals sit in the middle, driven by aerospace precision demands rather than efficiency obsolescence.
- Fiber Laser:Wall-plug efficiency above 30% and maintenance intervals exceeding 30,000 hours dominate commercial procurement. North American MRO facilities favor these platforms for turbine blade restoration where throughput economics override capital cost premiums.
- Disk Laser:Beam parameter product fidelity below 2 mm·mrad enables microstructural control in thin-wall aerospace components. German precision engineering clusters anchor demand as AS9100D certification requirements tighten beam quality specifications.
- Solid-State Laser:Nd:YAG architectures persist in research institutions and legacy defense maintenance depots with established spare part inventories.
- CO2 Laser:Wavelength compatibility with certain ceramic coatings sustains niche demand in tool manufacturing applications where capital replacement cycles extend beyond fifteen years.
Fiber laser systems anchor the volume base while disk laser configurations gain share at the steepest rate among new aerospace-qualified installations.
Technology:
Cold laser processing commands the highest equipment margins due to ultrafast pulse hardware requirements, while hot laser cladding spreads across price-competitive job shop tiers. Hybrid approaches concentrate where thermal distortion budgets vary across component geometries.
- Cold Laser Processing:Femtosecond and picosecond pulse integration limits heat-affected zones below 0.5 millimeters. Medical instrument manufacturers in Switzerland and Japan adopt these systems for surgical tool edge restoration where substrate metallurgy must remain unaltered.
- Hot Laser Cladding:Continuous-wave deposition at 2-10 kilowatts dominates wear-resistant coating applications. Oil and gas valve remanufacturing in the United States and Norway drives volume as EPA and EU methane emissions rules extend component life requirements.
- Hybrid Laser Cladding:Plasma-arc preheating combined with laser finishing addresses thick-section restoration where single-mode beams alone prove insufficient.
- Laser Metal Deposition:Wire-fed systems reduce powder handling costs in high-volume automotive die repair operations.
Hot laser cladding carries the largest installed base though cold laser processing is climbing the fastest among precision medical and electronics tooling segments.
Application:
Aerospace applications stretch replacement cycles through airworthiness certification delays, while automotive parts repair turns over equipment faster as model-year tooling demands shift. Oil and gas equipment restoration sits between these extremes, tied to commodity cycle timing.
- Aerospace:FAA airworthiness directives and EASA certification pathways constrain acceptable repair methods to qualified processes. Turbine blade restoration in the United States, Germany, and France absorbs the highest-specification equipment as OEM approval status determines contract eligibility.
- Automotive Parts Repair:Stamping die and injection mold restoration demands rapid turnaround to maintain production schedules. Tool and die shops in Japan and South Korea prioritize equipment with sub-24-hour job changeover capability.
- Oil & Gas Equipment:Subsea valve and drilling component remanufacturing faces NORSOK and API specification compliance.
- Tool Manufacturing:Cutting tool edge reinforcement and forming die surface engineering concentrate in China's Yangtze River Delta manufacturing corridor.
Aerospace anchors the premium equipment base while automotive parts repair is expanding most quickly among mid-tier job shop capital budgets.
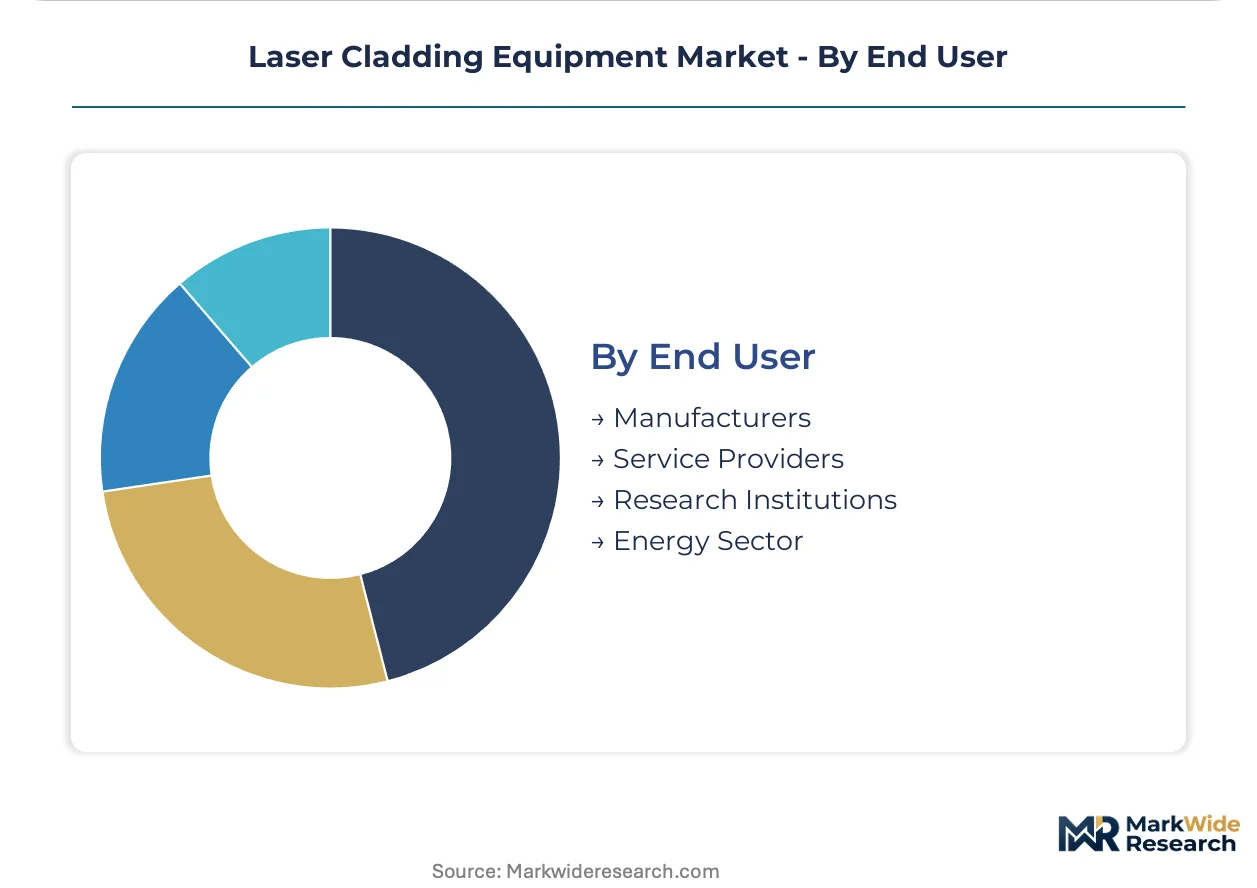
End User:
Manufacturers internalize equipment for captive remanufacturing with the longest depreciation schedules, while service providers refresh platforms faster to maintain competitive turnaround times. Research institutions cycle slowest, constrained by grant funding timelines.
- Manufacturers:Aerospace OEMs and power generation equipment builders operate captive cladding cells for warranty repair and life-extension programs. Rolls-Royce and Siemens Energy maintain proprietary process qualifications that lock in specific equipment configurations.
- Service Providers:Independent MRO shops compete on AS9100 and ISO 9001 certification breadth. German and United States repair networks are consolidating through equipment-as-service contracting models that shift capital risk to system vendors.
- Research Institutions:University-affiliated materials science laboratories in China and the United States develop novel alloy deposition parameters.
- Energy Sector:Nuclear and renewable power operators deploy cladding for turbine component life extension under NRC and national nuclear regulator oversight.
Service providers dominate annual unit volume while manufacturers are gaining share fastest among new high-power fiber laser installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in precision cladding systems while the United States and China absorb the majority of high-power fiber laser imports. Equipment flows concentrate through specialized distributors serving aerospace MRO networks and captive remanufacturing operations.
Germany
Bavarian precision engineering clusters drive disk laser demand for turbine blade restoration. The EU Green Deal circular economy mandates accelerate remanufacturing capital deployment across Baden-Württemberg automotive suppliers. Fraunhofer institutes in Aachen and Dresden anchor applied research partnerships with system vendors.
United States
FAA airworthiness directives constrain repair method qualification to AS9100D-certified processes. EPA emissions guidelines redirect power generation operators from component replacement toward cladding restoration. Houston and Pittsburgh host dense concentrations of oil and gas valve remanufacturing capacity.
China
Domestic aviation MRO providers scale fiber laser installations to reduce imported spare part dependency. Dual carbon goals under MEE frameworks extend component life requirements across Yangtze River Delta manufacturing corridors. Shenyang and Xi'an concentrate military-aerospace maintenance depot modernization.
Japan
METI industrial technology roadmaps prioritize cold laser processing for medical instrument edge restoration. JIS certification requirements filter equipment eligibility for precision tool manufacturing. Nagoya and Osaka anchor automotive die repair networks with sub-24-hour turnaround specifications.
India
PLI scheme incentives for capital goods open localized equipment assembly opportunities. DGFT import substitution policies redirect domestic aviation MRO investment toward captive cladding capability. Bengaluru and Hyderabad concentrate aerospace tier-one supplier development programs.
Laser Cladding Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around integrated source-to-system providers and specialized beam delivery component manufacturers. Three archetypes dominate: vertically integrated laser source vendors controlling specification pipelines, precision optics specialists capturing beam delivery margins, and regional system integrators serving price-sensitive job shop tiers. Competitive moves center on certification acceleration for aerospace OEM approval and equipment-as-service contracting models that shift capital risk downstream.
Within the integrated-source tier, TRUMPF and IPG Photonics Corporation exemplify vertical control over resonator-to-system value chains. Coherent Corp. occupies a differentiated position through wavelength flexibility modules. German GmbH-structured vendors including ALPHA LASER GmbH and Laserline GmbH anchor European precision engineering demand alongside Swiss-based OC Oerlikon Management AG.
| Leading Market Players |
|---|
| TRUMPF |
| OC Oerlikon Management AG |
| Coherent Corp. |
| IPG Photonics Corporation |
| ALPHA LASER GmbH |
| Laserline GmbH |
| Jenoptik AG |
| Höganäs AB |
| Preco LLC |
| Others |
Supply Flow & Price Mechanics
Bavarian precision engineering clusters anchor high-specification disk laser production, concentrating beam parameter product fidelity in German manufacturing corridors where OEM qualification requirements create pricing power for certified system vendors. This geographic concentration of precision capability cascades through downstream markets, compressing margins for uncertified competitors while sustaining premium positioning for AS9100D-qualified equipment suppliers.
Pricing Analysis
Next-generation fiber laser platforms command 15-25% premiums over prior-generation CO2 systems, while emerging cold laser processing configurations occupy the highest tier due to ultrafast pulse hardware requirements. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified disk laser systems from commercial fiber laser job shop equipment and legacy CO2 platforms. Cost compression in mid-tier fiber laser configurations is intensifying because Chinese domestic vendors are scaling production capacity for Yangtze River Delta manufacturing demand. Automotive die repair shops exhibit the greatest price sensitivity due to seasonal demand volatility, while aerospace OEM captive operations demonstrate the least sensitivity given airworthiness certification lock-in effects.
Supply Chain Analysis
Export control regimes under EU dual-use technology regulations and US Commerce Department restrictions limit high-power fiber laser resonator flows to Chinese military-aerospace maintenance depots, constraining supply elasticity for precision cladding components. German, Japanese, and United States suppliers concentrate beam delivery optics and specialty lens manufacturing, drawing from rare-earth mineral feedstocks and precision ceramic substrates. Single-source vulnerability concentrates in germanium and yttrium supply channels for optical component fabrication. Distribution runs through specialized industrial equipment distributors serving aerospace MRO networks and captive remanufacturing operations rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified laser cladding technicians and CAM software specialists capable of multi-axis path programming represent the critical bottleneck constraining service provider capacity expansion across aerospace and power generation repair networks.
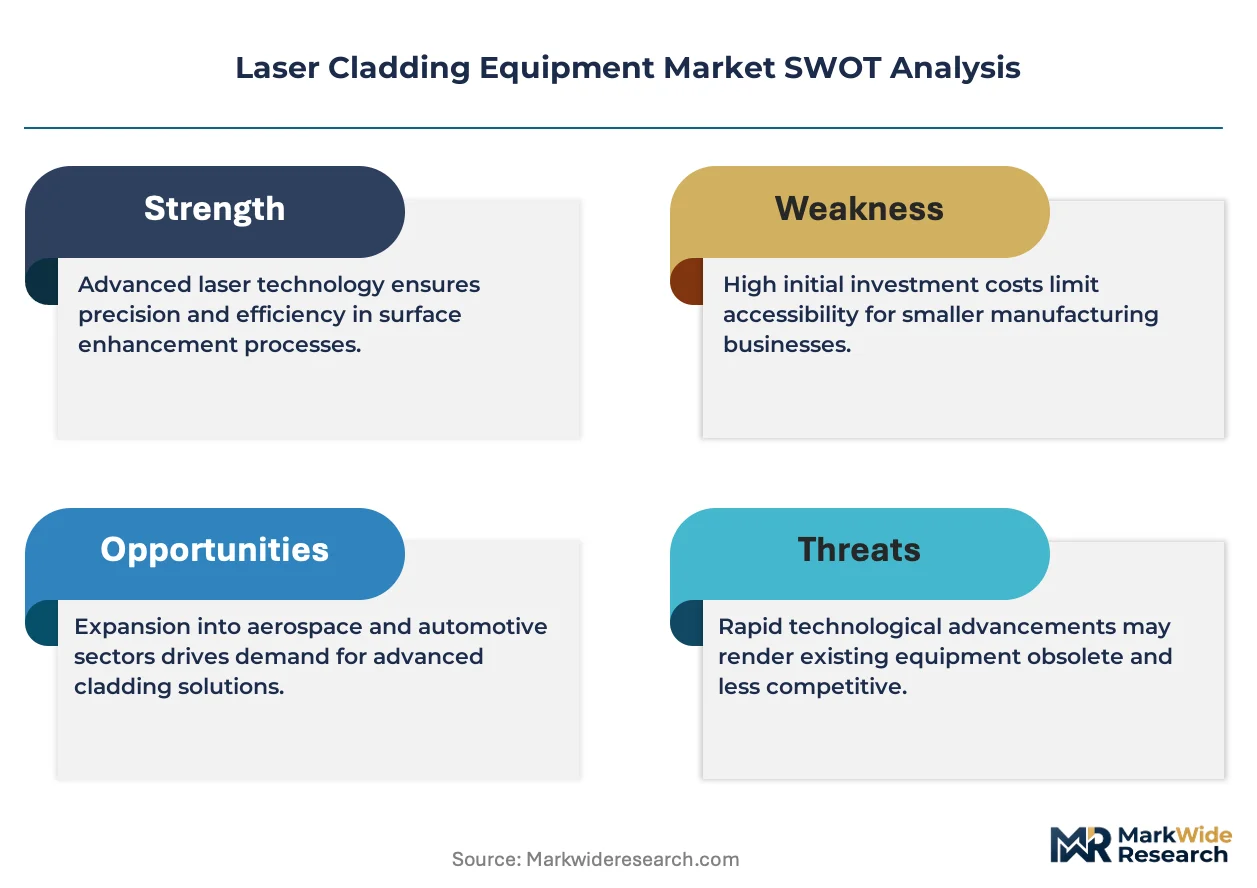
For Market Incumbents: Insulate proprietary process qualifications through accelerated AS9100D certification pipelines for emerging fiber laser platforms, while capturing backward integration into specialty powder metallurgy supply to defend against nickel and cobalt feedstock price volatility. Lock in equipment-as-service contracting relationships with mid-tier job shops to preempt Chinese vendor price competition in commercial repair segments. For New Entrants and Emerging Players: India's PLI scheme-subsidized capital goods assembly represents the most penetrable entry point for localized equipment production targeting South Asian aviation MRO demand. Medical instrument cold laser processing in Switzerland and Japan offers white-space positioning where substrate distortion constraints filter incumbent competition. Pursue partnership-based go-to-market structures with Fraunhofer-style applied research institutes to accelerate process parameter validation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision optics specialists with captive beam delivery component manufacturing and established aerospace OEM approval status. Long-term viability hinges on certification breadth across FAA, EASA, and emerging Chinese aviation regulator pathways. Watch for EU F-Gas Regulation compliance deadline acceleration as inflection indicator for thermal spray displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Acceleration | Reduces OEM qualification timelines from eighteen months to twelve months for new service entrants targeting Rolls-Royce and Siemens Energy contracts. |
| Equipment-as-Service Contracting | Shifts capital risk from balance-sheet-constrained job shops to system vendors through throughput-based pricing arrangements. |
| Backward Integration into Powder Supply | Captures margin compression protection against nickel and cobalt volatility while securing feedstock quality for aerospace microstructural specifications. |
| Cold Laser Processing Capability Addition | Opens medical instrument and electronics tooling segments where femtosecond pulse precision commands premium positioning. |
| Regional Assembly Hub Development | Localizes production in India under PLI scheme incentives to serve South Asian remanufacturing demand with reduced import duty exposure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment vendor technical specifications. Interviews with maintenance directors at aerospace MRO facilities, plant engineers at power generation operators, OEM procurement teams, and aftermarket service heads provided operational demand validation. Secondary sources include EPA emissions guideline documents, EASA certification pathway records, EU Green Deal circular economy mandate texts, and SEC filings from publicly traded laser source manufacturers. Bottom-up equipment shipment estimates triangulate against top-down remanufacturing market size calculations.
Forecast inputs incorporate laser architecture substitution curves, regulatory compliance deadline schedules, and aerospace OEM approval status expansion rates. Segmentation dimensions span product type, technology generation, application vertical, and end-user category across the projection horizon. CAGRs derive from fitted adoption curves calibrated to historical fiber laser displacement of CO2 platforms in comparable industrial equipment markets. Industry-specific inputs include EPA and EU methane emissions rule stringency trajectories, aviation MRO capacity expansion plans, and precious metal powder price volatility assumptions.
Practitioners should monitor EU F-Gas Regulation phase-down acceleration, Chinese dual carbon goal enforcement intensity, and nickel-cobalt alloy feedstock price spikes for early signals of demand or margin inflection. Forecasts reflect documented assumptions regarding certification timeline stability and aerospace OEM captive versus outsourced repair mix. Material shifts in export control regime stringency or AS9100D audit backlog duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Tower Crane Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Global Excavators Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Europe Forklift Rental Market