
 Global Operating Equipment Room Market | 2026-2036
Global Operating Equipment Room Market Size, Share, and Industry Trends Forecast 2026-2036
Global Operating Equipment Room Market Intelligence
Digital integration of operating room workflows is rewriting equipment architecture across surgical facilities. Stryker leverages its endoscopy and navigation platforms to anchor integrated digital suites. Siemens Healthineers sustains imaging-to-informatics connectivity through its advanced visualization systems. Getinge competes on infection control automation that links sterile processing to operating theater logistics.
An operating equipment room encompasses the engineered ensemble of surgical tables, illumination systems, anesthesia delivery platforms, patient monitoring devices, and electrosurgical instruments that enable sterile procedural environments. LED illumination and digital display interfaces now dominate new installations, replacing halogen and analog control panels while reducing thermal load and improving color rendering for tissue differentiation. Hospital operating theaters command the largest installed base, though ambulatory surgical centers represent the fastest-growing end-user category as outpatient procedure volumes shift away from inpatient settings. Orthopedic interventions and neurosurgery applications carry premium equipment specifications that concentrate margin pools in specialized configurations.
FDA clearance pathways and EU MDR conformity assessments shape product development timelines and market access for manufacturers distributing in the United States and European Union. The EPA regulates electromagnetic emissions and energy efficiency standards for powered surgical equipment sold domestically. Stakeholders must monitor how Japan's PMDA and South Korea's MFDS align their digital health device frameworks with FDA and EU precedents to anticipate regulatory convergence or divergence in Asia-Pacific approval strategies.
Market Dynamics
Digital workflow integration is compressing capital expenditure cycles across surgical facilities, forcing equipment vendors to bundle imaging, navigation, and data systems rather than sell discrete devices. This architectural shift favors suppliers with cross-platform software capabilities over pure hardware manufacturers.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume migration from hospital campuses to standalone ASCs in the United States and Germany is generating demand for compact, modular operating suites with integrated anesthesia and monitoring capabilities.
- EU MDR compliance deadlines:The Medical Device Regulation's stricter conformity assessment pathways are accelerating replacement cycles for legacy equipment that cannot meet enhanced clinical evidence requirements.
- LED surgical illumination:Thermal load reduction and superior color rendering index performance are driving retrofit demand across aging hospital infrastructure in Japan and South Korea.
Market Restraints
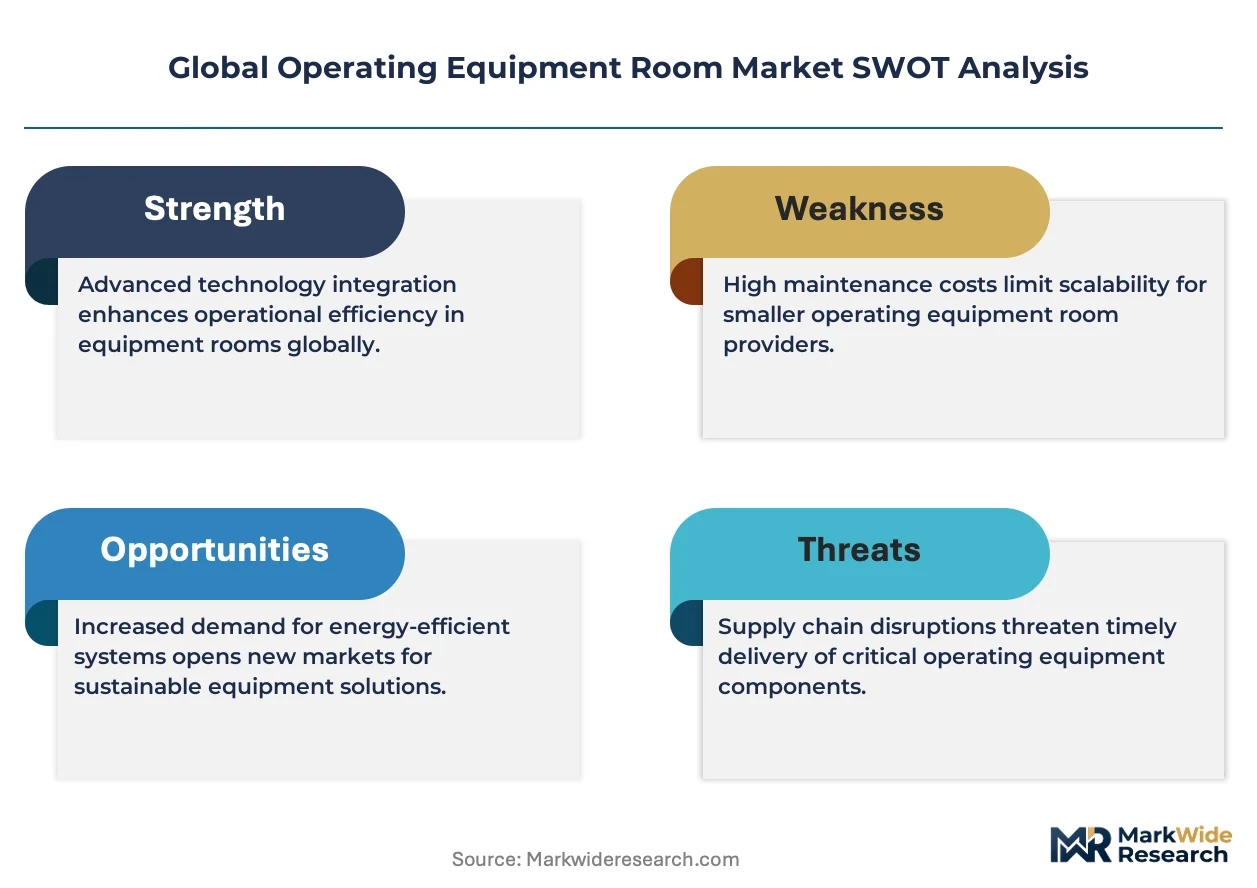
- Supply concentration in precision motors:German and Japanese suppliers dominate high-torque surgical table actuators, creating vulnerability for manufacturers without dual-source agreements.
- EU MDR certification timelines:Extended notified body capacity constraints are delaying product launches by 18-24 months for mid-tier manufacturers lacking legacy device grandfathering.
- Capital intensity of integrated suites:Single-procurement contracts exceeding $3-5 million per operating theater are restricting addressable market to health systems with balance sheet capacity.
Strategic Opportunities
- India's hospital modernization:Government-funded medical infrastructure programs under the Ayushman Bharat scheme are creating procurement windows for mid-range surgical tables and anesthesia workstations in tier-2 and tier-3 cities.
- Hybrid operating room convergence:Integration of intraoperative imaging with open surgical capability is opening specification opportunities for vendors with computed tomography or magnetic resonance imaging partnerships.
- Remote technical service channels:Augmented reality-enabled maintenance support is reducing service contract costs and expanding vendor reach into geographically dispersed ASC networks.
Industry Challenges
- Bioinformatics integration complexity:Surgical staff require training on data visualization platforms that aggregate patient monitoring, imaging, and electronic health record feeds, extending implementation timelines.
- Electromagnetic compatibility certification:Simultaneous FDA 510(k) clearance and EU MDR conformity for wireless-enabled devices demands redundant testing protocols that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Operating Equipment Room Market |
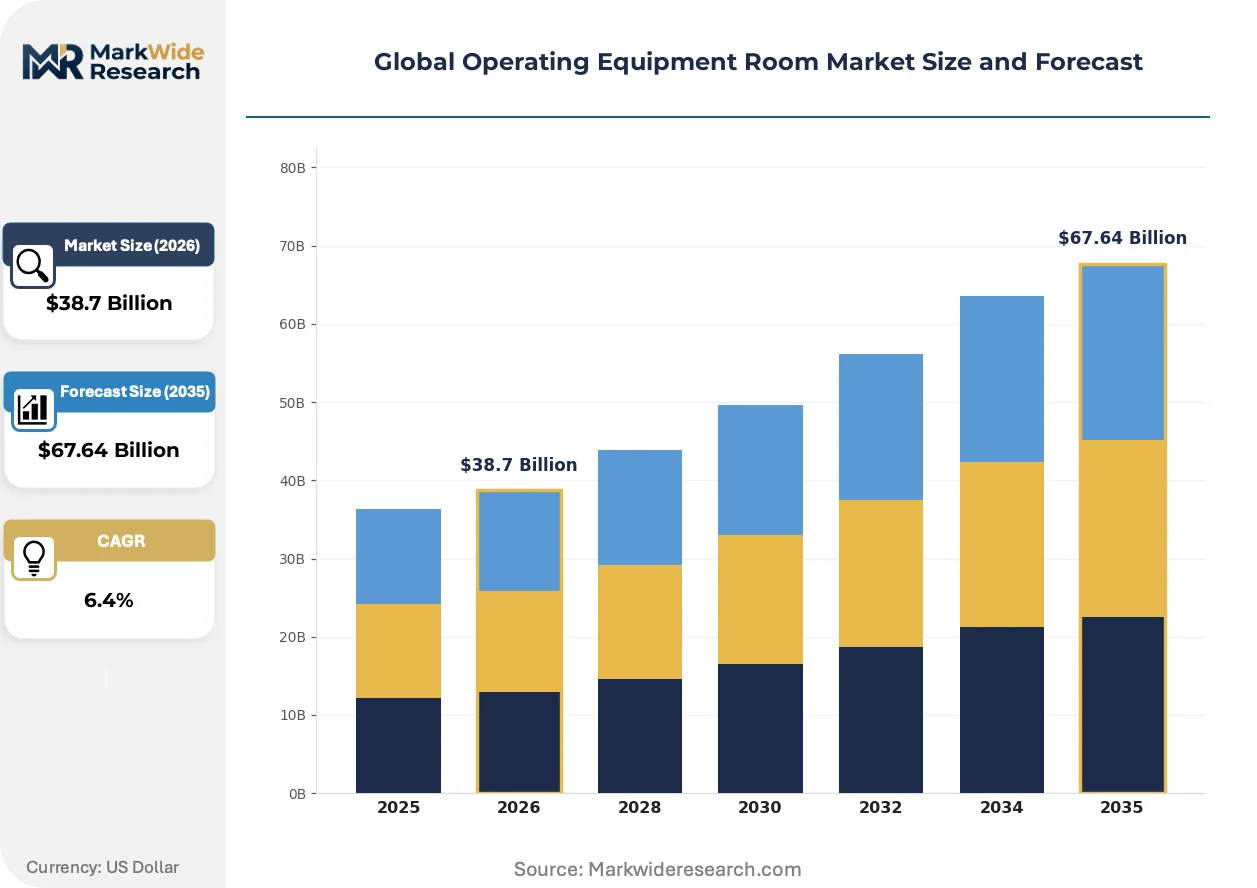
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operating Tables, Surgical Lights, Anesthesia Machines, Surgical Microscopes, Electrosurgical Units, Patient Monitors Technology: LED Illumination, Fiber Optic Lighting, Hydraulic Systems, Pneumatic Controls, Digital Display Interfaces, Wireless Connectivity Application: General Surgery, Cardiothoracic Procedures, Neurosurgery, Orthopedic Interventions, Obstetrics & Gynecology, Urology End User: Hospital Operating Theaters, Ambulatory Surgical Centers, Specialty Clinics, Academic Medical Centers, Research Institutes, Military Medical Units |
| Companies Covered | Stryker, Medtronic, Getinge, Zimmer Biomet, Koninklijke Philips, Siemens Healthineers, STERIS, KARL STORZ, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Operating Equipment Room Market Strategic Shifts & Innovations
Operating room architecture is undergoing platformization, with hardware vendors repositioning as workflow software providers. This transformation is altering competitive moats, procurement criteria, and service revenue models simultaneously.
Ultra-high-definition 4K and 8K surgical displays with near-zero latency signal processing are rendering obsolete standard-definition visualization towers in academic medical centers. Hospital procurement committees in the United States and Germany now mandate 4K minimum specifications for new installations. The technology is compressing replacement cycles from ten-year to five-year intervals.
The EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to embed real-time device performance telemetry. This regulatory architecture is raising compliance costs but creating differentiated service offerings for vendors with cloud infrastructure. German and French hospitals are prioritizing suppliers with demonstrated MDR technical documentation depth.
Subscription-based equipment access models are displacing outright purchase contracts among capital-constrained ASC chains. Third-party financing vehicles and equipment-as-a-service arrangements now dominate transactions for anesthesia delivery systems in the United States. This shift is most visible in Texas and Florida, where ASC roll-ups are consolidating procurement leverage.
Global Operating Equipment Room Market Segmentation
Operating equipment room procurement patterns diverge sharply across clinical settings and technical specifications. Capital allocation priorities in hospital systems favor integrated platforms over discrete devices, while ambulatory settings demand modular configurations. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
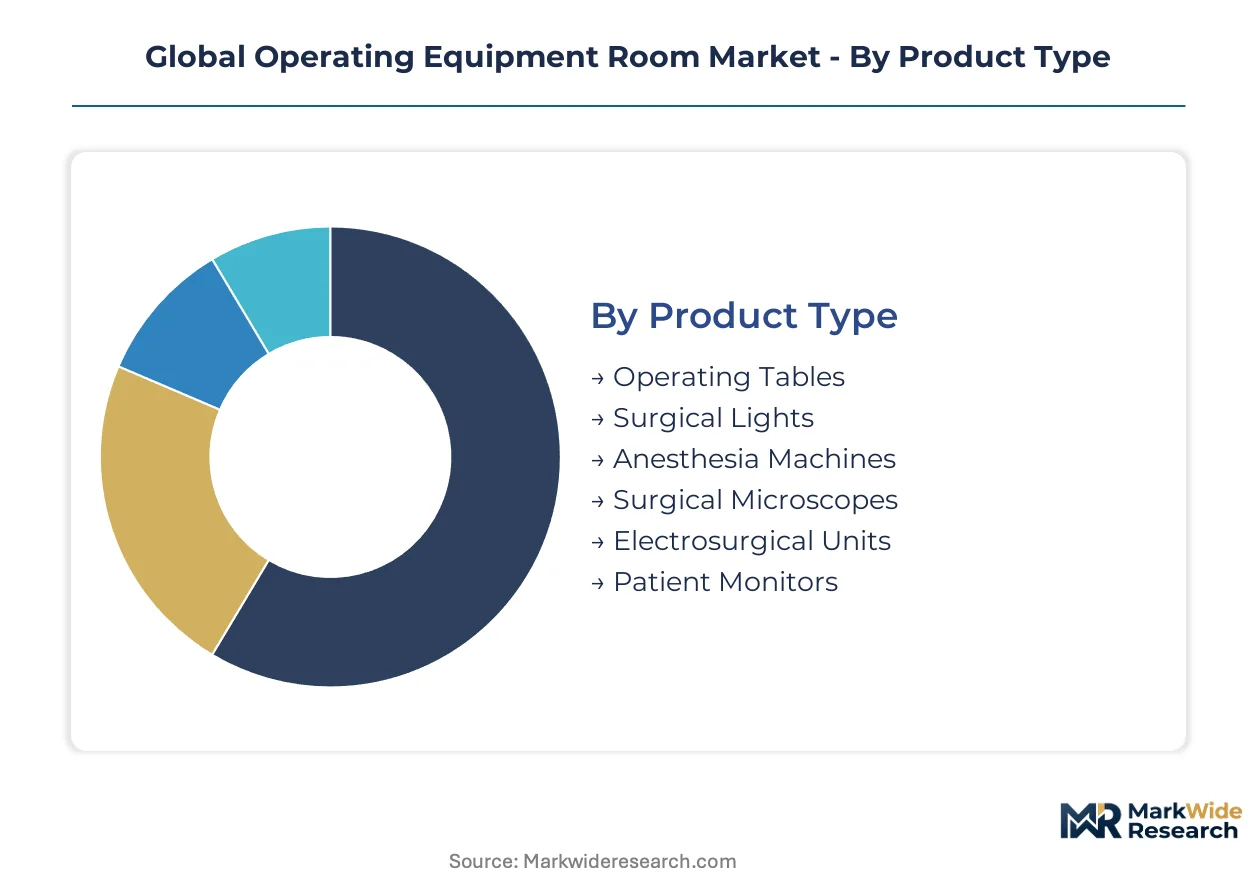
Equipment composition within surgical suites spans six core categories differentiated by capital intensity and replacement frequency.
- Operating Tables:Motorized surgical tables with carbon fiber tabletops enable intraoperative imaging compatibility without patient repositioning. Demand concentrates in Germany and the United States where academic medical centers prioritize hybrid OR configurations.
- Surgical Lights:LED-based ceiling-mounted illumination systems with adjustable color temperature now dominate new installations, replacing halogen fixtures across Japanese hospital infrastructure due to thermal load reduction requirements.
- Anesthesia Machines:Integrated workstations with electronic vaporizers and automated record-keeping.
- Surgical Microscopes:Optical systems with fluorescence imaging capability for neurovascular procedures.
- Electrosurgical Units:Radiofrequency generators with vessel-sealing technology for laparoscopic applications.
- Patient Monitors:Multi-parameter displays aggregating hemodynamic and respiratory data streams.
Operating tables command the established base. The steepest expansion runs through surgical lights as LED retrofit cycles accelerate.
Technology:
Six enabling technologies determine equipment performance tiers and regulatory classification pathways.
- LED Illumination:Solid-state lighting arrays with 90+ color rendering index and 50,000-hour operational lifespan. Hospital procurement committees in Germany and the United States now mandate LED minimums for new theater constructions.
- Digital Display Interfaces:Touchscreen control panels replacing analog switches enable centralized equipment management. Adoption concentrates in academic medical centers modernizing aging infrastructure.
- Fiber Optic Lighting:Cold light transmission systems for minimally invasive instrument illumination.
- Hydraulic Systems:Fluid-powered actuation for surgical table positioning in cost-sensitive installations.
- Pneumatic Controls:Compressed air mechanisms for brake and tilt functions.
- Wireless Connectivity:IEEE 802.11-based data transmission for device interoperability and remote monitoring.
LED illumination anchors the installed base. Wireless connectivity is climbing the fastest as FDA and EU MDR cybersecurity requirements reshape device architecture.
Application:
Six procedural categories drive divergent equipment specifications based on precision demands and imaging integration requirements.
- Orthopedic Interventions:Procedures requiring traction-capable tables and power tools with integrated irrigation systems. Demand concentrates in the United States where aging demographics expand joint replacement volumes.
- Neurosurgery:Cranial and spinal procedures mandating surgical microscopes with fluorescence angiography and stereotactic navigation interfaces.
- General Surgery:Abdominal procedures utilizing standard laparoscopic towers and electrosurgical platforms.
- Cardiothoracic Procedures:Open-heart and thoracoscopic interventions requiring perfusion support integration.
- Obstetrics & Gynecology:Delivery suites and gynecologic operating rooms with lithotomy positioning capability.
- Urology:Endourological procedures employing laser lithotripsy and flexible cystoscopy systems.
General surgery holds the largest procedure volume base. Orthopedic interventions are gaining share fastest as outpatient migration accelerates.
End User:
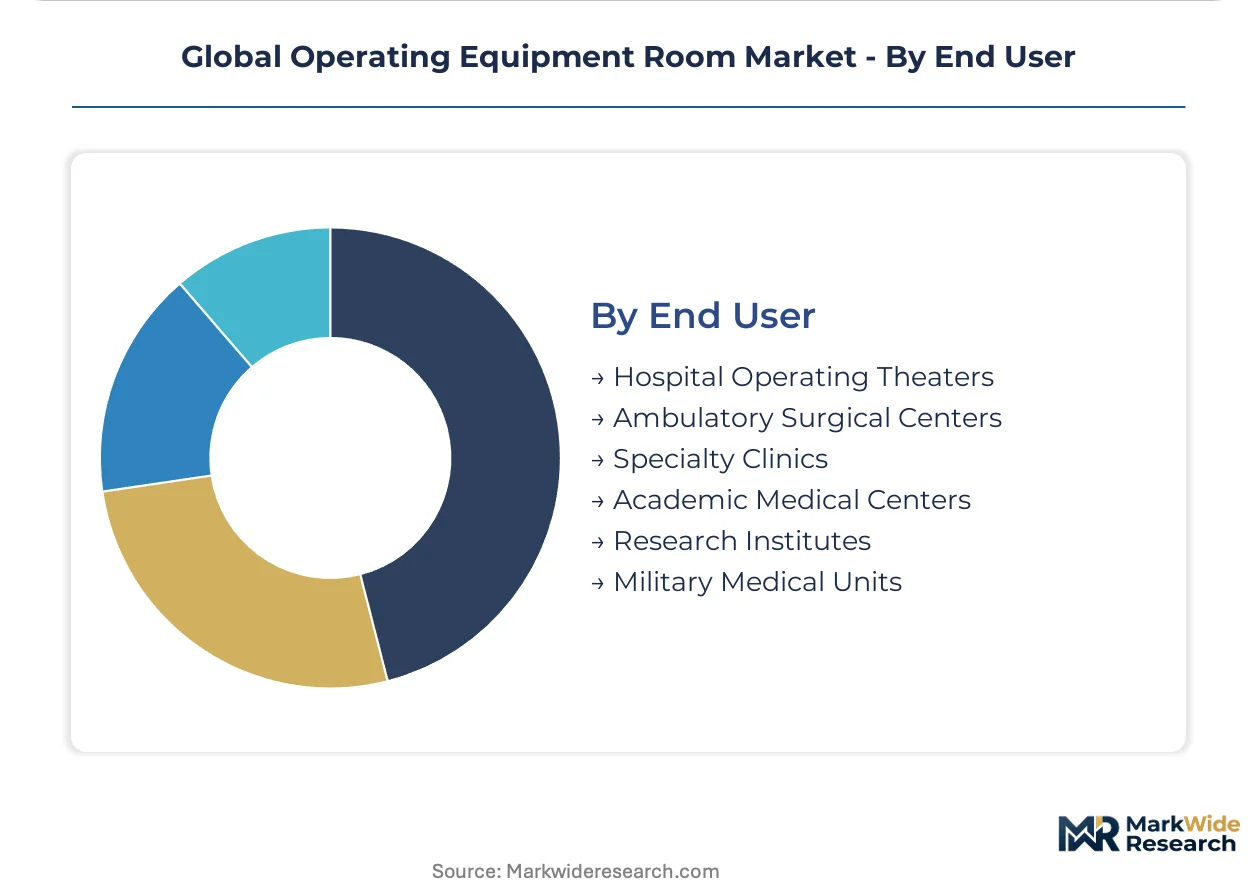
Six facility types exhibit distinct procurement patterns shaped by capital availability and procedure complexity.
- Hospital Operating Theaters:Inpatient surgical suites with highest capital budgets and longest equipment depreciation schedules. Procurement in Germany focuses on integrated digital suites with vendor consolidation.
- Ambulatory Surgical Centers:Standalone outpatient facilities demanding compact, modular configurations with rapid turnover capability. Expansion in Texas and Florida is reshaping United States equipment distribution.
- Specialty Clinics:Single-discipline facilities with procedure-specific equipment configurations.
- Academic Medical Centers:Teaching hospitals prioritating research-compatible platforms and training integration.
- Research Institutes:Preclinical and clinical trial facilities with customized experimental setups.
- Military Medical Units:Deployable surgical systems with ruggedized specifications and field sterilization capability.
Hospital operating theaters retain the dominant installed base. Ambulatory surgical centers are expanding most quickly as procedure volume shifts away from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers of surgical tables and integrated operating suites export heavily into United States academic medical centers, while Japanese LED illumination suppliers serve retrofit demand across South Korean hospital networks.
United States
Ambulatory surgical center roll-ups in Texas and Florida are consolidating procurement leverage for modular anesthesia workstations. FDA 510(k) clearance pathways shape product development timelines for wireless-enabled surgical devices. The Greater Boston cluster anchors hybrid operating room installations combining intraoperative imaging with open surgical capability.
Germany
Hospital operating theaters in Bavaria and North Rhine-Westphalia are expanding procurement of integrated digital suites with vendor consolidation strategies. EU MDR conformity assessment deadlines are accelerating replacement cycles for legacy electrosurgical equipment. The Tübingen-Stuttgart corridor concentrates surgical microscope manufacturing for neurovascular applications.
Japan
LED surgical illumination retrofits are displacing halogen fixtures across aging hospital infrastructure in Tokyo and Osaka due to thermal load reduction mandates. PMDA alignment with FDA digital health device frameworks is streamlining approval pathways for connected patient monitors. The Nagoya medical device cluster specializes in carbon fiber surgical tabletops for intraoperative imaging compatibility.
India
Government-funded medical infrastructure programs under Ayushman Bharat are creating procurement windows for mid-range surgical tables in tier-2 and tier-3 cities. CDSCO medical device registration requirements are tightening quality standards for imported anesthesia delivery systems. The Karnataka-Telangana corridor is emerging as a domestic manufacturing hub for cost-sensitive electrosurgical units.
South Korea
Academic medical centers in Seoul are modernizing aging infrastructure with 4K surgical display specifications. MFDS cybersecurity requirements for wireless-connected devices are reshaping product architecture for patient monitoring systems. The Busan-Ulsan industrial zone supplies precision motors for high-torque surgical table actuators to regional equipment assemblers.
Global Operating Equipment Room Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement hierarchies that favor bundled platform contracts over discrete device sales. The vendor base organizes into three tiers: diversified medical technology conglomerates with cross-platform software capabilities, mid-scale equipment specialists with regional service networks, and component suppliers feeding into integrated suite assemblers. Dominant competitive moves include strategic partnerships between imaging modality vendors and surgical equipment manufacturers, plus backward integration into precision motor and LED array production.
Among diversified medical technology conglomerates, Stryker and Medtronic exemplify channel-controlling archetypes that anchor integrated digital suite offerings through endoscopy and navigation platform consolidation. Getinge occupies a position within the infection control automation tier, linking sterile processing logistics to operating theater workflows. Siemens Healthineers represents the imaging-to-informatics connectivity archetype, sustaining competitive positioning through advanced visualization system integration rather than standalone hardware sales.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Getinge |
| Zimmer Biomet |
| Koninklijke Philips |
| Siemens Healthineers |
| STERIS |
| KARL STORZ |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in German precision motor manufacturing is compressing supplier margins while simultaneously extending payment terms for surgical table assemblers, creating asymmetric pricing power that favors buyers with multi-year fleet replacement contracts.
Pricing Analysis
The LED-to-halogen technology-generation pricing gap now spans three distinct tiers, with next-generation wireless-enabled suites commanding premium positioning against legacy analog configurations nearing end-of-life. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and EU MDR technical documentation depth as primary differentiation drivers. Cost compression in mid-range anesthesia workstations is intensifying because ASC roll-ups in Texas and Florida are consolidating procurement leverage. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers in the United States demonstrate lowest sensitivity given research grant funding pipelines.
Supply Chain Analysis
Export-control regimes restricting high-torque surgical actuator technology flows from Germany and Japan are forcing secondary sourcing into South Korean and domestic United States precision motor manufacturers. German, Japanese, and South Korean suppliers anchor global production of carbon fiber tabletops, LED illumination arrays, and high-torque actuators respectively. Supply chains draw from rare earth elements for magnetic components, medical-grade aluminum alloys for structural frames, and specialized optical glass for surgical microscopes. Single-source vulnerability concentrates in German surgical table motor production. Distribution runs through group purchasing organizations in the United States and direct hospital contracting in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cross-platform software engineering talent capable of integrating imaging, navigation, and electronic health record systems is constraining vendor expansion and consolidating competitive advantage among established players with captive development teams.
For Market Incumbents: Insulate service revenue streams by embedding real-time device performance telemetry required under EU MDR post-market surveillance rules, while simultaneously backward integrating into LED array production to reduce dependency on Japanese optical component suppliers facing export licensing delays. Threat of mid-tier manufacturers achieving wireless connectivity certification creates urgency for firmware platform consolidation. Channel control through GPO contract exclusivity remains the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 hospital modernization programs under Ayushman Bharat, where mid-range surgical tables and anesthesia workstations face limited competition from premium German and United States vendors. The most penetrable segment is cost-sensitive electrosurgical units for general surgery applications. Go-to-market through domestic manufacturing partnerships in the Karnataka-Telangana corridor minimizes import duty exposure and accelerates CDSCO registration timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid operating room configurations requiring computed tomography or magnetic resonance imaging partnerships, shifting viable returns toward vendors with imaging modality alliances rather than standalone equipment manufacturers. Acquisition targets should prioritize mid-scale equipment specialists with demonstrated EU MDR technical documentation depth and established service networks in ASC-dense geographies. Watch for FDA alignment with PMDA digital health device frameworks as signal of regulatory convergence enabling Asia-Pacific expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for legacy device manufacturers facing notified body capacity constraints. |
| Software Companion Development | Enables workflow platformization that repositions hardware vendors as recurring revenue software providers. |
| Hospital System Partnership | Locks in multi-theater procurement contracts exceeding three million dollars per integrated suite installation. |
| Reimbursement Strategy | Aligns equipment specifications with CMS and commercial payer coverage determinations for outpatient procedures. |
| CE Marking Pathway | Opens procurement channels in German and French hospitals prioritizing suppliers with demonstrated conformity assessment depth. |
Research Approach
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and sterile processing supervisors provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare outpatient procedure volume data. Primary interviews with equipment manufacturers and ASC chain operators combined with bottom-up and top-down triangulation across product category, end-user facility type, and geographic regulatory cluster.
Scenario-bracketing around ambulatory surgical center expansion velocity, EU MDR implementation delays, and LED retrofit penetration rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology generation, procedural application, and end-user facility tier. CAGRs derived from equipment replacement cycle compression and procedure volume migration patterns, with specific inputs from orthopedic intervention demographics and neurosurgery imaging integration requirements.
Sensitivities concentrate around notified body capacity constraints extending EU MDR certification timelines, FDA cybersecurity guidance reshaping wireless device architecture, and ASC financing availability affecting capital expenditure cycles. Forecasts reflect documented assumptions regarding regulatory alignment, technology substitution rates, and health system balance sheet capacity. Material shifts in EU MDR enforcement intensity or FDA digital health premarket pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Collapsible Gates Market
Building Automation Systems
Infrastructure Monitoring Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Global Nordic Building Automation and Control Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Platform Lifts Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Global Modularization Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Building Information Management System Market