
 Porter Cable Air Compressor Market | 2026-2036
Porter Cable Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Porter Cable Air Compressor Market Analytics
EPA Phase 3 emissions standards for small nonroad engines is shifting demand toward electric and cordless power source configurations across the portable compressor category. Ingersoll Rand leverages its industrial compressor heritage to anchor premium positioning in contractor-grade equipment. Atlas Copco competes through sustained R&D intensity in oil-free compression technology for sensitive finish-work applications. Elgi Equipments Limited differentiates through manufacturing scale advantages in cost-optimized pancake and hot dog configurations for price-sensitive DIY channels.
Porter Cable air compressors are portable positive-displacement machines utilizing reciprocating piston architecture with tank-mounted storage vessels ranging from six to thirty gallons, designed to deliver pressurized air for pneumatic fastening, inflation, and light spray finishing tasks in residential and light commercial environments. The product type landscape shows pancake and hot dog formats occupying the volume core due to their stability and portability on uneven job sites, while oil-free designs command margin premiums by eliminating maintenance intervals and contamination risk in finish carpentry. End user segmentation reveals contractors sustaining the replacement cycle through durability requirements, with cordless electric variants capturing incremental share among DIY enthusiasts seeking garage-based versatility without fuel storage constraints.
EPA small engine emissions regulations and OSHA workplace noise exposure limits jointly shape product development priorities, compressing allowable sound signatures while restricting conventional gas power options in certain indoor contracting scenarios. NHTSA and DOT indirect influence through transportation safety standards affects tank certification and portable unit highway mobility design. Stakeholders must monitor battery energy density trajectories and fast-charging infrastructure expansion to assess when cordless platforms can displace corded electric dominance in higher-capacity tank segments.
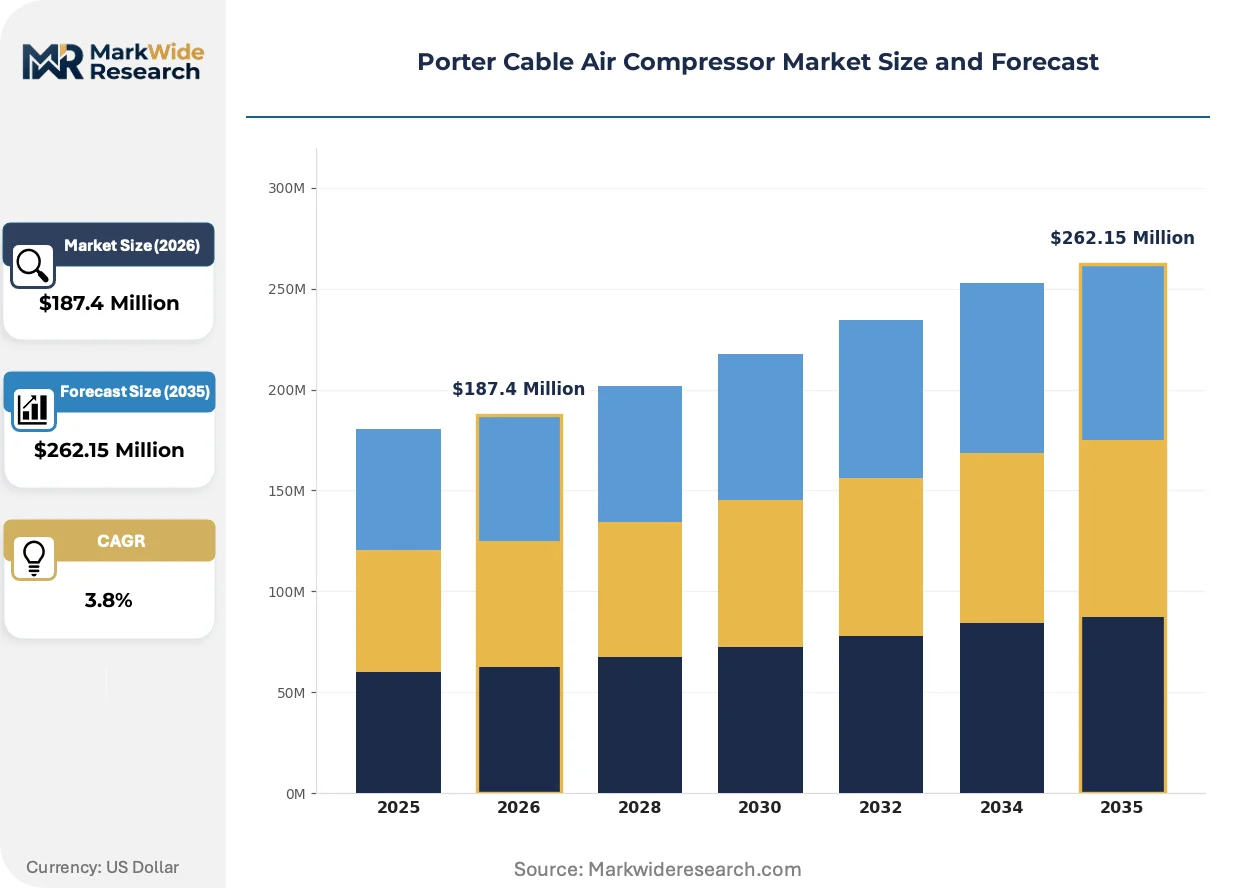
Market Dynamics
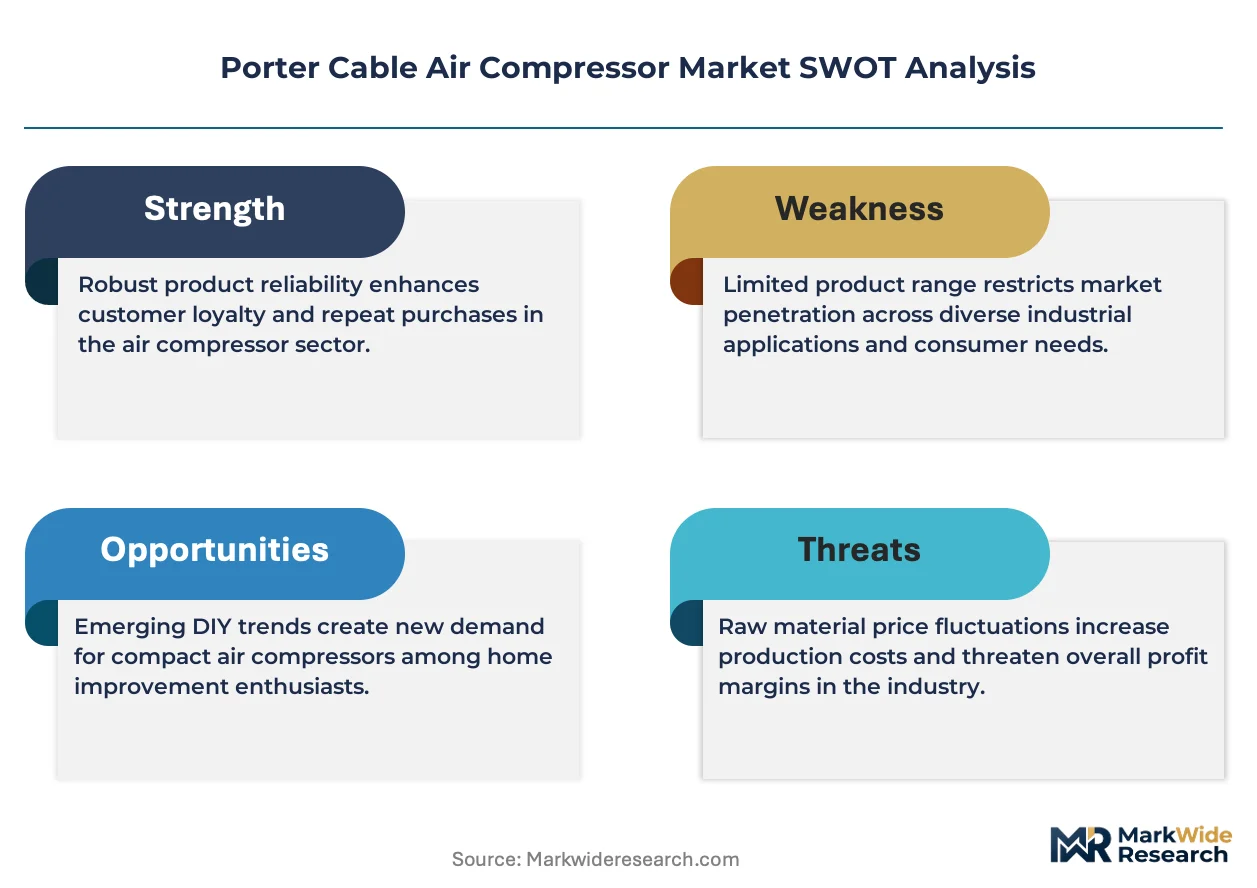
EPA Phase 3 emissions standards for small spark-ignition engines are compressing the addressable market for gasoline-powered portable compressors while accelerating electric and cordless platform development across residential contractor segments.
Growth Catalysts
- EPA Phase 3 Emissions Standards:Regulatory pressure on small nonroad engines is redirecting manufacturer R&D investment toward battery-electric architectures and expanding the certified product pipeline for indoor contracting applications.
- Residential Construction Concentration:Housing starts in Florida, Texas, and Georgia are sustaining replacement demand for pancake and hot dog format compressors among framing and finish carpentry crews.
- Lithium-Ion Energy Density Gains:Advancing cell chemistry is extending runtime duration for cordless compressors, enabling displacement of corded electric units in medium-tank capacity segments previously dominated by stationary power.
Market Restraints
- Steel Input Volatility:Tank fabrication costs fluctuate with hot-rolled coil pricing, compressing margin stability for manufacturers serving price-sensitive DIY retail channels.
- Compressor Motor Supply Concentration:Sourcing dependency on Asian motor winding suppliers creates lead time vulnerability and tariff exposure for US-based assembly operations.
- Acoustic Performance Limits:OSHA permissible exposure limits for workplace noise restrict maximum decibel output, constraining power-to-weight ratios in compact portable designs.
Strategic Opportunities
- Texas Suburban Sprawl Corridors:Exurban development around Dallas-Fort Worth and Houston is generating demand for homeowner-grade cordless compressors supporting deck, fence, and shed construction.
- Inflation Reduction Act Tax Credits:Residential energy efficiency incentives are cross-promoting battery-powered tool ecosystems, creating bundled sales opportunities for cordless compressor SKUs.
- Direct-to-Contractor E-Commerce:Pro-focused digital platforms are bypassing traditional distributor markups, enabling margin capture and customer data accumulation for manufacturers with logistics infrastructure.
Industry Challenges
- EPA Certification Timeline Compression:Engine family certification cycles for remaining gas-powered SKUs are extending product launch schedules and straining compliance engineering capacity.
- Battery Platform Interoperability:Proprietary cell and charger architectures across power tool ecosystems are fragmenting cordless compressor attachment rates and complicating inventory planning for multi-brand retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porter Cable Air Compressor Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancake, Hot Dog, Vertical, Oil-Free End User: Contractors, DIY Enthusiasts, Automotive, Manufacturing Power Source: Electric, Gas, Cordless, Dual Fuel Tank Size: 6 Gallon, 8 Gallon, 20 Gallon, 30 Gallon |
| Companies Covered | Ingersoll Rand, Atlas Copco, Elgi Equipments Limited, MAT Holdings, Sullair, Mitsubishi Heavy Industries, Bauer Compressors, VMAC, Kirloskar Pneumatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porter Cable Air Compressor Market Evolving Landscape
Product development trajectories in portable air compression are converging on electrification, acoustic engineering, and connected diagnostics. These shifts are reshaping competitive differentiation beyond tank capacity and pressure ratings.
Brushless DC motor technology is expanding into mid-capacity portable compressors previously served by universal AC motors. Finish carpentry contractors in the southeastern United States are adopting these platforms for trim nailer applications where runtime and portability balance matters. The technology is expanding into contractor-grade equipment lines by enabling higher duty cycles without brush maintenance intervals.
OSHA workplace noise exposure enforcement is tightening permissible sound signatures for pneumatic equipment operating in enclosed residential construction environments. Manufacturers are responding with acoustic shrouding and slower-running pump designs that trade fill speed for decibel reduction. Finish carpentry segments in multi-family construction are most affected, driving specification preference for oil-free designs with integrated sound dampening.
Service unbundling is altering aftermarket revenue structures as rental channels and big-box retailers introduce compressor maintenance subscription programs. DIY enthusiasts and small remodeling contractors are shifting from ownership-with-maintenance to usage-based access models. Florida and Texas metropolitan markets show highest penetration of these programs, correlating with elevated housing turnover and project-based tool demand.
Porter Cable Air Compressor Market Segmentation
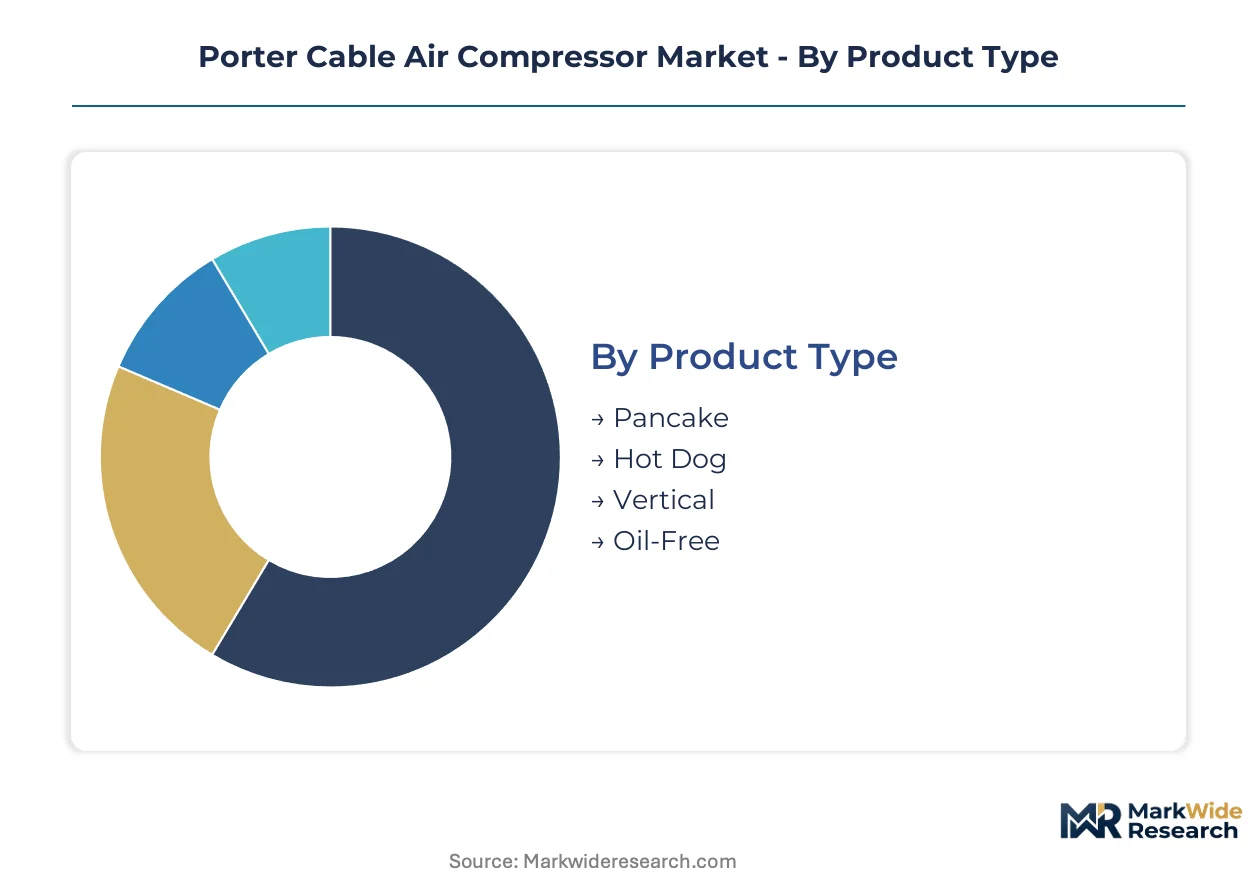
Portable air compressor purchasing patterns diverge sharply between trade professionals prioritizing durability cycles and residential users seeking storage convenience. Segmentation reveals how tank geometry, power architecture, and capacity tiers map to distinct jobsite constraints and garage-based workflows across the southeastern United States.
Product Type:
Buyers in this category sort by stability requirements on uneven surfaces and maintenance tolerance for finish-quality output.
- Pancake:Low-profile welded tanks with six-inch ground clearance dominate framing crews operating on graded dirt lots. Florida residential contractors specify these for hurricane shutter installation where tipping resistance matters.
- Hot Dog:Horizontal cylindrical tanks with wheeled frames suit finish carpentry crews moving between interior rooms. Texas trim crews favor these for baseboard and crown molding sequences requiring clean, oil-free output.
- Vertical:Upright tank configurations maximize floor space efficiency in compact garage workshops. Georgia DIY enthusiasts select these for intermittent brad nailer use where footprint constraints outweigh portability needs.
- Oil-Free:Permanent lubrication elimination removes contamination risk for spray finishing applications. These command specification preference among cabinet installers and furniture refinishers in humid Gulf Coast markets.
Pancake configurations lead volumes today; oil-free designs are gaining share fastest.
End User:
Volume concentration and replacement frequency separate commercial operators from intermittent residential purchasers.
- Contractors:Professional framing and finish crews drive replacement cycles through duty-cycle degradation. These buyers prioritize tank capacity and pump longevity over acquisition cost, concentrating demand in Florida and Texas metropolitan construction corridors.
- DIY Enthusiasts:Homeowners executing deck, fence, and shed projects seek cordless versatility without fuel storage complexity. Inflation Reduction Act battery tool incentives are accelerating cordless compressor attachment rates in suburban Dallas-Fort Worth and Houston exurbs.
- Automotive:Hobbyist mechanics and mobile detailing operators require moderate pressure output for impact wrench and inflation tasks. These users favor compact electric units with rapid recovery times for driveway-based maintenance.
- Manufacturing:Light assembly and packaging operations utilize portable units for pneumatic clamping and material handling. Demand concentrates in small-batch furniture and fixture production facilities across the southeastern United States.
Contractor segments anchor current revenue; DIY cordless adoption is expanding most quickly.
Power Source:
EPA regulatory pressure and runtime requirements are restructuring platform viability across indoor and outdoor applications.
- Electric:Corded AC motor designs dominate stationary workshop installations and indoor remodeling where exhaust ventilation is impractical. These units face displacement pressure as lithium-ion runtime extends.
- Gas:Small spark-ignition engines retain foothold in remote new construction sites lacking grid access. EPA Phase 3 certification timelines are compressing available SKU counts and extending manufacturer compliance costs.
- Cordless:Battery-electric architectures leveraging brushless DC motors are capturing share in medium-capacity segments previously reserved for corded designs. Advancing cell chemistry is enabling trim nailer runtime sufficient for full workday operation.
- Dual Fuel:Hybrid gasoline-propane configurations offer operational flexibility for disaster recovery contractors and utility maintenance crews. These serve niche demand in hurricane response and grid-down scenarios along the Gulf Coast.
Electric platforms sustain installed base dominance; cordless variants show steepest expansion trajectory.
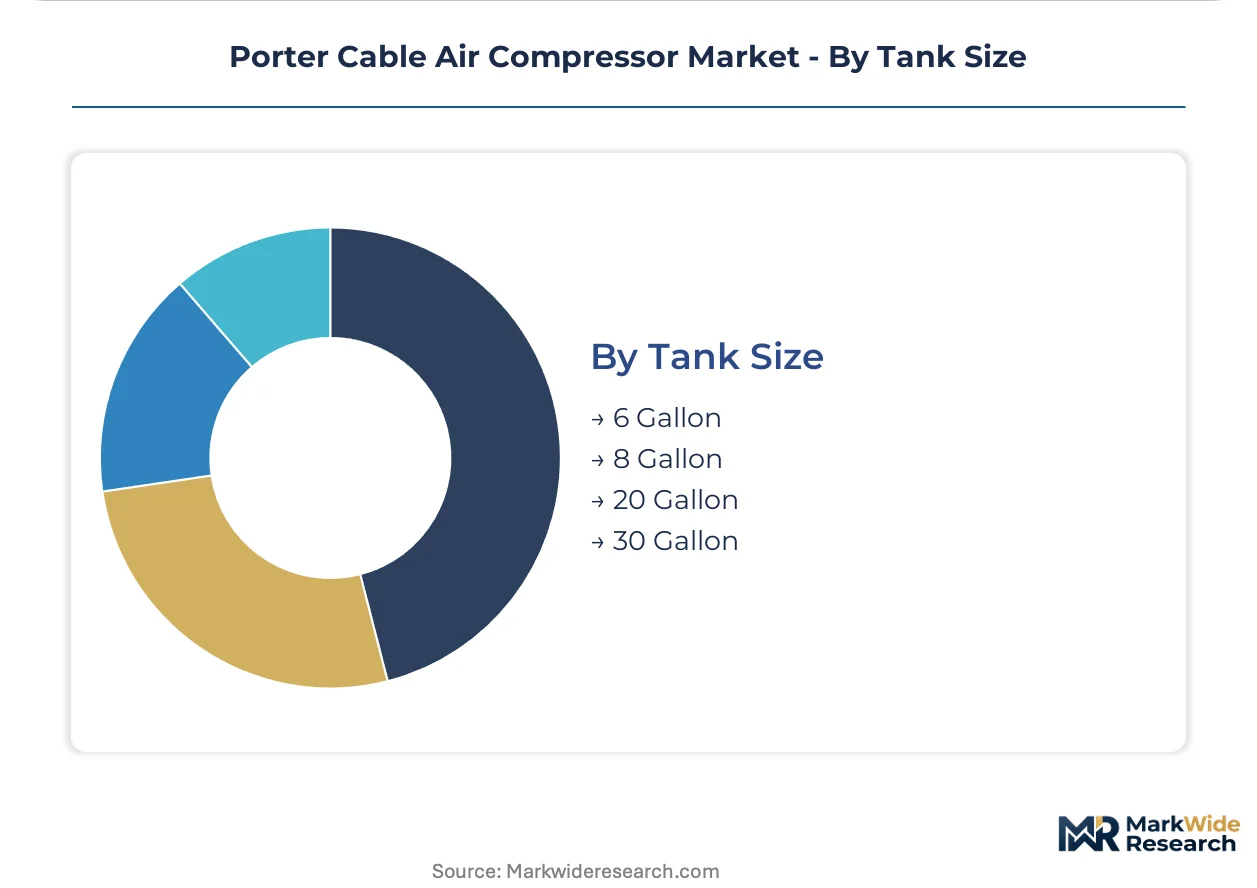
Tank Size:
Capacity selection correlates with tool air consumption profiles and mobility requirements across job types.
- 6 Gallon:Ultra-portable tanks pair with brad nailers and inflation accessories for single-user residential projects. These dominate big-box retail velocity in homeowner channels.
- 8 Gallon:Mid-compact vessels balance runtime extension with manageable transport weight for remodeling contractors. Georgia finish crews specify these for cabinet installation sequences.
- 20 Gallon:Expanded capacity supports framing nailers and light spray guns without excessive recovery cycling. These anchor contractor-grade product lines in Florida housing start markets.
- 30 Gallon:Maximum portable capacity enables extended operation of higher-consumption tools. These serve multi-user crew configurations and light commercial maintenance applications in Texas industrial parks.
Six-gallon formats command unit volume leadership; twenty-gallon configurations are climbing the fastest among professional upgraders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled residential construction crews anchor compressor demand across concentrated housing corridors, with regulatory pressure on small engines redirecting procurement toward electric platforms in established metropolitan markets.
United States
Florida framing contractors drive replacement cycles for pancake-format units through hurricane-season preparation and shutter installation demand. EPA Phase 3 certification timelines compress gasoline-powered SKU availability while accelerating cordless electric development for indoor remodeling compliance. Dallas-Fort Worth exurban sprawl generates homeowner-grade demand through deck and fence construction projects.
Germany
Precision finish carpentry workshops specify oil-free compressor configurations for cabinet and furniture production quality assurance. REACH chemical registration requirements influence lubricant formulation standards for portable compression equipment. Baden-Württemberg manufacturing clusters around Stuttgart integrate pneumatic systems into automated assembly lines for automotive supplier operations.
China
Export-oriented fabrication facilities in the Yangtze River Delta supply tank vessels and motor components to North American assembly operations. GB standards for mechanical safety and electromagnetic compatibility shape domestic product certification requirements. Shenzhen electronics manufacturing corridors drive demand for ultra-quiet oil-free units in cleanroom-adjacent production environments.
India
Small-scale automotive repair workshops in Maharashtra and Gujarat favor cost-optimized reciprocating compressors for tire inflation and impact wrench operation. BIS certification mandates for pressure vessels create compliance barriers for unorganized sector imports. Tamil Nadu manufacturing zones near Chennai assemble compressor components for Southeast Asian export markets.
Japan
Compact workshop culture in the Kanto region sustains demand for vertical tank configurations maximizing floor space efficiency. METI energy efficiency labeling programs influence consumer selection criteria for residential-grade electric models. Osaka-based industrial equipment distributors maintain extensive service networks supporting contractor-grade compressor maintenance intervals.
Porter Cable Air Compressor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the portable compressor category, with integrated manufacturers controlling tank fabrication and pump assembly while specialist brands outsource component sourcing. The structure remains moderately consolidated among industrial heritage players with established distribution infrastructure. Three archetypes dominate: diversified industrial conglomerates leveraging compressor technology as portfolio extension, dedicated pneumatic equipment specialists concentrating R&D on oil-free architectures, and regional fabricators competing on manufacturing scale for price-sensitive channels. Dominant competitive moves include strategic partnerships with battery platform ecosystems and geographic expansion through distributor acquisition in high-growth housing markets.
Among diversified industrial conglomerates, Ingersoll Rand and Atlas Copco exemplify premium-tier positioning anchored by decades of compressed air system heritage. Ingersoll Rand occupies a position representing North American contractor-grade equipment lineage, while Atlas Copco exemplifies European engineering focus on oil-free technology specialization. Elgi Equipments Limited represents the manufacturing-scale archetype, with its Coimbatore-based operations exemplifying cost-optimized production for high-volume DIY retail channels. These three anchors illustrate how competitive differentiation maps to industrial heritage, technical specialization, and manufacturing geography respectively.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Atlas Copco |
| Elgi Equipments Limited |
| MAT Holdings |
| Sullair |
| Mitsubishi Heavy Industries |
| Bauer Compressors |
| VMAC |
| Kirloskar Pneumatic |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Tennessee and Ohio anchor domestic tank production, creating pricing discipline through captive stamping capacity while resisting margin erosion from Asian import competition.
Pricing Analysis
Bundled maintenance subscriptions versus unbundled hardware-only transactions split the pricing landscape. Three-tier pricing structure across premium contractor-grade, standard prosumer, and economy DIY levels stratifies by duty-cycle certification and brushless motor inclusion. Cost compression in the six-gallon economy tier is intensifying because big-box retailers demand promotional slotting fees. DIY enthusiasts exhibit highest price sensitivity; framing crews prioritize pump longevity over acquisition cost.
Supply Chain Analysis
Workforce availability constraints in Coimbatore and Shenzhen manufacturing corridors are extending component lead times for motor windings and pressure vessels. Hot-rolled steel coil from US mills, lithium-ion cells from South Korean suppliers, and copper motor windings from Chinese facilities feed assembly operations. Tariff exposure on Asian motor imports creates margin vulnerability for brands lacking captive winding capacity. Distribution runs through pro-focused distributor networks and big-box retail channels serving divergent buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EPA Phase 3 compliance costs filter out marginal gas-powered competitors and concentrate demand among certified electric platforms with premium specifications.
For Market Incumbents: Lock in brushless DC motor supply agreements with Korean cell suppliers before capacity allocation tightens. Deepen backward integration into tank stamping operations to defend margin position against steel input volatility. Prioritize oil-free pump certification investment to capture specification preference among Gulf Coast finish carpenters facing OSHA noise enforcement.
For New Entrants and Emerging Players: Capture cordless compressor share in Dallas-Fort Worth exurban corridors where Inflation Reduction Act battery incentives accelerate homeowner-grade adoption. Target service-unbundled rental subscription models in Florida metropolitan markets with elevated housing turnover. Pursue direct-to-contractor e-commerce positioning to bypass traditional distributor markups and accumulate customer data assets.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators with captive tank production and underutilized stamping capacity. The five-to-ten year viability window favors manufacturers with certified electric platforms and battery ecosystem partnerships. Monitor NHTSA tank certification timeline delays as inflection signal for compliance-engineering capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Partnership | Secures cell supply allocation from Samsung SDI or LG Energy Solution for cordless expansion. |
| Backward Integration | Captive hot-rolled coil processing mitigates steel price volatility for tank fabrication. |
| Oil-Free Certification Program | UL and OSHA-compliant pump designs command specification preference in finish carpentry segments. |
| Direct-to-Contractor E-Commerce | Bypasses traditional distributor markups while accumulating proprietary demand data. |
| Acoustic Engineering Investment | Slower-running pump designs satisfy tightening OSHA workplace noise exposure limits. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and OEM procurement teams, distributor sales data, and customs import records — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from EPA certification filings, OSHA enforcement databases, SEC 10-K equipment disclosures, and residential construction permit data. Conversations with aftermarket service heads and big-box category buyers informed replacement cycle assumptions.
Historical shipment patterns were cross-referenced against expert panel inputs to establish baseline trajectory. The analytical framework segmented by product type, power architecture, tank capacity tier, and end-user archetype across the projection horizon. CAGRs were derived from fitted trend analysis incorporating housing start correlations and battery energy density improvement curves. Steel price indices and motor import tariff schedules served as industry-specific forecast modifiers.
Regulatory timeline slippage, battery cell supply disruption, and construction activity contraction are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding EPA certification completion rates and lithium-ion cost decline trajectories. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Assembly Machine Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Indonesia Construction Equipment Market