
 Global Dragline Excavator Market | 2026-2036
Global Dragline Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dragline Excavator Market Analysis
Market Context
The divergence between premium electric-drive draglines and commodity-tier hydraulic models is hardening as mining operators prioritize total cost of ownership over upfront capital expenditure. Caterpillar Inc. leverages its integrated powertrain manufacturing to anchor the high-capacity segment across North American coal basins. Komatsu Ltd. competes through sustained R&D investment in autonomous dragline control systems. Liebherr Group specializes in custom-engineered walking draglines for European lignite operations, occupying a niche where technical specification flexibility commands pricing power.
Technical Definition and Segment Structure
A dragline excavator is a surface mining machine employing a large bucket suspended from a boom and reeved with drag ropes that cast and retrieve material across open pits, with operating weights exceeding 1,000 metric tons and bucket capacities ranging from 25 to 220 cubic yards. Walking draglines dominate the high-volume coal and phosphate sectors where mobility between cut sequences eliminates crawler undercarriage wear, while crawler draglines anchor metal mining applications requiring frequent bench relocation. Electric drive technology captures expanding margin pools as pit operators retrofit DC hoist systems with AC variable-frequency drives to reduce energy intensity and maintenance intervals.
Regulatory Frame and Outlook
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine re-manufacturing or full replacement in diesel-hybrid auxiliary systems, reshaping aftermarket service revenue streams for incumbent suppliers. Australia's Department of Industry, Science and Resources and Canada's provincial mining regulators enforce progressive rehabilitation bonds that extend dragline operating lifecycles through precision excavation to minimize disturbance footprints. Stakeholders must monitor the pace of autonomous haulage integration to determine whether dragline fleet investment cycles accelerate or decouple from commodity price signals.
Market Dynamics
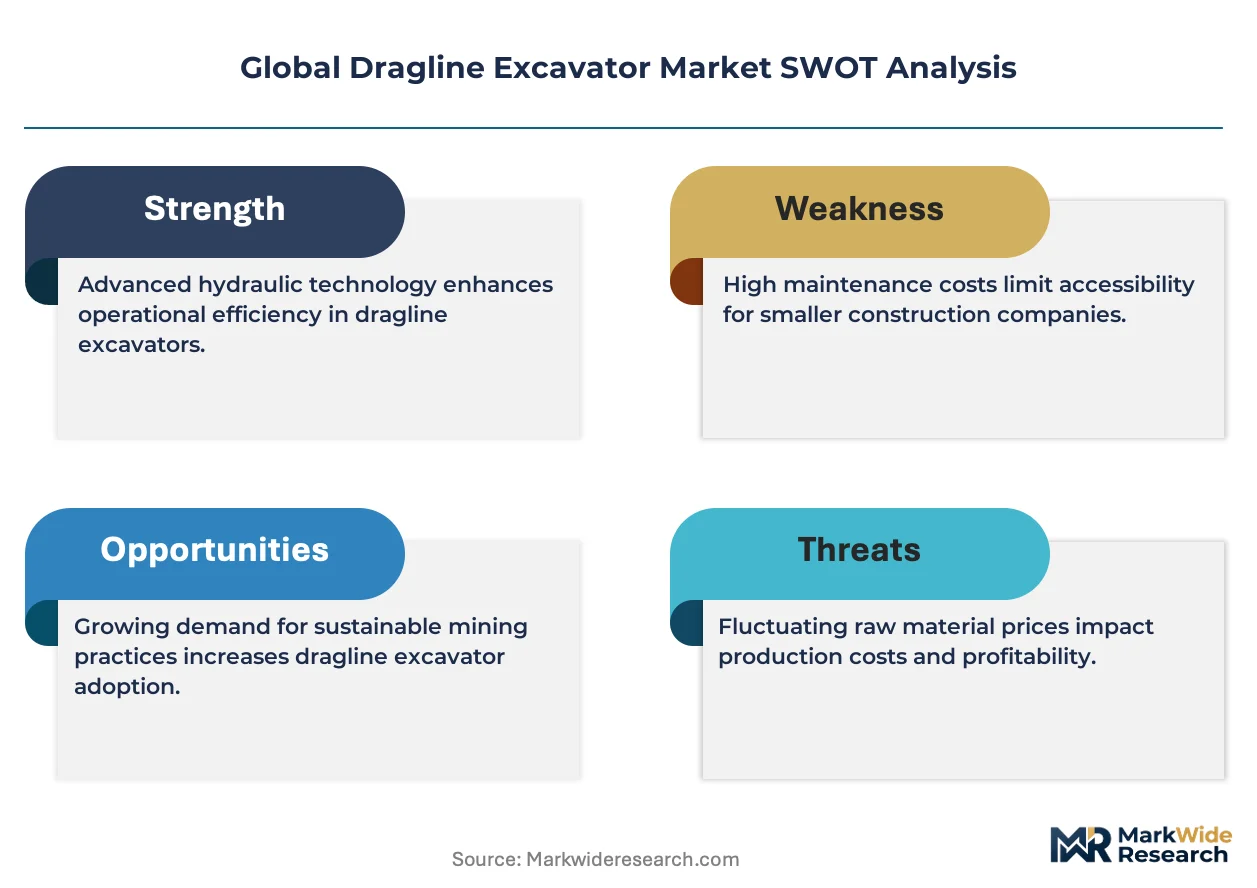
Electric drive retrofits are compressing maintenance intervals and reshaping capital allocation across surface mining fleets as operators confront EPA Tier 4 Final and EU Stage V engine mandates.
Growth Catalysts
- Emissions compliance deadlines:EPA Tier 4 Final and EU Stage V regulations force engine technology upgrades across Australian and Canadian surface mining corridors, triggering fleet renewal cycles.
- Copper extraction intensity:Electrification infrastructure buildouts drive demand for high-capacity walking draglines in Chilean and Peruvian open-pit operations.
- AC variable-frequency drives:Pit operators retrofit DC hoist systems to reduce energy intensity and extend component lifecycles in metallurgical coal basins.
Market Restraints
- Specialized steel input volatility:Boom and bucket fabrication depends on high-grade structural steel subject to concentrated supply from integrated mills.
- Engine remanufacturing bottlenecks:EPA Tier 4 Final compliance creates aftermarket service backlogs at authorized remanufacturing facilities.
- Mechanical drive lock-in:Legacy mechanical configurations in established coal basins resist full electric conversion due to sunk capital and operational familiarity.
Strategic Opportunities
- Autonomous control convergence:Integration of machine learning-based bucket positioning with existing fleet management systems opens retrofit revenue streams.
- Progressive rehabilitation bonds:Australia's Department of Industry, Science and Resources mandates precision excavation capabilities that extend dragline operating lifecycles.
- Phosphate sector expansion:Moroccan and Saudi Arabian phosphate mining corridors represent underpenetrated demand for walking dragline configurations.
Industry Challenges
- Electrical systems integration:AC drive retrofits require specialized technicians capable of harmonizing legacy DC infrastructure with modern variable-frequency systems.
- Autonomous haulage coordination:Dragline fleet investment cycles now depend on synchronization timelines with autonomous truck deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dragline Excavator Market |
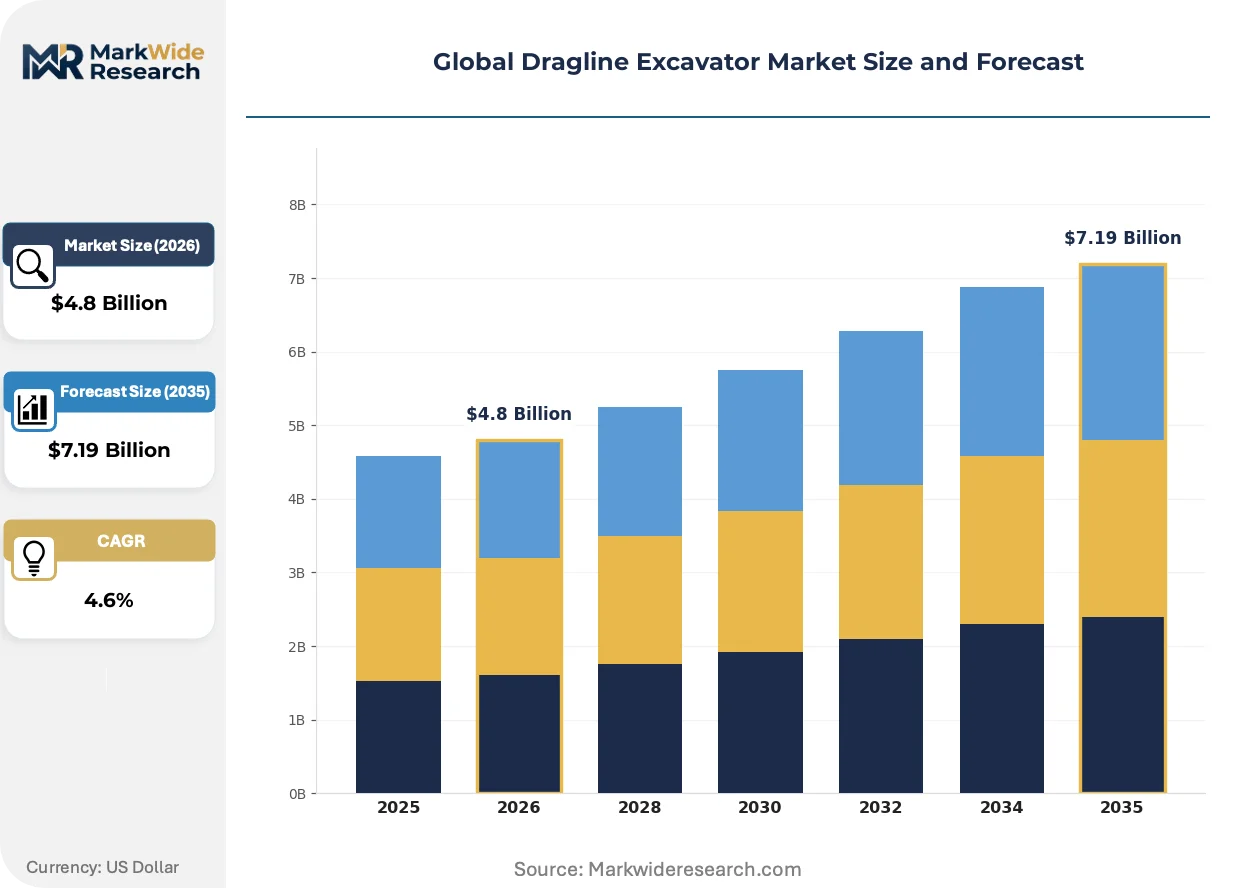
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Dragline, Walking Dragline, Crawler Dragline, Bucket Wheel Excavator Application: Mining, Construction, Dredging, Environmental Remediation End User: Mining Companies, Construction Firms, Government Agencies, Environmental Organizations Technology: Hydraulic Systems, Electric Drive, Automatic Control, Smart Sensors |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Liebherr Group, Hitachi Construction Machinery Co., Ltd., SANY Group, Hyundai Construction Equipment Co., Ltd., XCMG, Shandong Lingong Construction Machinery, Doosan Bobcat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dragline Excavator Market Emerging Trajectories
Digital twin deployment and predictive maintenance algorithms are compressing unplanned downtime windows while regulatory emissions frameworks accelerate powertrain technology turnover.
Siemens and ABB AC variable-frequency drive systems are electrifying hoist and drag motions in 100+ metric ton class draglines. Australian coal operators at BHP and Glencore sites adopt these retrofits to cut energy consumption by double-digit percentages. The technology is electrifying aftermarket service revenue models as OEMs shift from component sales to performance-based uptime contracts.
EU Stage V non-road mobile machinery regulations mandate particulate matter and nitrogen oxide limits that diesel-hybrid auxiliary systems cannot satisfy without exhaust after-treatment. Engine manufacturers face recertification costs that reshape supplier economics. European lignite operators in Germany and Poland accelerate electric drive procurement to preempt compliance deadlines.
Service contract unbundling allows pit operators to separate maintenance from original equipment procurement. Mining houses in Chile's Atacama Desert and Canada's Athabasca oil sands now solicit third-party technical service bids independent of machine purchase agreements. This pattern fragments traditional OEM aftermarket capture and creates openings for specialized electrical systems integrators.
Global Dragline Excavator Market Segmentation
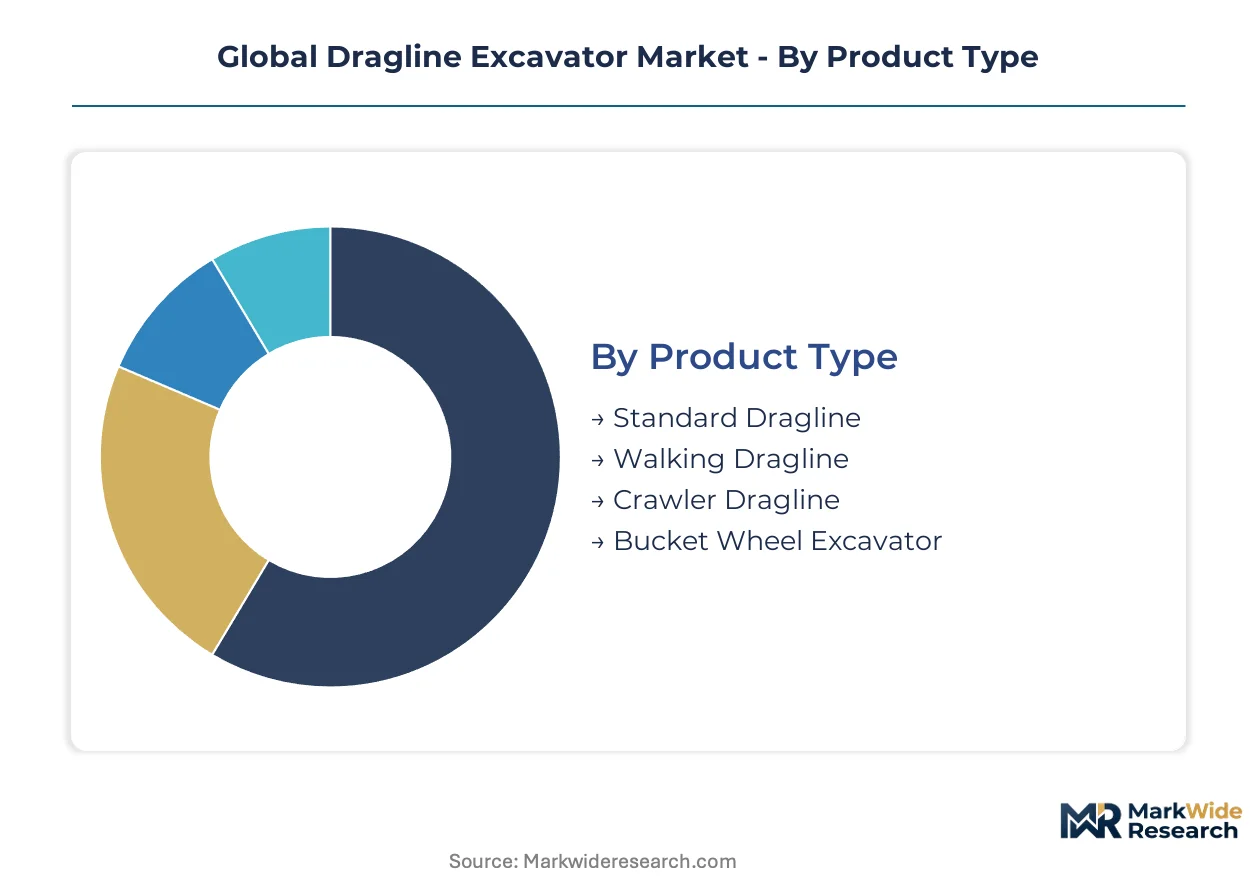
Dragline excavator procurement decisions pivot on mobility requirements, energy infrastructure availability, and regulatory compliance timelines. Mining operators segment purchases by pit geometry, material density, and haulage integration needs rather than standalone machine specifications.
Product Type:
Mining houses select dragline configurations based on bench mobility frequency and capital recovery horizons across multi-decade mine plans.
- Walking Dragline:These machines employ massive tubular booms suspended from walking mechanisms that relocate between cut sequences without crawler wear. Australian coal operators at BHP and Glencore sites deploy walking configurations across the Bowen Basin where pit dimensions exceed 5 kilometers.
- Crawler Dragline:Tracked undercarriages enable frequent bench relocation in metal mining applications. Chilean copper operations in the Atacama Desert favor crawler units for sequenced extraction of multiple ore lenses.
- Standard Dragline:Fixed-base configurations serve specialized dredging and port maintenance roles where mobility is secondary to reach.
- Bucket Wheel Excavator:Continuous digging technology dominates European lignite fields in Germany and Poland where overburden-to-coal ratios favor high-volume, low-selectivity extraction.
Walking draglines lead on scale; crawler draglines lead on momentum.
Application:
End-use concentration varies sharply by commodity cycle position and infrastructure buildout intensity.
- Mining:Surface coal and copper extraction generates the dominant demand pool. EPA Tier 4 Final and EU Stage V regulations force engine technology upgrades across Australian and Canadian surface mining corridors.
- Construction:Large-scale civil earthmoving projects employ draglines for dam construction and channel widening where reach exceeds conventional excavator capability.
- Dredging:Port deepening and waterway maintenance applications favor standard dragline configurations with extended boom geometries.
- Environmental Remediation:Contaminated site excavation commands precision bucket control for selective material handling.
Mining anchors absolute volume; environmental remediation climbs the fastest.
End User:
Procurement authority concentrates with operators bearing direct regulatory compliance liability and rehabilitation bond obligations.
- Mining Companies:Integrated majors and mid-tier producers drive fleet renewal cycles. Australia's Department of Industry, Science and Resources mandates progressive rehabilitation bonds that extend dragline operating lifecycles.
- Construction Firms:Civil contractors acquire draglines through project-specific lease arrangements rather than capital purchase.
- Government Agencies:Public works departments maintain limited fleets for waterway maintenance and flood control infrastructure.
- Environmental Organizations:Non-governmental remediation specialists contract dragline services for contaminated site rehabilitation.
Mining companies dominate capital deployment; environmental organizations gain share fastest.
Technology:
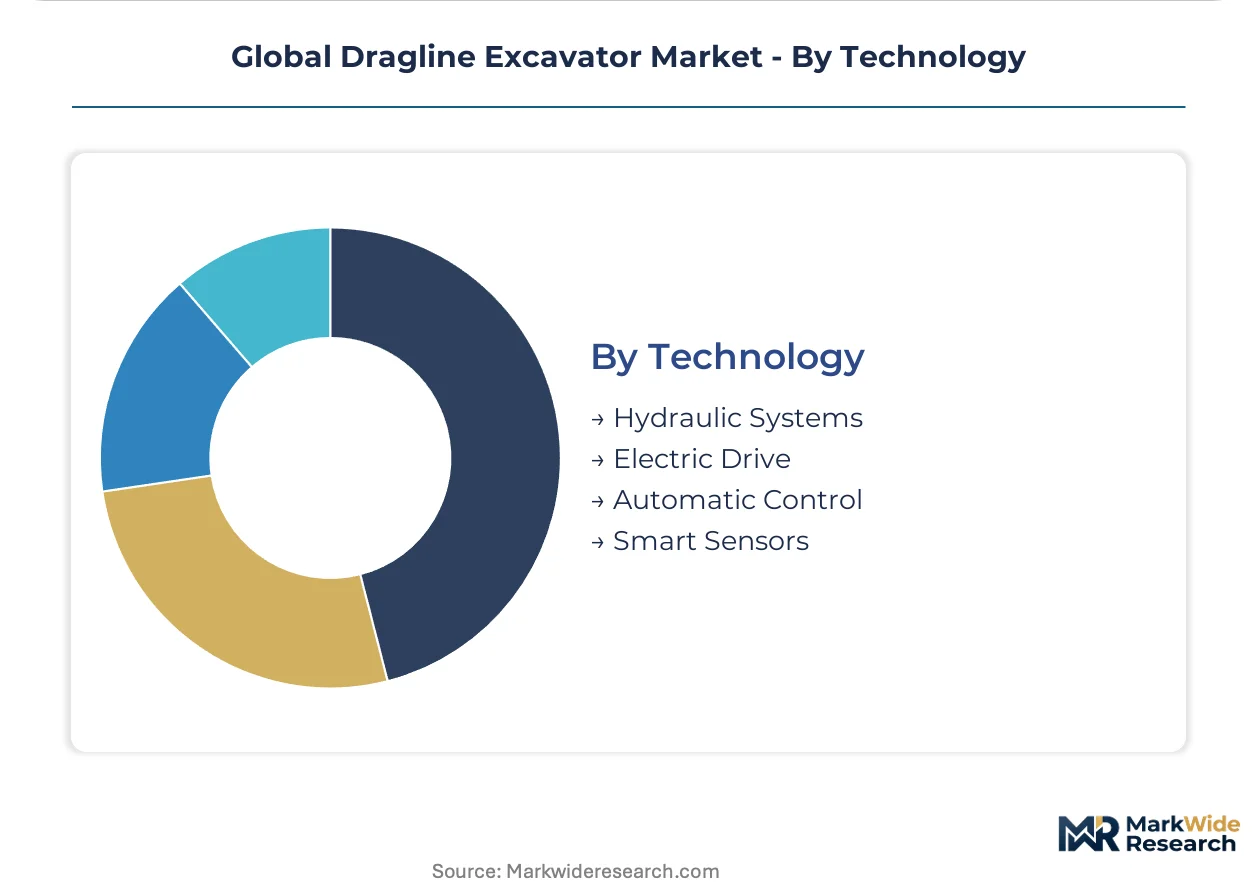
Powertrain selection determines regulatory compliance pathways and total cost of ownership across multi-decade asset lifecycles.
- Electric Drive:AC variable-frequency drive systems displace legacy DC hoist configurations. Pit operators retrofit DC systems to reduce energy intensity in metallurgical coal basins.
- Hydraulic Systems:Diesel-hybrid auxiliary powertrains face EPA Tier 4 Final and EU Stage V recertification costs that reshape supplier economics.
- Automatic Control:Machine learning-based bucket positioning integrates with fleet management systems for autonomous haulage coordination.
- Smart Sensors:Predictive maintenance algorithms compress unplanned downtime windows through real-time structural monitoring.
Electric drive leads on scale; smart sensors expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mining equipment technicians concentrate in Australia's Bowen Basin, Canada's Athabasca region, and Chile's Atacama Desert, anchoring regional service capabilities for dragline fleet operators confronting emissions compliance deadlines.
Australia
BHP and Glencore operate walking dragline fleets across Queensland's Bowen Basin where pit dimensions exceed five kilometers. The Department of Industry, Science and Resources mandates progressive rehabilitation bonds that extend operating lifecycles through precision excavation. Mackay serves as the primary maintenance hub for AC drive retrofits reducing energy intensity at coal operations.
Canada
Surface mining operators in Alberta and Saskatchewan face EPA Tier 4 Final engine remanufacturing requirements for diesel-hybrid auxiliary systems. Provincial mining regulators enforce rehabilitation bond structures that favor extended asset utilization. Fort McMurray clusters dragline service capacity for Athabasca oil sands extraction where electric drive conversions are accelerating.
Chile
Copper extraction intensity drives demand for crawler draglines in sequenced ore lens development across the Atacama Desert. The national mining regulator encloses environmental licensing requirements that shape capital recovery horizons. Antofagasta anchors fleet management coordination between dragline operations and autonomous haulage deployment schedules.
Germany
EU Stage V regulations compel electric drive procurement among lignite operators in the Rhenish and Lusatian mining districts. The KBA enforces non-road mobile machinery emissions limits that diesel-hybrid systems cannot satisfy without after-treatment. Cologne-Bonn concentrates engineering expertise for custom walking dragline specifications serving European brown coal corridors.
United States
Appalachian and Powder River Basin coal operators navigate EPA Tier 4 Final compliance timelines for fleet renewal cycles. The Environmental Protection Agency structures engine certification pathways that reshape aftermarket service economics. Gillette, Wyoming hosts concentrated dragline maintenance infrastructure for high-volume surface mining operations.
Global Dragline Excavator Market Vendor Landscape
Top-tier vendors anchor integrated powertrain manufacturing, while mid-tier fabricators compete through regional customization and aftermarket service density. The vendor base stratifies across three tiers: full-system OEMs controlling electric drive technology, specialized walking dragline engineers serving niche lignite applications, and diversified construction equipment manufacturers extending into mining attachments. Competitive moves concentrate on autonomous control convergence and service contract unbundling rather than pure equipment sales.
Within the full-system OEM tier, Caterpillar Inc., Komatsu Ltd., and Liebherr Group occupy positions that exemplify divergent strategic archetypes. Caterpillar Inc. represents North American market anchoring through captive powertrain integration. Komatsu Ltd. exemplifies sustained R&D positioning in autonomous machine control. Liebherr Group occupies the custom-engineered specialization niche where technical flexibility commands pricing power in European lignite corridors.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Liebherr Group |
| Hitachi Construction Machinery Co., Ltd. |
| SANY Group |
| Hyundai Construction Equipment Co., Ltd. |
| XCMG |
| Shandong Lingong Construction Machinery |
| Doosan Bobcat Inc. |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final and EU Stage V emissions mandates gate qualified supply for electric-drive draglines and anchor premium-tier pricing access for OEMs with certified powertrain integration. Mining operators in Australia and Canada confront compliance-driven fleet renewal cycles where only vendors with captive AC variable-frequency drive manufacturing can command performance-based contract premiums.
Pricing Analysis
Service contract unbundling splits the market between bundled OEM procurement-maintenance packages and unbundled third-party technical service bids. Three-tier pricing structure across premium, standard, and economy levels reflects electric drive certification status, aftermarket service density, and autonomous control integration depth. Cost compression in commodity-tier hydraulic configurations intensifies as Chinese manufacturers expand export capacity. Junior mining houses and civil contractors exhibit highest price sensitivity; integrated majors prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BHP and Glencore while specialized electrical systems integrators serve unbundled aftermarket retrofits. High-grade structural steel fabrication concentrates in Germany, Japan, and South Korea where integrated mills supply boom and bucket components. AC variable-frequency drive systems draw from Siemens and ABB manufacturing footprints in Europe and Asia. Single-source vulnerability in specialized steel inputs exposes fabricators to mill capacity allocation decisions. Distribution runs through authorized dealer networks anchored in Mackay, Fort McMurray, and Gillette.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dragline excavators rests on AC drive retrofit penetration and performance-based service contract conversion, with electric drive technology compressing maintenance intervals and extending component lifecycles.
For Market Incumbents: Lock in aftermarket capture by integrating predictive maintenance algorithms with existing fleet management systems before third-party electrical systems integrators fragment service revenue. Deepen backward integration into AC variable-frequency drive manufacturing to preempt component supply bottlenecks. Defend against Chinese hydraulic manufacturers by anchoring premium positioning through EPA Tier 4 Final and EU Stage V certification exclusivity.
For New Entrants and Emerging Players: Specialized electrical systems integrators represent the most penetrable channel partner type for aftermarket AC drive retrofits in Chilean copper corridors and Saudi Arabian phosphate expansions. Target unbundled service procurement patterns at mid-tier mining houses in the Atacama Desert and Athabasca oil sands where OEM maintenance contracts have lapsed. Pursue joint-venture structures with established walk-dragline fabricators to bypass capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because mining operator procurement decentralization fragments OEM capture and creates platform consolidation opportunities. Five-to-ten year viability favors electrical systems integrators with EPA Tier 4 Final and EU Stage V technician certification pipelines. Monitor autonomous haulage deployment schedules at BHP and Glencore sites as the inflection signal for dragline fleet investment cycle acceleration or decoupling from commodity price signals.
| Strategic Initiative | Industry Significance |
|---|---|
| AC Drive Retrofit Program | Siemens and ABB electrification partnerships cut energy intensity at Bowen Basin coal operations. |
| Autonomous Control Integration | Machine learning-based bucket positioning synchronizes with Komatsu autonomous haulage deployment. |
| Service Contract Unbundling | Third-party technical bids at Chilean copper sites fragment traditional OEM aftermarket capture. |
| Specialized Steel Backward Integration | German and Japanese mill partnerships secure boom fabrication capacity for European lignite orders. |
| Progressive Rehabilitation Bond Compliance | Precision excavation capabilities extend operating lifecycles under Australian Department of Industry mandates. |
Methodological Framework
Bottom-up mining operator fleet modeling reconciled against top-down OEM powertrain manufacturing tracking forms the analytical core. Primary interviews with maintenance directors at BHP and Glencore sites, plant engineers in Alberta oil sands operations, aftermarket service heads at Caterpillar and Komatsu dealerships, and procurement teams at Chilean copper majors combined with secondary validation. Secondary sources include EPA engine certification databases, EU Stage V type-approval registries, Australian Department of Industry rehabilitation bond filings, and Canadian provincial mining regulator disclosure records. Triangulation across these sources anchors volume and value estimates.
Input-output matrix framing connects dragline unit shipments to copper extraction intensity, metallurgical coal output, and phosphate sector capital expenditure across the projection horizon. Segmentation dimensions encompass product type (walking, crawler, standard), powertrain technology (electric drive, hydraulic, mechanical legacy), application (surface mining, construction, dredging), and end-user category (integrated majors, mid-tier producers, civil contractors, government agencies). CAGRs derive from regression analysis against commodity price scenarios and regulatory compliance deadline clustering. Industry-specific forecast inputs include autonomous haulage deployment timelines and progressive rehabilitation bond obligation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper demand volatility, Chinese hydraulic manufacturer export pricing, and EU Stage V recertification cost pass-through. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Radial Drilling Machine Market