
 Liquid Applied Roofing Market | 2026-2036
Liquid Applied Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Applied Roofing Market Analysis
FM Global 4470 approval and UL 2218 Class 4 impact ratings are redrawing competitive boundaries in liquid applied roofing. Sika AG leverages its Swiss manufacturing base to sustain premium positioning in polyurethane systems across European commercial projects. Johns Manville Corporation anchors North American distribution through its captive contractor network and building envelope integration. BASF SE competes on raw material backward integration, controlling polyol supply chains that feed downstream membrane formulations.
Liquid applied roofing comprises fluid-applied polymer membranes that cure into seamless, elastomeric waterproofing layers typically 20–120 mils thick, engineered to accommodate thermal cycling and structural movement across flat or low-slope substrates. Silicone formulations command margin pools in commercial re-roofing where UV resistance and ponding water tolerance justify premium pricing over acrylic alternatives. Spray application technology leads installation speed for large industrial decks, while brush and roll methods occupy the residential and maintenance segments where access constraints favor manual precision.
EPA VOC regulations in the United States restrict solvent-based formulation chemistries, pushing manufacturers toward waterborne and high-solids compliant systems. ECHA REACH registration requirements in Europe govern isocyanate handling in polyurethane production, elevating compliance costs for smaller compounders. Stakeholders must monitor how building energy codes in multiple jurisdictions integrate cool roof reflectivity requirements with liquid applied product specifications.
Market Dynamics
Seamless membrane technology is compressing installation timelines and eliminating seam-failure liabilities that plague traditional sheet roofing, while the EU Green Deal's building renovation mandates force specification upgrades across commercial portfolios.
Growth Catalysts
- Deep retrofit mandates:Germany's building energy efficiency regulations now require waterproofing upgrades during facade renovations, pulling silicone membrane specifications into standard commercial tenders.
- Spray application robotics:Automated plural-component equipment is cutting labor hours on industrial deck projects by half, expanding addressable project scale for applicator networks.
- Cool roof integration:EPA ENERGY STAR and Title 24 requirements in California are bundling high-reflectivity liquid systems with HVAC load reduction calculations.
Market Restraints
- Isocyanate supply concentration:European polyol feedstock production clusters in the Antwerp-Rotterdam-Rhine-Ruhr corridor, exposing formulators to single-point disruption risks.
- Acrylic substitution ceiling:Acrylic formulations face performance caps in ponding water conditions, restricting their deployment on poorly drained substrates.
- REACH registration costs:ECHA's extended dossier requirements for novel polyurethane catalysts are freezing formulation innovation among mid-tier compounders.
Strategic Opportunities
- Data center vertical expansion:Hyperscale facility construction in Northern Virginia and Frankfurt is specifying liquid membranes for roof-mounted cooling equipment plinths.
- Maintenance channel digitization:Drone-based substrate assessment platforms are enabling predictive re-coating contracts that lock in multi-year service revenue.
- Swiss building envelope convergence:SIA energy standards are mandating simultaneous air barrier and waterproofing upgrades, favoring fluid-applied systems that combine both functions.
Industry Challenges
- Certified applicator scarcity:Manufacturer warranty programs require factory-trained installation crews, creating bottlenecks in markets with sparse contractor density.
- Weather window compression:Silicone and polyurethane cure chemistry demands precise temperature and humidity conditions, squeezing viable application seasons in continental climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Applied Roofing Market |
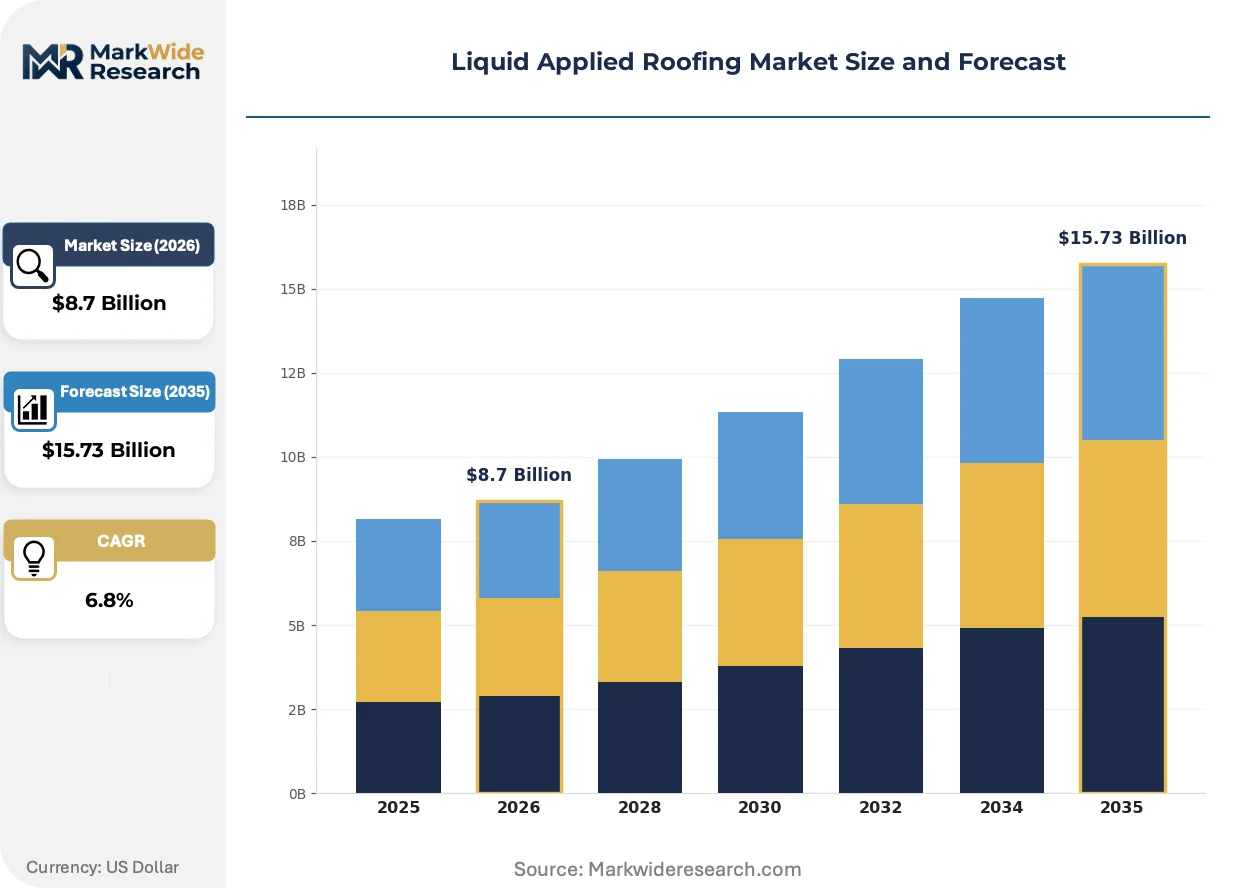
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Silicone, Bitumen Application: Residential, Commercial, Industrial, Agricultural End User: Contractors, Property Developers, Facility Managers, Homeowners Technology: Spray, Brush, Roll, Roller |
| Companies Covered | DOW Chemical, AkzoNobel N.V., Sika AG, Kemper System America Inc., Johns Manville Corporation, BASF SE, Saint-Gobain S.A., 3M Company, GAF Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Applied Roofing Market Emerging Trajectories
Formulation chemistry and application methodology are converging to eliminate the performance gaps that once separated liquid systems from mechanically attached alternatives.
Hybrid polyurea-silane formulations are displacing conventional polyurethane membranes in high-traffic rooftop amenity decks. Hotel and multifamily developers specify these systems for their rapid cure and abrasion resistance. The technology is displacing epoxy traffic coatings that previously required separate waterproofing layers beneath.
EPA VOC regulations are tightening solvent content thresholds in architectural coatings, forcing manufacturers toward waterborne and high-solids compliant chemistries. Formulation labs are re-engineering viscosity profiles to maintain sprayability without volatile thinners. California's South Coast Air Quality Management District rules are accelerating this transition fastest in the US market.
Building owners are bundling roof membrane replacement with solar mounting infrastructure, creating integrated procurement packages. EPC contractors are absorbing waterproofing scope that previously sat with specialty roofing firms. This consolidation is most visible in German commercial retrofit projects where the EU Green Deal subsidies require holistic envelope upgrades.
Liquid Applied Roofing Market Segmentation
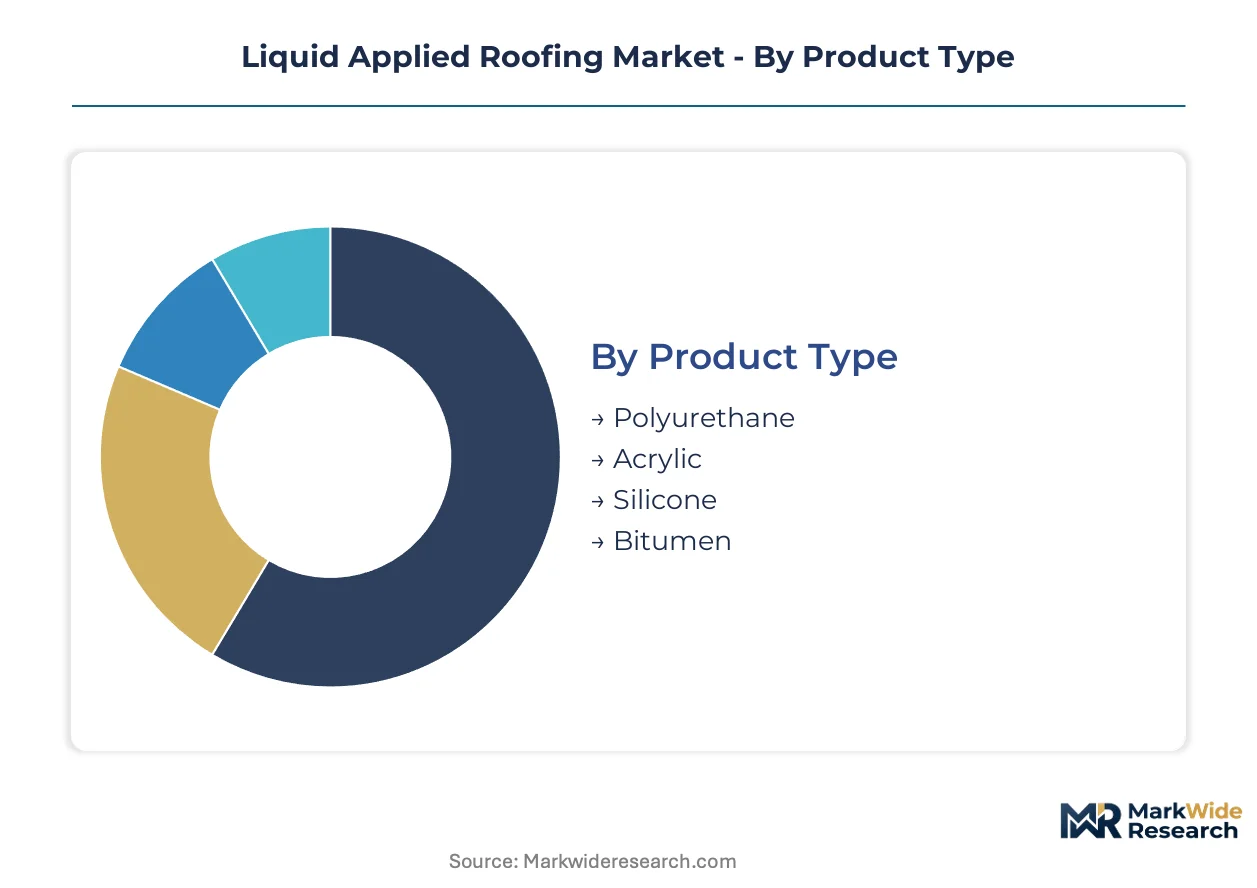
Segmentation in liquid applied roofing reveals how formulation chemistry, installation method, and procurement authority fragment margin capture across the value chain. Specification power sits with distinct buyer types, while application technology determines labor economics and project scalability.
Product Type:
Margin pools concentrate in silicone and polyurethane formulations where performance premiums justify higher price points, while acrylic and bitumen segments compete on installed cost.
- Polyurethane:Elastomeric membranes formed from isocyanate-polyol reactions cure into 60–120 mil seamless layers with exceptional tensile strength and chemical resistance. Demand clusters in German commercial retrofits where EU Green Deal renovation mandates require high-performance waterproofing upgrades during facade work, though isocyanate supply concentration in the Antwerp-Rotterdam-Rhine-Ruhr corridor exposes formulators to disruption risks.
- Silicone:Moisture-cure formulations deliver UV stability and permanent ponding water tolerance without re-emulsification failure. Commercial re-roofing specifications in California and Florida favor silicone where Title 24 cool roof requirements and hurricane-zone moisture exposure coincide, commanding price premiums over acrylic alternatives.
- Acrylic:Waterborne emulsions offer lower material cost and VOC compliance ease under EPA architectural coating rules. Performance ceilings in standing water conditions restrict deployment on poorly drained industrial substrates.
- Bitumen:Modified asphalt fluid systems provide cost-effective waterproofing for agricultural and utility building applications. Cure speed limitations and temperature sensitivity compress viable application windows in continental climates.
Polyurethane holds installed capacity. Silicone is rotating up the share rankings.
Application:
Volume distribution tracks building stock age and regulatory retrofit intensity across property types.
- Commercial:Office, retail, and hospitality portfolios drive membrane replacement cycles, with EU Green Deal building renovation requirements tightening waterproofing performance standards across European commercial assets. Procurement bundles increasingly combine roof replacement with solar mounting infrastructure.
- Industrial:Manufacturing facilities and logistics centers specify spray-applied systems for large deck areas where automated plural-component equipment cuts labor hours. FM Global 4470 approval requirements dominate specification authority in North American industrial risk engineering.
- Residential:Single-family and multifamily re-roofing favors brush and roll methods where access constraints and smaller surface areas favor manual precision over spray economics.
- Agricultural:Barns, silos, and processing facilities prioritize material cost containment, with bitumen and acrylic formulations capturing specification share.
Commercial commands current volume leadership. Industrial is expanding most quickly as hyperscale data center construction accelerates membrane demand for cooling equipment plinths.
End User:
Procurement authority determines specification complexity and warranty requirements.
- Contractors:Specialty roofing and general construction firms control installation scope and manufacturer warranty eligibility, with factory-trained crew certification creating bottlenecks in markets with sparse applicator density.
- Property Developers:Hotel and multifamily ground-up construction specifies hybrid polyurea-silane systems for rooftop amenity decks where rapid cure and abrasion resistance displace separate waterproofing and traffic coating layers.
- Facility Managers:Corporate and institutional portfolio owners are adopting drone-based substrate assessment platforms to enable predictive re-coating contracts that lock in multi-year service revenue streams.
- Homeowners:Individual residential buyers prioritize initial cost over lifecycle performance, limiting specification to entry-grade acrylic and bitumen systems.
Contractors dominate specification influence. Facility managers are climbing the fastest as predictive maintenance digitization shifts procurement toward outcome-based service contracts.
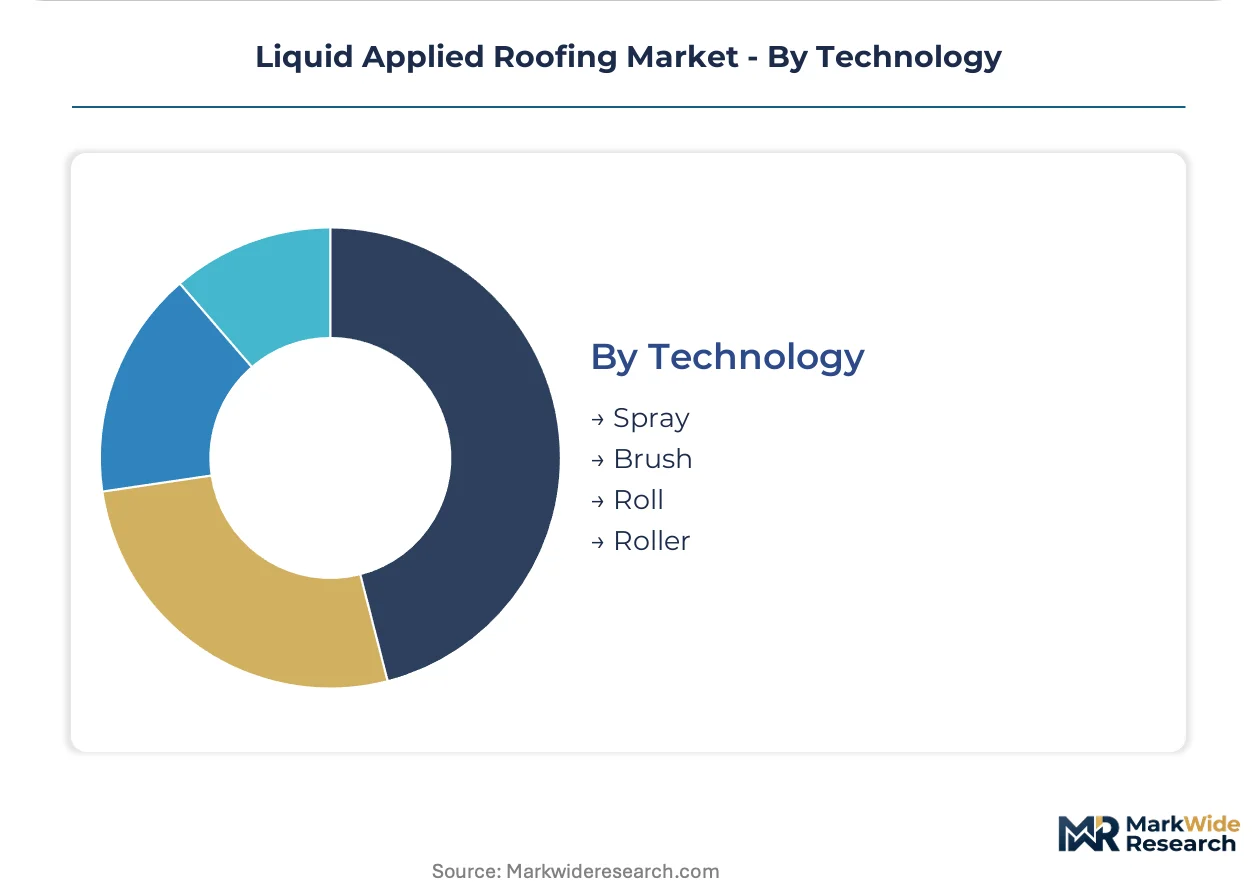
Technology:
Application method selection balances labor productivity against substrate complexity and environmental constraints.
- Spray:Plural-component heated spray systems deliver 1,000+ square feet per hour on large industrial decks, with robotic automation expanding addressable project scale for qualified applicator networks.
- Brush:Manual application provides precision around penetrations, curbs, and complex geometries where overspray risk and masking costs outweigh speed advantages.
- Roll:Roller application occupies mid-scale commercial maintenance segments where equipment mobilization costs and crew training requirements fall between spray and brush economics.
- Roller:Conventional paint-roller methods persist in residential and small commercial touch-up work where capital equipment investment is uneconomical.
Spray holds throughput leadership. Brush is gaining share fastest in maintenance channel digitization where precision application supports predictive coating contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building owners in Germany and the United States concentrate procurement authority for premium membrane systems, while industrial facility operators in China and data center developers in Northern Virginia drive specification volume for spray-applied installations.
Germany
Deep retrofit mandates under the EU Green Deal pull silicone and polyurethane specifications into standard commercial tenders during facade renovation cycles. ECHA REACH registration requirements govern isocyanate handling in polyurethane production, elevating compliance costs for formulators. The Rhine-Ruhr corridor anchors polyol feedstock production clusters, exposing membrane manufacturers to concentrated supply disruption risks.
United States
Hyperscale data center construction in Northern Virginia accelerates membrane demand for roof-mounted cooling equipment plinths. EPA VOC regulations restrict solvent-based formulation chemistries, pushing manufacturers toward waterborne and high-solids compliant systems. California's Title 24 cool roof requirements bundle high-reflectivity liquid systems with HVAC load reduction calculations.
China
Industrial logistics center expansion drives spray-applied system volume for large deck areas where labor productivity determines project economics. The country's national environmental regulator enforces volatile organic compound emission standards that parallel EPA thresholds. Yangtze River Delta manufacturing clusters concentrate formulation capacity for domestic polyurethane membrane supply.
Switzerland
SIA energy standards mandate simultaneous air barrier and waterproofing upgrades, favoring fluid-applied systems that combine both functions. Swissmedic-equivalent building material certification requirements ensure performance validation for commercial specifications. Zurich and Geneva commercial portfolios drive premium system uptake where skilled applicator density supports warranty-eligible installation.
United Kingdom
Commercial property retrofit programs accelerate membrane replacement cycles across aging office and retail portfolios. The country's building safety regulator enforces post-Grenfell facade and roofing material performance standards that favor certified seamless systems. London's commercial real estate concentration concentrates specification authority with portfolio owners managing multi-asset renovation programs.
Liquid Applied Roofing Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with backward integration into polyol supply chains, mid-tier regional compounders dependent on merchant feedstock, and captive building materials divisions of construction distribution networks. Strategic archetypes separate raw material controllers, formulation specialists with applicator certification programs, and integrated envelope system providers. Competitive moves concentrate on M&A to secure applicator network density and capacity expansion in high-growth data center corridors.
Within the diversified chemical tier, BASF SE and DOW Chemical exemplify raw material backward integration archetypes that control upstream polyol supply chains feeding downstream membrane formulations. Sika AG represents the European formulation specialist model with concentrated commercial project presence. Johns Manville Corporation anchors the building materials captive channel strategy through integrated distribution and envelope system bundling. Saint-Gobain S.A. occupies a position spanning multiple competitive archetypes through portfolio breadth across construction materials.
| Leading Market Players |
|---|
| DOW Chemical |
| AkzoNobel N.V. |
| Sika AG |
| Kemper System America Inc. |
| Johns Manville Corporation |
| BASF SE |
| Saint-Gobain S.A. |
| 3M Company |
| GAF Materials Corporation |
| Others |
Supply Flow & Price Mechanics
Project-based procurement with indexed raw material pass-through clauses locks in polyol supply access for German formulators while anchoring price visibility against isocyanate volatility. This contract architecture concentrates margin defense among backward-integrated chemical conglomerates.
Pricing Analysis
Cost-plus contracts with polyol indexation dominate procurement between membrane formulators and European chemical suppliers. Three-tier pricing structure across premium silicone, standard polyurethane, and economy acrylic levels separates specifications by FM Global certification grade and cool roof reflectivity performance. Pricing pressure stems from REACH registration cost absorption among mid-tier compounders. Facility managers exhibit lowest price sensitivity due to lifecycle cost modeling, while agricultural buyers prioritize material cost containment.
Supply Chain Analysis
Inventory cycles for isocyanate feedstocks extend lead times during Antwerp-Rotterdam-Rhine-Ruhr corridor maintenance turnarounds. Polyol production clusters in Germany, Belgium, and the Netherlands anchor upstream supply, while membrane formulation capacity concentrates in Germany, the United States, and China. Raw material dependencies include aromatic isocyanates, silicone polymers, and catalyst packages. Single-source vulnerability in European polyol supply creates disruption exposure. Distribution runs through captive contractor networks and building envelope specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility managers and portfolio owners as predictive maintenance digitization consolidates procurement authority across multi-asset renovation programs.
For Market Incumbents: Compound warranty-eligible applicator density in Northern Virginia and Frankfurt data center corridors to defend against EPC contractor scope absorption. Deepen backward integration into polyol supply chains to offset REACH-driven catalyst cost inflation. Invest in drone-based substrate assessment platforms to lock predictive re-coating contracts. For New Entrants and Emerging Players: Anchor in Swiss commercial retrofit markets where SIA energy standards mandate simultaneous air barrier and waterproofing upgrades. Target mid-tier German compounders facing REACH registration cost freezes for acquisition or partnership. Pursue white-label supply to drone-based maintenance platforms as the go-to-market angle. For Investors and Strategic Acquirers: Regional formulation specialists with captive applicator certification programs represent the most defensible acquisition profile. Long-term viability hinges on positioning within EU Green Deal renovation subsidy flows and data center construction pipelines. Monitor isocyanate supply disruption frequency as the inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Network Expansion | Factory-trained crew density secures warranty eligibility and locks out competitors in sparse markets. |
| Backward Integration into Polyols | In-house production of isocyanate-polyol feedstocks insulates margin from Antwerp-Rotterdam corridor disruptions. |
| Drone-Based Assessment Platform | Predictive maintenance digitization shifts procurement toward outcome-based service contracts with multi-year revenue. |
| Hybrid Formulation Development | Polyurea-silane systems displace separate waterproofing and traffic coating layers in rooftop amenity specifications. |
| Cool Roof Certification Investment | EPA ENERGY STAR and Title 24 compliance bundles membrane specifications with HVAC load reduction calculations. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with membrane formulators, applicator network managers, facility management directors, and EPC contractors; and secondary validation through ECHA REACH registration databases, EPA VOC compliance filings, FM Global approval directories, and EU Green Deal subsidy disbursement records. Bottom-up project pipeline triangulation against top-down chemical feedstock demand models anchored volume estimates.
Across the analysis window, the forecast framework modeled formulation chemistry tiers, application technology methods, building type segments, and procurement authority channels. CAGRs were derived from segment-level growth rate reconciliation against macro construction indicators. Industry-specific inputs included EU Green Deal renovation intensity projections and hyperscale data center cooling infrastructure deployment schedules.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continuous isocyanate supply availability assumptions; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
North America Steel Rebar Market