
 Europe Forklift Rental Market | 2026-2036
Europe Forklift Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Forklift Rental Market Insights
Equipment leasing partnerships between rental providers and third-party logistics platforms is reconfiguring how forklifts reach end-users across Europe. KION Group leverages its manufacturing scale to supply captive rental fleets through Jungheinrich, which sustains technology leadership in lithium-ion integration. Loxam competes through dense branch networks in France and Benelux, while Boels Rental anchors Nordic coverage with specialized cold-storage equipment.
A forklift rental arrangement provides temporary access to powered industrial trucks with load capacities typically spanning 1.5 to 16 tonnes, featuring mast heights, fork lengths, and powertrains matched to specific material handling tasks. Electric units dominate indoor warehousing contracts due to zero-emission operation in enclosed spaces, while rough terrain models serve outdoor construction sites where diesel powertrain reliability remains essential. Contractors represent the most price-sensitive customer type, often demanding flexible short-term agreements, whereas manufacturers negotiate longer tenures with maintenance bundling that locks in margin pools for rental operators.
EU Green Deal targets and the F-Gas Regulation are pressuring rental fleets to accelerate diesel-to-electric transitions, while CE marking requirements under the Machinery Directive enforce operator safety standards that shape equipment specification. ECHA chemical restrictions on battery materials and national workplace safety frameworks in Germany and France add compliance layers that favor larger rental providers with dedicated certification resources. Stakeholders must monitor battery supply chain bottlenecks and charging infrastructure gaps as fleet electrification timelines compress.
Market Dynamics
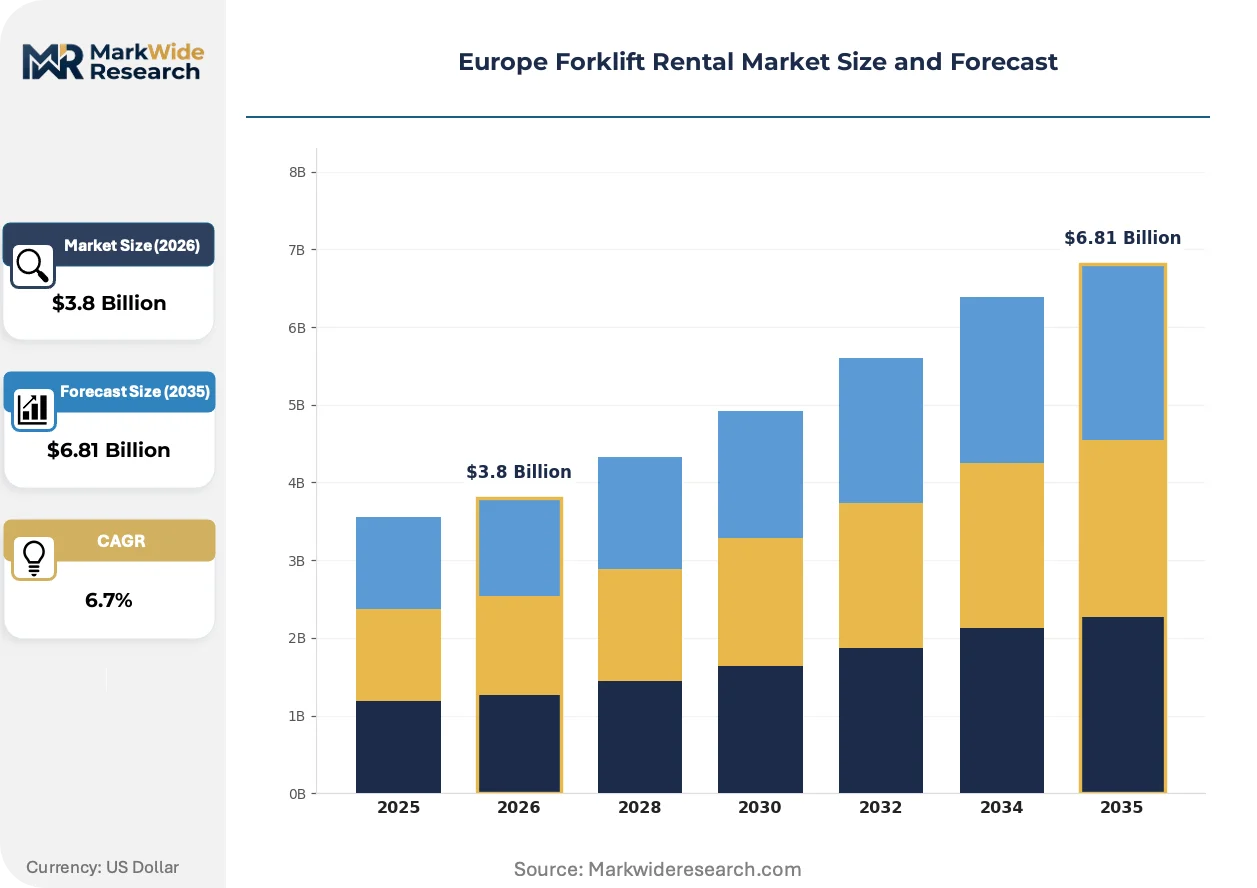
Fleet electrification mandates under the EU Green Deal are compressing diesel-to-electric transition timelines across European rental operators, forcing capital reallocation toward lithium-ion infrastructure and charging networks.
Growth Catalysts
- E-commerce fulfillment expansion:Third-party logistics platforms in Germany and Poland are scaling short-term equipment commitments to match seasonal demand volatility in parcel distribution centers.
- F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in material handling equipment are accelerating adoption of electric counterbalance trucks with sealed battery systems.
- Rhine-Ruhr logistics clustering:Dense warehousing corridors along the Dutch-German border generate concentrated demand for rapid-deployment rental fleets with same-day availability.
Market Restraints
- Lithium supply concentration:European rental operators depend on battery cell imports from East Asian suppliers, exposing fleet procurement to raw material price swings and shipping bottlenecks.
- CE marking complexity:Machinery Directive compliance for modified or attachments-equipped units extends certification timelines and restricts cross-border fleet mobility.
- Used equipment import competition:Refurbished diesel forklifts from Eastern European secondary markets undercut rental rates for short-term construction contracts.
Strategic Opportunities
- Nordic cold-storage specialization:Norway and Sweden's expanding frozen food logistics sector lacks sufficient low-temperature-rated electric forklift rental capacity.
- Equipment-as-a-service bundling:Integration of telematics-enabled fleet management with maintenance contracts creates recurring revenue streams distinct from hourly rental rates.
- CSRD disclosure requirements:Corporate Sustainability Reporting Directive obligations push large manufacturers toward rental models that transfer Scope 3 emissions accountability to providers.
Industry Challenges
- Certified technician scarcity:High-voltage battery service qualifications under German DGUV regulations outpace vocational training program output, extending equipment downtime.
- Legacy warehouse electrification:Older facilities in northern Italian manufacturing districts lack grid capacity for concurrent fast-charging of multiple electric units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Forklift Rental Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, LPG, Rough Terrain Industry Vertical: Construction, Warehousing, Manufacturing, Retail Operation Type: Indoor, Outdoor, Heavy-duty, Light-duty Customer Type: Contractors, Manufacturers, Distributors, Transportation |
| Companies Covered | Boels Rental, KION Group, Jungheinrich, Toyota Material Handling, Loxam, Ramirent, Kiloutou, Cramo, Zeppelin Rental, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Forklift Rental Market Trends and Innovations
Telematics integration and predictive maintenance algorithms are transforming how rental fleets are deployed, monitored, and monetized across European material handling operations.
Lithium-ion phosphate battery systems with opportunity-charging capability are digitizing fleet utilization tracking. Large retail distribution centers in France and the Netherlands are retrofitting existing electric fleets with cellular-connected battery management systems. Real-time state-of-charge monitoring is digitizing dispatch decisions, reducing unplanned downtime, and enabling dynamic pricing based on guaranteed availability windows.
The EU Green Deal's 2035 fleet decarbonization targets are mandating zero-emission equipment procurement in public-sector logistics contracts. National transposition of the Alternative Fuels Infrastructure Regulation requires member states to install charging infrastructure at major freight terminals. Cold-storage operators in Belgium and Denmark face the tightest compliance deadlines, accelerating replacement of propane-powered indoor units with fast-charge electric alternatives.
Flexible tenure structures are displacing fixed-term rental agreements in contract logistics. Pharmaceutical distributors and automotive tier-one suppliers now demand month-to-month extensions with embedded maintenance rather than annual commitments. This preference is most pronounced in the Iberian Peninsula, where seasonal export volatility drives demand for rapid fleet scaling without capital deployment.
Europe Forklift Rental Market Segmentation
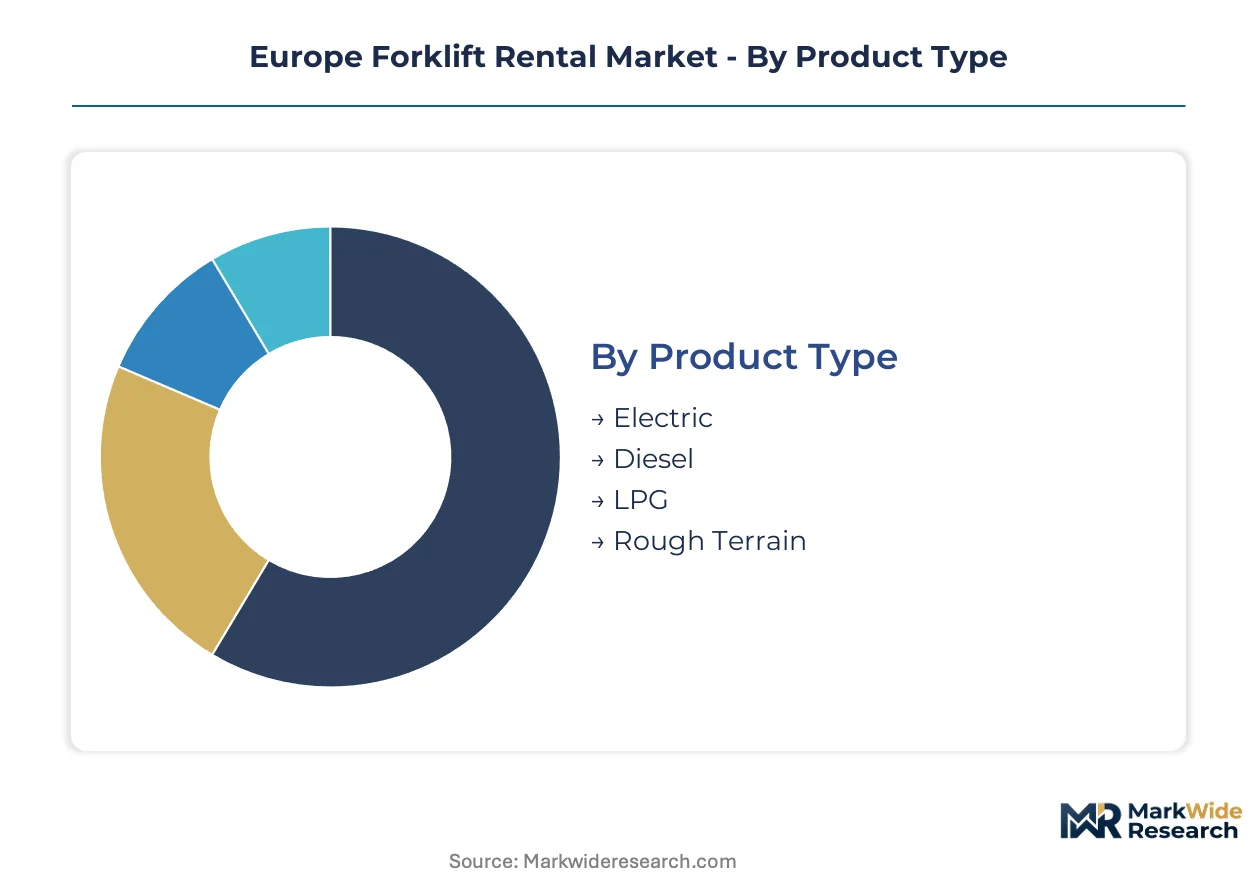
Forklift rental demand fragments across powertrain technologies, operational environments, and customer risk profiles. Each segmentation axis reveals distinct margin structures and fleet utilization patterns that shape provider strategy across European logistics corridors.
Product Type:
Powertrain selection dictates total cost of ownership, charging infrastructure requirements, and regulatory compliance timelines across rental contracts.
- Electric:Lithium-ion battery systems with opportunity-charging capability dominate indoor warehousing contracts in the Netherlands and northern Germany. Rhine-Ruhr distribution centers mandate zero-emission fleets under municipal clean air zones, compressing diesel replacement schedules.
- Diesel:Internal combustion units with particulate filtration retain dominance in outdoor construction sites across Poland and Romania where grid infrastructure remains insufficient for heavy-duty electric alternatives. Rental rates for these units face pressure from secondary market imports.
- LPG:Propane-powered counterbalance trucks serve cold-storage facilities in Belgium and Denmark requiring consistent indoor performance without battery thermal management complexity.
- Rough Terrain:All-wheel-drive diesel units with pneumatic tires access unpaved construction sites in Iberian infrastructure projects and Nordic wind farm developments.
The dominant share belongs to Electric, while Rough Terrain is closing the gap fastest.
Industry Vertical:
End-use concentration determines contract duration, maintenance bundling preferences, and seasonal volatility exposure.
- Warehousing:Third-party logistics platforms in Germany and Poland drive short-term rental commitments with embedded telematics for real-time fleet visibility. E-commerce fulfillment peaks generate 40-60% utilization swings.
- Construction:General contractors in France and Spain demand flexible tenure structures with rapid equipment substitution rights as project phases shift. Price sensitivity peaks in residential building segments.
- Manufacturing:Automotive tier-one suppliers in northern Italian districts negotiate multi-year agreements with guaranteed uptime clauses and preventive maintenance schedules.
- Retail:Hypermarket distribution networks in France and Benelux favor seasonal scaling without capital deployment, particularly for holiday inventory surges.
Warehousing commands the largest revenue pool, though Construction exhibits the steepest expansion trajectory.
Operation Type:
Environmental exposure and load intensity determine equipment specification, operator certification requirements, and insurance cost structures.
- Indoor:Emission-free electric units with cushion tires operate in racked warehouse environments across Dutch-German logistics corridors. CE marking under the Machinery Directive governs safety compliance.
- Outdoor:Pneumatic-tired diesel and LPG units serve lumber yards, building material suppliers, and port terminals in Baltic Sea freight hubs. Weather exposure accelerates maintenance frequency.
- Heavy-duty:Counterbalance trucks exceeding 8-tonne capacity handle steel coils and containerized cargo at Antwerp and Rotterdam port terminals. Specialized attachment compatibility expands addressable tasks.
- Light-duty:Pallet jacks and stackers below 2-tonne capacity support retail backrooms and small parcel sorting facilities with minimal operator training requirements.
Indoor operations generate the highest rental margins, while Heavy-duty contracts are gaining share fastest in port logistics.
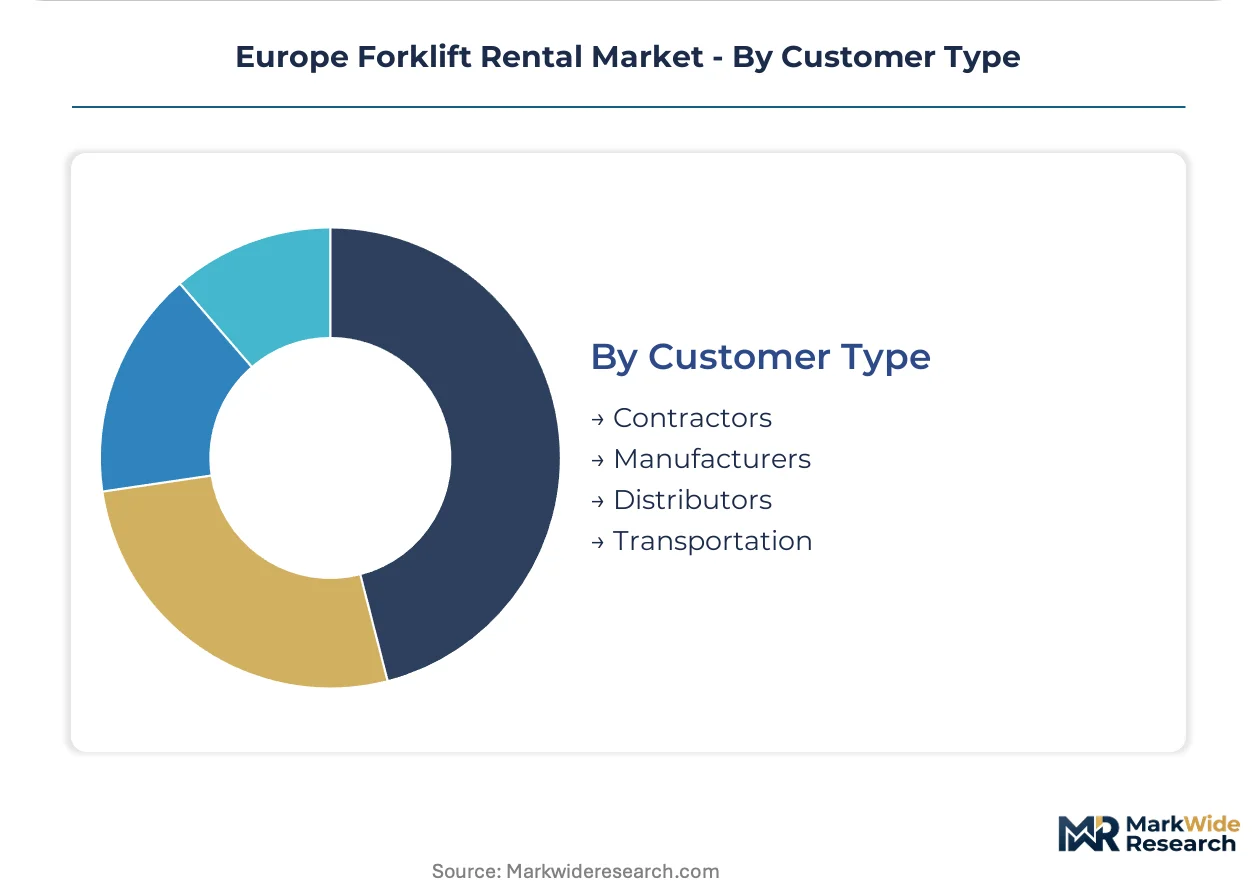
Customer Type:
Risk tolerance and capital constraints differentiate procurement behavior across account segments.
- Contractors:Price-sensitive construction firms in Southern Europe prioritize daily rental flexibility over maintenance bundling, accepting higher per-hour rates for zero commitment.
- Manufacturers:Capital-constrained SMEs in Czech and Slovak automotive supply chains favor operating leases that preserve credit lines for core production equipment.
- Distributors:Wholesale food and beverage networks in Iberia require rapid fleet scaling for export seasonality without warehousing asset ownership.
- Transportation:Freight forwarders at multimodal terminals in Milan and Hamburg integrate short-term rentals with cross-docking operations during peak shipping windows.
Manufacturers represent the most stable revenue base, while Transportation customers are expanding contract volume most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal fleet electrification mandates and national carbon targets are redistributing rental demand across European logistics corridors. Member states with dense warehousing infrastructure and stringent clean air regulations are accelerating diesel-to-electric transitions faster than peripheral markets.
Germany
Rhine-Ruhr distribution centers and Hamburg port terminals drive concentrated demand for rapid-deployment electric fleets. DGUV regulations governing high-voltage battery service technician qualifications create compliance barriers favoring established rental operators with certified training programs. Bavarian automotive supply chains around Munich and Ingolstadt negotiate multi-year agreements with guaranteed uptime clauses.
France
Third-party logistics platforms in Île-de-France and Auvergne-Rhône-Alpes scale short-term commitments to match e-commerce seasonal volatility. ANSM workplace safety frameworks and national carbon reduction targets accelerate LPG-to-electric transitions in cold-storage facilities. Loxam's dense branch networks anchor coverage across Paris Basin logistics corridors with same-day equipment availability.
Netherlands
Randstad warehousing clusters generate Europe's highest per-capita forklift rental density as Rotterdam-Antwerp port logistics integrate with inland distribution. Municipal clean air zones in Amsterdam and Utrecht mandate zero-emission fleets for indoor contracts. Dutch-German border logistics corridors concentrate demand for telematics-enabled fleet management with real-time utilization tracking.
Poland
E-commerce fulfillment center construction around Warsaw and Wrocław drives steepest regional growth in short-term equipment commitments. EU cohesion fund infrastructure investments expand Baltic Sea port connectivity, generating construction sector demand for rough terrain diesel units. Secondary market refurbished equipment imports from Eastern Europe undercut rental rates for price-sensitive contractors.
Italy
Northern manufacturing districts in Lombardy and Emilia-Romagna anchor multi-year rental agreements with preventive maintenance bundling. Legacy warehouse grid capacity constraints in Milan-Turin industrial corridors slow electric fleet charging infrastructure deployment. Automotive tier-one suppliers negotiate flexible tenure structures accommodating export seasonality volatility.
Europe Forklift Rental Market Competitive Landscape
On the supply side, the industry is consolidating around equipment manufacturers with captive rental operations and independent specialists with dense service networks. KION Group and Jungheinrich exemplify integrated manufacturing-rental models leveraging lithium-ion technology leadership. Independent branch-network operators compete through rapid response capabilities and cold-storage specialization. Dominant competitive moves include fleet electrification capital reallocation and telematics-enabled service bundling that locks in recurring revenue streams.
Among Germany-based integrated manufacturers, KION Group and Jungheinrich occupy positions anchoring technology-forward fleet supply through manufacturing scale and captive rental distribution. Netherlands-based Toyota Material Handling represents the multinational industrial equipment archetype with broad European coverage. France-based Loxam and Boels Rental exemplify independent rental specialists competing through geographic density and Nordic cold-storage equipment specialization respectively. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Boels Rental |
| KION Group |
| Jungheinrich |
| Toyota Material Handling |
| Loxam |
| Ramirent |
| Kiloutou |
| Cramo |
| Zeppelin Rental |
| Others |
Pricing and Supply Chain Analysis
East Asian lithium-ion cell production concentration in China, South Korea, and Japan anchors battery procurement costs for European rental fleets, compressing margin pools at the fleet-operator tier while amplifying pricing power for integrated manufacturers with captive cell supply agreements.
Pricing Analysis
Volume-discount tiering structures stratify rental rates across contract duration bands, with multi-year manufacturing agreements commanding standard-tier pricing while spot-market construction rentals sit at premium hourly rates. CE marking certification under the Machinery Directive and DGUV technician compliance separate premium providers from economy-tier competitors. Cost compression in short-term diesel segments is intensifying because refurbished equipment imports from Eastern European secondary markets undercut standardized rate cards. Contractors in Southern Europe exhibit the highest price sensitivity, whereas automotive tier-one suppliers in northern Italy negotiate least-sensitive bundled maintenance contracts.
Supply Chain Analysis
Supplier-financing facilities extended by KION Group and Jungheinrich allow mid-tier rental operators to defer lithium-ion fleet procurement payments across 36-48 month windows. Battery cell supply draws from Chinese, South Korean, and Japanese manufacturing hubs, while chassis fabrication rests on German and Czech steel processing. Single-source vulnerability concentrates in cathode active material supply from Chinese refiners. Distribution runs through dense branch networks in France and Benelux, with same-day availability clauses locking in contract logistics accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service models and telematics-enabled fleet management are reshaping competitive positioning, forcing incumbents to defend against substitute threats from third-party logistics platforms that internalize material handling capacity.
For Market Incumbents: Entrench lithium-ion technology leadership through backward integration into battery management system design, insulating margin pools from cell price volatility. Capture DGUV-certified technician capacity in Germany before vocational training bottlenecks widen. Cold-storage specialization in Nordic markets offers defensive positioning against generalist competitors.
For New Entrants and Emerging Players: Build out telematics-enabled fleet management platforms targeting pharmaceutical distributors and automotive tier-one suppliers demanding month-to-month flexibility. Iberian Peninsula contract logistics presents the most penetrable geography, with seasonal export volatility driving demand for rapid scaling without capital deployment. Partner with third-party logistics platforms for embedded equipment provisioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lithium-ion fleet transitions as charging infrastructure deployment absorbs incremental capital. Acquisition targets should display dense service networks in Rhine-Ruhr or Randstad corridors with certified maintenance capabilities. Watch battery supply contract renegotiation cycles as inflection indicators for fleet procurement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Fleet Transition | DGUV certification requirements favor established operators with technician training infrastructure. |
| Telematics Platform Integration | Real-time state-of-charge monitoring enables dynamic pricing based on guaranteed availability windows. |
| Cold-Storage Equipment Specialization | Nordic frozen food logistics expansion outpaces low-temperature-rated electric forklift rental capacity. |
| Charging Infrastructure Partnership | Alternative Fuels Infrastructure Regulation mandates member state installation at major freight terminals. |
| Equipment-as-a-Service Bundling | CSRD disclosure obligations push manufacturers toward rental models transferring Scope 3 emissions accountability. |
Research Methodology
A standing panel of fleet operations directors, maintenance service managers, OEM procurement specialists, and third-party logistics platform executives provided ongoing calibration throughout primary fieldwork. Secondary validation drew from EU customs trade data, DGUV certification records, F-Gas Regulation implementation reports, and national workplace safety framework filings. Bottom-up equipment deployment tracking across Rhine-Ruhr, Randstad, and northern Italian corridors triangulated against top-down rental revenue estimates from national industrial equipment associations.
Scenario-bracketing framed projections across electrification mandate timelines and battery supply disruption events. Segmentation dimensions modeled include powertrain technology, contract duration structure, end-use vertical, and regional regulatory cluster. CAGRs derived from logistic curve fitting to historical fleet replacement cycles, with electric penetration rates and charging infrastructure buildout pace as industry-specific forecast inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery cell manufacturers into downstream rental operations would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Baler Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Trenchers Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Global Seam Welding Machine Market