
 Wheeled Excavators Market | 2026-2036
Wheeled Excavators Market Size, Share, and Industry Trends Forecast 2026-2036
Wheeled Excavators Market Analysis
The split between premium long-reach configurations and commodity-standard wheeled units is realigning procurement patterns across European rental fleets. Caterpillar leverages its North American dealer density to sustain parts availability premiums for high-hour contractors. Liebherr anchors German-speaking markets through in-house axle manufacturing that reduces lead times for municipal buyers. Komatsu competes on telematics integration, offering fleet managers real-time fuel diagnostics that differentiate its hybrid line from conventional diesel alternatives.
Wheeled excavators are self-propelled digging machines mounted on rubber-tired undercarriages, typically offering travel speeds of 20–35 km/h and swing radii under 2 meters for road-legal mobility between job sites without low-loader transport. Standard excavators dominate rental fleet depreciation schedules due to their versatility across material handling and site preparation tasks, while compact excavators capture margin pools in urban demolition where weight-restricted bridge access determines contract eligibility. Hydraulic technology still occupies the majority of installed base hours, though hybrid systems are displacing pure diesel in emission-controlled zones where idle-time fuel burn drives operating cost divergence.
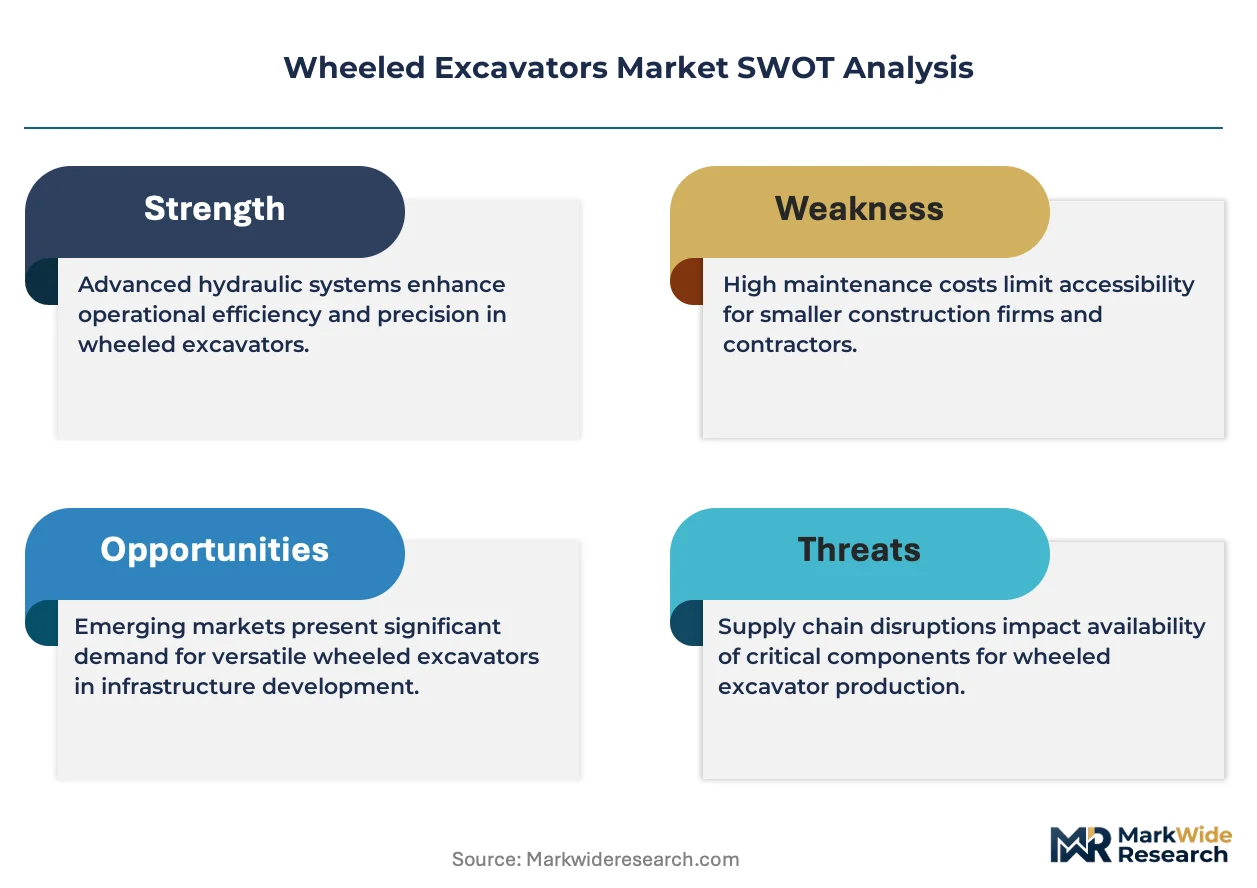
EPA Tier 4 Final and EU Stage V emissions frameworks force engine after-treatment upgrades that add base machine cost and compress residual values for pre-compliant fleets. OSHA excavation safety standards and ISO 6165 dimensional classifications shape manufacturer design constraints for North American and European market access. Stakeholders must monitor battery-electric prototype field trials and weigh total cost of ownership against diesel-hybrid retention as charging infrastructure matures for construction site deployment.
Market Dynamics
EU Stage V emissions mandates are compressing residual values for pre-compliant wheeled excavator fleets while accelerating hybrid and electric prototype deployment across municipal procurement channels in Germany and France.
Growth Catalysts
- Urban Utility Corridor Expansion:Compact wheeled excavator demand concentrates in France and Italy where narrow street access and weight-restricted bridge infrastructure determine municipal contract eligibility. Paris and Milan utility networks specify sub-10-ton units for gas line maintenance.
- EU Stage V Compliance Deadlines:German municipal road maintenance fleets face mandated fleet turnover schedules that expand wheeled excavator procurement windows through 2027. KBA enforcement timelines accelerate replacement cycles for diesel units lacking after-treatment systems.
- Road-Legal Mobility Economics:Rubber-tired undercarriages eliminate low-loader transport costs between dispersed job sites, reducing total project logistics expenditure for German and Austrian road contractors operating across multiple cantons.
Market Restraints
- After-Treatment Cost Burden:EU Stage V engine upgrades add base machine cost without proportional productivity gains, compressing rental fleet return thresholds for standard-configuration units.
- Axle Supply Concentration:In-house axle manufacturing at Liebherr and limited third-party suppliers create lead time vulnerability for municipal buyers requiring customized track widths.
- Battery-Electric Range Limitation:Current lithium-ion energy density constrains continuous operation to 4-6 hours for compact wheeled excavators, disqualifying electric units from full-shift highway maintenance contracts.
Strategic Opportunities
- Italian Urban Demolition Gap:Rome and Naples historic center renovation projects create demand for sub-8-ton wheeled excavators with zero-tail-swing configurations that navigate medieval street grids.
- Telematics-Enabled Fleet Management:Real-time fuel diagnostics and idle-time monitoring integrate with municipal ERP systems, offering differentiated service contracts for hybrid unit operators.
- Swiss Alpine Infrastructure Program:Gotthard Base Tunnel maintenance corridors and mountain pass road networks specify high-altitude-rated wheeled excavators with enhanced cooling systems.
Industry Challenges
- Hybrid Technician Scarcity:Municipal fleet maintenance departments lack certified personnel for high-voltage powertrain diagnostics, forcing reliance on manufacturer service networks with 48-72 hour response windows.
- ISO 6165 Certification Timeline:Dimensional classification revisions delay new compact model introductions by 8-12 months, misaligning product launches with municipal budget cycles.
- Legacy Fleet Integration:Telematics retrofit compatibility gaps prevent unified fleet monitoring across mixed-vintage wheeled excavator pools, fragmenting maintenance scheduling efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheeled Excavators Market |
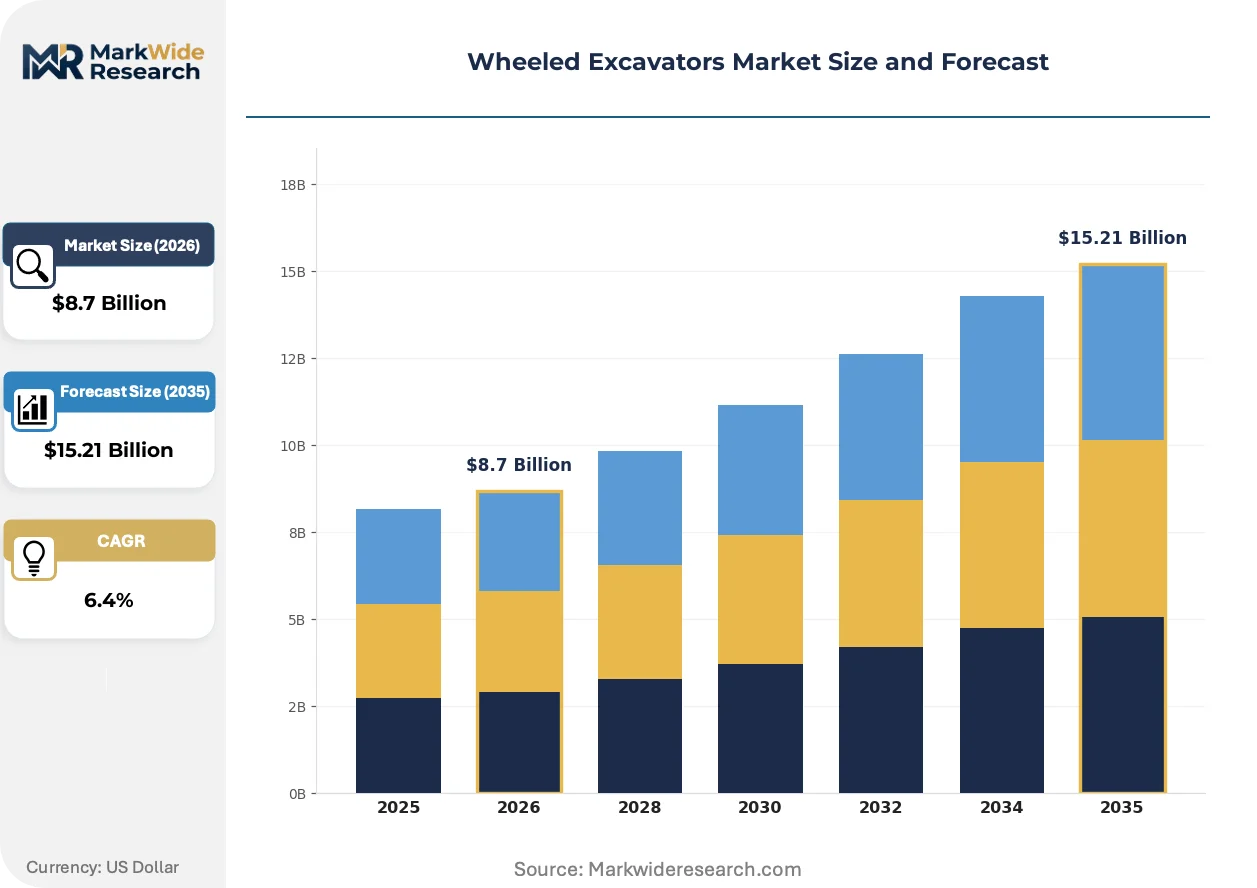
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Excavators, Compact Excavators, High-Capacity Excavators, Mini Excavators End User: Construction, Mining, Infrastructure, Landscaping Technology: Hydraulic, Electric, Hybrid, Diesel Application: Ditching, Demolition, Material Handling, Site Preparation |
| Companies Covered | Hitachi Construction Machinery, Liebherr, Caterpillar, Sany Heavy Industry, CASE Construction Equipment, Volvo Construction Equipment, JCB, XCMG, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheeled Excavators Market Emerging Trajectories
Powertrain electrification and connected fleet management systems are reconfiguring competitive differentiation in wheeled excavator procurement, with regulatory pressure and operational data monetization driving parallel investment streams.
Hybrid diesel-electric architectures are electrifying compact wheeled excavator offerings for urban emission-controlled zones. German municipal buyers in Stuttgart and Munich specify these units for inner-ring road maintenance where idle-time fuel burn previously dominated operating cost structures. The technology is compressing pure diesel residual values in EU Stage V enforcement regions while opening premium pricing tiers for compliant configurations.
EU Stage V emissions frameworks are forcing engine after-treatment upgrades that add base machine cost without performance enhancement. Rental fleet operators in France face compressed depreciation schedules as pre-compliant units lose eligibility for public sector contracts. Compact wheeled excavator segments respond fastest, with French and Italian urban utilities mandating compliant units for new procurement.
Rental fleet operators are unbundling after-sales service contracts from equipment lease agreements, creating standalone maintenance revenue pools. Independent service providers in Bavaria and Baden-Württemberg now compete directly with manufacturer-authorized networks for hydraulic system overhaul contracts. This shift concentrates in Germany where municipal fleet scale justifies dedicated maintenance infrastructure investment.
Wheeled Excavators Market Segmentation
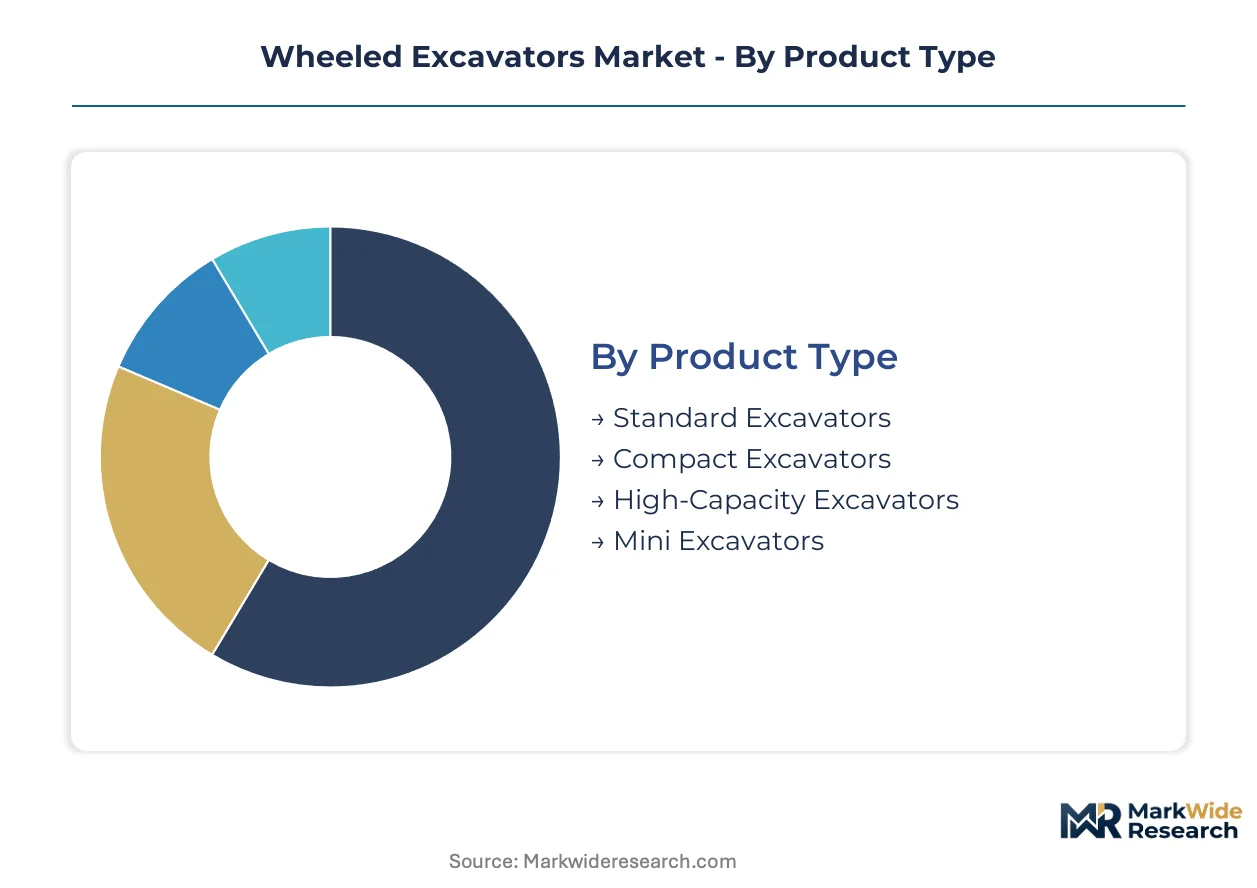
Segmentation in wheeled excavators reveals how capital deployment, regulatory exposure, and job-site constraints reshape procurement priorities across municipal fleets and private contractors. Equipment buyers balance upfront acquisition costs against residual value risk, fuel economics, and contract eligibility requirements.
Product Type:
Capital intensity varies sharply across product tiers, with high-capacity units demanding the largest upfront outlays while compact configurations minimize fleet depreciation exposure.
- Standard Excavators:These machines dominate rental fleet depreciation schedules through versatility across material handling and site preparation tasks. German and Austrian road contractors favor standard units for multi-canton operations where road-legal mobility eliminates low-loader transport costs between dispersed job sites.
- Compact Excavators:Sub-10-ton configurations concentrate demand in France and Italy where narrow street access and weight-restricted bridge infrastructure determine municipal contract eligibility. Paris and Milan utility networks specify these units for gas line maintenance in dense urban corridors.
- High-Capacity Excavators:Heavy-duty units require the steepest capital commitment and face compressed procurement windows as EU Stage V after-treatment costs disproportionately impact larger engine displacements.
- Mini Excavators:Sub-6-ton machines serve historic center renovation projects in Rome and Naples where medieval street grids demand zero-tail-swing maneuverability.
Standard excavators absorb the bulk of installed capacity; compact excavators are expanding most quickly.
End User:
Application-specific duty cycles determine technology selection and maintenance scheduling intensity across customer segments.
- Construction:General contractors prioritize versatile standard configurations that transition between foundation work and material handling without attachment changeover delays.
- Mining:Surface extraction operations in Germany and France specify high-capacity wheeled units for overburden removal where rubber-tired mobility reduces haul road maintenance.
- Infrastructure:Municipal road maintenance fleets in Germany face mandated EU Stage V turnover schedules that expand wheeled excavator procurement windows through 2027.
- Landscaping:Compact and mini excavators serve urban green space maintenance where weight restrictions protect sensitive turf and irrigation infrastructure.
Infrastructure commands the largest share of new unit volume; construction maintains the densest installed base hours.
Technology:
Powertrain selection increasingly reflects regulatory enforcement geography rather than pure operating economics.
- Hydraulic:Conventional systems still occupy the majority of installed base hours though hybrid architectures are displacing pure hydraulic in emission-controlled zones where idle-time fuel burn drives operating cost divergence.
- Hybrid:Diesel-electric configurations command premium pricing in Stuttgart and Munich where municipal buyers specify inner-ring road maintenance units. Komatsu competes on telematics integration offering fleet managers real-time fuel diagnostics that differentiate its hybrid line from conventional alternatives.
- Electric:Battery-powered prototypes face 4-6 hour range constraints that disqualify compact units from full-shift highway maintenance contracts until charging infrastructure matures.
- Diesel:Pure diesel configurations face compressed residual values in EU Stage V enforcement regions as pre-compliant units lose eligibility for public sector contracts.
Hydraulic technology retains the deepest installed base; hybrid systems are climbing the fastest.
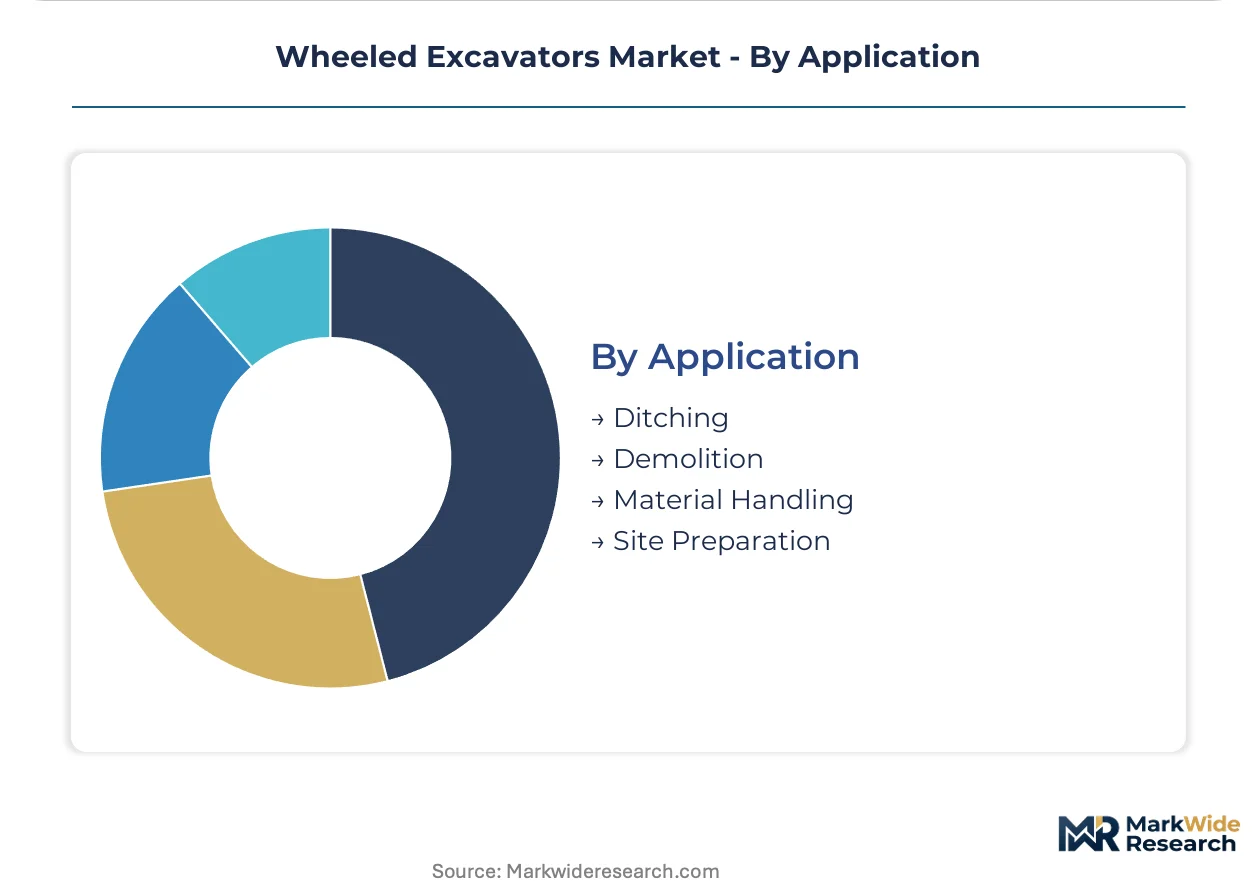
Application:
Job-site mobility requirements and material density dictate undercarriage specification and attachment configuration.
- Material Handling:Grapple and clamshell attachments dominate recycling yard and port operations where rubber-tired mobility enables rapid repositioning between stockpiles.
- Demolition:Urban teardown projects in Italian historic centers require sub-8-ton wheeled excavators with specialized boom geometry for selective deconstruction.
- Ditching:Slope-finishing attachments serve German agricultural drainage maintenance where road-legal travel between rural parcels justifies wheeled configuration over tracked alternatives.
- Site Preparation:Grading and leveling tasks concentrate in French commercial development corridors where standard excavators balance productivity with transport logistics efficiency.
Material handling generates the highest utilization hours; demolition is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European wheeled excavator procurement momentum, with municipal fleets in Baden-Württemberg accelerating EU Stage V compliant unit acquisition ahead of KBA enforcement deadlines.
Germany
Bavarian road maintenance contractors drive demand for rubber-tired configurations that eliminate low-loader transport costs across multi-canton operations. KBA enforcement timelines compress residual values for pre-compliant diesel fleets through 2027. Munich municipal procurement specifies hybrid units for inner-ring road maintenance corridors.
France
Paris utility networks mandate sub-10-ton compact excavators for gas line maintenance in dense urban corridors with weight-restricted bridge access. ANSM oversight of equipment certification aligns with EU Stage V implementation schedules. Île-de-France rental fleets face compressed depreciation schedules as non-compliant units lose public sector contract eligibility.
Italy
Rome and Naples historic center renovation projects create demand for sub-8-ton zero-tail-swing configurations navigating medieval street grids. Municipal procurement concentrates in Lombardy and Lazio where urban demolition contracts specify maneuverable equipment. Milan utility corridors drive compact excavator specification for narrow access maintenance.
Switzerland
Gotthard Base Tunnel maintenance corridors and Alpine mountain pass networks specify high-altitude-rated wheeled excavators with enhanced cooling systems. Swissmedic-equipment safety standards shape certification requirements for municipal fleet acquisition. Zurich municipal buyers prioritize road-legal mobility for dispersed canton operations.
United Kingdom
London congestion charge zones and ultra-low emission districts accelerate hybrid and electric prototype field trials among municipal contractors. HSE excavation safety standards align with ISO 6165 dimensional classifications for market access. Midlands rental fleets absorb standard configuration units for versatile material handling deployment.
Wheeled Excavators Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the wheeled excavator landscape, with integrated manufacturers controlling axle and hydraulic system supply against specialized assemblers sourcing third-party components. The vendor base stratifies into three tiers: premium European brands commanding municipal procurement premiums, Asian scale producers capturing rental fleet volume, and regional specialists serving narrow-application niches. Dominant competitive moves include backward integration into critical component manufacturing and telematics-enabled service contract unbundling from equipment lease agreements.
Among Japanese heavy machinery conglomerates, Hitachi Construction Machinery and Komatsu occupy positions exemplifying integrated powertrain and telematics development archetypes. Liebherr anchors German-speaking markets through in-house axle manufacturing capabilities that reduce municipal procurement lead times. Caterpillar leverages North American dealer density to sustain parts availability premiums for high-hour contractor segments. These three represent distinct strategic postures: Japanese technology integration, German component control, and American distribution scale.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Liebherr |
| Caterpillar |
| Sany Heavy Industry |
| CASE Construction Equipment |
| Volvo Construction Equipment |
| JCB |
| XCMG |
| Komatsu |
| Others |
Supply Flow & Price Mechanics
Certified hydraulic technician concentration in Baden-Württemberg and Bavaria widens labor-cost spreads between premium service-bundled configurations and bare-equipment procurement tiers, compressing margins for rental fleets lacking in-house maintenance infrastructure.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for municipal fleet operators in Stuttgart and Munich, where EU Stage V compliance certification and telematics integration command premium positioning against standard diesel alternatives. Price differentiation rests on after-treatment system certification grade and real-time diagnostic capability rather than base machine specifications. Cost compression in rental fleet depreciation schedules intensifies as pre-compliant units lose public sector contract eligibility. Municipal buyers demonstrate lowest price sensitivity due to mandated turnover schedules, while independent contractors in French commercial development corridors exhibit highest sensitivity to transport logistics efficiency.
Supply Chain Analysis
Refurbished axle and hydraulic component flows from German municipal fleet turnover programs feed secondary markets in Poland and Czech Republic, extending equipment lifecycle economics. Manufacturing concentration centers on Germany, Japan, and China for complete machine assembly, with axle systems drawing from captive production at Liebherr and specialized suppliers in Austria. Steel plate and high-pressure hydraulic hose assemblies constitute critical input dependencies. Single-source vulnerability concentrates in emission-certified engine supply from Tier 1 powertrain specialists. Distribution runs through manufacturer-authorized dealer networks for municipal procurement, while independent rental fleet operators source via direct OEM contracts and secondary equipment auctions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Stage V emissions mandates construct a cost-of-compliance moat that favors incumbents with certified after-treatment integration capabilities and compresses entry economics for capital-constrained assemblers.
For Market Incumbents: Deploy telematics-enabled service contract unbundling to capture standalone maintenance revenue pools from municipal fleet operators in Germany and France. Deepen backward integration into axle and hydraulic system manufacturing to reduce procurement lead times for customized track width specifications. Battery-electric prototype field trials from Komatsu and Hitachi Construction Machinery threaten hybrid line margins if charging infrastructure matures faster than projected. For New Entrants and Emerging Players: Enter via Italian urban demolition gap for sub-8-ton zero-tail-swing configurations serving Rome and Naples historic center renovation contracts. Swiss Alpine infrastructure maintenance corridors for high-altitude-rated units with enhanced cooling systems offer secondary penetration point. Direct municipal procurement bypassing rental fleet intermediaries provides lowest-friction go-to-market channel for compliant configurations. For Investors and Strategic Acquirers: Re-rating potential sits with component-integrated specialists given EU Stage V certification timeline compression and residual value volatility for pure assembly operations. Long-term viability favors manufacturers with captive axle production and telematics platform development capabilities. Monitor KBA enforcement acceleration and battery-electric range extension breakthroughs as inflection indicators for hybrid retention versus electric transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Axle Manufacturing | Liebherr's in-house production reduces municipal procurement lead times for customized specifications. |
| Telematics Platform Development | Komatsu's real-time fuel diagnostics differentiate hybrid offerings from conventional diesel alternatives. |
| EU Stage V Certification Investment | Engine after-treatment upgrades preserve public sector contract eligibility for German municipal fleets. |
| Service Contract Unbundling | Independent Bavarian providers now compete for hydraulic overhaul contracts outside manufacturer networks. |
| Battery-Electric Prototype Field Trials | Range-constrained compact units target Stuttgart and Munich inner-ring road maintenance corridors. |
Methodological Framework
Independent corroboration across municipal fleet maintenance directors, OEM procurement teams, rental fleet operators, and hydraulic system service providers underwrites the qualitative findings in this study. Primary interviews with equipment specification engineers and aftermarket service heads combined with secondary validation from KBA enforcement documentation, EU Stage V certification registries, and customs trade data for German and French equipment imports. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction across the analysis window.
Comparable-period anchoring to pre-EU Stage V enforcement baselines establishes the forecast framework for hybrid and electric displacement trajectories. Segmentation dimensions include product type tier, end-use application, powertrain technology, and municipal versus private procurement channel. CAGRs derive from equipment replacement cycle modeling and regulatory compliance deadline alignment. Forecast inputs incorporate KBA enforcement timeline acceleration scenarios and battery energy density improvement curves for compact wheeled excavator applications.
Revisions become necessary when KBA enforcement timelines accelerate, battery-electric range specifications exceed current lithium-ion constraints, or ISO 6165 dimensional classification revisions delay new model introductions. Forecasts reflect assumptions regarding charging infrastructure deployment pace and hybrid technician certification program expansion. Practitioners should monitor municipal budget cycle alignment with product launch schedules and telematics retrofit compatibility across mixed-vintage fleet pools for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Utility Locator Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Truck Mounted Knuckle Boom Cranes Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Grader Blades Market
Construction Equipment
Europe Welding Equipment Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Backhoes Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Automatic Clay Brick Making Machine Market