
 Sandblasting Machines Market | 2026-2036
Sandblasting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Sandblasting Machines Market Analysis
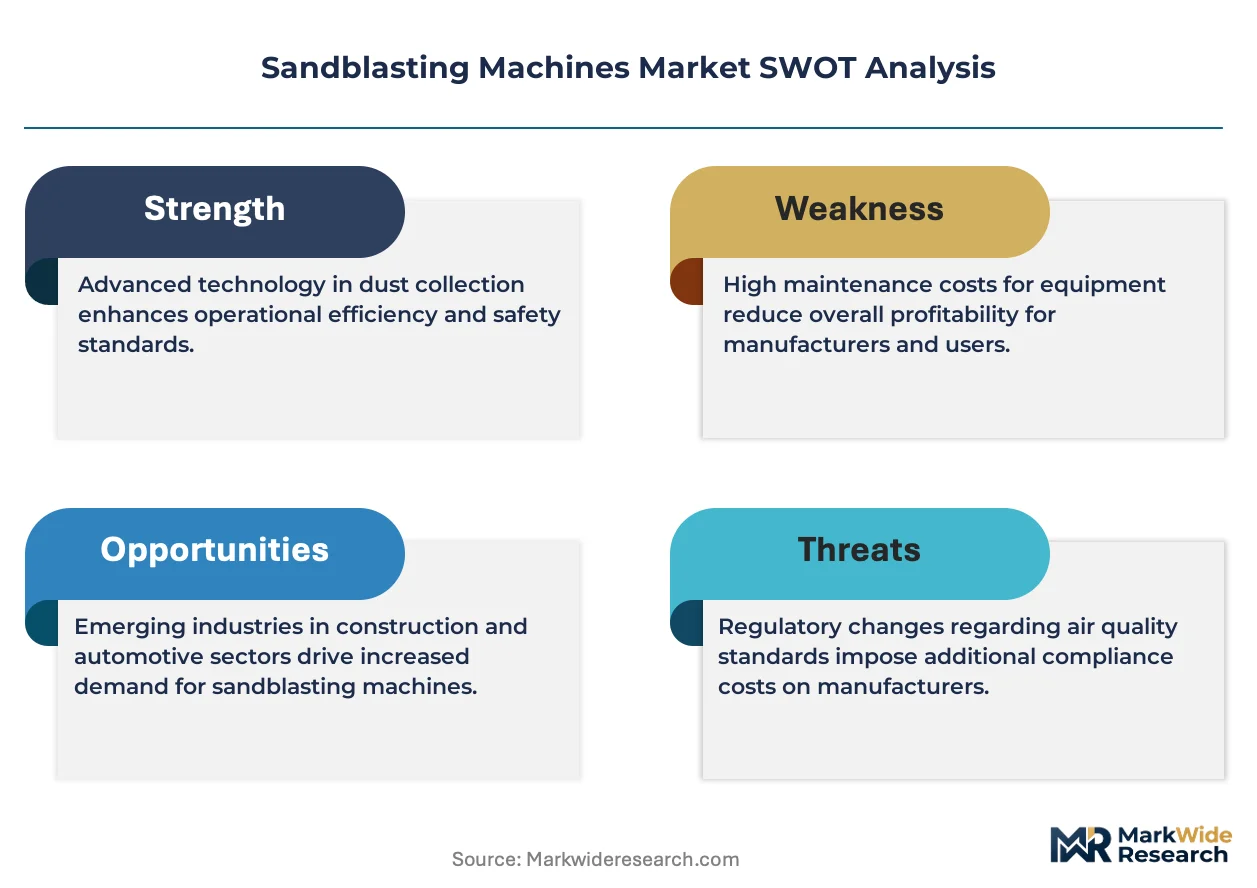
Aluminum oxide is broadening its displacement of silica sand across surface preparation workflows due to recyclability and lower respirable dust generation. Clemco Industries Corp leverages its captive supply of blast pot components to sustain margin control across North American distribution channels. Graco Inc anchors its position through R&D intensity in automated blasting controls for manufacturing lines. Empire Abrasive Equipment Company specializes in custom-engineered blast room systems for aerospace end users.
Sandblasting machines are mechanical systems that propel abrasive media through pressurized air or centrifugal force to clean, etch, or prepare material surfaces, typically operating at nozzle pressures between 60 and 120 PSI depending on substrate hardness and finish specification. Their primary industrial purpose centers on removing corrosion, coatings, and contaminants to achieve specified surface profiles for coating adhesion or aesthetic restoration. Pressure machines dominate installed base value due to their throughput advantage in heavy metal fabrication, while wet blasting systems represent the fastest-expanding technology segment as environmental compliance tightens around airborne particulate emissions. Portable units command premium pricing in marine maintenance applications where on-site mobility outweighs cycle-time efficiency.
OSHA enforces permissible exposure limits for respirable crystalline silica that directly constrain dry blasting operations and drive capital expenditure toward ventilated blast rooms and wet systems. EPA Clean Air Act provisions on particulate matter emissions shape equipment specifications for outdoor blasting contractors, particularly in non-attainment zones. The EU F-Gas Regulation and REACH restrictions on hazardous abrasives compound compliance complexity for multinational equipment suppliers. Stakeholders must weigh abrasive media substitution timelines against retrofit costs when planning fleet renewal cycles.
Market Dynamics
OSHA's respirable crystalline silica exposure limits are compressing the operational envelope for dry blasting contractors while simultaneously expanding the addressable market for wet systems and ventilated blast rooms across metal fabrication and automotive restoration end uses.
Growth Catalysts
- Wet blasting retrofits:EPA Clean Air Act particulate matter provisions in US non-attainment zones are mandating emission-compliant equipment upgrades among outdoor blasting contractors.
- Electric vehicle battery tray refurbishment:Automotive restoration workshops in Germany's Stuttgart supplier corridor are expanding equipment fleets to handle corrosion removal from aluminum EV undercarriages.
- Aluminum oxide substitution:REACH restrictions on hazardous abrasives are accelerating media displacement timelines as fabricators seek lower-toxicity, recyclable alternatives to silica sand.
Market Restraints
- Abrasive media cost volatility:Aluminum oxide and garnet prices fluctuate with bauxite mining output and shipping lane disruptions, compressing contractor margins on fixed-price restoration contracts.
- Blast pot component supply concentration:North American distribution channels depend on limited domestic foundry capacity for pressure vessel castings, creating lead time vulnerability.
- Technical limitation in precision finishing:Centrifugal wheel systems cannot achieve the surface profile tolerances required for aerospace turbine blade preparation, capping penetration in that segment.
Strategic Opportunities
- Underpenetrated marine maintenance:Shipyard operators in Singapore and UAE ports represent untapped demand for portable wet blasting units that enable on-site hull preparation without dry-docking delays.
- EU F-Gas Regulation compliance services:Equipment suppliers can bundle refrigerant recovery systems with blast room installations to capture cross-selling value from MRO contractors facing 2027 phase-down deadlines.
- Automated blasting control convergence:Integration of machine vision with robotic nozzle positioning enables lights-out operation in automotive OEM paint lines, reducing labor dependency.
Industry Challenges
- Certified operator scarcity:OSHA 29 CFR 1910.94 ventilation standard compliance requires documented training programs that few vocational schools currently offer, constraining workforce expansion.
- Legacy system integration friction:Retrofitting automated media recovery and filtration into existing blast rooms demands structural modifications that extend project timelines and disrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandblasting Machines Market |
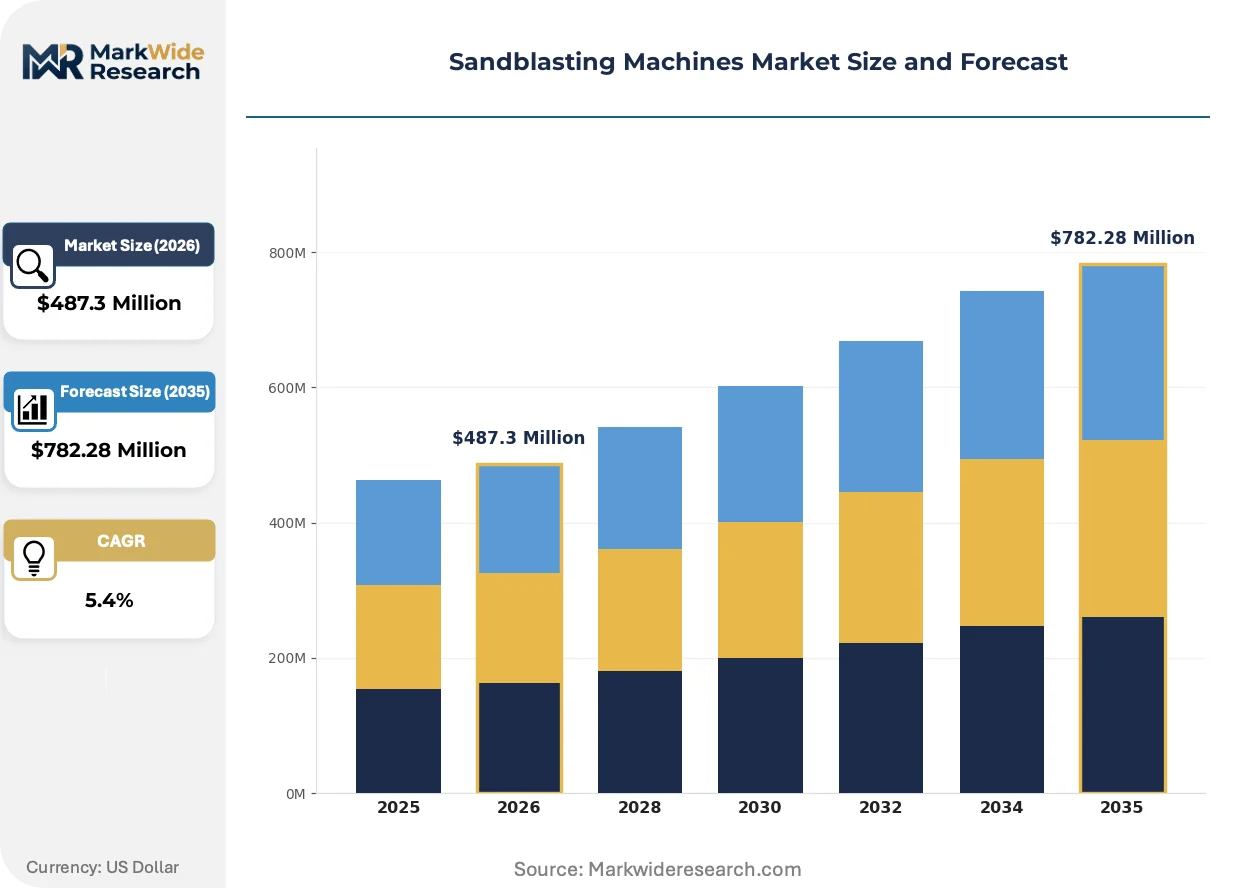
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $782.28 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suction Machines, Pressure Machines, Blast Rooms, Portable Units Application: Automotive Restoration, Metal Fabrication, Surface Preparation, Cleaning End User: Manufacturing, Construction, Aerospace, Marine Technology: Wet Blasting, Dry Blasting, Micro Blasting, Automated Systems |
| Companies Covered | Clemco Industries Corp, Graco Inc, Empire Abrasive Equipment Company, Airblast B.V., Sinto Group, Axxiom Manufacturing, Burwell Technologies, Norton Sandblasting Equipment, Guyson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandblasting Machines Market Emerging Trajectories
Wet abrasive blasting is consolidating its position as the dominant technology trajectory while regulatory pressure and buyer procurement evolution reshape competitive requirements across equipment categories.
Closed-loop water reclamation systems are consolidating their role in heavy fabrication workflows by eliminating slurry disposal costs and enabling continuous operation in water-scarce regions. Shipyards in the US Gulf Coast and Mediterranean ports are adopting these systems fastest, driven by EPA and EU discharge permit constraints. The technology is consolidating vendor margins by shifting revenue from consumable media sales toward long-term filtration service contracts.
REACH authorization requirements for chromium VI compounds are forcing coating removal contractors toward vacuum-assisted wet blasting configurations that suppress hexavalent chromium dust generation. German automotive suppliers around Stuttgart face the tightest compliance timelines under ECHA sunset dates. Equipment specifications now routinely mandate HEPA filtration and real-time dust monitoring as standard rather than optional features.
Service-based contracting is displacing capital purchase models among mid-sized metal fabricators who prefer fixed-cost-per-part arrangements over equipment ownership. Blast room operators in France and Italy are unbundling maintenance and media supply from hardware sales, capturing recurring revenue streams. This shift is most visible in automotive tier-two supplier networks where balance sheet constraints favor operational expenditure treatment.
Sandblasting Machines Market Segmentation
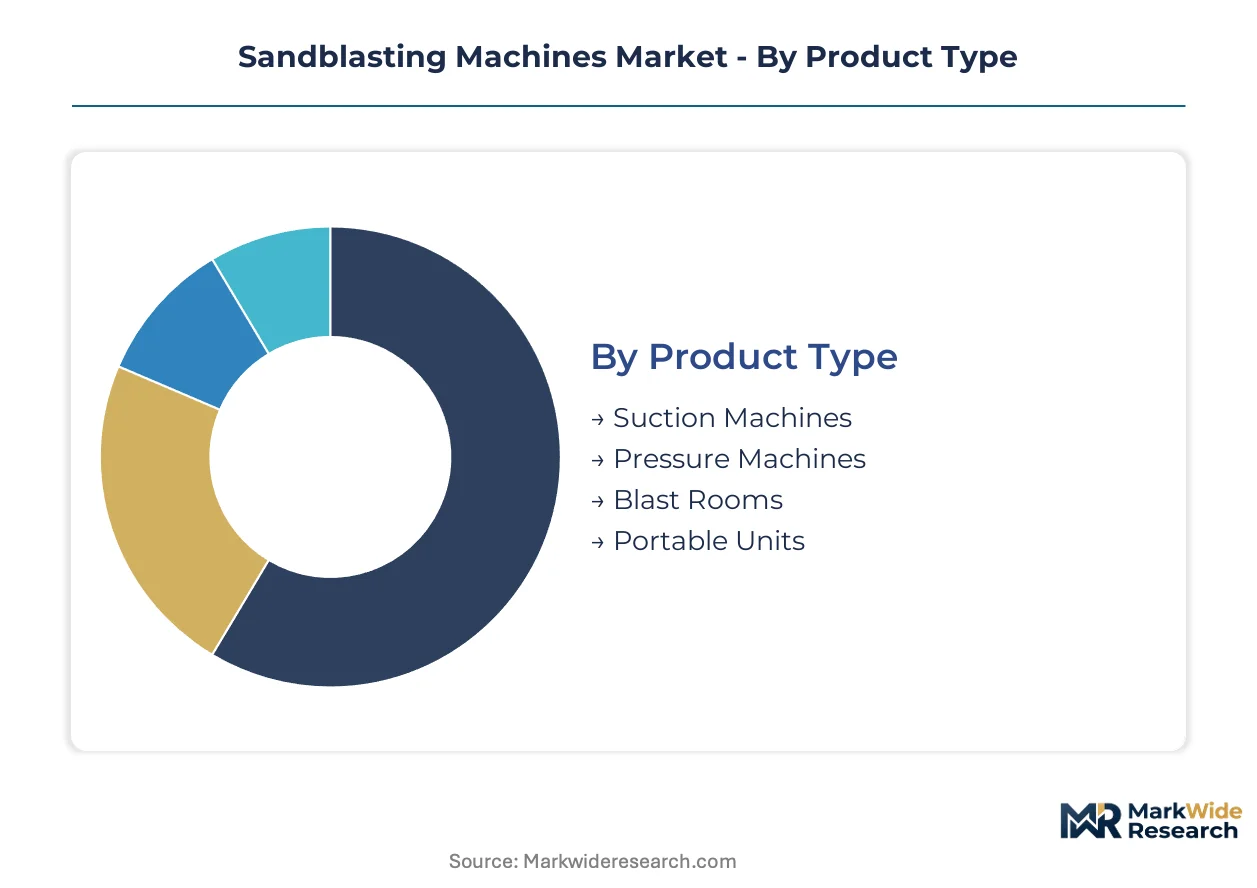
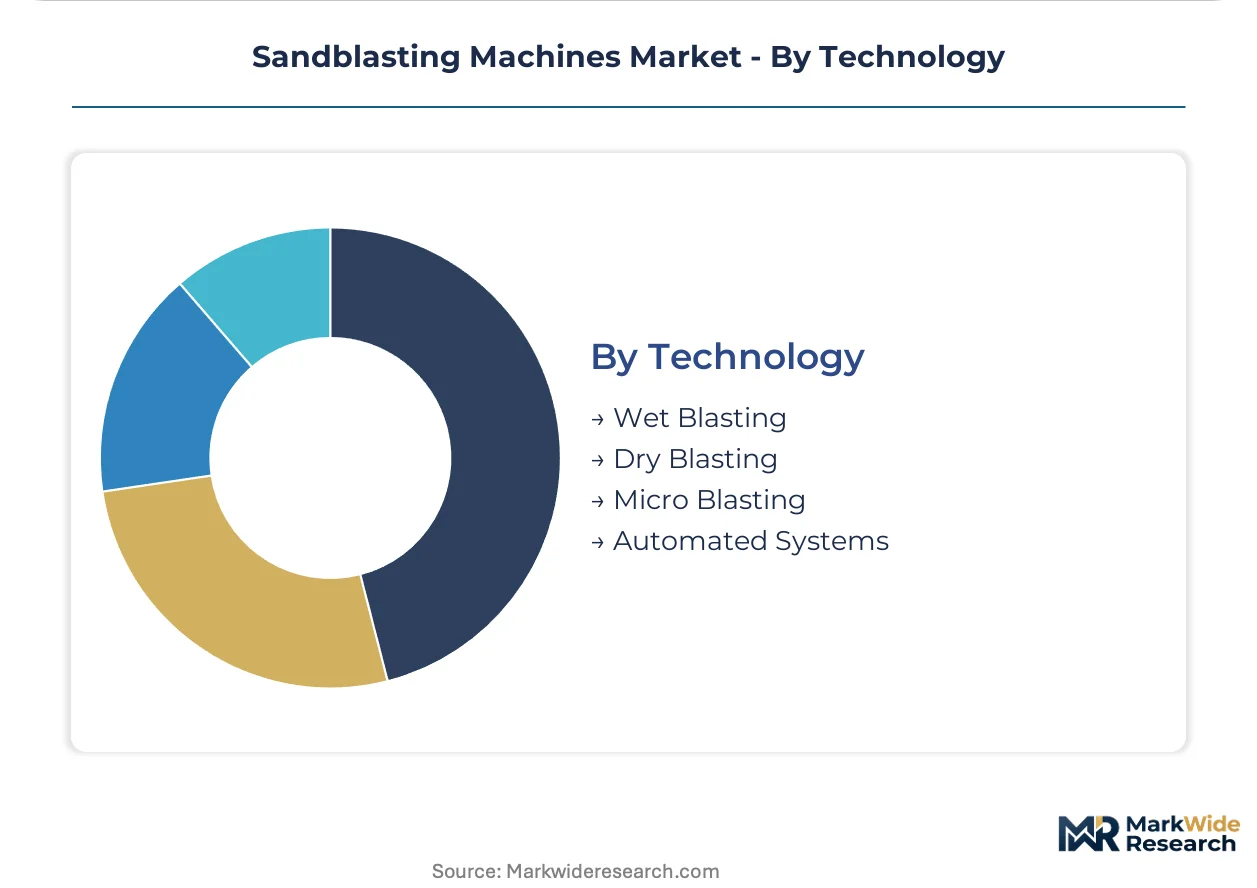
Segmentation reveals how capital intensity, regulatory exposure, and operational scale fragment demand across equipment categories. Buyers prioritize throughput efficiency in heavy fabrication while environmental compliance reshapes technology preferences.
Product Type:
Capital intensity varies sharply across this category, with blast rooms requiring structural enclosure investments that dwarf portable unit procurement costs.
- Pressure Machines:These systems operate at 60-120 PSI through pressurized blast pots, delivering abrasive media at velocities optimized for heavy corrosion removal on steel substrates. Metal fabrication contractors in Germany's Stuttgart corridor deploy pressure machines for EV battery tray refurbishment workflows. Pressure machines absorb the bulk of installed capacity; portable units are expanding most quickly.
- Blast Rooms:Enclosed systems integrate ventilation, media recovery, and dust collection for continuous operation in fixed facilities. OSHA silica exposure limits are accelerating wet blasting retrofits among US metal fabrication contractors who cannot achieve compliance with open-air configurations.
- Suction Machines:Venturi-based systems draw abrasive through induced airflow, suited for light-duty cleaning where substrate damage risk must be minimized.
- Portable Units:Mobile configurations trade cycle efficiency for on-site deployment flexibility, commanding premium pricing in marine maintenance applications.
Blast rooms dominate capital deployment; portable units capture the steepest expansion trajectory as shipyards prioritize mobility.
Application:
Regulatory stringency separates high-compliance surface preparation from price-sensitive cleaning contracts.
- Surface Preparation:Profile-achieving workflows for coating adhesion demand precise abrasive selection and nozzle control. REACH restrictions on hazardous abrasives are forcing German automotive suppliers toward aluminum oxide substitution timelines.
- Automotive Restoration:Corrosion removal and aesthetic refinishing for classic and electric vehicles requires substrate-specific pressure modulation. Workshops in Stuttgart's supplier corridor are expanding equipment fleets to handle aluminum EV undercarriage refurbishment.
- Metal Fabrication:Pre-coating treatment of structural steel and aluminum components for industrial equipment.
- Cleaning:General contaminant removal without profile specification, typically lowest-margin contract work.
Surface preparation commands the highest equipment specification; automotive restoration is climbing the fastest as EV fleet ages.
End User:
Volume concentration and margin structure diverge between capital-intensive manufacturing and project-based construction.
- Manufacturing:Continuous production lines integrate automated blasting for consistent throughput. EPA Clean Air Act provisions in US non-attainment zones are mandating emission-compliant equipment upgrades among OEM paint line operators.
- Aerospace:Precision finishing for turbine blades and airframe components demands tight surface profile tolerances that centrifugal wheel systems cannot achieve.
- Construction:Infrastructure and building restoration projects with seasonal demand patterns.
- Marine:Hull preparation and coating removal in shipyard environments.
Manufacturing holds the largest installed base; aerospace is gaining share fastest despite technical barriers.
Technology:
Environmental compliance timelines are compressing the operational window for legacy dry configurations.
- Wet Blasting:Water-abrasive slurry systems suppress respirable dust generation and enable continuous operation with closed-loop reclamation. Shipyards in US Gulf Coast and Mediterranean ports are adopting these systems fastest under EPA and EU discharge permit constraints.
- Automated Systems:Robotic nozzle positioning with machine vision enables lights-out operation in automotive OEM paint lines, reducing labor dependency.
- Dry Blasting:Conventional pressurized air systems facing operational constraints from OSHA respirable crystalline silica limits.
- Micro Blasting:Precision systems for delicate substrate treatment in electronics and medical device manufacturing.
Dry blasting retains the largest installed footprint; wet blasting is expanding most quickly as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg automotive supplier corridor concentrates wet blasting demand as Stuttgart-area workshops expand EV battery tray refurbishment capacity. Tax incentives for green manufacturing equipment accelerate capital deployment across the region's metal fabrication clusters.
United States
Gulf Coast shipyards drive portable wet blasting adoption for hull maintenance without dry-docking delays. EPA Clean Air Act particulate matter provisions in non-attainment zones mandate emission-compliant equipment upgrades. Houston-area contractors retrofit blast rooms with closed-loop reclamation to meet discharge permit constraints.
Germany
Stuttgart's automotive supplier corridor dominates EV undercarriage refurbishment equipment demand. ECHA REACH restrictions on hazardous abrasives force aluminum oxide substitution timelines. Baden-Württemberg fabricators deploy ventilated blast rooms to comply with hexavalent chromium dust suppression mandates.
China
Yangtze River Delta manufacturing hubs integrate automated blasting controls for automotive OEM paint lines. MEE discharge regulations tighten wastewater treatment requirements for wet blasting operations. Shanghai-area shipyards adopt portable units for on-site hull preparation in bonded port zones.
Japan
Kansai region precision manufacturers deploy micro-blasting systems for electronics substrate treatment. METI industrial efficiency standards promote media recovery system adoption. Osaka-area metal fabricators upgrade pressure machines for aerospace component surface preparation.
United Arab Emirates
Dubai Maritime City operators invest in mobile wet blasting fleets for vessel maintenance without dry-dock delays. MOHAP industrial safety guidelines align equipment specifications with EU-equivalent dust exposure limits. Jebel Ali port contractors command premium pricing for on-site deployment flexibility.
Sandblasting Machines Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive component supply sustaining margin control for integrated producers while pure-play equipment vendors compete on specification breadth. The installed base concentrates around pressure machine specialists with foundry-linked supply chains. Three archetypes dominate: vertically integrated blast pot manufacturers, automated controls developers, and custom-engineered blast room specialists. Competitive moves center on captive supply consolidation and R&D partnerships for machine vision integration.
Within the integrated manufacturing tier, Clemco Industries Corp and Graco Inc exemplify divergent strategic positions. Clemco's captive supply of blast pot components anchors its North American distribution footprint. Graco's R&D intensity in automated blasting controls occupies the manufacturing-line automation vector. Empire Abrasive Equipment Company represents the custom-engineered specialization archetype, with its focus on aerospace end-user requirements. These three patterns illustrate how technical differentiation and supply chain configuration separate sustainable margin positions from commodity pressure.
| Leading Market Players |
|---|
| Clemco Industries Corp |
| Graco Inc |
| Empire Abrasive Equipment Company |
| Airblast B.V. |
| Sinto Group |
| Axxiom Manufacturing |
| Burwell Technologies |
| Norton Sandblasting Equipment |
| Guyson Corporation |
| Others |
Supply Flow & Price Mechanics
Captive supply of blast pot components anchors pricing power for integrated manufacturers serving North American distribution channels, while outsourced foundry dependence leaves pure-play equipment vendors exposed to margin compression during aluminum oxide price volatility cycles.
Pricing Analysis
Volume-scale fabricators negotiate contract-based long-term equipment offtake with blast room specialists, while project-based restoration contractors face spot-market exposure to abrasive media cost swings. Price differentiation separates premium-tier automated systems with machine vision integration from standard pressure machines and economy portable units lacking reclamation features. Pricing pressure stems from bauxite mining output fluctuations that transmit through aluminum oxide supply contracts. Tier-two automotive suppliers exhibit highest price sensitivity due to balance sheet constraints favoring operational expenditure treatment, whereas aerospace end users prioritize specification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in domestic foundry operations across the United States and Germany limit pressure vessel casting output, extending lead times for blast pot components. Supply concentrates in China for steel fabrication and precision machining, in Germany for engineered blast room systems, and in the United States for portable unit assembly. Raw material dependencies center on bauxite-derived aluminum oxide, garnet abrasives, and high-grade steel alloys. Single-source vulnerability characterizes North American distribution channels dependent on limited domestic foundry capacity. Distribution runs through authorized dealer networks for capital equipment and direct procurement for consumable media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around equipment suppliers with captive component production as OSHA silica enforcement and REACH abrasive restrictions force undercapitalized competitors toward exit.
For Market Incumbents: Deploy machine vision integration as the priority lever to capture automotive OEM paint line automation demand and defend against emerging robotics specialists. Deepen backward integration into blast pot foundry operations to secure margin control against aluminum oxide price volatility. Expand ventilated blast room capacity in Germany's Stuttgart corridor to capture EV battery tray refurbishment demand growth. For New Entrants and Emerging Players: Digital-channel route through equipment-as-a-service platforms offers lowest-friction entry for mid-sized fabricators seeking fixed-cost-per-part arrangements. Target marine maintenance operators in Singapore and UAE ports with portable wet blasting rental fleets. Prioritize closed-loop water reclamation bundling to differentiate against capital-sale incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial equipment conglomerates seeking surface preparation technology adjacencies. Five-to-ten-year viability favors suppliers with automated controls development capability and regulatory compliance service bundling. Acquisition target archetype: custom-engineered blast room specialists with aerospace certification relationships. Signal to watch: EPA non-attainment zone expansion accelerating wet blasting retrofit mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive blast pot casting capacity insulates margin control against North American supply concentration. |
| Machine Vision System Development | Robotic nozzle positioning enables lights-out operation for automotive OEM paint line contracts. |
| Wet Blasting Retrofit Service Bundling | EPA Clean Air Act compliance upgrades capture recurring revenue from metal fabrication contractors. |
| Closed-Loop Reclamation Technology Licensing | Water-scarce region adaptation opens shipyard demand in Mediterranean and Gulf Coast ports. |
| Equipment-as-a-Service Platform Launch | Fixed-cost-per-part contracting aligns procurement with balance-sheet-constrained tier-two automotive suppliers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving blast room operators, OEM procurement teams, aftermarket service heads, and plant engineers across metal fabrication and automotive restoration facilities. Bottom-up equipment shipment data triangulated against top-down abrasive media consumption patterns derived from EPA discharge permit filings and ECHA REACH registration databases.
Data-stream reconciliation across product type, application workflow, technology configuration, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories weighted by capital intensity differentials between blast room and portable unit categories. Forecast inputs incorporated OSHA enforcement intensity indices and EU F-Gas Regulation phase-down timelines.
The model holds under steady regulatory enforcement intensity and stable bauxite supply conditions; deviation in aluminum oxide price volatility or accelerated EPA non-attainment designations would shift equipment mix assumptions. Forecasts reflect documented assumptions regarding wet blasting adoption curves and abrasive media substitution timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Broaching Machine Market
Construction Equipment
GCC Crane Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Hydraulic Spreader Market