
 Drilling Jumbo Market | 2026-2036
Drilling Jumbo Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Jumbo Market Foresight
The EU Green Deal's carbon-border adjustment mechanism is restructuring procurement criteria for underground excavation equipment across European tunneling contracts. Epiroc leverages its automation software stack to sustain premium positioning in electrified drill rigs. Sandvik Construction anchors its competitive stance through integrated rock-tools-to-drill-systems coverage. Furukawa competes aggressively on hydraulic reliability in Southeast Asian hard-rock conditions.
A drilling jumbo is a mobile, multi-boom rock-drilling machine mounted on a tracked or wheeled carrier, typically equipped with two to four drill arms that position hydraulic or pneumatic drifters against tunnel faces with precision boom articulation. Its primary industrial purpose is to create blast-hole patterns in underground mining and tunnel construction, where drilling accuracy directly determines fragmentation quality, advance rates, and support-cycle efficiency. Jumbo drills occupy the largest product share due to universal deployment across metal and non-metal underground operations, while automation technology is expanding fastest as remote-operation protocols reduce face exposure and labor intensity. Electromechanical systems are gaining ground in geotechnical services applications where emission restrictions at urban tunnel portals limit diesel deployment.
The US Mine Safety and Health Administration enforces respirable dust and noise exposure limits that compel fleet upgrades toward enclosed-cabin, automated drilling platforms. China's Ministry of Emergency Management and GB standards for non-coal underground mines are accelerating domestic replacement of legacy pneumatic rigs with hydraulics and electromechanical alternatives. Australia's state-based mining regulators mandate collision-avoidance and remote-operation readiness for new underground equipment purchases. Stakeholders must weigh the capital intensity of full automation against phased electromechanical retrofits as compliance timelines compress and labor availability tightens in mature mining districts.
Market Dynamics
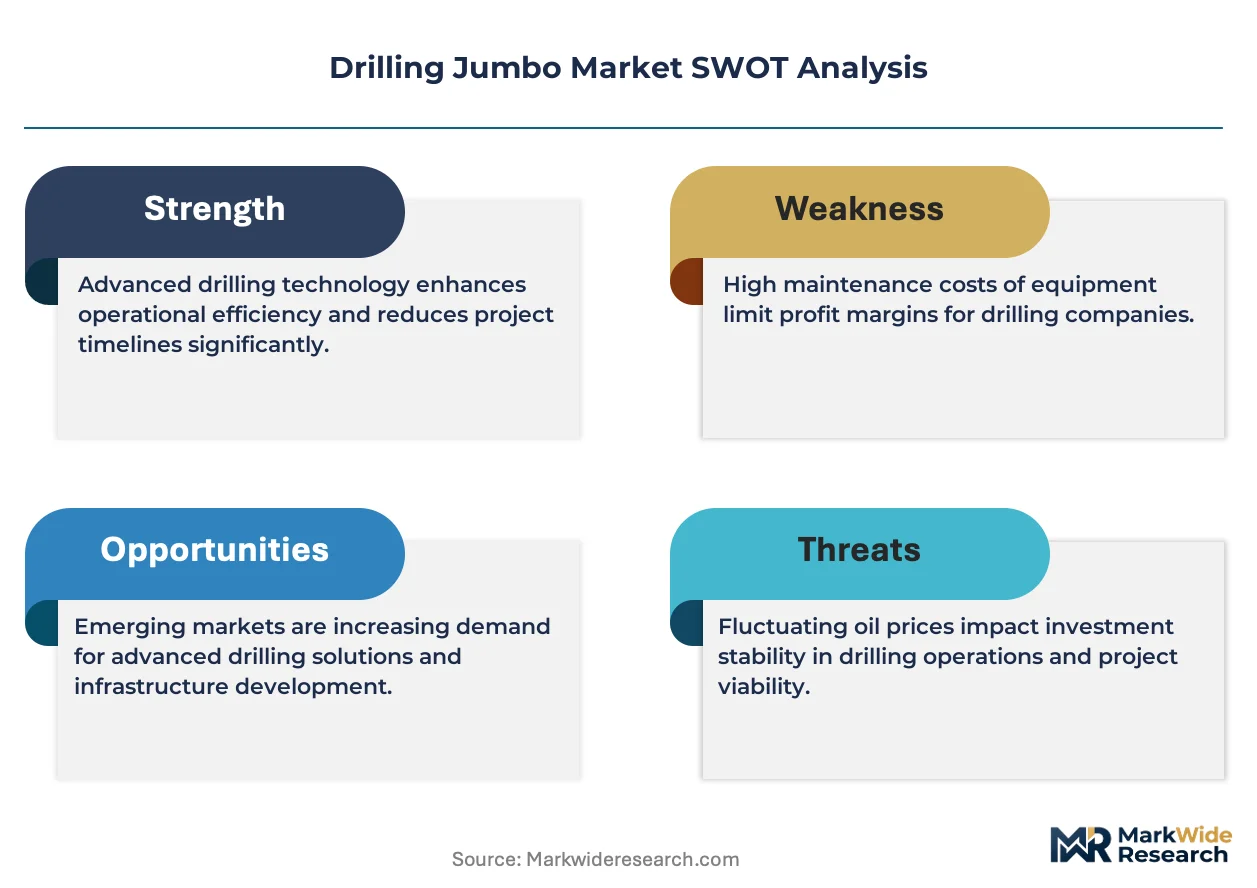
Automation mandates from Australia's state mining regulators are compressing replacement cycles for legacy pneumatic rigs, forcing capital allocation toward electromechanical and remote-capable platforms before full depreciation.
Growth Catalysts
- ISO 19434 safety framework:Australia's national resources regulator embeds collision-avoidance and remote-operation protocols into equipment certification, accelerating fleet turnover in Western Australia's Pilbara iron ore belt.
- Electromechanical drilling systems:Urban tunnel portals in European metropolitan zones face emission restrictions that ban diesel deployment, opening procurement pathways for battery-electric jumbos in geotechnical services.
- Respirable dust enforcement:The US Mine Safety and Health Administration tightens exposure limits for silica and noise, compelling underground operators toward enclosed-cabin platforms with integrated dust suppression.
Market Restraints
- Battery cell supply concentration:Electromechanical rig production depends on lithium-ion cell supply chains concentrated in East Asian manufacturing zones, exposing fleet operators to input cost volatility and delivery uncertainty.
- Technical limitation in thermal management:Underground hard-rock conditions above 40°C degrade battery performance and cycle life, constraining electrification in deep South African platinum and Chilean copper operations.
- Substitution threat from raise-boring:Vertical shaft development increasingly deploys raise-boring machines for ventilation and ore-pass construction, displacing jumbo-drilled blast patterns in specific mine development phases.
Strategic Opportunities
- Underpenetrated geography:Kazakhstan's expanding copper and uranium operations maintain legacy Soviet-era pneumatic fleets, creating replacement demand as the national mining ministry modernizes safety standards.
- Regulatory tailwind:China's dual carbon goals and Ministry of Emergency Management directives accelerate domestic substitution of pneumatic rigs with hydraulics and electromechanical alternatives in non-coal underground mines.
- Technology convergence:Integration of real-time rock-mass characterization sensors with automated drill control is automating blast-pattern optimization, reducing face exposure and improving fragmentation consistency.
Industry Challenges
- Automation engineering talent scarcity:Remote-operation readiness requires mechatronics specialists capable of integrating drill control systems with mine-wide digital infrastructure, a skill set concentrated at OEM engineering centers.
- Capex intensity of full automation:Retrofit pathways for collision-avoidance and tele-remote capability demand substantial modification of existing hydraulic architectures, complicating fleet-upgrade economics for mid-tier contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Jumbo Market |
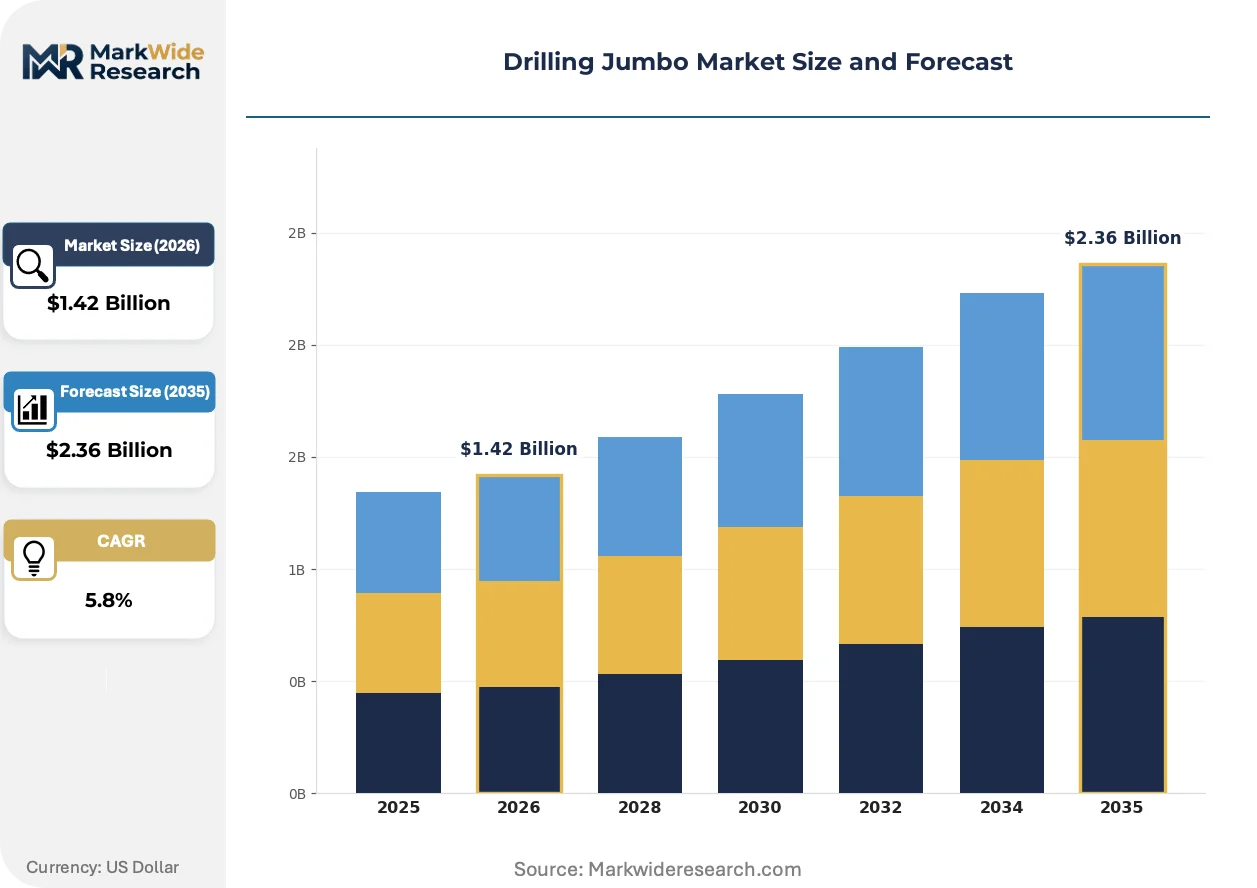
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Miners, Raise Bores, Jumbo Drills, Rock Drills End User: Mining Companies, Construction Firms, Oil & Gas, Geotechnical Services Technology: Electromechanical, Hydraulics, Pneumatics, Automation Application: Underground Mining, Tunnel Construction, Water Well Drilling, Geothermal |
| Companies Covered | Epiroc, Sandvik Construction, Furukawa, Komatsu Mining Corp, J.H. Fletcher, XCMG, Jiangxi Siton Machinery Manufacturing Co., Ltd, RDH Mining Equipment, Kaishan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Jumbo Market Shifts & Advancements
Electrification and autonomous operation are converging to redefine equipment specifications, with regulatory pressure accelerating technology deployment faster than traditional replacement cycles would permit.
Tele-remote drill control systems are automating face-exposure reduction in Australian and Canadian underground operations. Tier-one miners deploy these platforms to remove operators from blast zones during drilling cycles. The technology is automating labor reallocation toward supervisory roles while compressing shift-change downtime.
The EU Green Deal's carbon-border adjustment mechanism is restructuring procurement criteria for European tunneling contracts. Equipment suppliers must now document embodied carbon and operational emissions across machine lifecycles. Hydraulics-dominated fleets in Alpine infrastructure projects face accelerated replacement pressure.
Service unbundling is fragmenting traditional OEM aftermarket relationships. Mining contractors in Chile's copper districts now source rock-tool consumables, maintenance labor, and automation software through separate channels. This pattern is most visible in mature mining regions where technical competency for self-maintenance has developed.
Drilling Jumbo Market Segmentation
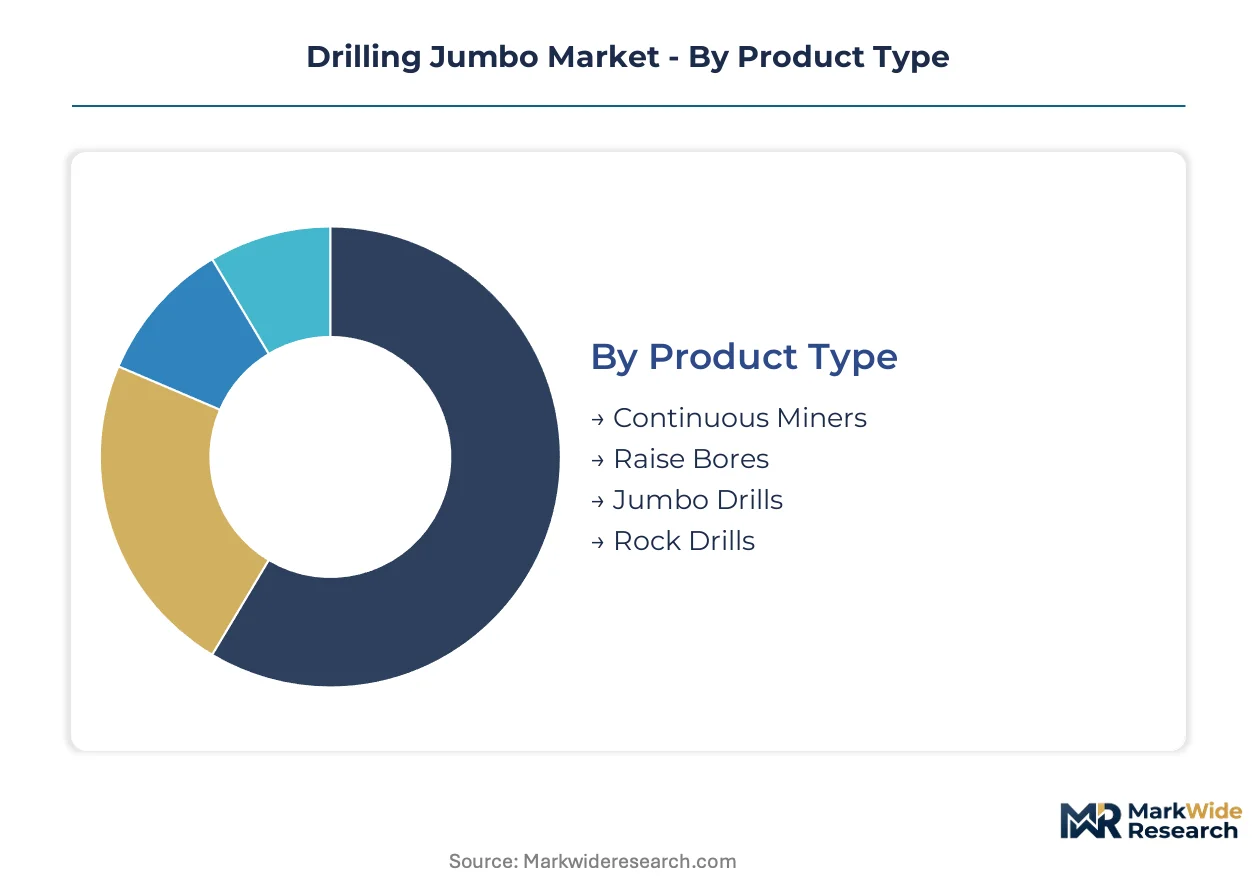
Drilling jumbo procurement decisions cluster around automation readiness and powertrain architecture, with regulatory mandates compressing traditional replacement cycles. Capital allocation now prioritizes platforms capable of remote operation and emission compliance over legacy hydraulic specifications.
Product Type:
Jumbo drills command the highest upfront capital outlay among underground drilling platforms due to multi-boom complexity and precision articulation systems.
- Jumbo Drills:Mobile multi-boom machines mount two to four drill arms on tracked carriers, positioning hydraulic or electromechanical drifters against tunnel faces with precision boom articulation. Western Australia's Pilbara iron ore belt and Queensland's metallurgical coal regions concentrate demand as Australia's state mining regulators mandate collision-avoidance and remote-operation readiness for new underground equipment purchases.
- Raise Bores:Vertical shaft development systems deploy full-face cutting heads for ventilation and ore-pass construction, eliminating blast-hole patterns in specific mine development phases. The technology is displacing jumbo-drilled raises in deep South African platinum and Chilean copper operations where thermal management constraints already limit battery-electric alternatives.
- Continuous Miners:Mechanized cutting platforms for soft-rock coal seams integrate gathering arms and conveyor systems for continuous material extraction.
- Rock Drills:Single-boom or handheld pneumatic and hydraulic units serve secondary breaking and narrow-vein applications with lower capital thresholds.
Jumbo drills absorb the bulk of installed capacity; raise bores are expanding most quickly in vertical shaft applications.
End User:
Customer procurement scale determines automation tier access, with tier-one miners deploying full tele-remote capability while mid-tier contractors phase upgrades.
- Mining Companies:Underground metal and coal operators drive specification standards through fleet renewal programs. Australia's national resources regulator embeds ISO 19434 collision-avoidance protocols into equipment certification, forcing capital allocation toward electromechanical and remote-capable platforms before full depreciation of legacy pneumatic rigs.
- Construction Firms:Urban tunneling contractors face emission restrictions at metropolitan portals that ban diesel deployment, opening procurement pathways for battery-electric jumbos in European infrastructure projects.
- Oil & Gas:Exploration and production operators deploy specialized rigs for well completion and workover applications in hydrocarbon basins.
- Geotechnical Services:Site investigation and ground-stabilization contractors operate smaller fleets with intermittent utilization patterns.
Mining companies dominate absolute unit demand; construction firms are climbing the fastest as urban emission restrictions tighten.
Technology:
Powertrain selection now hinges on thermal environment and automation integration rather than pure mechanical reliability.
- Automation:Tele-remote drill control systems remove operators from blast zones during drilling cycles, automating labor reallocation toward supervisory roles. Tier-one miners in Australian and Canadian underground operations deploy these platforms to compress shift-change downtime while reducing face exposure.
- Electromechanical:Battery-electric architectures eliminate diesel particulate and noise emissions at tunnel portals, though underground hard-rock conditions above 40°C degrade lithium-ion performance and cycle life.
- Hydraulics:Fluid-power systems maintain dominance in high-torque, high-impact drilling sequences where instantaneous power density exceeds electric motor capabilities.
- Pneumatics:Compressed-air systems persist in legacy fleets and developing markets with established compressor infrastructure and lower capital barriers.
Hydraulics retains the largest installed base; automation is gaining share fastest as regulatory mandates compress replacement cycles.
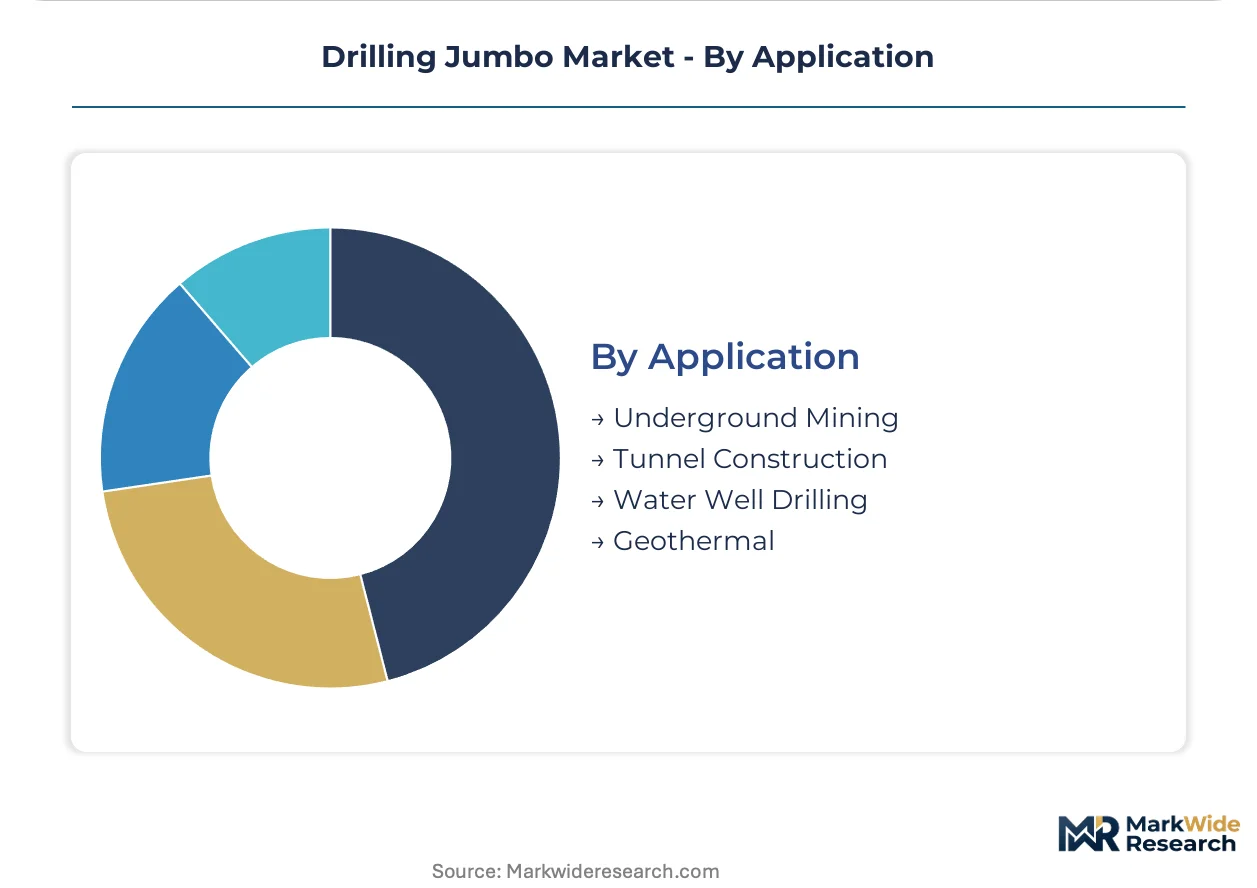
Application:
Operating environment dictates boom configuration, dust suppression integration, and ground support sequencing.
- Underground Mining:Hard-rock metal and coal operations require multi-boom patterns for blast-hole drilling with immediate ground support installation. The US Mine Safety and Health Administration enforces respirable dust and noise exposure limits that compel fleet upgrades toward enclosed-cabin, automated drilling platforms.
- Tunnel Construction:Urban infrastructure projects face EU Green Deal carbon-border adjustment mechanisms that restructure procurement criteria toward documented embodied carbon and operational emissions across machine lifecycles.
- Water Well Drilling:Potable and irrigation water access drives demand for rotary and percussion rigs in arid and semi-arid regions.
- Geothermal:Renewable energy development deploys specialized high-temperature drilling systems for reservoir access and heat exchange installation.
Underground mining commands the deepest equipment penetration; tunnel construction shows the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara iron ore belt concentrates fleet renewal activity as automation mandates from Australia's state mining regulators compress replacement cycles for legacy pneumatic rigs.
Australia
Underground mining operations in Queensland's metallurgical coal regions and Western Australia's Pilbara belt are expanding fleet renewals. The national resources regulator embeds ISO 19434 collision-avoidance protocols into equipment certification, forcing capital allocation toward electromechanical platforms. Perth-based procurement teams coordinate specification standards across BHP and Rio Tinto operations.
United States
Underground metal operators in Nevada's gold districts and Arizona's copper corridors face compressed compliance timelines. The Mine Safety and Health Administration enforces respirable dust and noise exposure limits that compel fleet upgrades toward enclosed-cabin, automated drilling platforms. Denver and Salt Lake City serve as equipment specification hubs for Rocky Mountain operations.
China
Domestic non-coal underground mines are accelerating substitution of legacy pneumatic rigs with hydraulics and electromechanical alternatives. The Ministry of Emergency Management and GB standards for mine safety are driving replacement demand. Shanxi Province's coal machinery clusters and Jiangxi's hard-rock mining districts concentrate procurement activity.
Chile
Deep copper operations in the Atacama Desert face thermal management constraints that limit battery-electric alternatives. Service unbundling is fragmenting traditional OEM aftermarket relationships as contractors source rock-tool consumables and maintenance labor through separate channels. Santiago-based mining services firms coordinate fleet specifications for Codelco and private operators.
Germany
Alpine infrastructure projects face accelerated replacement pressure from EU Green Deal carbon-border adjustment mechanisms. Equipment suppliers must document embodied carbon and operational emissions across machine lifecycles. Munich and Stuttgart anchor engineering specification activity for tunnel boring and underground excavation contracts.
Drilling Jumbo Market Competitive Landscape
The competitive structure tilts toward integrated rock-tools-to-drill-systems coverage. Tier-one mining OEMs anchor premium positioning through automation software stacks and electrified platforms. Mid-tier regional fabricators compete on hydraulic reliability and aftermarket service density. Dominant competitive moves include strategic partnerships for battery-electric powertrain integration and geographic expansion into underpenetrated Central Asian mining districts.
Within the automation-integrated tier, Epiroc and Sandvik Construction exemplify platform providers combining drill control systems with mine-wide digital infrastructure. Furukawa occupies a position among hydraulic reliability specialists serving Southeast Asian hard-rock conditions. Chinese fabricators including XCMG and Jiangxi Siton Machinery Manufacturing Co., Ltd represent scale-driven regional suppliers addressing domestic replacement demand and export markets in Central Asia and Africa.
| Leading Market Players |
|---|
| Epiroc |
| Sandvik Construction |
| Furukawa |
| Komatsu Mining Corp |
| J.H. Fletcher |
| XCMG |
| Jiangxi Siton Machinery Manufacturing Co., Ltd |
| RDH Mining Equipment |
| Kaishan |
| Others |
Supply & Pricing Matrix
Australia's ISO 19434 automation mandates are forcing fleet operators toward electromechanical and remote-capable platforms, compelling OEMs to absorb battery-cell cost volatility and restructure component sourcing around qualified suppliers. This demand-side specification shift is compressing margins on legacy hydraulic architectures while creating premium capture opportunities for automation-integrated systems.
Pricing Analysis
Throughput-based value anchoring dominates as tier-one miners contract for guaranteed availability and drill-meter performance rather than capital equipment ownership. Three-tier pricing structure across premium automation-integrated, standard hydraulic, and economy pneumatic levels separates Epiroc and Sandvik at the top from Chinese fabricators serving replacement demand. Cost compression in mid-tier hydraulics is intensifying because lithium-ion cell supply bottlenecks force OEMs to either absorb input spikes or pass through to price-sensitive contractors in Central Asia and Africa. Construction firms in European urban tunneling show least price sensitivity due to EU Green Deal emission compliance deadlines, while mid-tier mining contractors in Kazakhstan and Chile exhibit highest sensitivity, extending legacy pneumatic fleet life through aftermarket rebuilds.
Supply Chain Analysis
Domestic-content mandates in China's non-coal mining sector and India's push for local manufacturing under PLI-equivalent schemes are reshaping sourcing patterns for battery-electric powertrains and automation control systems. Electromechanical rig production draws from lithium-ion cell supply chains concentrated in China, South Korea, and Japan, with hydraulic component clusters anchored in Germany, Sweden, and Japan. Permanent magnet motors, high-torque gearboxes, and rock-tool consumables constitute critical input dependencies. Single-source vulnerability in rare-earth magnet processing creates exposure to export restriction shocks. Distribution runs through OEM-direct sales for tier-one miners, regional dealer networks for mid-tier contractors, and unbundled service channels in mature mining districts like Chile's Atacama.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation engineering talent scarcity and capex intensity of full tele-remote capability are consolidating competitive position around OEMs with captive software stacks, forcing mid-tier hydraulic specialists toward acquisition or exit.
For Market Incumbents: Deploy automation software stack licensing as the primary defensive lever. Epiroc and Sandvik should deepen upstream control over battery-electric powertrain integration through exclusive partnerships with cell suppliers, eliminating dual-sourcing complexity for tier-one miners. Collision-avoidance certification investment creates switching costs that lock out regional hydraulic fabricators lacking mechatronics capabilities. The raise-boring substitution threat in vertical shaft development demands counter-positioning through jumbo flexibility in complex geometries where full-face cutters fail. For New Entrants and Emerging Players: Mid-tier contractors in Kazakhstan's copper and uranium belt represent the most penetrable buyer archetype. These operators maintain legacy Soviet-era pneumatic fleets and face modernization pressure from the national mining ministry's evolving safety standards. A go-to-market angle anchored in phased retrofit pathways—collision-avoidance add-ons before full automation—aligns with compressed capital budgets and extends equipment finance relationships. Secondary white-space sits in African hard-rock gold operations where established OEM service density remains thin and Chinese fabricators have not yet built aftermarket capability. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive rock-tool production and established regional service networks. Long-term viability over the coming decade rests on automation-readiness rather than hydraulic reliability heritage. Acquisition targets should demonstrate installed base density in underpenetrated geographies and technical competency for tele-remote retrofit execution. The signal to watch is regulatory adoption of ISO 19434-equivalent frameworks in Central Asian and African mining jurisdictions, which would trigger fleet replacement demand and validate premium positioning for automation-capable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Powertrain Integration | Eliminates diesel particulate exposure at tunnel portals while meeting EU Green Deal emission thresholds for Alpine infrastructure contracts. |
| Tele-Remote Control Platform Deployment | Removes operators from blast zones during drilling cycles, compressing shift-change downtime in Australian and Canadian underground operations. |
| Real-Time Rock-Mass Sensor Integration | Automates blast-pattern optimization, reducing face exposure and improving fragmentation consistency for tier-one miners. |
| Aftermarket Service Unbundling Response | Counter-fragments traditional OEM relationships by offering consumable subscription bundles to Chilean copper contractors. |
| Central Asian Geographic Expansion | Captures replacement demand as Kazakhstan's national mining ministry modernizes safety standards for legacy pneumatic fleets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this drilling jumbo market assessment. Primary interviews with mine operations managers, OEM product line directors, aftermarket service heads, and procurement officers at tier-one mining houses combined with secondary validation from ISO certification databases, Australia's national resources regulator disclosures, and US MSHA enforcement records. Bottom-up triangulation across equipment unit shipments and top-down reconciliation against mining capital expenditure surveys ensured cross-verified demand estimation.
Data-stream reconciliation across unit volume, average selling price, and technology mix informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, powertrain architecture, automation tier, end-user scale, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year installed base and replacement-cycle compression factors. Industry-specific forecast inputs incorporated battery-electric adoption curves tied to thermal environment constraints and automation mandate implementation timelines by jurisdiction.
Revisions become necessary when battery cell supply disruptions, thermal management breakthroughs, or regulatory acceleration in unpenetrated geographies materially alter replacement-cycle assumptions. Forecasts reflect documented assumptions regarding automation engineering talent availability and lithium-ion cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Drill Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Africa Mining Market
Mining Equipment
Logging Cable Market