
 Global Excavators Market | 2026-2036
Global Excavators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Excavators Market Analysis
Electrification of powertrains is reshaping excavator engineering, forcing OEMs to redesign hydraulic architectures around battery packs and electric motors. Caterpillar Inc. leverages its North American dealer network to sustain aftermarket revenue while transitioning its product line. Komatsu Ltd. anchors Japanese mining demand through autonomous haulage integration with its excavator fleet. SANY Group dominates Chinese infrastructure bids by controlling domestic steel casting supply chains.
An excavator is a self-propelled earthmoving machine comprising a boom, arm, and bucket assembly mounted on a rotating platform, with operating weights spanning below 5 tons to above 20 tons depending on application duty. Its primary industrial purpose is trenching, material handling, and bulk earth removal across construction sites, open-pit mines, and utility corridors. Mini excavators lead urban utility contracts where space constraints restrict machine footprint, while electric and hybrid technologies capture the fastest expansion as city councils ban diesel equipment from centers. Above 20 ton capacity units retain the deepest margin pools due to aftermarket parts density and rebuild cycles.
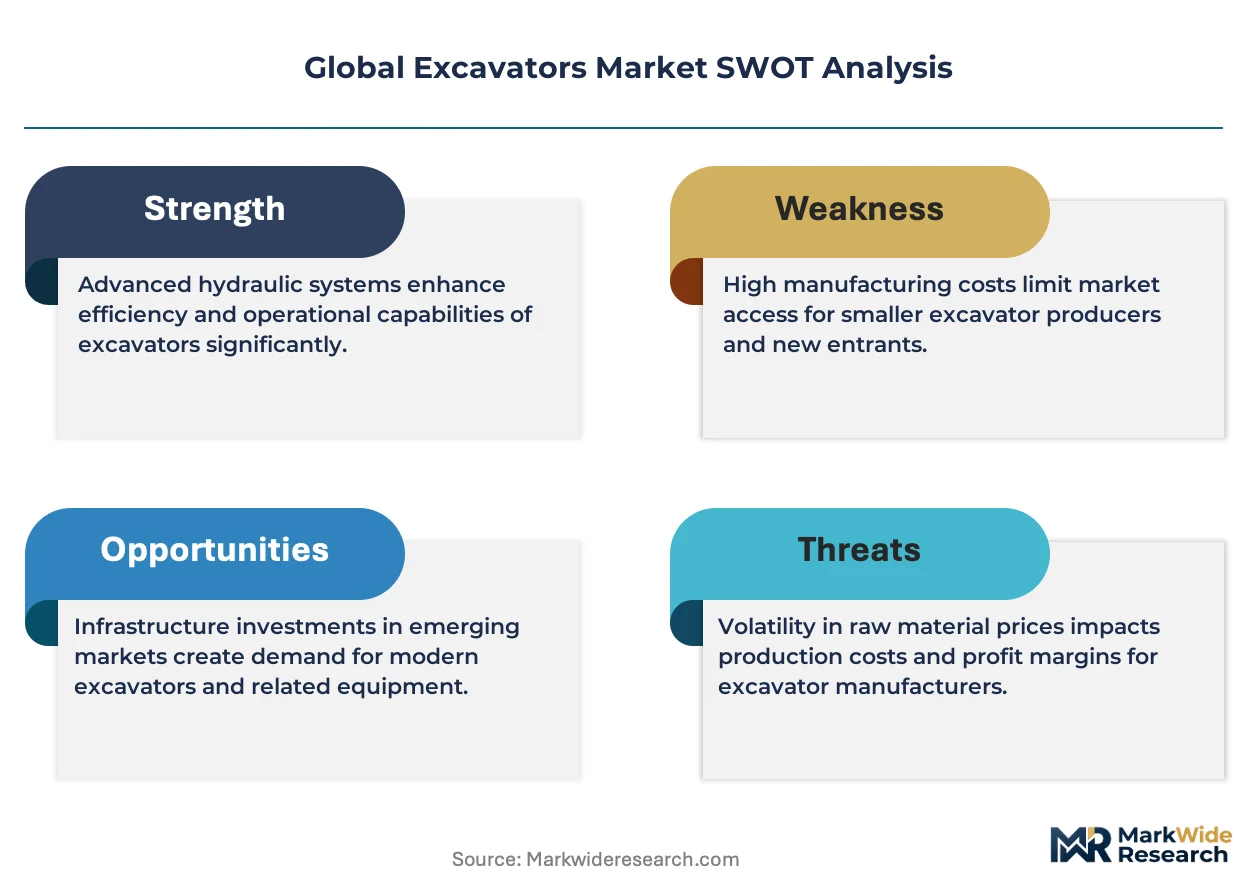
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine suppliers to deploy selective catalytic reduction and diesel particulate filters, adding cost but blocking non-compliant imports from accessing North American and European job sites. China's MIIT enforces GB standards on construction machinery fuel consumption, directing domestic R&D toward hybrid architectures. Japan's METI promotes hydrogen fuel cell demonstrations for heavy equipment, creating alternative compliance pathways. Stakeholders must monitor battery supply agreements and regional charging infrastructure commitments before committing to platform electrification timelines.
Market Dynamics
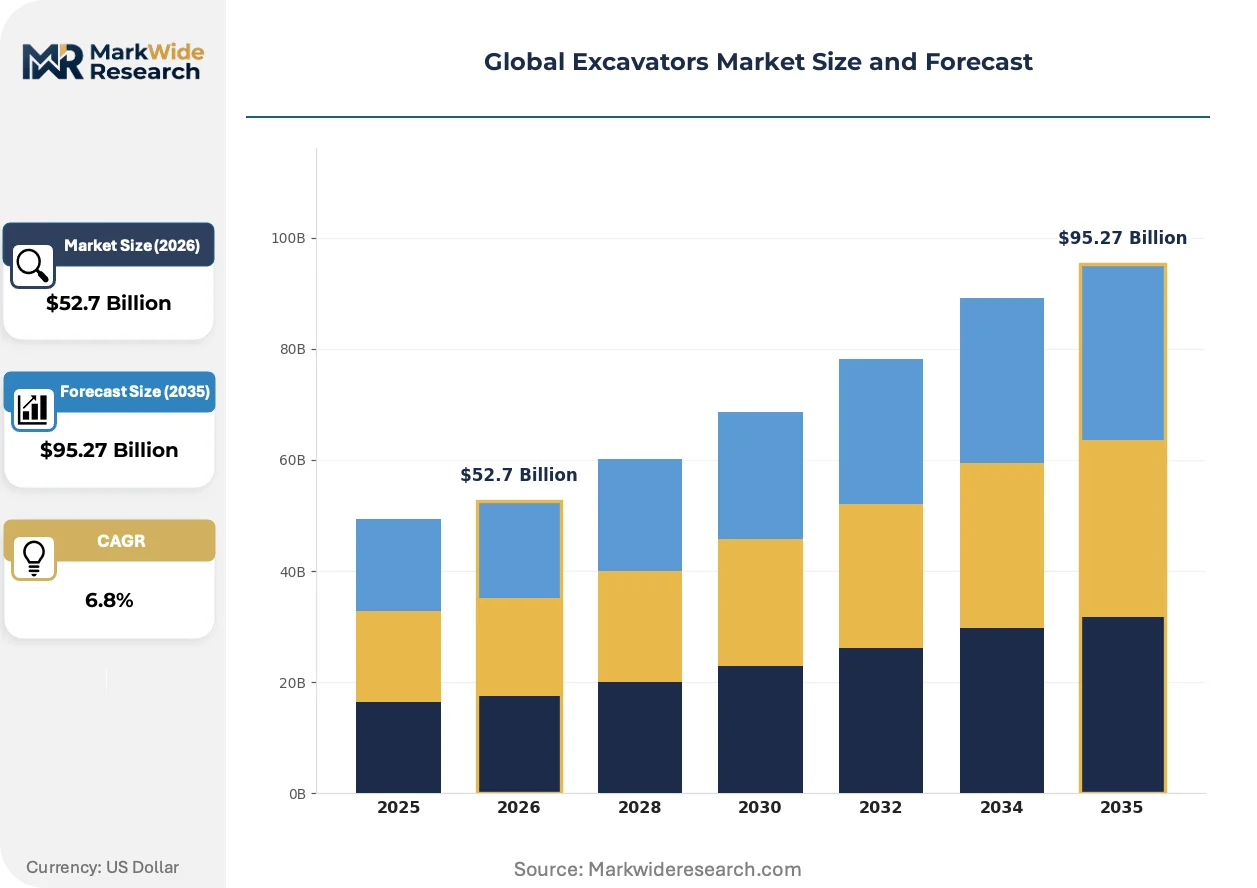
Electrification of powertrains is forcing excavator OEMs to redesign hydraulic architectures around battery packs and electric motors, compressing development cycles while opening new revenue pools in charging infrastructure and fleet management software.
Growth Catalysts
- EPA Tier 4 Final compliance:North American emissions frameworks block non-compliant imports, insulating domestic manufacturers from low-cost competition and preserving margin structures for certified equipment.
- Australian mining expansion:Iron ore and lithium extraction operations drive replacement demand for high-capacity crawler units above 20 tons, with operators prioritizing uptime over capital cost.
- Urban densification:Mini excavators capture trenching contracts in constrained city centers where machine footprint determines bid eligibility, with electric variants qualifying for zero-emission zone access.
Market Restraints
- Battery supply concentration:Lithium-ion cell production clusters in China create import dependency risks for Western OEMs pursuing electrification roadmaps.
- Steel casting bottlenecks:Specialized foundry capacity for boom and arm assemblies limits production scaling, with lead times extending 18-24 months for critical components.
- Hydrogen infrastructure gaps:Japan's METI demonstration programs lack parallel refueling networks, constraining fuel cell excavator deployment to captive mine sites with on-site generation.
Strategic Opportunities
- India infrastructure build-out:National highway and metro expansion projects create first-time equipment demand outside traditional China-Japan supply corridors.
- Autonomous integration:Convergence of machine vision and telematics enables single-operator fleet control, reducing labor costs in Australian and Chilean mining operations.
- EU Green Deal procurement mandates:Public construction contracts increasingly specify electric or hybrid equipment, creating regulatory-tied demand visibility for compliant OEMs.
Industry Challenges
- Electrification skill gaps:Field technicians lack training in high-voltage battery systems and thermal management, slowing service response times and raising warranty costs.
- Legacy fleet integration:Mixed diesel-electric job sites require interoperable telematics protocols that current OEM data architectures do not support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Excavators Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Standard Excavators, Crawler Excavators, Wheeled Excavators End User: Construction, Mining, Infrastructure, Agriculture Technology: Hydraulic, Electric, Hybrid, Pneumatic Capacity: Below 5 Tons, 5-10 Tons, 10-20 Tons, Above 20 Tons |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., Volvo Construction Equipment, SANY Group, Liebherr Group, Doosan Infracore, JCB, XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Excavators Market Emerging Trajectories
Telematics and predictive maintenance systems are digitizing equipment lifecycle management, shifting revenue from unit sales to subscription-based uptime guarantees and remote diagnostics.
Machine learning algorithms applied to hydraulic pressure sensors and boom position data enable real-time component wear prediction. Mining contractors in Western Australia and Chile adopt these systems fastest, accepting per-hour service fees in exchange for guaranteed availability. The technology is digitizing maintenance scheduling from calendar-based to condition-based intervals, compressing parts inventory requirements and extending rebuild cycles.
EU Stage V emissions rules now mandate onboard diagnostic systems and permanent emissions data logging for engines above 19 kW. This forces engine suppliers to integrate telematics hardware at the factory, eliminating retrofit pathways for older equipment. The regulation hits rental fleet operators hardest, accelerating replacement cycles for non-compliant machines in Germany and France.
Equipment-as-a-service contracts now bundle excavators with fuel, maintenance, and operator training into single monthly payments. Municipal utilities in Scandinavia and the Netherlands favor this model for urban trenching projects, transferring residual value risk to OEMs. Channel disintermediation follows, with manufacturers selling direct to end-users and bypassing traditional dealer networks for standardized machine configurations.
Global Excavators Market Segmentation
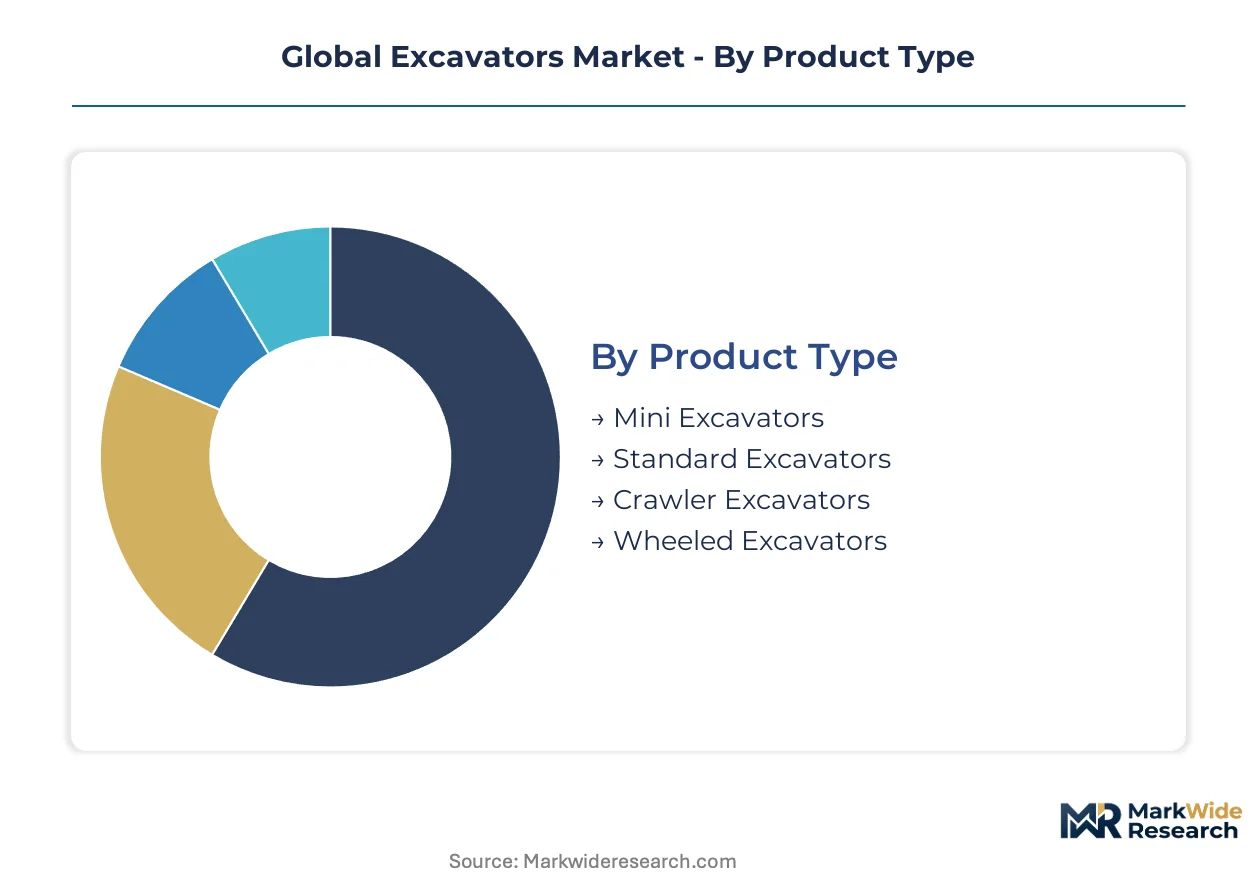
Excavator segmentation maps directly to job site constraints and regulatory exposure. Equipment buyers select configurations based on emission zone access, material density, and labor availability rather than capital cost alone.
Product Type:
Use cases span confined utility trenches to open-pit bulk removal, with mobility requirements dictating undercarriage design.
- Mini Excavators:Operating weights below 6 tons with zero-tail-swing configurations dominate urban utility corridors. Municipal contractors in Amsterdam and Copenhagen specify electric variants to comply with diesel bans in historic centers.
- Crawler Excavators:Tracked undercarriages distribute weight across soft ground conditions in Australian iron ore and Chilean copper operations. High ground clearance and gradeability specifications prioritize uptime over transport speed.
- Standard Excavators:Mid-size units serve general construction with balanced reach and lifting capacity for foundation work and material loading.
- Wheeled Excavators:Rubber-tired mobility enables rapid repositioning between roadwork segments without low-bed transport, capturing highway maintenance contracts across Germany and France.
The dominant share belongs to Crawler Excavators, while Mini Excavators is closing the gap fastest.
End User:
Capital deployment cycles and fleet replacement urgency vary sharply across customer categories.
- Construction:Residential and commercial building contractors drive volume through standardized equipment configurations. Demand clusters in India's highway expansion and Indonesia's port modernization, with rental fleets absorbing depreciation risk for small contractors.
- Mining:Surface extraction operations in Western Australia and northern Chile specify units above 20 tons with autonomous retrofit compatibility. Komatsu and Caterpillar anchor fleet decisions through integrated haulage system contracts.
- Infrastructure:Government-funded rail, metro, and water projects in Brazil and Saudi Arabia generate lumpy procurement with local content requirements.
- Agriculture:Drainage ditching and land clearing applications favor used equipment imports, limiting OEM direct sales.
Construction commands the largest equipment base, though Mining generates the highest revenue per unit.
Technology:
Powertrain architecture determines regulatory compliance pathways and total cost of ownership calculations.
- Electric:Battery-electric systems eliminate exhaust emissions for indoor demolition and tunneling work. Urban job sites in Oslo and Stockholm mandate zero-emission equipment, with charging infrastructure commitments from municipal utilities enabling fleet conversion.
- Hybrid:Diesel-electric architectures reduce fuel consumption through regenerative boom lowering and engine downsizing. Japan's METI demonstration programs and EU Stage V compliance deadlines accelerate OEM development spending.
- Hydraulic:Conventional open-center and load-sensing systems retain cost advantages for remote job sites lacking electrical infrastructure.
- Pneumatic:Compressed-air powertrains serve explosive atmospheres in underground coal operations where ignition sources are prohibited.
Hydraulic systems retain installed base dominance, while Electric expands most quickly in municipal procurement.
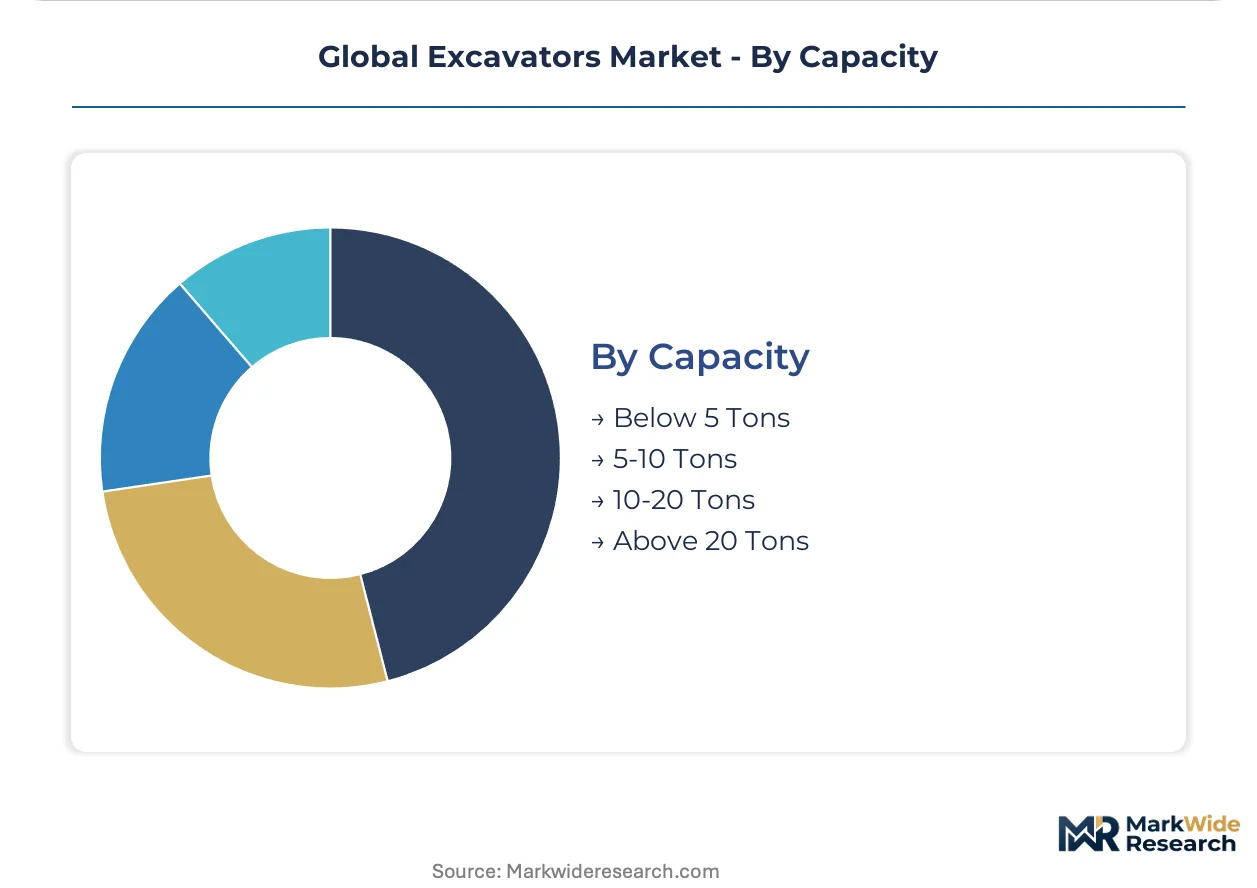
Capacity:
Operating weight thresholds align with transport regulations, operator licensing requirements, and attachment compatibility.
- Above 20 Tons:Heavy-duty units handle mass excavation with reinforced boom structures and high-pressure hydraulics. Mining contractors in Australia prioritize component commonality across fleets to compress parts inventory and technician training costs.
- Below 5 Tons:Compact dimensions enable trailer transport behind standard pickup trucks, eliminating commercial driver's license requirements. Landscaping and rental yards in Texas and Florida drive replacement demand.
- 5-10 Tons:Mid-range machines balance residential foundation work with road shoulder maintenance versatility.
- 10-20 Tons:General-purpose configurations serve building construction with sufficient reach for three-story demolition and utility trenching.
Above 20 Tons generates the deepest aftermarket revenue pools, while Below 5 Tons is gaining share fastest through rental channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining contractors in Western Australia and infrastructure developers in India represent the dominant buyer archetypes, each demanding distinct equipment specifications and service models. Their procurement patterns diverge sharply on uptime guarantees versus capital cost sensitivity.
United States
Highway rehabilitation and utility corridor projects drive crawler and wheeled excavator demand across Texas and Florida. EPA Tier 4 Final compliance blocks non-certified imports, insulating domestic manufacturers from price competition. Equipment rental yards in Houston and Dallas absorb depreciation risk for small contractors through fleet leasing programs.
Germany
Rail tunneling and urban metro expansion in Munich and Stuttgart require zero-emission electric variants for confined underground work. EU Stage V mandates onboard diagnostic systems with permanent emissions logging, accelerating replacement cycles for non-compliant rental fleets. Manufacturing clusters in Bavaria supply precision hydraulic components to OEM assembly lines.
China
National infrastructure stimulus and Belt and Road port projects sustain volume demand for mid-size units. MIIT enforces GB standards on construction machinery fuel consumption, directing R&D investment toward hybrid powertrain architectures. Production gravity concentrates in Xuzhou and Changsha, where SANY and XCMG anchor vertically integrated supply chains spanning steel casting to final assembly.
Japan
Demolition and narrow-site foundation work in Tokyo and Osaka prioritize mini excavators with zero-tail-swing configurations. METI promotes hydrogen fuel cell demonstrations for heavy equipment, creating alternative compliance pathways beyond battery electrification. Component suppliers in Aichi Prefecture specialize in high-pressure hydraulic valves and precision sensors.
India
National highway expansion and metro rail construction in Maharashtra and Karnataka generate first-time equipment demand outside traditional supply corridors. Central Electricity Authority regulations on construction equipment emissions are tightening, though enforcement remains uneven. Rental fleet operators in Mumbai and Bangalore aggregate demand for standardized 10-20 ton configurations.
Global Excavators Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: full-line manufacturers with integrated haulage systems, regional champions with captive domestic supply chains, and component-specialist licensors. Consolidation pressures intensify as electrification R&D costs favor scale, while M&A activity targets autonomous control software capabilities and foundry capacity for boom assemblies.
Within the full-line manufacturer tier, Caterpillar Inc. and Komatsu Ltd. represent integrated system providers whose competitive positioning rests on fleet-wide interoperability rather than standalone machine performance. SANY Group exemplifies the regional champion archetype, leveraging location-derived advantages in steel casting and domestic procurement scale. These three anchors illustrate how competitive differentiation increasingly separates channel-integrated players from product-only suppliers.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| Volvo Construction Equipment |
| SANY Group |
| Liebherr Group |
| Doosan Infracore |
| JCB |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in China and Germany drives 18-24 month lead times for boom and arm castings, forcing OEMs to pre-pay for capacity slots and compress margin buffers on long-term contracts. This utilization squeeze rewards suppliers with captive steel casting while penalizing arm's-length buyers with price escalation clauses tied to scrap metal indices.
Pricing Analysis
Cost-plus contracts with steel scrap indexation dominate above-20-ton excavator procurement, insulating manufacturers from raw material volatility while exposing buyers to quarterly adjustments. Price differentiation rests on EPA Tier 4 Final certification tier and aftermarket parts bundling intensity. Cost compression in the mini excavator tier is intensifying because rental fleet operators consolidate specifications to maximize utilization. Small contractors in Texas and Florida exhibit highest price sensitivity, while Australian mining contractors prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for Western OEMs pursuing electrification roadmaps. Lithium-ion cell production clusters in China, South Korea, and Japan feed battery pack assembly, while specialized foundry capacity for hydraulic components rests on German and Japanese precision machining. Single-source vulnerability in rare earth permanent magnets for electric motors threatens production continuity. Distribution runs through manufacturer-owned dealer networks in North America and rental fleet aggregators in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Excavator fleet interoperability is shifting from machine-level competition to ecosystem-level platform economics, with autonomous haulage integration and telematics data architectures determining customer lock-in.
For Market Incumbents: Build switching-cost moats through proprietary telematics protocols that fragment mixed-fleet job sites. Deepen backward integration into battery supply agreements with Korean cell manufacturers to secure electrification roadmaps. Defend against Chinese OEM price pressure by anchoring fleet decisions through integrated haulage system contracts with Australian and Chilean miners. For New Entrants and Emerging Players: Pursue white-space opportunities in India's highway and metro expansion, where first-time equipment demand escapes established supply corridors. Target municipal electric fleet conversions in Scandinavian cities with charging infrastructure partnerships. Lead with equipment-as-a-service contracts that transfer residual value risk and bypass entrenched dealer networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with installed base telemetry penetration and aftermarket parts density. Long-term viability hinges on electrification R&D scale and autonomous software capabilities. Monitor battery supply agreement announcements as the critical inflection signal for platform competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Korean manufacturers for electric excavator platforms. |
| Autonomous Haulage Integration | Links excavator fleets to Komatsu and Caterpillar mine-site automation systems in Western Australia. |
| Foundry Capacity Expansion | Adds steel casting capacity for boom assemblies in Xuzhou to compress 18-24 month lead times. |
| Equipment-as-a-Service Launch | Bundles excavators with maintenance and charging for Dutch and Scandinavian municipal utilities. |
| Telematics Platform Integration | Enables predictive maintenance subscriptions tied to hydraulic sensor data from Chilean copper operations. |
Methodological Framework
Desk research of trade customs data, EPA certification filings, and mining contractor fleet disclosures preceded structured interviews with OEM product strategy directors, aftermarket service heads, and rental fleet procurement managers. Primary fieldwork captured equipment replacement cycles, telematics adoption rates, and battery supply negotiation dynamics. Secondary validation drew from EU Stage V implementation reports, Australian Bureau of Statistics mining capital expenditure series, and China MIIT fuel consumption standard bulletins. Bottom-up unit shipment estimates triangulated against top-down construction and mining equipment spend projections.
Assumptions held fixed include current EPA Tier 4 Final and EU Stage V regulatory frameworks, existing battery cell cost curves, and autonomous haulage deployment rates in Australian iron ore operations. Variables tested across the analysis window encompassed infrastructure stimulus intensity in India, hydrogen refueling network buildout in Japan, and municipal diesel ban enforcement in European historic centers. Segmentation modeling spanned product type, capacity tier, powertrain technology, and end-use industry. CAGRs derived from regression against historical replacement cycles and regulatory compliance deadlines, with electric variant penetration calibrated to charging infrastructure commitments in Oslo and Stockholm.
Sensitivities concentrate around lithium supply disruption, steel casting capacity expansion delays, and autonomous technology adoption curves in surface mining. Forecasts reflect documented assumptions on regulatory stability and battery cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Crane Rail Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Snow Removal Market
Construction Equipment
Europe Multi Attachment Loaders Market