
 Drone-Based Solutions in Construction Market | 2026-2036
Drone-Based Solutions in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-Based Solutions in Construction Market Analysis
Software-defined flight planning and data analytics subscription layers is consolidating value away from hardware transactions toward recurring revenue models in the drone construction ecosystem. SZ DJI Technology Co., Ltd. leverages its manufacturing scale to dominate consumer-to-prosumer transitions. Skydio differentiates through autonomous navigation systems purpose-built for complex structural inspections. DroneDeploy Inc. anchors cloud-based photogrammetry workflows that integrate directly with project management suites.
Drone-based solutions in construction encompass unmanned aerial vehicles equipped with sensors, cameras, and positioning systems to capture geospatial data, generate 3D models, and monitor worksite conditions without manned flight operations. These systems typically operate at altitudes below 400 feet with payloads integrating LiDAR scanners, RGB cameras, or thermal imagers to deliver centimeter-grade accuracy for earthwork quantification and structural assessments. Multirotor configurations currently lead deployment frequency due to vertical takeoff flexibility in congested urban jobsites, while fixed-wing platforms sustain demand across linear infrastructure corridors where endurance and coverage area outweigh maneuverability requirements. Photogrammetry technology occupies the largest installed base among imaging modalities, though LiDAR is displacing conventional methods in vegetation-heavy terrain where bare-earth extraction demands penetrate canopy cover.
FAA Part 107 mandates pilot certification and operational limitations that shape training investments and fleet standardization across US construction firms. EASA U-space regulations and emerging EU AI Act risk classifications will force interoperability upgrades for vendors serving European contractors. OSHA worksite safety directives increasingly reference aerial inspection protocols, creating compliance-driven procurement cycles. Stakeholders must monitor evolving beyond-visual-line-of-sight waivers and automated flight authorization systems that will determine which service providers capture high-frequency monitoring contracts.
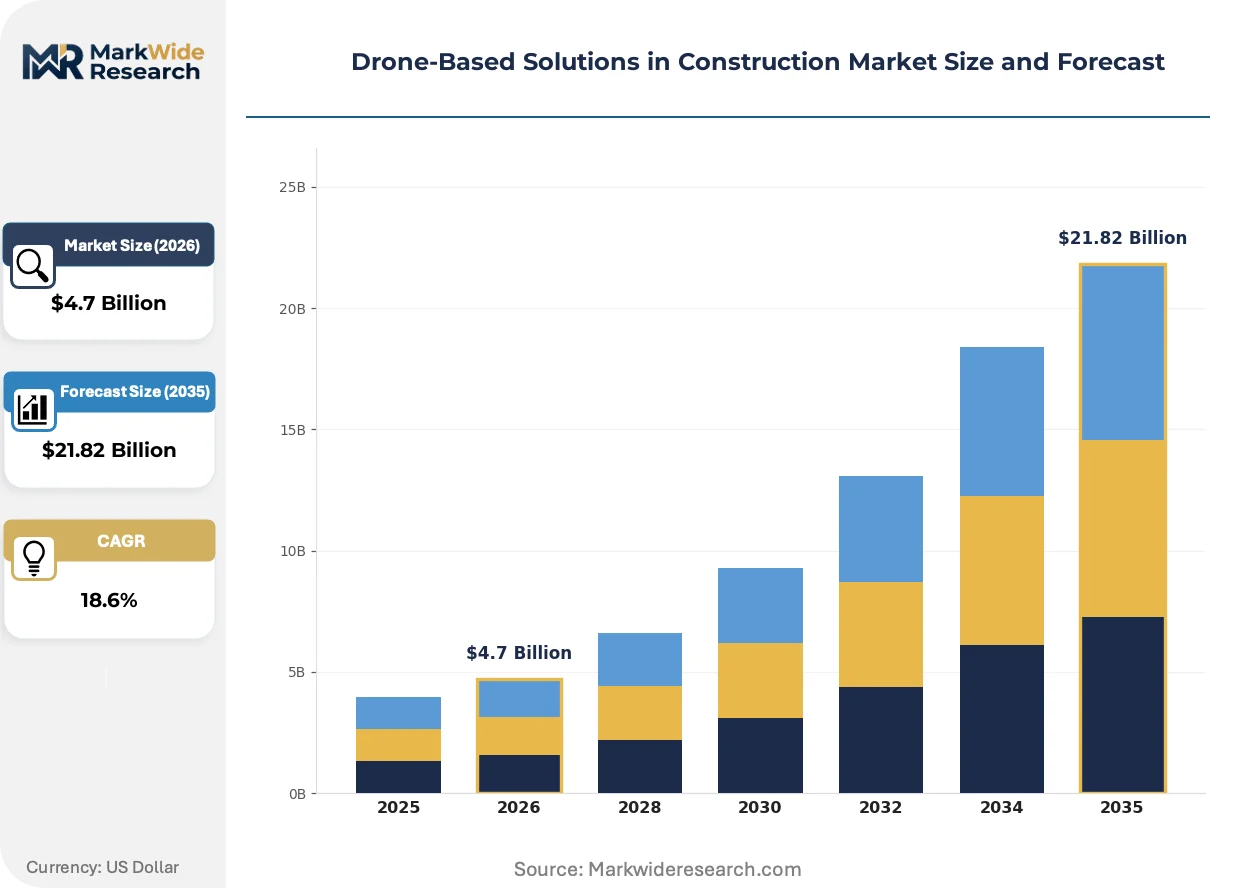
Market Dynamics
Software-defined flight planning is decentralizing operational control from centralized service providers toward self-sufficient general contractor fleets, compressing the addressable market for third-party drone operators while expanding hardware and subscription software penetration across mid-tier construction firms.
Growth Catalysts
- FAA Part 107 recurrent training mandates:Pilot certification requirements create recurring revenue streams for training providers and fleet standardization consultants serving US construction enterprises.
- LiDAR sensor miniaturization:Reduced payload weight and power draw enable longer flight endurance on multirotor platforms, expanding viable deployment scenarios for vegetation-heavy earthwork sites.
- State-level infrastructure spending clusters:Texas, California, and Florida DOTs integrate drone surveying into mandatory pre-bid documentation, creating procurement pull-through for equipment vendors.
Market Restraints
- Battery chemistry cost volatility:Lithium-ion cell price fluctuations constrain fleet expansion timelines for cash-constrained regional contractors.
- Geographic supply concentration:Shenzhen-based manufacturing clusters create single-point-of-failure exposure for North American and European hardware distributors.
- Beyond-visual-line-of-sight waiver scarcity:FAA case-by-case authorization protocols limit linear infrastructure corridor monitoring economics.
Strategic Opportunities
- EU U-space framework implementation:EASA automated flight authorization standards create first-mover advantage for vendors achieving interoperability certification ahead of 2026 enforcement deadlines.
- Thermal imaging convergence with AI edge processing:Onboard defect detection eliminates cloud latency for real-time structural integrity alerts during active construction phases.
- Equipment-as-a-service channel innovation:Pay-per-flight-meter models reduce capital barriers for specialty trade contractors entering aerial inspection services.
Industry Challenges
- Part 107 remote pilot skill gaps:Certified operator scarcity constrains fleet utilization rates below hardware capacity thresholds.
- Photogrammetry-to-BIM integration complexity:Point cloud standardization delays between capture software and legacy design platforms extend project onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-Based Solutions in Construction Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Hybrid, VTOL Application: Site Surveying, Progress Monitoring, Aerial Imaging, Safety Inspections Technology: LiDAR, Photogrammetry, GPS Navigation, Real-Time Data Analytics End User: General Contractors, Architects, Surveyors, Project Managers |
| Companies Covered | SZ DJI Technology Co., Ltd., Skydio, Parrot Drones SAS, DroneDeploy Inc., PrecisionHawk, 3DR, Inc., Autel Robotics Co. Ltd., Yuneec, Terra Drone Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-Based Solutions in Construction Market Emerging Trajectories
Edge computing architectures and autonomous navigation stacks are compressing the technical barrier between consumer-grade hardware and enterprise-grade inspection workflows, enabling new entrant participation in previously specialized service tiers.
Swarm coordination algorithms are decentralizing large-area surveying operations across multiple low-cost units rather than single high-endurance platforms. Regional earthwork contractors in Australia and Canada adopt distributed flight patterns for mining reclamation and agricultural-to-residential conversion projects. This topology reduces single-point-of-failure risk while expanding daily acreage coverage without BVLOS regulatory exposure.
EASA U-space framework implementation is mandating interoperability standards for detect-and-avoid systems serving European construction corridors. German and French infrastructure consortia now require C2 link redundancy and remote identification broadcast capability in equipment procurement specifications. Vendors lacking EU-type certification face exclusion from public-sector tendering processes beginning 2026.
General contractors are unbundling aerial data capture from bundled engineering services, establishing direct software subscriptions with cloud photogrammetry platforms. This disintermediation compresses margins for traditional survey firms while expanding addressable spend for SaaS-native workflow providers. The pattern is most pronounced in US Sun Belt metropolitan markets where developer-led project delivery dominates.
Drone-Based Solutions in Construction Market Segmentation
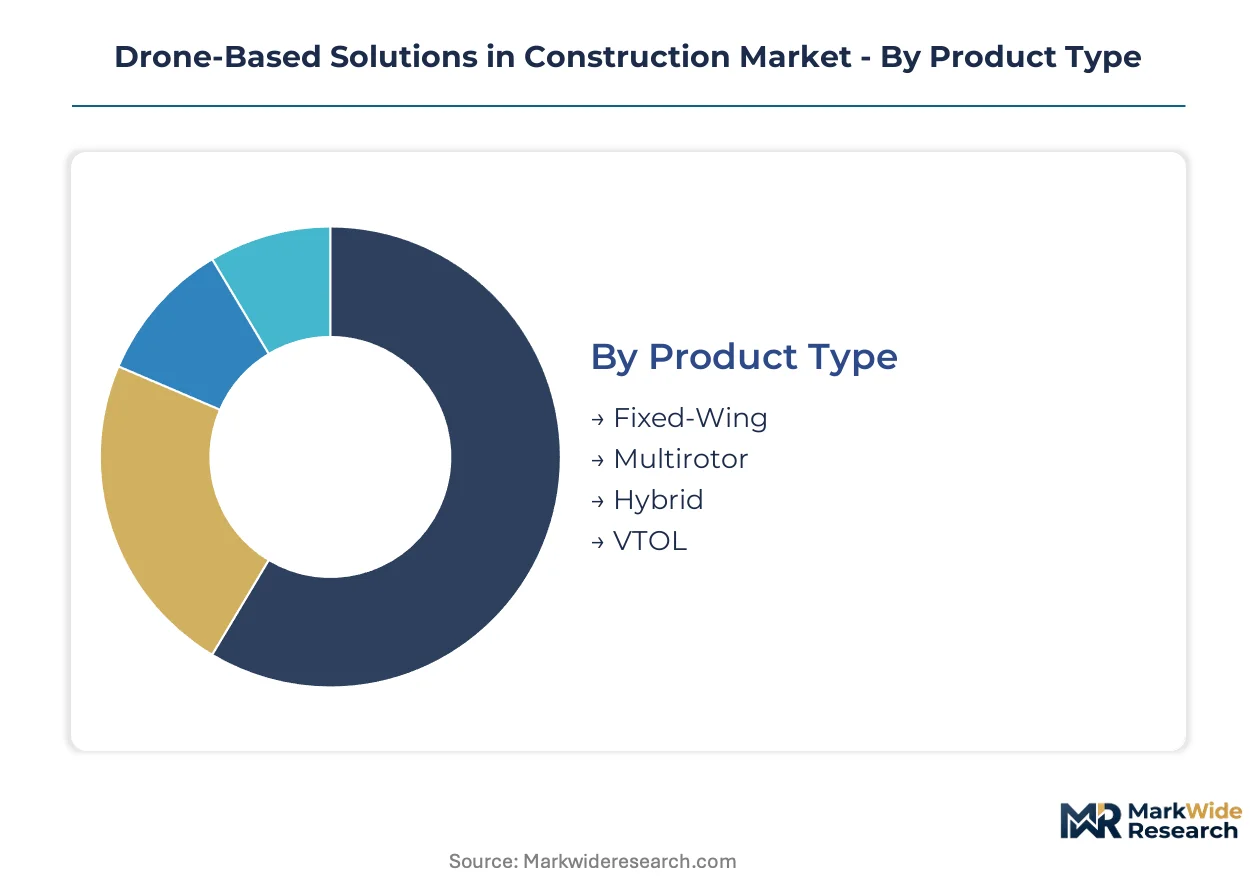
Segmentation in drone-based construction solutions reveals how hardware configurations, imaging modalities, and operator types align with distinct value extraction models. Procurement patterns diverge sharply between self-operated contractor fleets and third-party service dependencies.
Product Type:
Integration depth varies substantially across airframe architectures, with standalone platforms dominating discrete survey missions while embedded navigation systems enable autonomous fleet coordination.
- Multirotor:Vertical takeoff capability suits congested urban jobsites where launch space constraints eliminate runway-dependent alternatives. General contractors in Texas and Florida DOT corridors deploy these for mandatory pre-bid documentation, though battery endurance caps mission radius.
- Fixed-Wing:Extended flight duration and glide efficiency optimize linear infrastructure corridor coverage where endurance outweighs maneuverability. Demand concentrates among mining reclamation contractors in Australia and agricultural-to-residential conversion projects in Canada.
- Hybrid:Combines VTOL flexibility with fixed-wing cruise efficiency for transitional site conditions.
- VTOL:Purpose-built for precision structural inspections requiring stable hover positioning.
Multirotor configurations lead volumes today; hybrid architectures are gaining share fastest.
Application:
Cost tier stratification separates bundled engineering services from unbundled data capture subscriptions, reshaping margin pools across the value chain.
- Site Surveying:Centimeter-grade geospatial capture for earthwork quantification and pre-construction documentation. State-level infrastructure spending clusters in Texas, California, and Florida mandate drone surveying in procurement specifications, creating equipment pull-through.
- Progress Monitoring:Time-series aerial documentation tracking construction milestones against schedule baselines. General contractors establish direct SaaS subscriptions with cloud photogrammetry platforms, disintermediating traditional survey firms.
- Aerial Imaging:RGB and thermal payload capture for marketing documentation and stakeholder reporting.
- Safety Inspections:Structural integrity assessment reducing manned exposure to hazardous heights.
Site surveying leads volumes today; progress monitoring is expanding most quickly.
Technology:
Maturity gradients separate established imaging modalities from emerging edge-processing capabilities that compress latency for real-time decision support.
- Photogrammetry:Dense image matching algorithms generating 3D point clouds from overlapping aerial photographs. Currently occupies the largest installed base, though vegetation-heavy terrain limits bare-earth extraction without supplemental sensors.
- LiDAR:Active laser ranging penetrating canopy cover for accurate ground surface modeling. Miniaturized sensors reducing payload weight and power draw enable longer multirotor endurance, expanding viable deployment scenarios.
- GPS Navigation:RTK and PPK correction protocols enabling centimeter-grade positional accuracy.
- Real-Time Data Analytics:Onboard AI edge processing eliminating cloud latency for immediate defect alerts.
Photogrammetry leads volumes today; real-time data analytics shows the steepest expansion trajectory.
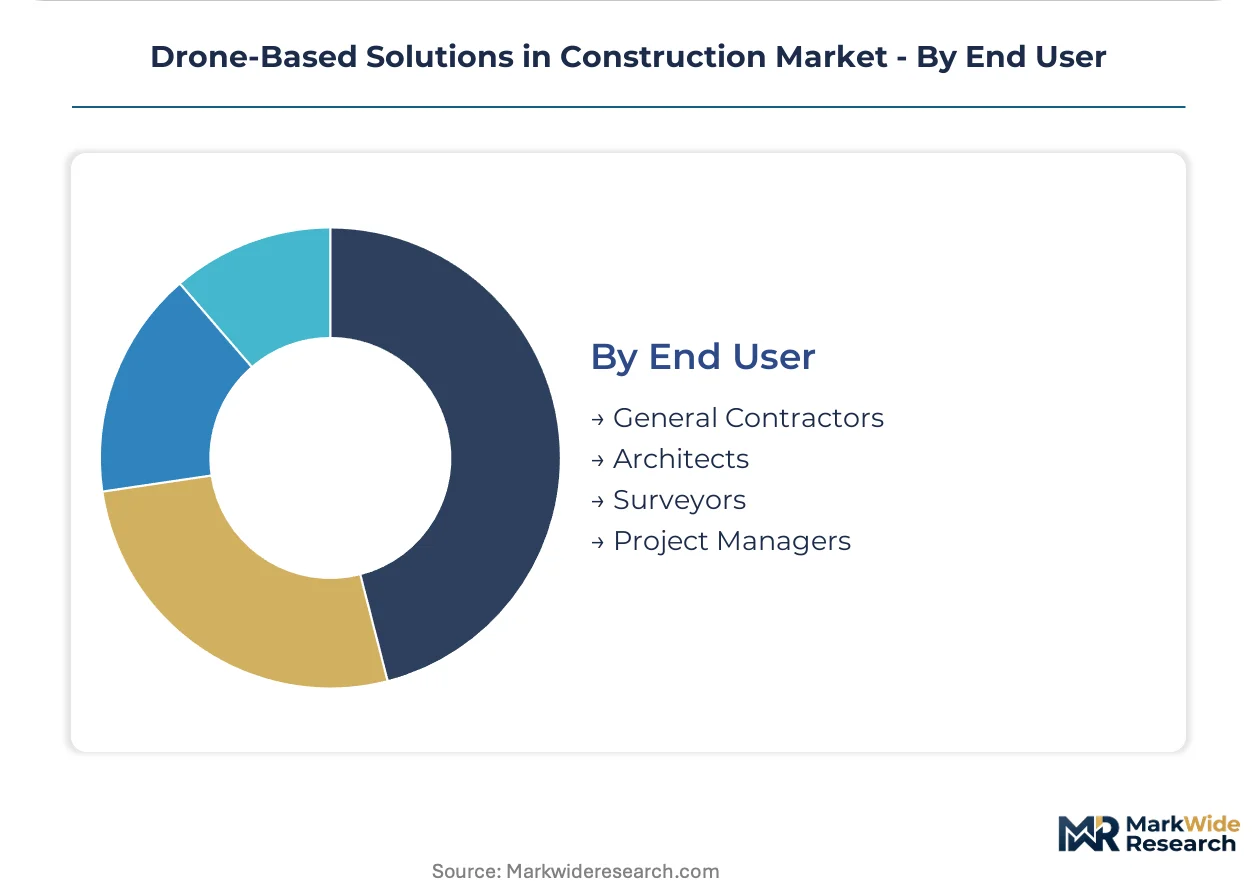
End User:
Customer type fragmentation reflects divergent technical capabilities, with self-sufficient fleets compressing third-party operator addressable markets while expanding software subscription penetration.
- General Contractors:Self-operated drone fleets capturing direct control over aerial data workflows. Software-defined flight planning decentralizes operational control from centralized service providers, driving hardware and recurring software spend across mid-tier firms.
- Surveyors:Traditional geospatial professionals facing margin compression as contractors unbundle capture from engineering interpretation.
- Architects:Design-phase visualization and as-built verification supporting BIM integration workflows.
- Project Managers:Schedule and cost control applications leveraging time-series aerial documentation.
General contractors lead volumes today; project managers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor market entry strategies, with Shenzhen-based manufacturing clusters capturing hardware economics while US and EU operators absorb compliance-driven cost premiums. This divergence concentrates value capture in software and service layers across North American and European construction markets.
United States
FAA Part 107 mandates pilot certification and operational waivers that standardize fleet investments across Texas, California, and Florida DOT corridors. State-level infrastructure spending clusters in these regions now integrate drone surveying into mandatory pre-bid documentation. Houston and Dallas metropolitan contractors deploy multirotor configurations for earthwork quantification under progressive state-level drone integration policies.
Germany
EASA U-space framework implementation is forcing interoperability upgrades for detect-and-avoid systems serving construction corridors. German infrastructure consortia require C2 link redundancy and remote identification broadcast capability in procurement specifications. Bavarian and North Rhine-Westphalian construction clusters anchor equipment certification demand ahead of 2026 enforcement deadlines.
China
Shenzhen-based manufacturing concentration supplies multirotor and fixed-wing platforms to global distributors, though domestic construction demand concentrates in Yangtze River Delta megaprojects. MIIT standards for unmanned aerial systems shape export certification pathways. Shanghai and Guangzhou municipal infrastructure bureaus pilot swarm coordination algorithms for large-area surveying operations.
Australia
Mining reclamation contractors in Queensland and Western Australia adopt distributed flight patterns across agricultural-to-residential conversion projects. CASA regulations for beyond-visual-line-of-sight operations lag FAA and EASA frameworks, preserving third-party operator economics. Perth and Brisbane earthwork specialists deploy fixed-wing platforms for linear infrastructure corridor coverage.
Canada
Transport Canada RPAS regulations mandate visual-line-of-sight limitations that constrain linear infrastructure monitoring economics. Provincial infrastructure spending in Alberta and British Columbia drives demand for thermal imaging convergence with cold-climate construction workflows. Calgary and Vancouver metropolitan contractors unbundle aerial data capture from bundled engineering services.
Drone-Based Solutions in Construction Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software providers capturing recurring revenue pools while component suppliers compete on manufacturing scale. The vendor base concentrates around three strategic archetypes: manufacturing-scale platform vendors, autonomous navigation specialists, and cloud-native workflow providers. Consolidation pressure is accelerating through strategic partnerships between sensor manufacturers and flight planning software developers, alongside geographic expansion by Asia-Pacific hardware vendors into North American service channels.
Within the manufacturing-scale tier, SZ DJI Technology Co., Ltd. and Autel Robotics Co. Ltd. exemplify Shenzhen-based production concentration that supplies global hardware distribution networks. Skydio occupies a position among autonomous navigation specialists purpose-built for complex structural inspection workflows. DroneDeploy Inc. anchors the cloud-native archetype, representing the shift toward software-defined flight planning and direct SaaS relationships with general contractor fleets.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Skydio |
| Parrot Drones SAS |
| DroneDeploy Inc. |
| PrecisionHawk |
| 3DR, Inc. |
| Autel Robotics Co. Ltd. |
| Yuneec |
| Terra Drone Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price volatility cascades through Shenzhen battery cell manufacturers into tiered hardware pricing, compressing margins for North American distributors while accelerating subscription software bundling among mid-tier contractors seeking cost predictability.
Pricing Analysis
Distributor margins of 15-25 percent separate Shenzhen factory gates from US contractor procurement desks, with pricing stratifying across FAA-certified enterprise tiers, state-compliant mid-market bundles, and uncertified prosumer imports. Certification-driven price differentiation widens as EASA U-space deadlines approach, with German and French infrastructure consortia commanding premium interoperability pricing. Cost compression in entry-level multirotor tiers intensifies due to Shenzhen manufacturing scale, while general contractor fleets show lowest price sensitivity for integrated software-hardware subscriptions that reduce pilot training overhead.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Texas and California DOT contractors, while distributor networks serve fragmented regional earthwork specialists across Australia and Canada. Manufacturing concentrates in Shenzhen for airframes, South Korea for solid-state batteries, and Germany for precision LiDAR sensors. Raw material dependencies span lithium carbonate for cells, rare-earth magnets for motors, and gallium arsenide for thermal imagers. Single-source vulnerability in Shenzhen-based flight controller chip fabrication exposes North American distributors to MIIT export certification delays. Distribution runs through certified training providers bundling Part 107 compliance with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
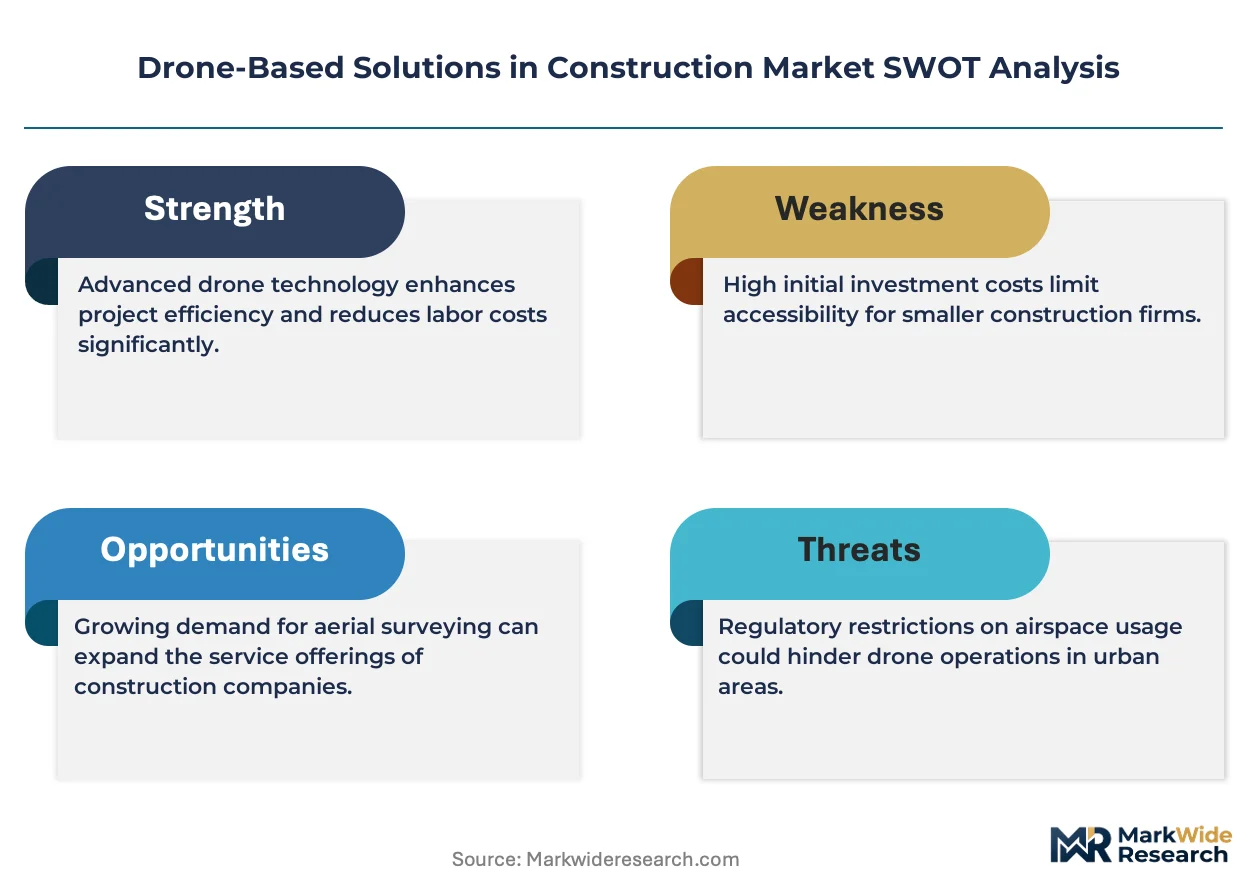
This market compounds value through regulatory layering, with FAA Part 107 recurrent training mandates and EASA U-space interoperability deadlines generating recurring revenue streams that outpace hardware transaction cycles.
For Market Incumbents: Deepen backward integration into LiDAR sensor calibration and cloud photogrammetry software stacks to defend against SaaS-native workflow providers disintermediating traditional survey partnerships. Fortify EU-type certification ahead of 2026 enforcement deadlines to exclude uncertified competitors from German and French public-sector tendering. Prioritize C2 link redundancy and remote identification broadcast capability as table-stakes procurement requirements. For New Entrants and Emerging Players: Equipment-as-a-service channel partners offer the lowest-friction entry path for specialty trade contractors seeking pay-per-flight-meter models without capital deployment. White-space concentrates in thermal-AI edge processing for real-time structural defect alerts during active construction phases, and in swarm coordination algorithms for Australian mining reclamation and Canadian agricultural conversion projects. Target direct SaaS subscriptions with Sun Belt general contractors unbundling capture from engineering interpretation. For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous navigation software specialists possessing purpose-built structural inspection stacks rather than manufacturing-scale hardware vendors facing Shenzhen cost compression. Long-term viability favors vendors achieving vertical integration across flight planning, edge processing, and project management suite connectivity. Watch FAA beyond-visual-line-of-sight waiver approval velocity as the inflection signal determining which service providers capture high-frequency linear infrastructure monitoring contracts.| Strategic Initiative | Industry Significance |
|---|---|
| EU-Type Certification Investment | EASA U-space interoperability locks out uncertified vendors from German and French public tenders. |
| Software-Defined Flight Planning Launch | DroneDeploy-style SaaS subscriptions disintermediate traditional survey firms in US Sun Belt markets. |
| LiDAR Sensor Miniaturization Partnership | Reduced payload weight extends multirotor endurance for vegetation-heavy Texas DOT earthwork sites. |
| Equipment-as-a-Service Channel Expansion | Pay-per-flight-meter models reduce capital barriers for specialty trade contractors entering inspection services. |
| Thermal-AI Edge Processing Integration | Onboard defect detection eliminates cloud latency for real-time structural integrity alerts. |
Methodological Framework
Bottom-up general contractor fleet modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with FAA-certified remote pilots, DOT procurement officers, cloud photogrammetry platform engineers, and construction safety directors inform demand-side assumptions. Secondary validation draws from FAA Part 107 certification databases, EASA U-space regulatory filings, state infrastructure spending appropriations, and Shenzhen customs export records. Triangulation between contractor-reported software subscription growth and distributor inventory movements ensures segmentation coherence.
Historical trendline analysis of multirotor versus fixed-wing deployment ratios, photogrammetry-to-LiDAR technology transitions, and self-operated fleet versus third-party service dependencies anchors the projection framework. Modeled dimensions span airframe architecture, imaging modality, end-user type, and regional regulatory cluster. CAGRs derive from segment-level growth rate synthesis rather than top-down scaling. Industry-specific inputs include FAA waiver approval rates, battery chemistry cost trajectories, and state-level infrastructure spending cluster densities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to beyond-visual-line-of-sight regulatory liberalization and lithium-ion cell price volatility. Base assumptions reflect current FAA Part 107 training mandate enforcement, EASA U-space interoperability deadlines, and Shenzhen manufacturing concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Excavator Market
Construction Equipment
Bale Openers Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market