
 Compact Track Loader Market | 2026-2036
Compact Track Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Track Loader Market Analysis
Equipment dealership networks across North America is fragmenting as manufacturers build direct-to-fleet digital sales platforms alongside traditional branch operations. Caterpillar leverages its captive finance arm to sustain dealer loyalty in contested territories. Komatsu competes through telematics-integrated fleet management contracts that extend beyond hardware transactions. John Deere anchors its position in agricultural-adjacent loader demand through shared powertrain platforms with its tractor lines.
A compact track loader is a rubber-tracked, skid-steer platform machine with operating loads typically spanning 1,000 to 3,200 pounds, engineered for traction on sensitive or uneven terrain where wheeled alternatives compact soil or lose grip. Its primary commercial purpose centers on material handling, excavation, and attachment-driven tasks across construction, agriculture, and landscaping workflows. Standard track loaders dominate volume shipments due to their versatility across mid-size job sites, while electric technology represents the fastest-expanding segment as fleet operators confront total-cost-of-ownership pressures and site-level emissions restrictions. Heavy-duty track loaders command the deepest margin pools in mining and forestry applications where durability premiums justify higher price points.
EPA Tier 4 Final standards govern diesel emissions thresholds and compel ongoing after-treatment investments from all manufacturers selling in the United States. OSHA workplace noise and rollover protective structure requirements shape cab design specifications and operator safety feature integration. The EU Machinery Directive and CE marking framework govern access for imported equipment across European member states. Stakeholders must monitor battery-electric platform development timelines and charging infrastructure readiness to time capital deployment decisions against evolving fleet decarbonization mandates.
Market Dynamics
The compact track loader market is undergoing structural transformation as fleet operators confront EPA Tier 4 Final after-treatment costs while simultaneously piloting battery-electric platforms for urban job sites with emissions restrictions.
Growth Catalysts
- Urban infill construction:Residential contractors in dense metropolitan areas are specifying rubber-tracked loaders for soil-sensitive landscaping and foundation work where wheeled equipment damages finished grades.
- Telematics integration:Equipment manufacturers are bundling fleet management software with hardware sales, creating recurring revenue streams and locking in operator training dependencies.
- OSHA rollover protection mandates:Updated workplace safety requirements are accelerating cab replacement cycles among smaller fleet operators who deferred upgrades during prior regulatory phases.
Market Restraints
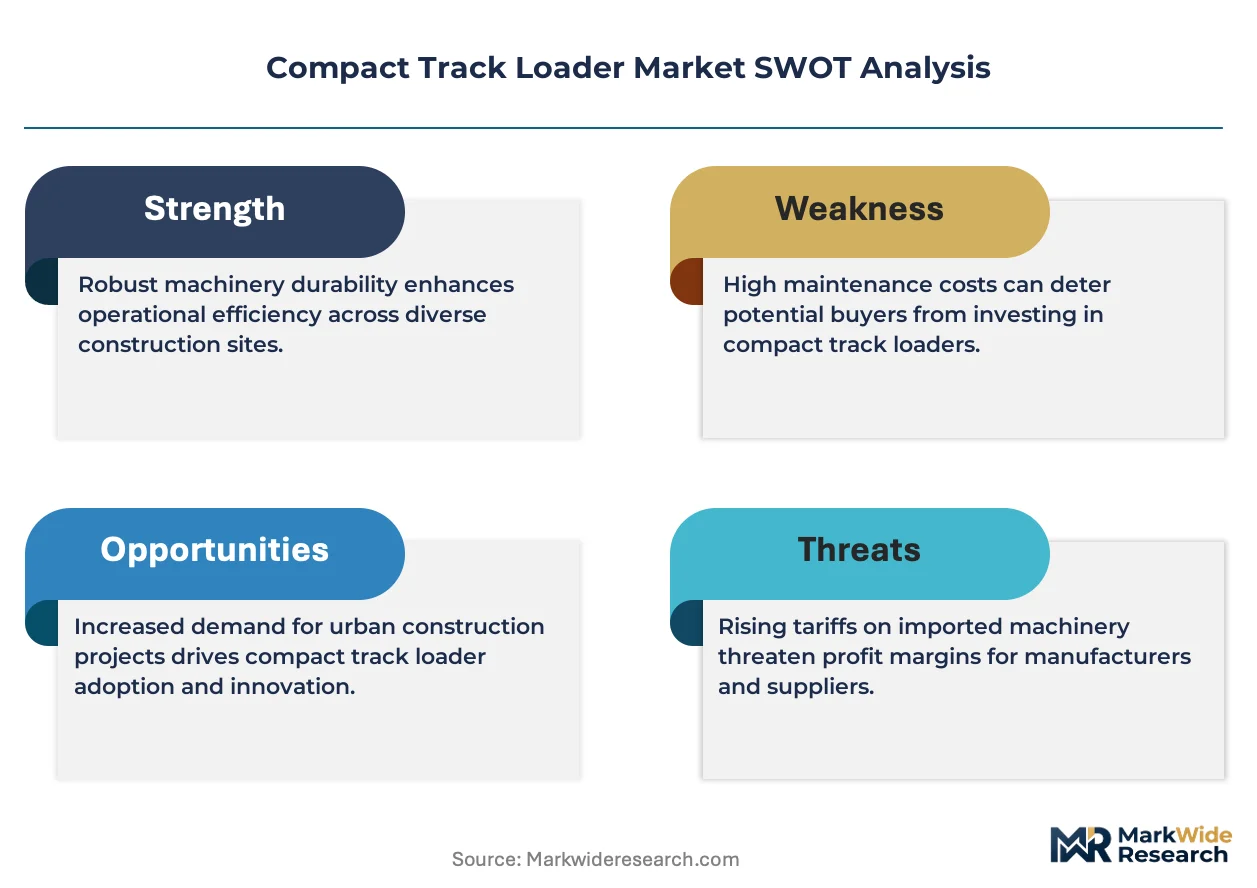
- Diesel after-treatment cost inflation:EPA-mandated selective catalytic reduction systems and diesel particulate filters now represent 15-20% of engine package costs, compressing margin pools for mid-size fleet buyers.
- Steel and rubber track supply concentration:Specialty track belt manufacturing clusters in Southeast Asia create vulnerability to regional logistics disruptions and input price volatility.
- Skid-steer loader substitution:Wheeled skid-steer alternatives with foam-filled tires are reclaiming share on hard-surface commercial sites where ground disturbance is not a constraint.
Strategic Opportunities
- Electric platform leasing models:Battery-electric track loader pilots in California and New York are demonstrating total-cost-of-ownership parity when charging infrastructure is bundled into municipal fleet contracts.
- Agricultural crossover applications:Shared powertrain architectures with tractor lines are opening livestock operations and dairy facilities to compact track loader attachments previously limited to construction.
- Direct-to-fleet digital sales:Manufacturers are bypassing traditional dealership networks for large national accounts, capturing customer data and reducing channel margin leakage.
Industry Challenges
- Electric technician skill gaps:Fleet maintenance departments lack personnel trained on high-voltage battery systems and thermal management diagnostics, forcing reliance on manufacturer service networks.
- Attachment standardization delays:Proprietary hydraulic quick-coupler designs across OEMs prevent interoperability, frustrating contractors who operate mixed fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Track Loader Market |
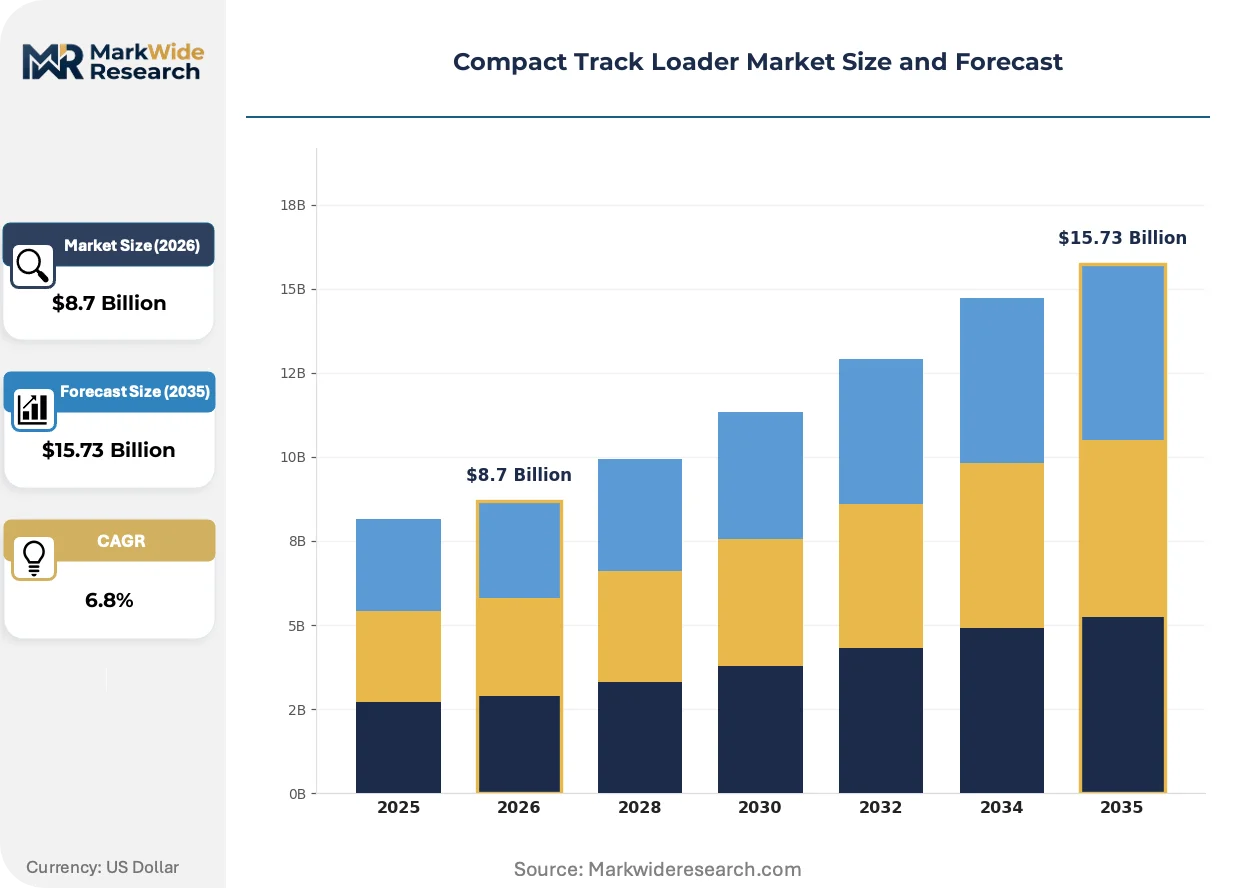
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Track Loaders, Standard Track Loaders, Heavy-duty Track Loaders, Multi-terrain Loaders End User: Construction, Agriculture, Landscaping, Snow Removal Deployment: On-Road, Off-Road, Rental, Sale Technology: Hydraulic, Electric, Diesel, Hybrid |
| Companies Covered | John Deere, Volvo, Caterpillar, New Holland, Komatsu, Kubota, JCB, Takeuchi, Bobcat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Track Loader Market Emerging Trajectories
Electrification architecture, emissions compliance automation, and procurement digitization are converging to redefine equipment lifecycle economics and channel relationships across the compact track loader value chain.
Battery-electric drivetrains with onboard fast-charging capability are rendering obsolete the diesel-electric hybrid transitional platforms that manufacturers introduced as Tier 4 Final stopgaps. Municipal fleet operators in emissions-restricted zones are specifying pure-electric units for urban infrastructure contracts. This shift is compressing residual value forecasts for late-model diesel inventory in coastal metropolitan markets.
EPA's evolving enforcement posture on tampering with emissions control systems is tightening field audit protocols and expanding manufacturer liability for owner-operator modifications. Dealership service departments are investing in diagnostic equipment to detect deleted after-treatment systems during routine maintenance. The rental fleet segment is most exposed, as short-term lessees represent elevated tampering risk and contract liability.
Consolidated national contractors are unbundling after-sales service from equipment acquisition, negotiating parts-direct agreements and third-party maintenance contracts that bypass traditional dealer service bays. This disintermediation is most advanced among landscaping and site preparation specialists operating standardized fleets above fifty units. Equipment financiers are adapting by collateralizing service revenue streams separately from hardware notes.
Compact Track Loader Market Segmentation
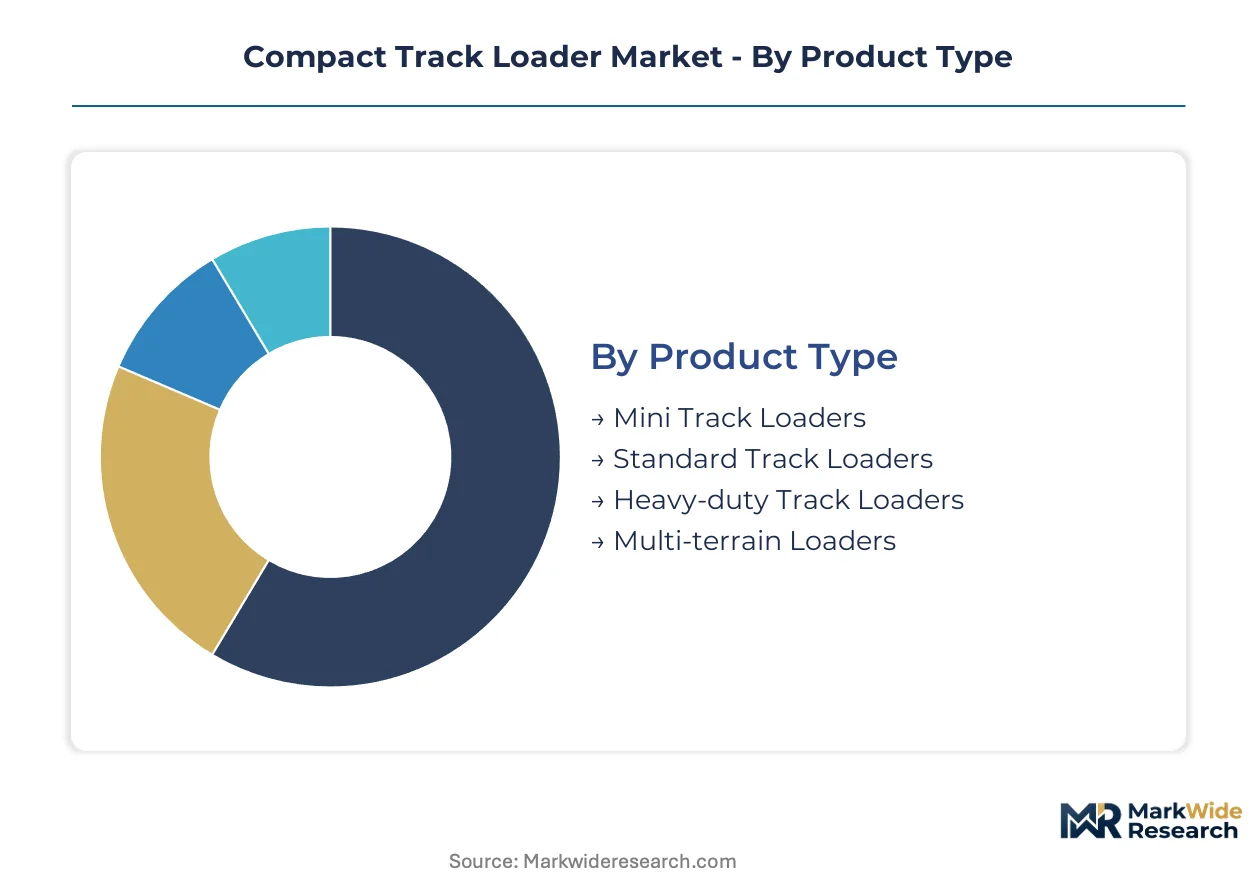
Compact track loader procurement patterns diverge sharply across operating environments, powertrain preferences, and ownership models. Fleet managers weight total-cost-of-ownership calculations differently when specifying equipment for urban infill versus agricultural crossover applications. Understanding these segment boundaries clarifies where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Physical specifications and rated operating capacity determine fleet suitability across job site constraints and attachment compatibility requirements.
- Standard Track Loaders:Mid-range platforms with operating loads between 1,500 and 2,700 pounds dominate volume shipments across general construction and landscaping workflows. Contractors in the United States specify these units for foundation work and material handling where soil sensitivity prohibits wheeled alternatives. EPA Tier 4 Final compliance costs are most acutely felt in this segment due to thin margin pools and price-sensitive mid-size fleet buyers.
- Heavy-duty Track Loaders:Reinforced undercarriage architectures and elevated lift arms support operating loads exceeding 3,000 pounds in mining overburden removal and forestry slash clearing. Demand concentrates in the Appalachian coal regions and Pacific Northwest timber operations where durability premiums justify acquisition cost spreads. Extended service intervals and proprietary track belt designs lock operators into manufacturer service networks.
- Mini Track Loaders:Sub-1,000-pound rated capacity units with stand-on operator stations penetrate residential landscaping and interior demolition where footprint constraints exclude conventional cabs.
- Multi-terrain Loaders:Suspended undercarriage systems with all-terrain track geometry address wetland remediation and coastal dune restoration projects requiring flotation over unstable substrates.
Standard track loaders command the established base. The steepest expansion runs through heavy-duty configurations as extraction operators replace aging fleets.
End User:
Application-specific duty cycles and attachment utilization rates create divergent equipment lifecycle economics across customer verticals.
- Construction:General contractors and site preparation specialists represent the dominant demand concentration, deploying loaders for excavation, grading, and material transport across commercial and residential building phases. Urban infill projects in dense metropolitan areas are specifying rubber-tracked units to protect finished landscaping and avoid soil compaction penalties. Telematics integration is becoming a standard procurement requirement among national contractors managing distributed fleets.
- Agriculture:Livestock operations and dairy facilities are adopting compact track loaders for feed handling, manure management, and barn cleaning tasks previously served by tractor-mounted implements. John Deere's shared powertrain architecture with its tractor lines accelerates penetration in agricultural-adjacent demand. Seasonal utilization patterns and corrosion exposure from animal waste accelerate replacement cycles versus construction applications.
- Landscaping:Municipal parks departments and commercial grounds maintenance contractors prioritize low ground pressure for turf protection and precision grading capabilities.
- Snow Removal:Regional equipment rental fleets in the Upper Midwest and Northeast deploy dedicated snow pusher configurations during winter peak demand periods.
Construction anchors volume procurement. Agricultural crossover applications are climbing the fastest as shared powertrain platforms reduce operator training barriers.
Deployment:
Ownership economics and utilization volatility shape whether fleet operators acquire equipment outright or access through third-party providers.
- Sale:Direct equipment acquisition remains predominant among contractors with predictable utilization above 1,200 annual hours and established maintenance capabilities. National landscaping chains and regional site preparation specialists are negotiating direct-to-fleet digital sales agreements that bypass traditional dealership margins. Financiers are collateralizing hardware notes separately from service revenue streams as procurement patterns unbundle.
- Rental:Short-term equipment access addresses seasonal demand spikes, project-specific requirements, and fleet gap coverage during maintenance intervals. The rental segment faces elevated EPA enforcement exposure for emissions control tampering by short-term lessees. Rental fleet operators are investing in diagnostic equipment to detect deleted after-treatment systems during routine service.
- On-Road:Street-legal configurations with lighting packages and speed limiters serve utility contractors and municipal infrastructure maintenance.
- Off-Road:Unrestricted site-only deployments dominate mining, quarry, and landfill applications where transport between job sites occurs via lowboy trailer.
Sale transactions command the established base. Rental penetration is expanding most quickly as contractors seek balance sheet flexibility and utilization optimization.
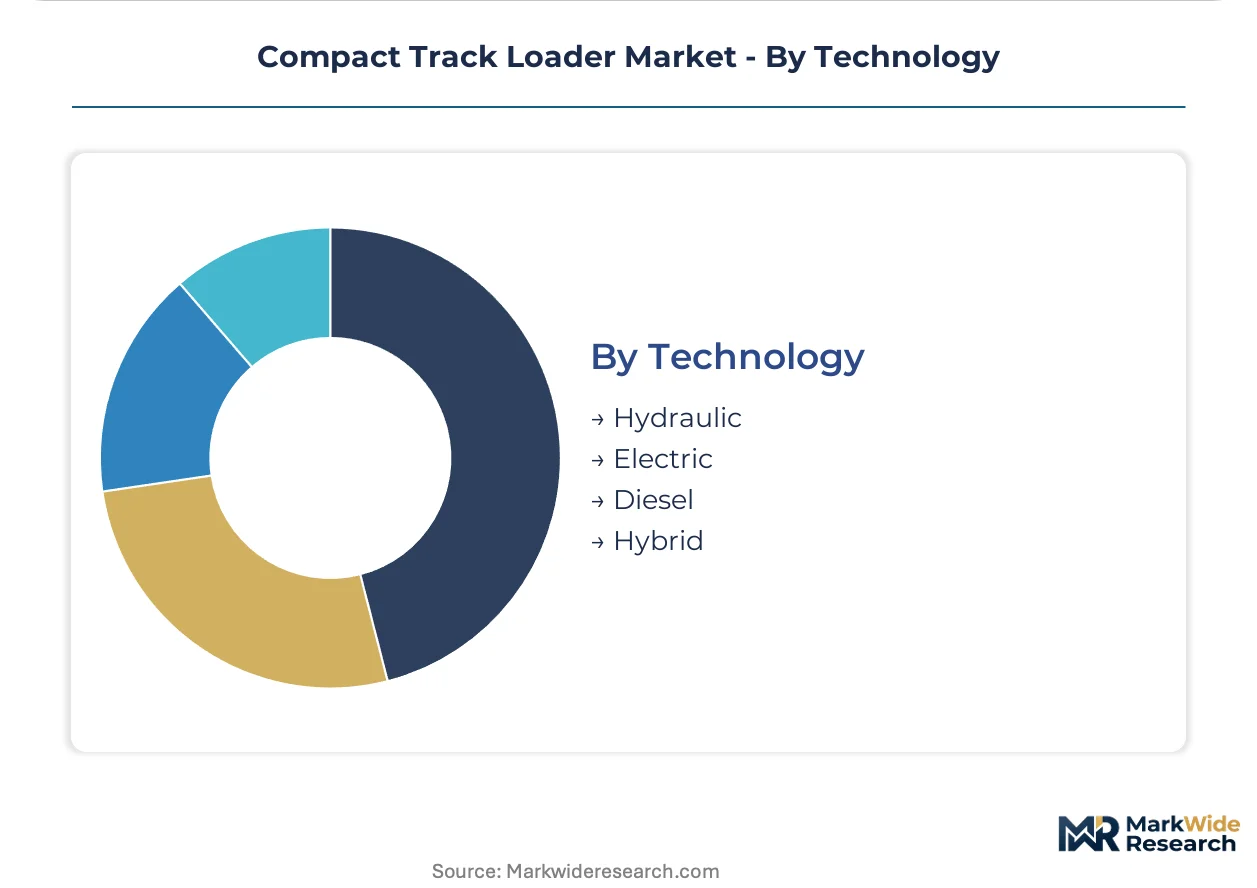
Technology:
Powertrain architecture selection reflects regulatory compliance costs, site-level emissions restrictions, and total-cost-of-ownership calculations across operating duty cycles.
- Electric:Battery-electric drivetrains with onboard fast-charging capability are displacing transitional diesel-electric hybrid platforms introduced as Tier 4 Final stopgaps. Municipal fleet operators in California and New York are specifying pure-electric units for urban infrastructure contracts with emissions restrictions. Residual value compression for late-model diesel inventory in coastal metropolitan markets is accelerating electric transition timelines.
- Diesel:Compression-ignition engines with selective catalytic reduction and diesel particulate filter after-treatment remain predominant in high-utilization applications and regions without charging infrastructure. After-treatment systems now represent 15-20% of engine package costs, compressing affordability for mid-size fleet buyers. Field audit protocols for emissions control tampering are tightening manufacturer liability exposure.
- Hydraulic:Open-center and load-sensing hydraulic architectures govern attachment responsiveness and fuel efficiency across all powertrain categories.
- Hybrid:Diesel-electric hybrid configurations are retreating to niche applications as battery-electric platforms achieve total-cost-of-ownership parity in suitable duty cycles.
Diesel powertrains command the established base. Battery-electric platforms are gaining share fastest where charging infrastructure and municipal procurement mandates converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system underwrites North American equipment distribution, while the Rhine-Alpine rail corridor shapes European machinery logistics. Pacific port throughput in Shanghai and Busan governs component sourcing timelines for Asian manufacturing clusters.
United States
Residential construction contractors in Dallas-Fort Worth and Phoenix are specifying rubber-tracked loaders for soil-sensitive foundation work. EPA Tier 4 Final enforcement is tightening field audit protocols for emissions control tampering across rental fleets. The Upper Midwest snow removal corridor from Minneapolis to Milwaukee drives seasonal demand spikes for dedicated pusher configurations.
Germany
Bavarian quarry operators are replacing aging fleets with reinforced undercarriage units for overburden removal. The EU Machinery Directive and CE marking framework govern equipment access across member states. Stuttgart's automotive supplier ecosystem is piloting battery-electric platforms for factory logistics applications with emissions restrictions.
China
Yangtze River Delta infrastructure contractors are deploying compact track loaders for wetland remediation and coastal dune restoration. The Ministry of Ecology and Environment's dual carbon goals are accelerating electric platform development timelines. Zhengzhou's machinery manufacturing cluster is expanding track belt production capacity for domestic and export markets.
Japan
Tokyo metropolitan area urban infill projects are specifying low ground pressure equipment for finished grade protection. METI industrial standards shape hydraulic system specifications and attachment interoperability requirements. Osaka-Kobe port logistics operations are integrating telematics-enabled fleet management for distributed equipment tracking.
Australia
Queensland mining contractors are sourcing heavy-duty configurations for overburden removal in coal regions. The country's national workplace safety regulator mandates rollover protective structures and operator restraint systems. Perth's resource extraction equipment hub is servicing replacement cycles across Western Australian iron ore operations.
Compact Track Loader Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hydraulic architectures and track belt assemblies. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive finance arms, agricultural machinery crossovers leveraging shared powertrain platforms, and pure-play construction equipment specialists. Consolidation pressures are intensifying as manufacturers pursue direct-to-fleet digital channels and telematics-integrated service contracts.
Within the diversified industrial tier, Caterpillar and Komatsu occupy positions anchored by captive financing and fleet management ecosystems. John Deere exemplifies the agricultural crossover archetype, leveraging shared powertrain architectures with tractor lines to penetrate livestock and dairy facility applications. These three manufacturers represent distinct competitive vectors: finance-driven loyalty programs, telematics-enabled service bundling, and vertical integration into adjacent machinery categories.
| Leading Market Players |
|---|
| John Deere |
| Volvo |
| Caterpillar |
| New Holland |
| Komatsu |
| Kubota |
| JCB |
| Takeuchi |
| Bobcat |
| Others |
Supply Flow & Price Mechanics
Tariff exposure between Southeast Asian track belt manufacturing clusters and North American assembly plants determines both three-tier pricing spreads across premium, standard, and economy equipment tiers and the geographic distribution of component sourcing. Steel and rubber compound price volatility feeds directly into margin compression for mid-size fleet buyers while reinforcing manufacturer incentives to consolidate supplier relationships.
Pricing Analysis
Volume-discount tiering structures separate national fleet accounts from regional contractors and small landscaping operators. Premium pricing attaches to telematics-integrated packages and extended warranty coverage, while economy tiers strip after-sales service to hit acquisition cost targets. Cost compression in the standard tier is intensifying because EPA Tier 4 Final after-treatment systems now absorb 15-20% of engine package costs. Regional contractors with 50-150 unit fleets exhibit the sharpest price sensitivity, whereas mining operators in Appalachia accept durability premiums with minimal negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for track belt and hydraulic component procurement. Specialty rubber track manufacturing concentrates in Thailand, Vietnam, and Indonesia, with steel undercarriage forgings sourcing from South Korea and Japan. The supply chain rests on synthetic rubber feedstocks and high-strength alloy steel grades vulnerable to commodity price swings. Distribution runs through manufacturer-authorized dealer networks, though direct-to-fleet digital channels are capturing national account volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compact track loader market sits in early-cycle recovery as residential construction permit activity accelerates and deferred fleet replacement demand releases. Equipment procurement patterns are normalizing after inventory destocking phases.
For Market Incumbents: Insulate service revenue streams from hardware margin erosion by expanding telematics-enabled fleet management contracts that lock operator training dependencies. Deepen backward integration into rubber track belt production to reduce Southeast Asian supply concentration exposure. Capture national landscaping chains through direct-to-fleet digital sales agreements that bypass traditional dealer margins. For New Entrants and Emerging Players: Build out battery-electric platform offerings targeting municipal fleet operators in California and New York with emissions restrictions and charging infrastructure partnerships. Agricultural crossover applications in livestock operations represent the most penetrable white space, leveraging shared powertrain architectures with tractor lines. Pursue equipment-as-a-service leasing models that bundle maintenance and charging access. For Investors and Strategic Acquirers: The market sits at a replacement-cycle upturn phase that favors aftermarket service specialists and electric drivetrain technology providers. Acquisition targets should demonstrate installed base density in coastal metropolitan markets where diesel residual value compression accelerates electric transition timelines. Monitor battery-electric platform total-cost-of-ownership parity announcements as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Creates recurring revenue streams and locks operator training dependencies beyond hardware transactions. |
| Backward Integration into Track Manufacturing | Reduces Southeast Asian supply concentration and captures margin from rubber compound to finished belt. |
| Electric Platform Leasing Models | Addresses municipal procurement mandates in California and New York with bundled charging infrastructure. |
| Direct-to-Fleet Digital Sales Channel | Bypasses dealer margin leakage and captures customer data from national landscaping contractors. |
| Agricultural Powertrain Sharing | Accelerates penetration into livestock operations through shared architectures with tractor lines. |
Methodological Framework
A spread of perspectives from equipment fleet managers, OEM procurement directors, dealership service heads, and aftermarket parts distributors converged on the working assumptions driving this analysis. Primary field interviews with maintenance directors and plant engineers at construction and agricultural operations were cross-validated against secondary sources including EPA enforcement disclosures, customs trade data on track belt imports, and SEC filings from diversified industrial manufacturers. Bottom-up unit shipment estimates by powertrain type and end-use vertical were triangulated against top-down equipment finance origination data.
Demand-supply balance dynamics across operating load categories and regional construction permit flows anchored the forecast framework. Segmentation dimensions modeled include product type, end-use vertical, deployment mode, and powertrain technology across the projection horizon. CAGRs were derived from fitted growth curves incorporating equipment replacement cycle timing, regulatory compliance cost trajectories, and electric platform adoption elasticity. Forecast inputs included regional diesel-electric total-cost-of-ownership crossover analysis and municipal fleet electrification mandate schedules.
Stress conditions across steel and rubber commodity price bands, tariff rate scenarios, and electric charging infrastructure buildout timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EPA enforcement posture and battery technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Jackhammer Market
Construction Equipment
Part Feeder Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Bale Openers Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Plasma Welding Machine Market