
 Bucket Teeth and Tips Market | 2026-2036
Bucket Teeth and Tips Market Size, Share, and Industry Trends Forecast 2026-2036
Bucket Teeth and Tips Market Outlook
Premium alloy specification upgrades is redrawing competitive boundaries in ground-engaging tools. Caterpillar leverages captive metallurgy R&D to sustain margins on high-wear applications. Komatsu anchors its position through integrated supply chains spanning foundry operations to final assembly. ESCO Corporation differentiates via proprietary tooth-and-adapter systems that reduce field changeout downtime.
Bucket teeth and tips are hardened steel or tungsten carbide components affixed to excavator buckets, loader buckets, and dozer blades to penetrate, fracture, and transport earth, rock, and debris under extreme abrasive stress; manufacturers typically achieve hardness ratings between 450 and 700 Brinell through controlled quench-and-temper cycles or overlay welding with chromium carbide deposits. Excavator teeth command the largest volume share due to universal deployment across construction and mining fleets, while tungsten carbide inserts represent the fastest-expanding material category as operators prioritize interval-between-replacement over upfront unit cost. Mining companies generate the deepest margin pools among end users because their continuous-operation models penalize unplanned downtime more severely than intermittent construction schedules.
FDA oversight applies indirectly through occupational safety linkages to equipment operator exposure, while ISO 9001 and ISO 14001 certifications function as de facto market access filters for tier-one OEM procurement teams across North America, Europe, and Asia-Pacific. China's GB standards for construction machinery set domestic minimums that increasingly align with ISO hardness specifications, compressing export opportunities for uncertified regional foundries. Stakeholders must monitor how EU machinery directive revisions on repairability and spare parts availability reshape aftermarket channel economics for independent tooth suppliers.
Market Dynamics
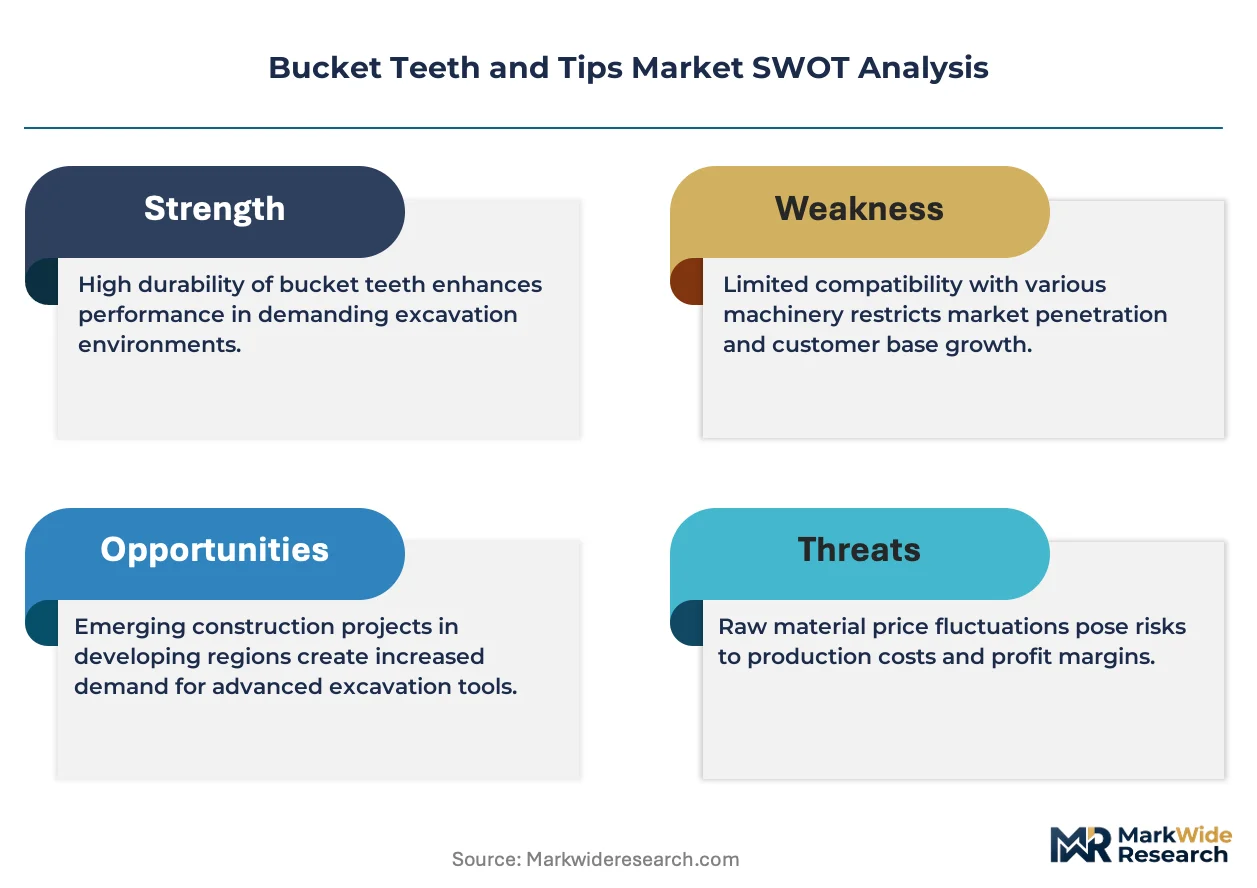
Alloy formulation upgrades are compressing margins for commodity-grade suppliers while rewarding metallurgical specialists capable of delivering 600+ Brinell hardness ratings under ISO 9001 protocols.
Growth Catalysts
- EU machinery directive revisions:Repairability mandates on spare parts availability are accelerating aftermarket channel formalization across European mining and construction fleets.
- Tungsten carbide insert penetration:Underground hard-rock mining operators in Chile and Australia are prioritizing interval-between-replacement metrics over unit procurement costs.
- China's construction equipment clusters:Domestic OEM captive production of wear-resistant ground-engaging tools is absorbing regional foundry capacity.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when alloy-grade scrap spreads widen against pig iron benchmarks.
- Supply concentration in Shandong Province:Overreliance on Chinese foundry networks exposes procurement teams to logistics disruptions during environmental compliance inspections.
- Technical limitation in overlay welding:Chromium carbide deposit consistency remains difficult to replicate at scale below 500 Brinell thresholds.
Strategic Opportunities
- Underpenetrated Indonesian mining:Nickel laterite extraction expansion creates demand for corrosion-resistant tooth formulations adapted to tropical humidity cycles.
- Remanufacturing regulatory tailwinds:EU circular economy action plan incentives are legitimizing re-tipping services as OEM-warranty-compliant alternatives.
- Digital inventory convergence:RFID-enabled tooth tracking systems are merging with fleet telematics platforms to automate replacement scheduling.
Industry Challenges
- Weld metallurgist scarcity:Qualified technicians capable of certifying 700 Brinell overlay deposits command premium compensation in North American mining districts.
- ISO 14001 certification timelines:Foundries in emerging supply markets face 18-24 month compliance gaps that freeze tier-one OEM qualification pathways.
- Legacy adapter incompatibility:Proprietary tooth-and-adapter geometries from established suppliers lock aftermarket competitors out of installed base maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bucket Teeth and Tips Market |
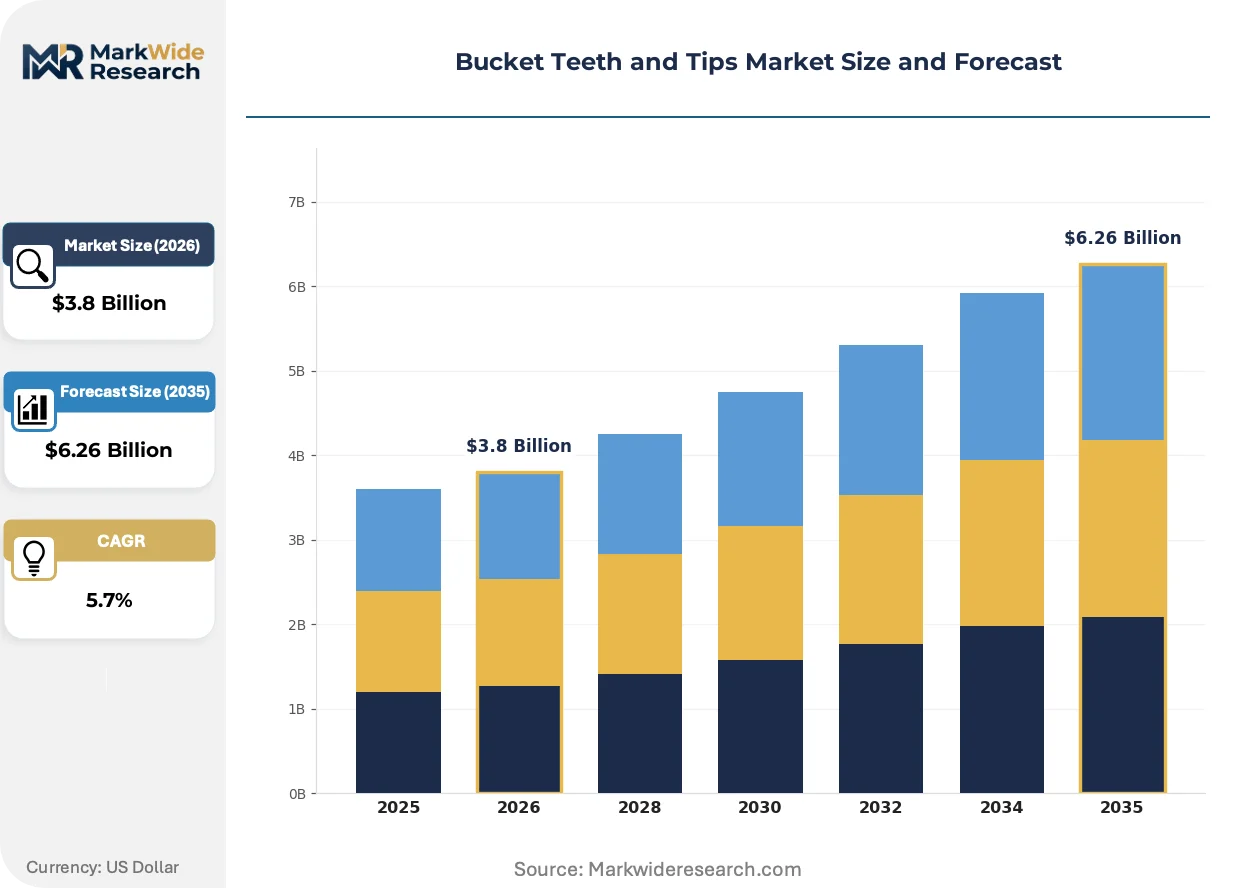
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavator Teeth, Loader Teeth, Dozer Blades, Grader Blades Material: Hardox Steel, Alloy Steel, Carbon Steel, Tungsten Carbide Application: Construction, Mining, Waste Management, Demolition End User: Contractors, Mining Companies, Waste Management Firms, Equipment Rental Services |
| Companies Covered | Hensley Industries, Volvo Construction Equipment, Caterpillar, H & L Tooth Company, Hitachi Construction Machinery, Komatsu, MTG Systems, XCMG, ESCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bucket Teeth and Tips Market Strategic Shifts
Material science advances and regulatory pressure on equipment lifecycle accountability are converging to transform how ground-engaging tools are specified, procured, and retired.
Composite steel-carbide hybrid teeth are displacing monolithic forged designs in high-impact mining applications. Rio Tinto and BHP fleet managers specify these configurations for Pilbara iron ore operations where rock hardness exceeds 250 MPa compressive strength. The shift is compressing demand for conventional quench-and-temper forgings in premium wear segments.
REACH authorization requirements on hexavalent chromium compounds are forcing reformulation of hardfacing weld consumables across European foundry networks. Suppliers are migrating to tungsten-carbide and complex boride alternatives that maintain deposit hardness without restricted substance content. German and Polish mining contractors report 12-15% cost premiums on compliant overlay materials.
Buyer consolidation through mining fleet centralization is compressing supplier count per procurement category. Anglo American and Glencore technical teams now mandate dual-source qualification for critical ground-engaging components, reducing viable vendor pools. South African platinum belt operations exhibit the most aggressive consolidation, with three contractors controlling 70% of tooth specification authority.
Bucket Teeth and Tips Market Segmentation
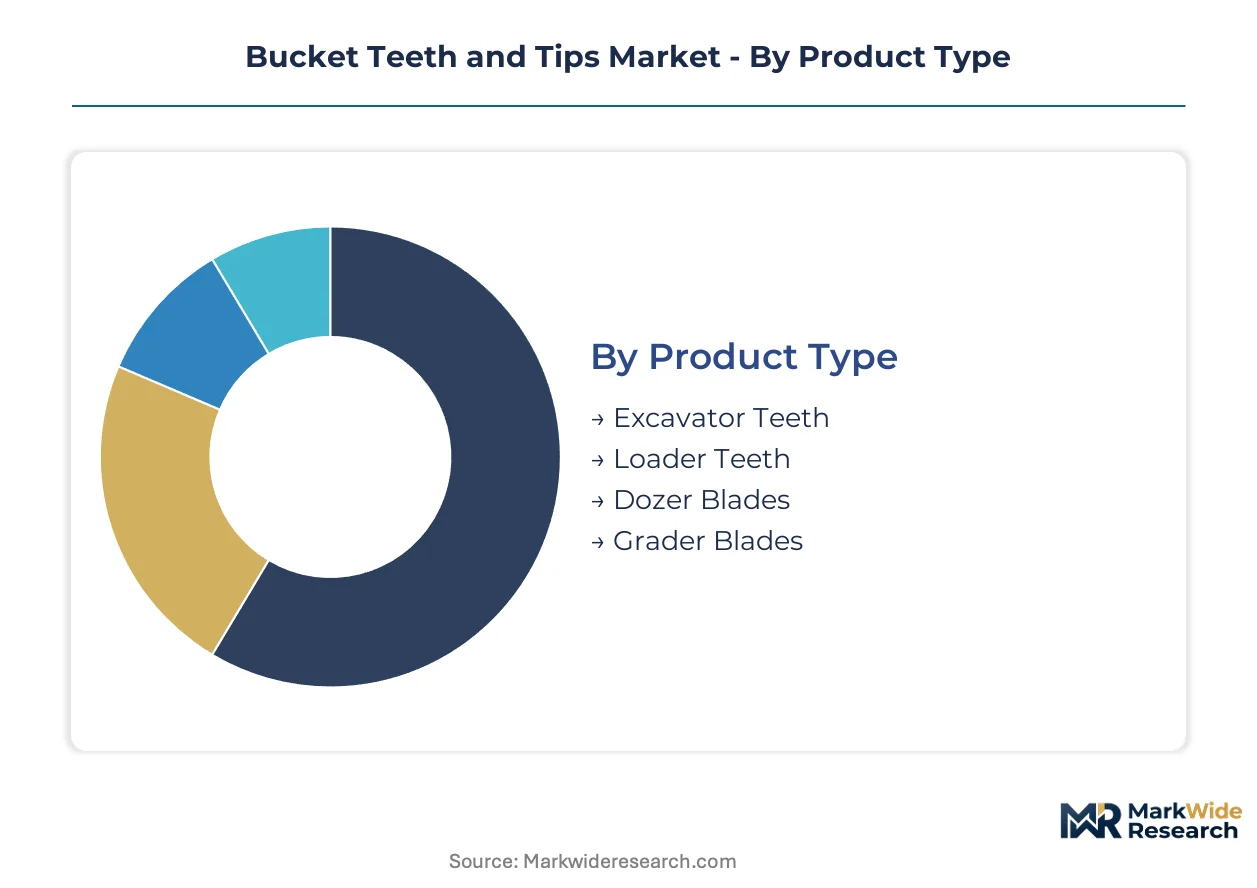
Ground-engaging tools fragment across four intersecting dimensions that determine procurement logic. Product geometry dictates wear patterns and replacement intervals. Material specification separates price-driven construction fleets from uptime-sensitive mining operations.
Product Type:
Margin pools concentrate in excavator teeth due to universal fleet deployment and premium alloy upgrade rates across mining contractors.
- Excavator Teeth:These forged or cast steel components attach to bucket lips via pin-and-retainer systems, with hardness specifications ranging from 450 to 700 Brinell depending on rock abrasiveness. Australian iron ore operators in the Pilbara region specify composite steel-carbide hybrids for compressive strengths exceeding 250 MPa, compressing demand for conventional forgings in premium segments.
- Loader Teeth:Designed for high-impact loading cycles in surface mining and quarry operations, loader teeth prioritize fracture resistance over maximum hardness. Chilean copper mines favor through-hardened alloy formulations that withstand repetitive shock loading without catastrophic failure.
- Dozer Blades:These edge components require balanced hardness and toughness profiles for push-loading and ripping applications across construction and mining sites.
- Grader Blades:Long cutting edges for road maintenance and fine-grading operations prioritize uniform wear distribution over extreme hardness ratings.
The dominant share belongs to Excavator Teeth, while Loader Teeth is closing the gap fastest in surface mining procurement specifications.
Material:
Cost tiers separate commodity carbon grades from metallurgical specialties commanding 40-60% price premiums.
- Tungsten Carbide:Sintered carbide inserts deliver 600-800 Brinell equivalent hardness for interval-between-replacement optimization. Underground hard-rock operators in Chile and Australia accept 25-35% upfront cost premiums to reduce changeout frequency in confined shaft environments.
- Hardox Steel:Quench-and-tempered wear plate derivatives offer 400-500 Brinell hardness with superior weldability for field repair. European construction fleets specify Hardox grades to satisfy EU machinery directive repairability mandates without full component replacement.
- Alloy Steel:Nickel-chromium-molybdenum formulations achieve controlled through-hardening for balanced toughness in impact applications.
- Carbon Steel:Standard grades serve price-sensitive demolition and general construction where replacement frequency matches equipment rental cycles.
Tungsten Carbide commands the steepest expansion trajectory as mining operators prioritize total cost of ownership over procurement unit economics.
Application:
Volume concentrates in construction, yet mining applications generate the deepest margin pools through specification complexity.
- Mining:Continuous-operation models penalize unplanned downtime severely, driving specification toward 600+ Brinell grades and captive supplier relationships. Anglo American and Glencore technical teams mandate dual-source qualification for critical ground-engaging components, reducing viable vendor pools.
- Construction:Intermittent equipment utilization and project-based procurement favor standard alloy grades with rapid aftermarket availability. China's construction equipment manufacturing clusters absorb regional foundry capacity through domestic OEM captive production.
- Waste Management:Municipal and industrial landfill operations require corrosion-resistant formulations for exposure to leachate and variable debris composition.
- Demolition:Impact-focused applications prioritize fracture resistance over maximum hardness for concrete and rebar processing.
Construction maintains volume leadership, while Mining is gaining specification authority fastest through fleet centralization and technical standardization.
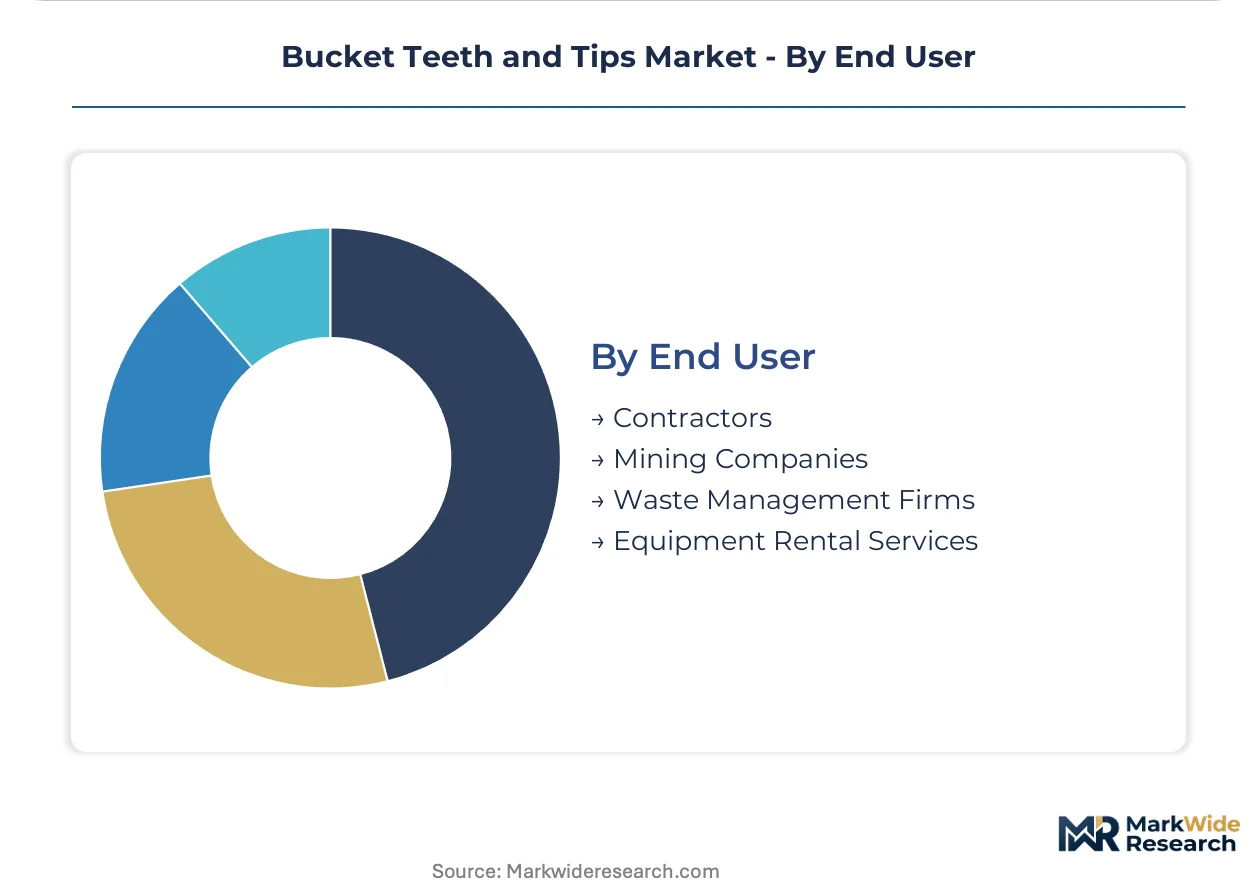
End User:
Customer type determines procurement channel structure and price sensitivity thresholds.
- Mining Companies:Technical specification authority resides with centralized procurement teams that negotiate multi-year supply agreements. South African platinum belt operations exhibit aggressive consolidation, with three contractors controlling specification authority for 70% of regional demand.
- Contractors:Project-based purchasing favors distributor networks and rapid fulfillment over metallurgical optimization. Indonesian nickel laterite extraction contractors represent emerging demand for corrosion-resistant formulations adapted to tropical humidity cycles.
- Waste Management Firms:Municipal procurement cycles and lifecycle cost modeling drive specification toward standardized grades with predictable replacement intervals.
- Equipment Rental Services:Fleet utilization metrics and damage liability structures favor replaceable consumables over premium long-life formulations.
Mining Companies anchor premium segment demand, while Equipment Rental Services is expanding procurement scale fastest through fleet aggregation across North American and European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity clusters heavily in Shandong Province, exposing procurement networks to environmental compliance disruptions. Australian iron ore operators and Chilean copper mines anchor demand for premium alloy formulations. Regulatory divergence across mining jurisdictions is fragmenting specification standards.
Australia
Pilbara iron ore operators specify composite steel-carbide hybrids for rock hardness exceeding 250 MPa. TGA-equivalent mining safety protocols mandate certified metallurgical documentation for underground applications. Perth-based procurement teams coordinate fleet standardization across BHP and Rio Tinto operations.
Chile
Underground hard-rock copper miners prioritize tungsten carbide inserts to minimize confined-space changeout frequency. National mining regulator Sernageomin enforces equipment certification for subterranean deployments. Antofagasta and Calama districts concentrate specification authority for Codelco and Anglo American contracts.
China
Domestic OEMs in Xuzhou and Changzhou manufacturing clusters scale captive production of wear-resistant ground-engaging tools. MIIT-administered GB standards for construction machinery align increasingly with ISO hardness specifications. Shandong Province foundries supply regional construction equipment manufacturers while facing intensifying environmental inspections.
Germany
REACH authorization requirements on hexavalent chromium compounds force hardfacing consumable reformulation across Ruhr Valley foundry networks. KBA-equivalent machinery safety inspections validate repairability compliance under EU directives. Dortmund and Essen districts host specialized overlay welding contractors serving European mining contractors.
United States
Appalachian coal operators and Arizona copper mines drive specification toward 600+ Brinell grades for continuous-operation uptime. OSHA mining safety enforcement creates documentation requirements for ground-engaging component traceability. Peoria and Milwaukee industrial corridors concentrate aftermarket distribution networks for North American fleet maintenance.
Bucket Teeth and Tips Market Competitive Environment
Concentration sits with integrated OEMs commanding captive metallurgy capabilities and proprietary adapter geometries. The vendor base stratifies across three tiers: global equipment manufacturers with in-house foundry operations, specialized ground-engaging tool suppliers with proprietary locking systems, and regional fabricators serving price-sensitive construction segments. Strategic moves center on backward integration into alloy formulation and geographic expansion through distributor network acquisition.
Among integrated equipment manufacturers, Caterpillar, Komatsu, and Hitachi Construction Machinery exemplify the captive-production archetype. These entities control specification authority through proprietary tooth-and-adapter interfaces that constrain aftermarket access. ESCO Corporation and Hensley Industries occupy positions as specialized suppliers with differentiated locking technologies. MTG Systems represents the European specialist tier with focused ground-engaging portfolios. XCMG anchors Chinese domestic OEM expansion into wear-resistant component manufacturing.
| Leading Market Players |
|---|
| Hensley Industries |
| Volvo Construction Equipment |
| Caterpillar |
| H & L Tooth Company |
| Hitachi Construction Machinery |
| Komatsu |
| MTG Systems |
| XCMG |
| ESCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of inventory cover among Australian mining procurement teams signals supply-chain rigidity that amplifies pricing power for ISO 9001-certified foundries while squeezing commodity-grade competitors. This lead-time exposure concentrates buyer leverage with metallurgical specialists capable of certifying 600+ Brinell deposits under compressed delivery windows.
Pricing Analysis
EU machinery directive repairability mandates dictate the pricing tier structure across European aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates captive OEM tooth-and-adapter systems from independent suppliers and uncertified regional fabricators. Pricing pressure stems from scrap steel volatility compressing electric arc furnace margins. Construction contractors exhibit highest price sensitivity due to project-based procurement cycles, while mining operators prioritize interval-between-replacement metrics over unit economics.
Supply Chain Analysis
China and Australia anchor foundry capacity and mining demand respectively. Shandong Province foundries feed regional OEM captive production while Pilbara iron ore operators specify composite steel-carbide hybrids. Raw material flows draw from alloy-grade scrap networks, tungsten carbide feedstock, and chromium carbide welding consumables. Single-source vulnerability concentrates in Shandong environmental compliance inspections. Distribution runs through OEM-authorized service networks and independent aftermarket distributors serving construction fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified weld metallurgists capable of certifying 700 Brinell overlay deposits command premium compensation across North American mining districts, creating a chokepoint that constrains tier-one OEM supplier qualification pathways. This capability scarcity rewards backward integration strategies and long-term technical talent development.
For Market Incumbents: Consolidate metallurgical certification advantages by locking in ISO 14001-compliant foundry partnerships before emerging-market competitors close compliance gaps. Defend against proprietary adapter geometry lockout by licensing tooth-and-adapter interfaces to selective aftermarket distributors. Prioritize captive R&D in tungsten carbide hybrid formulations to maintain margin separation from commodity-grade competitors. For New Entrants and Emerging Players: Lead with corrosion-resistant tooth formulations targeting Indonesian nickel laterite extraction expansion, where tropical humidity cycles degrade standard alloy specifications. Penetrate the remanufacturing segment by positioning re-tipping services as EU-warranty-compliant alternatives to full replacement. Pursue digital inventory convergence partnerships with fleet telematics platforms to automate replacement scheduling and bypass entrenched distribution channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mining fleet centralization compresses supplier count per procurement category while ISO certification timelines freeze tier-one qualification pathways for unqualified entrants. Target specialized ground-engaging tool suppliers with proprietary locking technologies and established dual-source relationships with Anglo American or Glencore technical teams. Watch for inflection signals in EU circular economy action plan implementation legitimizing remanufacturing channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Formulation | Captive metallurgy R&D insulates margins from scrap steel volatility and quality certification gaps. |
| Proprietary Tooth-and-Adapter System Development | ESCO-style locking geometries lock aftermarket competitors out of installed base maintenance revenue. |
| RFID-Enabled Tooth Tracking Integration | Fleet telematics convergence automates replacement scheduling and deepens customer data ownership. |
| Remanufacturing Service Expansion | EU circular economy incentives legitimize re-tipping as OEM-warranty-compliant aftermarket alternatives. |
| Indonesian Market Entry with Corrosion-Resistant Formulations | Nickel laterite extraction expansion creates first-mover advantage in tropical humidity-adapted alloys. |
Study Parameters
A spread of perspectives from mining procurement directors, foundry operations managers, OEM technical specification teams, and aftermarket distribution heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews across Australian Pilbara operations, Chilean Antofagasta mining districts, and Shandong Province manufacturing clusters with secondary validation from SEC filings of listed equipment manufacturers, customs trade data on alloy steel imports, and EU machinery directive implementation guidance documents. Bottom-up volume builds across product type, material specification, application, and end-user segments triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled include product geometry, metallurgical grade tier, end-use application intensity, and customer procurement channel structure across the analysis window. CAGRs derive from regression analysis against mining fleet utilization rates, construction equipment production indices, and alloy formulation adoption curves. Industry-specific forecast inputs incorporate tungsten carbide insert penetration rates in underground hard-rock operations and environmental inspection frequency impacts on Shandong foundry output.
The analysis sits within stated boundaries; outcomes outside sustained mining capital expenditure cycles or abrupt REACH authorization enforcement on hexavalent chromium compounds would require recalibration. Forecasts reflect documented assumptions on scrap steel price band stability and OEM captive production expansion rates in Chinese manufacturing clusters. Recalibration cycles align with material shifts in EU machinery directive repairability mandates and ISO 14001 certification timeline compression in emerging supply markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Jackhammer Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Trenchers Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
United States Crane Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market