
 Street Washer Machine Market | 2026-2036
Street Washer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Street Washer Machine Market Outlook
Steel chassis construction is shifting toward high-strength aluminum alloys in street washer machine fabrication, reducing curb weight and improving fuel efficiency across municipal fleets. Nilfisk leverages its Nordic engineering heritage to anchor premium electric product lines in European cities. Kärcher competes through backward integration into pump system manufacturing, controlling critical component costs. Tennant Company specializes in water recycling technology, differentiating its offering in drought-prone North American markets.
A street washer machine is a specialized municipal vehicle equipped with high-pressure spray systems, vacuum recovery, and debris collection mechanisms designed for surface cleaning of roads, sidewalks, and public plazas. Operating pressures typically range from 150 to 250 bar with water tank capacities between 3,000 and 12,000 liters depending on chassis configuration. Electric product types are capturing expanding share as battery costs decline and charging infrastructure proliferates in urban cores. Water recycling technology commands premium positioning by reducing freshwater consumption and enabling compliance with tightening discharge regulations. Municipal end users represent the dominant demand pool, though private contractors are gaining traction through service outsourcing arrangements with budget-constrained local governments.
EPA emissions standards for off-road diesel engines in the United States are accelerating electric platform development, while EU Green Deal targets and F-Gas Regulation in Europe mandate refrigerant-free thermal systems. China's MIIT dual carbon goals are pushing domestic manufacturers toward hybrid drivetrain adoption. Stakeholders must monitor regulatory divergence across these jurisdictions to optimize platform architecture and avoid redundant certification investments.
Market Dynamics
Municipal fleet managers face simultaneous pressure from EPA Tier 4 Final emissions mandates and EU F-Gas refrigerant prohibitions, forcing parallel platform development for diesel, hybrid, and fully electric street washer architectures.
Growth Catalysts
- EU Green Deal decarbonization targets:Municipalities across Germany, France, and the Netherlands must electrify 50% of sanitation fleets by decade-end, creating pull-through demand for battery-powered chassis with integrated high-pressure systems.
- Water recycling technology maturation:Closed-loop filtration systems now achieve 85% freshwater recovery rates, enabling compliance with California's urban runoff discharge restrictions and drought contingency ordinances.
- Smart city infrastructure deployment:Urban centers in China are integrating street washers into IoT-enabled sanitation grids with real-time route optimization and predictive maintenance scheduling.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing remains dependent on Chinese cathode material processing, exposing European and North American OEMs to export control volatility and freight cost spikes.
- High-pressure pump technical limitation:Electric drivetrains struggle to match diesel torque curves for simultaneous propulsion and 250-bar spray operation, constraining operational duty cycles.
- Substitution threat from autonomous sweepers:Robotic surface cleaning units with AI-guided debris detection are capturing plaza and pedestrian zone contracts previously served by manned washers.
Strategic Opportunities
- Underpenetrated Indian urban sanitation:Swachh Bharat Mission 2.0 funding is unlocking municipal procurement in tier-2 cities lacking mechanized cleaning infrastructure.
- Technology convergence of hydrogen fuel cells and high-pressure hydraulics:South Korean and Japanese pilot programs are testing fuel cell range extenders for 24-hour continuous operation without charging downtime.
- Service outsourcing channel innovation:Private contractors are securing 10-15 year availability-based contracts with municipalities, shifting capital burden from public balance sheets.
Industry Challenges
- Electrification skill gap:Municipal maintenance departments lack certified high-voltage technicians capable of servicing battery packs and regenerative braking systems.
- Multi-jurisdiction certification complexity:OEMs must navigate separate EPA, KBA, and MIIT homologation processes for engine, hydraulic, and electrical subsystems, extending product launch timelines.
- Legacy fleet integration friction:Existing depots require charging infrastructure retrofit and grid capacity upgrades, complicating mixed-fleet operations during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street Washer Machine Market |
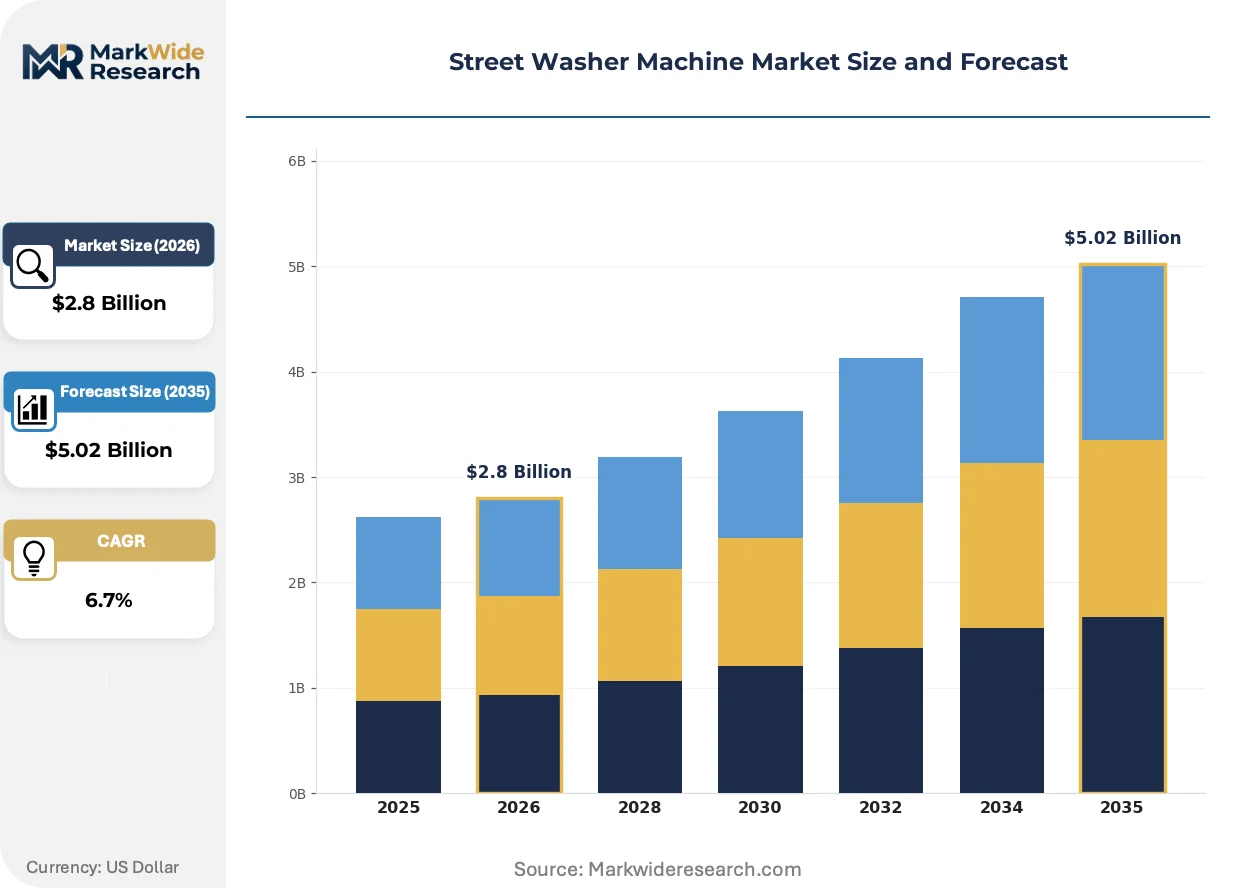
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, Manual Technology: Pressure Washing, Steam Cleaning, Vacuum Cleaning, Water Recycling End User: Municipalities, Private Contractors, Facility Managers, Cleaning Companies Installation: Mobile Units, Stationary Units, Integrated Systems, Rented Equipment |
| Companies Covered | Nilfisk, Kärcher, Tennant Company, Hako, Dulevo, Aebi Schmidt, Bucher Industries, Boschung Group, Schwarze Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street Washer Machine Market Strategic Shifts
Active thermal management and solid-state battery chemistry are converging to extend electric platform viability beyond current operational envelopes. Equipment manufacturers are racing to embed predictive analytics and autonomous navigation before regulatory mandates harden.
Solid-state battery packs with silicon-anode architecture are electrifying the heavy-duty municipal vehicle segment by delivering 40% energy density gains over conventional lithium-ion cells. German and Chinese fleet operators are piloting these systems for overnight charging compatibility with standard depot infrastructure. The technology is electrifying competitive positioning by compressing total cost of ownership parity timelines against diesel equivalents.
EPA's updated Tier 4 Final off-road diesel standards and EU F-Gas Regulation phase-down schedules are forcing refrigerant-free thermal system redesigns across compressor and vacuum recovery subassemblies. Manufacturers must eliminate hydrofluorocarbon-based cooling loops or face market exclusion in North America and Europe. Water recycling platforms with passive cooling architectures are capturing preferential positioning in jurisdictions with overlapping emissions and discharge mandates.
Municipal procurement departments are consolidating vendor relationships around full-service availability contracts rather than discrete equipment purchases. Private contractors and direct municipal buyers alike are unbundling maintenance, consumables, and uptime guarantees into subscription-style arrangements. This behavioral pivot is most visible in Australian and Canadian markets where municipal budget volatility has accelerated outsourcing adoption.
Street Washer Machine Market Segmentation
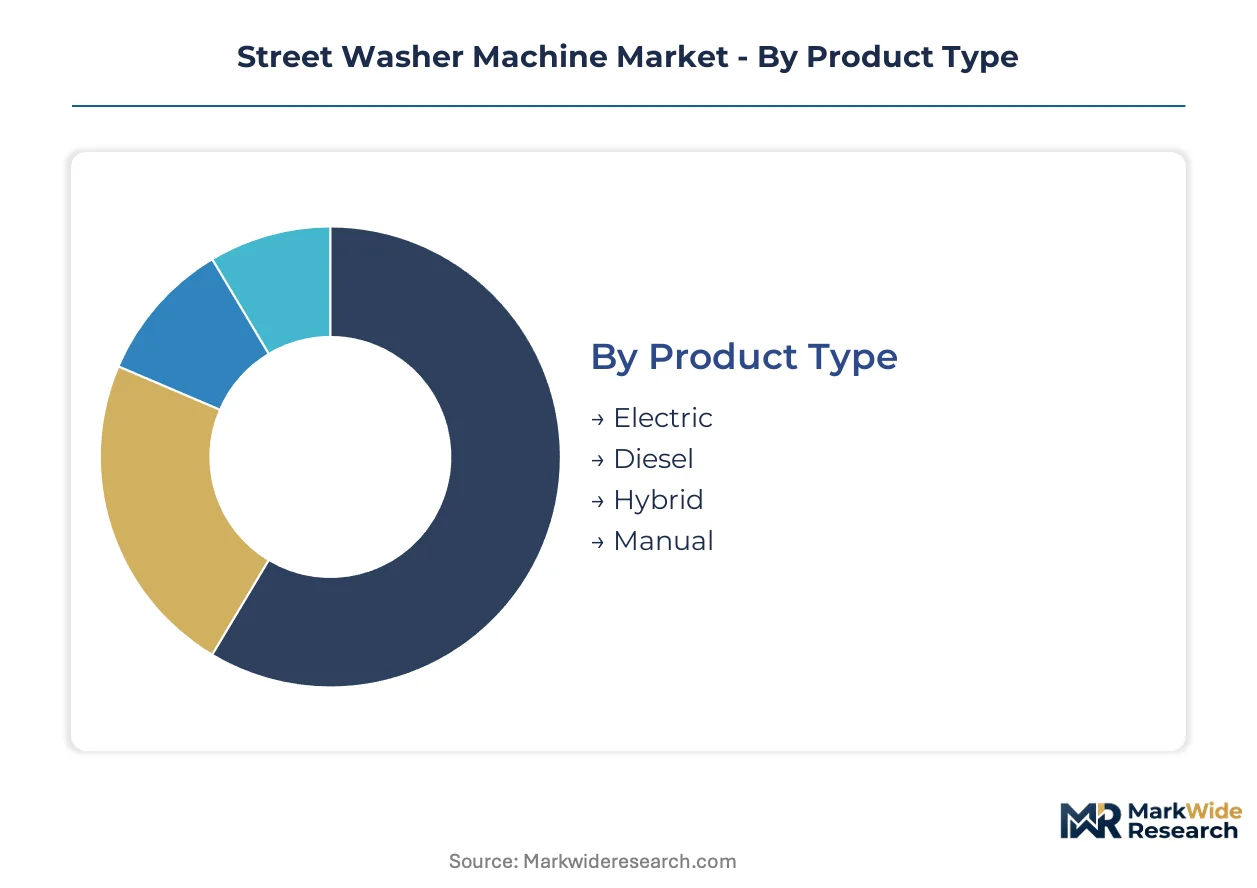
Segmentation in the street washer machine market determines regulatory exposure, capital intensity, and operational flexibility for fleet operators. Procurement decisions hinge on matching product architecture to specific municipal mandates, terrain constraints, and water access conditions.
Product Type:
EPA Tier 4 Final, EU F-Gas Regulation, and China's MIIT dual carbon goals impose divergent certification burdens across powertrain architectures, forcing OEMs to maintain parallel homologation tracks.
- Electric:Battery-electric platforms with 150-250 kWh packs and regenerative braking systems dominate German and Dutch municipal tenders driven by EU Green Deal fleet electrification mandates. High-voltage technician shortages constrain maintenance scalability in North American deployments.
- Diesel:Compression-ignition engines with selective catalytic reduction and diesel particulate filters retain share in budget-constrained tier-2 Indian cities and remote Australian mining towns lacking grid infrastructure. EPA and KBA emissions certification cycles extend product launch timelines.
- Hybrid:Parallel drivetrains combining diesel range extenders with electric traction motors bridge operational gaps in Chinese smart city pilots requiring 18-hour continuous duty cycles. MIIT fuel consumption standards drive domestic engineering priorities.
- Manual:Walk-behind units with gasoline or battery-powered pumps serve pedestrian zones and narrow European alleys inaccessible to chassis-mounted systems. Low capital barriers attract small private contractors in underpenetrated Indian urban markets.
Diesel sits at the top of the volume ranking, with Electric climbing the fastest.
Technology:
Cost tiers separate premium closed-loop systems from standard open-cycle configurations, with drought-prone geographies commanding substantial price premiums for water recovery capabilities.
- Pressure Washing:High-pressure pump systems delivering 150-250 bar through ceramic nozzle arrays constitute the baseline technology deployed across 80% of municipal fleets. California's urban runoff discharge restrictions and drought contingency ordinances tighten operational constraints in western US markets.
- Water Recycling:Closed-loop filtration with membrane separation and UV sterilization achieves 85% freshwater recovery, commanding 40-60% capital premiums over standard configurations. Australian and Middle Eastern municipalities prioritize these systems under severe water scarcity conditions.
- Vacuum Cleaning:Negative-pressure debris recovery with cyclonic separation and baghouse filtration targets construction zones and post-event cleanup contracts. Heavy particulate loads accelerate consumable replacement cycles.
- Steam Cleaning:Superheated vapor systems at 150-180°C sanitize surfaces without chemical detergents, penetrating German and Swiss organic certification markets for pedestrian plaza maintenance. Thermal energy demands constrain battery-electric platform compatibility.
Pressure Washing retains the dominant share, with Water Recycling expanding most quickly.
End User:
Customer type determines contract structure, with direct municipal procurement favoring capital purchase models while private operators gravitate toward availability-based service agreements.
- Municipalities:City sanitation departments with centralized fleet management and dedicated maintenance depots represent the anchor demand pool for chassis-mounted electric and hybrid platforms. EU public procurement directives mandate lifecycle cost evaluation over sticker price.
- Private Contractors:Specialized service providers securing 10-15 year availability contracts with municipalities shift capital burden from public balance sheets, concentrating in Australian and Canadian markets with volatile municipal budgets. Outsourcing penetration remains limited in France and Germany due to strong public sector unions.
- Facility Managers:Campus and industrial park operators with captive cleaning requirements favor compact electric units for controlled environments. Procurement autonomy bypasses municipal tender complexity.
- Cleaning Companies:Multi-service janitorial firms deploy manual and small mobile units for supplemental street and parking structure contracts. Price sensitivity drives rental equipment utilization.
Municipalities command the volume lead, with Private Contractors gaining share fastest.
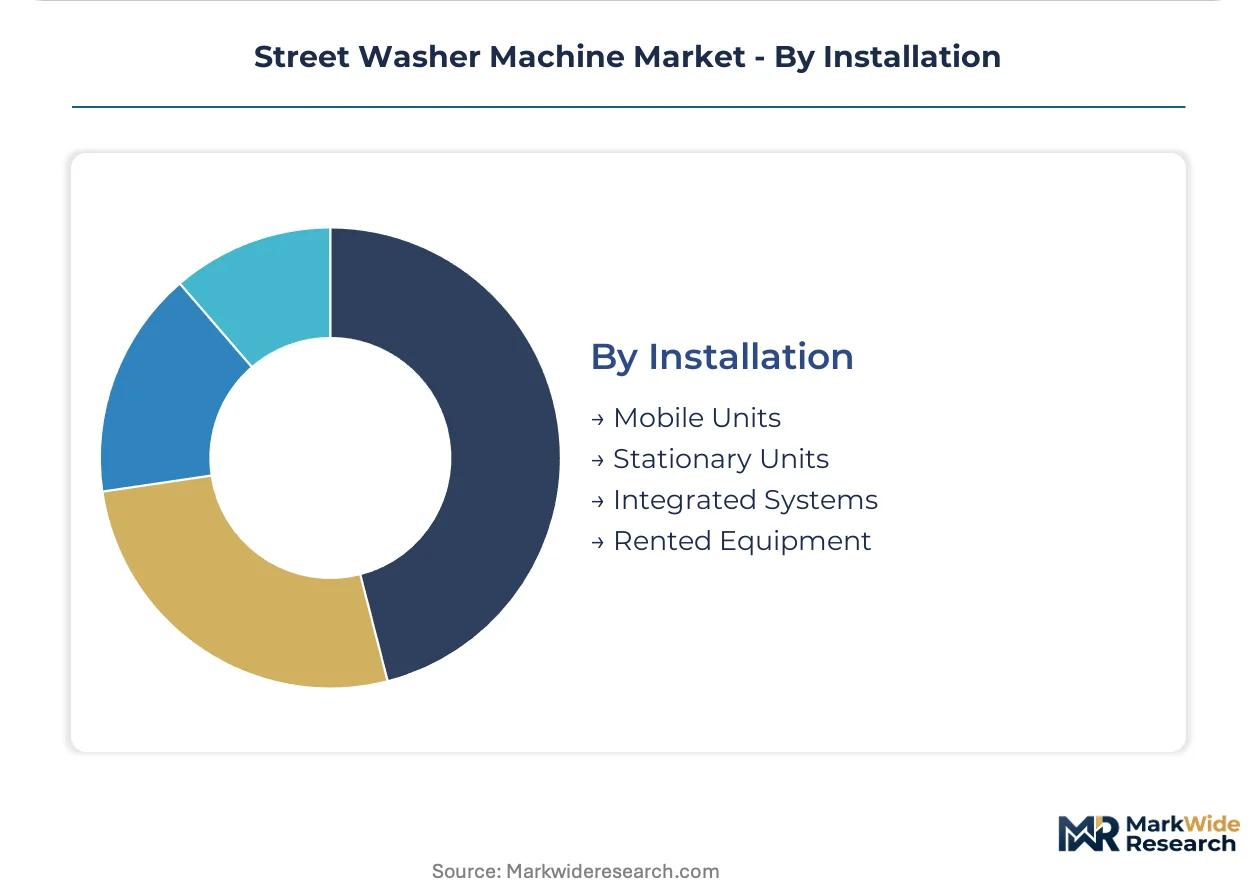
Installation:
Supply concentration in chassis manufacturing versus distributed fabrication of cleaning subassemblies creates divergent margin structures across installation modalities.
- Mobile Units:Self-propelled truck or trailer-mounted systems with integrated water tanks and powertrains dominate municipal fleet standardization. German KBA vehicle type approval and EPA on-highway emissions certification apply.
- Rented Equipment:Short-term leasing of compact electric and manual units enables seasonal demand smoothing and emergency response surge capacity. Rental penetration concentrates in North American markets with flexible municipal procurement regulations.
- Stationary Units:Fixed-position cleaning stations with underground water storage serve tunnel and bridge maintenance depots. Civil engineering integration extends deployment timelines.
- Integrated Systems:Custom-engineered permanent installations for airport tarmac and container terminal applications combine high-capacity water treatment with automated gantry positioning. Project-specific engineering margins exceed standard product lines.
Mobile Units anchor volume, with Rented Equipment showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters in Stuttgart and Munich anchor electric platform development for municipal sanitation fleets, with battery-integrated chassis designs now dominating EU Green Deal procurement tenders.
United States
California's urban runoff discharge restrictions and drought contingency ordinances drive water recycling technology penetration in Los Angeles and San Diego municipal fleets. EPA Tier 4 Final off-road diesel standards accelerate electric platform development among Midwest fleet operators. Chicago and Detroit sanitation departments pilot solid-state battery configurations for overnight depot charging compatibility.
China
MIIT dual carbon goals push domestic manufacturers toward hybrid drivetrain adoption in Yangtze River Delta smart city pilots. Shanghai and Hangzhou integrate street washers into IoT-enabled sanitation grids with real-time route optimization. Shenzhen fleet operators test 18-hour continuous duty cycle configurations combining diesel range extenders with electric traction motors.
Germany
KBA vehicle type approval requirements and EU F-Gas refrigerant prohibitions force refrigerant-free thermal system redesigns across compressor subassemblies. Munich and Hamburg sanitation departments mandate 50% fleet electrification by decade-end under EU Green Deal targets. Stuttgart engineering clusters concentrate solid-state battery pilot programs with silicon-anode architecture.
India
Swachh Bharat Mission 2.0 funding unlocks municipal procurement in tier-2 cities lacking mechanized cleaning infrastructure. Maharashtra and Gujarat urban development authorities prioritize compact electric units for narrow alley access. Bangalore and Hyderabad facility managers deploy captive cleaning fleets for technology park maintenance.
Australia
Severe water scarcity conditions in Queensland and Western Australia prioritize closed-loop filtration systems achieving 85% freshwater recovery. Sydney and Melbourne municipal budget volatility accelerates 10-15 year availability-based contracting with private service providers. Perth sanitation departments retrofit existing depots with charging infrastructure for mixed-fleet transition periods.
Street Washer Machine Market Competitive Environment
Global majors compete with regional champions across certification complexity, with consolidated premium positioning in German and Swiss markets fragmenting into price-sensitive procurement in Indian tier-2 cities. Three strategic archetypes dominate: integrated chassis-cleaning system manufacturers, specialized pump and vacuum technology licensors, and municipal service contractors bundling equipment with long-term availability guarantees. Capacity expansion concentrates in Chinese Yangtze River Delta clusters, while strategic partnerships between battery cell suppliers and European OEMs accelerate solid-state platform development.
Within the integrated-system tier, Nilfisk anchors Nordic engineering heritage in premium electric product lines, while Kärcher exemplifies backward integration into pump system manufacturing to control critical component costs. Tennant Company occupies a specialist position in water recycling technology differentiation. These three represent distinct competitive vectors: geographic brand anchoring, upstream supply control, and drought-market technology specialization.
| Leading Market Players |
|---|
| Nilfisk |
| Kärcher |
| Tennant Company |
| Hako |
| Dulevo |
| Aebi Schmidt |
| Bucher Industries |
| Boschung Group |
| Schwarze Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into pump system manufacturing anchors both supply security and margin control for chassis-integrated OEMs serving municipal procurement channels. Kärcher's captive production of high-pressure hydraulics insulates against component cost volatility while Nilfisk's Nordic supply clustering supports premium electric platform positioning.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials and high-strength aluminum alloys shapes contract structures across electric and hybrid product tiers. Three-tier pricing structure across premium, standard, and economy levels separates water recycling platforms with closed-loop certification from baseline pressure-washing configurations. Cost compression in mid-tier hybrid systems is intensifying because MIIT dual carbon compliance adds engineering overhead without full electrification subsidies. Private contractors in Australian and Canadian outsourcing markets exhibit highest price sensitivity, while German municipalities under EU Green Deal mandates show lowest elasticity for certified electric platforms.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material processing for battery packs deployed across European and North American electric chassis programs. Manufacturing concentration in Germany, China, and South Korea feeds global assembly lines, while steel chassis fabrication draws from domestic metalworking clusters in each major demand geography. Supply chain risk centers on export control volatility affecting lithium-ion cell logistics from Chinese processing hubs. Distribution runs through municipal procurement departments and private contractor fleets rather than retail channels, with availability-based service contracts capturing expanding share in budget-constrained markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The street washer machine market functions as a stable compounder anchored by irreversible municipal fleet electrification mandates across German, Chinese, and US urban centers. Regulatory compliance requirements create sustained replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Deploy solid-state battery platform development as the primary defensive lever. Nilfisk and Kärcher should accelerate silicon-anode pilot programs in Stuttgart and Munich to preempt emerging entrants from capturing EU Green Deal tender share. Backward integration into thermal management subassemblies counters refrigerant-free redesign costs imposed by EU F-Gas Regulation phase-down schedules.
For New Entrants and Emerging Players: Municipal service contractors represent the most penetrable channel partner type for bypassing incumbent brand loyalty in Australian and Canadian availability-contract markets. Tier-2 Indian cities under Swachh Bharat Mission 2.0 funding lack mechanized cleaning infrastructure and present white-space opportunity for compact electric manual units. Technology licensing from South Korean hydrogen fuel cell pilots offers differentiation for 24-hour continuous duty cycle configurations.
For Investors and Strategic Acquirers: Roll-up economics work for regional pump and vacuum technology specialists because certification fragmentation across EPA, KBA, and MIIT homologation processes favors acquired regulatory expertise over greenfield investment. Five-to-ten-year viability rests on exposure to municipal electrification mandates rather than cyclical infrastructure spending. The signal to watch is solid-state battery cost parity announcements from German engineering clusters, which would compress diesel-to-electric transition timelines and revalue installed base replacement rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Manufacturing | Kärcher's captive supply of high-pressure systems controls critical component costs against cathode material volatility. |
| Solid-State Battery Platform Development | Silicon-anode architectures from Stuttgart clusters extend electric range for EU Green Deal compliance without depot retrofit. |
| Water Recycling Technology Licensing | Tennant Company's closed-loop filtration commands 40-60% capital premiums in California drought contingency markets. |
| Availability-Based Service Contracting | Private operators in Sydney and Melbourne shift capital burden from municipal balance sheets through 10-15 year uptime guarantees. |
| Hydrogen Fuel Cell Range Extender Pilots | South Korean programs test 24-hour continuous operation configurations bypassing lithium-ion charging downtime constraints. |
Study Parameters
Direct dialogue with municipal fleet managers, high-voltage maintenance technicians, OEM platform engineers, and private contractor procurement leads grounded qualitative findings in operational reality. Secondary validation drew from EPA Tier 4 Final filings, KBA vehicle type approval databases, MIIT dual carbon policy releases, and EU F-Gas Regulation implementation schedules. Bottom-up triangulation against top-down municipal budget expenditure patterns ensured segmentation integrity across electric, hybrid, diesel, and manual product architectures.
Bottom-up modeling of unit economics across powertrain configurations combined with top-down sanitation infrastructure spending forecasts across the projection horizon. Segmentation dimensions included propulsion technology, water recovery capability, end-user procurement model, and installation modality. CAGRs were derived from replacement cycle analysis of existing municipal fleets against electrification mandate deadlines, with battery energy density improvement curves and charging infrastructure deployment rates as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply chain disruptions and autonomous sweeper substitution rates in pedestrian zones. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and municipal budget continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Powered Screed Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Rockbreakers Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Stud Welding Guns Market