
 Static and Rotating Equipment Market | 2026-2036
Static and Rotating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Static and Rotating Equipment Market Intelligence
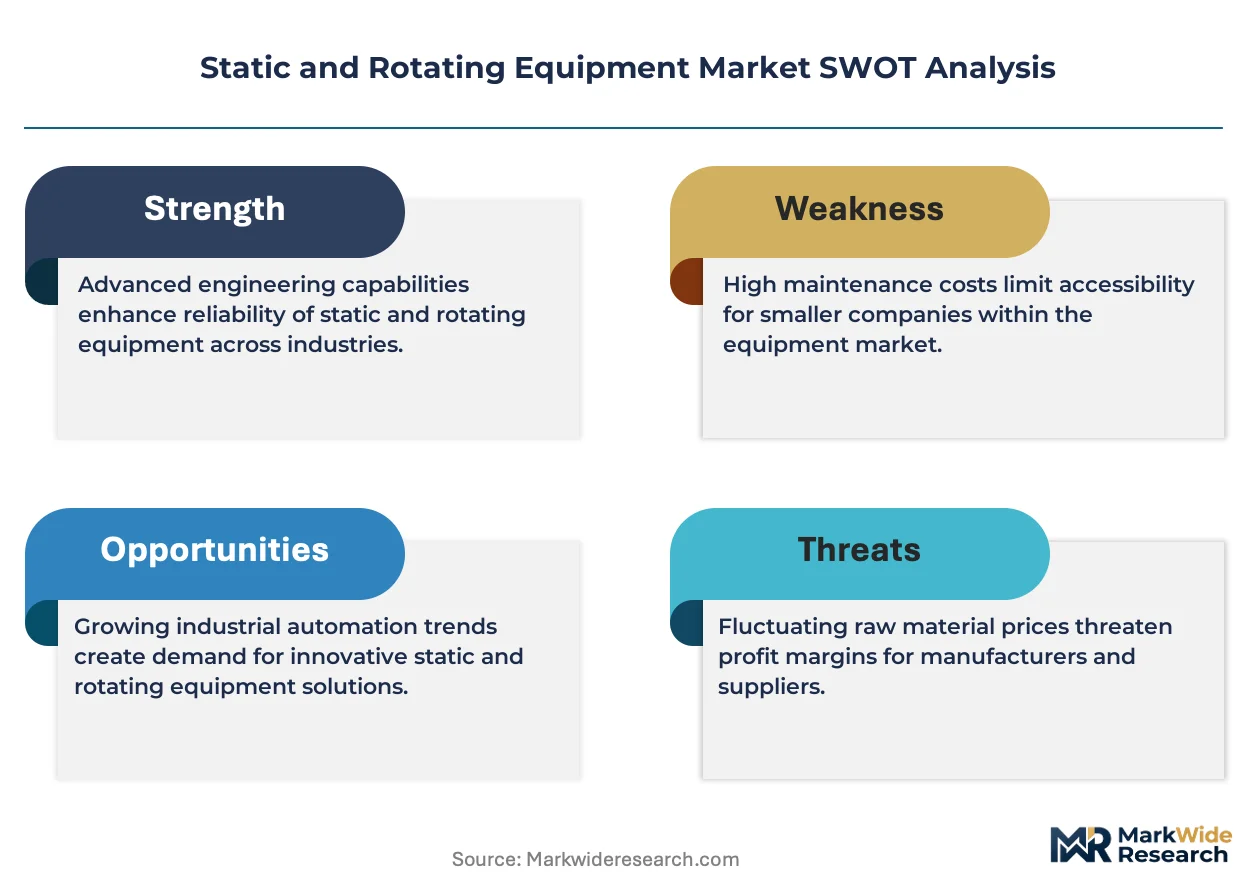
A shift toward equipment-as-a-service and long-term leasing models is tilting the competitive landscape away from pure capital sales. This trend favors large, well-capitalized firms that can finance these arrangements. Siemens AG leverages its extensive financial services division to offer integrated solutions. Meanwhile, Sulzer Limited specializes in high-performance pumps and services for critical applications, maintaining its position through technical expertise.
Static and rotating equipment encompasses machinery critical for fluid and energy transfer in industrial processes. This includes devices like centrifugal pumps, which use impellers to move fluids, and heat exchangers that operate based on thermal conductivity principles. Within the equipment types, compressors and turbines represent major capital investments with long replacement cycles. The oil and gas end-user sector remains the largest consumer, though the power generation segment shows significant growth potential driven by grid modernization.
Compliance with standards from the American Petroleum Institute (API) is essential for oil and gas applications. In Europe, the EU's Machinery Directive and CE marking govern safety and performance requirements for all equipment placed on the market. These regulations mandate specific design, testing, and documentation protocols. Vendor selection increasingly hinges on the ability to demonstrate lifecycle efficiency and compliance with evolving international emissions standards.
Market Dynamics
The push for industrial decarbonization and energy efficiency is the central force shaping the static and rotating equipment market. This pressure compels operators to invest in modern, compliant machinery, influencing design, material selection, and lifecycle service models.
Growth Catalysts
- Petrochemical Expansion:New project developments in industrial clusters such as the US Gulf Coast and throughout China create sustained demand for pumps, compressors, and heat exchangers to support ethylene and derivatives production.
- EU F-Gas Regulation:Phasedowns of high global warming potential refrigerants under this European Union directive are accelerating the replacement of older compressors with models using compliant alternatives like HFOs or natural refrigerants.
- Grid Modernization:Investments in upgrading and expanding power grids, particularly to support renewable energy integration, drive demand for new turbines, generators, and associated balance-of-plant equipment in the power generation sector.
Market Restraints
- Long Replacement Cycles:Major capital equipment like industrial turbines and large-scale compressors have operational lifespans measured in decades, which structurally slows the overall pace of market replacement and technology adoption.
- Multi-Jurisdictional Compliance:Manufacturers face significant costs and complexities in designing and certifying equipment to meet divergent standards, such as API specifications in North America and the EU's Machinery Directive.
- Specialty Material Volatility:The performance of critical equipment depends on high-grade alloys and composites, whose price and availability are subject to supply chain disruptions and geopolitical factors, creating input cost uncertainty.
Strategic Opportunities
- Equipment-as-a-Service Models:Shifting from capital sales to long-term leasing and service contracts allows suppliers to capture recurring revenue streams while offering customers predictable operational costs and guaranteed uptime.
- Carbon Capture Applications:The global build-out of carbon capture, utilization, and storage (CCUS) infrastructure opens a significant new market for specialized, high-pressure CO2 compressors, pumps, and transportation systems.
- Digital Twin Integration:Creating virtual models of physical assets allows for advanced predictive maintenance, performance optimization, and simulation, offering a high-value service layer on top of traditional equipment sales.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians and engineers qualified to install, operate, and service digitally-integrated, high-performance rotating machinery creates operational bottlenecks for both manufacturers and end-users.
- Legacy System Integration:Integrating new, highly efficient equipment into existing industrial plants with older control systems and physical footprints presents significant engineering and interoperability challenges.
- Supply Chain Reconfiguration:Adapting supply chains to produce equipment for new applications like hydrogen service requires qualifying new material suppliers and retooling manufacturing processes, introducing operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static and Rotating Equipment Market |
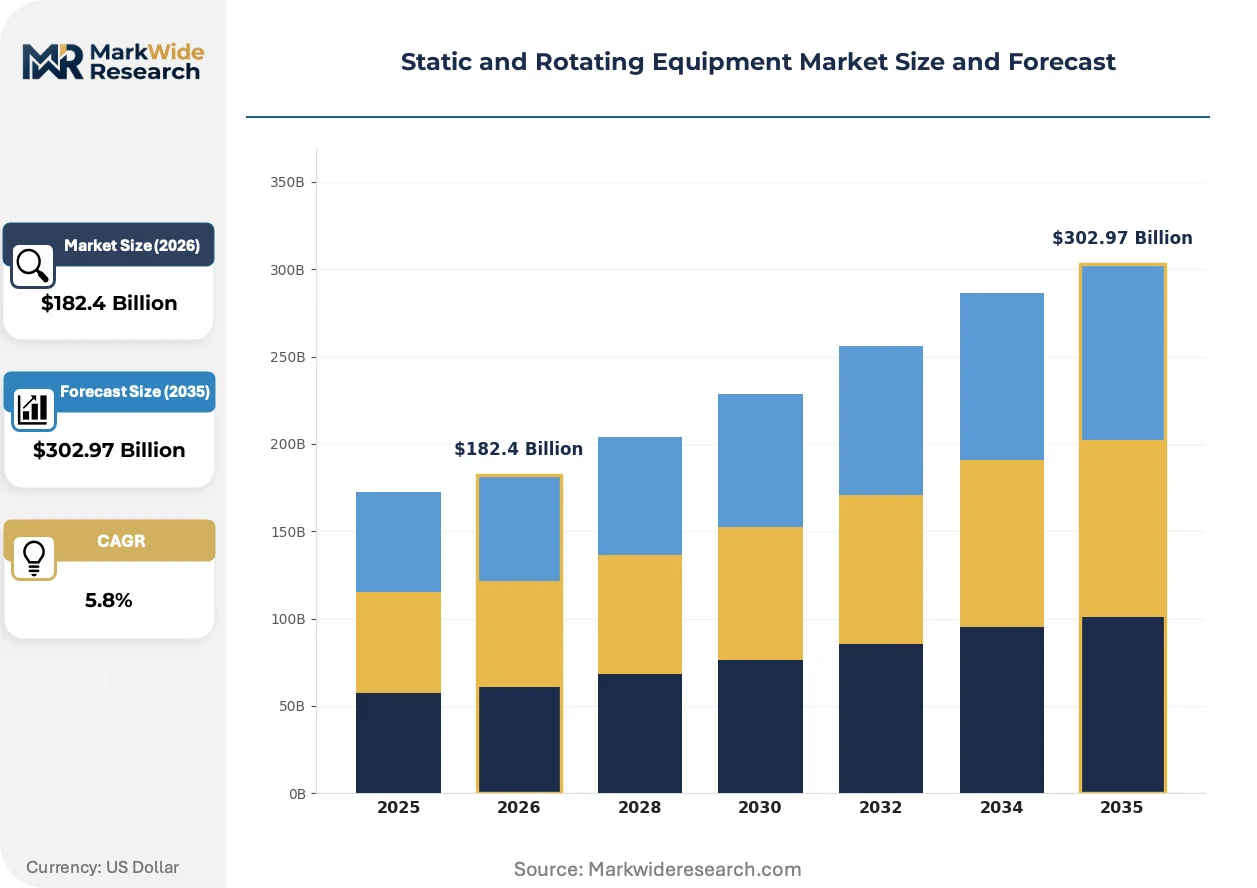
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $302.97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Compressors, Turbines, Pumps, Heat Exchangers End User Sector: Oil & Gas, Power Generation, Chemical Processing, Water Treatment Maintenance Strategy: Predictive Maintenance, Preventive Maintenance, Reactive Maintenance, Condition Monitoring Installation Method: On-site, Off-site, Modular, Integrated |
| Companies Covered | General Electric Company, Siemens AG, Alfa Laval AB, Metso Oyj, Sulzer Limited, Atlas Copco AB, Baker Hughes Company, Flowserve Corporation, Pentair PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static and Rotating Equipment Market Strategic Shifts & Innovations
Digitalization and servitization are transforming the market's value proposition. The focus is shifting from the one-time sale of physical hardware toward providing guaranteed operational outcomes, such as uptime and energy efficiency, through integrated digital services and advanced analytics.
Magnetic bearing technology provides frictionless support for rotating shafts in high-speed machinery. Centrifugal compressor and turboexpander users in the LNG and industrial gas sectors are adopting this technology to improve reliability and eliminate complex oil lubrication systems. Equipment design is migrating from a dependency on conventional fluid-film bearings toward contactless, digitally controlled systems that enable higher rotational speeds and greater operational efficiency.
The US Inflation Reduction Act (IRA) provides substantial tax incentives for domestic clean energy and decarbonization projects. This policy directly stimulates demand for equipment essential to green hydrogen production, carbon capture, and biofuel facilities. Consequently, manufacturers are accelerating the development and certification of pumps and compressors designed for high-pressure hydrogen and supercritical CO2 applications to target IRA-funded projects.
End-users are increasingly favoring long-term service agreements (LTSAs) and performance-based contracts over traditional outright equipment purchases. This model disrupts the transactional sales channel by placing the burden of financing, maintenance, and operational risk on the OEM. This trend is most prominent in the power generation and oil and gas sectors, where operators prioritize predictable expenditures and asset availability.
Static and Rotating Equipment Market Segmentation
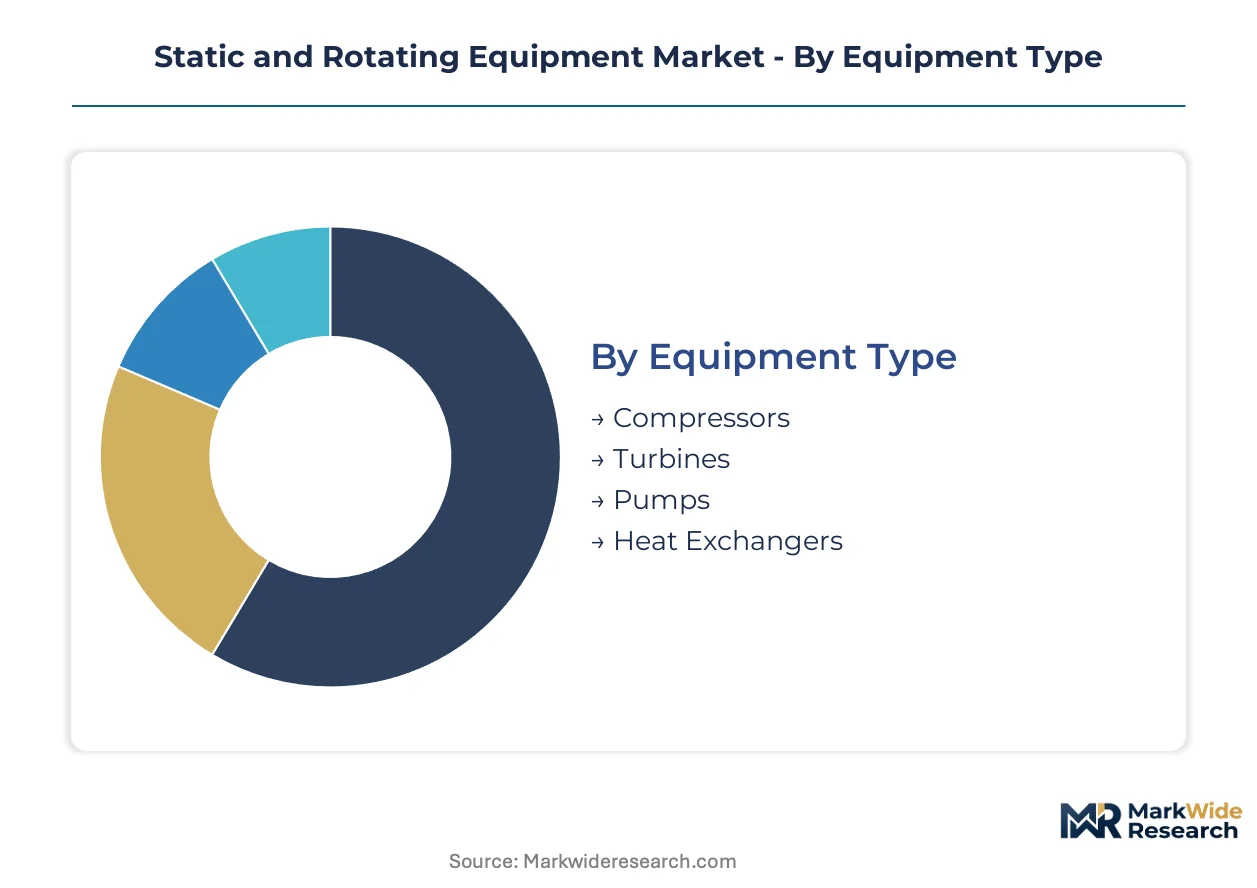
Understanding the distinct segments within the static and rotating equipment market is critical for identifying specific demand patterns and technological shifts. Equipment characteristics, end-user requirements, maintenance approaches, and installation complexities all define unique sub-markets. This segmentation provides a framework for analyzing specific growth opportunities and competitive dynamics across the industrial landscape.
Equipment Type:
The use-case spectrum for static and rotating equipment ranges from basic fluid movement to complex energy conversion processes. Each equipment type serves specialized functions within industrial operations, demanding specific design and performance criteria.
- Compressors:These devices increase the pressure of gases, essential for chemical processing, refrigeration, and natural gas transmission. New installations in the US Gulf Coast petrochemical hubs frequently specify high-efficiency centrifugal compressors to meet production targets.
- Turbines:Turbines convert fluid flow into rotational energy, primarily for power generation and mechanical drive applications. Investments in grid modernization projects across Europe are driving demand for advanced gas and steam turbines that offer improved efficiency and flexibility.
- Pumps:Pumps are mechanical devices moving fluids by mechanical action, widely used across all industrial sectors. Industrial facilities in China deploy large volumes of centrifugal and positive displacement pumps for water circulation and chemical transfer.
- Heat Exchangers:These devices transfer heat between two or more fluids, crucial for temperature control in chemical, power, and HVAC systems. Shell and tube heat exchangers remain a staple in refineries globally for process heating and cooling.
Established volume favors Pumps for broad industrial utility; emerging adoption favors Compressors for specialized high-pressure applications like carbon capture.
End User Sector:
Application focus varies significantly across different industrial sectors, each requiring specialized static and rotating equipment tailored to specific operational environments and regulatory compliance needs.
- Oil & Gas:This sector utilizes a wide array of equipment for extraction, processing, and transportation of hydrocarbons, often under extreme conditions. Compliance with API standards remains paramount for equipment deployed in North American oil and gas fields.
- Power Generation:Equipment here focuses on converting various energy sources into electricity, including turbines, generators, and associated balance-of-plant machinery. Grid modernization initiatives in countries like Germany increase demand for advanced turbines supporting renewable energy integration.
- Chemical Processing:This industry relies on equipment for mixing, separating, reacting, and transferring chemicals, demanding corrosion resistance and precise control. New ethylene plants in China require extensive heat exchangers and pumps.
- Water Treatment:Equipment in this sector manages water and wastewater, including pumps, filters, and aeration systems. Municipal water utilities in India are expanding their infrastructure, creating demand for robust pumping solutions.
The Oil & Gas sector holds the largest installed base; the Power Generation sector is expanding most quickly due to energy transition investments.
Maintenance Strategy:
Operational focus dictates the selection of maintenance strategies, influencing equipment design and the integration of digital technologies to maximize uptime and reduce lifecycle costs.
- Predictive Maintenance:This strategy uses data analytics and condition monitoring to forecast equipment failures, enabling proactive intervention. Digital twin integration allows operators in the US Gulf Coast to optimize compressor maintenance schedules.
- Condition Monitoring:Continuous or periodic assessment of equipment health through sensors and data collection informs maintenance decisions. Turbines in European power plants frequently employ vibration analysis and temperature monitoring to prevent unexpected outages.
- Preventive Maintenance:Scheduled maintenance tasks performed at regular intervals or after a certain amount of operating time. Many industrial pumps undergo routine inspections and component replacements to ensure operational continuity.
- Reactive Maintenance:Repairing equipment only after a breakdown occurs, often leading to unplanned downtime and higher repair costs. Smaller, less critical equipment in some facilities still relies on this approach due to lower initial investment in monitoring.
Predictive Maintenance gains traction for high-value assets; Reactive Maintenance persists for lower-priority components.
Installation Method:
Project complexity influences the choice of installation method, impacting construction timelines, site logistics, and overall project costs for new industrial facilities.
- Modular:Equipment is pre-assembled into self-contained units off-site, then transported and connected at the final location. This method accelerates project delivery for new petrochemical units in China.
- Integrated:Components are designed to work seamlessly within a larger system, often requiring custom engineering and precise alignment during installation. Large-scale power generation plants utilize integrated turbine-generator sets for optimal performance.
- On-site:Equipment is assembled and installed directly at the final operational location, common for traditional construction projects. Many older industrial facilities expanded using on-site installation techniques for pumps and heat exchangers.
- Off-site:Manufacturing and initial assembly occur away from the final site, with transport of sub-assemblies for final installation. This approach reduces on-site labor requirements and improves quality control for specialized equipment.
On-site installation remains common for established infrastructure; Modular installations are gaining share for new, time-sensitive projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act (IRA) provides substantial incentives for clean energy and decarbonization, significantly influencing demand for static and rotating equipment. This policy framework drives investments in green hydrogen production and carbon capture infrastructure. Global industrialization efforts further accelerate equipment needs across diverse regions.
United States
Demand for high-pressure compressors and pumps is driven by new petrochemical expansions and carbon capture projects. The US Inflation Reduction Act (IRA) directly stimulates investment in essential equipment for green hydrogen and CCUS facilities. The US Gulf Coast industrial hubs are experiencing sustained demand for advanced rotating machinery.
China
Petrochemical expansion and infrastructure development create sustained demand for pumps, compressors, and heat exchangers. China's dual carbon goals accelerate the adoption of energy-efficient equipment and new material solutions. Industrial clusters in the Yangtze River Delta are driving significant equipment procurement for new chemical plants.
Germany
Investments in grid modernization and renewable energy integration are boosting demand for advanced turbines and generators. The EU's F-Gas Regulation compels manufacturers to upgrade compressors with lower global warming potential refrigerants. Power generation facilities across the Rhine-Ruhr region are prioritizing efficiency upgrades for existing assets.
India
Infrastructure development and municipal water utility expansions are fueling demand for robust pumping solutions and associated equipment. India's PLI scheme encourages domestic manufacturing, including components for industrial machinery. Urban centers like Mumbai and Delhi are seeing increased adoption of water treatment and processing equipment.
Saudi Arabia
Major oil and gas projects, alongside diversification into petrochemicals, require extensive static and rotating equipment. The Saudi Vision 2030 initiatives drive investments in advanced processing facilities and energy infrastructure. Industrial cities like Jubail and Yanbu are expanding capacity with new compressor stations and heat exchanger installations.
Static and Rotating Equipment Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified conglomerates and specialized technology providers. Global players leverage extensive financial services divisions to offer integrated solutions, including equipment-as-a-service models, which are reshaping traditional capital sales. Competitive moves involve strategic partnerships for new applications like carbon capture and green hydrogen, alongside continuous portfolio diversification into energy-efficient and digitally-integrated solutions. Geographic expansion into emerging industrial hubs and M&A activities also remain key strategies to consolidate market share.
On the premium-tier vector, Siemens AG, a German multinational conglomerate, exemplifies companies offering broad industrial solutions with significant financial services integration. Sulzer Limited, a Swiss industrial engineering and manufacturing firm, represents specialized expertise in high-performance pumps and critical application services. Meanwhile, Atlas Copco AB, a Swedish industrial company, occupies a position focused on compressors, vacuum solutions, and industrial tools. These firms anchor innovation in digitalization and lifecycle service models.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens AG |
| Alfa Laval AB |
| Metso Oyj |
| Sulzer Limited |
| Atlas Copco AB |
| Baker Hughes Company |
| Flowserve Corporation |
| Pentair PLC |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta's robust manufacturing capacity for industrial components directly influences global pricing power for high-volume static equipment. This concentration of production capability creates a competitive pricing environment for standard units.
Pricing Analysis
Certification level (API, CE marking) creates the primary spread in static and rotating equipment pricing, reflecting compliance costs and performance guarantees. The dominant pricing model is project-based, particularly for large capital investments such as turbines and high-pressure compressors. Customization levels and integrated service agreements are significant differentiation drivers. Pricing softness reflects intense competition in standard component categories, while oil and gas operators prioritize reliability over initial cost, making them less price-sensitive than water treatment utilities.
Supply Chain Analysis
Major industrial equipment manufacturers and specialized foundries in China and Germany hold significant capacity for key static and rotating equipment components. The supply chain draws from high-grade alloys, specialized castings, and advanced seal materials, often sourced globally. Single-source vulnerabilities for critical components, especially high-pressure valves or magnetic bearings, pose a structural risk. Distribution runs through a mix of direct sales channels, regional distributors, and engineering, procurement, and construction (EPC) firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the shift towards industrial decarbonization and the demand for specialized equipment in new energy applications. These emerging segments create distinct niches for focused innovation.
For Market Incumbents: Insulate core market share by deepening long-term service agreements (LTSAs) and integrating digital twin capabilities for predictive maintenance. Invest in R&D for high-pressure hydrogen and supercritical CO2 applications to counter the threat from specialized new entrants. Leveraging financial services divisions to offer equipment-as-a-service models can mitigate margin pressure from pure capital sales.
For New Entrants and Emerging Players: Pursue white-space opportunities in carbon capture, utilization, and storage (CCUS) and green hydrogen production, focusing on specialized compressors and pumps. The power generation sector, particularly grid modernization projects, represents a penetrable segment for innovative balance-of-plant equipment. A go-to-market angle emphasizing lifecycle efficiency and compliance with evolving emissions standards will resonate with industrial operators.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering integrated digital services and long-term maintenance contracts, providing stable cash flows over the long term. Acquisition targets should be specialized technology providers with strong intellectual property in magnetic bearing technology or advanced materials for corrosive fluids. The signal to watch is the acceleration of large-scale CCUS project final investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Equipment-as-a-Service Offerings | Provides stable revenue streams and improves customer uptime for critical industrial machinery. |
| Invest in Green Hydrogen Compressor R&D | Addresses future demand for high-pressure systems in clean energy infrastructure. |
| Develop Digital Twin Integration Platforms | Enhances predictive maintenance capabilities and optimizes asset performance for end-users. |
| Secure Long-Term Alloy Supply Contracts | Mitigates input cost volatility for high-performance equipment manufacturing. |
| Pursue CE Marking for EU Market Access | Ensures compliance with European safety and performance regulations for new products. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from plant managers, OEM procurement teams, R&D directors, and maintenance supervisors across diverse industrial sectors. Secondary research leveraged industrial association reports, government energy policy documents, and company financial filings. A bottom-up and top-down triangulation approach ensured comprehensive data accuracy.
Forecast inputs being considered included historical market performance, projected industrial capital expenditure, and anticipated regulatory impacts. The analytical framework modeled market dynamics across the analysis window, segmenting by equipment type, end-user sector, and regional industrial growth. Compound Annual Growth Rates (CAGRs) were derived from a quantitative model integrating these variables. Energy transition investments served as a key industry-specific forecast input.
Macroeconomic conditions sit as an overlay; deviation in global industrial output or energy commodity prices would shift the trajectory. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Quarterly review of industrial production indices and new project announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Crane Rail Market
Construction Equipment
Bale Openers Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Case Erectors Market