
 Bitumen Sprayer Market | 2026-2036
Bitumen Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen Sprayer Market Outlook
Chinese equipment manufacturing is decoupling from traditional pneumatic-heavy output toward hydraulic and electric platforms. XCMG leverages its domestic supply chain scale to dominate truck-mounted sprayer assembly lines across Asia. AMMANN Group anchors its European position through specialized road construction machinery with ISO-certified production protocols. Fayat Group competes on technology leadership in precision spraying systems for high-specification paving contracts.
A bitumen sprayer is a purpose-built machine that heats and distributes bituminous binder at controlled temperatures and application rates onto road surfaces, typically operating at spray bar widths of two to six meters and tank capacities ranging from three to fifteen thousand liters. Its primary industrial purpose is to create uniform tack coats, prime coats, and surface dressings that ensure proper adhesion between asphalt layers in road construction and maintenance. Truck-mounted sprayers lead product type demand due to their mobility and integration with highway fleets, while pneumatic technology retains share in emerging markets though hydraulic systems capture margin pools in premium paving segments. Electric sprayer variants represent the fastest-growing technology category as contractors face tightening emission compliance on urban job sites.
The EPA enforces emission standards that restrict diesel-powered equipment operation in non-attainment zones, directly shaping electric sprayer R&D priorities among US manufacturers. ECHA REACH regulations govern chemical handling in European bitumen distribution, requiring sealed heating systems and operator exposure controls that elevate equipment specification thresholds. India's BIS certification mandates structural and safety standards for road construction machinery sold to government agencies, creating a compliance gateway for market access. Stakeholders must monitor how overlapping national emission frameworks and infrastructure procurement rules reshape equipment specification requirements across their served geographies.
Market Dynamics
The EU F-Gas Regulation and EPA emission standards are compressing diesel-powered sprayer viability, forcing manufacturers to reconfigure thermal systems and powertrains around electric and hydraulic architectures. This regulatory compression is reshaping R&D allocation, supply chain partnerships, and equipment specification requirements across highway construction procurement.
Growth Catalysts
- National highway widening projects:India's Ministry of Road Transport and Highways is expanding fleet purchases of truck-mounted sprayers for continuous bitumen application on multi-lane corridor development.
- REACH chemical handling mandates:ECHA regulations governing bitumen distribution require sealed heating systems and operator exposure controls, elevating equipment specification thresholds and replacement demand.
- Electric platform development:Battery-electric powertrains are penetrating urban job sites where diesel operation faces tightening non-attainment zone restrictions.
Market Restraints
- Steel and aluminum input volatility:Tank fabrication costs fluctuate with commodity pricing, compressing margin predictability for mid-tier equipment assemblers.
- Hydraulic component supply concentration:Precision pump and valve sourcing clusters in German and Japanese industrial centers, exposing procurement to single-source risk.
- Technical limitation in cold-climate battery performance:Electric sprayer operating range degrades below minus fifteen degrees Celsius, restricting year-round deployment in northern geographies.
Strategic Opportunities
- Underpenetrated municipal maintenance segments:Indian state public works departments are upgrading from manual spray methods to mechanized equipment for rural road resurfacing programs.
- Technology convergence of telematics and precision spraying:GPS-guided application rate control is integrating with fleet management platforms to reduce binder waste and document compliance.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for construction equipment is attracting component localization investments.
Industry Challenges
- Skill gap in mechatronic maintenance:Field technicians trained on pneumatic and mechanical systems require retraining for electric drivetrain and electronic control diagnostics.
- BIS certification timeline compression:Road construction machinery sold to Indian government agencies faces extended testing and approval cycles that delay market entry.
- Integration complexity with legacy fleet management:Telematics-enabled sprayers must interface with existing contractor ERP and maintenance scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen Sprayer Market |
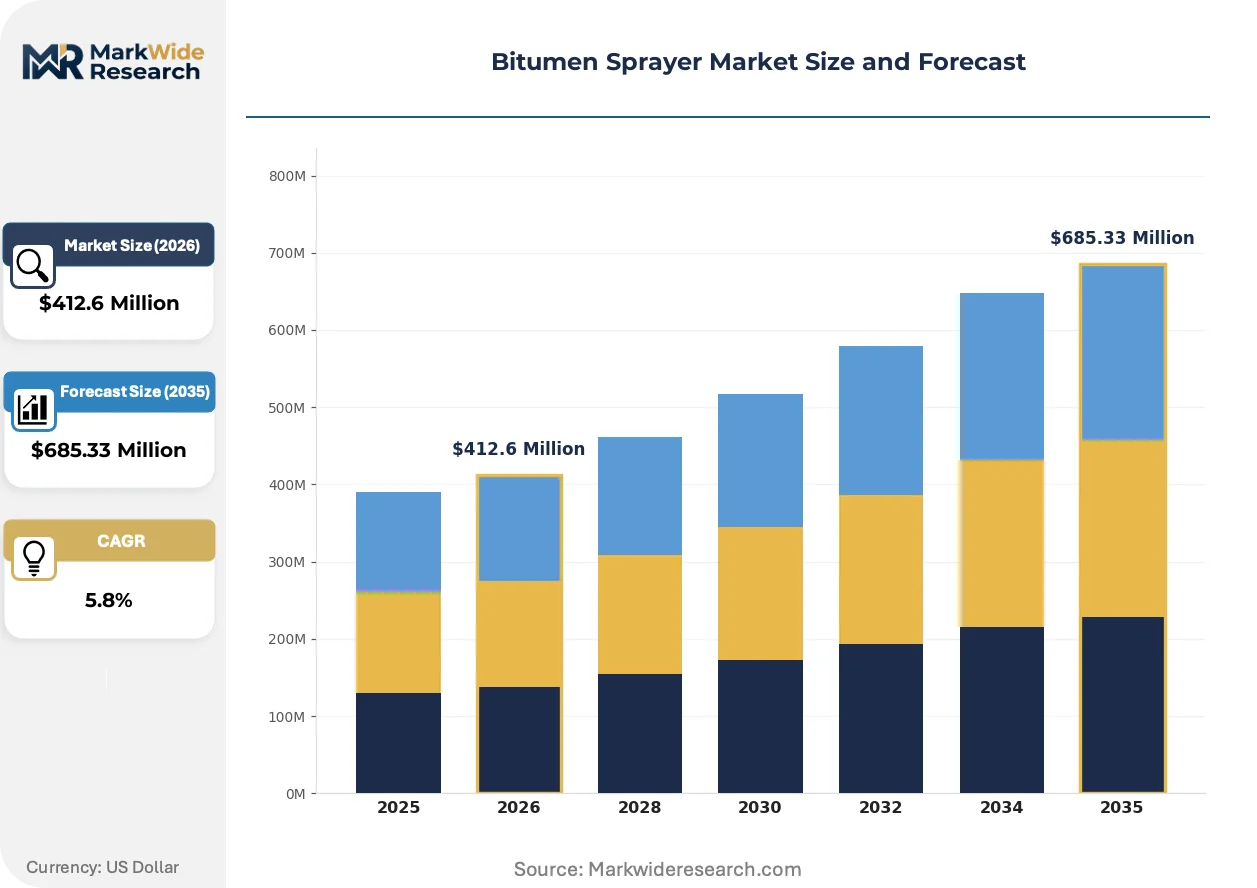
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Bitumen Sprayers, Stationary Bitumen Sprayers, Truck-mounted Sprayers, Trailer-mounted Sprayers Application: Road Construction, Paving, Sealing, Roofing Technology: Pneumatic, Hydraulic, Electric, Manual End User: Construction Companies, Governments, Road Maintenance Agencies, Contractors |
| Companies Covered | Weisig Maschinenbau GmbH, Zhejiang Metong Road Construction Machinery, AMMANN Group, XCMG, AB Volvo, Fayat Group, Schäfer Technic, ACMAR, Atlas Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen Sprayer Market Strategic Shifts
Equipment architecture is bifurcating between emission-compliant electric platforms for urban deployment and refined hydraulic systems for high-volume highway contracts. This divergence is fragmenting R&D roadmaps and supplier relationships across the manufacturer base.
Electric bitumen sprayer technology is electrifying urban construction equipment fleets. Municipal contractors in European non-attainment zones are adopting battery-powered units to maintain EPA and local air quality compliance. This transition is electrifying the product mix, compressing diesel engine supplier relationships while opening procurement channels to battery and power electronics vendors.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition in bitumen heating systems. Manufacturers must redesign thermal management around lower-global-warming-potential alternatives or electric resistance heating. European premium paving segments are absorbing specification upgrades fastest, with German and French highway agencies embedding F-Gas compliance into tender requirements.
Indian national highway authorities are consolidating equipment procurement through centralized fleet leasing arrangements. State-level road agencies are shifting from ownership to long-term rental models with bundled maintenance. This concentration is visible in Maharashtra and Gujarat, where widening projects now specify contractor-provided equipment rather than agency-owned assets.
Bitumen Sprayer Market Segmentation
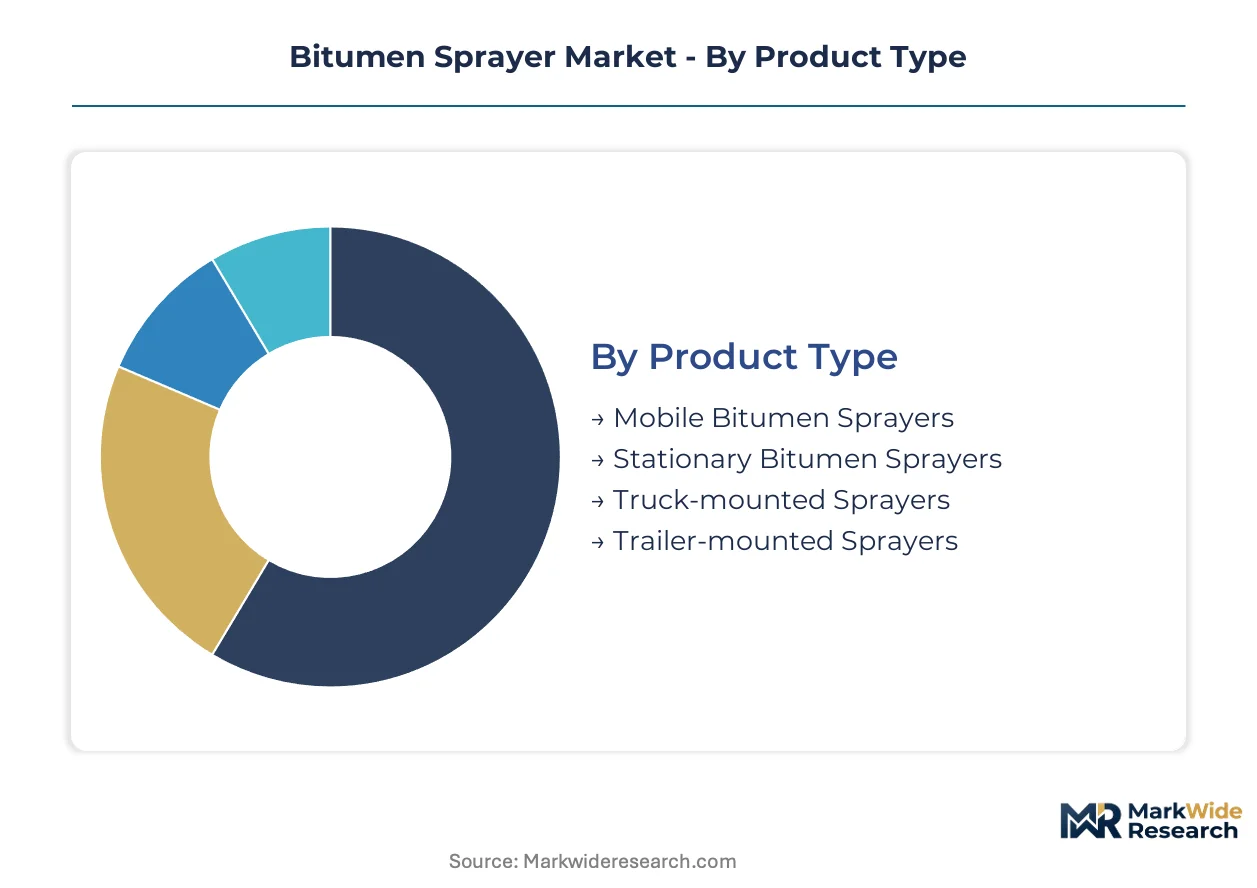
Equipment specification requirements vary sharply across deployment contexts. Highway agencies prioritize mobility and continuous operation capacity, while municipal maintenance programs balance capital constraints against mechanization gains. Technology platform selection increasingly hinges on emission compliance geography rather than pure performance metrics.
Product Type:
Fleet procurement managers weigh mobility against tank capacity and integration complexity when selecting equipment configurations.
- Truck-mounted Sprayers:These units integrate heating tanks, pumping systems, and spray bars onto commercial chassis for seamless highway fleet deployment. India's Ministry of Road Transport and Highways is expanding centralized leasing arrangements for these units on multi-lane corridor projects in Maharashtra and Gujarat.
- Mobile Bitumen Sprayers:Self-propelled designs with independent powertrains enable rapid repositioning across dispersed job sites without chassis dependency. Demand concentrates in European urban maintenance contracts where EPA non-attainment zone restrictions favor emission-compliant platforms.
- Stationary Bitumen Sprayers:Fixed-installation systems serve centralized asphalt production facilities with high-throughput binder distribution.
- Trailer-mounted Sprayers:Towable configurations offer lower capital entry points for regional contractors serving rural road networks.
Truck-mounted sprayers lead on scale; mobile sprayers lead on momentum.
Application:
Surface preparation intensity and binder specification requirements create distinct equipment performance tiers.
- Road Construction:Tack coat and prime coat applications demand precise temperature control and uniform spray bar distribution across two-to-six-meter widths. German highway agencies embed F-Gas Regulation compliance into tender specifications for thermal management systems.
- Paving:Continuous binder application during asphalt laying requires synchronized operation with paver fleets and real-time flow rate adjustment.
- Sealing:Surface dressing applications prioritize rapid deployment and minimal traffic disruption on maintenance schedules.
- Roofing:Modified bitumen membrane installation uses smaller-capacity units with specialized spray patterns for waterproofing systems.
Road construction commands the largest equipment volumes; paving applications are climbing fastest on highway widening intensity.
Technology:
Regulatory compression on diesel emissions is fragmenting R&D roadmaps across powertrain architectures.
- Electric:Battery-electric powertrains eliminate tailpipe emissions for urban job site compliance. Municipal contractors in European non-attainment zones are adopting these units to satisfy EPA and local air quality mandates, though operating range degrades below minus fifteen degrees Celsius.
- Hydraulic:Precision pump and valve systems deliver controlled application rates for high-specification paving contracts. German and Japanese industrial centers concentrate component supply, exposing procurement to single-source risk.
- Pneumatic:Compressed-air systems retain share in emerging markets with lower specification thresholds and limited emission enforcement.
- Manual:Hand-operated equipment serves small-scale maintenance in underpenetrated municipal segments upgrading from traditional spray methods.
Hydraulic systems dominate premium paving margins; electric platforms are gaining share fastest on regulatory pressure.
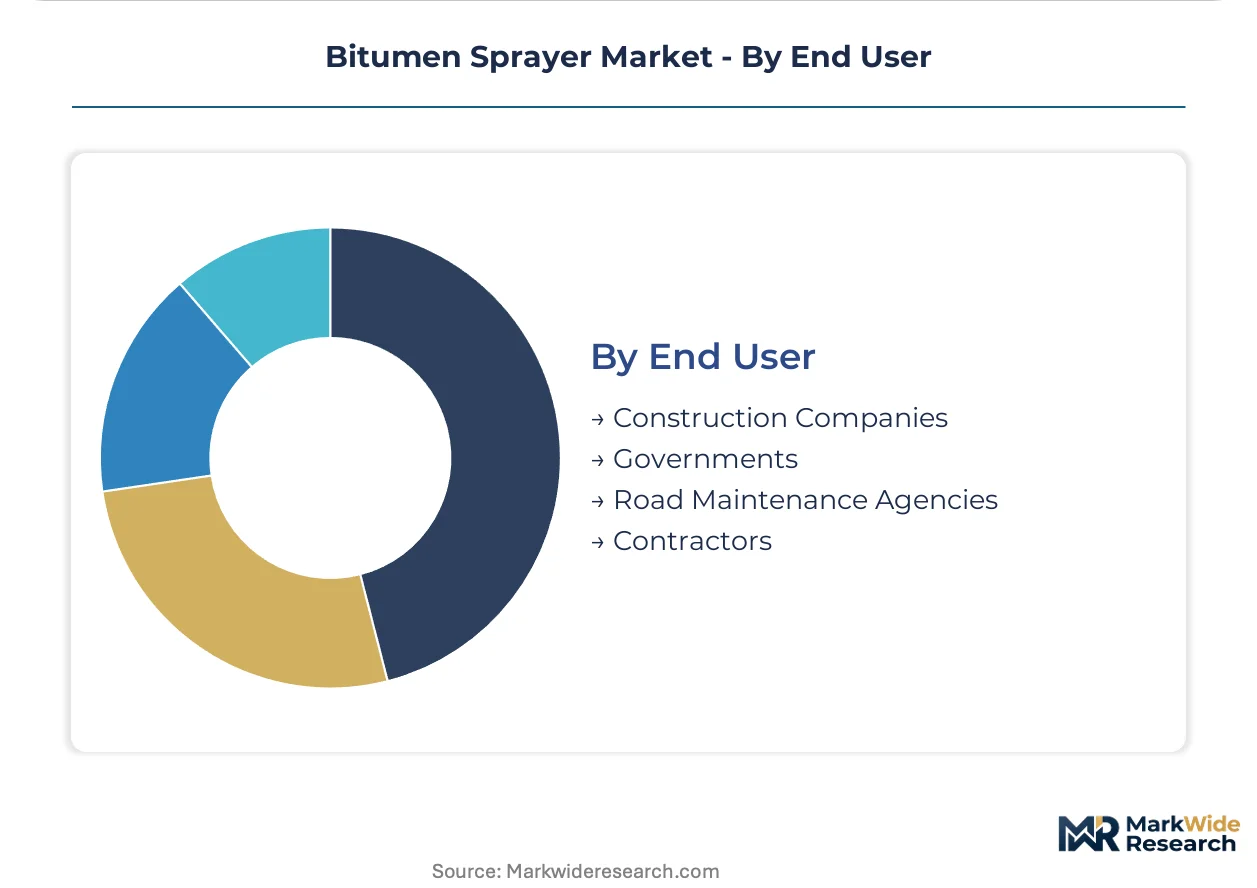
End User:
Procurement centralization and ownership models reshape equipment specification and service bundling requirements.
- Governments:National highway authorities in India are consolidating fleet purchases through centralized leasing with bundled maintenance, shifting from agency ownership to contractor-provided equipment models.
- Road Maintenance Agencies:State-level public works departments mechanize rural resurfacing programs, creating replacement demand from manual spray methods.
- Construction Companies:Integrated contractors serving multi-lane corridor development specify truck-mounted units with telematics integration for fleet management platforms.
- Contractors:Independent operators prioritize capital efficiency and rapid depreciation recovery on equipment utilization rates.
Government procurement leads on volume concentration; road maintenance agencies are expanding fastest on mechanization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate toward jurisdictions with lower emission compliance costs while demand concentrates in high-infrastructure-spending markets. Equipment specification thresholds now diverge sharply between mature emission-control regimes and emerging mechanization zones.
Germany
Highway agencies in Bavaria and North Rhine-Westphalia are embedding EU F-Gas Regulation compliance into tender specifications for thermal management systems. The KBA enforces stringent type-approval standards for road construction machinery sold to federal and state procurement programs. Industrial clusters around Stuttgart and Munich concentrate precision hydraulic component fabrication for premium paving equipment.
India
National highway widening projects across Maharashtra and Gujarat are driving centralized fleet leasing arrangements for truck-mounted sprayers. The BIS mandates structural and safety certification for machinery sold to government agencies, creating compliance gateways for market access. Manufacturing investment is concentrating in Tamil Nadu and Karnataka under PLI scheme incentives for construction equipment localization.
China
XCMG leverages domestic supply chain scale to dominate truck-mounted sprayer assembly across Asia-Pacific markets. The MIIT enforces GB standards for construction machinery emissions and safety protocols. Production gravity centers on Xuzhou and Shanghai industrial corridors where integrated chassis-tank fabrication achieves cost efficiencies.
United States
Municipal contractors in California and Texas are adopting electric sprayer platforms to satisfy EPA non-attainment zone restrictions on diesel equipment operation. The EPA enforces emission standards that directly shape manufacturer R&D priorities toward battery-electric architectures. Equipment distribution clusters around Houston and Los Angeles metro areas serving multi-state highway maintenance contracts.
France
Fayat Group anchors technology leadership in precision spraying systems for high-specification paving contracts across Île-de-France and Auvergne-Rhône-Alpes. The EU Green Deal implementation is accelerating refrigerant transition schedules in bitumen heating systems. Lyon and Paris metropolitan procurement offices are specifying telematics-enabled equipment for fleet compliance documentation.
Bitumen Sprayer Market Competitive Environment
German producers anchor the premium-tier segment; Chinese fabricators hold the scale-driven volume tier. The vendor base splits between consolidated multinational machinery groups and specialized regional equipment assemblers. Strategic archetypes include integrated highway fleet suppliers, precision spraying technology specialists, and emerging-market cost-optimized fabricators. Dominant competitive moves encompass geographic expansion through distributor partnerships and portfolio diversification into electric platform development.
Among German-based manufacturers, Weisig Maschinenbau GmbH and Schäfer Technic occupy positions within the precision-engineering archetype, exemplifying specialized road construction machinery production with ISO-certified protocols. Chinese fabricators Zhejiang Metong Road Construction Machinery and XCMG represent the scale-integrated tier, anchoring domestic supply chain advantages for truck-mounted sprayer assembly across Asia-Pacific markets. AMMANN Group and Fayat Group sit within the multinational technology-leadership tier, serving high-specification paving contracts with advanced thermal management and application control systems.
| Leading Market Players |
|---|
| Weisig Maschinenbau GmbH |
| Zhejiang Metong Road Construction Machinery |
| AMMANN Group |
| XCMG |
| AB Volvo |
| Fayat Group |
| Schäfer Technic |
| ACMAR |
| Atlas Technologies |
| Others |
Value Chain & Pricing Dynamics
Steel and aluminum tank fabrication costs cascade through three distinct pricing tiers, with commodity volatility compressing margins for mid-tier assemblers while premium hydraulic systems command specification premiums in German and Japanese procurement channels.
Pricing Analysis
Distributor margins widen on electric platform sales where EPA non-attainment zone compliance creates captive demand. Three-tier pricing structure across premium, standard, and economy levels separates ISO-certified European thermal systems from Chinese pneumatic units and manual equipment for rural Indian maintenance programs. Price differentiation hinges on certification grade and after-sales service bundling, with government fleet buyers in India exhibiting lowest sensitivity due to PLI scheme offsets. Cost compression in the standard tier intensifies because steel input volatility erodes assembler margin predictability.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Xuzhou, and Houston anchor hub-and-spoke patterns serving highway construction corridors. Hydraulic component supply concentrates in Germany and Japan, exposing procurement to single-source vulnerability when precision pump and valve lead times extend. Bitumen sprayer manufacturing draws from steel tank fabrication, electronic control modules, and battery power electronics as core inputs. Distribution runs through OEM-direct channels for fleet procurement and specialized distributors for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory pressure into equipment replacement cycles, with EU F-Gas Regulation phase-down schedules embedding compliance costs into tender specifications across European highway agencies.
For Market Incumbents: Deepen backward integration into precision hydraulic component fabrication to offset single-source concentration risk from German and Japanese suppliers. Expand captive heating system production capacity to capture margin pools from F-Gas refrigerant transition mandates, while defending against emerging Chinese electric platform entrants through ISO-certified service bundling.
For New Entrants and Emerging Players: Begin with underpenetrated Indian state public works departments mechanizing rural road resurfacing programs from manual spray methods. Target trailer-mounted configurations for regional contractors in Maharashtra and Gujarat as the most penetrable capital-efficient entry point, then leverage PLI scheme localization incentives to establish component assembly presence in Tamil Nadu.
For Investors and Strategic Acquirers: Consolidation pressure builds where hydraulic technology specialists lack electric platform R&D capabilities and face stranded asset risk from emission compliance timelines. Long-term viability favors targets with dual-architecture competence spanning refined hydraulic systems and battery-electric powertrains. Watch Indian BIS certification approval velocity as the inflection indicator for market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Platform Development | Battery-electric powertrains satisfy EPA non-attainment zone restrictions for municipal contractors in California and Texas. |
| Hydraulic Component Localization | In-house precision pump fabrication reduces single-source dependency on German and Japanese industrial centers. |
| F-Gas Compliant Thermal Systems | Lower-global-warming-potential refrigerant designs meet EU Green Deal procurement specifications in Bavaria and Île-de-France. |
| Telematics Integration Partnership | GPS-guided application control interfaces with contractor ERP platforms to document compliance and reduce binder waste. |
| PLI Scheme Manufacturing Investment | Component localization in Tamil Nadu and Karnataka accesses Indian government fleet procurement preference. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with highway agency procurement officers, construction equipment fleet managers, hydraulic component sourcing leads, and aftermarket service heads with secondary validation from customs trade data, SEC machinery filings, EIA infrastructure spending disclosures, and BIS certification registries. Bottom-up equipment shipment triangulation against top-down highway construction budget analysis anchored volume estimates.
Segment-weighting applied product type, technology platform, application intensity, and end-user procurement centralization as core dimensions across the projection horizon. CAGRs derived from regression analysis of historical fleet purchase patterns against regulatory milestone schedules, with electric platform penetration curves and steel price elasticity as industry-specific forecast inputs.
Caveats apply where battery cold-climate performance limitations or BIS certification timeline compression could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Grader Blades Market
Construction Equipment
Compact Loaders Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
GCC Crane Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Global Hydraulic Hammer Market