
 Drilling Machine Market | 2026-2036
Drilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Machine Market Intelligence
Modular drill rig configurations with swappable mast and power-pack units is realigning capital deployment patterns for mid-size contractors. DMG MORI leverages its CNC spindle integration to dominate precision metalworking applications. Atlas Copco sustains its underground mining franchise through captive compressor-driller bundling. Sandvik AB anchors its position via carbide-insert supply backward into drill string manufacturing.
A drilling machine is a motorized or manually operated device that rotates a cutting tool or drill bit against a workpiece to produce cylindrical holes, typically specified by spindle speed ranges, quill travel distances, and maximum drilling diameters. Its primary industrial purpose is hole generation in metals, composites, concrete, wood, and geological formations for assembly, extraction, or construction. CNC Drills command the highest margin pools in aerospace manufacturing where tolerances below 0.01 mm justify premium pricing. Pneumatic Technology retains share in mining and tunneling where explosive atmospheres restrict electric alternatives. Magnetic Base Drills occupy a growing niche in shipyard steel plate fabrication where portability outweighs fixed-machine precision.
The US Mine Safety and Health Administration mandates continuous methane monitoring on underground coal drills, forcing electric and battery-powered retrofits. China's MIIT enforces GB standards on machine tool energy efficiency that filter import eligibility for foreign builders. The EU's CE marking and Machinery Directive impose functional-safety validation on automated drilling cells entering European fabrication shops. Stakeholders must monitor how battery energy density advances against pneumatic reliability in underground duty cycles.
Market Dynamics
Modular drill rig architectures are fragmenting capital deployment patterns across mid-size contractors, forcing manufacturers to unbundle mast and power-pack configurations while Australia's declining ore grades accelerate fleet renewal cycles.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon refrigerants is accelerating electric-drive substitution for pneumatic underground equipment in European mining operations.
- China's Shanxi coal basin:Concentrated demand from coal extraction and surrounding heavy manufacturing clusters is sustaining order volumes for high-tonnage drill rigs.
- GB standards enforcement:China's MIIT energy efficiency mandates are filtering import eligibility and elevating domestic equipment specifications across machine tool categories.
Market Restraints
- Carbide supply concentration:Tungsten carbide insert production clusters in select Asian supply zones create vulnerability for drill string manufacturers dependent on captive raw material flows.
- Explosive atmosphere restrictions:Pneumatic technology retains mandatory deployment in gassy underground seams where methane accumulation prohibits electric alternatives.
- CE marking compliance costs:The EU Machinery Directive's functional-safety validation requirements impose extended certification timelines for automated drilling cells entering European fabrication shops.
Strategic Opportunities
- Battery energy density advances:Lithium-ion cell chemistry improvements are creating white space for cordless underground drill retrofits against entrenched pneumatic reliability.
- Shipyard steel plate fabrication:Magnetic base drill portability is capturing share in maritime construction where fixed-machine precision is secondary to maneuverability.
- US MSHA methane mandates:Continuous monitoring requirements on underground coal drills are forcing electric and battery-powered equipment conversions across Appalachian operations.
Industry Challenges
- CNC spindle integration complexity:Aerospace tolerance demands below 0.01 mm require specialized technician pools that mid-tier manufacturers struggle to recruit and retain.
- Legacy pneumatic infrastructure:Existing compressor networks and maintenance protocols create switching friction for contractors evaluating electric-drive alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Machine Market |
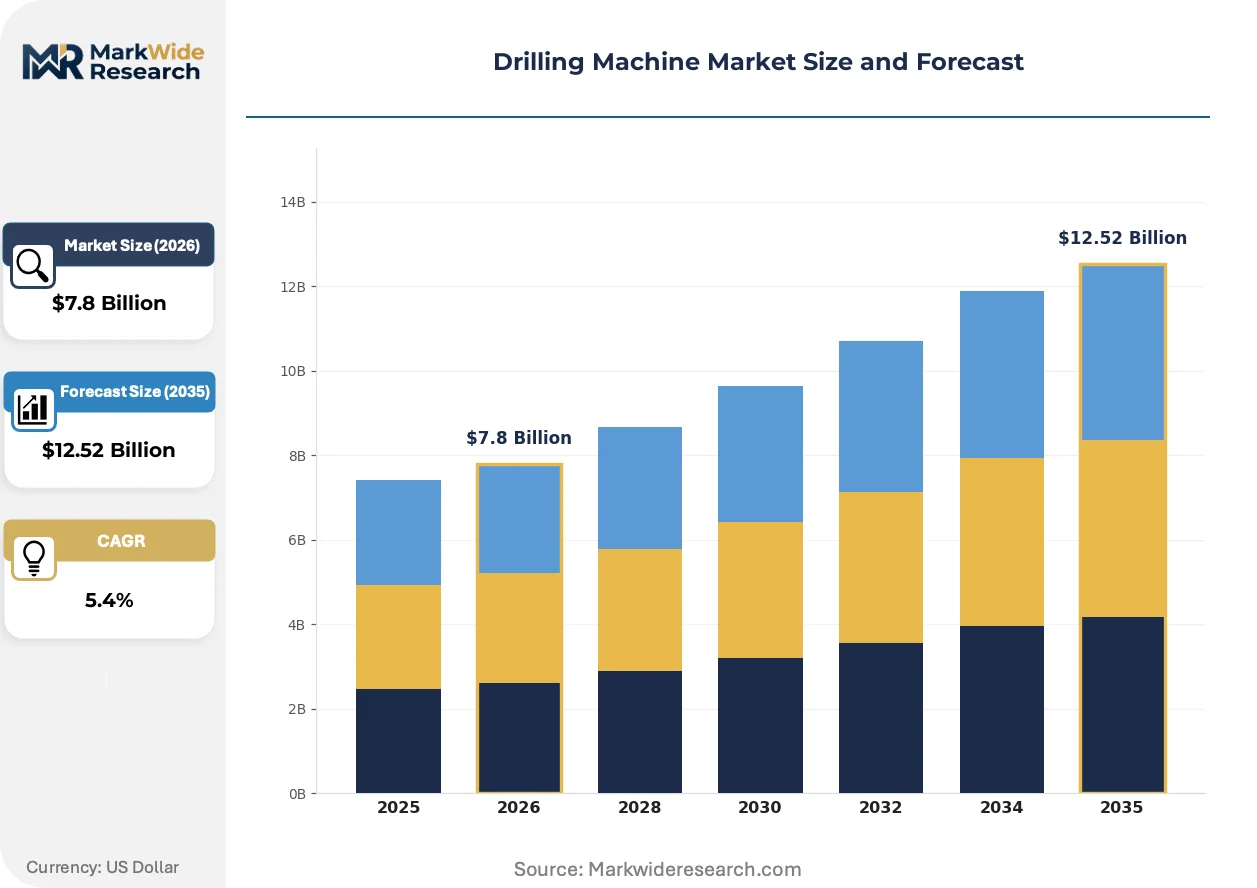
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Radial Arm, Gang Drills, CNC Drills, Magnetic Base Drills Technology: Electric, Pneumatic, Hydraulic, Cordless, Magnetic Drilling Application: Metal Fabrication, Construction Sites, Shipbuilding, Aerospace Manufacturing, Woodworking End User: Machine Shops, Fabricators, Aircraft Assemblers, Shipyards, Contractors |
| Companies Covered | DMG MORI, Atlas Copco, Sandvik AB, Robert Bosch GmbH, Shenyang Machine Tool Corp Ltd, Dalian Machine Tool Corporation, Hitachi Construction Machinery Ltd, Ingersoll Rand, Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Machine Market Strategic Shifts & Innovations
Drill rig automation and powertrain electrification are compressing operating cost structures while reshaping how contractors evaluate total cost of ownership across duty cycles.
Battery-electric drill systems are absorbing share in underground mining applications where ventilation costs and diesel particulate exposure have tipped lifecycle economics. Tier-one operators in Australian hard-rock operations are piloting fast-swap battery packs to maintain continuous shift productivity. The technology is absorbing capital previously allocated to ventilation infrastructure and respiratory protection compliance.
The EU F-Gas Regulation is forcing refrigerant-dependent pneumatic cooling systems toward obsolescence in European underground operations. Compressor-driller bundling strategies that anchored historical market positions now face retrofit cost burdens. Underground mining franchises with heavy European exposure are accelerating electric platform development to preserve installed base relationships.
Service unbundling is separating maintenance contracts from original equipment sales in fabrication shop segments. Independent service providers are capturing aftermarket revenue through remote diagnostics and predictive spindle replacement programs. This pattern is most visible in North American aerospace manufacturing clusters where OEM-agnostic support reduces downtime penalties.
Drilling Machine Market Segmentation
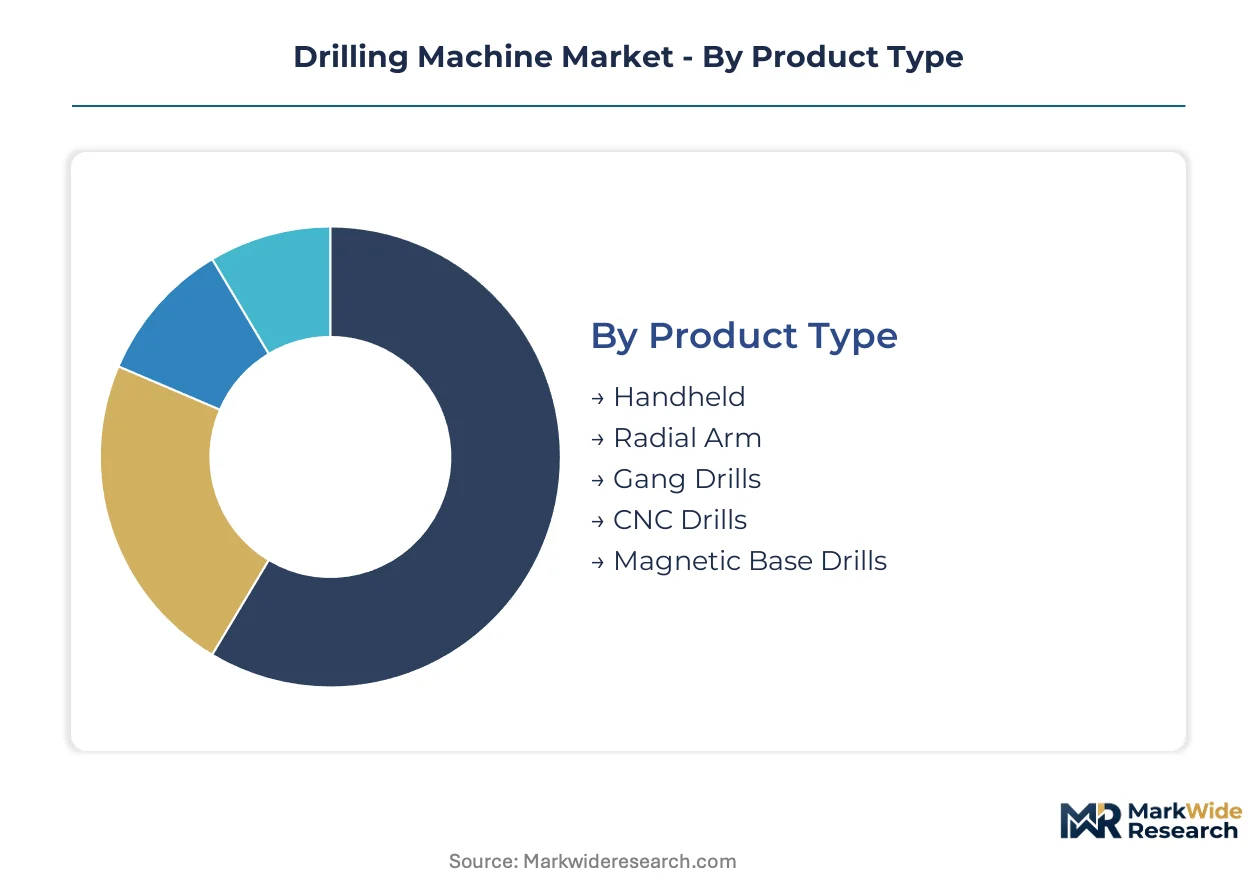
Drilling machine procurement splits sharply between standardized volume equipment and application-specific engineered systems. Contractors optimize fleet mix across product tiers while regulatory mandates in mining and aerospace force technology-specific sourcing decisions.
Product Type:
Customization intensity varies from commodity handheld units to precision-engineered CNC platforms requiring spindle integration and control architecture tailoring.
- CNC Drills:Computer-numerical control platforms integrate multi-axis spindle positioning with automated tool changers for hole patterns below 0.01 mm tolerance. Aerospace manufacturing clusters in Toulouse and Seattle concentrate demand where airframe assembly justifies premium capital deployment against labor cost arbitrage.
- Magnetic Base Drills:Electromagnetic clamping systems enable portable drilling on vertical steel surfaces without fixture infrastructure. Shipyards in South Korea and Germany absorb volume where hull section maneuverability outweighs fixed-machine precision constraints.
- Handheld:Compact pistol-grip and angle-head configurations serve maintenance crews for field repairs and light fabrication.
- Radial Arm:Articulated spindle positioning over large workpieces dominates legacy machine shop floors with mixed-batch production.
- Gang Drills:Multi-spindle fixed-head arrays execute simultaneous hole patterns in high-volume automotive component lines.
Leading the category by volume: Handheld. Expanding most quickly: Magnetic Base Drills.
Technology:
Powertrain selection hinges on duty cycle environment — electric dominates fabrication shops while pneumatic retains captive share in gassy underground seams.
- Electric:AC and DC motor drives deliver precise speed control with energy efficiency compliance under China's GB standards. Machine shops across Germany's Baden-Württemberg region favor three-phase induction systems for continuous production economics.
- Pneumatic:Compressed-air actuation eliminates ignition risk in methane-accumulating coal seams. Australia's Bowen Basin operators maintain fleet parity where MSHA-equivalent ventilation mandates restrict battery alternatives.
- Hydraulic:High-torque fluid power systems penetrate foundation drilling and piling rigs for geotechnical construction.
- Cordless:Lithium-ion battery packs enable untethered operation in remote maintenance and confined-space retrofit work.
- Magnetic Drilling:Integrated electromagnetic clamping with electric spindle drive hybridizes portability and cutting stability.
Dominant by installed base: Electric. Steepest expansion trajectory: Cordless.
Application:
End-use concentration patterns reflect capital intensity — aerospace commands precision premiums while construction absorbs volume through rental channels.
- Metal Fabrication:Structural steel and plate processing drives gang drill and radial arm deployment. Fabricators in India's Gujarat cluster source mid-tonnage equipment for infrastructure project subcontracting.
- Aerospace Manufacturing:Titanium and composite drilling demands thermal management and vibration damping. Tier-one suppliers around Toulouse, Hamburg, and Wichita specify spindle-integrated platforms for wing box and fuselage assembly.
- Construction Sites:Mobile foundation drilling and anchor bolt installation absorb crawler-mounted hydraulic rigs.
- Shipbuilding:Hull section assembly and outfitting favors magnetic base portability over fixed gantry systems.
- Woodworking:Furniture and millwork operations deploy benchtop and column drills for dowel and hardware insertion.
Highest margin pool: Aerospace Manufacturing. Volume leader: Metal Fabrication.
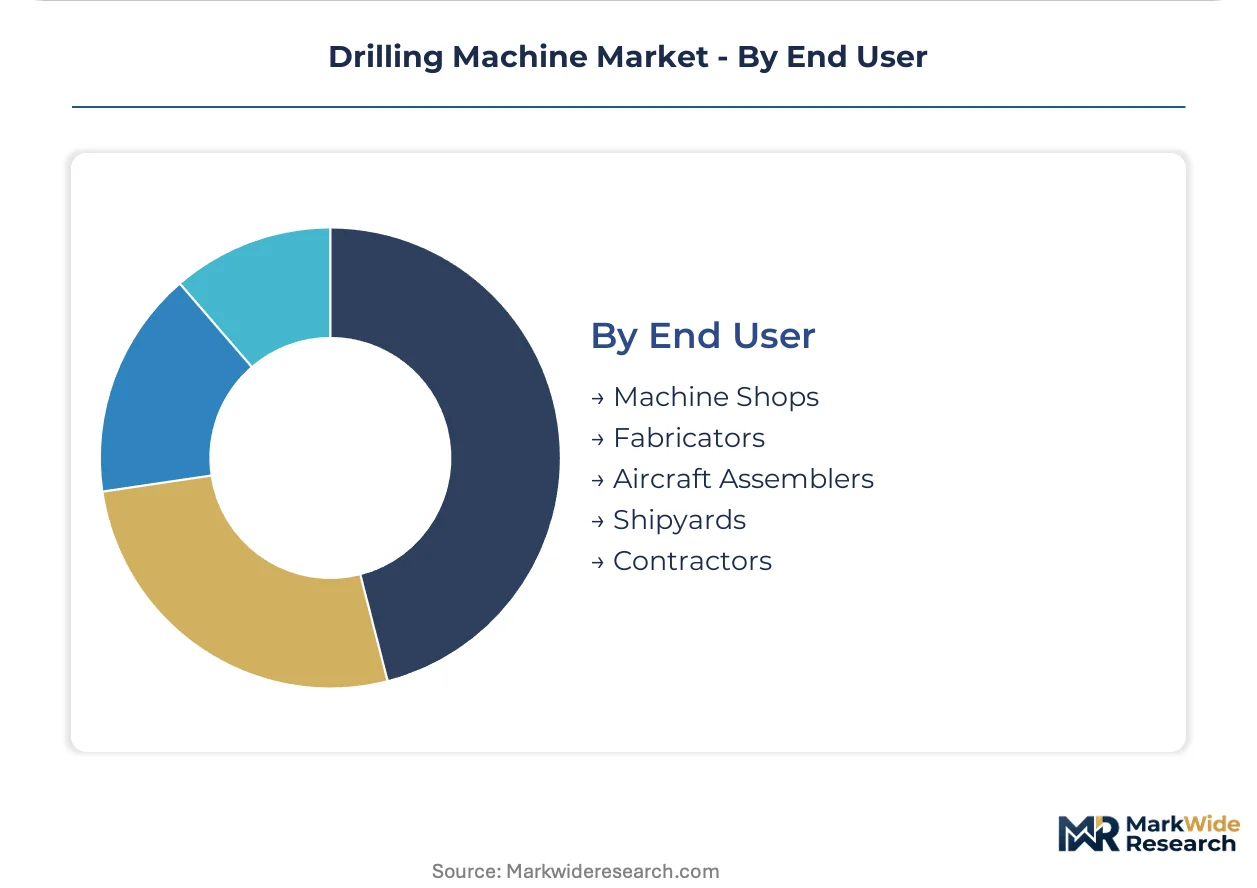
End User:
Procurement sophistication stratifies — aircraft assemblers specify integrated cells while contractors prioritize rental availability and field service response.
- Aircraft Assemblers:Prime contractors and tier-one aerostructures manufacturers mandate CNC platform certification for airworthiness traceability. Boeing's Everett and Airbus's Hamburg final assembly lines drive specification standards across supplier tiers.
- Shipyards:Korean majors Hyundai Heavy and DSME deploy magnetic base fleets for double-hull construction productivity.
- Machine Shops:Job shops and production facilities balance flexibility against spindle utilization rates across mixed customer portfolios.
- Fabricators:Steel service centers and structural contractors source radial arm and gang configurations for beam and plate processing.
- Contractors:Rental-dependent construction and mining operators prioritize equipment availability over ownership economics.
Specification authority concentrates: Aircraft Assemblers. Rental volume leader: Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates drilling machine production capacity while Australia and Germany absorb premium equipment for mining and precision manufacturing. Consumption patterns diverge sharply between commodity volume markets and specification-driven aerospace and underground mining segments.
China
Shanxi province coal basin operators drive high-tonnage rig demand alongside heavy manufacturing clusters in Jiangsu and Shandong. MIIT enforces GB standards on machine tool energy efficiency that filter import eligibility for foreign builders. Zhengzhou and Dalian machine tool concentrations anchor domestic supply for infrastructure and automotive component drilling.
Australia
Bowen Basin hard-rock operators accelerate fleet renewals as ore grades decline and ventilation costs mount. State-level mining safety regulators enforce methane monitoring protocols equivalent to US MSHA standards. Perth-based mining services contractors pilot fast-swap battery packs to maintain continuous shift productivity in Pilbara iron ore operations.
Germany
Baden-Württemberg machine shops favor three-phase electric induction systems for continuous production economics in automotive supplier tiers. The EU F-Gas Regulation accelerates electric-drive substitution for pneumatic underground equipment. Stuttgart and Munich aerospace clusters specify CNC platforms with spindle integration for titanium and composite drilling below 0.01 mm tolerance.
United States
Appalachian underground coal operations face MSHA-mandated continuous methane monitoring that forces electric and battery-powered retrofits. Everett and Wichita final assembly lines drive specification standards across Boeing supplier tiers for airframe drilling cells. Texas and Gulf Coast fabrication shops absorb radial arm and gang drill volumes for energy infrastructure subcontracting.
South Korea
Hyundai Heavy and DSME shipyards deploy magnetic base drill fleets for double-hull construction productivity where hull section maneuverability outweighs fixed-machine precision. Korean occupational safety regulators align ventilation mandates with ISO standards for confined-space battery operation. Ulsan and Geoje shipbuilding concentrations sustain demand for portable electromagnetic clamping systems in maritime steel plate fabrication.
Drilling Machine Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive component supply and specialized precision engineering groups. Consolidation pressure runs high in CNC platforms where aerospace certification requirements favor established spindle integration capabilities. Three archetypes dominate: mining equipment bundlers leveraging compressor-driller integration, precision metalworking specialists with CNC control architecture, and carbide-insert backward integrators securing drill string raw material flows. Capacity expansion and strategic partnerships constitute the primary competitive moves, with electric platform development accelerating among European-exposed underground franchises.
Among diversified industrial conglomerates, DMG MORI and Atlas Copco occupy positions at opposite ends of the technology spectrum. DMG MORI represents the precision-engineering archetype through its CNC spindle integration dominance in aerospace manufacturing clusters. Atlas Copco exemplifies the bundling strategy that anchored historical underground mining market positions through captive compressor-driller offerings. Sandvik AB sits within the materials-anchored tier, its carbide-insert supply backward into drill string manufacturing creating defensive positioning against raw material volatility.
| Leading Market Players |
|---|
| DMG MORI |
| Atlas Copco |
| Sandvik AB |
| Robert Bosch GmbH |
| Shenyang Machine Tool Corp Ltd |
| Dalian Machine Tool Corporation |
| Hitachi Construction Machinery Ltd |
| Ingersoll Rand |
| Liebherr Group |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists across Germany's Baden-Württemberg machine tool belt anchor supply discipline through generational capital allocation patterns that resist short-term margin erosion. Their ownership structures buffer pricing volatility by maintaining captive service networks and long-dated customer relationships that transactional competitors cannot replicate.
Pricing Analysis
Margin tightening in standard CNC platforms traces to Chinese GB standards enforcement that elevates energy efficiency compliance costs for import-dependent fabricators. Three-tier pricing structure across aerospace-certified, industrial-grade, and economy machine tool levels separates buyers by spindle tolerance requirements and CE marking validation depth. Cost-down pressure on pneumatic underground equipment accelerates because EU F-Gas Regulation retrofits force compressor-driller bundling strategies toward obsolescence. Rental-dependent contractors exhibit highest price sensitivity; aerospace assemblers tolerate premium positioning for airworthiness traceability.
Supply Chain Analysis
Freight cost volatility from Asian tungsten carbide clusters to European drill string manufacturers has amplified raw material exposure for producers without backward integration into insert production. Supply concentrates in China's Zhengzhou and Dalian machine tool concentrations, Germany's Stuttgart precision engineering belt, and South Korea's Ulsan shipbuilding corridor. Carbide insert production draws from tungsten ore processing in Jiangxi province and cobalt refining in the DRC. Single-source vulnerability concentrates in carbide powder metallurgy where three Asian suppliers control spherical powder grades. Distribution runs through OEM-direct channels for aerospace-certified platforms and rental-services intermediaries for construction-site deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU F-Gas Regulation compliance costs and Chinese GB standards enforcement filter marginal pneumatic equipment producers from European and Asian markets. Survivors will possess captive carbide supply or CNC spindle integration capabilities that mid-tier assemblers cannot replicate.
For Market Incumbents: Lock in carbide-insert backward integration through long-term offtake agreements with Jiangxi tungsten processors before commodity volatility escalates. Accelerate electric platform development for European underground mining exposure where compressor-driller bundling faces regulatory obsolescence. Defensive patent positioning around fast-swap battery architectures for Australian hard-rock applications preserves installed base relationships against emerging cordless specialists. For New Entrants and Emerging Players: Mid-size Australian mining contractors with declining ore grade pressures represent an underserved buyer archetype seeking modular rig configurations with unbundled mast and power-pack units. White space concentrates in shipyard magnetic base drill segments where Korean and German hull construction demands portability over fixed-machine precision. Target battery-electric retrofits for Appalachian underground coal operations facing MSHA methane mandate conversions through equipment-as-a-service financing structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor carbide-integrated drill string manufacturers in China's Shanxi coal basin region where domestic MIIT standards enforcement elevates local specification authority. Long-term viability hinges on electric platform transition completion and aerospace certification maintenance across the projection horizon. Watch battery energy density advances against pneumatic reliability in underground duty cycles as the inflection signal for cordless substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Insert Production | Secures tungsten powder supply from Jiangxi processors against raw material volatility for drill string manufacturers. |
| Electric Platform Development for Underground Mining | Preserves European mining franchise relationships as EU F-Gas Regulation phases out pneumatic cooling systems. |
| Fast-Swap Battery Architecture Deployment | Maintains continuous shift productivity for Pilbara iron ore operators piloting cordless retrofits. |
| Modular Rig Configuration Unbundling | Captures capital-constrained mid-size contractors seeking flexible mast and power-pack deployment options. |
| Aerospace CNC Spindle Integration Investment | Defends margin pools in Toulouse and Seattle manufacturing clusters where sub-0.01 mm tolerances command premium positioning. |
Research Approach
Trade association filings, customs and import-export databases, and machine tool OEM technical documentation formed the secondary backbone for supply-side validation. Primary interviews with maintenance directors at Australian hard-rock operations, procurement leads at Korean shipyards, plant engineers in Germany's automotive supplier tiers, and aftermarket service heads at North American fabrication shops supplied demand-side triangulation. Bottom-up equipment shipment data and top-down industrial capital expenditure patterns were cross-referenced to establish volume baselines.
Bottom-up modeling aggregated segment-level demand across CNC platform, magnetic base, pneumatic, and cordless technology tiers. Top-down validation tested aggregate figures against national machine tool production statistics and mining capital expenditure surveys. Segmentation dimensions included product type, powertrain technology, end-use application, and regional regulatory cluster. CAGRs were derived from fitted trend lines across historical shipment data and projected replacement cycle intensities, with specific adjustment for Australia's ore grade decline trajectory and China's MIIT enforcement timeline.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery chemistry advances, EU F-Gas Regulation phase-down acceleration, and tungsten carbide supply concentration disruptions. Forecasts reflect assumptions about regulatory enforcement consistency and commodity price stability that industry stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Piles Turner Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Shield Machines Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
PU Casting Machine Market