
 Japan Waterjet Cutting Machines Market | 2026-2036
Japan Waterjet Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Waterjet Cutting Machines Market Insights
Market Context
Modular system bundling is pivoting buyer preference toward integrated waterjet platforms pairing cutting heads with automated material handling. Sugino Machine leverages its domestic manufacturing footprint to anchor supply relationships with Japanese automotive tier-one suppliers. Flow International Corporation competes through technology leadership in ultra-high-pressure pump systems for aerospace-grade applications. KMT Waterjet Systems sustains its position via specialized abrasive delivery systems optimized for hard-metal fabrication workflows.
Technical Definition and Segment Structure
Japan waterjet cutting machines are industrial fabrication systems using pressurized water streams—pure or abrasive-laden—to cut metals, composites, ceramics, and glass without thermal distortion, typically operating at pressures exceeding 60,000 psi. These systems serve precision manufacturing where heat-affected zones compromise material integrity, particularly in aerospace turbine components and automotive structural elements. Abrasive waterjet systems dominate installed base value due to their versatility across metal thicknesses, while micro waterjet represents the fastest-growing product category driven by electronics and medical device prototyping demand. CNC waterjet technology commands the technology segment's margin pool through software-integrated automation that reduces operator dependency and repeat-order cycle times.
Regulatory Framework
METI's energy efficiency standards and JIS certification requirements shape equipment procurement specifications, particularly for factory automation integration under the Industrial Value Chain Initiative. PMDA-adjacent manufacturing guidelines for medical device fabricators indirectly steer micro waterjet specification toward contamination-controlled cutting environments. Stakeholders must monitor evolving METI carbon-neutrality roadmaps for manufacturing equipment, as lifecycle emissions criteria increasingly filter into capital equipment selection protocols.
Market Dynamics
METI's Society 5.0 smart factory certification is compressing upgrade cycles for CNC-integrated waterjet platforms across Japan's precision manufacturing base, forcing capital equipment decisions toward automation-ready configurations.
Growth Catalysts
- Titanium aerospace demand:Heat-sensitive titanium and composite cutting requirements in Nagoya-Osaka corridors are pulling abrasive waterjet installations into tier-one supplier facilities.
- Industrial Value Chain Initiative:METI's factory automation integration mandates are accelerating procurement of software-integrated cutting systems with automated material handling.
- Micro waterjet electronics prototyping:Medical device and semiconductor fabrication workflows in Tokyo-Yokohama clusters are driving specification of contamination-controlled micro cutting environments.
Market Restraints
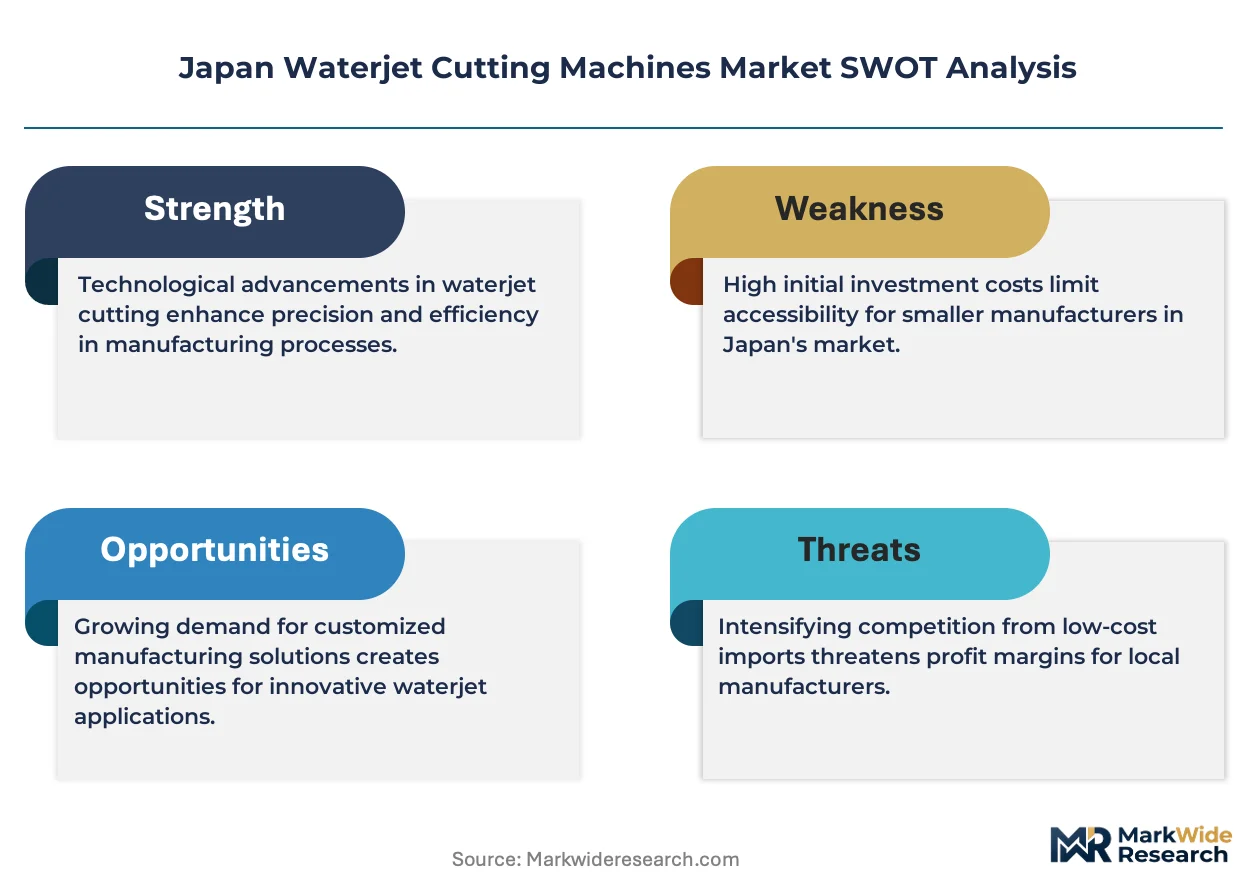
- Ultra-high-pressure pump import dependency:Domestic supply gaps in 60,000+ psi pump technology create exposure to overseas component lead times and currency fluctuation.
- Abrasive garnet cost volatility:Hard rock mining supply concentration outside Japan generates input price instability for abrasive waterjet operators.
- JIS certification timeline friction:Factory automation equipment approval protocols extend capital deployment cycles for mid-tier fabricators.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe manufacturing corridors show lower waterjet density per capita than Kanto, creating whitespace for precision fabrication equipment deployment.
- Carbon-neutrality equipment mandates:Evolving METI lifecycle emissions criteria will filter capital selection toward energy-efficient pump and recovery systems.
- 5G-enabled remote diagnostics:Convergence of industrial IoT sensors and predictive maintenance software is opening subscription-based service revenue streams.
Industry Challenges
- CNC-integrator skill scarcity:Shortage of technicians capable of calibrating software-integrated cutting heads with automated handling systems extends commissioning timelines.
- Legacy equipment retrofit complexity:Older mechanical cutting installations in tier-two automotive suppliers resist seamless integration with Society 5.0 data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Waterjet Cutting Machines Market |
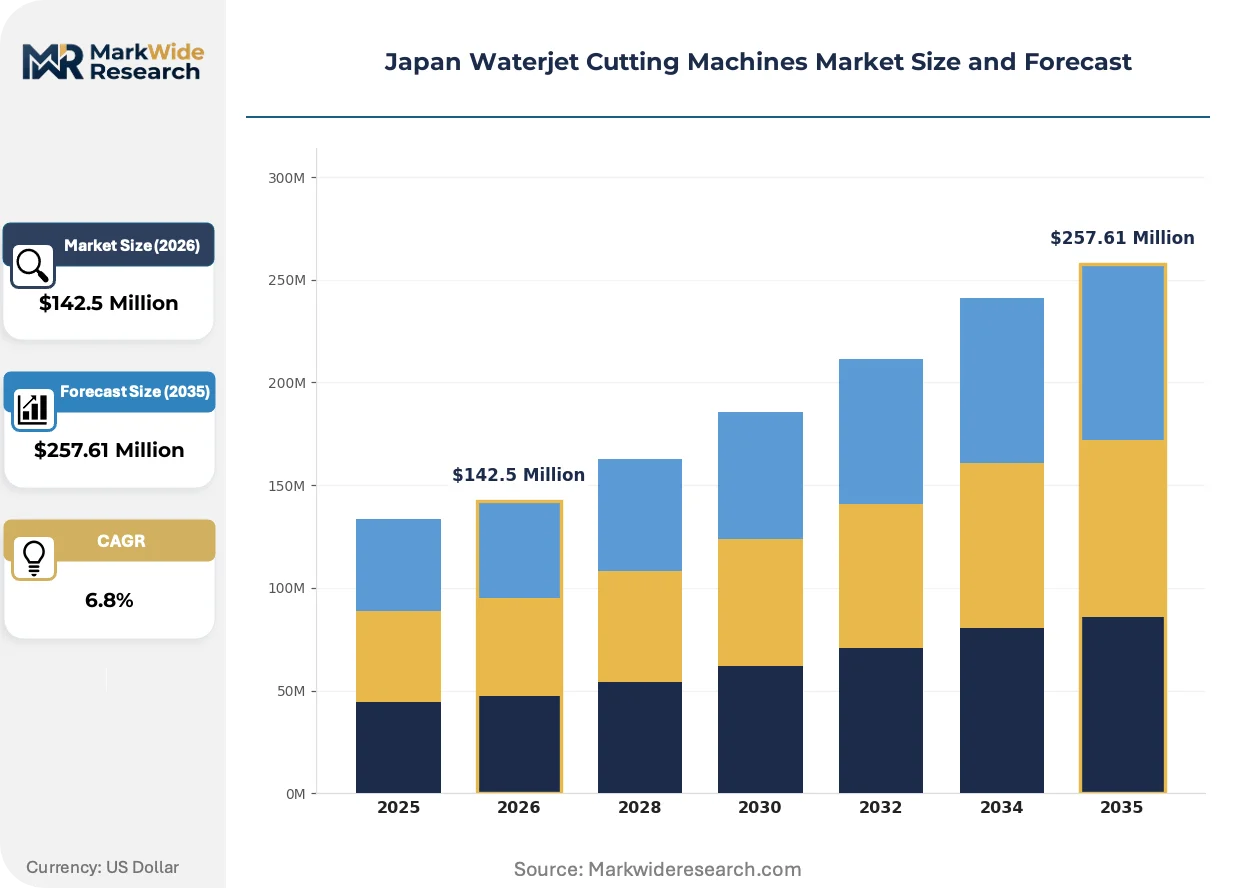
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Waterjet, Abrasive Waterjet, Combination, Micro Waterjet End User: Aerospace, Automotive, Tile & Glass, Metal Fabrication Technology: 2D Cutting, 3D Cutting, Robotic Waterjet, CNC Waterjet Application: Industrial Manufacturing, Signage, Artistic Cutting, Prototyping |
| Companies Covered | Sugino Machine, KMT Waterjet Systems, Flow International Corporation, OMAX Corporation, Techni Waterjet, Jet Edge, WardJet, Bystronic Group, Koike Aronson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Waterjet Cutting Machines Market Trends and Innovations
Software-defined cutting parameter optimization is displacing operator-dependent setup protocols across Japan's precision fabrication sector, compressing repeat-order cycle times while elevating quality consistency thresholds.
Pure waterjet systems with closed-loop pressure modulation are electrifying thin-material cutting workflows in electronics and medical device prototyping. Osaka-based semiconductor fabricators are adopting these platforms at twice the rate of conventional abrasive systems. The technology is electrifying competitive positioning for suppliers capable of delivering sub-millimeter kerf precision without thermal distortion.
METI's energy efficiency standards for industrial equipment are mandating pump recovery systems and variable-frequency drive retrofits. Factory automation procurement specifications now embed power consumption metrics alongside cutting speed benchmarks. Aerospace-grade applications in Aichi Prefecture are responding earliest, driven by tier-one supplier sustainability audit requirements.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete modules—predictive diagnostics, consumables replenishment, and remote calibration. Tokyo-Yokohama manufacturing clusters are piloting outcome-based uptime guarantees in place of fixed preventive schedules. This behavioral shift is most visible among medical device fabricators facing PMDA-adjacent contamination control mandates.
Japan Waterjet Cutting Machines Market Segmentation
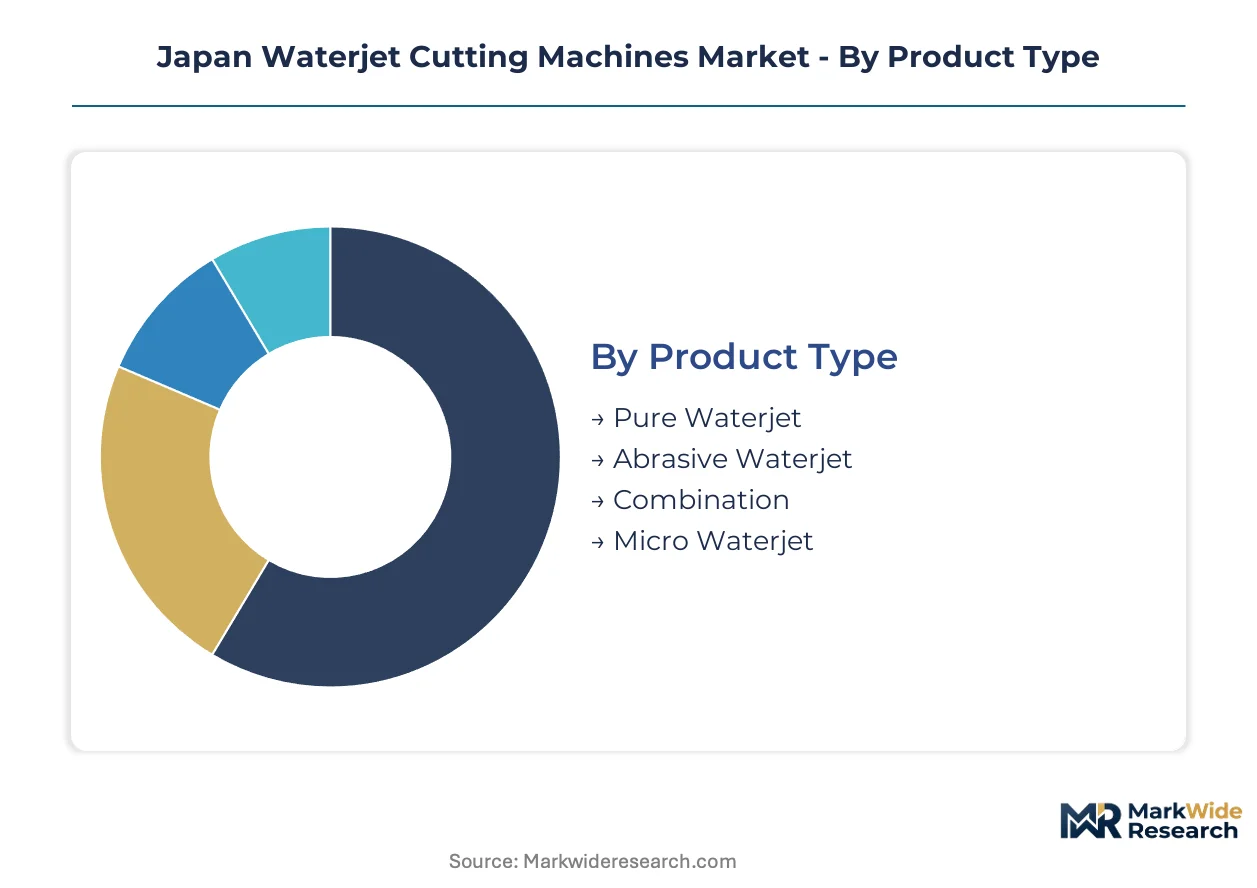
Segmentation in Japan's waterjet cutting market reveals how METI certification requirements and JIS factory automation standards fragment procurement behavior across product configurations. Buyers segment their specifications by thermal sensitivity of target materials, automation integration depth, and contamination control mandates from PMDA-adjacent medical device workflows.
Product Type:
JIS certification timelines vary substantially across product configurations, with micro waterjet systems facing extended approval protocols for medical-grade contamination control while abrasive platforms navigate standard industrial equipment pathways.
- Abrasive Waterjet:Systems inject garnet abrasive into pressurized water streams exceeding 60,000 psi to cut hardened metals and thick composites. Demand concentrates in Nagoya aerospace corridors where tier-one suppliers process titanium turbine components requiring zero heat-affected zones. METI energy efficiency standards are forcing pump recovery retrofits that extend equipment lifecycles.
- Micro Waterjet:Ultra-precise platforms achieve sub-millimeter kerf widths through closed-loop pressure modulation without thermal distortion. Tokyo-Yokohama electronics clusters and Osaka semiconductor fabricators specify these systems for PMDA-adjacent contamination-controlled environments in medical device prototyping workflows.
- Pure Waterjet:Pressurized water-only cutting for soft materials and thin substrates operates at lower operational cost without abrasive consumption.
- Combination:Modular platforms switch between pure and abrasive modes through automated head exchange systems.
Abrasive waterjet sits at the top of the volume ranking, with micro waterjet climbing the fastest.
End User:
Cost tier stratification separates aerospace and automotive buyers seeking premium automation-integrated platforms from metal fabrication shops prioritizing capital efficiency in standardized cutting workflows.
- Aerospace:Tier-one manufacturers in Aichi Prefecture demand CNC-integrated systems with automated material handling for heat-sensitive titanium and carbon fiber composite processing. Sustainability audit requirements from international OEMs are accelerating specification of energy-efficient pump recovery systems.
- Automotive:Structural element fabrication in Toyota City supplier networks requires abrasive waterjet for high-strength steel cutting without metallurgical degradation. Society 5.0 smart factory certification is compressing upgrade cycles toward software-integrated configurations.
- Metal Fabrication:General job shops across Kanto and Kansai regions serve mixed-material cutting contracts with lower automation requirements.
- Tile & Glass:Artistic and architectural cutting applications favor pure waterjet systems for brittle material processing without fracture propagation.
Aerospace commands the premium pricing tier, while automotive represents the steepest expansion trajectory as electrification reshapes structural component specifications.
Technology:
Margin concentration follows automation depth, with software-integrated platforms capturing superior returns over mechanical systems amid technician scarcity for CNC calibration.
- CNC Waterjet:Computer-numerical control platforms integrate cutting parameter optimization software that displaces operator-dependent setup protocols. Kanto manufacturing clusters are deploying these systems under Industrial Value Chain Initiative mandates for factory automation integration.
- Robotic Waterjet:Six-axis articulated arms enable complex 3D contour cutting for aerospace engine components and automotive structural elements. Nagoya-Osaka corridors are piloting these configurations for unmanned shift operations.
- 2D Cutting:Flat-bed configurations dominate legacy installed base for sheet metal and plate processing.
- 3D Cutting:Five-axis head positioning enables bevel and contour cutting without secondary operations.
CNC waterjet holds the dominant revenue share, with robotic waterjet gaining share fastest in tier-one supplier facilities.
Application:
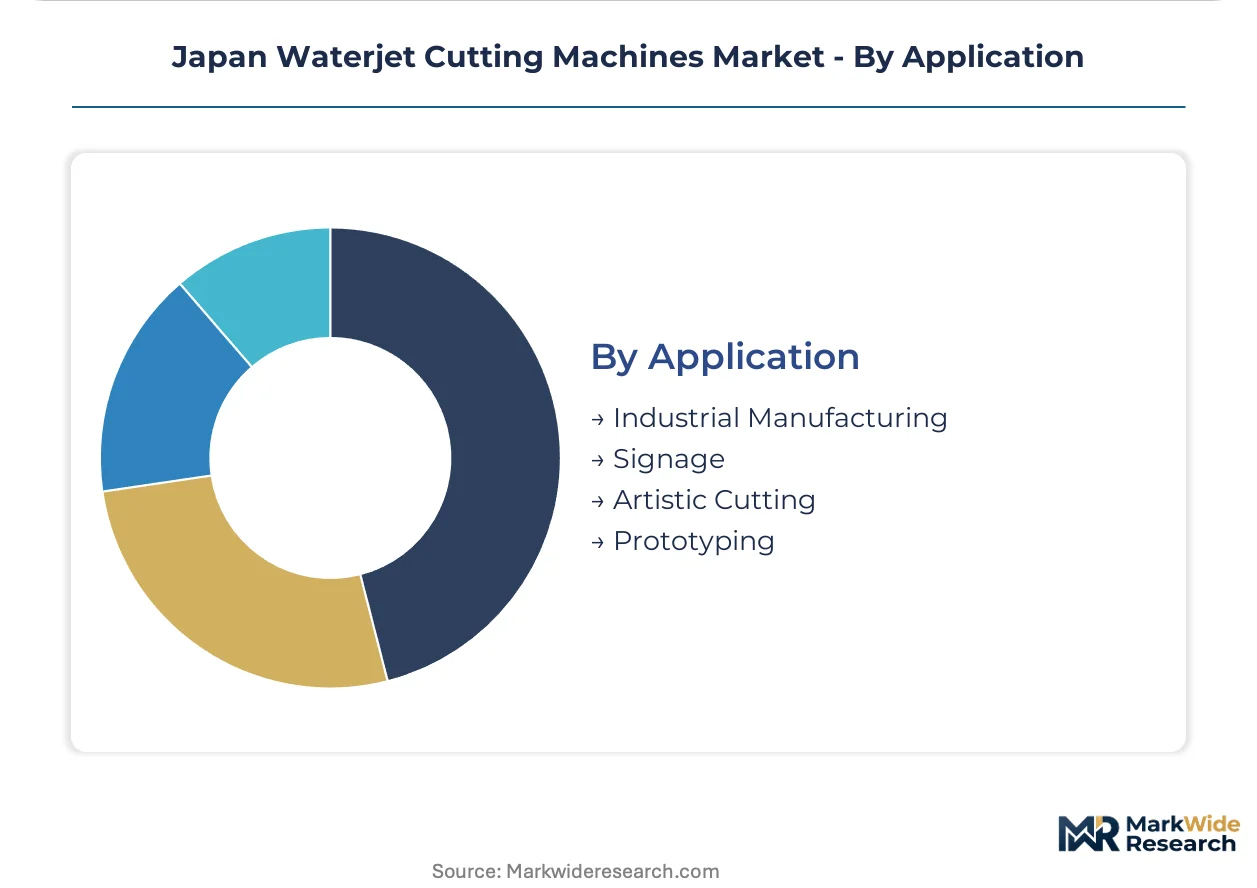
Customer type fragmentation separates high-volume contract manufacturers from low-volume prototype shops with divergent requirements for repeatability certification and setup flexibility.
- Industrial Manufacturing:High-volume production lines in automotive and aerospace tier-one facilities require automated material handling integration with Society 5.0 data architectures. METI smart factory certification mandates are filtering procurement toward predictive maintenance-enabled platforms.
- Prototyping:Medical device and semiconductor fabricators in Tokyo-Yokohama clusters demand micro waterjet systems for rapid iteration without tooling investment. PMDA-adjacent contamination control requirements specify closed-loop filtration and cleanroom-compatible configurations.
- Signage:Commercial graphics and architectural lettering applications favor pure waterjet for acrylic and metal substrate cutting.
- Artistic Cutting:Custom fabrication shops serve architectural and decorative markets with mixed-technology platforms.
Industrial manufacturing anchors volume demand, with prototyping expanding most quickly in medical device and electronics verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterjet cutting technology traces its industrial roots to the 1970s aerospace boom in the United States, where ultra-high-pressure systems first commercialized for heat-sensitive titanium processing before diffusing to precision manufacturing clusters worldwide.
Kanto Region
Tokyo-Yokohama manufacturing corridors drive procurement of CNC-integrated waterjet platforms for electronics and medical device prototyping. METI's Industrial Value Chain Initiative mandates factory automation integration across precision fabrication facilities. Chiba and Kanagawa prefectures host tier-one automotive suppliers upgrading to Society 5.0-certified smart factory configurations.
Kansai Region
Osaka-Kobe industrial zones show lower waterjet density per capita than Kanto, creating deployment whitespace for abrasive systems in metal fabrication. JIS certification requirements for factory automation equipment extend capital deployment cycles for mid-tier manufacturers. Hyogo Prefecture's semiconductor fabricators are piloting micro waterjet systems for contamination-controlled cutting environments.
Chubu Region
Aichi Prefecture anchors Japan's aerospace waterjet demand, with Nagoya-based tier-one suppliers processing titanium turbine components. METI energy efficiency standards are forcing pump recovery retrofits across existing installations. Toyota City supplier networks require abrasive waterjet for high-strength steel cutting without metallurgical degradation.
Kyushu Region
Fukuoka and Saga prefectures concentrate automotive component manufacturing with emerging precision fabrication capacity. PMDA-adjacent manufacturing guidelines for medical device fabricators are steering specification toward contamination-controlled micro cutting environments. Local metalworking clusters are adopting pure waterjet systems for thin-material electronics workflows.
Japan Waterjet Cutting Machines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation integration depth and certification compliance capabilities. The vendor base organizes into three tiers: domestic manufacturers with JIS-certified supply relationships, international pump technology specialists, and regional system integrators serving job-shop fabricators. Archetypes include automation-integrated platform providers, ultra-high-pressure component specialists, and abrasive delivery system optimizers. Dominant competitive moves center on strategic partnerships for factory automation integration and portfolio diversification into predictive maintenance service modules.
Among Japan-based manufacturers, Sugino Machine occupies a position exemplifying domestic supply relationship anchoring with automotive tier-one networks. Flow International Corporation and KMT Waterjet Systems represent international technology leadership archetypes in ultra-high-pressure pump systems and specialized abrasive delivery configurations respectively. These three companies illustrate the competitive structure where geographic origin intersects with technical specialization depth.
| Leading Market Players |
|---|
| Sugino Machine |
| KMT Waterjet Systems |
| Flow International Corporation |
| OMAX Corporation |
| Techni Waterjet |
| Jet Edge |
| WardJet |
| Bystronic Group |
| Koike Aronson |
| Others |
Pricing and Supply Chain Analysis
METI carbon-neutrality roadmaps for manufacturing equipment gate qualified supply access and premium-tier pricing power for waterjet platforms meeting lifecycle emissions criteria. Buyers seeking Society 5.0 smart factory certification face procurement specifications that filter toward energy-efficient pump recovery systems, compressing margins for non-compliant suppliers while elevating pricing floors for certified configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CNC-integrated automation platforms from mechanical cutting systems and entry-level job-shop configurations. Price differentiation rests on JIS certification grade and after-sales service bundling depth. Cost compression in standard-tier abrasive waterjet is intensifying because of abrasive garnet cost volatility and import-dependent ultra-high-pressure pump lead times. Tier-two automotive suppliers in Toyota City supplier networks exhibit highest price sensitivity, while Nagoya aerospace tier-one buyers prioritize thermal precision over capital efficiency.
Supply Chain Analysis
Regional distribution centers in Osaka and Nagoya operate hub-and-spoke patterns feeding Kanto and Chubu manufacturing clusters with compressed lead-time requirements. Ultra-high-pressure pump technology concentrates in the United States and Germany, while abrasive garnet supply draws from Australia and India. Single-source vulnerability in 60,000+ psi pump components creates exposure to currency fluctuation and overseas component lead times. Distribution runs through authorized system integrators serving automotive and aerospace tier-one suppliers with factory automation integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's waterjet cutting machines market represents a late-cycle quality story as aerospace and medical device demand shifts toward contamination-controlled micro cutting environments with premium specification requirements. This demand migration favors suppliers with JIS-certified automation platforms and predictive maintenance service modules.
For Market Incumbents: Acquire CNC-integrator technical capabilities to address technician scarcity compressing commissioning timelines for software-integrated cutting heads. Secure backward integration into ultra-high-pressure pump component supply to mitigate import dependency exposure. Defend against emerging pure waterjet specialists in electronics prototyping by accelerating energy-efficient pump recovery system deployment under METI mandates. For New Entrants and Emerging Players: Begin with Kansai region metal fabrication whitespace, where Osaka-Kobe corridors show lower waterjet density per capita than Kanto manufacturing clusters. Target medical device prototyping workflows in Tokyo-Yokohama with contamination-controlled micro waterjet configurations. Establish go-to-market partnerships with factory automation integrators holding existing Society 5.0 certification relationships. For Investors and Strategic Acquirers: Roll-up economics work for domestic system integrators with JIS-certified supply relationships because METI smart factory mandates are compressing upgrade cycles toward automation-ready configurations. Long-term viability hinges on service contract unbundling into predictive diagnostics and outcome-based uptime guarantees. Watch for inflection where 5G-enabled remote diagnostics penetration crosses threshold for subscription revenue materiality.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Components | Reduces exposure to overseas ultra-high-pressure technology lead times and currency fluctuation. |
| Predictive Maintenance Service Unbundling | Captures recurring revenue from Tokyo-Yokohama medical device fabricators facing PMDA contamination mandates. |
| Micro Waterjet Platform Development | Addresses sub-millimeter kerf precision demand from Osaka semiconductor fabricators at twice conventional adoption rates. |
| Kansai Distribution Footprint Expansion | Exploits whitespace in Osaka-Kobe metal fabrication corridors with lower per-capita waterjet density. |
| JIS Certification Acceleration | Compresses capital deployment cycles for mid-tier fabricators facing extended factory automation approval protocols. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at tier-one automotive and aerospace suppliers were combined with secondary validation from METI industrial statistics, JIS certification registries, customs trade data for ultra-high-pressure pump imports, and SEC filings from listed waterjet technology providers. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production and shipment data.
Historical trendline analysis of installed base evolution and upgrade cycle compression informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology automation depth, end-user industry vertical, and regional manufacturing cluster concentration. CAGRs were derived from fitted growth curves incorporating METI smart factory certification penetration rates and aerospace titanium processing demand expansion. Industry-specific forecast inputs include abrasive garnet price volatility indices and ultra-high-pressure pump import lead time fluctuations.
Caveats apply where METI carbon-neutrality roadmap revisions or PMDA contamination control guideline updates could materially shift the outlook for capital equipment procurement specifications. Forecasts reflect assumptions about Society 5.0 adoption velocity and tier-one supplier sustainability audit stringency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Pressure Vessel Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Powered Screed Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Shield Machines Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
CNC Machine Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Backhoes Market
Construction Equipment
ASEAN Construction Equipment Rental Market