
 High Pressure Heat Exchanger Market | 2026-2036
High Pressure Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Heat Exchanger Market Foresight
Stainless steel is consolidating its position against carbon steel in high pressure heat exchanger fabrication as corrosion resistance requirements intensify. Alfa Laval leverages its welded plate technology leadership to anchor premium positioning in hydrogen and carbon capture applications. Koch Heat Transfer competes through specialized shell and tube designs for extreme pressure service, while Mersen sustains graphite and silicon carbide expertise for aggressive chemical environments.
A high pressure heat exchanger is a thermal transfer device engineered to operate above standard design pressures, typically constructed with ASME-certified materials, precision-welded joints, and reinforced tube sheets to contain process fluids under elevated mechanical stress. Its primary purpose is to recover or reject heat in continuous industrial processes where pressure containment integrity directly determines safety and operational uptime. Shell and tube configurations dominate installed base across petrochemical and power generation applications due to proven reliability at extreme pressure-temperature combinations. Plate technology captures fastest growth in hydrogen and pharmaceutical end uses where compact footprint and thermal efficiency outweigh higher capital cost. Direct expansion systems lead technology adoption in refrigeration-linked chemical processes where precise temperature control protects product yield.
ASME Boiler and Pressure Vessel Code Section VIII governs US fabrication standards, while the EU Pressure Equipment Directive mandates CE marking for European market access, both elevating inspection and documentation burdens that filter out uncertified suppliers. EPA emissions rules and OSHA process safety management requirements compound compliance complexity for operators replacing legacy units. Stakeholders must monitor evolving hydrogen infrastructure codes and carbon border adjustment mechanisms as these frameworks reshape material sourcing decisions and geographic sourcing strategies.
Market Dynamics
ASME Section VIII and PED compliance burdens are filtering fabrication capacity toward certified suppliers with captive metallurgy and welding qualification programs, compressing the vendor base while elevating pricing power for qualified manufacturers.
Growth Catalysts
- Hydrogen infrastructure buildout:Electrolyzer and ammonia synthesis projects in the US Gulf Coast and Rotterdam cluster are specifying compact welded plate exchangers for 700-bar service. Germany's hydrogen core grid initiative accelerates demand for pressure-boundary-qualified units.
- Carbon capture retrofits:Post-combustion amine stripping requires corrosion-resistant alloys in high-pressure regeneration loops. The US Inflation Reduction Act's carbon capture tax credits are pulling forward procurement timelines for integrated capture facilities.
- ASME Section VIII Division 2 adoption:Advanced analysis methods permit thinner-walled vessels at equivalent pressure ratings, reducing material intensity for hydrogen and supercritical CO2 applications while maintaining safety margins.
Market Restraints
- Nickel alloy supply concentration:Inconel 625 and 718 plate availability depends on a concentrated North American and European mill base, exposing project timelines to raw material queue delays.
- PED Notified Body capacity:European certification backlogs extend lead times for CE-marked equipment, forcing project developers to pre-order equipment 18-24 months ahead of installation.
- Supercritical CO2 Brayton cycle immaturity:Turbomachinery and heat exchanger sealing technology for 250-bar CO2 service remains pre-commercial, limiting near-term order flow outside pilot demonstrations.
Strategic Opportunities
- Saudi hydrogen megaprojects:NEOM and Jubail Industrial City developments represent greenfield demand for modular, shop-fabricated high-pressure exchanger trains with full material traceability.
- Modular process intensification:Containerized hydrogen liquefaction and ammonia synthesis units favor compact plate-and-frame geometries over field-erected shell-and-tube systems.
- EU Carbon Border Adjustment Mechanism:Embodied carbon accounting in imported pressure equipment is creating preference for European-fabricated units with verified low-carbon steel and alloy sourcing.
Industry Challenges
- ASME IX welding procedure qualification:Qualified welder availability constrains throughput at fabrication shops, particularly for exotic alloy combinations in hydrogen service.
- Legacy asset integration:Retrofitting high-pressure exchangers into 1970s-vintage petrochemical trains requires custom nozzle orientation and foundation adaptation engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Pressure Heat Exchanger Market |
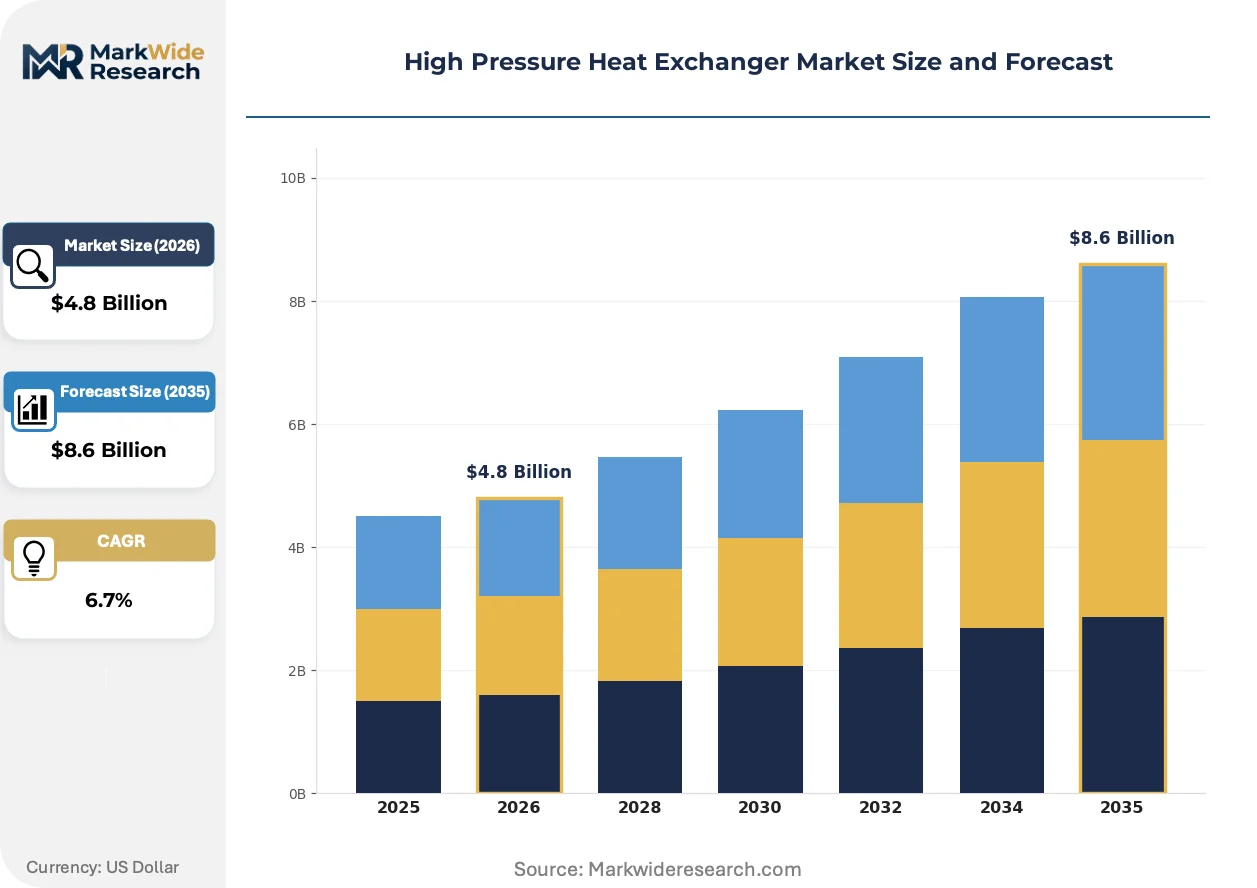
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell & Tube, Plate, Air Cooled, Double Pipe Application: Petrochemical, Power Generation, Food & Beverage, HVAC End User: Oil & Gas, Pharmaceuticals, Chemical Manufacturing, Automotive Technology: Direct Expansion, Steam Heating, Thermal Storage, Refrigeration |
| Companies Covered | Alfa Laval, SPX Flow, HRS Heat Exchangers, Kelvion Holding, Danfoss, API Heat Transfer, Koch Heat Transfer, Mersen, Hisaka Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Heat Exchanger Market Shifts & Advancements
Additive manufacturing of heat exchanger headers and nozzle reinforcements is compressing lead times for complex geometries while enabling topology-optimized flow distribution previously unmachinable from forged blanks.
Diffusion-bonded microchannel heat exchangers are converging with printed circuit heat exchanger architectures to deliver thousand-square-meter surface area in cubic-meter footprints. Hydrogen liquefaction plant developers in Germany and Japan are specifying these units for 300-bar helium and hydrogen service. The technology is compressing plot plan requirements for offshore and urban-limited installations.
The EU F-Gas Regulation's phasedown of fluorinated refrigerants is forcing refrigeration-linked chemical processors to redesign high-pressure condensers and intercoolers for ammonia, CO2, and hydrocarbon working fluids. Equipment suppliers are qualifying new gasket materials and pressure-relief sizing methodologies. Pharmaceutical cold chain applications in the Netherlands and Denmark are experiencing the most intensive requalification burden.
Lifecycle cost contracting is displacing capital-purchase evaluation for hydrogen and carbon capture projects. Engineering-procurement-construction firms are bundling exchanger supply with 15-year performance guarantees and predictive maintenance subscriptions. This shift concentrates procurement authority with integrated technology licensors and away from standalone vessel purchasers, most visibly in US Gulf Coast blue hydrogen developments.
High Pressure Heat Exchanger Market Segmentation
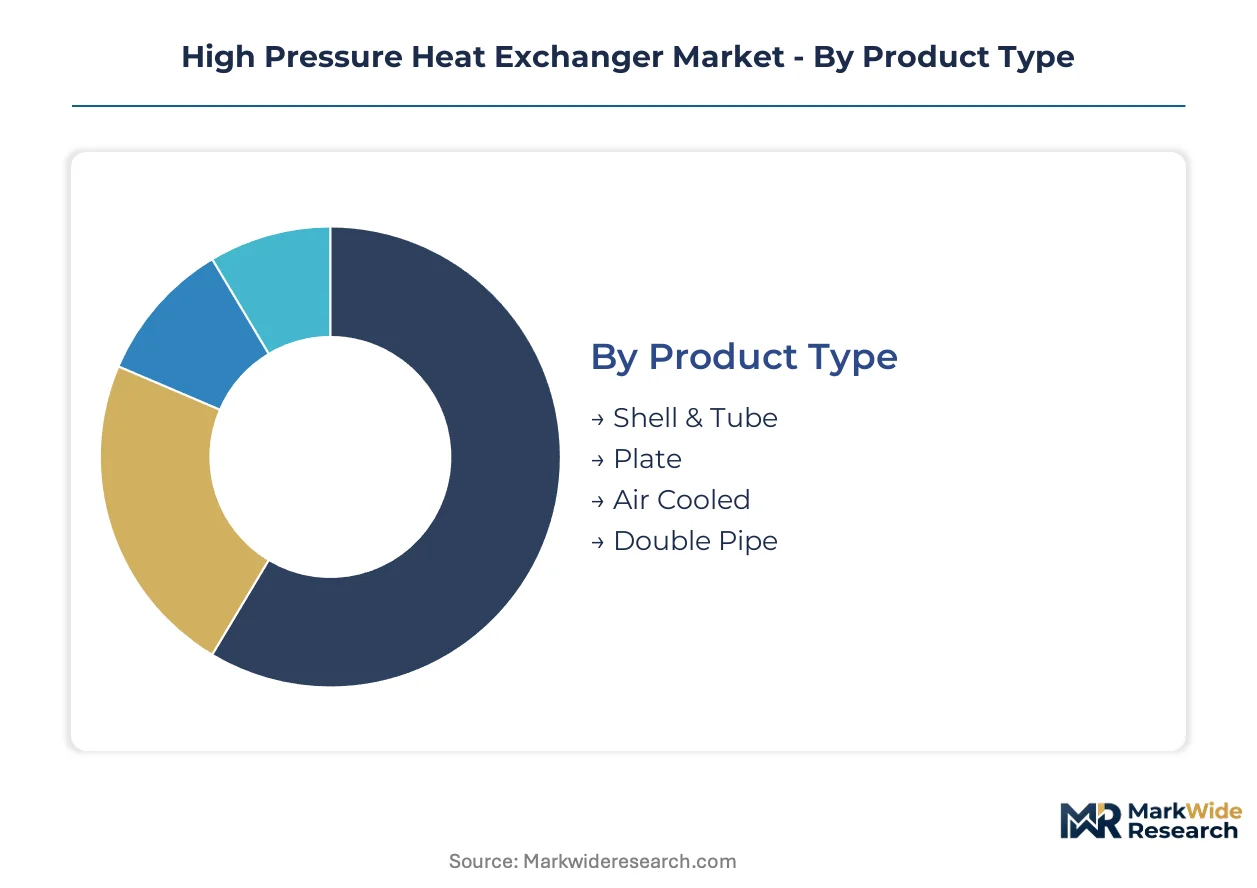
High pressure heat exchanger procurement patterns diverge sharply across product architectures and end-use requirements. Fabrication capacity concentrates in ASME-certified shops capable of welding exotic alloys for hydrogen service. Each segment carries distinct qualification burdens that reshape vendor selection criteria.
Product Type:
Supply concentration tilts toward shops with captive metallurgy programs and ASME IX welding qualifications, compressing viable supplier pools for advanced designs.
- Shell & Tube:Fabricated from seamless alloy tubing with reinforced tube sheets and expansion joints rated for extreme pressure-temperature combinations. Demand concentrates in US Gulf Coast petrochemical complexes where proven reliability outweighs footprint penalties. These units anchor procurement budgets for brownfield expansions.
- Plate:Precision-welded corrugated plates deliver compact surface area density in cubic-meter footprints. Hydrogen liquefaction developers in Germany and Japan specify these for 300-bar helium and hydrogen service. The technology gains share where plot constraints dominate engineering decisions.
- Air Cooled:Fin-tube bundles with induced-draft fans serve remote installations lacking cooling water infrastructure. Arid-region refineries in Saudi Arabia and West Texas favor these for water-stressed environments.
- Double Pipe:Concentric tube arrangements handle small-scale high-pressure duties in pilot plants and specialty chemical batches. Pharmaceutical API manufacturers specify these for validated cleaning protocols.
Today's leader: Shell & Tube. Tomorrow's challenger: Plate.
Application:
Cost tier stratification separates capital-intensive process industries from specification-light commercial installations, with certification grade driving price multiples.
- Petrochemical:Continuous crackers and reformers demand pressure-boundary integrity at 700-bar hydrogen partial pressures. Rotterdam cluster operators specify PED Notified Body-certified units with full material traceability.
- Power Generation:Supercritical steam cycles and combined heat recovery require creep-resistant alloys for sustained thermal cycling. US independent power producers prioritize ASME Section VIII Division 2 compliance for thinner-walled vessels.
- Food & Beverage:Sanitary plate exchangers for UHT milk processing and beverage pasteurization operate at moderate pressures with 3A sanitary standards. European dairy cooperatives drive specification harmonization.
- HVAC:Commercial building heat pumps and district heating substations utilize standard-pressure plate units. The EU F-Gas Regulation's refrigerant phasedown forces redesign for ammonia and CO2 working fluids.
Petrochemical commands premium pricing. Power Generation offers steepest expansion trajectory as supercritical CO2 cycles mature.
End User:
Customer type determines procurement authority concentration, with integrated technology licensors displacing standalone vessel purchasers in hydrogen and carbon capture developments.
- Oil & Gas:Upstream gas processing and LNG liquefaction trains specify cryogenic aluminum alloys and nickel steel for subzero hydrocarbon service. QatarEnergy and ADNOC megaprojects require modular shop-fabricated trains.
- Pharmaceuticals:cGMP-validated units for API synthesis and sterile processing demand surface finish documentation and material certificates. Swiss and Danish cold chain applications face intensive EU F-Gas requalification.
- Chemical Manufacturing:Aggressive acid service in chlor-alkali and sulfuric acid plants specifies graphite and silicon carbide constructions. Mersen maintains specialized fabrication capacity for these environments.
- Automotive:Hydrogen fueling station compressors and onboard thermal management operate at 700-bar service pressures. German automotive OEMs anchor early demand for compact welded plate architectures.
Oil & Gas retains volume leadership. Automotive represents the fastest-climbing trajectory as hydrogen infrastructure scales.
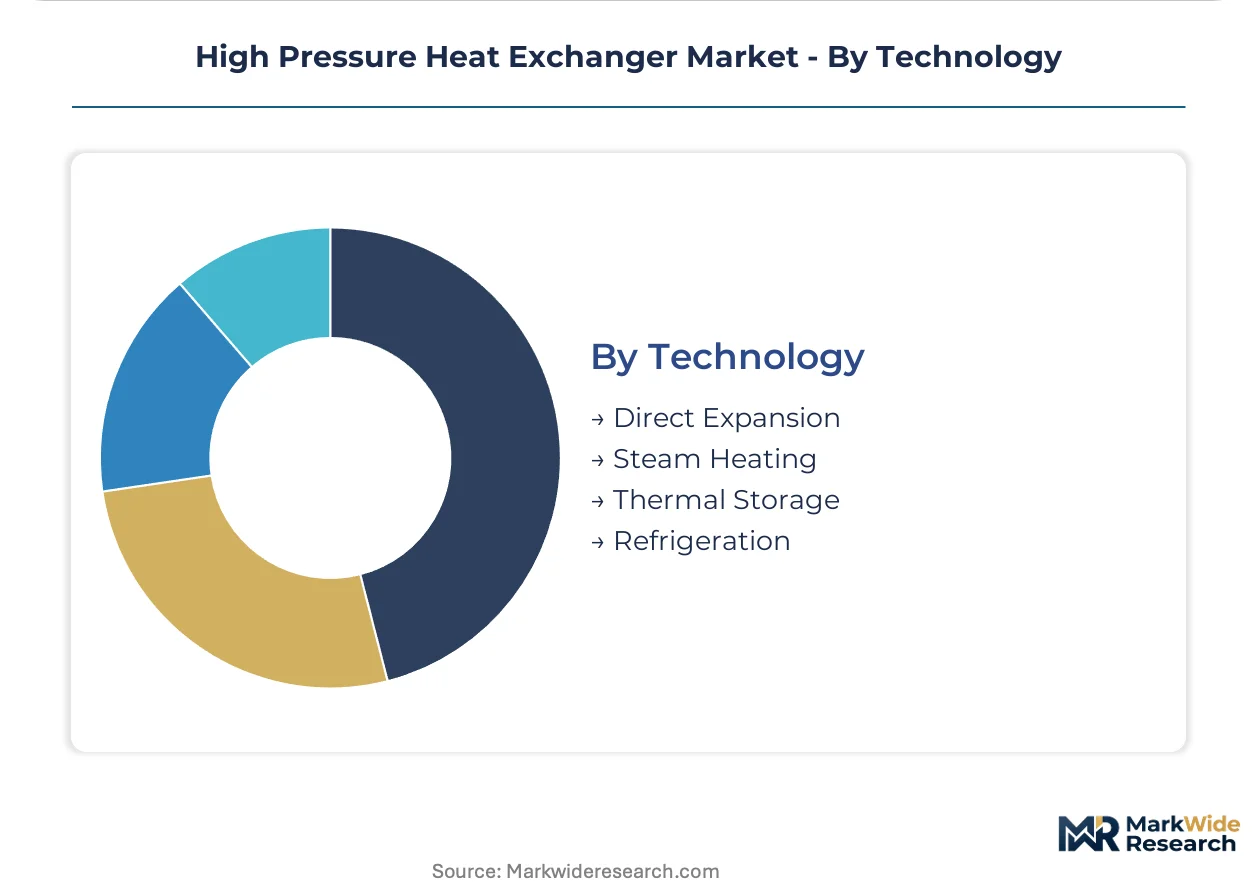
Technology:
Maturity gradients separate field-proven thermal methods from emerging process intensification approaches, with qualification timelines stretching commercialization horizons.
- Direct Expansion:Refrigerant-evaporating designs deliver precise temperature control for chemical processes with narrow operating windows. Ammonia and CO2 conversions dominate Netherlands and Denmark pharmaceutical cold chain retrofits.
- Steam Heating:Saturated and superheated steam supply for reboilers and preheaters remains the thermal utility default across petrochemical complexes. US Gulf Coast operators prioritize condensate recovery efficiency.
- Thermal Storage:Phase-change material integration buffers intermittent renewable heat for continuous process duty. German chemical parks pilot these for industrial heat decarbonization.
- Refrigeration:Compression-based cooling for gas processing and cryogenic separation requires specialized aluminum brazed exchangers. Japanese LNG liquefaction developers specify these for mixed refrigerant cycles.
Steam Heating dominates installed base. Direct Expansion gains share fastest amid refrigerant transition pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor anchors procurement volume for high-pressure heat exchanger demand. Hydrogen infrastructure buildout and carbon capture retrofits are redrawing geographic order patterns. Regulatory divergence between ASME-certified North American fabrication and PED-governed European supply is fragmenting vendor qualification pathways.
United States
Electrolyzer projects and blue hydrogen developments in Texas and Louisiana are specifying compact welded plate units for 700-bar service. The Inflation Reduction Act's carbon capture tax credits are accelerating procurement timelines for integrated capture facilities. Houston-area fabricators with ASME Section VIII Division 2 qualifications are capturing premium positioning in supercritical CO2 applications.
Germany
The hydrogen core grid initiative is driving demand for pressure-boundary-qualified units in ammonia synthesis and liquefaction plants. EU F-Gas Regulation compliance is forcing refrigeration-linked chemical processors to redesign condensers for ammonia and CO2 working fluids. Industrial clusters in the Ruhr and around Hamburg are experiencing intensive requalification burdens for pharmaceutical cold chain applications.
Saudi Arabia
NEOM and Jubail Industrial City green hydrogen megaprojects represent modular, shop-fabricated demand with full material traceability requirements. The national industrial development strategy is concentrating procurement authority with integrated technology licensors. Eastern Province fabrication yards are expanding capacity to serve domestic content mandates for exchanger trains.
Japan
LNG liquefaction developers are specifying aluminum brazed exchangers for mixed refrigerant cycles in Kyushu and Chubu regions. Hydrogen liquefaction plant developers are adopting diffusion-bonded microchannel architectures for 300-bar helium and hydrogen service. METI's hydrogen roadmap is compressing plot plan requirements for urban-limited installations.
Netherlands
Rotterdam cluster operators are specifying PED Notified Body-certified units with full material traceability for post-combustion amine stripping applications. The EU Carbon Border Adjustment Mechanism is creating preference for European-fabricated units with verified low-carbon steel sourcing. Pharmaceutical API manufacturers in the Randstad are driving specification harmonization for cGMP-validated surface finish documentation.
High Pressure Heat Exchanger Market Competitive Landscape
Capacity expansion dominates the current landscape as certified fabrication shops invest in captive metallurgy and welding qualification programs. The vendor base compresses toward ASME IX-qualified suppliers capable of exotic alloy combinations for hydrogen service. Three archetypes occupy distinct positions: diversified thermal engineering conglomerates, specialized pressure vessel fabricators, and materials-science-focused niche players. Strategic partnerships and geographic licensing agreements are the primary competitive moves as qualified capacity scarcity elevates pricing power.
Among diversified thermal engineering groups, Alfa Laval and Danfoss exemplify technology-led positioning through welded plate architectures. Specialized pressure vessel expertise concentrates in Koch Heat Transfer and Mersen, representing contrasting material strategies—metallic extreme-pressure service versus graphite and silicon carbide for aggressive chemical environments. These named entities anchor the competitive structure without exhausting the qualified supplier pool, as regional fabrication shops with ASME and PED certifications retain meaningful share in geographically concentrated petrochemical corridors.
| Leading Market Players |
|---|
| Alfa Laval |
| SPX Flow |
| HRS Heat Exchangers |
| Kelvion Holding |
| Danfoss |
| API Heat Transfer |
| Koch Heat Transfer |
| Mersen |
| Hisaka Works |
| Others |
Supply & Pricing Matrix
The EU Carbon Border Adjustment Mechanism gates both qualified supply and premium-tier pricing access for high pressure heat exchanger procurement, as verified low-carbon steel and alloy sourcing becomes a prerequisite for European market entry while simultaneously commanding material cost premiums that filter toward certified fabricators.
Pricing Analysis
Input-cost pass-through from nickel alloy plate and seamless tubing anchors pricing dynamics, with Inconel 625 and 718 availability constraints compressing margins for non-captive suppliers. Three-tier pricing structure across ASME-certified premium, PED-compliant standard, and uncertified economy levels separates procurement budgets, with hydrogen service applications showing least price sensitivity due to safety-critical specifications while HVAC and commercial building segments face acute cost compression. Pricing pressure stems from qualified welder scarcity and extended PED Notified Body certification queues, forcing project developers to absorb premium markups for expedited delivery.
Supply Chain Analysis
Warehouse-distribution layer concentration in Houston, Rotterdam, and Jubail Industrial City shapes regional fulfillment patterns, with hub-and-spoke logistics serving petrochemical corridor demand. Manufacturing concentrates in the United States, Germany, and Saudi Arabia, drawing from seamless alloy tubing, nickel-based superalloys, and precision-welded plate components. Single-source vulnerability runs through concentrated North American and European mill bases for Inconel plate, exposing project timelines to raw material queue delays. Distribution runs through integrated technology licensors and EPC contractors rather than standalone vessel purchasers, particularly for hydrogen and carbon capture developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ASME Section VIII Division 2 adoption and modular process intensification, as thinner-walled vessel designs reduce material intensity while maintaining safety margins for hydrogen and supercritical CO2 applications.
For Market Incumbents: Deepen captive metallurgy programs and ASME IX welding qualification capacity to defend against emerging modular fabricators from Saudi Arabia and South Korea. Prioritize certification investment in PED Notified Body relationships to compress European lead times and capture premium positioning in Rotterdam cluster developments. Expand Houston-area fabrication yards to serve US Gulf Coast electrolyzer and blue hydrogen project timelines. For New Entrants and Emerging Players: Engineering-procurement-construction firms represent the most accessible channel partner type for market entry, particularly those bundling 15-year performance guarantees with predictive maintenance subscriptions. Target pharmaceutical API manufacturing and hydrogen fueling station compressor applications where specification requirements remain less stringent than petrochemical pressure-boundary service. Pursue geographic licensing agreements with established European fabricators to bypass PED certification backlogs. For Investors and Strategic Acquirers: Roll-up economics work for regional ASME-certified fabrication shops because qualified capacity scarcity elevates pricing power and compresses the vendor base toward certified suppliers with captive welding programs. Target mid-cap specialists with existing hydrogen service qualifications and material traceability systems across the 5-10 year infrastructure buildout window. Monitor Inconel plate mill expansion announcements and PED Notified Body capacity additions as inflection indicators for supply constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Section VIII Division 2 Certification Investment | Enables thinner-walled vessel designs that reduce material intensity for hydrogen applications. |
| Backward Integration into Nickel Alloy Supply | Captive Inconel 625 and 718 sourcing insulates project timelines from mill queue delays. |
| PED Notified Body Partnership Expansion | Compresses European certification lead times for CE-marked equipment in Rotterdam cluster. |
| Modular Shop-Fabricated Train Development | Aligns with NEOM and Jubail Industrial City greenfield demand for containerized units. |
| Predictive Maintenance Subscription Launch | Captures lifecycle revenue from hydrogen and carbon capture project performance guarantees. |
Research Methodology
Coverage spans North America, Europe, Middle East, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant engineers, EPC procurement leads, aftermarket service heads, and OEM technical directors alongside secondary validation from ASME certification databases, PED Notified Body registries, SEC filings of listed thermal engineering groups, and customs trade data for alloy plate imports. Bottom-up project pipeline tracking triangulates against top-down industrial capacity assessments.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon, with segmentation dimensions spanning product architecture, application severity, end-user industry, and regional regulatory framework. CAGRs derive from fitted growth curves calibrated to announced electrolyzer, ammonia synthesis, and carbon capture project timelines. Forecast inputs incorporate hydrogen infrastructure code evolution, carbon border adjustment implementation schedules, and supercritical CO2 Brayton cycle commercialization milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel alloy supply expansion, PED Notified Body capacity growth, and hydrogen infrastructure code finalization. Forecasts reflect documented assumptions regarding project sanctioning rates and certification timeline normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Global Modular Chillers Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Hybrid Air Conditioner Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Commercial RAC PD Compressor Market