
 Global Skid Steer Attachments Market | 2026-2036
Global Skid Steer Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skid Steer Attachments Market Outlook
Dealer networks and direct-to-contractor digital platforms are reconfiguring how operators source replacement attachments. Titan Attachments leverages its e-commerce infrastructure to reach mid-sized landscaping fleets across the United States. Virnig Manufacturing anchors its position through specialized grapple and brush cutter lines engineered for severe-duty forestry applications. Paladin Attachments competes via broad product breadth serving rental company procurement consolidation.
Skid steer attachments are purpose-built implements that mount to universal quick-attach plates on compact loader arms, typically rated for hydraulic flows between 10 and 40 gallons per minute depending on tool function. These implements convert a single base machine into task-specific equipment for material handling, earthmoving, vegetation control, and surface conditioning across confined job sites. Buckets retain the largest revenue share in the product type dimension due to universal applicability across construction and agriculture, while grapples command premium positioning in forestry and demolition where hydraulic precision determines productivity. Site preparation and material handling dominate usage scenarios, though snow removal exhibits pronounced seasonality concentrated in northern climates and alpine municipalities.
OSHA workplace safety mandates govern operator protection and attachment locking mechanism integrity in the United States, while CE marking under the EU Machinery Directive establishes conformity requirements for hydraulic coupler systems sold across Europe. EPA Tier 4 Final and EU Stage V emissions frameworks indirectly shape attachment demand by extending skid steer loader replacement intervals, increasing reliance on attachment versatility to maximize fleet utilization. Stakeholders must monitor electrification timelines from major loader OEMs to ensure hydraulic attachment compatibility with battery-electric base machines entering commercial deployment.
Market Dynamics
Electrification-ready hydraulic architecture is forcing attachment manufacturers to redesign coupler systems and flow circuits for compatibility with battery-electric skid steer loaders entering commercial fleets.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V:Extended replacement intervals for base machines concentrate investment in versatile attachments to maximize fleet utilization rates.
- Urban maintenance:Municipalities in the United States and Germany are expanding compact equipment fleets for confined-space infrastructure renewal.
- Quick-attach standardization:Universal plate geometry across OEM platforms reduces operator training costs and accelerates tool switching on multi-task job sites.
Market Restraints
- Steel input volatility:Abrasion-resistant plate and hydraulic cylinder tubing costs fluctuate with commodity indexes, compressing margin visibility for attachment fabricators.
- Supply concentration:High-pressure hydraulic seal and valve production clusters in Germany and Japan, creating exposure to single-source dependencies.
- Technical limitation:Conventional hydraulic systems face heat dissipation constraints that limit continuous-duty cycle performance in high-ambient conditions.
Strategic Opportunities
- Underpenetrated geography:India’s infrastructure build-out programs create first-mover positioning for attachment suppliers establishing local assembly.
- Technology convergence:Integration of telematics-enabled couplers with fleet management software allows usage-based attachment rental pricing.
- Distribution innovation:Direct-to-contractor digital platforms bypass traditional dealer markups and capture mid-sized landscaping fleet procurement.
Industry Challenges
- Skill gap:Certified hydraulic technician shortages delay field service response times for attachment warranty claims.
- Certification timeline:CE marking conformity assessment under the EU Machinery Directive extends product launch cycles by four to six months.
- Integration complexity:Legacy loader fleets with pre-standard quick-attach plates require adapter fabrication, increasing total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skid Steer Attachments Market |
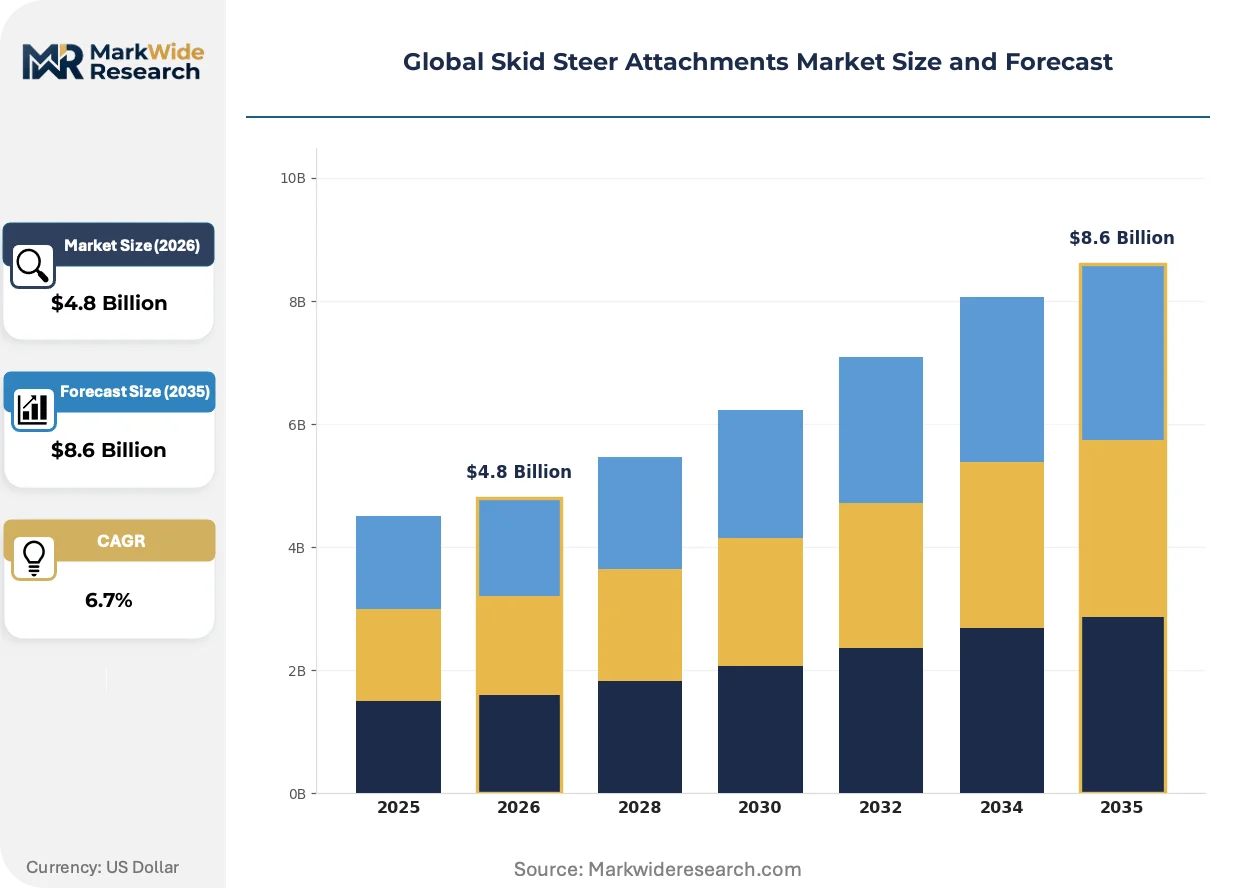
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buckets, Pallet Forks, Snow Plows, Grapples Application: Construction, Landscaping, Agriculture, Demolition Usage Scenario: Ground Leveling, Material Handling, Snow Removal, Site Preparation End User: Contractors, Farmers, Municipalities, Rental Companies |
| Companies Covered | Titan Attachments, Jenkins Iron & Steel, Paladin Attachments, Top Dog Attachments, Skid Steer Solutions, Stinger Attachments, Virnig Manufacturing, Maxx Attachments, Blue Diamond Attachments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skid Steer Attachments Market Strategic Shifts
Attachment intelligence and connectivity are redefining how operators monitor tool performance and schedule maintenance, shifting value capture from hardware sales to data-enabled service models.
Telematics-equipped hydraulic couplers are digitizing attachment utilization tracking across rental fleets and municipal equipment pools. Construction contractors in the United States are adopting these systems to document billable hours and prevent unauthorized off-rent use. The technology is digitizing fleet management workflows by automating maintenance interval alerts and warranty documentation.
EU Stage V emissions frameworks are tightening particulate matter thresholds for diesel-powered base machines, indirectly accelerating attachment demand as owners extend loader replacement cycles. Attachment manufacturers are responding with electrification-ready designs featuring optimized hydraulic efficiency for battery-electric powertrains. Forestry and demolition segments face the steepest compliance cost increases due to high-duty cycle requirements.
Rental company procurement consolidation is compressing supplier bases and demanding standardized cross-brand compatibility. National rental chains in the United States are specifying universal quick-attach geometry and common hydraulic port configurations to reduce inventory duplication. This concentration is visible most acutely in snow removal and site preparation categories where seasonal demand spikes require rapid tool rotation.
Global Skid Steer Attachments Market Segmentation
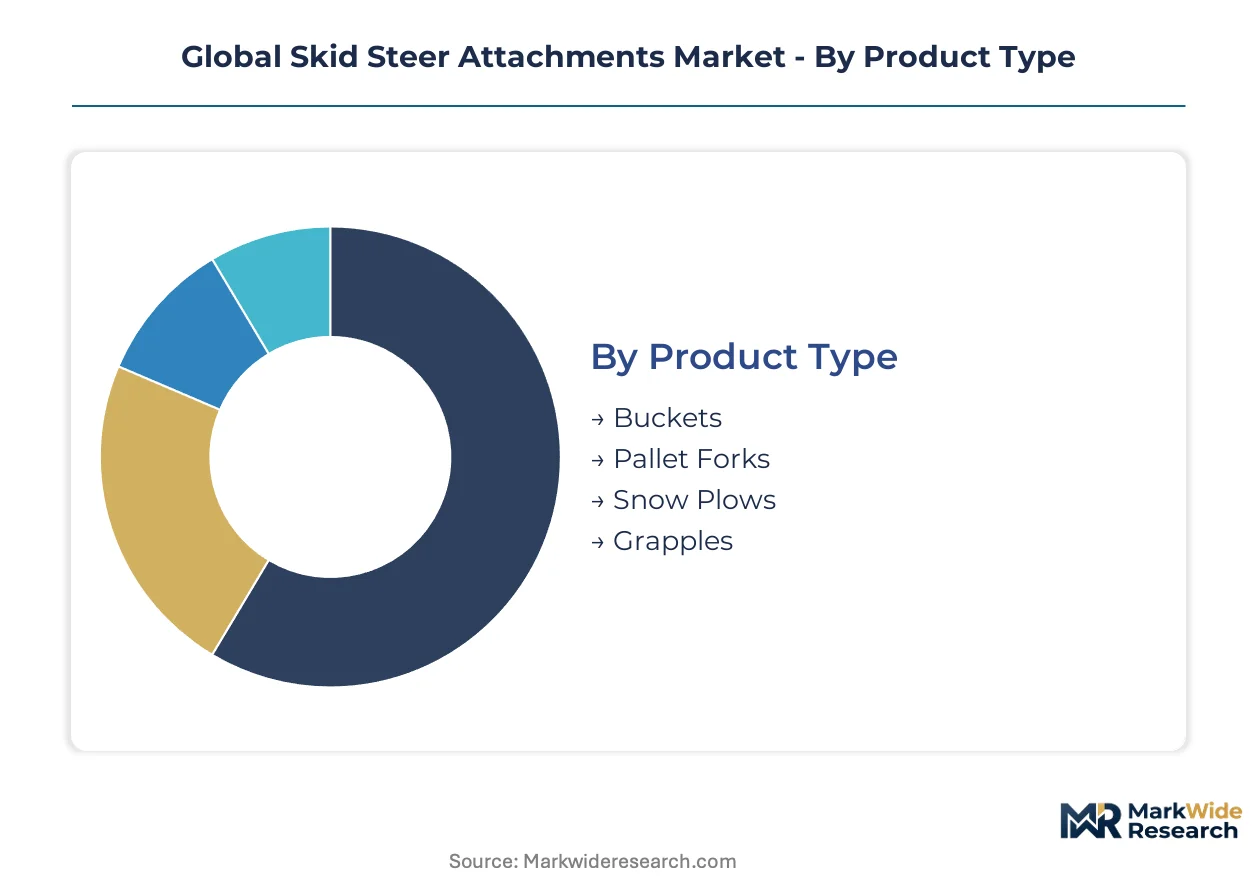
Attachment selection criteria vary sharply across operator profiles and job site conditions. Product architecture, hydraulic flow requirements, and duty cycle intensity create natural fault lines that manufacturers must address through specialized design configurations.
Product Type:
Cost tier differentiation separates universal implements from specialized premium tools requiring precision hydraulic control.
- Buckets:Fabricated from abrasion-resistant steel plate with reinforced cutting edges rated for rock and demolition debris. Construction fleets in the United States specify high-capacity models for aggregate handling, while agricultural operators prioritize light-material buckets with bolt-on wear edges for grain and feed operations.
- Grapples:Hydraulic cylinder-actuated tine configurations deliver controlled clamping force for irregular loads in forestry and scrap metal applications. German demolition contractors specify severe-duty models with protected cylinder housings, where hydraulic precision determines cycle productivity and fuel efficiency.
- Pallet Forks:Carriage-mounted tine systems rated for load capacities matching compact loader lift specifications.
- Snow Plows:Moldboard and pusher configurations with trip-edge or full-trip mechanisms for municipal and commercial snow management.
Buckets hold installed capacity. Grapples is rotating up the share rankings.
Application:
Volume concentration patterns reflect infrastructure investment cycles and seasonal equipment utilization patterns across end-use sectors.
- Construction:Foundation excavation, structural demolition, and material transport operations demand attachments engineered for high-impact duty cycles. Chinese urban renewal programs are accelerating replacement demand for severe-duty buckets and hydraulic breakers in tier-one municipal construction markets.
- Landscaping:Finish grading, soil conditioning, and vegetation management require precision control for aesthetic outcomes. Mid-sized United States landscaping fleets are consolidating procurement through direct digital channels, favoring quick-attach versatility over dedicated single-purpose equipment.
- Agriculture:Manure handling, feed mixing, and light material transport drive seasonal attachment demand patterns.
- Demolition:Structural dismantling and debris sorting operations require reinforced attachment architecture and protected hydraulic systems.
Construction holds installed capacity. Landscaping is rotating up the share rankings.
Usage Scenario:
Customer type priorities determine attachment specification emphasis, from rental fleet standardization to municipal procurement compliance requirements.
- Material Handling:Pallet forks, grapples, and multi-purpose buckets configured for load stability and cycle speed. Rental companies in Germany specify universal quick-attach compatibility across loader brands to minimize inventory duplication and accelerate tool rotation.
- Site Preparation:Land clearing, rough grading, and soil stabilization attachments engineered for continuous-duty hydraulic performance. Indian infrastructure build-out programs are creating first-mover positioning for suppliers establishing local assembly capacity for dozer blades and rakes.
- Ground Leveling:Laser-compatible and manual grading attachments for precision surface finishing.
- Snow Removal:Seasonal implements with high-visibility moldboard designs and quick-mount systems for municipal fleet deployment.
Material Handling holds installed capacity. Site Preparation is rotating up the share rankings.
End User:
Margin structure varies by procurement channel sophistication and fleet scale, from price-sensitive independent operators to consolidated national accounts.
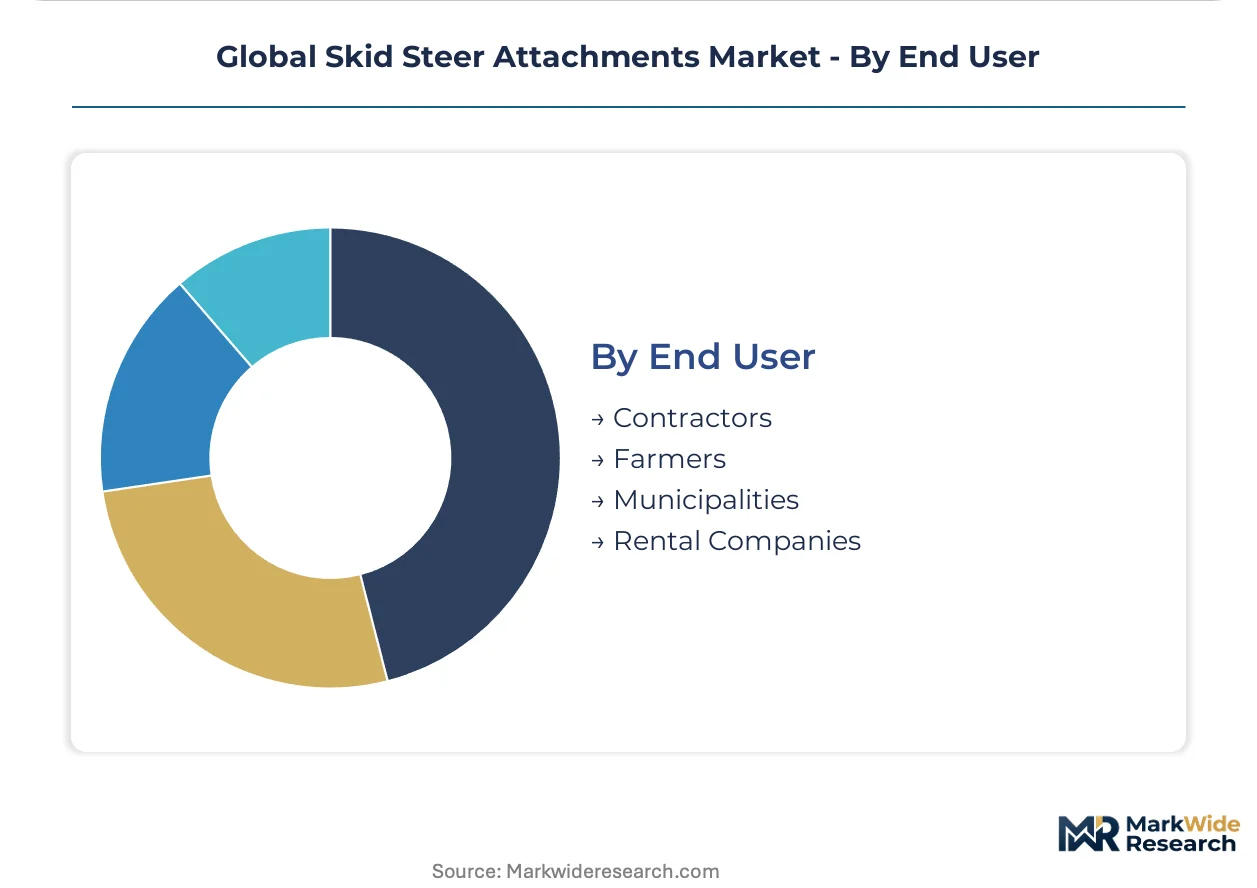
- Contractors:General construction and specialty trade operators prioritize attachment durability and rapid tool switching for multi-task job site efficiency. OSHA workplace safety mandates in the United States govern operator protection and attachment locking mechanism integrity, driving specification compliance in commercial procurement.
- Rental Companies:National chains demand standardized cross-brand compatibility and telematics-enabled utilization tracking. United States rental consolidation is compressing supplier bases and specifying universal quick-attach geometry to reduce inventory carrying costs.
- Farmers:Owner-operators and agricultural enterprises select attachments for seasonal versatility and total cost of ownership optimization.
- Municipalities:Public works departments specify attachments for urban maintenance, confined-space infrastructure renewal, and seasonal snow management.
Contractors hold installed capacity. Rental Companies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates and EPA emissions frameworks anchor the United States as the dominant geography, while EU Stage V regulations and infrastructure renewal programs concentrate demand across Germany and China. Municipal fleet investments and electrification timelines are reshaping procurement patterns in each market.
United States
Urban maintenance programs and confined-space infrastructure renewal drive municipal fleet expansion across Midwest and Northeast metropolitan areas. OSHA governs operator protection and attachment locking mechanism integrity, mandating compliance in commercial procurement. Dallas-Fort Worth and Chicago anchor severe-duty attachment demand for demolition and material handling applications.
Germany
Forestry and demolition contractors specify precision hydraulic grapples for high-duty cycle productivity in Bavaria and Baden-Württemberg. EU Stage V emissions frameworks extend loader replacement intervals, concentrating investment in versatile attachments. Stuttgart industrial clusters host specialized fabricators engineering protected cylinder housings for severe-duty applications.
China
Tier-one municipal construction markets accelerate replacement demand for buckets and hydraulic breakers through urban renewal programs. GB standards and MIIT industrial policies shape equipment certification and local content requirements. Yangtze River Delta manufacturing bases concentrate attachment production capacity for domestic and export markets.
India
National infrastructure build-out programs create first-mover positioning for suppliers establishing local assembly capacity. BIS certification requirements and PLI scheme incentives influence procurement specifications for public works projects. Maharashtra and Gujarat industrial corridors attract attachment fabricators targeting road construction and site preparation demand.
Canada
Seasonal snow removal fleets in Alberta and Ontario drive concentrated demand for quick-mount moldboard systems. Health Canada and provincial workplace safety regulators govern attachment integrity standards for municipal procurement. Prairie provinces anchor agricultural attachment demand for manure handling and feed mixing operations.
Global Skid Steer Attachments Market Competitive Environment
Full-line manufacturers and specialized fabricators split the market into distinct capability tiers. The vendor base organizes around scale-driven volume producers, application-specific specialists, and digital-native distributors. Three archetypes dominate: broad-catalog suppliers serving rental consolidation, severe-duty engineers targeting forestry and demolition, and e-commerce platforms capturing mid-sized fleet procurement. Competitive moves center on electrification-ready hydraulic architecture and direct-to-contractor channel bypass.
Among North American fabricators, Titan Attachments occupies a position exemplifying digital distribution scale, while Virnig Manufacturing anchors the severe-duty specialization tier. Paladin Attachments represents the broad-catalog archetype serving consolidated rental procurement. These three entities collectively illustrate how channel strategy and application focus determine competitive positioning across the United States and Canadian markets.
| Leading Market Players |
|---|
| Titan Attachments |
| Jenkins Iron & Steel |
| Paladin Attachments |
| Top Dog Attachments |
| Skid Steer Solutions |
| Stinger Attachments |
| Virnig Manufacturing |
| Maxx Attachments |
| Blue Diamond Attachments |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese fabrication capacity for abrasion-resistant steel plate is compressing input costs for attachment manufacturers while simultaneously eroding pricing power among mid-tier fabricators dependent on commodity-grade outputs.
Pricing Analysis
Price spreads between United States and Chinese attachment markets reflect tariff exposure and logistics cost differentials exceeding twenty percentage points for comparable severe-duty grapple specifications. Pricing stratifies across premium, standard, and economy tiers, with certification grade under EU Machinery Directive and hydraulic flow capacity serving as primary differentiation drivers. Cost compression in standard-tier buckets is intensifying because of import competition from Yangtze River Delta manufacturing bases. Independent contractors exhibit highest price sensitivity, while consolidated rental chains prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from German hydraulic seal manufacturers to Italian valve assemblers illustrate working capital pressure cascading through tier-two component networks. Geographic supply concentration centers on China for steel plate fabrication, Germany for precision hydraulic components, and Japan for high-pressure cylinder tubing. Raw material dependencies draw from European abrasion-resistant plate mills, Southeast Asian rubber seal compounds, and domestic North American tubing producers. Single-source vulnerability in German high-pressure seal production creates exposure to regional logistics disruption. Distribution runs through authorized dealer networks, direct-to-contractor digital platforms, and rental company procurement consolidation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure renewal cycles across North American and European municipalities signal cyclical recovery positioning, with replacement demand for aging compact equipment fleets driving attachment procurement velocity.
For Market Incumbents: Build switching-cost moats through telematics-enabled coupler integration that locks rental fleets into proprietary fleet management ecosystems. Deepen backward integration into hydraulic cylinder production to offset single-source exposure from German seal suppliers. Secure CE marking pre-certification for electrification-ready designs ahead of EU Stage V enforcement tightening.
For New Entrants and Emerging Players: Build out local assembly capacity in Maharashtra and Gujarat industrial corridors to capture Indian infrastructure build-out demand before incumbent footprint establishment. Target site preparation attachments for road construction applications where BIS certification requirements create barrier-filtered competition. Deploy direct-to-contractor digital platforms bypassing traditional dealer markups to reach mid-sized landscaping fleets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated attachment suppliers with usage-based rental pricing models. Long-term viability over the next decade hinges on electrification-ready hydraulic architecture compatibility with battery-electric loader deployment timelines. Acquisition target archetype: specialized severe-duty fabricators with protected cylinder housing IP serving forestry and demolition segments. Monitor loader OEM electrification announcements as inflection signal for attachment compatibility demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification-Ready Hydraulic Architecture Redesign | Positions attachment compatibility with CAT, Bobcat, and JCB battery-electric loader roadmaps. |
| Telematics-Enabled Coupler Integration | Enables usage-based rental pricing for United Rentals and Herc Holdings fleet contracts. |
| Local Assembly Capacity in India | Captures NHAI road construction demand under PLI scheme localization incentives. |
| CE Marking Pre-Certification Investment | Accelerates EU market entry timelines amid Machinery Directive conformity assessment delays. |
| Direct-to-Contractor Digital Platform Launch | Bypasses traditional dealer markups to reach mid-sized landscaping fleet procurement consolidation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, rental company procurement managers, OEM attachment engineers, municipal equipment superintendents, and hydraulic component sourcing leads. Secondary validation drew from EPA emissions filings, EU Machinery Directive conformity databases, OSHA workplace safety enforcement records, and customs trade data for abrasion-resistant steel plate imports. Bottom-up attachment shipment data triangulated against top-down compact loader production forecasts.
Calibration against historical replacement cycles and infrastructure investment announcements anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, application intensity, hydraulic flow requirement tier, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of normalized replacement demand curves. Industry-specific forecast inputs incorporated municipal fleet age profiles and electrification readiness timelines from major loader OEMs.
Stress conditions across steel commodity volatility, hydraulic component lead time extension, and tariff rate fluctuation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure program continuity and emissions regulation enforcement. Macroeconomic contraction, regulatory delay, or battery-electric loader deployment acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Loaders Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Piles Turner Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Case Erectors Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Cable Winches Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Grout Bags Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Spray Washer Market