
 US and Mexico Metal Stamping Market | 2026-2036
US and Mexico Metal Stamping Market Size, Share, and Industry Trends Forecast 2026-2036
US and Mexico Metal Stamping Market Intelligence
Aluminum is shifting stamped component economics across the US-Mexico corridor as OEMs pursue weight reduction mandates. Magna International Inc. leverages its cross-border manufacturing footprint to serve Detroit Three automakers with integrated stamping and assembly. Martinrea International Inc. anchors its position through captive aluminum stamping capacity co-located with major vehicle assembly plants in Ontario and Mexico.
Metal stamping encompasses the cold-forming of flat metal sheets or coils into precise three-dimensional shapes using dies and presses, typically achieving tolerances within 0.1 mm for automotive structural components. The process serves as a foundational manufacturing method for high-volume production of chassis brackets, body panels, and electronic enclosures across industrial sectors. Automotive Parts dominates product type output as EV platforms require redesigned stampings for battery tray housings and motor mounts. Aluminum within the Material category represents the fastest-expanding input as electrification drives substitution away from conventional steel body-in-white assemblies.
US EPA fuel economy standards and NHTSA crash safety regulations jointly dictate material selection and thickness specifications for stamped structural components sold into the US market. Mexico's SECOFI metrology standards and alignment with USMCA rules of origin shape cross-border supply chain configuration and qualification requirements for stamping suppliers. Stakeholders must monitor evolving EV platform architectures and corresponding die retooling cycles to align capacity investments with shifting volume mix between ICE and electric vehicle stampings.
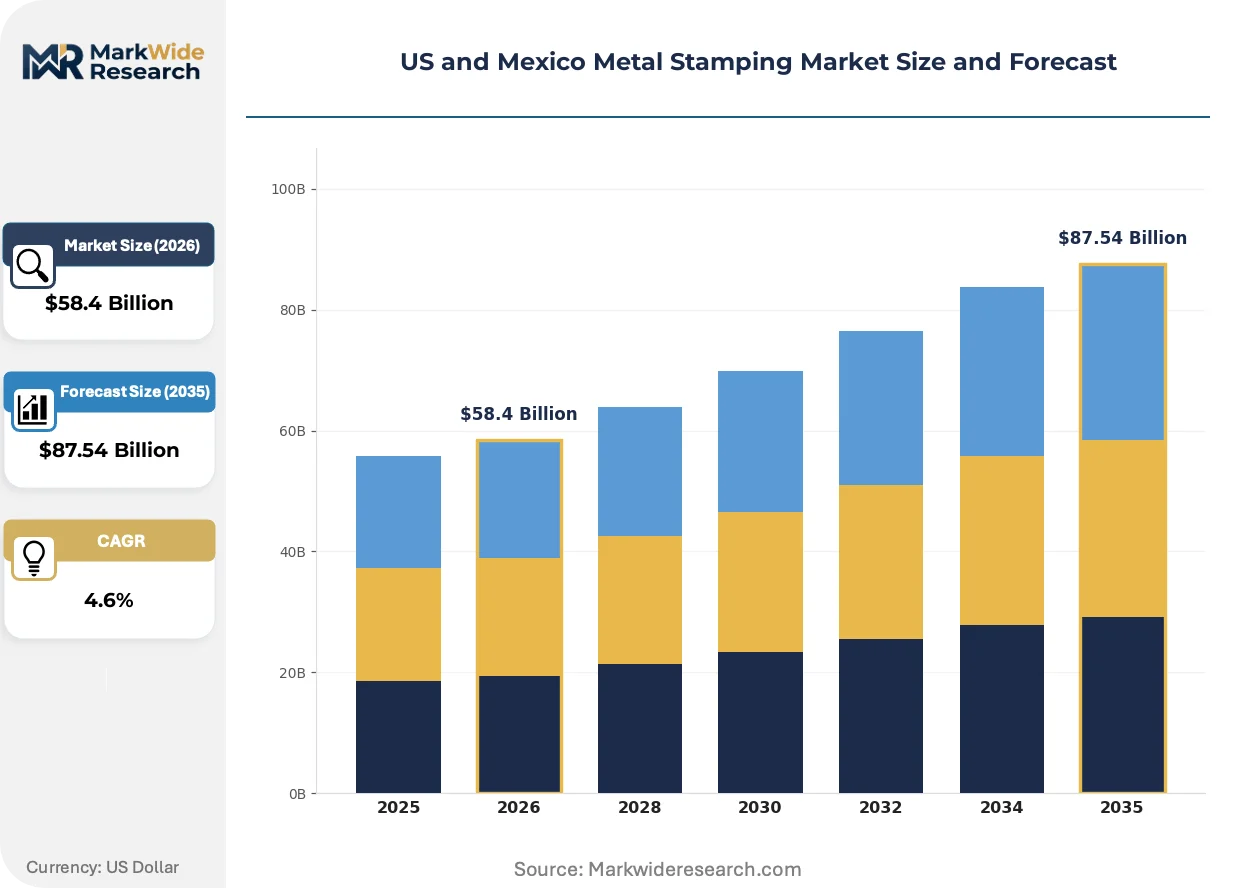
Market Dynamics
US EPA fuel economy mandates are compressing body-in-white material specifications across the US-Mexico automotive corridor, forcing die retooling investments and aluminum capacity expansion at tier suppliers co-located with vehicle assembly plants.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:The 2027-2032 fleet efficiency targets mandate stamped aluminum body panels for weight reduction, pulling capacity investments into Mexico's automotive manufacturing corridor.
- Battery electric vehicle platforms:EV architectures require redesigned stampings for battery tray housings and structural motor mounts, generating incremental die demand distinct from ICE vehicle specifications.
- USMCA rules of origin:Regional content requirements for automotive qualification are concentrating stamping capacity within the US-Mexico trade zone to preserve tariff-free component flows.
Market Restraints
- Aluminum price volatility:LME aluminum pricing swings compress margin predictability for stampers locked into long-term OEM supply agreements with fixed pass-through terms.
- Tooling lead time concentration:Die engineering and build capacity clusters in Germany and Japan, creating 14-18 month procurement bottlenecks for new vehicle program launches.
- Hydrogen embrittlement in high-strength steels:Advanced high-strength steel stampings for crash structures face processing limitations that constrain thickness reduction beyond current specifications.
Strategic Opportunities
- Nuevo León industrial cluster:Monterrey's expanding supplier park offers greenfield sites for integrated stamping-assembly operations serving Tesla and legacy OEM ramp-ups.
- Closed-loop aluminum recycling:On-site scrap reprocessing at stamping plants aligns with OEM circularity commitments and reduces ingot cost exposure.
- Hot stamping process adoption:Press-hardened boron steel lines for EV battery protection structures represent underdeployed capacity across Mexican supplier bases.
Industry Challenges
- Tool and die maker shortage:The US-Mexico corridor faces acute deficits in CNC machinists and die tryout technicians capable of precision automotive work.
- Die retooling cycle compression:Accelerated EV platform launches demand 18-month die development timelines against traditional 24-30 month schedules.
- Cross-border logistics coordination:Just-in-sequence delivery requirements across the US-Mexico border require real-time customs clearance and rail scheduling precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Mexico Metal Stamping Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $87.54 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Parts, Electronic Components, Hardware, Appliances Material: Steel, Aluminum, Copper, Brass End User: Automotive OEMs, Aerospace Manufacturers, Electronics Industry, General Manufacturing Technology: Progressive Die, Servo Press, Rotary Die, Stamping Press |
| Companies Covered | Kapco Metal Stamping, Oberg Industries, Magna International Inc., Goshen Stamping Company, Harvey Vogel Manufacturing Co., Martinrea International Inc., ACRO Metal Stamping, Pacific Metal Stampings, Inc., Ford Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Mexico Metal Stamping Market Strategic Shifts & Innovations
Digital die design and servo press technology are converging to reshape stamping economics across the US-Mexico corridor, enabling shorter production runs and faster material changeovers that align with EV platform diversification.
Servo-mechanical press technology is unifying the historically separate process steps of blanking, forming, and coining into single-stroke precision sequences. Tier suppliers serving Detroit Three automakers are retrofitting hydraulic lines with servo drives to capture 30% energy reductions and programmable slide motion. This unifying capability is compressing the minimum efficient scale for aluminum stamping runs, enabling economically viable production of EV-specific components at volumes below traditional ICE thresholds.
NHTSA crash safety standards are tightening pedestrian protection requirements for hood and fender assemblies, mandating controlled deformation characteristics in stamped aluminum outer panels. The regulatory pressure is accelerating adoption of tailored tempering processes and localized thickness optimization through patchwork blank technology. Hood stampings for US-market crossovers face the most stringent compliance timelines, with 2026 model year programs already locked in design verification phases.
Automotive OEM sourcing departments are consolidating supplier panels and demanding integrated stamping-assembly modules rather than discrete components. Tier suppliers in Querétaro and Guanajuato are responding by adding robotic welding and adhesive bonding cells adjacent to press lines. This consolidation pattern is most visible in battery tray supply chains, where single-source accountability for structural integrity is displacing multi-tier component sourcing.
US and Mexico Metal Stamping Market Segmentation
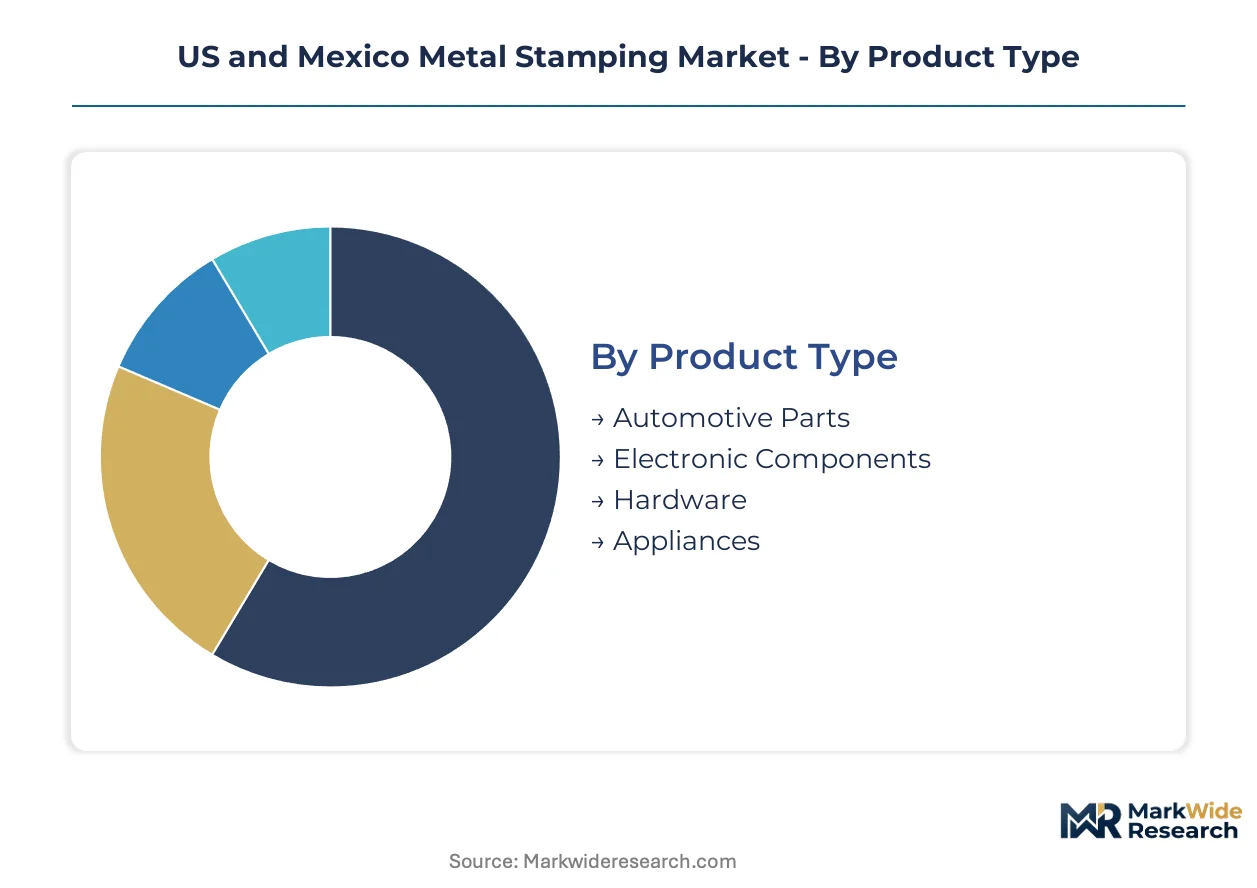
Segmentation reveals how material substitution and die technology choices reshape procurement economics across the US-Mexico automotive corridor. Buyers prioritize weight reduction compliance and die flexibility over legacy volume commitments.
Product Type:
End-use specifications dictate die complexity, surface finish requirements, and lot size economics for stamping suppliers serving cross-border supply chains.
- Automotive Parts:Structural stampings achieve tolerances within 0.1 mm for chassis brackets, body panels, and closure assemblies. Demand concentrates in Querétaro and Guanajuato assembly corridors where Detroit Three OEMs source aluminum-intensive body-in-white components under EPA fuel economy mandates.
- Electronic Components:Precision enclosures, shielding cans, and connector housings require fine-blanking dies with sub-0.05 mm repeatability. Volume is fragmenting across Nuevo León industrial parks serving appliance and telecommunications OEMs with shorter product lifecycles than automotive programs.
- Hardware:Fastener brackets, hinges, and mounting clips utilize standard progressive dies with 12-18 month tool lifespans.
- Appliances:Washing machine drums, refrigerator liners, and HVAC housings demand deep-draw capabilities with corrosion-resistant coatings.
Automotive Parts leads on scale; Electronic Components leads on momentum.
Material:
Density targets and forming limits determine alloy selection, with electrification forcing recalibration of traditional steel-centric supply chains.
- Aluminum:5xxx and 6xxx series alloys enable 30-50% weight reduction versus comparable steel stampings for hood, decklid, and door outer panels. Demand is accelerating fastest across Mexican supplier parks where Tesla and legacy OEMs co-locate aluminum stamping capacity with vehicle assembly.
- Steel:Advanced high-strength steels (AHSS) and press-hardened boron grades retain dominance in crash structures, A-pillars, and roof rails where stiffness-to-cost ratios favor ferrous metallurgy. USMCA rules of origin preserve integrated mill-to-stamper supply chains in Indiana, Ohio, and Michoacán.
- Copper:Busbar stampings and electrical terminals require high conductivity with work-hardening control during forming.
- Brass:Decorative and corrosion-resistant applications in marine hardware and plumbing fittings utilize C260 cartridge brass with half-hard tempers.
Steel leads on scale; Aluminum climbs the fastest.
End User:
Customer technical requirements span from PPAP-heavy automotive qualification to rapid-turn electronics prototyping, fragmenting supplier capabilities.
- Automotive OEMs:Just-in-sequence delivery mandates require stamping plants within 150 kilometers of vehicle assembly, driving geographic concentration in Mexico's Bajío region. Battery tray stampings for EV platforms demand hot-forming lines with in-die quenching capabilities absent from traditional ICE-focused suppliers.
- Electronics Industry:Consumer device and telecommunications OEMs prioritize die changeover speed over absolute volume, favoring servo press investments that enable 15-minute material swaps. Demand clusters in Tijuana and Ciudad Juárez maquiladora corridors serving US consumer electronics brands.
- Aerospace Manufacturers:Titanium and heat-resistant alloy stampings for airframe brackets require NADCAP-accredited heat treatment and non-destructive testing.
- General Manufacturing:Diverse industrial stampings for construction, agriculture, and material handling equipment tolerate wider tolerance bands and longer lead times.
Automotive OEMs lead on scale; Electronics Industry leads on momentum.
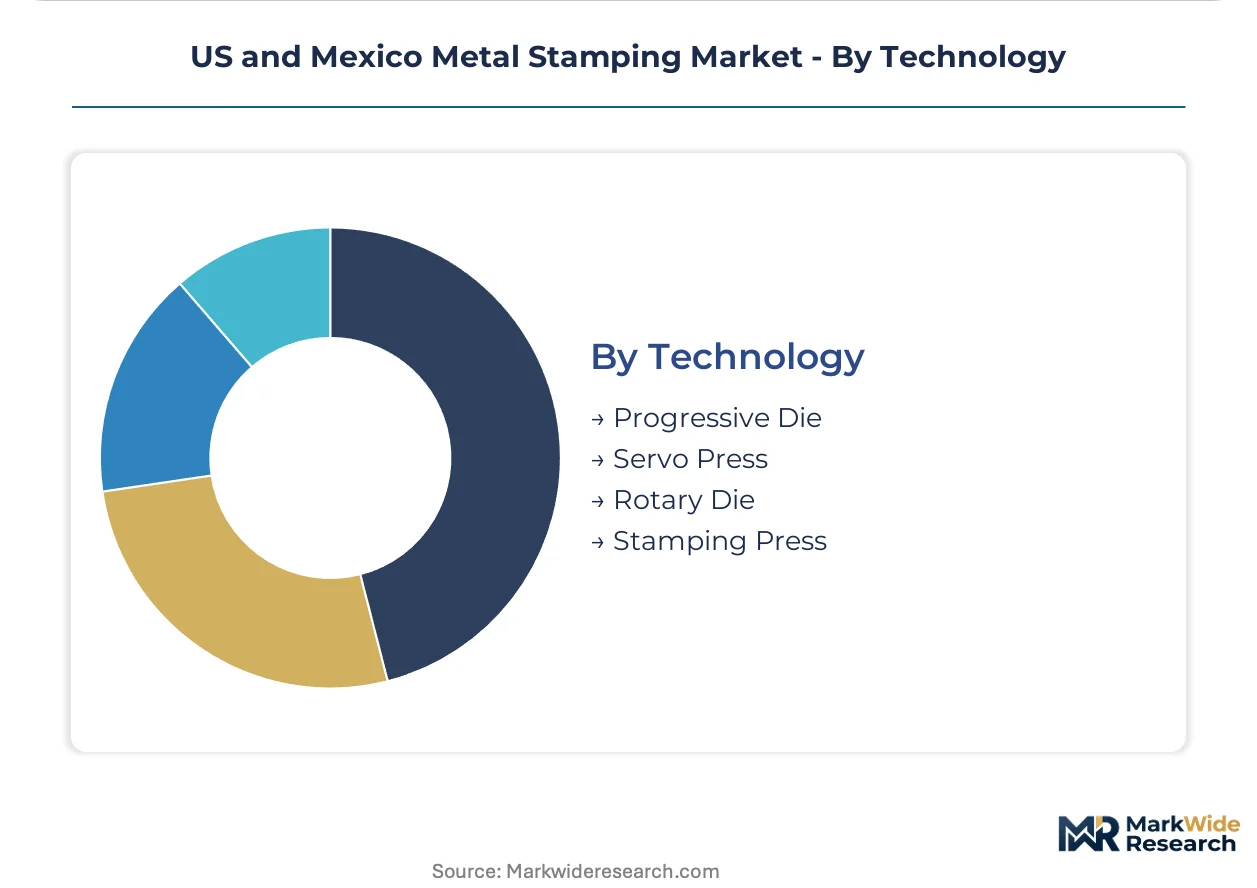
Technology:
Capital equipment choices determine energy efficiency, stroke programmability, and minimum efficient scale for aluminum versus steel production runs.
- Servo Press:Programmable slide motion unifies blanking, forming, and coining into single-stroke sequences while capturing 30% energy reduction versus hydraulic alternatives. Mexican tier suppliers retrofit legacy lines to serve EV component volumes below traditional ICE thresholds.
- Progressive Die:Multi-station tooling feeds coil stock through sequential cutting, bending, and piercing operations at rates exceeding 600 strokes per minute. High-volume automotive fasteners and electronic terminals concentrate demand in Guanajuato supplier parks with dedicated tool maintenance cells.
- Rotary Die:Cylindrical tooling enables continuous forming of cylindrical parts such as filter housings and bearing cups.
- Stamping Press:Conventional mechanical and hydraulic presses retain installed base dominance for large-part automotive stampings with lower complexity.
Progressive Die leads on scale; Servo Press gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's Bajío automotive corridor anchors metal stamping demand across the US-Mexico trade zone, with Querétaro and Guanajuato hosting concentrated capacity for aluminum body panel production serving EPA-compliant vehicle platforms.
United States
Michigan and Ohio retain dominance in high-volume stamping for Detroit Three OEMs, with Indiana and Kentucky serving as secondary hubs for light truck and SUV body-in-white components. NHTSA crash safety standards and EPA fuel economy mandates jointly dictate material specifications and thickness requirements for structural stampings. Tool and die engineering clusters in Detroit-Warren-Dearborn and Grand Rapids maintain specialized capacity for complex automotive dies.
Mexico
Nuevo León's Monterrey metropolitan area attracts greenfield stamping investments from Tesla and legacy OEM suppliers seeking USMCA-compliant regional content. SECOFI metrology standards and alignment with USMCA rules of origin shape supplier qualification requirements for cross-border component flows. The state's expanding supplier park offers integrated stamping-assembly sites with rail connectivity to Texas border crossings.
Canada
Ontario's Windsor-Toronto corridor maintains stamping capacity co-located with vehicle assembly plants serving the US market. Health Canada's alignment with US safety standards enables seamless component qualification for cross-border supply chains. Martinrea International anchors aluminum stamping operations in Ontario with captive capacity tied to major OEM assembly facilities.
US and Mexico Metal Stamping Market Key Industry Players
Capacity expansion dominates the current landscape as tier suppliers retrofit servo press lines and add hot-forming capabilities for EV battery structures. The vendor base stratifies into three tiers: integrated multinational suppliers with cross-border footprints, mid-cap specialists focused on single-material expertise, and regional job shops serving aftermarket and industrial demand. Two archetypes define competitive positioning: scale-driven stampers with OEM-integrated assembly modules, and flexibility-focused operators capturing EV program diversity. Geographic expansion into Mexico's Bajío region and technology licensing for servo press retrofits represent the dominant competitive moves.
Within the integrated multinational tier, Magna International Inc. and Martinrea International Inc. exemplify cross-border manufacturing structures aligned with Detroit Three supply chains. Among US-based specialists, Kapco Metal Stamping and Oberg Industries occupy positions in precision automotive and industrial stamping segments. Harvey Vogel Manufacturing Co. represents the mid-cap archetype serving diversified end-use demand.
| Leading Market Players |
|---|
| Kapco Metal Stamping |
| Oberg Industries |
| Magna International Inc. |
| Goshen Stamping Company |
| Harvey Vogel Manufacturing Co. |
| Martinrea International Inc. |
| ACRO Metal Stamping |
| Pacific Metal Stampings, Inc. |
| Ford Motor Company |
| Others |
Cost & Logistics Intelligence
Aluminum certification tiers for automotive body panels bifurcate procurement economics across the US-Mexico corridor, with OEMs demanding mill-certified 6xxx series alloys at premium contract rates while commodity-grade stampings face spot-market volatility. This divergence concentrates supply chain investment in SECOFI-qualified Mexican supplier parks capable of traceable temper documentation, while compressing margins for job shops serving aftermarket segments without metallurgical certification capabilities.
Pricing Analysis
Input-cost pass-through mechanisms in aluminum stamping operate through LME-linked contract structures with 90-day lag adjustments, exposing tier suppliers to margin compression when alloy premiums spike between pricing resets. OEM procurement teams differentiate suppliers by ISO/TS 16949 certification tier and in-die sensor capability, with premium pricing reserved for integrated stamping-assembly modules versus discrete component supply. Price erosion runs through commodity-grade hardware stampings as Chinese import competition intensifies in standard progressive die segments. Electronics OEMs in Tijuana exhibit highest price sensitivity due to short product lifecycles, while Detroit Three platform engineering teams prioritize performance compliance over unit cost in structural aluminum programs.
Supply Chain Analysis
Dual-sourcing requirements for critical body-in-white stampings mandate parallel qualification of suppliers in Mexico's Bajío region and the US Midwest, with OEMs maintaining active die sets at Magna and Martinrea facilities across both geographies. Raw material flows draw from Canadian aluminum smelters, German tool steel mills, and domestic scrap processors for closed-loop recycling programs. Tariff exposure under USMCA regional content rules creates compliance risk for stampers sourcing Chinese die components or non-qualifying alloy ingot. Distribution runs through just-in-sequence rail corridors connecting Querétaro assembly plants to Detroit and Kentucky vehicle facilities, with cross-border customs pre-clearance reducing transit variability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
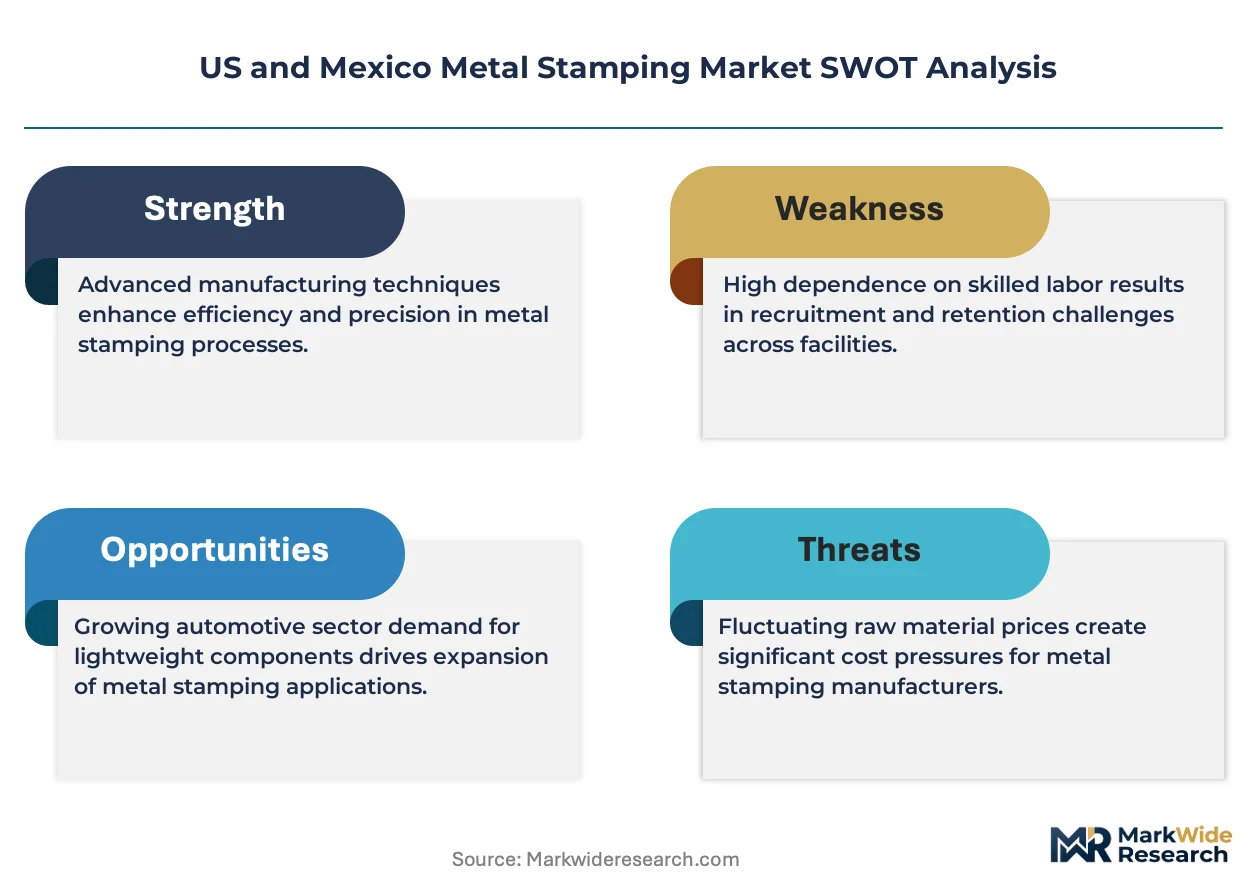
The US and Mexico Metal Stamping Market represents a late-cycle quality story as EPA fuel economy mandates force material specification upgrades toward heat-treatable aluminum alloys with full metallurgical traceability. OEM platform engineering teams now specify stampings by crash-performance tier rather than unit cost, rewarding suppliers with servo press flexibility and in-house assembly integration.
For Market Incumbents: Extend captive aluminum recycling capabilities to offset ingot cost volatility and secure circularity credentials with sustainability-focused OEM procurement teams. Add hot-forming press capacity for EV battery protection structures before competitor tool-build slots fill at limited German die engineering houses. Defend position by locking multi-year platform engineering contracts with Tesla and legacy OEM ramp-ups in Nuevo León, as die retooling cycle compression limits supplier switching flexibility. For New Entrants and Emerging Players: Enter via precision electronic component stamping in Tijuana maquiladora corridors, where shorter product lifecycles and rapid die changeover requirements favor servo press investments over scale-dependent automotive programs. Target appliance and HVAC housing segments in Guanajuato industrial parks, where deep-draw capabilities and corrosion-resistant coating expertise face less entrenched competition than automotive body panels. Pursue white-label manufacturing partnerships with US-based design houses seeking Mexico-based production without captive facility investment. For Investors and Strategic Acquirers: Consolidation pressure builds where tool and die engineering capacity constraints throttle program launch timelines for mid-tier stampers lacking in-house die design capabilities. Long-term viability favors integrated suppliers with cross-border manufacturing footprints and active OEM platform engineering relationships over regional job shops dependent on aftermarket volume. Target acquisition archetypes include SECOFI-qualified Mexican stampers with idle press capacity and established rail logistics to US border crossings. Watch die engineering lead time quotations from German and Japanese tool-builders as the inflection signal for supplier margin compression intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Recycling | Captive scrap reprocessing at stamping plants reduces LME price exposure and satisfies OEM circularity commitments. |
| Servo Press Line Retrofit | Programmable slide motion enables economically viable production of EV-specific components below traditional ICE volume thresholds. |
| Hot Stamping Capacity Addition | Press-hardened boron steel lines for battery protection structures address underdeployed capability across Mexican supplier bases. |
| Cross-Border Logistics Pre-Certification | USMCA-aligned customs clearance protocols reduce just-in-sequence delivery variability for Querétaro-to-Detroit rail corridors. |
| Die Engineering Partnership | Strategic alliances with German tool-builders secure 14-18 month procurement slots for accelerated EV platform launches. |
Research Approach
Multiple input streams — OEM platform engineering specifications, tier supplier production data, and USMCA trade flow records — were reconciled through structured primary interviews with stamping plant managers, automotive procurement directors, and tool and die engineering specialists. Secondary validation incorporated SEC filings from listed suppliers, vehicle production databases tracking platform-level content per vehicle, and customs records documenting aluminum alloy trade movements across the US-Mexico border. Bottom-up capacity modeling at individual facility level was cross-checked against top-down demand aggregation from OEM assembly schedules.
Historical volume trajectories for aluminum-intensive vehicle platforms were cross-referenced against panel input from tier supplier engineering directors to establish segment-level growth assumptions across the projection horizon. The analytical framework modeled demand by propulsion architecture, body panel application, material specification tier, and regional production cluster. CAGRs were derived from slope analysis of fitted trend lines applied to OEM platform launch timelines and corresponding die procurement cycles. Industry-specific forecast inputs included EPA fuel economy compliance cost curves and NHTSA pedestrian protection standard implementation schedules.
Inputs from OEM platform engineering disclosures and supplier SEC filings were available through the study window; gaps in private company die utilization rates and unreported contract pricing terms introduce uncertainty bands around capacity expansion timing assumptions. Deviation in EPA fuel economy standard stringency or USMCA regional content threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Bulk Material Handling System Market