
 North America Valves Market | 2026-2036
North America Valves Market Size, Share, and Industry Trends Forecast 2026-2036
North America Valves Market Analytics
The EPA Lead and Copper Rule Revision is hardening material certification requirements for municipal water infrastructure, forcing foundries and distributors to absorb new testing and compliance costs before bidding on public projects. Emerson Electric Co. leverages its vertical integration into metallurgical testing to sustain faster certification cycles than import-dependent competitors. Flowserve Corporation anchors its position through dedicated service hubs in Houston and Calgary that reduce turnaround times for oilfield valve rebuilds.
North America valves are mechanical flow-control devices manufactured from stainless steel, brass, PVC, or carbon steel, designed to start, stop, throttle, or regulate fluid and gas movement through piping systems at specified pressure and temperature ratings. Ball valves dominate commercial and residential plumbing for their quarter-turn sealing reliability, while butterfly valves capture share in large-diameter water treatment and HVAC applications where space and weight constraints matter. Carbon steel gate and globe variants retain primacy in upstream oil and gas isolation duties, though stainless steel alternatives are gaining ground in sour gas service where chloride corrosion resistance determines field life.
EPA drinking water standards, OSHA process safety management requirements, and ASME pressure vessel codes collectively shape product design, testing protocols, and market access across the United States and Canada. The Department of Transportation's pipeline safety regulations further constrain valve selection for interstate natural gas transmission, mandating specific fire-safe and fugitive-emission performance thresholds. Stakeholders must track how impending EPA per- and polyfluoroalkyl substances restrictions affect seal and coating chemistries, as reformulation timelines could disrupt established supply chains before compliance deadlines crystallize.
Market Dynamics
The North America valves market is being restructured by the collision of aging municipal water infrastructure replacement cycles with EPA Lead and Copper Rule Revision compliance deadlines, forcing foundries to requalify entire product lines under compressed timelines.
Growth Catalysts
- EPA Lead and Copper Rule Revision:Municipal water utilities across the United States are accelerating procurement of certified low-lead brass valve assemblies to meet federal drinking water standards, creating sustained replacement demand.
- Permian Basin shale expansion:Upstream oilfield operators in West Texas and southeastern New Mexico are deploying high-pressure isolation systems for unconventional production growth.
- LNG export corridor buildout:Gulf Coast petrochemical facilities require cryogenic and high-pressure control valves for liquefaction train capacity additions.
Market Restraints
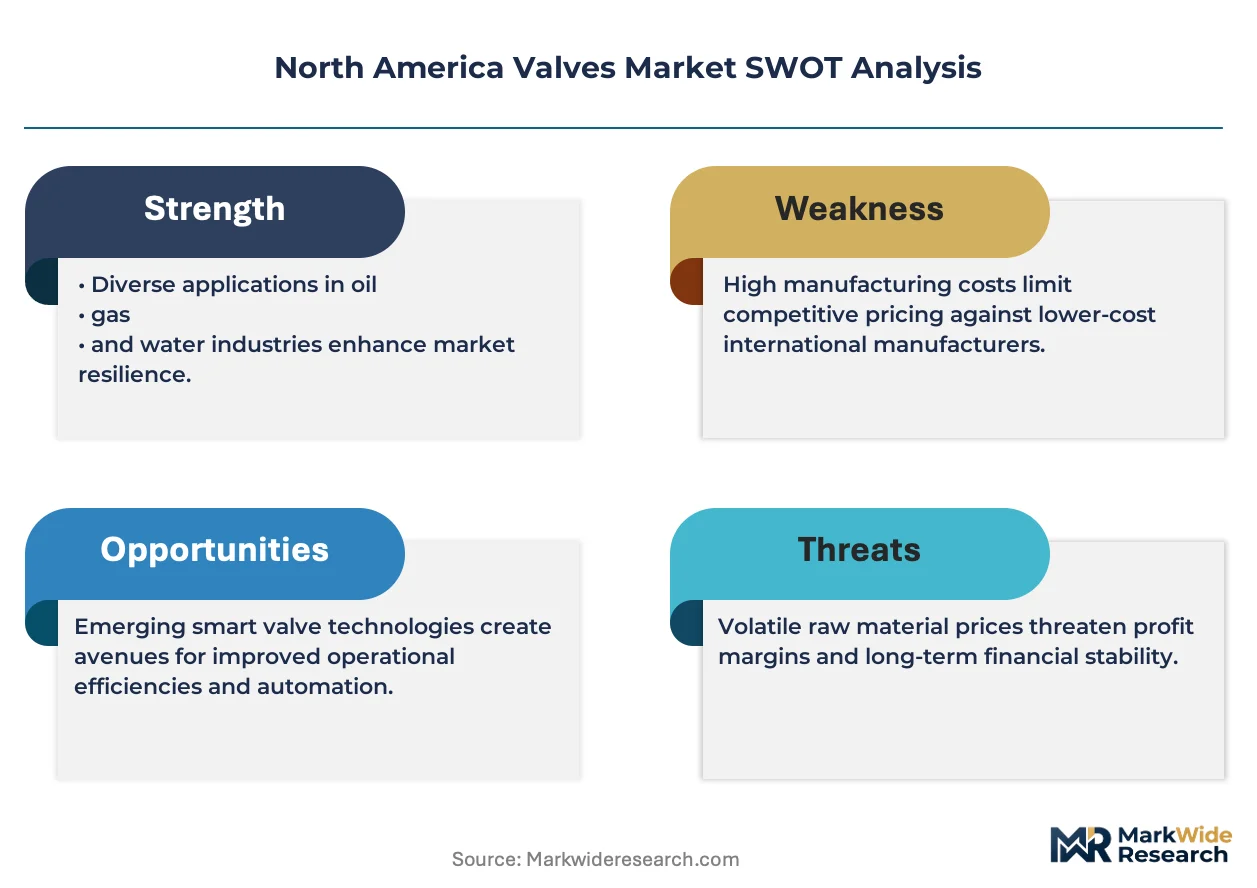
- Copper and brass alloy cost volatility:Foundries face margin compression from base metal price swings that municipal contracts rarely index.
- Import concentration in commodity castings:Low-margin bronze and iron valve bodies rely heavily on Asian foundry supply, exposing distributors to tariff and shipping cost shocks.
- Technical limitation in sour gas service:Chloride-induced stress corrosion cracking restricts carbon steel gate valve deployment in high-H2S Canadian formations.
Strategic Opportunities
- Underpenetrated Canadian oil sands aftermarket:SAGD thermal operations in Alberta require specialized high-temperature steam valve rebuild services with limited local provider density.
- Digital valve positioners converging with IIoT platforms:Asset-intensive water utilities are piloting predictive maintenance integration for actuated distribution network valves.
- Buy America procurement preference:Infrastructure Investment and Jobs Act domestic content requirements favor US-based foundries with established melt-and-pour certifications.
Industry Challenges
- Metallurgical certification timeline compression:Third-party testing laboratory capacity constraints are extending lead times for NSF/ANSI 61 and low-lead material approvals.
- Legacy SCADA integration complexity:Smart valve actuator deployments require protocol bridging with decades-old municipal telemetry infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Valves Market |
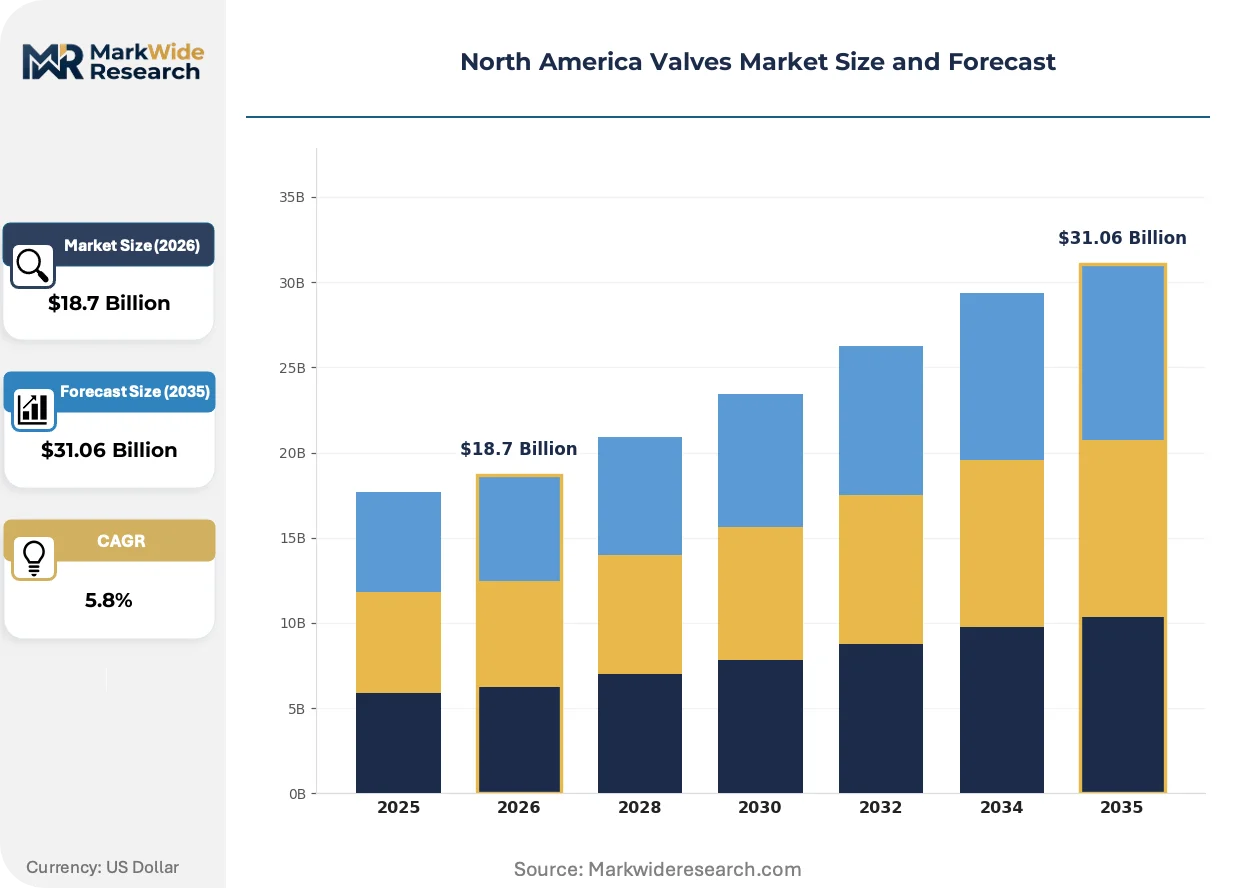
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valve, Gate Valve, Globe Valve, Butterfly Valve Material: Stainless Steel, Brass, PVC, Carbon Steel End User: Oil & Gas, Water Treatment, Power Generation, Manufacturing Application: Control, Isolation, Regulation, Safety |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Company, Schlumberger Limited, Alfa Laval Corporate AB, Velan Inc., IMI, Metso, Rotork Plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Valves Market Evolving Landscape
Digital instrumentation and material science advances are compressing the functional gap between commodity mechanical valves and intelligent flow-control nodes, while regulatory chemistry restrictions are forcing seal and coating reformulations across the supply base.
Additive manufacturing is absorbing low-volume, complex geometry casting production for specialty alloy valve bodies. Offshore oilfield service companies are adopting laser powder bed fusion for titanium and nickel superalloy components in subsea choke valves. The technology is absorbing prototype-to-production lead times from eighteen months to under eight weeks, compressing supplier qualification cycles for sour gas applications.
The EPA per- and polyfluoroalkyl substances restriction pathway is forcing elastomer seal compound reformulation across the North American valve industry. Fluoropolymer-based O-ring and packing suppliers face eighteen-to-twenty-four-month chemistry requalification timelines. Water treatment OEMs in the Great Lakes corridor are accelerating testing of thermoplastic elastomer alternatives to maintain NSF certification continuity.
Integrated valve-actuator-positioner packages are displacing separately sourced component procurement in large municipal water districts. Chicago, Houston, and Phoenix utilities have shifted specification language to favor factory-integrated smart packages over field-assembled configurations. The shift concentrates aftermarket service revenue with OEMs possessing diagnostic software platforms and regional technician networks.
North America Valves Market Segmentation
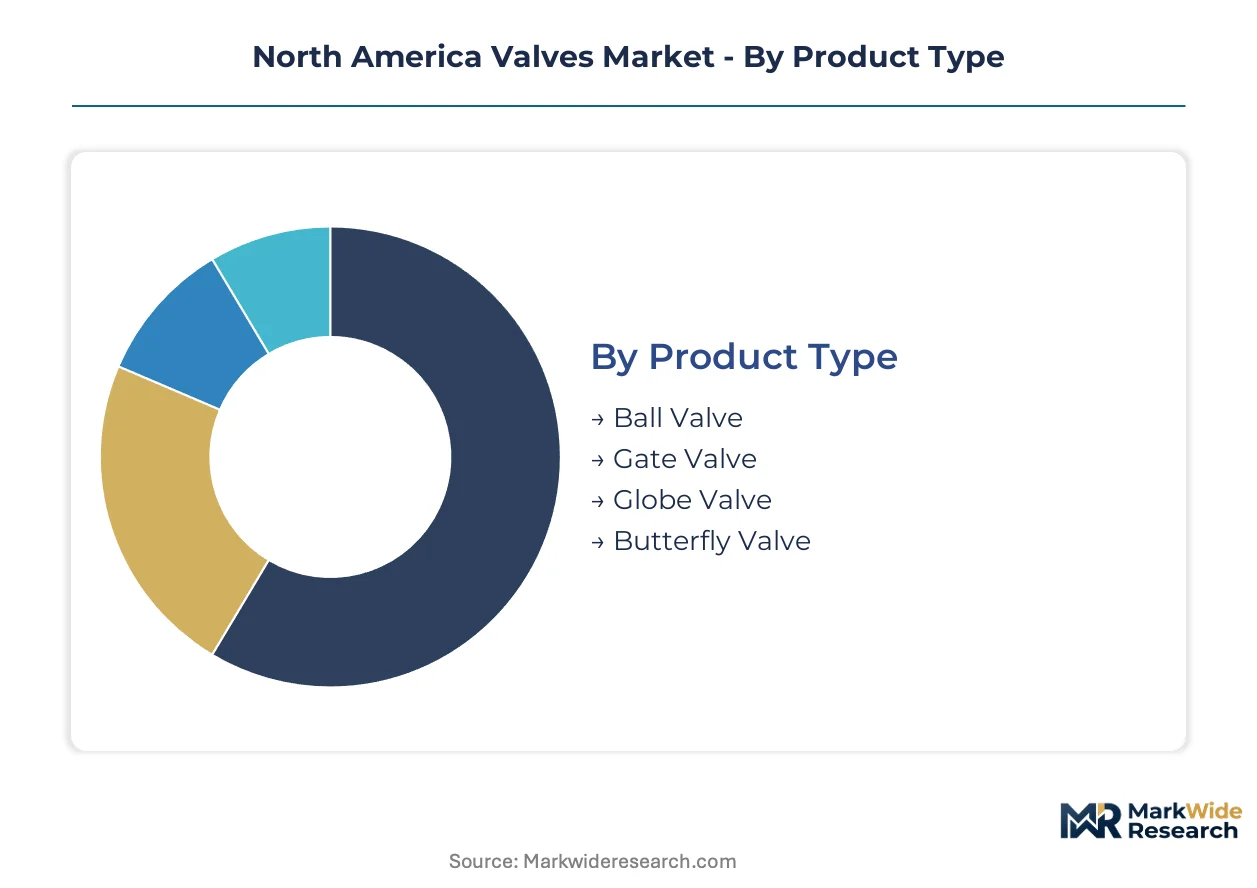
Valve specification in North America follows a cascading logic: application requirements dictate material selection, which then constrains product type choices. Procurement teams across municipal water districts and upstream operators segment their sourcing strategies around pressure ratings, corrosion resistance, and lifecycle serviceability rather than unit cost alone.
Product Type:
Ball valves operate as standalone quarter-turn isolation devices in residential and light commercial plumbing, while gate and globe variants embed into complex process piping skids requiring precise throttling sequences.
- Ball Valve:Spherical closure element rotates 90 degrees to achieve bubble-tight sealing with minimal operating torque. Municipal water utilities in Phoenix and Houston specify full-port ball configurations for distribution network isolation points where sediment passage and low head-loss dominate procurement criteria.
- Gate Valve:Wedge-shaped disc moves perpendicular to flow direction, providing straight-through passage with minimal pressure drop. Permian Basin operators deploy expanding gate variants in high-pressure wellhead Christmas trees where double-block-and-bleed isolation meets API 6A certification requirements.
- Globe Valve:Disc seats against parallel or inclined plane to enable precise flow modulation. Steam service applications in Alberta SAGD facilities favor Y-pattern globe designs for high-temperature thermal cycling resistance.
- Butterfly Valve:Circular disc pivots on shaft axis to occupy minimal face-to-face dimension. Great Lakes water treatment plants specify rubber-lined butterfly configurations for raw water intake structures where space constraints and large bore diameters converge.
Ball valves lead volumes today; butterfly valves are gaining share fastest in large-diameter municipal retrofits.
Material:
Cost tier stratification separates commodity bronze and iron castings from premium alloy grades, with certification complexity widening the procurement gap between import-dependent distributors and domestic melt-and-pour suppliers.
- Stainless Steel:Austenitic and duplex grades deliver chloride corrosion resistance for sour gas and seawater applications. Gulf Coast LNG liquefaction trains specify CF8M cast stainless for cryogenic butterfly valve bodies where thermal shock resistance determines field reliability.
- Brass:Copper-zinc alloys machine readily and solder reliably for potable water service. EPA Lead and Copper Rule Revision compliance is forcing foundries toward bismuth and silicon bronze formulations that maintain machinability below 0.25% lead content thresholds.
- PVC:Thermoplastic construction eliminates galvanic corrosion in aggressive chemical environments. Semiconductor fabrication facilities in Arizona and Oregon specify PVC ball valves for ultrapure water distribution where metallic ion contamination risks override pressure rating requirements.
- Carbon Steel:WCC and LCC cast grades dominate high-pressure oilfield isolation duties. Canadian oil sands thermal operations favor carbon steel gate valves for steam distribution headers where temperature cycling rather than corrosion governs material selection.
Carbon steel anchors upstream oilfield procurement; stainless steel climbs fastest on sour gas and chemical processing demand.
End User:
Customer type fragmentation separates asset-intensive process industries with dedicated maintenance staffs from municipal utilities reliant on contractor networks for valve installation and rebuild services.
- Oil & Gas:Upstream, midstream, and downstream operations span wellhead isolation through refinery catalytic cracking. West Texas shale producers are standardizing on metal-seated ball valves for high-cycle hydraulic fracturing manifolds where sand erosion destroys soft-seat alternatives.
- Water Treatment:Municipal distribution, wastewater reclamation, and desalination facilities. Chicago and Toronto utilities are consolidating actuator specifications across their distribution networks to simplify spare parts inventory and technician training protocols.
- Power Generation:Thermal, nuclear, and renewable electricity production. Combined-cycle gas turbine plants in Pennsylvania and Ohio require high-temperature steam valves with ASME Section I certification for supercritical service conditions.
- Manufacturing:General industrial process plants including food, pharmaceutical, and chemical production. FDA-regulated bioprocessing facilities specify sanitary diaphragm valves with surface finishes below 20 Ra for aseptic clean-in-place protocols.
Water treatment commands the largest unit volumes; oil and gas generates the highest average transaction values per valve assembly.
Application:
Maturity gradients separate commoditized on-off isolation from emerging smart regulation applications, with safety system integration representing the highest specification barrier to supplier entry.
- Control:Modulating valve position in response to process variable feedback. Refinery fluid catalytic cracking units deploy high-performance butterfly valves with digital positioners to maintain reactor temperature within narrow operating bands.
- Isolation:Positive shutoff to enable equipment maintenance or emergency shutdown. Pipeline operators along the TransCanada and Rockies Express corridors specify full-bore gate valves with fire-safe actuator configurations per DOT pipeline safety regulations.
- Regulation:Pressure or flow control through variable orifice adjustment. Municipal water districts in California are piloting pressure-reducing valves with embedded pressure sensors to manage distribution zone hydraulics and reduce main break frequency.
- Safety:Automatic intervention during process upset or equipment failure. Petrochemical facilities in the Houston Ship Channel maintain redundant pressure relief valve inventories sized per API 520/521 standards for runaway reaction scenarios.
Isolation dominates installed base counts; control applications are expanding most quickly through digital positioner adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled valve technicians and certified welders concentrate along the Gulf Coast petrochemical corridor and the Great Lakes manufacturing belt, anchoring North American production capacity for precision-machined flow control equipment.
United States
EPA Lead and Copper Rule Revision deadlines are driving municipal water utility procurement of certified low-lead brass assemblies across the Midwest and Southwest. The Infrastructure Investment and Jobs Act channels federal funding toward distribution network replacement in legacy cities. Houston anchors Gulf Coast demand for high-pressure isolation systems serving LNG export terminal expansions.
Canada
Alberta SAGD thermal operations require specialized high-temperature steam valve rebuild services with limited local provider density. Health Canada maintains parallel drinking water material certification pathways that extend testing timelines for cross-border suppliers. Calgary and Edmonton host concentrated oilfield service infrastructure supporting oil sands maintenance cycles.
Mexico
Pemex refinery modernization and private midstream investment are expanding demand for carbon steel gate valves in Tamaulipas and Veracruz. The country's national petroleum regulator enforces equipment standards aligned with API specifications for upstream installations. Monterrey's industrial base is absorbing valve assembly work previously sourced from Asian foundries under nearshoring arrangements.
North America Valves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels in the North America valves market. Large-scale industrial automation groups leverage captive metallurgical testing and distribution networks to compress certification cycles for municipal infrastructure projects. Mid-cap specialists anchor positions in oilfield aftermarket services through dedicated regional repair hubs. Strategic moves concentrate on backward integration into foundry operations and selective acquisitions of digital actuator technology platforms.
Among publicly traded industrial conglomerates, Emerson Electric Co. exemplifies the vertically integrated archetype with in-house material certification capabilities, while Flowserve Corporation occupies a position emphasizing regional service density. Velan Inc. represents the specialist fabricator model focused on severe-service applications. These three anchors illustrate how competitive positioning diverges between scale-driven platform coverage and technical specialization in corrosion-resistant alloys.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Company |
| Schlumberger Limited |
| Alfa Laval Corporate AB |
| Velan Inc. |
| IMI |
| Metso |
| Rotork Plc |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up valve specialists concentrate foundry ownership across Ohio and Pennsylvania, compressing procurement leverage for municipal distributors while enforcing disciplined pricing tiers that reflect melt-and-pour certification status rather than commodity casting economics.
Pricing Analysis
The bundled-vs-unbundled service split separates OEM-integrated smart valve packages from field-assembled commodity configurations. Three-tier pricing structure across premium, standard, and economy levels reflects NSF/ANSI 61 certification grade and domestic melt-and-pour origin. Cost compression in economy brass castings intensifies because Asian foundry supply faces tariff exposure. Municipal water utilities exhibit highest price sensitivity; Permian Basin operators prioritize field reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese foundry capacity for commodity bronze and iron valve bodies. Supply draws from China, India, and domestic Great Lakes manufacturing clusters for raw castings. Copper and zinc alloy feedstock, elastomer seal compounds, and precision-machined actuator components anchor material dependencies. Tariff exposure on imported castings creates margin volatility for distributors. Distribution runs through authorized OEM networks and independent industrial distributors serving contractor installation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America valves market functions as a stable compounder, with EPA infrastructure replacement mandates and LNG export capacity buildouts generating predictable procurement cycles across municipal and industrial buyer segments.
For Market Incumbents: Extend metallurgical testing capabilities to compress NSF/ANSI 61 certification timelines before competitors secure municipal contract lock-in. Acquire regional service hubs in Alberta SAGD corridors to capture high-margin rebuild revenue. Defend against digital actuator specialists by integrating predictive maintenance software with factory-installed valve packages. For New Entrants and Emerging Players: Begin with aftermarket service specialization in Canadian thermal oil sands operations where local provider density remains thin. Target digital valve positioner retrofit opportunities in legacy municipal SCADA networks. Pursue direct contracting with Great Lakes water treatment OEMs seeking PFAS-compliant seal alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap foundry operators lacking EPA low-lead certification but possessing melt-and-pour infrastructure. Five-to-ten-year viability hinges on Infrastructure Investment and Jobs Act domestic content enforcement. Watch for EPA PFAS restriction finalization as inflection indicator for seal chemistry reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive melt-and-pour capacity secures Buy America eligibility for municipal infrastructure contracts. |
| Digital Actuator Platform Acquisition | Smart valve positioner technology enables predictive maintenance revenue from water utility networks. |
| Regional Service Hub Expansion | Calgary and Edmonton facilities reduce turnaround times for Alberta SAGD steam valve rebuilds. |
| PFAS-Compliant Seal Development | Thermoplastic elastomer alternatives maintain NSF certification continuity under EPA chemistry restrictions. |
| Long-Term Municipal Supply Agreement | Chicago and Houston utilities consolidate specifications around factory-integrated valve-actuator packages. |
Research Methodology
Multiple input streams — primary interviews with municipal procurement directors, oilfield maintenance supervisors, and foundry operations managers; secondary validation through EPA regulatory filings, ASME certification databases, and Infrastructure Investment and Jobs Act funding disclosures; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against panel input from industry participants to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use industry, and application function. CAGRs were derived from regression analysis of replacement cycle timing, regulatory deadline phasing, and capital project pipeline visibility. Shale production growth curves and LNG liquefaction train commissioning schedules provided industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen EPA rulemaking acceleration, trade policy shifts affecting foundry import economics, and breakthroughs in additive manufacturing cost parity. Forecasts reflect documented assumptions about infrastructure funding continuity and certification laboratory capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valve Positioners Market
Valves
Float Traps Market
Valves
Aerospace Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
Blasting Stemming Plugs Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Thermal Power Valve Market
Valves
APAC Valves Market
Valves
Global Level Gauge Market
Valves
Blow - Off Valves Market
Valves
Portable Valve Actuator Market
Valves
Mooring Inspection Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Rising Stem Ball Valve Market
Valves
HVAC Valves Market